
 DLP Projector Market | 2026-2036
DLP Projector Market Size, Share, and Industry Trends Forecast 2026-2036
DLP Projector Market Analysis
Asian semiconductor foundries is recalibrating DMD chip output schedules to match rebounding projector assembly rates. Texas Instruments leverages its captive MEMS fabrication network to sustain component leadership across single-chip and three-chip architectures. Barco NV anchors the high-lumen professional segment through specialized cinema and large-venue product lines. Optoma Corporation competes aggressively in home theater and short-throw categories where price-performance ratios determine purchase decisions.
A DLP projector employs a digital micromirror device—an array of microscopic aluminum mirrors tilted electrostatically—to modulate light and produce images with high contrast ratios and minimal pixel gaps. The technology serves commercial presentation, cinematic exhibition, immersive gaming, and residential entertainment applications where color accuracy and maintenance intervals matter. Lamp-based systems still occupy the bulk of education procurement budgets, though laser variants are capturing margin pools in corporate and premium home theater channels. Portable units lead volume shipments, while three-chip installations dominate the large-venue application tier where brightness thresholds exceed twenty thousand lumens.
FCC equipment authorization rules govern radio-frequency emissions from wireless-enabled projector models sold in the United States, while EU RoHS and REACH frameworks restrict hazardous substances in optical engines and power supplies bound for European markets. China's GB standards for electronic display energy consumption, enforced by SAMR, shape local procurement specifications and import qualification protocols. Stakeholders must monitor how regional efficiency mandates and substance restrictions cascade through supply chains to determine whether lamp-based portfolios require accelerated phase-out planning or geographic repositioning.
Market Dynamics
Laser phosphor illumination is compressing replacement cycles for lamp-based DLP fleets while EPA energy-efficiency thresholds accelerate obsolescence schedules for legacy optical engines.
Growth Catalysts
- Hybrid workplace mandates:Corporate real estate teams in the United States are outfitting conference suites with wireless-enabled laser units to support distributed collaboration protocols.
- REACH substance restrictions:The EU RoHS framework is phasing out mercury-bearing lamp assemblies, creating replacement demand for solid-state illumination in European education and public sector tenders.
- Immersive entertainment venues:Location-based experience operators in the United Arab Emirates are installing high-lumen three-chip systems for projection-mapped attractions and themed environment rendering.
Market Restraints
- DMD chip supply concentration:Texas Instruments maintains captive MEMS fabrication for micromirror arrays, creating single-source vulnerability for projector OEMs outside its licensing network.
- Rare earth magnet pricing volatility:Neodymium and dysprosium cost swings in Chinese processing facilities feed through to color wheel motor and galvanometer actuator bill-of-materials.
- Flat-panel display substitution:Direct-view LED video walls are capturing large-venue applications above 10,000 lumens where seamless scaling and ambient light immunity outweigh projection flexibility.
Strategic Opportunities
- Tier-two Chinese city penetration:Provincial education bureaus in Sichuan and Shaanxi are consolidating classroom AV standards, opening procurement windows for mid-lumen laser projectors.
- GB standards compliance services:SAMR energy-efficiency certification requirements are creating adjacent revenue streams for testing laboratories and retrofit consulting around legacy lamp inventories.
- Extended reality integration:Convergence of DLP light engines with spatial computing headsets is enabling low-persistence, high-refresh-rate near-eye display architectures for simulation and training.
Industry Challenges
- Optical engine thermal management expertise:Laser phosphor system design requires competencies in fluorescence wheel degradation modeling and sealed-light-path engineering that remain scarce outside established cinema projector manufacturers.
- FCC equipment authorization timelines:Wireless-enabled models face extended certification queues for radio-frequency emission testing, compressing product launch windows against seasonal education procurement cycles.
- Legacy control protocol fragmentation:Integration with existing Crestron, Extron, and AMX room automation installations demands backward compatibility layers that inflate firmware complexity and support costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DLP Projector Market |
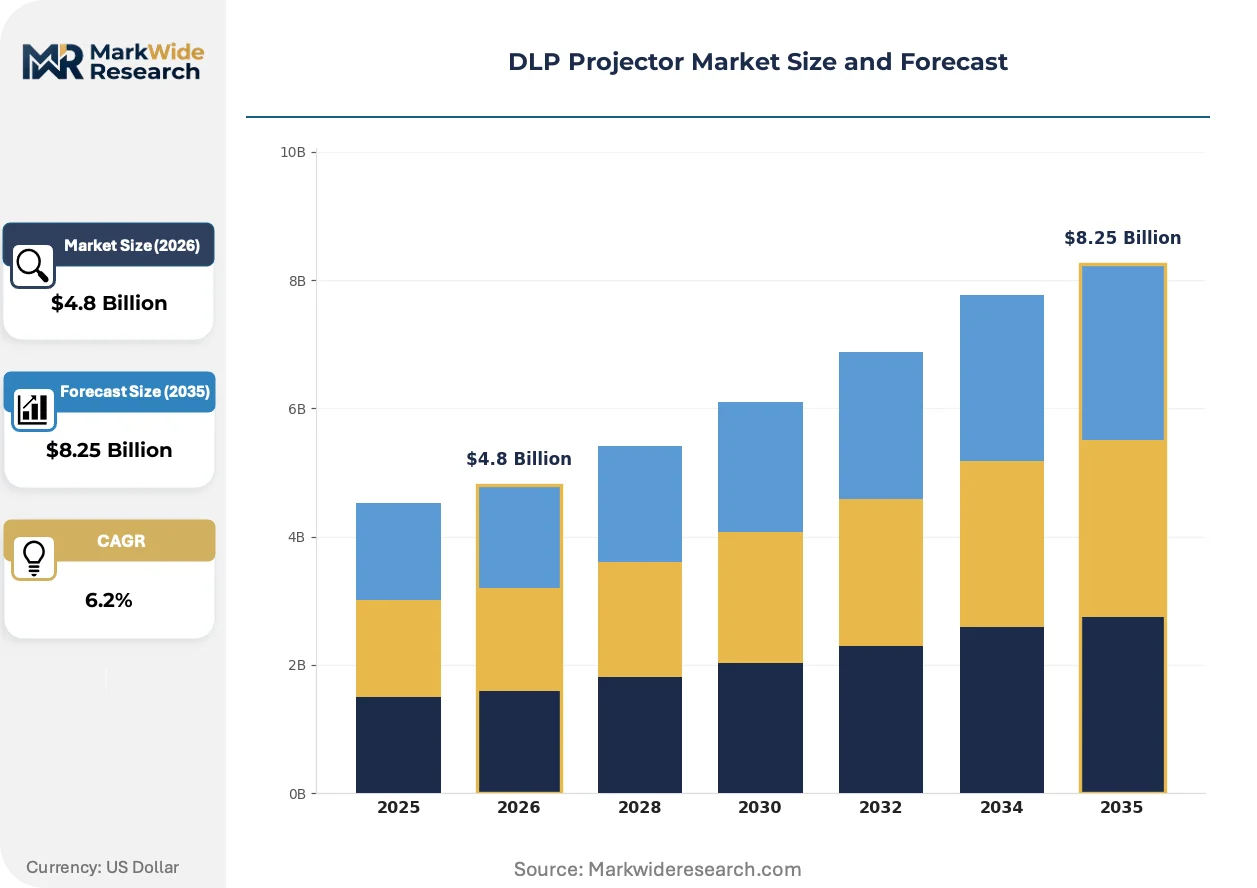
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Mounted, Short Throw, Ultra Short Throw Technology: Single-Chip, Three-Chip, Laser, Lamp-Based End User: Education, Corporate, Home Theater, Entertainment Application: Presentations, Movies, Gaming, Events |
| Companies Covered | Texas Instruments Inc., Barco NV, Optoma Corporation, BenQ Corporation, NEC Display Solutions, Digital Projection Ltd., ViewSonic Corporation, Christie Digital Systems, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DLP Projector Market Emerging Trajectories
Illumination architecture, regulatory chemistry restrictions, and procurement centralization are converging to reshape how DLP projectors are specified, financed, and deployed across end-use verticals.
RGB pure laser illumination is rewriting brightness-per-watt benchmarks for professional cinema and large-venue installations. Premium theater chains in Saudi Arabia and South Korea are retrofitting auditoriums with dual-laser light sources that eliminate color wheels and extend operational life beyond 30,000 hours. This solid-state transition is compressing service contract pricing and shifting vendor revenue toward lamp-less hardware margins.
EPA energy-efficiency guidelines for electronic displays are tightening standby power thresholds and luminous efficacy minimums for equipment sold into federal procurement channels. Lamp-based models face disqualification from General Services Administration schedules, forcing manufacturers to accelerate laser SKU transitions or surrender institutional volume. School districts and municipal buyers are consolidating specifications around ENERGY STAR-compliant laser alternatives.
Centralized procurement through AV integrator consortia is displacing direct OEM relationships in North American enterprise and higher education segments. Purchasing cooperatives like OMNIA Partners and E&I Cooperative Services are aggregating demand across hundreds of member institutions, extracting volume pricing and standardized five-year total-cost-of-ownership warranties. This channel consolidation favors manufacturers with dedicated education sales engineering and nationwide depot service networks.
DLP Projector Market Segmentation
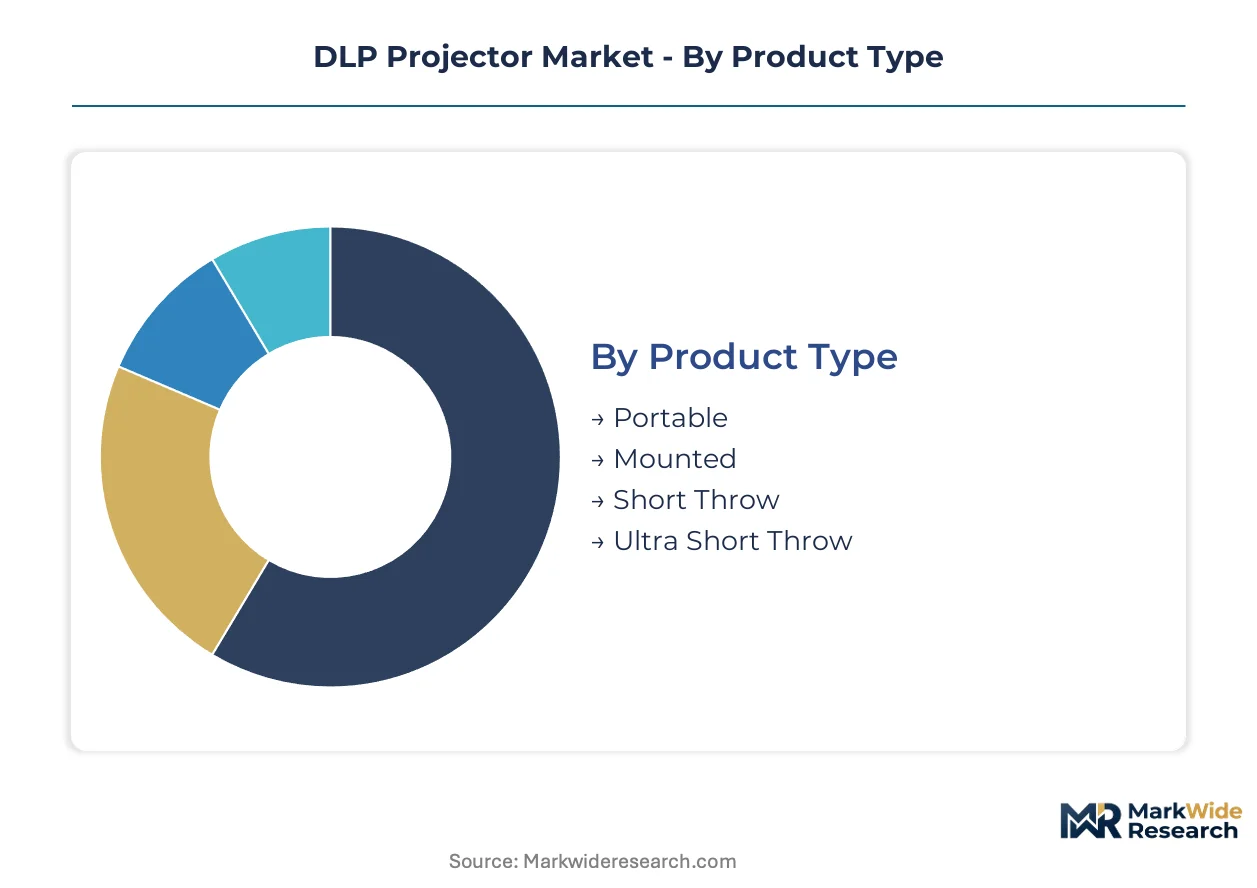
DLP projector procurement patterns diverge sharply across installation contexts, illumination architectures, and end-use workflows. Understanding how replacement cycles and specification standards vary by segment enables vendors to align SKU portfolios with actual deployment economics rather than nominal category labels.
Product Type:
Upgrade cycles for installed projection hardware vary dramatically by physical form factor and mounting configuration, with mobility requirements and room geometry driving diverging replacement timelines.
- Portable:Battery-capable units under five kilograms serve mobile presenters and field sales teams. China's tier-one cities are consolidating procurement for district-level education inspectors, with laser variants displacing lamp-based inventory ahead of GB standards enforcement.
- Mounted:Ceiling-installed systems dominate corporate conference room retrofits. United States hybrid workplace mandates are accelerating refresh rates for wireless-enabled laser units in Fortune 500 real estate portfolios.
- Short Throw:Projection ratios below 0.5 enable large images from constrained throw distances. Home theater installations in Saudi Arabia and South Korea favor these for ambient light management in residential media rooms.
- Ultra Short Throw:Sub-0.25 throw ratios eliminate shadow interference for interactive whiteboard applications. Education bureaus in Sichuan province are specifying these for new classroom construction to reduce mounting infrastructure costs.
Portable units sit at the top of the volume ranking, with ultra short throw climbing the fastest as interactive display substitution accelerates in Asian education tenders.
Technology:
Illumination source and chip architecture decisions lock in operational cost structures and compliance trajectories for multi-year deployment horizons.
- Single-Chip:One DMD device with sequential color processing via spinning wheel or solid-state phosphor. Corporate procurement in the United States favors these for sub-5,000-lumen conference room applications where total cost of ownership dominates capital expenditure decisions.
- Three-Chip:Dedicated DMD arrays for red, green, and blue channels eliminate color breakup artifacts. Cinema chains in the United Arab Emirates are deploying these for premium large-format auditoriums above 20,000 lumens.
- Laser:Solid-state phosphor or RGB direct-diode illumination eliminates lamp replacement cycles. EPA energy-efficiency thresholds are disqualifying lamp alternatives from federal procurement schedules.
- Lamp-Based:Mercury vapor arc lamps with 2,000-4,000 hour lifespans still occupy budget-constrained education segments. EU RoHS mercury restrictions are compressing available replacement windows for European institutional buyers.
Single-chip architectures dominate unit shipments, with laser configurations gaining share fastest as regulatory chemistry restrictions harden across major procurement jurisdictions.
End User:
Customer-type segmentation reveals how procurement authority centralization and usage intensity reshape vendor go-to-market requirements.
- Education:K-12 and higher education institutions operate on rigid fiscal year cycles with aggregated purchasing cooperative membership. OMNIA Partners and E&I Cooperative Services in the United States are consolidating specifications around five-year total-cost-of-ownership warranties.
- Corporate:Enterprise AV teams prioritize wireless casting integration and room automation compatibility. Hybrid meeting space retrofits are compressing decision timelines from twelve to six months.
- Home Theater:Enthusiast buyers emphasize contrast ratios and color gamut coverage over raw brightness. Online review aggregation and calibration community forums increasingly determine brand consideration sets.
- Entertainment:Location-based experience operators and cinema exhibitors demand 24/7 operational reliability with minimal downtime. Saudi Arabia's entertainment sector investment mandates are accelerating large-venue deployment timelines.
Education represents the largest addressable base by unit volume, with entertainment exhibiting the steepest expansion trajectory as immersive venue construction accelerates in Gulf Cooperation Council markets.
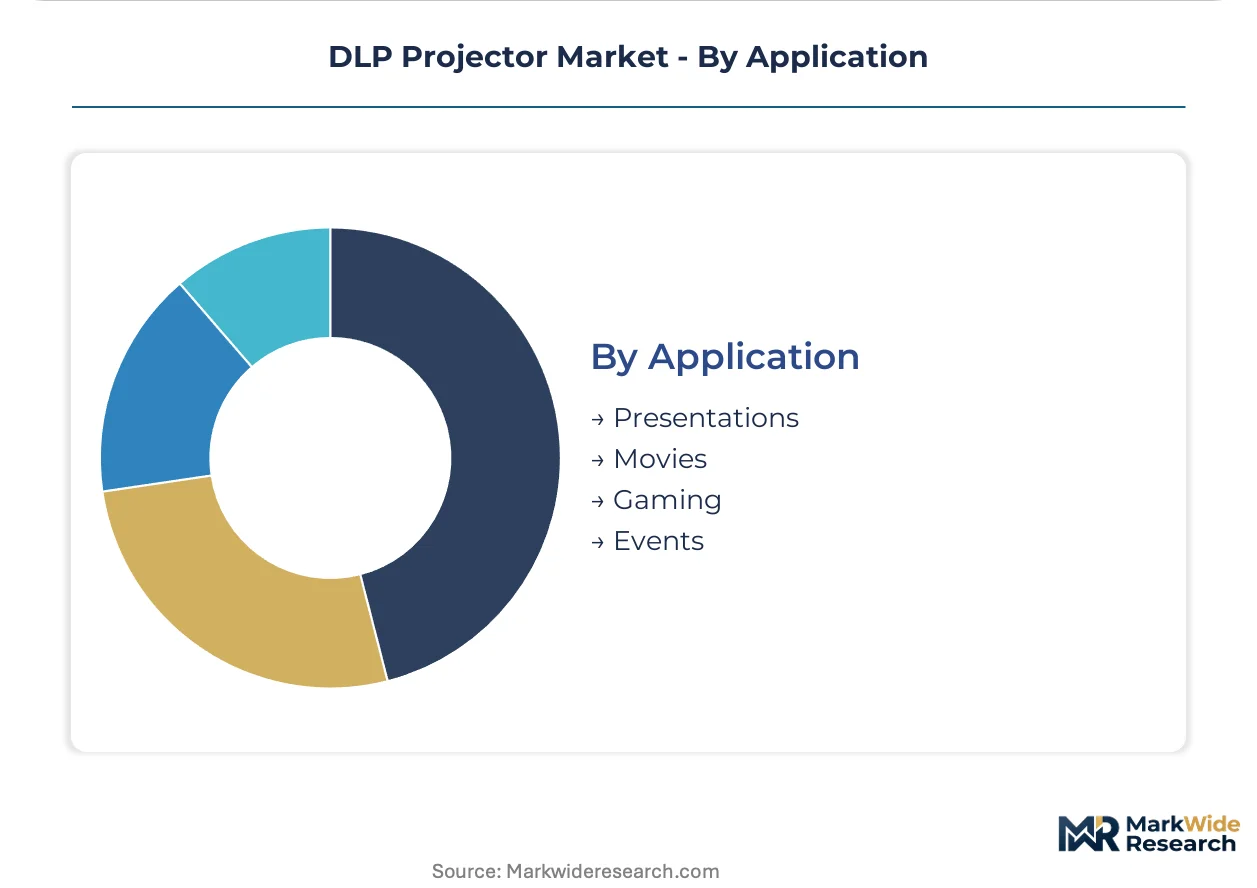
Application:
Usage scenario segmentation exposes how content type and ambient environment dictate brightness, resolution, and connectivity specifications.
- Presentations:Static slide and spreadsheet visualization prioritizes readability over cinematic color accuracy. Corporate procurement teams in the United States are mandating 4K resolution minimums for executive briefing centers.
- Movies:Cinematic exhibition demands DCI-P3 color space compliance and high dynamic range support. Premium theater chains in South Korea are retrofitting auditoriums with RGB pure laser to eliminate color wheels.
- Gaming:Low input lag and high refresh rates determine competitive viability. Esports venue operators in the United Arab Emirates are specifying sub-16ms latency thresholds for tournament-grade installations.
- Events:Temporary deployment scenarios prioritize rapid rigging and ambient light immunity. Projection mapping for themed environments in Saudi Arabia is driving demand for 30,000+ lumen three-chip systems.
Presentations anchor current installed base volumes, with events applications climbing fastest as location-based entertainment construction outpaces traditional cinema screen growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as lamp-based production migrates toward jurisdictions with deferred mercury-restriction timelines while laser assembly concentrates near premium demand clusters.
United States
Fortune 500 real estate teams are accelerating conference room retrofits with wireless-enabled laser units to support hybrid collaboration mandates. EPA energy-efficiency guidelines are tightening standby power thresholds and disqualifying lamp-based alternatives from General Services Administration procurement schedules. Corporate AV deployment concentrates in Dallas-Fort Worth and Chicago metro corridors where integrator consortia aggregate demand.
China
Tier-one city cinema chains and education bureaus are replacing aging projection fleets with solid-state illumination systems. SAMR enforcement of GB standards for electronic display energy consumption is reshaping local procurement specifications and import qualification protocols. Sichuan and Shaanxi provincial education authorities are consolidating classroom AV standards for mid-lumen laser tenders.
Germany
Industrial training centers and automotive engineering facilities are specifying high-lumen installations for simulation and immersive visualization workflows. ECHA REACH substance restrictions are phasing out mercury-bearing lamp assemblies in public sector tenders. Bavaria's precision manufacturing corridor anchors specialized optical engine assembly for professional cinema equipment.
Saudi Arabia
Entertainment sector investment mandates are accelerating large-venue deployment timelines for location-based experience operators. MOHAP and SFDA frameworks govern equipment import standards for public assembly venues. Riyadh and Jeddah clusters are driving demand for 30,000+ lumen three-chip systems in projection-mapped themed environments.
South Korea
Premium theater chains are retrofitting auditoriums with RGB pure laser illumination to eliminate color wheels and extend operational life. MFDS and national broadcasting regulator standards shape cinema equipment certification requirements. Seoul's digital content production district anchors demand for high-refresh-rate reference displays in post-production workflows.
DLP Projector Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in spatial computing and near-eye display architectures. The vendor base stratifies across captive component suppliers, specialized cinema manufacturers, and volume-oriented consumer brands. Three strategic archetypes dominate: MEMS fabrication specialists controlling DMD supply, professional-grade system integrators serving large-venue applications, and price-competitive brands capturing home theater and education volume. Competitive moves center on laser SKU transitions to meet regulatory chemistry restrictions and vertical integration into sealed-optical-engine manufacturing.
Within the component-tier, Texas Instruments Inc. anchors DMD supply through captive MEMS fabrication networks. Barco NV and Optoma Corporation exemplify divergent positioning strategies—one toward specialized cinema and large-venue professional segments, the other toward aggressive price-performance competition in home theater and short-throw categories. These three entities represent the span from upstream component control through premium system integration to volume consumer positioning.
| Leading Market Players |
|---|
| Texas Instruments Inc. |
| Barco NV |
| Optoma Corporation |
| BenQ Corporation |
| NEC Display Solutions |
| Digital Projection Ltd. |
| ViewSonic Corporation |
| Christie Digital Systems |
| Panasonic Corporation |
| Others |
Supply Flow & Price Mechanics
Optical engine thermal engineering talent concentration in Bavaria and Dallas-Fort Worth feeds directly into pricing-tier spreads, as laser phosphor system design competencies command wage premiums that propagate through premium cinema and large-venue product lines while commoditized single-chip assembly in coastal China enables aggressive economy-tier positioning.
Pricing Analysis
Distributor margin layers absorb 15-25 points before integrator consortia negotiate volume discounts for education and enterprise fleets. Three-tier pricing structure across premium RGB laser cinema systems, standard laser phosphor corporate units, and economy lamp-based education SKUs separates buyers by certification grade and after-sales bundling intensity. Cost compression in the lamp-based tier is intensifying because EPA energy-efficiency disqualification from federal schedules forces fire-sale inventory liquidation. Education procurement cooperatives exhibit highest price sensitivity, while entertainment venue operators prioritize uptime guarantees over capital expenditure.
Supply Chain Analysis
Dual-sourcing requirements from projector OEMs outside the Texas Instruments licensing network face qualification barriers that extend component validation timelines. DMD chip fabrication draws from captive MEMS facilities in Texas and selected Asian foundries, while rare earth magnet processing for color wheel motors rests on Chinese neodymium and dysprosium supply. Single-source vulnerability in micromirror arrays creates tariff-immune but contract-locked supply risk. Distribution runs through AV integrator consortia and direct OEM relationships to end-use verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU RoHS mercury restrictions and EPA energy-efficiency thresholds are systematically disqualifying legacy lamp architectures from institutional procurement channels, forcing accelerated capital redeployment toward solid-state illumination.
For Market Incumbents: Extend laser SKU coverage into mid-lumen education tiers before provincial Chinese bureaus consolidate specifications around GB-compliant alternatives. Captive MEMS fabrication anchors component cost control against DMD supply concentration risk from single-source dependency. Sealed-optical-engine manufacturing integration preserves margin pools as service contract pricing compresses. For New Entrants and Emerging Players: Launch via white-label arrangements with established integrator consortia serving Sichuan and Shaanxi education authorities. Tier-two Chinese city penetration offers the most penetrable procurement window as provincial AV standard consolidation opens mid-lumen laser tenders. Spatial computing headset integration for near-eye display architectures provides a defensible adjacent application with divergent competitive dynamics. For Investors and Strategic Acquirers: Valuations sit cheapest among lamp-dependent component suppliers facing accelerated obsolescence schedules. Five-to-ten year viability hinges on laser transition completion rates and sealed-engine manufacturing scale attainment. Watch for Texas Instruments licensing network expansion announcements as inflection indicators for competitive entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Laser SKU Transition Acceleration | EPA and RoHS disqualification of lamp-based systems from federal and EU public tenders forces portfolio restructuring. |
| Sealed-Optical-Engine Manufacturing Scale-Up | Cinema and large-venue reliability demands favor vendors with in-house fluorescence wheel and thermal management capabilities. |
| Integrator Consortium Partnership | OMNIA Partners and E&I Cooperative Services aggregation of education demand extracts volume pricing and warranty standardization. |
| RGB Pure Laser Cinema Retrofit | Saudi and South Korean premium theater chains eliminate color wheels and extend operational life beyond thirty thousand hours. |
| Spatial Computing Display Integration | Convergence with near-eye architectures for simulation and training opens adjacent revenue streams outside traditional projection. |
Methodological Framework
Multiple input streams — projector OEM procurement directors, cinema chain technical operations leads, education bureau AV specification officers, and semiconductor foundry planning managers — were reconciled against customs shipment records, EPA ENERGY STAR certification databases, and SAMR GB standards disclosure filings. Secondary validation drew from Texas Instruments SEC disclosures, Barco and Optoma annual reports, and trade flow analysis across major assembly hubs. Bottom-up unit shipment modeling and top-down value reconciliation triangulated segment-level estimates.
Data-stream reconciliation across the projection horizon applied product-type, illumination architecture, and end-use workflow segmentation with regional regulatory cluster differentiation. CAGRs were derived from replacement cycle analysis, fleet aging profiles, and procurement centralization trends. Forecast inputs incorporated EPA schedule disqualification timelines, EU RoHS mercury phase-out enforcement windows, and Chinese provincial education consolidation schedules.
Several conditions sit outside the modeled scope, including geopolitical disruption to rare earth magnet supply chains, breakthrough flat-panel display cost reductions above ten thousand lumens, and unilateral Texas Instruments licensing policy shifts. Deviation in EPA or SAMR enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Low Power Display Market
Display Technologies
Display Material Market
Display Technologies
Global Projector Market
Display Technologies
Mono LCD Displays Market
Display Technologies
Electrochromic Window Market
Display Technologies
Phosphor Screen Market
Display Technologies
Plasma Display Module Market
Display Technologies
Dot-Matrix LCD Modules Market
Display Technologies
Global Center Stack Display Market
Display Technologies
Global Smartphone Display Panel Market
Display Technologies
Transparent Digital Signage Market
Display Technologies
Computer Monitor Market
Display Technologies
1440p Gaming Monitors Market
Display Technologies
Smartphone Display Market
Display Technologies
Electroluminescent Display Market
Display Technologies
Paper-Thin Display Market