
 Large Industrial Displays Market | 2026-2036
Large Industrial Displays Market Size, Share, and Industry Trends Forecast 2026-2036
Large Industrial Displays Market Outlook
Embedded software engineering talent is rotating toward industrial human-machine interface development, tightening the labor pool for legacy automation vendors. Siemens AG leverages its digital twin software stack to bind display hardware with predictive maintenance workflows. Rockwell Automation, Inc. anchors its position through FactoryTalk visualization platforms that dominate North American automotive assembly lines. Samsung Electronics Co., Ltd. competes by extending its semiconductor-grade panel expertise into high-brightness factory-floor installations.
Large industrial displays are ruggedized visual output devices engineered for continuous operation in harsh environments, typically rated for wide temperature ranges, shock resistance, and IP65 or higher ingress protection against dust and moisture. These systems render process data, alarm states, and control interfaces to operators in manufacturing plants, transportation hubs, and critical infrastructure facilities. LED product types dominate volume shipments due to superior luminance and longevity in 24/7 operational settings, while OLED panels command premium positioning where contrast ratio and viewing angle flexibility justify higher procurement costs. Touchscreen technology leads interface adoption across manufacturing end users, though 4K resolution is displacing standard HD in control rooms requiring granular schematic visibility.
FCC Part 15 emissions limits in the United States and CE marking requirements under the EU Electromagnetic Compatibility Directive constrain product design and market access for non-compliant manufacturers. IEC 62443 cybersecurity standards for industrial automation systems are reshaping firmware architecture and network segmentation protocols in display controllers. Stakeholders must monitor evolving functional safety certifications as IEC 61508 and sector-specific derivatives expand from process industries into discrete manufacturing deployments.
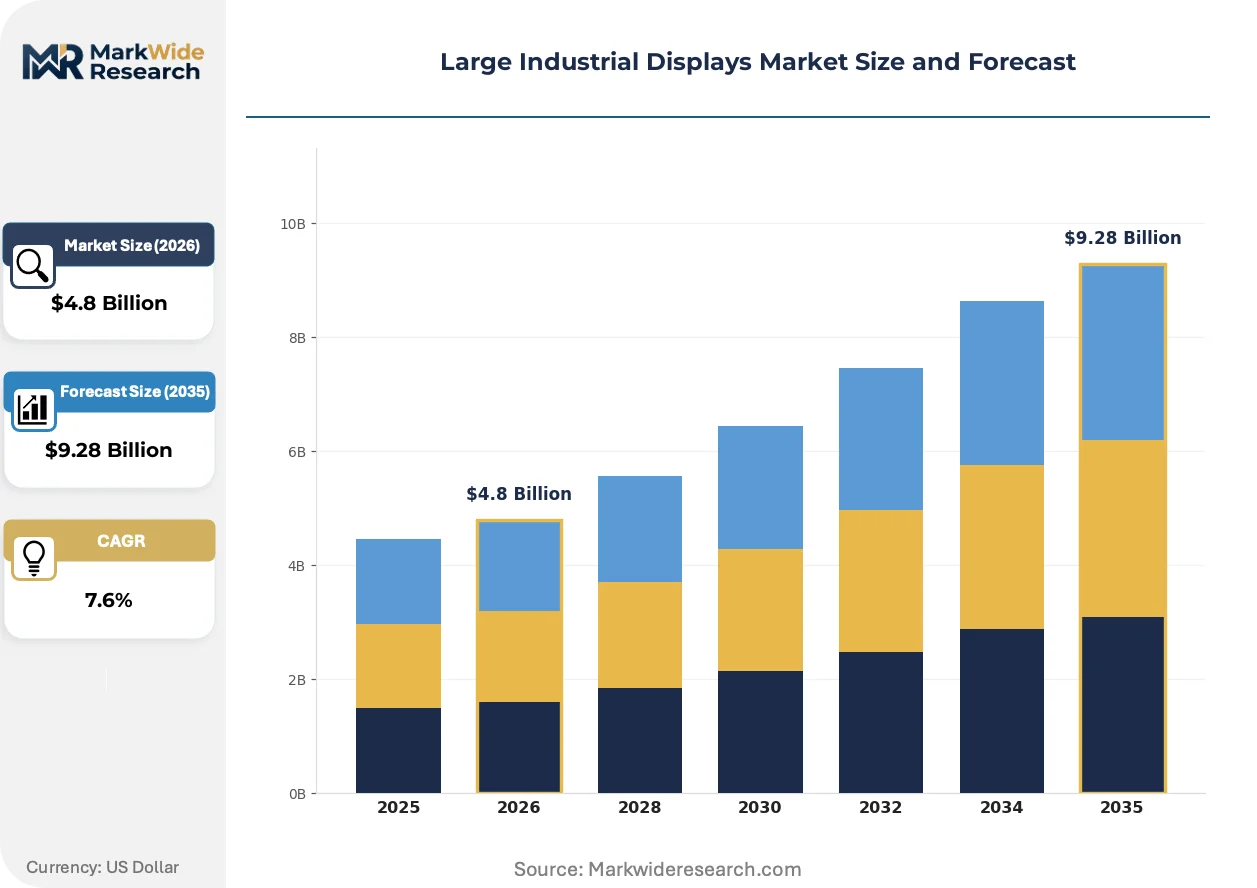
Market Dynamics
Industrial display procurement is consolidating around cybersecurity-hardened architectures as IEC 62443 mandates penetrate discrete manufacturing, forcing vendors to reengineer firmware stacks and network segmentation protocols.
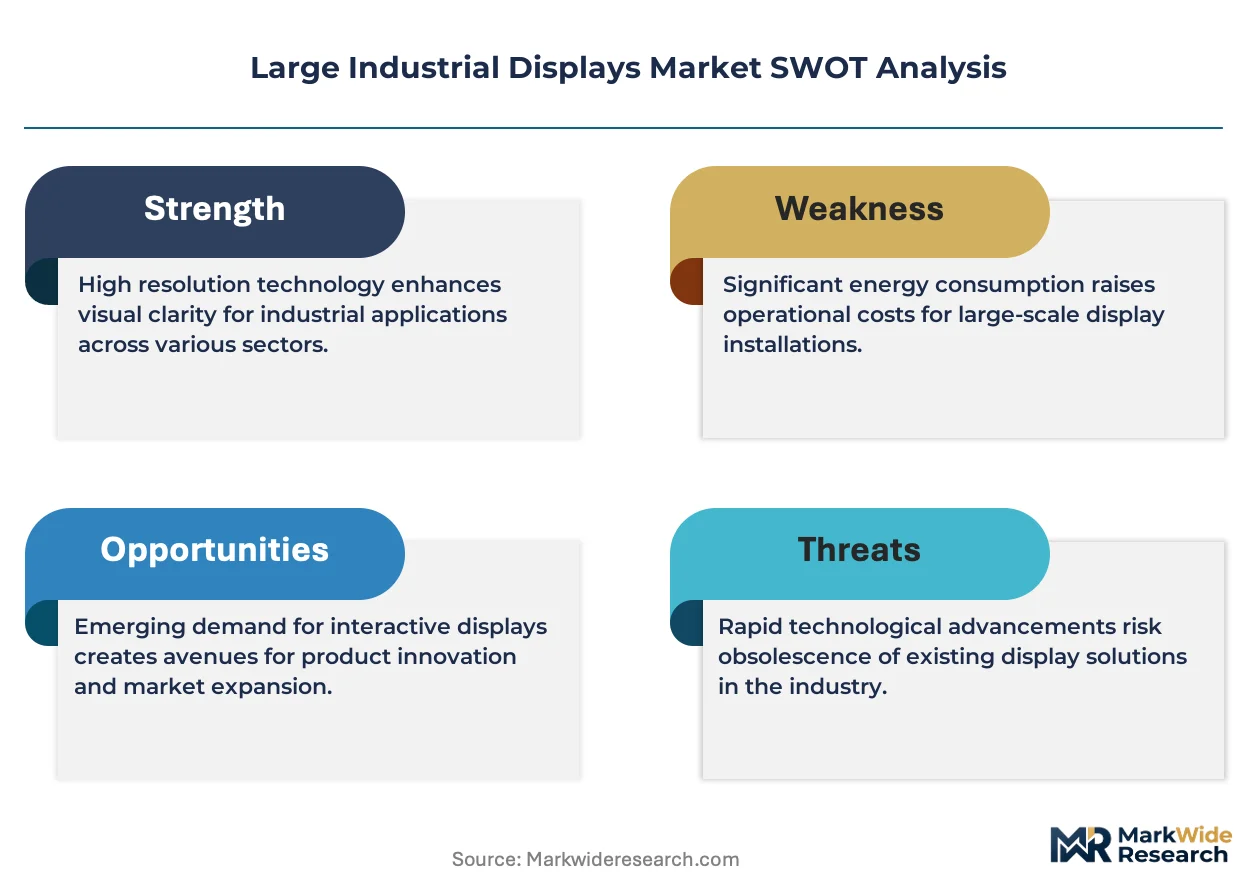
Growth Catalysts
- Semiconductor fabrication investments:Germany, Japan, and the United States are expanding cleanroom visualization infrastructure for real-time wafer monitoring and yield optimization.
- IEC 61508 functional safety expansion:Sector-specific derivatives are migrating from process industries into automotive and electronics assembly lines, mandating SIL-rated display controllers.
- 4K resolution displacement:Control room operators in critical infrastructure facilities are upgrading from standard HD to ultra-high-definition panels for granular schematic visibility.
Market Restraints
- Panel supply concentration:Semiconductor-grade substrate fabrication clusters in South Korea and Taiwan create single-source vulnerability for high-brightness industrial OLED procurement.
- NEMA 4X certification costs:Ingress protection testing and electromagnetic compatibility validation add 18-24 months to product qualification cycles.
- Embedded software talent scarcity:Industrial human-machine interface development is competing with consumer electronics for firmware engineering capacity.
Strategic Opportunities
- India manufacturing corridors:PLI scheme incentives for electronics assembly are creating first-mover advantage for ruggedized display deployment in greenfield automotive plants.
- Predictive maintenance integration:Digital twin visualization platforms are converging with edge analytics to create subscription-based display-plus-software bundles.
- EU Green Deal procurement rules:Ecodesign requirements for energy-efficient industrial equipment are favoring LED over legacy LCD in public infrastructure tenders.
Industry Challenges
- Cybersecurity firmware architecture:IEC 62443 compliance demands secure boot capabilities and encrypted communication stacks that legacy controller hardware cannot accommodate.
- Multi-standard certification overlap:Simultaneous FCC Part 15, CE marking, and country-specific electromagnetic compatibility testing fragments engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Large Industrial Displays Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, LCD, OLED, Projection Technology: Touchscreen, 4K, 8K, Ultra HD End User: Manufacturing, Retail, Transportation, Healthcare Installation: Wall-mounted, Floor-standing, Ceiling-mounted, Portable |
| Companies Covered | Advantech Co., Ltd., Siemens AG, Rockwell Automation, Inc., Panasonic Holdings Corporation, Samsung Electronics Co., Ltd., AU Optronics Corporation, Winmate Inc., Schneider Electric SE, Kontron AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Large Industrial Displays Market Strategic Shifts
Display interface technology is bifurcating between touch-native architectures for factory-floor mobility and specialized non-touch systems for hazardous environment safety compliance.
Optical bonding is supplanting traditional air-gap lamination in high-vibration industrial settings. Mining equipment manufacturers and offshore platform operators are specifying bonded glass-to-panel construction to eliminate condensation and parallax errors. This shift is compressing margins for display integrators lacking in-house optical processing capabilities.
CE marking requirements under the EU Electromagnetic Compatibility Directive are tightening radiated emission limits for industrial computing peripherals. German automotive OEMs are now requiring display suppliers to pre-certify against amended EN 55032 Class A limits before design-in approval. Panel vendors with existing test infrastructure are capturing specification control from smaller competitors.
Specification authority is migrating from plant engineering departments to centralized procurement functions with enterprise cybersecurity mandates. North American automotive assemblers are consolidating vendor lists to three pre-approved display platforms with pre-validated firmware architectures. Tier-two machine builders are losing direct supplier relationships as OEMs enforce captive supply agreements for human-machine interface components.
Large Industrial Displays Market Segmentation
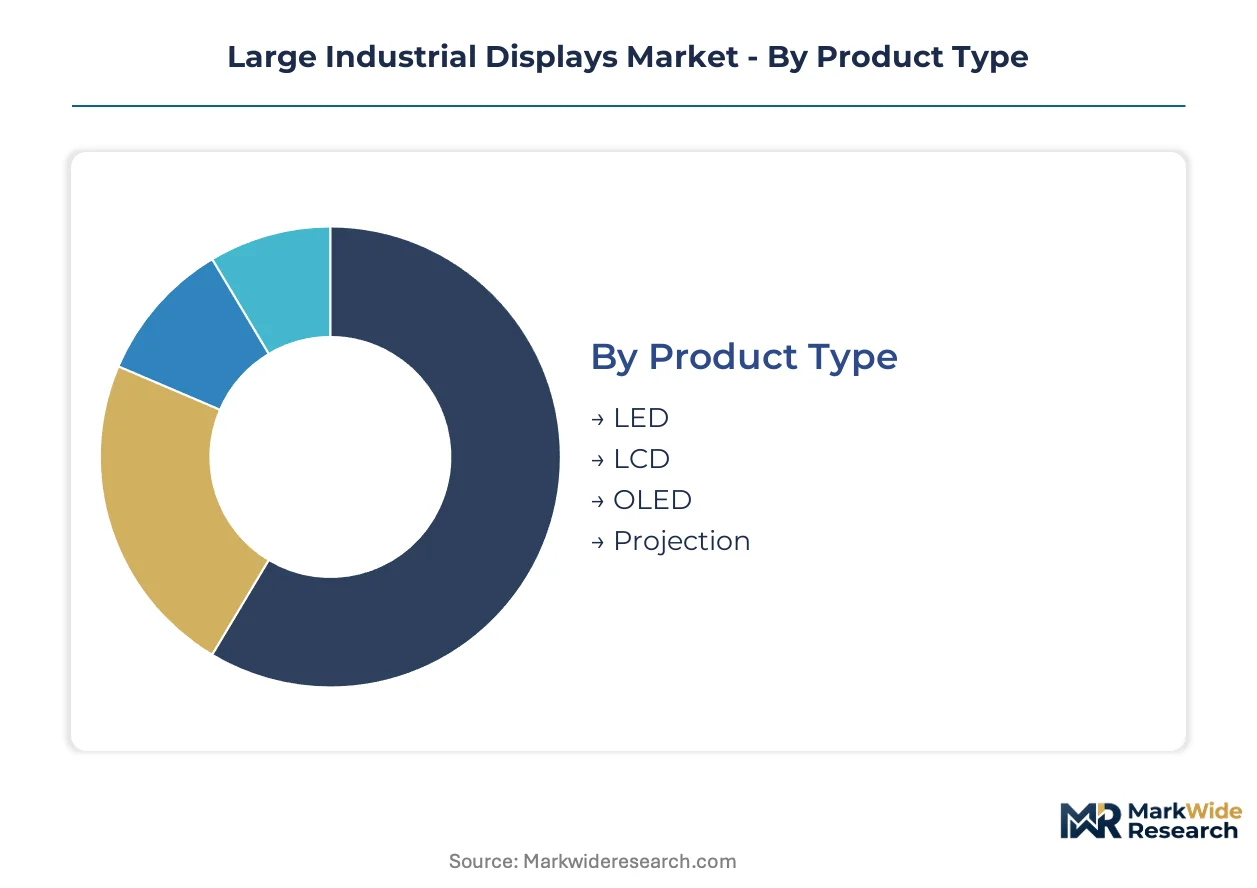
Industrial display procurement decisions cascade through certification requirements, interface specifications, and mounting constraints. Each segmentation dimension carries distinct regulatory and operational implications for facility operators.
Product Type:
NEMA 4X and IEC ingress protection ratings differentiate panel technologies for harsh environment deployment.
- LED:Solid-state backlighting delivers 50,000+ hour operational lifespans in continuous-duty manufacturing settings. German automotive assembly plants and Japanese semiconductor fabs specify LED panels for 24/7 process visualization due to luminance stability and minimal heat generation.
- LCD:Twisted-nematic and in-plane switching architectures persist in cost-sensitive applications where viewing angle constraints are manageable. Legacy industrial control rooms in United States municipal water treatment facilities continue LCD refresh cycles on decade-long replacement schedules.
- OLED:Organic emissive layers enable infinite contrast ratios for dark-field schematic rendering in cleanroom environments.
- Projection:Laser phosphor and DLP systems address ultra-large format requirements exceeding direct-view panel dimensional limits.
LED handles the majority of throughput; OLED is the fastest mover on share.
Technology:
Interface resolution and input modality determine operator workflow efficiency across control room and floor-mounted deployments.
- Touchscreen:Projected capacitive and resistive layers enable direct manipulation of HMI elements without peripheral input devices. Manufacturing floor operators in United States automotive plants prioritize touchscreen panels for mobile workflow flexibility.
- 4K:3840×2160 pixel density resolves fine-grained P&ID schematics and multi-window process dashboards. German chemical processing control rooms are displacing standard HD with 4K panels to reduce operator eye strain during 12-hour shifts.
- 8K:7680×4320 resolution addresses specialized medical imaging and semiconductor mask inspection applications.
- Ultra HD:Marketing designation encompassing 4K and 8K standards for procurement specification alignment.
Touchscreen commands the largest installed base; 4K is climbing the fastest on new deployment share.
End User:
Operational environment severity and regulatory exposure shape display specification requirements across vertical markets.
- Manufacturing:Discrete and process automation applications demand IP65+ enclosures, wide temperature operation, and vibration resistance. Japanese electronics assembly lines and German machine tool builders specify ruggedized panels for coolant mist and metal particulate exposure.
- Retail:Digital signage and customer-facing kiosks prioritize aesthetic integration and brightness performance over industrial sealing. United States quick-service restaurant chains deploy high-brightness panels for drive-thru menu boards.
- Transportation:Railway signaling, airport FIDS, and marine bridge systems require specialized electromagnetic compatibility and shock certification.
- Healthcare:Surgical displays and patient monitoring systems demand IEC 60601 medical electrical equipment compliance.
Manufacturing absorbs the highest unit volume; Healthcare is gaining share fastest on regulatory upgrade cycles.
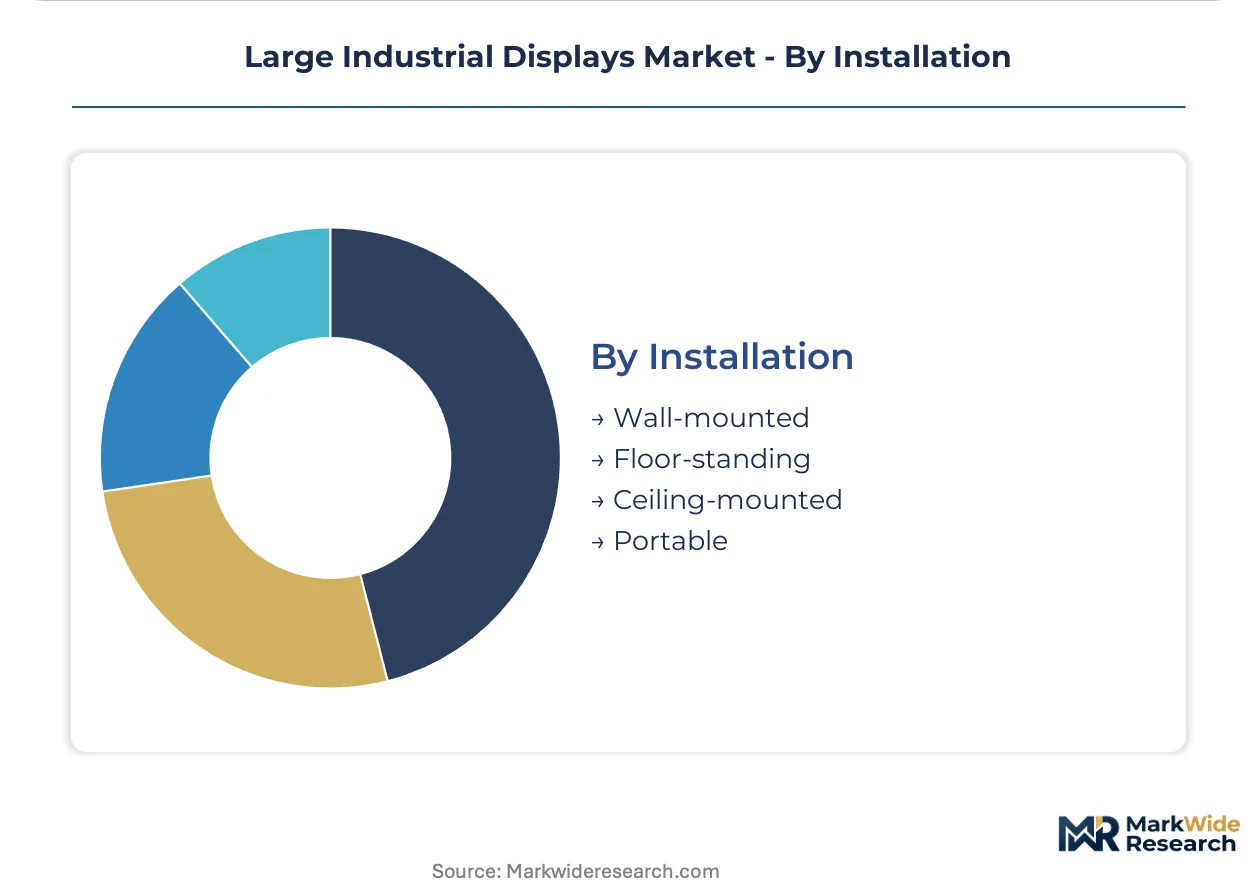
Installation:
Mechanical mounting configuration dictates enclosure engineering and service accessibility for facility maintenance teams.
- Wall-mounted:Flush or articulating arm installations maximize floor space in congested control rooms. German automotive OEMs standardize on VESA-compatible wall mounts for uniform facility aesthetics.
- Floor-standing:Pedestal and kiosk enclosures protect electronics in high-traffic manufacturing corridors. United States food and beverage processors specify stainless steel floor stands for washdown compliance.
- Ceiling-mounted:Overhead suspension enables operator viewing without sightline obstruction in assembly line configurations.
- Portable:Mobile carts and battery-powered units support temporary deployment and maintenance troubleshooting workflows.
Wall-mounted represents the dominant configuration; Portable is expanding most quickly on flexible manufacturing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC Part 15 emissions standards in the United States establish the baseline electromagnetic compatibility framework that industrial display vendors must satisfy for market access. German automotive OEMs and Japanese semiconductor fabricators are tightening procurement specifications beyond baseline compliance. Facility operators across four major manufacturing economies are consolidating vendor lists around pre-certified platform suppliers.
United States
Automotive assembly plants in Michigan and Tennessee are upgrading control room visualization infrastructure to 4K resolution panels for granular schematic visibility. OSHA workplace safety mandates are accelerating touchscreen displacement of mechanical pushbutton interfaces on factory floors. Dallas-Fort Worth logistics hubs are deploying ruggedized ceiling-mounted displays for real-time freight tracking across distribution corridors.
Germany
Machine tool builders in Stuttgart and Munich are specifying IP65-rated LED panels for coolant mist and metal particulate exposure on shop floors. CE marking requirements under the EU Electromagnetic Compatibility Directive are tightening radiated emission limits for computing peripherals. Bavarian automotive OEMs now require EN 55032 Class A pre-certification before design-in approval for human-machine interface components.
Japan
Semiconductor fabrication facilities in Kumamoto and Hiroshima are expanding cleanroom visualization infrastructure for real-time wafer monitoring. METI industrial standards are mandating IEC 62443 cybersecurity compliance for automation system components. Nagoya electronics assembly lines are standardizing on optical-bonded displays to eliminate condensation in high-vibration mounting configurations.
South Korea
Display panel substrate fabrication clusters in Gyeonggi Province are creating single-source vulnerability for high-brightness industrial OLED procurement. The Ministry of Trade, Industry and Energy is channeling support toward domestic supply chain resilience for critical manufacturing components. Seoul-based system integrators are capturing specification authority from tier-two machine builders through captive supply agreements.
India
PLI scheme incentives for electronics assembly are creating first-mover advantage for ruggedized display deployment in greenfield automotive plants near Chennai and Pune. BIS certification requirements are extending product qualification timelines for imported industrial computing equipment. Gujarat manufacturing corridors are consolidating procurement around three pre-approved display platforms with pre-validated firmware architectures.
Large Industrial Displays Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the industrial display value chain. The market structure consolidates around diversified automation conglomerates with captive software ecosystems and specialized panel fabricators with semiconductor-grade manufacturing expertise. Three strategic archetypes dominate competitive positioning: integrated automation platform vendors, display panel specialists extending into industrial applications, and ruggedized system integrators serving niche environment specifications. M&A activity concentrates on firmware engineering capabilities and optical bonding processing infrastructure.
Within the integrated automation tier, Siemens AG and Rockwell Automation, Inc. exemplify platform vendors binding display hardware with predictive maintenance workflows and FactoryTalk visualization ecosystems. Among East Asian panel specialists, Samsung Electronics Co., Ltd. and AU Optronics Corporation occupy positions leveraging semiconductor-grade substrate expertise for high-brightness factory-floor installations. These named entities represent archetype anchors rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Advantech Co., Ltd. |
| Siemens AG |
| Rockwell Automation, Inc. |
| Panasonic Holdings Corporation |
| Samsung Electronics Co., Ltd. |
| AU Optronics Corporation |
| Winmate Inc. |
| Schneider Electric SE |
| Kontron AG |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between German automotive OEMs and South Korean panel suppliers lock in both semiconductor-grade substrate access and price visibility across multi-year procurement windows. These contracts insulate volume buyers from spot-market volatility in high-brightness OLED procurement while embedding IEC 62443 cybersecurity compliance costs into fixed unit pricing.
Pricing Analysis
Price spreads between German and Indian procurement markets exceed forty percent for identically specced IP65-rated LED panels, reflecting certification burden differentials and logistics overhead. Three-tier pricing structure across premium OLED, standard LED, and economy LCD levels stratifies by luminance stability and ingress protection ratings. Cost compression in the LCD tier is intensifying because legacy control room refresh cycles are extending beyond decade-long replacement schedules. Municipal water treatment operators in the United States exhibit the highest price sensitivity, while Japanese semiconductor fabricators prioritize luminance stability over unit cost.
Supply Chain Analysis
Inventory buffers for semiconductor-grade display substrates have compressed to twelve-week horizons as Taiwanese and South Korean fabrication clusters prioritize consumer electronics allocation. Industrial panel production draws from indium tin oxide, polarizer films, and driver integrated circuits as critical inputs. Single-source vulnerability concentrates in Gyeonggi Province substrate fabrication, where Ministry of Trade, Industry and Energy interventions are attempting supply chain resilience builds. Distribution runs through captive supply agreements that German automotive OEMs enforce on tier-two machine builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as IEC 61508 functional safety mandates migrate from process industries into discrete manufacturing, forcing replacement demand across installed base.
For Market Incumbents: Compound platform stickiness by binding display hardware with predictive maintenance software subscriptions that embed Siemens AG-style digital twin visualization. Defend against South Korean panel specialists extending semiconductor-grade expertise by accelerating optical bonding capability builds in-house. Certification investment in pre-validated IEC 62443 firmware architectures captures specification authority from centralized procurement functions. For New Entrants and Emerging Players: Differentiate on cybersecurity-hardened controller design for mid-sized automotive suppliers losing direct supplier relationships under captive supply agreements. White-space targets cluster in India PLI scheme corridors where greenfield automotive plants lack established vendor relationships, and in portable display configurations for flexible manufacturing adoption. Go-to-market angle should emphasize rapid BIS certification completion against fragmented import qualification timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated automation platform vendors with captive software ecosystems rather than standalone panel fabricators. Long-term viability favors diversified conglomerates binding hardware with predictive maintenance workflows over pure-play display specialists. Acquisition target archetype: ruggedized system integrators with in-house optical bonding infrastructure. Signal to watch is consolidation of vendor lists to three pre-approved platforms among North American automotive assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Firmware Certification | IEC 62443 pre-validation captures specification authority from centralized procurement functions at German OEMs. |
| Optical Bonding Capability Build | In-house glass-to-panel processing eliminates margin compression for mining and offshore platform specifications. |
| Software Subscription Bundling | Digital twin visualization platforms create recurring revenue streams that hardware-only vendors cannot replicate. |
| India Manufacturing Corridor Entry | PLI scheme incentives create first-mover positioning before vendor consolidation locks in three-platform standards. |
| Backward Integration into Driver ICs | Upstream control over controller hardware enables secure boot capabilities that legacy architectures cannot accommodate. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, customs and trade data, IEC certification registries, and OEM procurement disclosures. Plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads provided operational perspective on specification migration and replacement cycles. Bottom-up unit shipment estimates triangulate against top-down value projections derived from disclosed contract values and vendor revenue segmentation.
Segmentation dimensions modeled include product type, interface technology, end-use vertical, and mounting configuration across the projection horizon. CAGRs derive from regression analysis of historical replacement cycles, overlaying regulatory mandate acceleration effects and semiconductor fabrication investment trajectories. Forecast inputs incorporate cleanroom visualization infrastructure buildouts in Japan and Germany, plus IEC 61508 SIL-rated controller adoption curves in automotive assembly.
Decision-makers should treat outputs as directional under assumptions of sustained semiconductor fabrication investment and stable electromagnetic compatibility regulatory frameworks; material deviation in panel substrate allocation or tariff exposure would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Transparent Digital Signage Market
Display Technologies
OLED Microdisplay Market
Display Technologies
Global Portable Monitor Market
Display Technologies
Paper-Thin Display Market
Display Technologies
Global Transparent Display Market
Display Technologies
AMOLED Substrate Market
Display Technologies
Virtual Retinal Display (VRD) Market
Display Technologies
OLED Laptops Market
Display Technologies
Electronic Display Market
Display Technologies
TFT LCD Panel Market
Display Technologies
Electronic Paper Display (EPD) Market
Display Technologies
Visual Computing Market
Display Technologies
Global 5K Display Resolution Market
Display Technologies
Europe Microdisplay Market
Display Technologies
Laptop Panels Market
Display Technologies
Glasses Free 3D Display Market