
 Display Glass Substrate Market | 2026-2036
Display Glass Substrate Market Size, Share, and Industry Trends Forecast 2026-2036
Display Glass Substrate Market Analysis
Automotive display buyers is collapsing into the dominant growth archetype as dashboard digitization and head-up display penetration accelerate across vehicle tiers. Corning Incorporated leverages its fusion draw process to sustain unmatched thin-glass yields for curved automotive panels. BOE anchors massive Gen 10.5 capacity in Hefei and competes aggressively on price for LCD substrates bound for television OEMs. Nippon Electric Glass specializes in alkali-free borosilicate formulations that dominate high-temperature polysilicon backplane applications.
Display glass substrate denotes a precision-manufactured sheet of borosilicate or soda-lime glass engineered to thickness tolerances below 0.1 millimeter, serving as the structural foundation upon which thin-film transistor arrays and organic or liquid-crystal layers are deposited. The substrate must exhibit thermal stability above 600 degrees Celsius, minimal thermal shrinkage, and near-zero alkali ion migration to prevent pixel degradation during fabrication. OLED substrates command premium positioning due to stringent thermal and barrier requirements for flexible and foldable panel architectures, while LCD glass remains volume-dominant though margin-compressed by capacity overhang. Thin film technology leads growth velocity as roll-to-roll and solution-processed deposition methods gain traction for lightweight display modules.
China's MIIT enforces GB standards on display glass dimensional precision and chemical durability, while South Korea's METI-aligned industrial policy channels subsidies toward domestic substrate supply chain resilience. REACH in Europe restricts cadmium and lead content in glass compositions, compelling reformulation investments by SCHOTT and AGC Inc. for EU-bound automotive display exports. Stakeholders must monitor polysilicon price volatility and thin-film encapsulation yield rates as determinants of substrate thickness roadmaps and capital allocation priorities.
Market Dynamics
Fusion-draw and float-glass furnace technologies compete for substrate thickness roadmaps as automotive display buyers demand sub-0.3 millimeter glass for curved dashboard integration, while China's dual carbon goals force energy intensity recalibration across borosilicate production lines.
Growth Catalysts
- Automotive HUD digitization:Dashboard glass area per vehicle expands threefold across premium and mass-market tiers, pulling ultra-thin substrate specifications into standard procurement cycles.
- REACH reformulation mandates:Cadmium and lead restrictions in Europe compel alkali-free borosilicate investments that yield superior thermal stability for high-temperature polysilicon backplanes.
- South Korean panel cluster concentration:Domestic substrate supply chain resilience policies channel capital toward captive glass-melting capacity adjacent to Gen 8.5 and Gen 10.5 fabs.
Market Restraints
- Natural gas price volatility:Float glass furnace operations face margin compression when energy input costs spike, particularly affecting soda-lime substrate producers without long-term fuel hedging.
- Fusion-draw yield limitations:Thin-glass manufacturing below 0.1 millimeter exhibits defect-rate escalation that constrains viable output for flexible OLED architectures.
- Polysilicon supply concentration:Semiconductor-grade silicon feedstock for thin-film transistor arrays concentrates among limited refiners, creating input cost transmission risk.
Strategic Opportunities
- India display fab buildout:PLI scheme subsidies for panel manufacturing create first-mover substrate supply contracts as domestic glass-melting capacity remains underdeveloped.
- Roll-to-roll deposition convergence:Solution-processed organic electronics enable polymer substrate alternatives that bypass rigid glass thermal processing constraints.
- EU F-Gas Regulation phase-down:Fluorinated gas restrictions for etching processes accelerate dry-process equipment upgrades that favor thinner glass handling systems.
Industry Challenges
- High-temperature process engineering talent:Borosilicate melting and precision forming require specialized furnace operators whose training pipelines lag capacity expansion timelines.
- Gen 10.5 equipment commissioning cycles:Substrate size escalation to 2940mm × 3370mm demands 18-24 month qualification periods that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Display Glass Substrate Market |
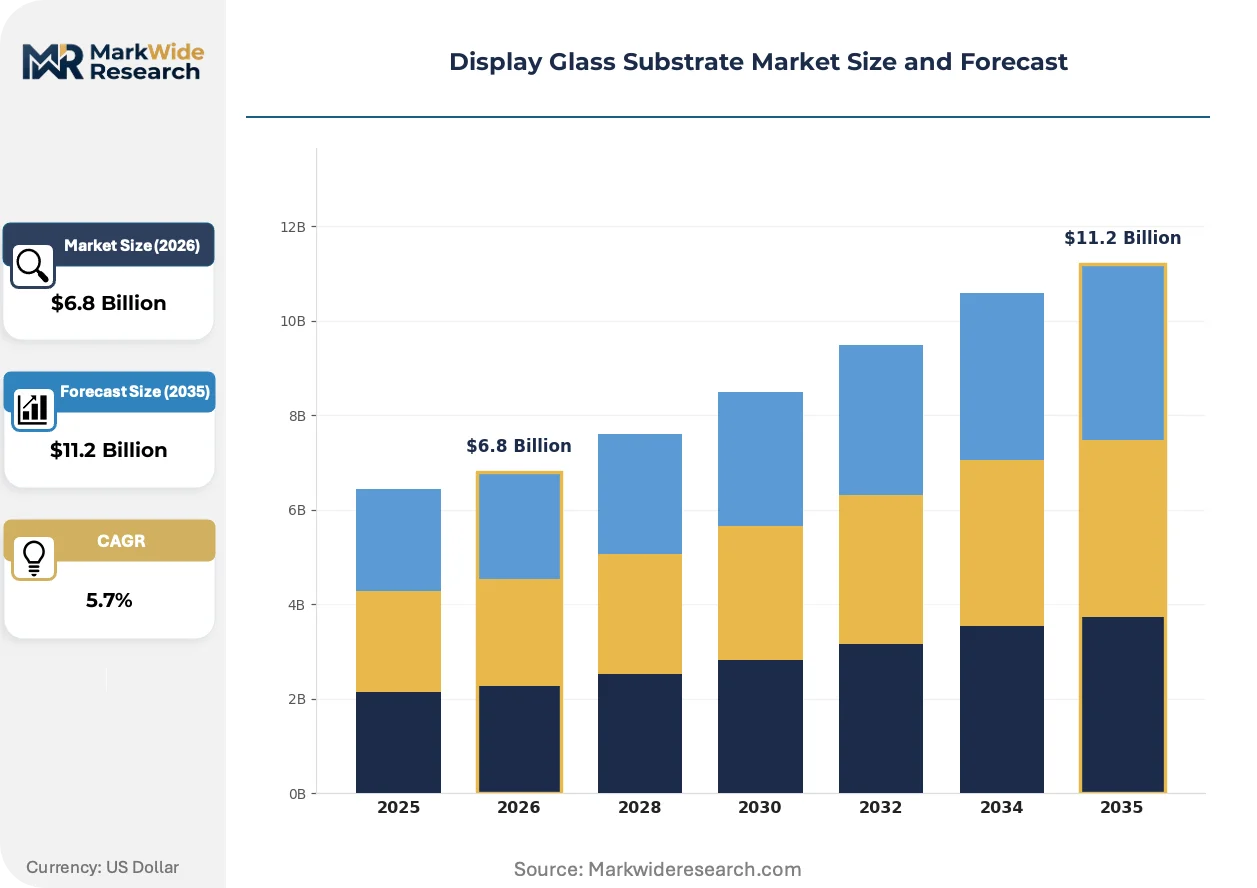
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
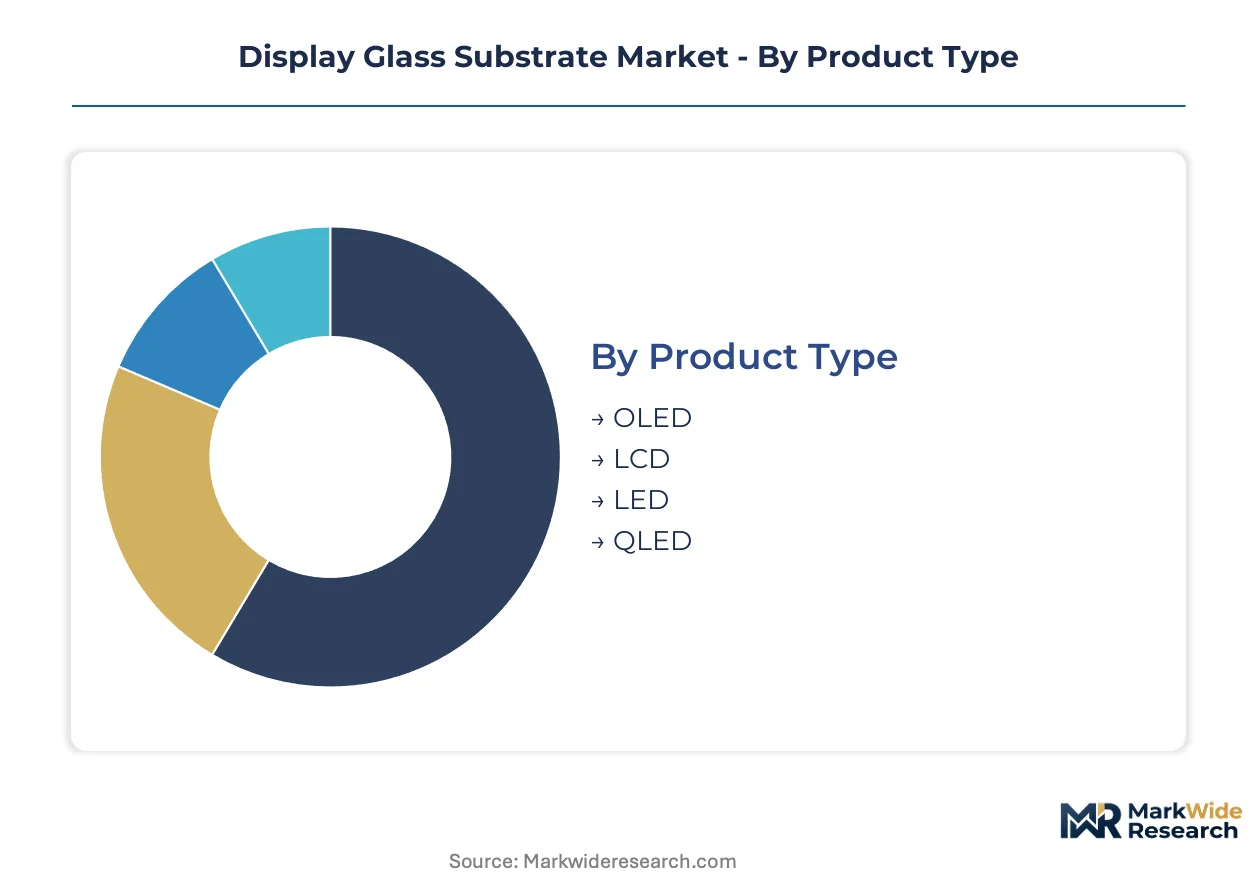
| Segmentation | Product Type: OLED, LCD, LED, QLED Technology: Thin Film, Bulk Glass, Coated Glass, Laminated Glass Application: Television Displays, Smartphone Screens, Monitors, Automotive Displays End User: Consumer Electronics, Industrial, Healthcare, Retail |
| Companies Covered | Samsung Electronics, LG Innotek, Corning Incorporated, SCHOTT, Asahi Glass Co Ltd, AGC Inc., BOE, Plan Optik AG, Nippon Electric Glass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Display Glass Substrate Market Emerging Trajectories
Substrate thickness roadmaps diverge as OLED flexible architectures demand polymer alternatives while automotive rigid panels pursue ever-thinner glass for weight reduction, creating parallel technology investment tracks.
Thin-film encapsulation is fragmenting barrier-layer deposition approaches across the display stack. Atomic layer deposition and multi-layer sintered coatings compete for moisture-ingress protection in foldable panels. Automotive OEMs adopt hybrid glass-polymer laminates that sacrifice optical purity for impact resistance. The substrate supply base is fragmenting into specialty thin-glass, chemically strengthened, and polymer-replacement camps with incompatible equipment footprints.
China's MIIT enforces GB standards on dimensional precision and chemical durability that exceed legacy JIS benchmarks for alkali ion migration limits. Domestic panel makers must certify substrate suppliers against these specifications to qualify for state procurement contracts. Korean and Japanese glass manufacturers face reformulation costs to maintain Hefei and Suzhou fab access, compressing margin structures for LCD-bound volume grades.
Procurement consolidation among tier-one automotive display integrators forces substrate vendors to absorb warranty liability for delamination and thermal shock failures. Direct OEM contracting displaces traditional panel-maker intermediation for head-up display projects. This pattern concentrates most visibly in German premium vehicle programs where KBA certification requirements extend to substrate-level traceability documentation.
Display Glass Substrate Market Segmentation
Display glass substrate procurement splits sharply across thermal processing requirements and dimensional tolerances. Regulatory divergence between China's GB standards, Europe's REACH mandates, and South Korea's METI-aligned policies forces suppliers to maintain parallel formulation portfolios.
Product Type:
REACH cadmium restrictions and China's dual carbon goals enforce divergent purity and energy-intensity specifications across substrate chemistries.
- OLED:Alkali-free borosilicate formulations withstand polysilicon backplane processing above 600 degrees Celsius. South Korean panel clusters in Gyeonggi-do pull captive substrate capacity for flexible and foldable architectures where barrier-layer integrity is paramount.
- LCD:Soda-lime compositions dominate volume throughput but face margin compression from Gen 10.5 capacity overhang in Hefei and Suzhou. BOE's price aggression for television OEM contracts forces reformulation investments to meet MIIT GB standards on dimensional precision.
- LED:Sapphire and silicon carbide alternatives compete for direct-emission displays in industrial signage applications.
- QLED:Quantum dot enhancement layers require modified thermal expansion coefficients for cadmium-free European compliance.
LCD handles the majority of throughput; OLED is the fastest mover on share.
Technology:
Cost tiers separate precision fusion-draw outputs from commodity float-glass furnace products.
- Thin Film:Roll-to-roll deposition compatibility drives polymer substrate alternatives, though glass remains mandatory for high-temperature polysilicon processing. Solution-processed organic electronics in Japanese R&D pipelines threaten rigid glass thermal processing dominance.
- Bulk Glass:Float-glass furnace operations concentrate in China's Yangtze River Delta where natural gas hedging determines margin viability against soda-lime volume grades.
- Coated Glass:Atomic layer deposition and multi-layer sintered coatings compete for moisture-ingress protection in foldable panels.
- Laminated Glass:Hybrid glass-polymer constructions sacrifice optical purity for impact resistance in automotive HUD applications.
Bulk Glass carries the volume baseline; Thin Film is climbing the fastest on process convergence.
Application:
End-use thermal and mechanical stress profiles dictate substrate thickness roadmaps and certification requirements.
- Automotive Displays:Dashboard digitization and HUD penetration across German premium vehicle programs demand sub-0.3 millimeter glass with KBA-level traceability documentation. Corning's fusion draw process sustains unmatched thin-glass yields for curved panel integration.
- Television Displays:Gen 10.5 substrate scaling to 2940mm × 3370mm concentrates procurement among Chinese panel makers with 18-24 month equipment qualification cycles.
- Smartphone Screens:Flexible OLED architectures push thickness below 0.1 millimeter where defect-rate escalation constrains viable output.
- Monitors:Commercial and gaming segments prioritize refresh-rate performance over substrate thermal specifications.
Television Displays absorb the bulk substrate tonnage; Automotive Displays are gaining share fastest on specification premiumization.
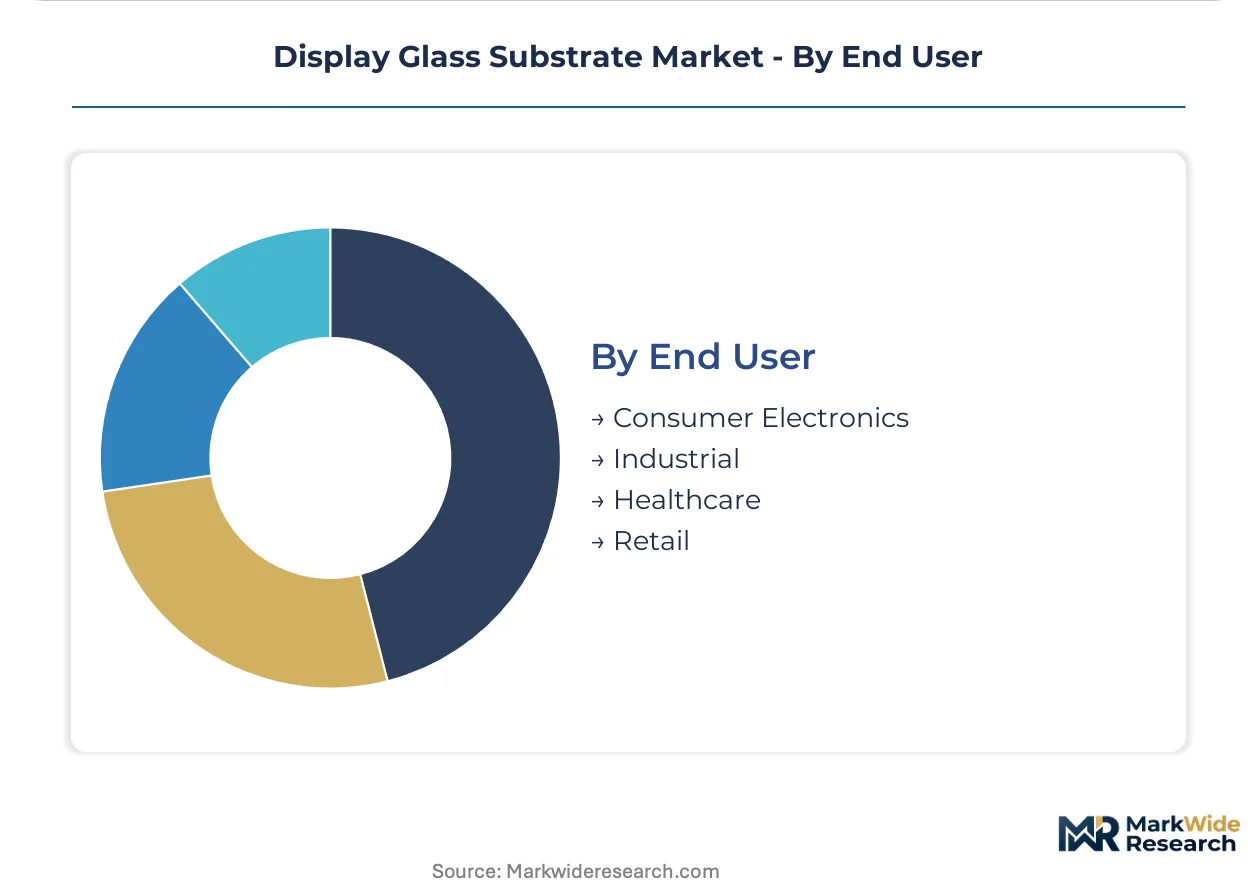
End User:
Customer procurement sophistication separates direct OEM contracting from traditional panel-maker intermediation.
- Consumer Electronics:Tier-one integrators force substrate vendors to absorb warranty liability for delamination and thermal shock failures. Procurement consolidation displaces panel-maker intermediation for premium smartphone and television programs.
- Industrial:HMI and control panel applications tolerate thicker substrates with relaxed alkali ion migration limits.
- Healthcare:Diagnostic imaging displays require ISO-certified dimensional stability for calibration consistency.
- Retail:Digital signage procurement prioritizes luminance uniformity over thermal processing margins.
Consumer Electronics commands the procurement volume; Industrial is expanding most quickly on underpenetrated HMI retrofit cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese substrate manufacturers export precision borosilicate formulations to South Korean panel clusters, while Chinese producers supply soda-lime volume grades to domestic Gen 10.5 fabs. This trade-flow pattern concentrates high-value substrate production in Northeast Asia with diverging regulatory compliance requirements.
China
MIIT GB standards on dimensional precision and chemical durability exceed legacy benchmarks for alkali ion migration limits. The dual carbon goals enforce energy intensity recalibration across borosilicate production lines in the Yangtze River Delta. Hefei and Suzhou host massive Gen 10.5 capacity where BOE anchors price-aggressive procurement for television OEM contracts.
South Korea
Gyeonggi-do panel clusters pull captive substrate capacity for flexible OLED architectures requiring barrier-layer integrity. METI-aligned industrial policy channels subsidies toward domestic supply chain resilience adjacent to Gen 8.5 and Gen 10.5 fabs. Samsung Electronics and LG Innotek concentrate demand for high-temperature polysilicon backplane specifications.
Japan
Alkali-free borosilicate specialists dominate polysilicon backplane applications above 600 degrees Celsius processing thresholds. JIS standards on thermal shrinkage and near-zero alkali ion migration shape formulation portfolios for export markets. Nippon Electric Glass and AGC Inc. maintain melting capacity serving both domestic display makers and Korean panel buyers.
Germany
KBA certification requirements extend to substrate-level traceability documentation for automotive HUD programs in premium vehicle manufacturing. REACH cadmium and lead restrictions compel reformulation investments for EU-bound automotive display exports. SCHOTT operates precision glass melting for alkali-free borosilicate serving high-temperature process requirements.
United States
Corning Incorporated leverages fusion draw process technology from New York state operations for curved automotive panel specifications. NHTSA safety standards indirectly influence substrate impact resistance requirements through tier-one automotive display integrators. The company sustains thin-glass yield advantages for sub-0.3 millimeter dashboard integration specifications.
Display Glass Substrate Market Vendor Landscape
Player mix skews toward integrated glass-ceramic specialists with captive melting capacity and precision forming expertise. The vendor base separates into volume-driven soda-lime producers and premium borosilicate specialists serving divergent thermal processing requirements. Three archetypes dominate: fusion-draw precision specialists, float-glass furnace operators, and alkali-free formulation chemists. Capacity expansion and strategic partnerships constitute the primary competitive moves as substrate size escalation demands 18-24 month equipment qualification cycles.
Among integrated specialists, Corning Incorporated, Nippon Electric Glass, and AGC Inc. occupy positions spanning precision thin-glass and high-temperature formulation segments. Corning exemplifies the fusion-draw archetype with unmatched yields for sub-0.3 millimeter specifications. Nippon Electric Glass anchors alkali-free borosilicate expertise for polysilicon backplane applications. AGC Inc. sits within the diversified glass-ceramic portfolio tier serving both display substrate and adjacent industrial markets. BOE represents the captive scale-driven model with massive Gen 10.5 integration in Hefei.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Innotek |
| Corning Incorporated |
| SCHOTT |
| Asahi Glass Co Ltd |
| AGC Inc. |
| BOE |
| Plan Optik AG |
| Nippon Electric Glass |
| Others |
Supply Flow & Price Mechanics
KBA certification requirements for automotive HUD traceability gate both supplier qualification and price tier access simultaneously. MIIT GB standards on alkali ion migration enforce parallel formulation portfolios that fragment pricing power across Chinese domestic and export-bound substrate grades.
Pricing Analysis
Gen 10.5 substrate scaling commands premium positioning against Gen 8.5 legacy capacity and pre-qualification Gen 11 development lines. Contract-based long-term offtake dominates volume procurement, with price differentiation driven by certification grade against MIIT GB standards and volume scale commitments. Cost compression in soda-lime LCD grades intensifies because BOE's Hefei price aggression forces margin recalibration across Yangtze River Delta float-glass furnace operators. Television OEMs exhibit highest price sensitivity; automotive HUD integrators show lowest sensitivity due to KBA-mandated traceability premiums.
Supply Chain Analysis
Natural gas pipeline terminus constraints at Yangtze River Delta ports underwrite supply vulnerability for float-glass furnace operations. Production concentrates in China, South Korea, and Japan. Borosilicate melting draws from semiconductor-grade silica sand, high-purity soda ash, and natural gas feedstock. Single-source vulnerability concentrates in polysilicon backplane material supply for OLED thermal processing. Distribution runs through captive glass-melting facilities adjacent to Gen 8.5 and Gen 10.5 panel fabs with direct OEM contracting displacing traditional intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Substrate thickness roadmaps diverging across automotive rigid and OLED flexible architectures fragment incumbent dominance into specialty camps. Dashboard digitization and foldable panel proliferation create distinct qualification niches for formulation specialists and precision forming technologists.
For Market Incumbents: Shield fusion-draw yield advantages by accelerating sub-0.3 millimeter qualification for German premium automotive programs before float-glass furnace operators achieve comparable thin-glass output. Absorb warranty liability for thermal shock failures to lock direct OEM contracting relationships. Backward integration into high-purity silica sand mining secures feedstock cost control against natural gas price volatility.
For New Entrants and Emerging Players: After-sales technical service for furnace commissioning and alkali-free borosilicate reformulation represents an underserviced layer where incumbents under-serve mid-tier panel makers. Target India's PLI-subsidized display fab buildout as the most penetrable geography given domestic glass-melting capacity gaps. Lead with process engineering talent recruitment and training pipeline development as the go-to-market angle.
For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down reshapes the acquisition landscape toward dry-process equipment upgrade specialists and thinner glass handling system vendors. Five-to-ten year viability favors alkali-free borosilicate specialists with captive melting capacity and METI-aligned Korean supply chain access. Watch thin-film encapsulation yield rates as the inflection signal for substrate thickness roadmap abandonment or acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Silica | AGC Inc. and Nippon Electric Glass secure feedstock cost control against commodity volatility. |
| Gen 10.5 Equipment Qualification Acceleration | BOE compresses 18-24 month commissioning cycles to capture television OEM contract timing. |
| Alkali-Free Borosilicate Reformulation | SCHOTT adapts compositions for REACH cadmium restrictions in EU automotive HUD exports. |
| Direct OEM Contracting for Automotive HUD | Corning bypasses panel-maker intermediation to capture KBA traceability premium pricing. |
| Process Engineering Talent Pipeline Development | Specialized furnace operator training addresses lagging capacity expansion timelines in Northeast Asia. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with furnace operations managers, panel maker procurement directors, automotive HUD integration engineers, and alkali-free borosilicate R&D leads; alongside secondary validation through MIIT GB standard filings, Korean METI subsidy disclosures, REACH restriction updates, and SEC 10-K filings from listed glass-ceramic specialists. Bottom-up substrate volume estimates triangulated against top-down display panel production forecasts.
Across the projection horizon, the analytical framework modeled demand across product type, technology generation, application thermal profile, and end-user procurement sophistication. CAGRs derived from segment-level volume build-ups incorporating equipment qualification timelines and reformulation investment cycles. Forecast inputs included polysilicon price volatility assumptions and thin-film encapsulation yield progression curves.
Underlying assumptions cover sustained OLED flexible architecture adoption and natural gas price stabilization, with deviation risk concentrated in China's dual carbon goal enforcement intensity and South Korean supply chain resilience subsidy duration. Practitioners should keep alternative scenarios live as EU F-Gas Regulation phase-down timelines and India PLI scheme renewal conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Tablets and Notebook Display Market
Display Technologies
Glasses Free 3D Display Market
Display Technologies
Automotive LCD Display Market
Display Technologies
AMOLED Display Market
Display Technologies
Global Projector Market
Display Technologies
Paper-Thin Display Market
Display Technologies
Commercial Display Market
Display Technologies
IGZO Display Market
Display Technologies
Smartwatch Display Panel Market
Display Technologies
Portable Projector Market
Display Technologies
Ultra High Definition (UHD) Panel (4K) Market
Display Technologies
Middle East and Africa Industrial Display Market
Display Technologies
Seven Segment Display Market
Display Technologies
Interactive Video Wall Market
Display Technologies
Touch Screen Module Market
Display Technologies
Resistive Touchscreen Market