
 North America TFT LCD Panel Market | 2026-2036
North America TFT LCD Panel Market Size, Share, and Industry Trends Forecast 2026-2036
North America TFT LCD Panel Market Intelligence
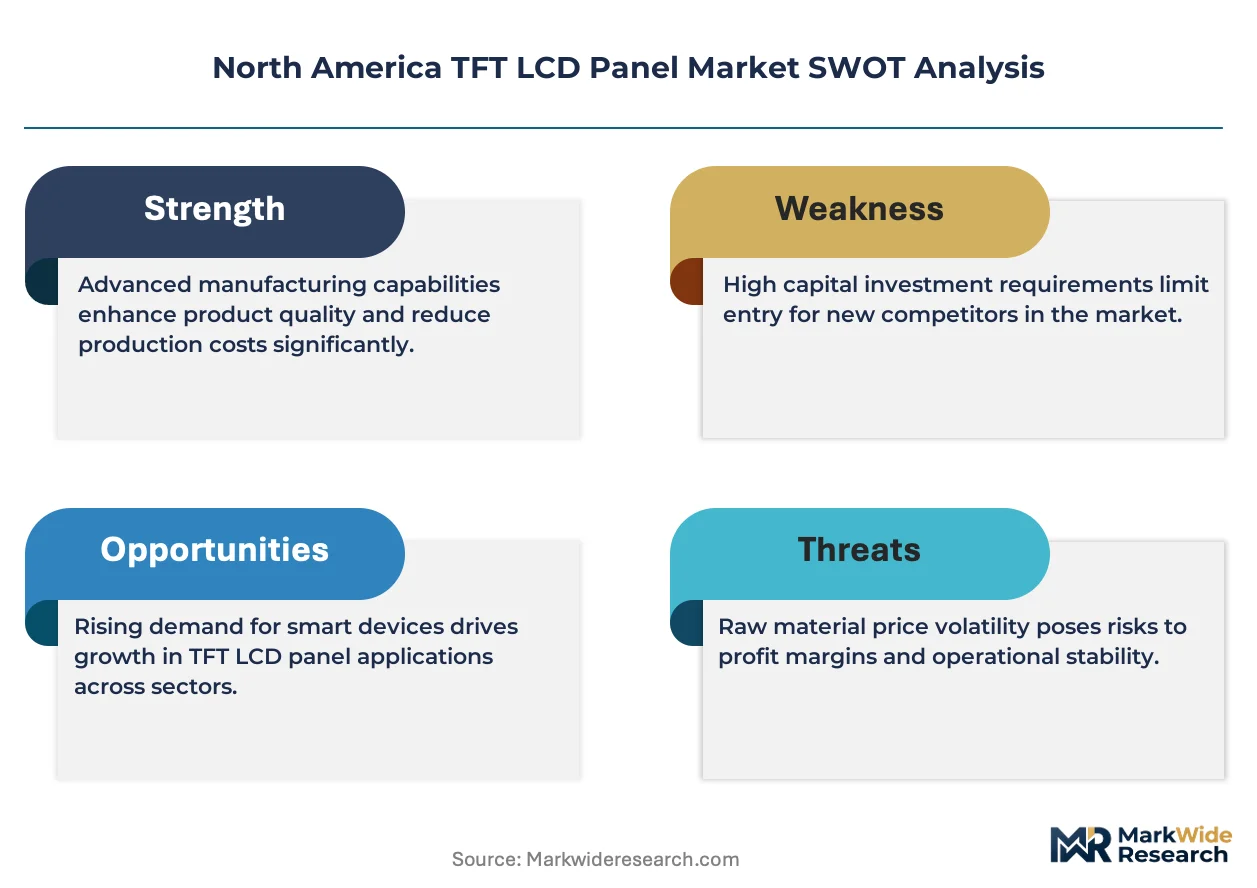
The gap between premium In-Plane Switching automotive-grade panels and commodity Twisted Nematic industrial displays is realigning procurement strategies across North American supply chains. LG Display leverages captive glass melting in Mexico to anchor high-margin automotive contracts with Detroit-area OEMs. Samsung Display competes through R&D intensity in active-matrix OLED-LCD hybrid architectures, while BOE Technology extends cost leadership in standard monitor panels through scale manufacturing in Baja California.
Thin-film transistor liquid crystal display panels sandwich amorphous silicon or low-temperature polysilicon transistor arrays between glass substrates, modulating backlight transmission through liquid-crystal orientation to render images at resolutions from HD to 8K. Display panels for medical imaging command premium pricing due to FDA color-calibration requirements, whereas touch panels for industrial automation represent the fastest-growing application as factory-floor HMI upgrades accelerate. Monitors face margin compression from oversupply, while TV screens concentrate demand in 65-inch-plus formats where Vertical Alignment technology dominates living-room specifications.
EPA ENERGY STAR specifications and California Energy Commission Title 20 standards constrain backlight power budgets, forcing manufacturers to redesign LED driver circuits. The IRA clean energy manufacturing tax credits incentivize domestic panel assembly, though NHTSA FMVSS 111 rear-visibility rules drive specialized automotive display demand with stringent temperature-cycling tests. Stakeholders must weigh Mexican tariff advantages against IRA domestic-content thresholds when siting new module capacity.
Market Dynamics
Automotive display procurement is consolidating around Michigan-Ontario assembly corridors as EPA energy-efficiency mandates and IRA clean-manufacturing credits reshape panel sourcing requirements, forcing OEMs to rebalance Mexican tariff advantages against domestic-content thresholds.
Growth Catalysts
- IRA Clean Energy Manufacturing Tax Credits:Domestic panel assembly incentives are pulling module production away from offshore alternatives toward US and Mexican facilities.
- NHTSA FMVSS 111 Rear-Visibility Rules:Mandated backup camera displays with stringent temperature-cycling specifications are expanding automotive-grade TFT LCD procurement.
- Baja California Electronics Cluster:OEMs building dedicated module lines in Mexico's border region capture tariff-advantaged access to North American automotive and industrial buyers.
Market Restraints
- Glass Substrate Supply Concentration:Captive melting capacity concentrates among Korean and Japanese suppliers, exposing assemblers to input bottlenecks.
- Amorphous Silicon Deposition Equipment Lead Times:Thin-film transistor array fabrication tools face 18-24 month delivery windows, constraining capacity expansion.
- Active-Matrix OLED Substitution:Samsung Display and LG Display redirect R&D toward hybrid OLED architectures, threatening long-term LCD share in premium automotive segments.
Strategic Opportunities
- Medical Imaging Color Calibration:FDA-certified diagnostic displays command premium pricing with limited qualified suppliers, creating defensible margin pools.
- Industrial Automation HMI Upgrades:Factory-floor human-machine interface refresh cycles are accelerating touch-panel adoption beyond traditional monitor applications.
- Low-Temperature Polysilicon Convergence:Integration of LTPS backplanes with in-cell touch sensing is electrifying next-generation automotive cockpit designs.
Industry Challenges
- LED Driver Circuit Redesign:EPA ENERGY STAR and California Energy Commission Title 20 backlight power budgets force rapid engineering cycles without guaranteed design wins.
- Automotive Temperature-Cycling Certification:NHTSA FMVSS 111 qualification protocols extend product development timelines by 12-18 months.
- Legacy Industrial Monitor Integration:Retrofitting new TFT LCD modules into existing automation systems requires custom firmware and mechanical adapters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America TFT LCD Panel Market |
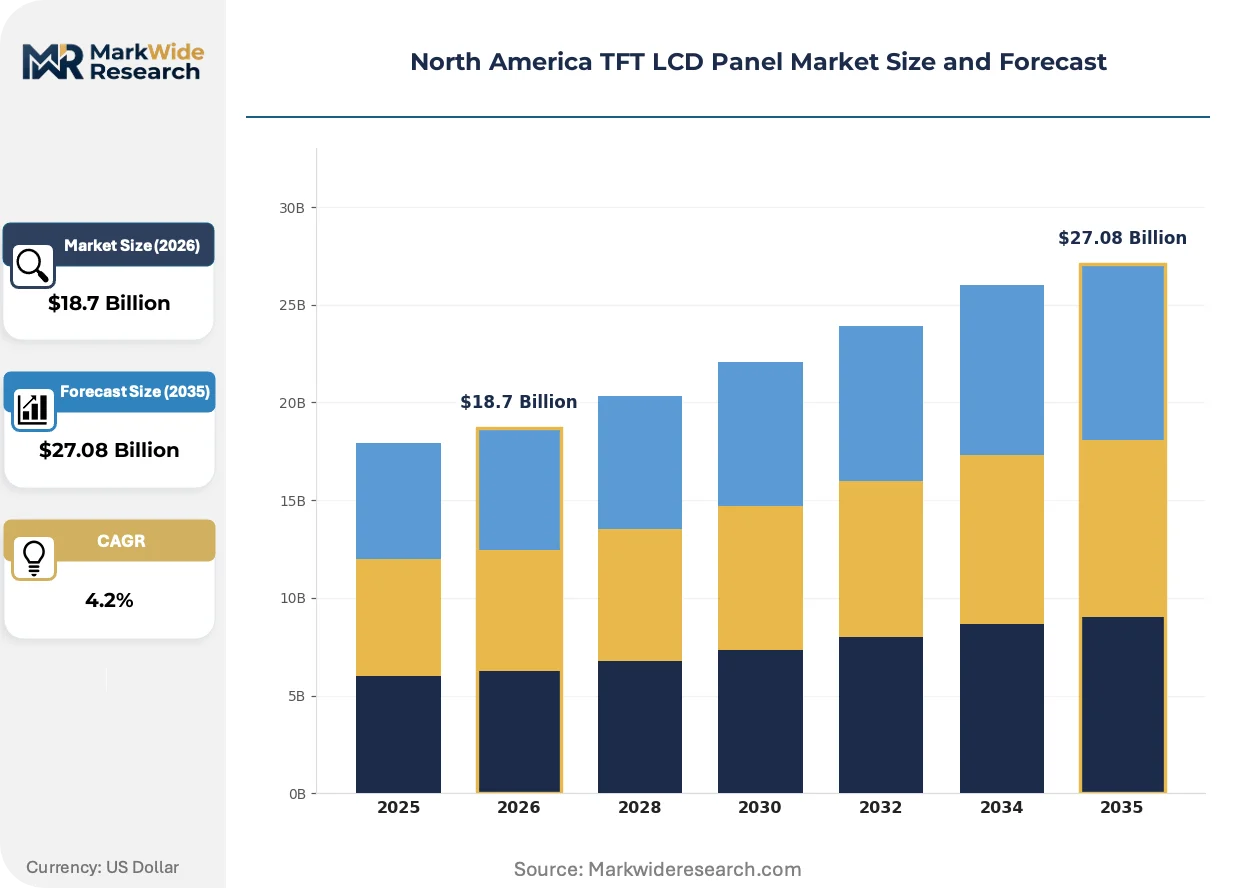
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Display Panels, Touch Panels, Monitors, TV Screens Application: Consumer Electronics, Automotive Displays, Industrial Automation, Medical Devices End User: Retailers, Manufacturers, Distributors, Service Providers Technology: In-Plane Switching, Twisted Nematic, Vertical Alignment, Active Matrix |
| Companies Covered | LG Display, Samsung Display, AU Optronics, Innolux Corporation, BOE Technology, Sharp Corporation, Tianma Microelectronics, Japan Display, HannStar Display, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America TFT LCD Panel Market Strategic Shifts & Innovations
Display technology evolution is bifurcating between premium automotive-grade specifications and cost-optimized industrial formats, with regulatory energy budgets and hybrid OLED competition forcing simultaneous innovation across multiple technical fronts.
Low-temperature polysilicon thin-film transistor arrays are electrifying next-generation automotive cockpit displays by enabling higher electron mobility and tighter pixel density than conventional amorphous silicon alternatives. Detroit-area OEMs and Tier 1 suppliers are specifying LTPS for curved instrument clusters and passenger entertainment screens. This technology is electrifying the gap between commodity industrial panels and premium automotive contracts, compressing margins for mid-tier suppliers lacking LTPS deposition capability.
California Energy Commission Title 20 appliance efficiency standards are forcing LED driver circuit redesigns that reduce backlight power consumption without sacrificing luminance uniformity. Manufacturers must requalify entire product families to maintain access to the US residential and commercial monitor markets. Medical imaging and broadcast reference monitor segments are absorbing these compliance costs most readily, while standard office display categories face margin compression.
Factory-floor buyers are consolidating procurement around integrated touch-display modules rather than sourcing discrete panels and touch sensors separately. Industrial automation OEMs in Michigan and Ontario are specifying bonded optical stacks with projected-capacitive touch for new HMI installations. This pattern is most visible in automotive parts manufacturing and food processing facilities, where glove-compatible touch operation and chemical resistance are non-negotiable.
North America TFT LCD Panel Market Segmentation
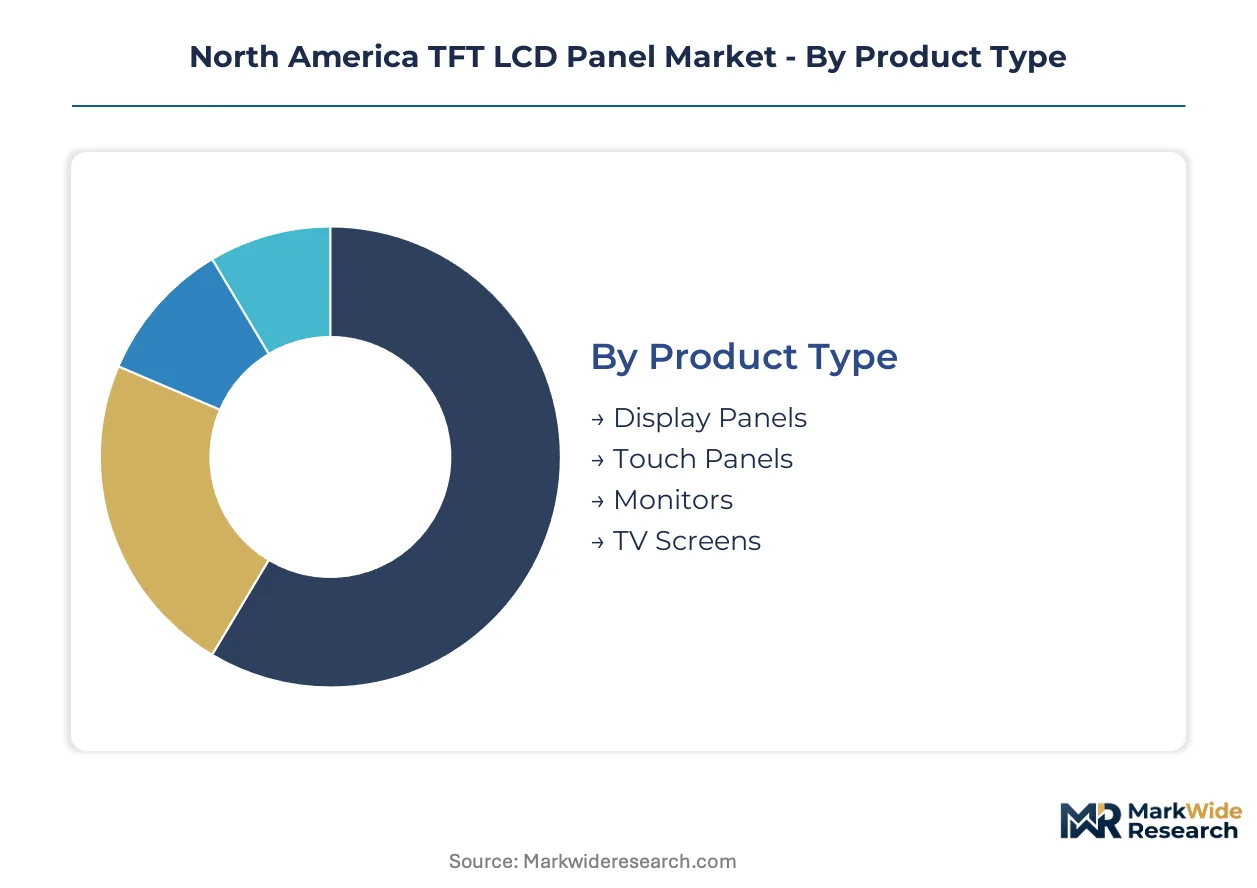
Segmentation in the North America TFT LCD Panel Market reveals how capital requirements, regulatory compliance burdens, and end-use specifications fragment procurement strategies across automotive, medical, and industrial verticals.
Product Type:
Capital intensity varies sharply across product categories, with automotive-grade display panels demanding the heaviest upfront investment in glass melting and thin-film transistor deposition equipment.
- Display Panels:These core modules sandwich amorphous silicon transistor arrays between glass substrates to modulate backlight transmission. Demand concentrates in Michigan-Ontario automotive assembly corridors where Detroit-area OEMs specify high-brightness units for instrument clusters. NHTSA FMVSS 111 temperature-cycling requirements extend qualification timelines and lock in supplier relationships.
- Touch Panels:Projected-capacitive and resistive touch sensors bond to TFT LCD substrates for HMI applications. Factory-floor automation OEMs in Ontario and Michigan are consolidating procurement around integrated touch-display modules rather than discrete components. Glove-compatible operation and chemical resistance specifications favor bonded optical stacks over add-on sensors.
- Monitors:Standard desktop and commercial display panels face margin compression from oversupply in Baja California manufacturing clusters. EPA ENERGY STAR compliance forces LED driver circuit redesigns that erode profitability in volume categories.
- TV Screens:Large-format residential displays concentrate demand in 65-inch-plus formats where Vertical Alignment technology dominates. California Energy Commission Title 20 standards constrain backlight power budgets and favor efficient designs.
Display Panels absorb the bulk of installed capacity; Touch Panels are expanding most quickly.
Application:
Application segmentation follows cost-tier stratification, with medical and automotive commanding premium pricing against commoditized consumer electronics.
- Consumer Electronics:Smartphones, tablets, and personal devices drive volume but compress margins through scale manufacturing in Mexican border facilities. IRA clean-manufacturing credits are pulling some module assembly toward domestic facilities.
- Automotive Displays:Curved instrument clusters and passenger entertainment screens specify low-temperature polysilicon backplanes for higher electron mobility. Detroit-area OEMs and Tier 1 suppliers anchor procurement around Michigan-Ontario corridors. NHTSA FMVSS 111 rear-visibility mandates expand qualified supplier pools.
- Industrial Automation:Factory-floor HMI upgrades accelerate touch-panel adoption beyond traditional monitor applications. Food processing and automotive parts manufacturing facilities in Ontario demand glove-compatible touch operation.
- Medical Devices:FDA color-calibration requirements for diagnostic imaging command premium pricing with limited qualified suppliers. Radiological and surgical displays require tight luminance uniformity and grayscale accuracy.
Automotive Displays command the highest unit economics; Industrial Automation is gaining share fastest.
End User:
End-user segmentation reflects customer-type differentiation in procurement sophistication and volume commitment.
- Retailers:Big-box and specialty electronics channels move commoditized monitor and TV inventory with thin margins. Price sensitivity dominates sourcing decisions.
- Manufacturers:Industrial automation OEMs and automotive Tier 1 suppliers specify custom panel configurations with extended qualification cycles. Long-term supply agreements lock in capacity.
- Distributors:Electronics component distributors buffer inventory for small and mid-sized industrial buyers. Mexican tariff advantages influence stocking location decisions.
- Service Providers:Medical equipment lessors and industrial systems integrators demand FDA-certified diagnostic displays with field service support.
Manufacturers commit the longest procurement horizons; Service Providers extract the highest service premiums.
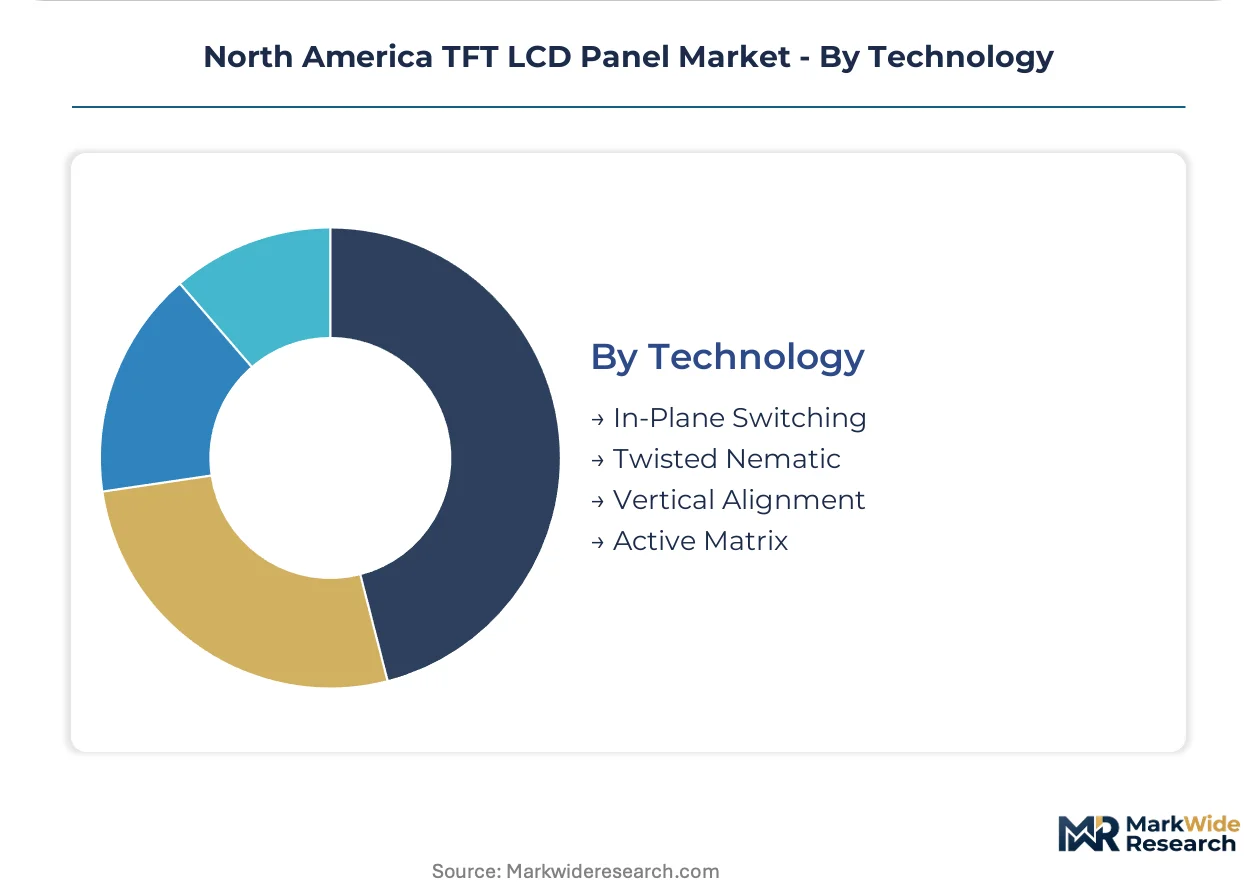
Technology:
Technology segmentation tracks maturity curves, with established architectures defending share against emerging alternatives.
- In-Plane Switching:Wide viewing angles and color stability make IPS the default for automotive-grade and medical imaging panels. LG Display leverages captive glass melting in Mexico to anchor high-margin contracts.
- Twisted Nematic:Lower-cost TN panels serve industrial automation and entry-level monitor segments where response time matters more than color accuracy. Baja California scale manufacturing sustains cost leadership.
- Vertical Alignment:Deep blacks and high contrast ratios dominate living-room TV specifications in 65-inch-plus formats. California Energy Commission efficiency standards favor VA backlight designs.
- Active Matrix:Active-matrix addressing architectures underpin all modern TFT LCD variants, with low-temperature polysilicon implementations electrifying next-generation automotive cockpit designs.
In-Plane Switching holds the largest revenue share; Active Matrix LTPS implementations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Michigan-Ontario assembly corridors anchor North American TFT LCD procurement, with Detroit-area OEMs driving automotive-grade panel demand through specialized low-temperature polysilicon specifications.
United States
Detroit automotive OEMs and Tier 1 suppliers specify curved instrument clusters requiring NHTSA FMVSS 111 temperature-cycling certification. IRA clean energy manufacturing tax credits pull module assembly toward domestic facilities. California Energy Commission Title 20 standards constrain backlight power budgets for monitors and TV screens sold into Western states.
Canada
Ontario automotive parts manufacturers consolidate procurement around integrated touch-display modules for factory-floor HMI upgrades. Health Canada medical device regulations align with FDA color-calibration requirements for diagnostic imaging panels. Toronto-Waterloo corridor hosts service providers demanding FDA-certified displays with field support networks.
Mexico
Baja California electronics clusters attract OEMs building dedicated TFT LCD module lines for tariff-advantaged North American access. Mexican manufacturing facilities capture automotive and industrial buyer demand through scale production. Nuevo León industrial zones serve as distribution hubs buffering inventory for mid-sized buyers.
North America TFT LCD Panel Market Key Industry Players
Capital-heavy producers compete with asset-light designers across a consolidated vendor base where Korean and Japanese suppliers control captive glass melting capacity. The market structures around three tiers: integrated display manufacturers with in-house transistor deposition, module assemblers sourcing third-party arrays, and regional distributors buffering inventory. Dominant competitive moves include capacity expansion in Mexican border zones and strategic partnerships securing long-term automotive supply agreements.
Among Korean-based integrated manufacturers, LG Display and Samsung Display occupy positions at opposite ends of the technology spectrum. LG Display exemplifies the captive-supply archetype through Mexico-based glass melting operations anchoring Detroit-area automotive contracts. Samsung Display represents the R&D-intensive hybrid-technology path, redirecting investment toward OLED-LCD architectures. BOE Technology, a Chinese Co., Ltd., sits within the scale-driven tier extending cost leadership through Baja California manufacturing.
| Leading Market Players |
|---|
| LG Display |
| Samsung Display |
| AU Optronics |
| Innolux Corporation |
| BOE Technology |
| Sharp Corporation |
| Tianma Microelectronics |
| Japan Display |
| HannStar Display |
| Others |
Cost & Logistics Intelligence
Korean and Japanese sovereign-backed display manufacturers anchor supply discipline through captive glass melting capacity, translating upstream control into pricing power across automotive-grade panel contracts. This ownership pattern tightens margin capture at the high end while Mexican module assemblers compete on cost for industrial touch-panel volumes.
Pricing Analysis
Value-based pricing anchored to NHTSA FMVSS 111 temperature-cycling certification outcomes dominates automotive-grade procurement, with qualified suppliers commanding premiums against unverified competitors. Three-tier pricing structure across automotive-certified, industrial-standard, and commodity monitor levels separates FDA color-calibration tiers from ENERGY STAR compliance grades. Cost compression in standard monitor categories is intensifying because Baja California scale manufacturing erodes differentiation. Retailers and big-box electronics channels exhibit highest price sensitivity, while Detroit-area OEMs prioritize qualification reliability over unit cost.
Supply Chain Analysis
Workforce availability in South Korea, Japan, and Taiwan constrains expansion of thin-film transistor deposition capacity despite demand pull from North American automotive corridors. Glass substrate production draws from Corning and AGC captive melting facilities, while amorphous silicon deposition equipment feeds from Applied Materials and Tokyo Electron order backlogs. Single-source vulnerability concentrates in low-temperature polysilicon deposition tools with 18-24 month delivery windows. Distribution runs through Tier 1 automotive suppliers and industrial automation OEMs in Michigan-Ontario corridors, with Mexican border facilities buffering inventory for mid-sized buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America TFT LCD Panel Market reads as a cost-of-compliance story where IRA clean energy manufacturing tax credits and NHTSA FMVSS 111 certification requirements erect barrier-to-entry moats favoring incumbent qualified suppliers.
For Market Incumbents: Lock in long-term supply agreements with Detroit-area OEMs before LTPS deposition capacity shortages harden. Secure captive glass melting partnerships to defend against Korean supplier bottleneck risks. Expand module assembly footprints in Baja California to capture tariff-advantaged industrial demand without sacrificing IRA domestic-content eligibility for automotive contracts.
For New Entrants and Emerging Players: Launch via medical imaging color-calibration specialization where FDA certification requirements limit qualified competition and sustain premium pricing. Target industrial automation HMI upgrade cycles in Ontario food processing facilities where glove-compatible touch specifications favor bonded optical stack suppliers over commodity panel vendors.
For Investors and Strategic Acquirers: Distressed-cycle entries favor module assemblers with IRA-compliant US footprints and existing NHTSA qualification relationships over greenfield technology plays. Long-term viability hinges on hybrid OLED substitution timelines in premium automotive segments. Watch Samsung Display and LG Display R&D allocation shifts as inflection signals for LCD share erosion in curved instrument cluster applications.
| Strategic Initiative | Industry Significance |
|---|---|
| LTPS Backplane Capacity Expansion | Captures Detroit OEM demand for curved automotive cockpit displays with higher electron mobility specifications. |
| IRA-Compliant Module Assembly | Qualifies domestic production for clean energy manufacturing tax credits against Mexican tariff advantages. |
| FDA Diagnostic Display Certification | Opens premium-priced medical imaging segments with limited qualified supplier pools and recurring calibration revenue. |
| Integrated Touch-Display Bonding | Consolidates factory-floor HMI procurement around single-source modules for Ontario industrial automation OEMs. |
| Hybrid OLED-LCD R&D Partnership | Defends long-term automotive share against Samsung Display and LG Display technology migration threats. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across Tier 1 automotive supplier procurement officers, industrial automation OEM platform engineers, medical device biomedical engineers, and electronics distributor inventory managers. FDA 510(k) submissions, EPA ENERGY STAR certification databases, NHTSA FMVSS 111 test reports, and SEC 10-K equipment capex disclosures provided validation layers. Bottom-up panel shipment triangulation against top-down automotive production and industrial automation capex forecasts calibrated volume estimates.
Granularity-level modeling addressed product type, application vertical, technology architecture, and end-user procurement sophistication across the analysis window. Automotive display content per vehicle, industrial HMI refresh cycle timing, and medical imaging equipment replacement rates informed segment-specific trajectory assumptions. CAGRs derived from regression against historical panel pricing elasticities and regulatory compliance cost absorption patterns.
IRA credit policy revisions, NHTSA rulemaking updates, and Korean glass substrate supply disruptions are the dominant revision risks to installed capacity and pricing assumptions. Forecasts reflect documented assumptions about regulatory stability and equipment delivery timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Electronic Paper Display (EPD) Market
Display Technologies
Global Projector Market
Display Technologies
Flat Panel Display (FPD) Market
Display Technologies
Holographic Display Market
Display Technologies
Asia Pacific Computer Monitor Market
Display Technologies
Industrial Display Market
Display Technologies
Digital Kiosk Display Market
Display Technologies
Europe Microdisplay Market
Display Technologies
Europe Computer Monitor Market
Display Technologies
Global Transparent Display Market
Display Technologies
Global Monochrome Display Market
Display Technologies
Backlit Displays Market
Display Technologies
OLED Laptops Market
Display Technologies
Global 4K Display Resolution Market
Display Technologies
Next Generation 3D Display Market
Display Technologies
Projector Screen Market