
 Industrial UV-C Disinfection Lighting Market | 2026-2036
Industrial UV-C Disinfection Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial UV-C Disinfection Lighting Market Insights
China's manufacturing base is reshaping supply chain dynamics for UV-C lamp components. Trojan Technologies leverages vertical integration across quartz sleeve production to sustain cost advantages in medium-pressure systems. Kuraray anchors Asian market presence through specialized UV-C fiber optic bundles for confined-space disinfection. Atlantic Ultraviolet Corporation dominates North American aftermarket service networks for legacy mercury vapor installations.
Industrial UV-C disinfection lighting employs ultraviolet radiation at 200–280 nanometer wavelengths to inactivate microorganisms through photochemical damage to nucleic acids, with low-pressure mercury lamps emitting peak germicidal output at 253.7 nanometers. Mercury vapor technology still occupies the largest installed base across municipal water treatment, though gallium nitride LED UV-C is accelerating fastest in HVAC retrofit applications where mercury bans constrain new deployments. Pulsed xenon systems command premium positioning in pharmaceutical sterilization lines where rapid cycle times justify higher capital outlays.
EPA disinfection byproduct rules and EU REACH restrictions on mercury-containing products are forcing utilities toward LED and excimer alternatives before phase-out deadlines. China's GB standards for drinking water and NMPA pharmaceutical manufacturing guidelines shape product certification requirements for equipment suppliers. FDA validation protocols for medical device sterilization create additional compliance layers for pharmaceutical end users. Stakeholders must monitor regulatory divergence between mercury ban timelines and LED UV-C output efficiency thresholds to calibrate technology transition investments.
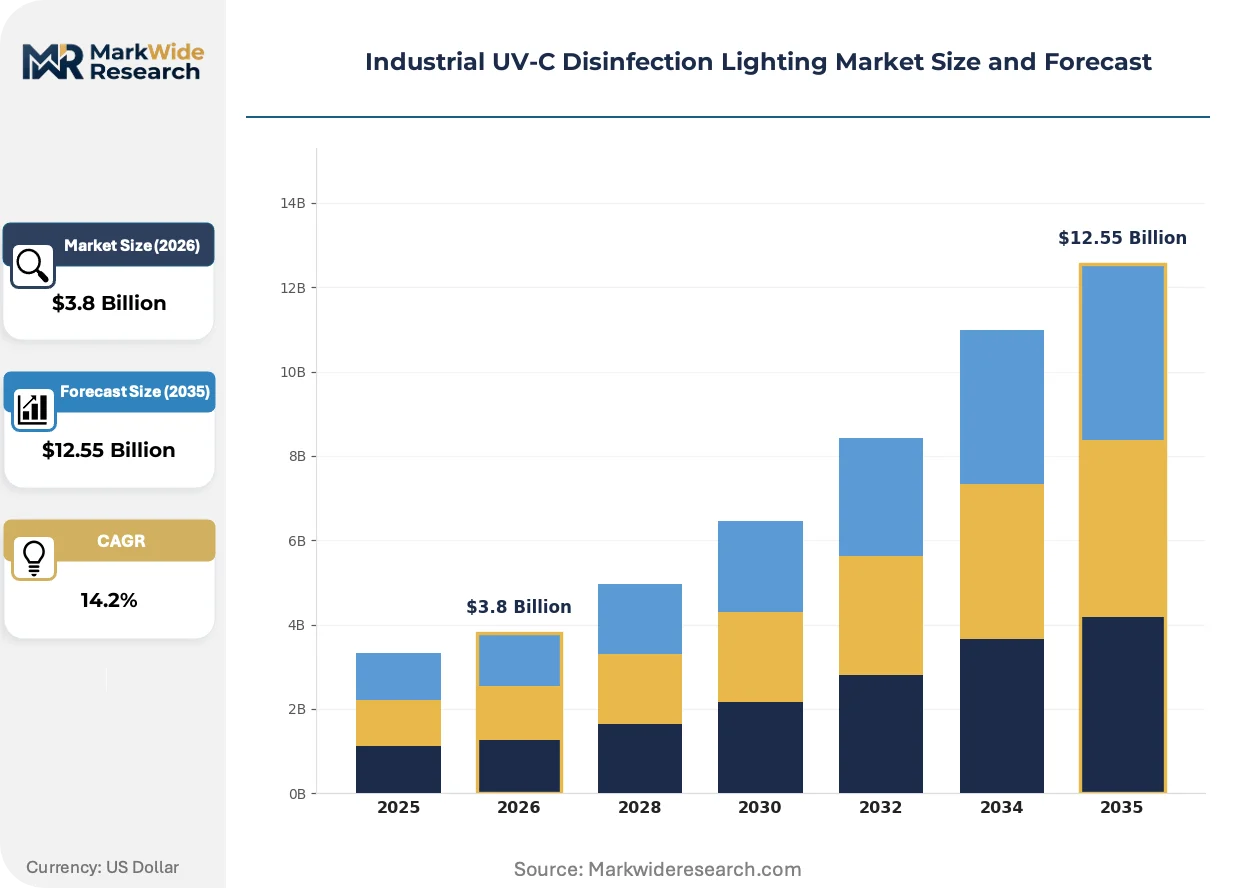
Market Dynamics
Mercury phase-out mandates across the EU and select US states are compressing technology transition timelines, forcing municipal utilities and industrial sterilization operators to accelerate LED UV-C and excimer lamp deployments ahead of end-of-life replacement cycles.
Growth Catalysts
- EPA Disinfection Byproduct Rules:Stricter trihalomethane and haloacetic acid limits are compelling US municipal water systems to upgrade from chlorine-based treatment to UV-C disinfection, particularly in Great Lakes corridor utilities.
- Semiconductor Clean Room Demand:China's Yangtze River Delta and Pearl River Delta manufacturing clusters are installing medium-pressure UV-C systems for ultra-pure water loops in advanced node fabs.
- Gallium Nitride LED Maturation:Improved wall-plug efficiency above 5% at 275 nanometers is enabling HVAC retrofit applications where mercury bans already prohibit new lamp installations.
Market Restraints
- Quartz Sleeve Supply Concentration:High-purity fused quartz production concentrates in Germany and China, creating single-source vulnerability for medium-pressure lamp manufacturers.
- LED UV-C Output Efficiency Gap:Current solid-state systems deliver 2-3% of electrical input as germicidal UV-C versus 30-35% for optimized low-pressure mercury, limiting viable application scope.
- REACH Mercury Restrictions:EU exemptions for water treatment lamps expire progressively through 2027, forcing premature capital expenditure on unproven alternatives.
Strategic Opportunities
- Ballast Water Treatment Retrofit:IMO D-2 compliance deadlines are driving UV-C system installations on existing merchant vessels, particularly in Singapore and Rotterdam port hubs.
- Pharmaceutical Aseptic Processing:Pulsed xenon systems for isolator and restricted access barrier decontamination are penetrating fill-finish lines where hydrogen peroxide vapor cycles create bottlenecks.
- Smart UV-C Monitoring Convergence:Integration of UV-C dosage sensors with building management systems enables predictive lamp replacement and energy optimization in commercial HVAC networks.
Industry Challenges
- Photometric Calibration Expertise Shortage:Qualified technicians for UV-C intensity mapping and bioassay validation are scarce, extending commissioning timelines for pharmaceutical sterilization installations.
- Legacy Mercury Infrastructure Stranding:Municipal utilities with 15-20 year amortization schedules on existing UV-C banks face stranded asset risk from accelerated mercury ban timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial UV-C Disinfection Lighting Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Pressure Lamps, Medium-Pressure Lamps, LED UV-C, Excimer Lamps, Fiber Optic UV-C Technology: Mercury Vapor, Gallium Nitride, Pulsed Xenon, Krypton Chloride, Rare-Earth UV-C Application: Water Treatment, Surface Sanitization, HVAC Disinfection, Food Processing, Pharmaceutical Sterilization End User: Manufacturing Plants, Food & Beverage Facilities, Research Laboratories, Clean Rooms |
| Companies Covered | Xylem, Trojan Technologies, Halma, Kuraray, Atlantic Ultraviolet Corporation, American Ultraviolet, Atlantium Technologies, Hönle, Xenex Disinfection Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial UV-C Disinfection Lighting Market Trends and Innovations
Technology substitution is compressing product lifecycles across lamp architectures, with solid-state and pulsed systems eroding mercury vapor's installed base while regulatory pressure eliminates new deployment pathways.
Excimer lamps emitting at 172 nanometers are digitizing surface disinfection protocols in flat-panel display manufacturing, where Korean and Taiwanese fabs are replacing mercury vapor banks for photoresist stripping applications. These systems enable single-wafer processing with reduced thermal load, compressing cycle times by 40% in advanced lithography clean rooms.
REACH Annex XVII mercury restrictions are forcing European water utilities toward LED and medium-pressure alternatives before 2027 exemption expirations. German municipal operators are piloting amalgam lamp retrofits as interim solutions, while Nordic utilities accelerate direct LED transitions for small-scale drinking water plants.
Service unbundling is disrupting traditional equipment-plus-maintenance bundling in North American municipal procurement. California and Texas water districts are separating lamp supply from system integration contracts, enabling third-party quartz sleeve refurbishment and specialized UV intensity auditing services to capture aftermarket value pools.
Industrial UV-C Disinfection Lighting Market Segmentation
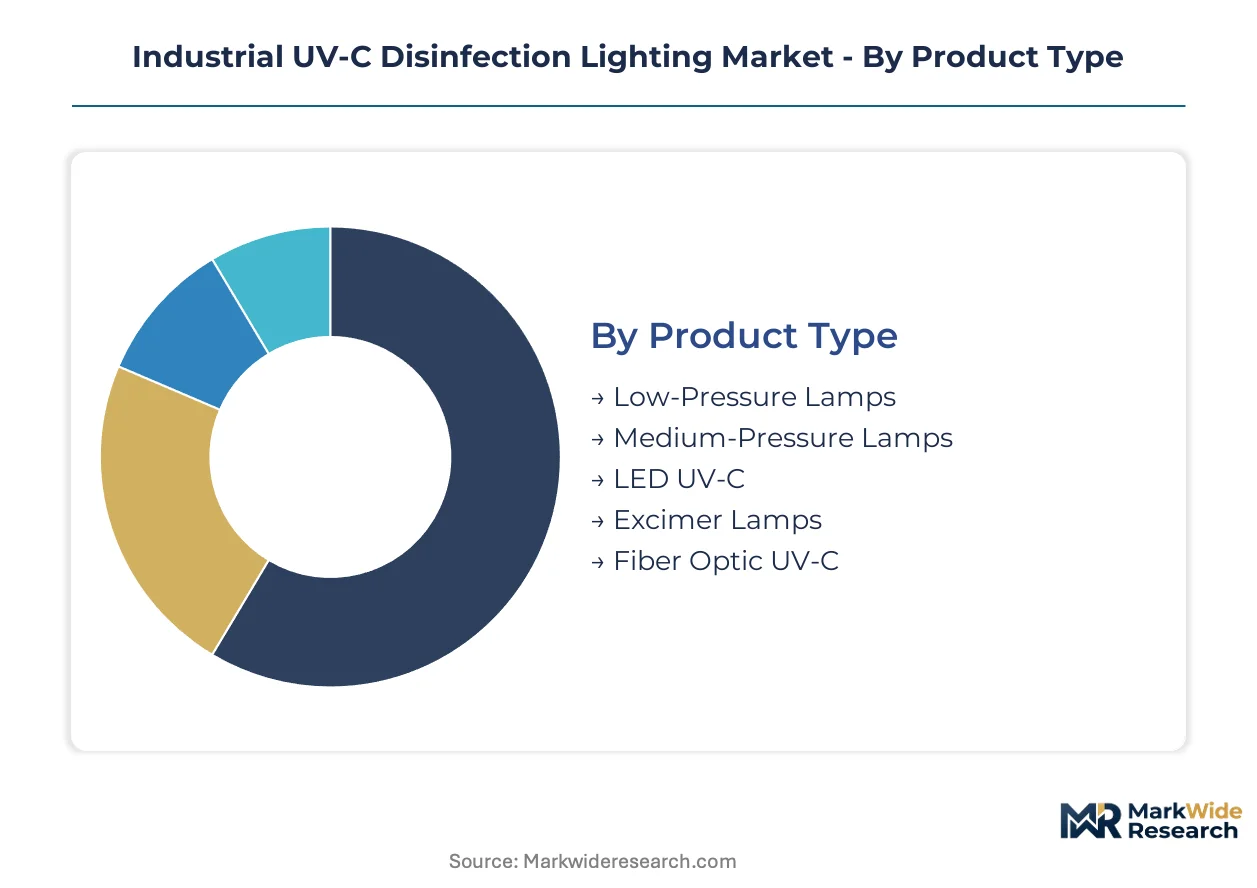
Industrial UV-C disinfection lighting segments diverge sharply by technical maturity and regulatory tolerance. Product architecture determines capital intensity and replacement cadence. Application context dictates wavelength specificity and dosage validation requirements.
Product Type:
Cost tier stratification separates mature mercury-based systems from premium solid-state alternatives facing divergent compliance timelines.
- Low-Pressure Lamps:Mercury vapor tubes emitting monochromatic 253.7 nanometer radiation dominate municipal water treatment installations across Germany and the United States. EPA disinfection byproduct rules are accelerating replacement demand in Great Lakes corridor utilities where chlorine reduction mandates bite hardest.
- Medium-Pressure Lamps:Polychromatic mercury arc systems deliver higher intensity across broader wavelength spectra for industrial high-flow applications. Wastewater treatment plants in Germany and semiconductor fabs in China's Yangtze River Delta cluster are expanding installations for ultra-pure water loops.
- LED UV-C:Solid-state gallium nitride emitters at 275 nanometers are penetrating HVAC retrofit markets where mercury bans already prohibit new lamp deployments.
- Excimer Lamps:Krypton chloride and xenon chloride systems generate 172-222 nanometer vacuum ultraviolet for surface disinfection without thermal loading.
- Fiber Optic UV-C:Specialized quartz fiber bundles deliver directed radiation into confined reactor geometries for pharmaceutical isolator decontamination.
Low-pressure mercury commands the established base. The steepest expansion runs through LED UV-C as gallium nitride wall-plug efficiency crosses commercial viability thresholds.
Technology:
Application requirements for wavelength precision and cycle speed are fragmenting technology adoption across end-use verticals.
- Mercury Vapor:Low-pressure and amalgam lamp architectures retain installed base dominance in drinking water treatment due to proven bioassay validation and lower capital cost per kilowatt.
- Gallium Nitride:Semiconductor emitters are displacing mercury in building automation systems where continuous operation and vibration tolerance outweigh peak efficiency concerns.
- Pulsed Xenon:Broadband flashlamp systems achieve 6-log microbial reduction in under 30 seconds for pharmaceutical fill-finish line isolators.
- Krypton Chloride:Excimer discharge at 222 nanometers enables human-safe far-UVC deployment in occupied commercial spaces.
- Rare-Earth UV-C:Cerium and terbium-doped phosphor systems are emerging for specialized photoreactor applications requiring tunable emission spectra.
Mercury vapor retains volume leadership. Gallium nitride is climbing the fastest as regulatory phase-outs compress replacement timelines.
Application:
Volume concentration in water treatment contrasts with value concentration in pharmaceutical and semiconductor sterilization protocols.
- Water Treatment:Municipal drinking water and wastewater disinfection represents the largest installed base segment, with medium-pressure systems handling combined sewer overflow and industrial effluent in German Ruhrgebiet utilities.
- Surface Sanitization:Far-UVC deployment in transportation hubs and healthcare facilities is accelerating following human safety validation studies.
- HVAC Disinfection:Coil irradiation and upper-room systems are retrofitting commercial building stock in US Sun Belt markets where cooling load drives mold and biofilm accumulation.
- Food Processing:Conveyor-based UV-C tunnels for packaging sterilization are penetrating ready-to-eat meat and produce wash systems.
- Pharmaceutical Sterilization:Aseptic processing lines require validated 6-log reduction protocols with continuous UV-C monitoring and redundant lamp banks.
Water treatment anchors volume demand. Pharmaceutical sterilization is gaining share fastest on per-unit value premiums and regulatory compliance intensity.
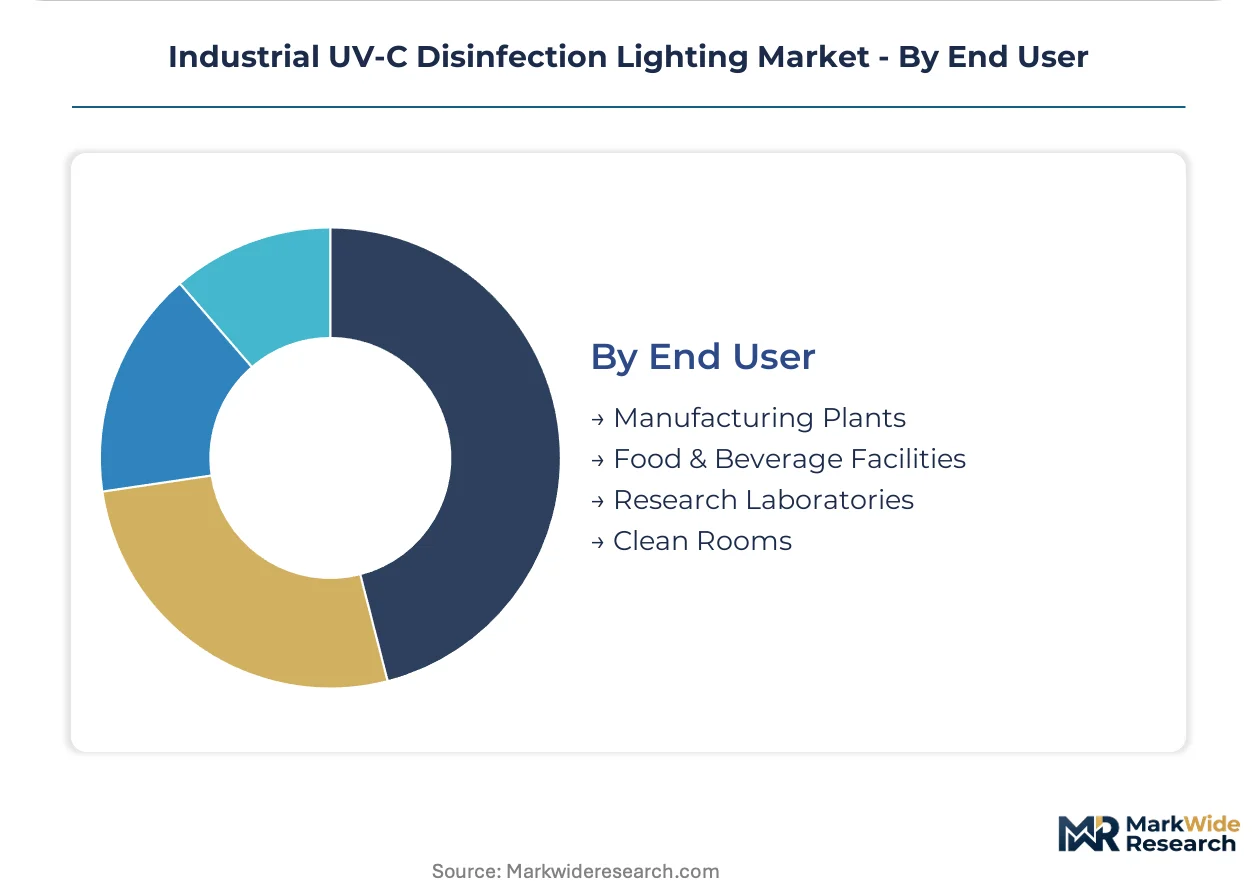
End User:
Customer type determines procurement sophistication, with municipal utilities favoring lifecycle cost analysis and pharmaceutical operators prioritizing validation documentation.
- Manufacturing Plants:Electronics and automotive assembly lines deploy UV-C for process water disinfection and surface decontamination of sensitive components.
- Food & Beverage Facilities:Breweries and dairy processors are retrofitting CIP systems with UV-C to reduce chemical sanitizer consumption and wastewater loading.
- Research Laboratories:BSL-3 and BSL-4 containment facilities require redundant UV-C barriers for personnel protection and waste stream treatment.
- Clean Rooms:ISO 14644 Class 1-3 environments in semiconductor and pharmaceutical manufacturing specify sub-ppb TOC water systems with medium-pressure UV-C oxidation stages.
Manufacturing plants represent the broadest installed base. Clean rooms are expanding most quickly on advanced node semiconductor capacity builds and cell therapy manufacturing scale-up.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German municipalities prioritize medium-pressure systems for combined sewer overflow. Chinese semiconductor fabs drive ultra-pure water specifications. US utilities face EPA compliance deadlines forcing chlorine displacement.
United States
Great Lakes corridor utilities are replacing chlorine banks with UV-C arrays to meet trihalomethane limits. The EPA's stricter disinfection byproduct rules tighten compliance thresholds quarterly. California water districts are unbundling lamp supply from integration contracts, enabling third-party quartz sleeve refurbishment.
Germany
Ruhrgebiet wastewater operators are accelerating medium-pressure lamp installations for industrial effluent treatment. REACH Annex XVII mercury exemptions expire through 2027, forcing premature capital cycles. Bavarian municipal utilities pilot amalgam retrofits as interim bridge solutions.
China
Yangtze River Delta semiconductor fabs specify sub-ppb TOC water systems with medium-pressure UV-C oxidation stages. NMPA pharmaceutical manufacturing guidelines shape equipment certification requirements. Pearl River Delta clean room construction is outpacing global capacity additions.
South Korea
Flat-panel display manufacturers are replacing mercury vapor banks with 172-nanometer excimer systems for photoresist stripping. The country's national environmental regulator is aligning semiconductor discharge standards with EU benchmarks. Gyeonggi Province fabs report 40% cycle time compression from single-wafer processing.
Singapore
Port authorities are mandating UV-C ballast water treatment retrofits ahead of IMO D-2 compliance deadlines. The Maritime and Port Authority coordinates with shipyards on installation scheduling. Tuas Port expansion is integrating shore-based treatment alternatives for vessel compatibility.
Industrial UV-C Disinfection Lighting Market Competitive Landscape
Capability concentration sits with specialized lamp architects; scale advantage sits with diversified water technology conglomerates. The vendor base separates into three tiers: integrated water technology platforms, pure-play UV-C specialists, and component suppliers with captive disinfection divisions. Two dominant competitive moves are reshaping positioning: backward integration into high-purity quartz production and unbundling of aftermarket service contracts from equipment sales.
Among North American-anchored specialists, Trojan Technologies and Atlantic Ultraviolet Corporation exemplify divergent strategic postures. Trojan represents the vertically integrated archetype with captive quartz sleeve production. Atlantic Ultraviolet occupies the aftermarket-focused position with dense service networks. Halma sits within the diversified industrial technology tier, its UV-C exposure nested within broader safety and environmental monitoring portfolios.
| Leading Market Players |
|---|
| Xylem |
| Trojan Technologies |
| Halma |
| Kuraray |
| Atlantic Ultraviolet Corporation |
| American Ultraviolet |
| Atlantium Technologies |
| Hönle |
| Xenex Disinfection Services |
| Others |
Pricing and Supply Chain Analysis
Rhine-Main corridor freight costs feed directly into quartz sleeve pricing tiers, amplifying cost differentials between German-engineered medium-pressure systems and Asian-manufactured LED alternatives while compressing margins for lamp assemblers without captive quartz production.
Pricing Analysis
Long-term offtake agreements dominate municipal utility procurement, locking in quartz sleeve supply and lamp replacement schedules across 10-15 year amortization windows. Three-tier pricing structure across premium, standard, and economy levels separates validated pharmaceutical systems from unbundled water treatment retrofits and commodity HVAC components. Pricing pressure stems from REACH mercury phase-out deadlines forcing premature replacement cycles. Municipal utilities exhibit highest price sensitivity due to ratepayer oversight, while semiconductor fabs prioritize specification compliance over unit cost.
Supply Chain Analysis
Extended payment terms from German quartz refiners are squeezing working capital for medium-pressure lamp manufacturers without balance sheet depth. High-purity fused quartz production concentrates in Germany and China, with gallium nitride substrates sourcing from Taiwan and South Korea. The supply chain draws from rare-earth phosphor deposits and specialized gas mixtures for excimer discharge. Single-source vulnerability in fused quartz creates procurement risk for European assemblers. Distribution runs through OEM-direct channels for large utilities and specialized industrial distributors for retrofit applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a capital expenditure trough driven by regulatory compliance deadlines compressing replacement timelines. Mercury phase-out mandates are triggering a cyclical upswing in LED and excimer system deployment.
For Market Incumbents: Build regulatory certification moats by accelerating FDA validation protocols and NMPA alignment ahead of competitor filings. Trojan Technologies and Atlantic Ultraviolet Corporation should deepen backward integration into quartz refining to defend against Asian cost pressure. Secure long-term offtake agreements with Yangtze River Delta fabs before LED efficiency thresholds cross commercial viability. For New Entrants and Emerging Players: Pursue ballast water treatment retrofit opportunities at Singapore and Rotterdam port hubs where IMO D-2 deadlines concentrate demand and incumbent service networks remain underdeveloped. Target pharmaceutical aseptic processing lines with pulsed xenon isolator systems, exploiting hydrogen peroxide vapor cycle bottlenecks. Lead with predictive monitoring software bundled with hardware to differentiate from legacy equipment-plus-maintenance contracts. For Investors and Strategic Acquirers: Specialized UV-C fiber optic bundle manufacturers with pharmaceutical validation credentials represent the most defensible acquisition profile. Excimer lamp specialists serving Korean flat-panel display fabs offer exposure to photoresist stripping substitution cycles. Watch gallium nitride wall-plug efficiency thresholds as the inflection signal for LED UV-C market share acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quartz Refining | Captive high-purity fused quartz supply insulates Trojan Technologies from German-China supply concentration risk. |
| Smart UV-C Monitoring Platform Launch | Integration with building management systems enables predictive replacement and energy optimization for HVAC networks. |
| Pharmaceutical Validation Partnership | FDA-aligned bioassay protocols open aseptic processing lines to pulsed xenon isolator penetration. |
| Ballast Water Retrofit Service Expansion | IMO D-2 compliance deadlines at Singapore port concentrate merchant vessel installation demand. |
| Excimer Lamp Manufacturing Scale-Up | 172-nanometer systems replace mercury vapor banks in Korean flat-panel display photoresist stripping. |
Research Methodology
Initial hypotheses were tested against primary input from municipal water utility engineers, pharmaceutical manufacturing directors, semiconductor fab facilities managers, and UV-C system integration specialists and refined through secondary validation against EPA enforcement databases, ECHA REACH exemption registries, NMPA pharmaceutical equipment certifications, and semiconductor industry capital expenditure disclosures. Bottom-up triangulation across lamp shipment volumes and top-down reconciliation against utility capital budgets anchored market size estimates.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon, with segmentation modeled by product architecture, application vertical, technology maturity, and end-user procurement sophistication. CAGRs were derived from replacement cycle compression analysis and regulatory deadline impact assessment. Forecast inputs incorporated mercury phase-out timeline scenarios and gallium nitride efficiency improvement curves.
Sensitivities concentrate around EPA disinfection byproduct rule enforcement intensity and EU mercury exemption extension decisions. Forecasts reflect documented assumptions regarding LED UV-C commercial viability thresholds and semiconductor fab construction timelines. Macroeconomic contraction, regulatory timeline deviation, or solid-state efficiency breakthroughs would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Solid State Lighting System Market
Lighting
GCC Smart Lighting Market
Lighting
Asia-Pacific Lighting Control Market
Lighting
Ultra Violet (UV) Lamps Market
Lighting
Flexible Lighting Foils Market
Lighting
Smart Lights Market
Lighting
Smart Lighting Market
Lighting
Global Commercial Lighting Market
Lighting
Specialty Lighting Market
Lighting
Global Machine Vision Lighting Market
Lighting
Xenon Lights Market
Lighting
High Bay Lighting Market
Lighting
COB Photo Light Market
Lighting
Bacteriological Light Market
Lighting
Ultraviolet Lamps Market
Lighting
Graphene Lighting Market