
 Advanced (3D/4D) Visualization Systems Market | 2026-2036
Advanced (3D/4D) Visualization Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced (3D/4D) Visualization Systems Market Analysis
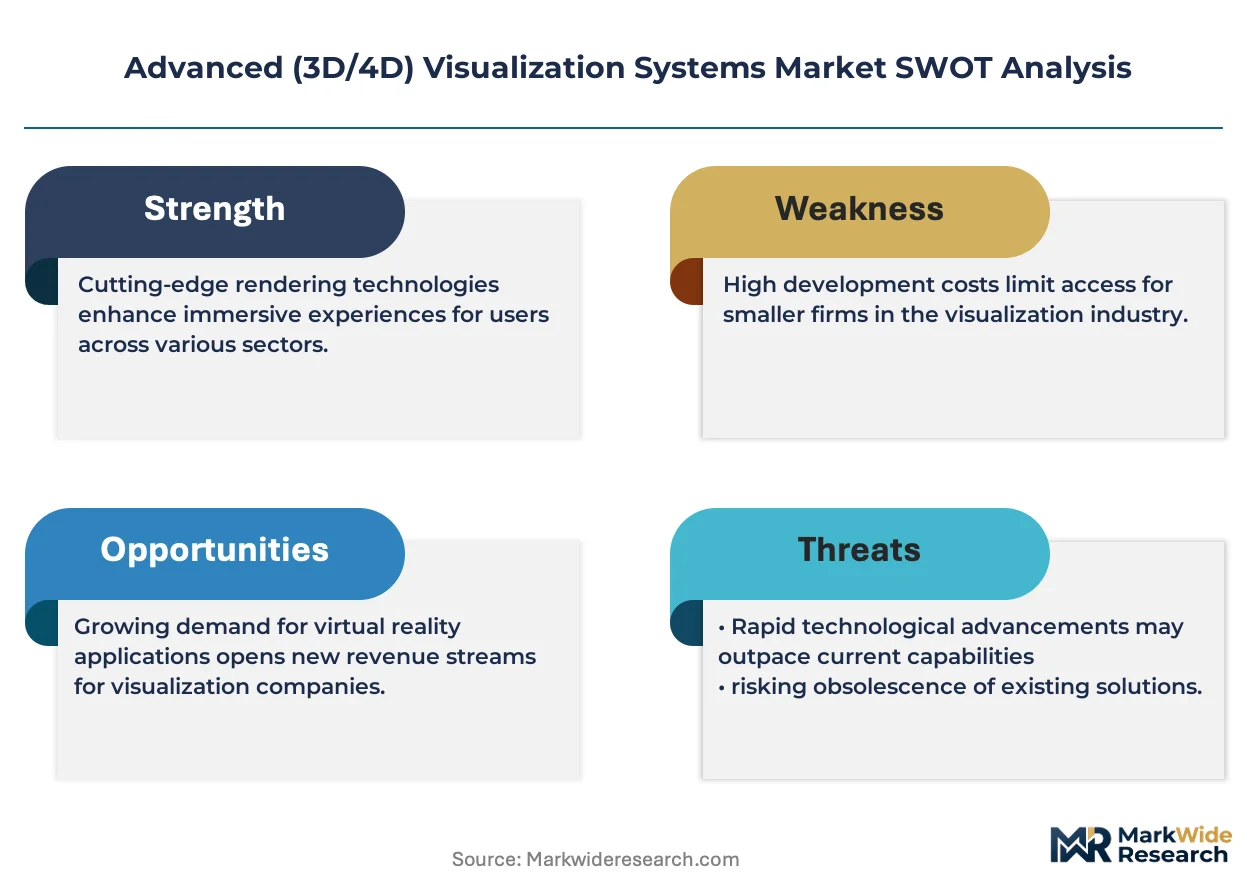
Direct-to-hospital software licensing is fragmenting as cloud-based subscription models and platform-agnostic rendering engines gain traction among buyers. Siemens Healthineers leverages its installed base of imaging hardware to bundle visualization software at point-of-sale. GE Healthcare competes through edge-computing architectures that reduce latency in intraoperative 3D rendering. Koninklijke Philips anchors its position in cardiology workflows where real-time 4D echocardiography demands tight hardware-software integration.
Advanced (3D/4D) visualization systems encompass software algorithms, GPU clusters, and display hardware that generate spatially accurate, time-resolved volumetric models from multi-modal data streams, typically processing DICOM datasets or LiDAR point clouds at refresh rates exceeding 30 frames per second for interactive manipulation. Their primary commercial purpose spans preoperative surgical simulation, immersive architectural walkthroughs, and physics-based virtual prototyping that reduces physical iteration cycles. Hardware components still occupy the dominant revenue share due to specialized GPU arrays and stereoscopic displays, though software is expanding fastest as standalone modules decouple from proprietary hardware ecosystems. Medical Imaging applications command premium pricing relative to Entertainment or Architectural Visualization, reflecting stringent validation requirements and clinical liability frameworks.
The FDA's 510(k) pathway and the EU Medical Device Regulation (MDR) impose divergent conformity assessment burdens on vendors selling across Atlantic markets, with MDR's clinical evidence requirements extending approval timelines for algorithm-driven visualization tools. ISO 13485 quality management standards and IEC 62304 software lifecycle protocols further shape development costs for healthcare-facing products. Stakeholders must monitor how emerging AI Act risk classifications in Europe will recategorize autonomous segmentation features within diagnostic visualization suites.
Market Dynamics
Cloud-native rendering engines are decoupling visualization software from proprietary GPU hardware, forcing incumbent vendors to unbundle historically integrated offerings and compete on algorithmic performance alone.
Growth Catalysts
- FDA 510(k) Software-as-a-Medical-Device Pathway:The streamlined clearance mechanism accelerates commercialization timelines for algorithm-driven diagnostic tools, reducing regulatory friction for visualization platforms targeting surgical planning workflows.
- Automotive Virtual Prototyping:German OEMs and tier-one suppliers deploy 4D visualization to compress physical iteration cycles, generating cross-industry demand for GPU clusters originally developed for medical imaging.
- LiDAR Point Cloud Processing:Geospatial surveying and autonomous vehicle development pipelines require real-time volumetric reconstruction at 30+ frames per second, pulling hardware-agnostic software modules into industrial applications.
Market Restraints
- Specialized GPU Supply Concentration:Foundry capacity for high-bandwidth memory chips concentrates in Taiwan and South Korea, exposing visualization hardware vendors to geopolitical supply disruptions and allocation constraints.
- EU MDR Clinical Evidence Burden:The Medical Device Regulation's extended approval timelines for algorithm-driven diagnostic tools impose 12-18 month delays versus FDA 510(k) pathways, fragmenting commercialization cadence across Atlantic markets.
- Edge Computing Capex Requirements:Intraoperative 3D rendering demands sub-20-millisecond latency, forcing hospital systems to deploy on-premise GPU clusters rather than cloud instances, raising total cost of ownership.
Strategic Opportunities
- India's PLI Scheme for Medical Devices:Production-linked incentives for domestic manufacturing of high-value diagnostic equipment create localized assembly opportunities for visualization hardware targeting price-sensitive hospital networks.
- AI Act Risk Classification Tailwinds:Europe's emerging framework for autonomous segmentation features will recategorize certain diagnostic visualization suites as lower-risk Class IIa devices, potentially streamlining conformity assessment.
- Subscription-Based Software Licensing:Cloud-based rendering engines enable per-procedure pricing models for surgical planning platforms, penetrating mid-tier hospitals previously excluded by perpetual license costs.
Industry Challenges
- Cross-Functional Talent Scarcity:Visualization platform development requires simultaneous expertise in GPU kernel optimization, DICOM interoperability, and clinical workflow design, with qualified engineers concentrated at a handful of academic medical centers.
- ISO 13485 Quality System Burden:Medical-facing products must maintain software lifecycle documentation under IEC 62304 protocols, adding 15-20% overhead to development budgets versus industrial visualization tools.
- Legacy PACS Integration Complexity:Hospital procurement committees prioritize seamless connectivity with existing picture archiving systems, forcing vendors to maintain backward compatibility with decade-old DICOM implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced (3D/4D) Visualization Systems Market |
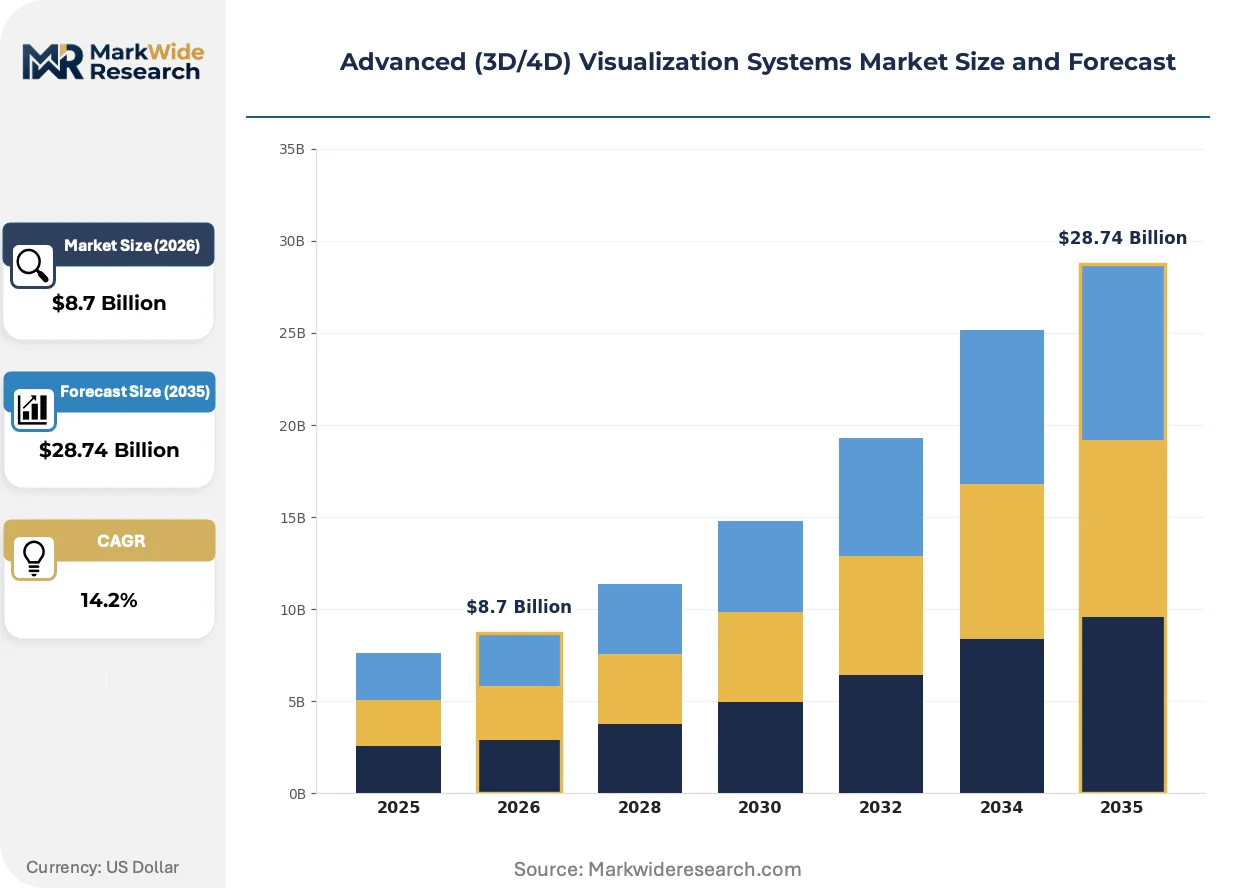
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Integrated Systems, Simulation Tools Application: Entertainment, Medical Imaging, Architectural Visualization, Virtual Prototyping Technology: Augmented Reality, Virtual Reality, Holography, Photogrammetry End User: Healthcare Providers, Design Firms, Educational Institutions, Manufacturing Companies |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips, Canon Medical Systems, Fujifilm Holdings, Agfa-Gevaert Group, Carestream Health, Olympus Corporation, Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced (3D/4D) Visualization Systems Market Emerging Trajectories
Real-time volumetric reconstruction is migrating from dedicated hardware stacks to browser-based WebGL implementations, compressing deployment timelines and democratizing access to previously specialized capabilities.
Neural radiance fields (NeRFs) are digitizing photogrammetric workflows by replacing traditional mesh-based reconstruction with continuous volumetric representations derived from sparse 2D image sets. Academic medical centers in the United States adopt NeRF-based preoperative planning for complex craniofacial procedures, compressing scan-to-model timelines from hours to minutes. The technology is digitizing competitive positioning in surgical simulation by lowering the barrier to patient-specific anatomical modeling.
The EU AI Act's risk-based classification framework is recalibrating development roadmaps for autonomous segmentation algorithms embedded in diagnostic suites. Vendors must now document clinical validation datasets and post-market surveillance protocols before commercializing AI-enhanced visualization tools in European markets. Cardiology workflows face the steepest compliance burden, as real-time 4D echocardiography with automated chamber quantification falls under high-risk system designations.
Hospital procurement committees are unbundling software licenses from hardware maintenance contracts, forcing vendors to compete on standalone algorithmic performance. Subscription pricing for cloud-rendered surgical planning tools is displacing capital-intensive GPU cluster purchases at mid-tier institutions in Germany and France. This behavioral shift is most visible in orthopedic departments, where procedure-specific visualization modules now outpace bundled enterprise agreements.
Advanced (3D/4D) Visualization Systems Market Segmentation
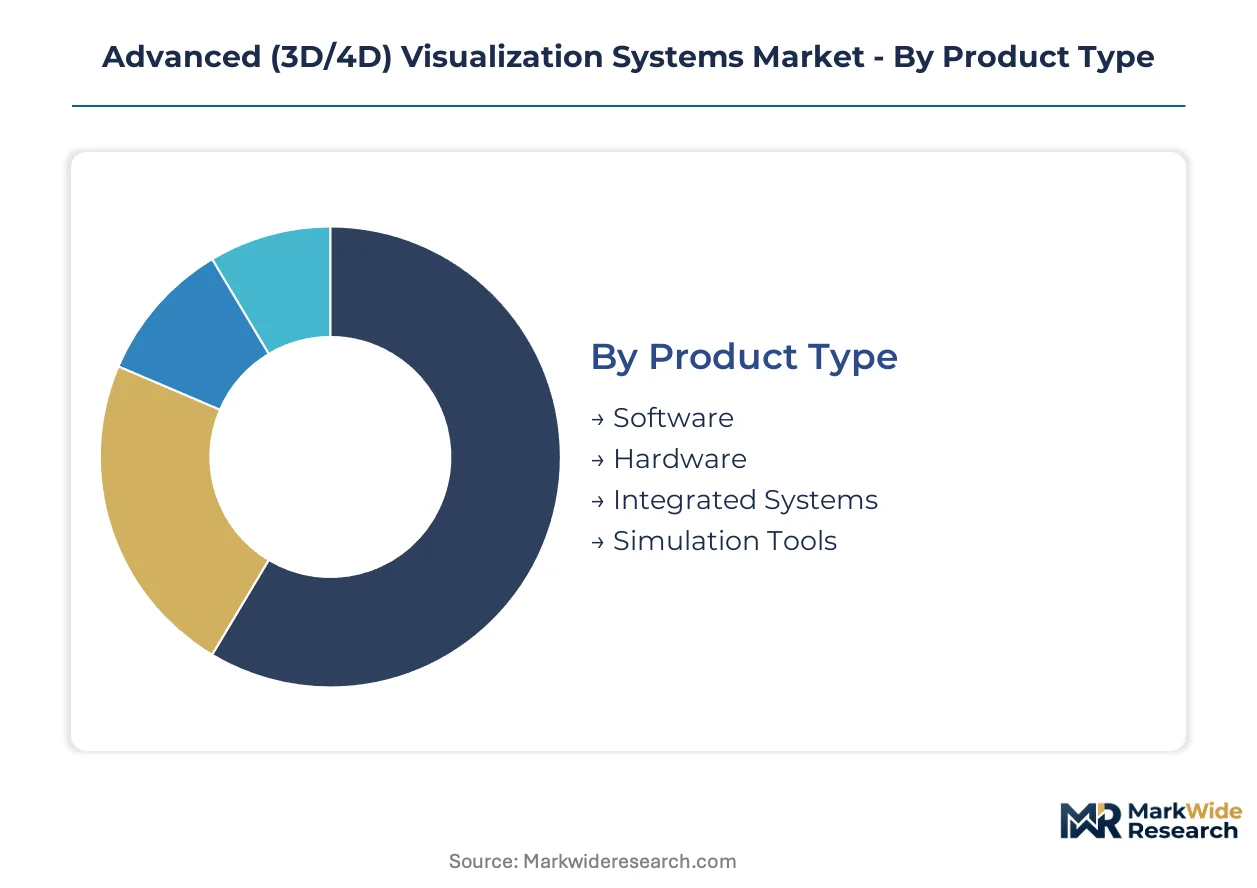
Segmentation in the Advanced (3D/4D) Visualization Systems Market reveals how hardware-software coupling, clinical validation requirements, and end-user procurement power reshape competitive dynamics across product tiers. Vendors must align development roadmaps with the specific latency, interoperability, and liability frameworks governing each application vertical.
Product Type:
Cost tier differentiation separates capital-intensive hardware deployments from recurring software revenue streams, with procurement committees increasingly unbundling these historically integrated offerings.
- Software:Cloud-native rendering engines and browser-based WebGL implementations are decoupling visualization capabilities from proprietary GPU hardware. German university hospitals and automotive design studios in Stuttgart now license standalone modules for cross-platform deployment, compressing deployment timelines while demanding algorithmic performance guarantees independent of hardware vendors.
- Hardware:Specialized GPU clusters and stereoscopic displays command premium pricing due to foundry concentration in Taiwan and South Korea for high-bandwidth memory chips. United States healthcare systems deploy these on-premise to achieve sub-20-millisecond latency for intraoperative 3D rendering, raising total cost of ownership versus cloud alternatives.
- Integrated Systems:Bundled hardware-software offerings dominate cardiology workflows where real-time 4D echocardiography demands tight coupling between acquisition devices and rendering engines.
- Simulation Tools:Physics-based virtual prototyping platforms serve German OEMs compressing physical iteration cycles in automotive development pipelines.
Hardware holds installed capacity. Software is rotating up the share rankings.
Application:
Clinical liability frameworks and validation requirements create margin stratification across use cases, with medical applications commanding substantial premiums over industrial or entertainment deployments.
- Medical Imaging:FDA 510(k) clearance pathways and EU MDR clinical evidence requirements impose divergent conformity assessment burdens, with European approval timelines extending 12-18 months versus United States pathways. Preoperative surgical simulation and diagnostic imaging generate the steepest pricing power due to stringent ISO 13485 quality management standards and IEC 62304 software lifecycle protocols.
- Virtual Prototyping:German automotive OEMs and tier-one suppliers deploy 4D visualization to compress physical iteration cycles, pulling hardware-agnostic software modules originally developed for medical imaging into industrial applications. LiDAR point cloud processing at 30+ frames per second drives GPU cluster demand without clinical liability overhead.
- Architectural Visualization:Immersive walkthroughs for commercial real estate development utilize photogrammetric and NeRF-based reconstruction, with lower validation barriers than medical counterparts.
- Entertainment:Media production and gaming applications prioritize frame rate performance over spatial accuracy, accessing commoditized rendering engines at compressed price points.
Medical Imaging captures margin concentration. Virtual Prototyping is expanding most quickly.
Technology:
Maturity curves and hardware dependency vary sharply across visualization modalities, with some technologies requiring specialized optics while others leverage existing display infrastructure.
- Virtual Reality:Fully immersive headsets with six-degrees-of-freedom tracking dominate surgical training and preoperative planning at United States academic medical centers, though edge computing capex requirements limit penetration at mid-tier hospital networks.
- Augmented Reality:Optical see-through displays overlay volumetric models onto physical anatomy during procedures, with German hospitals piloting intraoperative guidance systems that demand sub-20-millisecond latency.
- Photogrammetry:Dense 3D reconstruction from 2D image sets serves architectural and entertainment applications with moderate computational requirements.
- Holography:Volumetric displays without head-mounted hardware remain confined to specialized medical education and high-end automotive design review due to cost and form factor constraints.
Virtual Reality holds installed capacity. Augmented Reality is climbing the fastest.
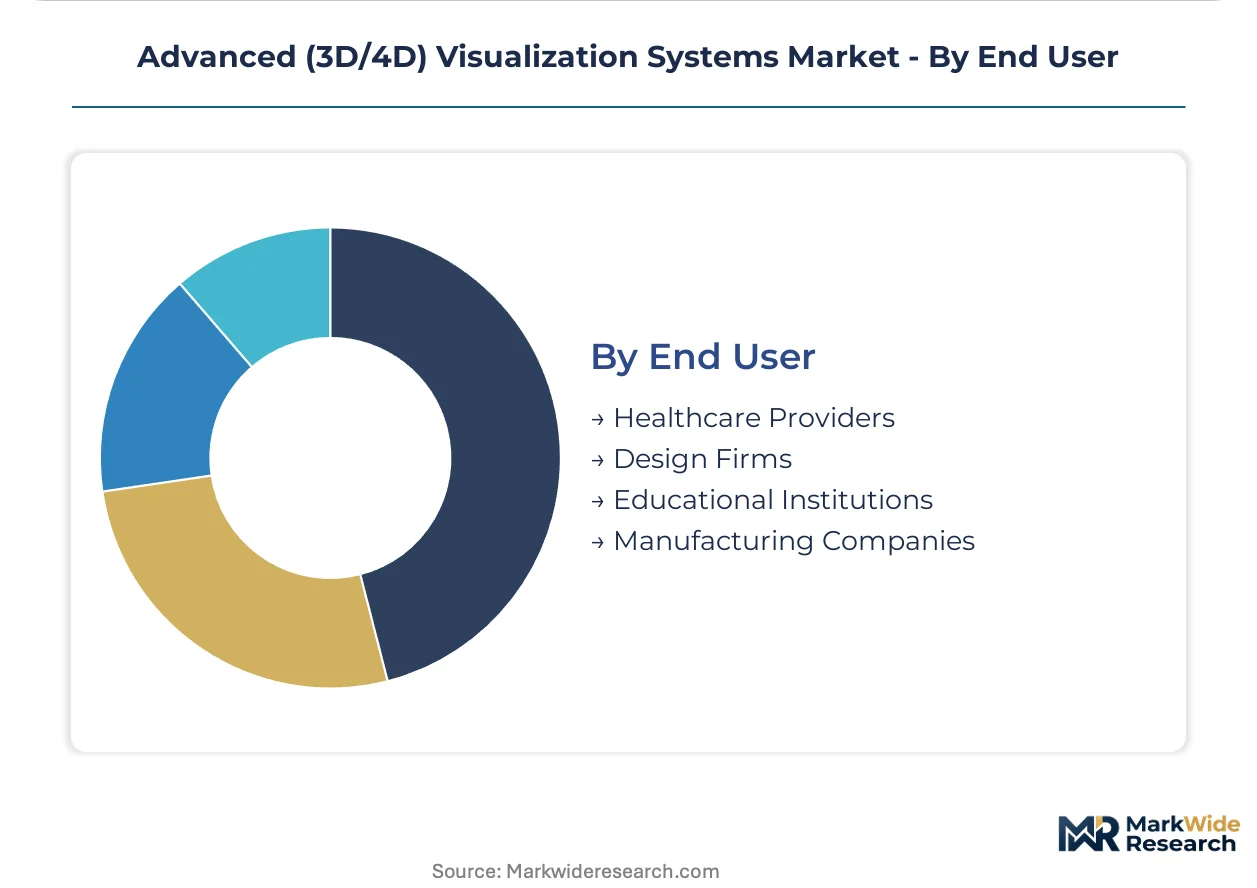
End User:
Procurement authority and technical integration capabilities determine how visualization platforms penetrate organizational workflows, with healthcare providers facing the most complex legacy system interoperability challenges.
- Healthcare Providers:Hospital procurement committees prioritize seamless connectivity with existing PACS infrastructure, forcing vendors to maintain backward compatibility with decade-old DICOM implementations. United States health systems balance FDA 510(k) cleared tools against EU MDR validated alternatives when selecting surgical planning platforms.
- Manufacturing Companies:German automotive and industrial equipment producers leverage visualization for virtual prototyping, with fewer regulatory constraints than medical counterparts enabling faster technology refresh cycles.
- Design Firms:Architectural and product design studios adopt subscription-based cloud rendering to avoid capital-intensive GPU cluster purchases.
- Educational Institutions:Medical schools and engineering programs utilize simulation tools for skills training, with procurement decisions driven by grant funding availability and curriculum integration requirements.
Healthcare Providers hold installed capacity. Manufacturing Companies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Hamburg-Copenhagen fiber corridor and transatlantic subsea cable landing points at Marseille and Bilbao underwrite Europe's data throughput capacity for volumetric rendering workloads. Frankfurt's GPU cluster density and Amsterdam's internet exchange nodes anchor cloud-native visualization infrastructure deployment.
United States
Academic medical centers in Boston and Stanford drive surgical simulation demand for FDA 510(k) cleared platforms. The FDA's streamlined Software-as-a-Medical-Device pathway accelerates commercialization timelines for algorithm-driven diagnostic tools. Hospital networks in Texas and Florida deploy on-premise GPU clusters to achieve sub-20-millisecond latency for intraoperative 3D rendering.
Germany
Automotive OEMs in Stuttgart and Munich compress physical iteration cycles through 4D virtual prototyping platforms originally developed for medical imaging. The EU MDR imposes 12-18 month approval delays versus FDA pathways, fragmenting commercialization cadence. University hospitals in Heidelberg and Berlin license standalone software modules for cross-platform deployment across medical and industrial visualization workflows.
China
Domestic GPU foundry investments in Shanghai and Hefei reduce dependence on Taiwan and South Korean high-bandwidth memory supply. NMPA medical device registration requirements shape localization strategies for foreign visualization vendors. Yangtze River Delta hospital procurement committees prioritize seamless PACS integration with legacy DICOM implementations.
India
Production-linked incentives for domestic manufacturing of high-value diagnostic equipment create localized assembly opportunities for visualization hardware. CDSCO medical device regulations govern import and distribution of surgical planning platforms. Maharashtra and Karnataka hospital networks adopt subscription-based cloud rendering to avoid capital-intensive GPU cluster purchases.
Japan
PMDA quality management standards extend development timelines for AI-enhanced diagnostic visualization suites. METI industrial digitization programs accelerate adoption of virtual prototyping in automotive and precision machinery sectors. Osaka-based medical device distributors navigate reimbursement complexity for real-time 4D echocardiography systems.
Advanced (3D/4D) Visualization Systems Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying GPU clusters and stereoscopic display hardware. The vendor base concentrates among diversified medical technology conglomerates with installed imaging hardware bases. Three archetypes dominate: imaging equipment manufacturers bundling visualization software at point-of-sale, standalone software vendors decoupling rendering engines from proprietary hardware, and industrial automation firms cross-selling virtual prototyping tools. Strategic moves center on unbundling historically integrated offerings and competing on algorithmic performance alone.
Among diversified health technology conglomerates, Siemens Healthineers, GE Healthcare, and Koninklijke Philips occupy positions anchored by installed bases of imaging acquisition devices. These firms exemplify the platform-integrator archetype where tight hardware-software coupling dominates cardiology and surgical planning workflows. Canon Medical Systems and Fujifilm Holdings represent the imaging-specialist tier competing through edge-computing architectures and point-of-care deployment flexibility.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips |
| Canon Medical Systems |
| Fujifilm Holdings |
| Agfa-Gevaert Group |
| Carestream Health |
| Olympus Corporation |
| Stryker |
| Others |
Supply Flow & Price Mechanics
High-bandwidth memory foundry concentration in Taiwan and South Korea anchors GPU cluster pricing power at visualization hardware vendors, while cloud-native rendering engines are decoupling software from this silicon dependency and redistributing margin pools toward algorithm developers.
Pricing Analysis
Volume-discount tiering structures separate enterprise hospital networks purchasing bundled hardware-software systems from mid-tier institutions licensing per-procedure cloud modules. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) certification status, ISO 13485 quality system investment, and after-sales service bundling. Cost compression in the standard tier is intensifying because browser-based WebGL implementations eliminate proprietary GPU requirements. Academic medical centers exhibit lowest price sensitivity due to grant-funded procurement, while mid-tier orthopedic departments in Germany and France drive hardest bargain on subscription terms.
Supply Chain Analysis
Upstream feedstock for high-performance visualization systems draws from Taiwan and South Korea for HBM3 memory stacks, the United States for GPU architecture licensing, and China for display panel assembly. Specialized inputs include TSMC-manufactured AI accelerators, Samsung HBM modules, and precision optics from German and Japanese suppliers. Single-source vulnerability concentrates at the foundry level where two vendors control advanced packaging capacity. Distribution runs through hospital GPO contracts in North America, direct OEM relationships with German automotive manufacturers, and cloud marketplace listings for software-only deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Visualization platform economics are shifting toward service-attach revenue as cloud-rendered surgical planning subscriptions expand faster than capital-intensive GPU cluster sales, rewarding vendors who embed recurring licensing into clinical workflows.
For Market Incumbents: Build switching-cost moats through deep PACS integration and legacy DICOM backward compatibility that locks hospital procurement committees into upgrade cycles. Siemens Healthineers and GE Healthcare should accelerate edge-computing capacity additions in Texas and Florida health systems to defend against cloud-native entrants. FDA 510(k) clearance velocity serves as the critical lever for maintaining premium positioning against software-only competitors. For New Entrants and Emerging Players: Establish a beachhead in India's price-sensitive hospital networks by leveraging PLI scheme incentives for localized hardware assembly paired with cloud-delivered software modules. German automotive design studios present secondary white-space opportunity for cross-selling medical-origin visualization tools into virtual prototyping workflows. Go-to-market angle should emphasize per-procedure pricing that bypasses capital committee approval thresholds. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed software vendors possessing FDA-cleared segmentation algorithms but lacking installed imaging hardware bases. Long-term viability over the coming decade hinges on regulatory moat durability as EU AI Act risk classifications reshape competitive barriers. Monitor NMPA registration timelines for foreign visualization vendors in China as inflection signal for geographic expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Rendering Engine Development | Decouples software revenue from Taiwan-foundry GPU supply constraints. |
| FDA 510(k) Software-as-a-Medical-Device Submission | Accelerates commercialization timelines for algorithm-driven surgical planning tools. |
| Hospital System GPO Partnership | Secures multi-year software licensing commitments with embedded service contracts. |
| NeRF-Based Preoperative Planning Module Launch | Compresses scan-to-model timelines from hours to minutes for craniofacial procedures. |
| EU MDR Clinical Evidence Investment | Reduces 12-18 month approval gap versus FDA pathways for European market access. |
Methodological Framework
A standing panel of biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and automotive platform engineers provided ongoing calibration across primary interview cycles. FDA 510(k) clearance databases, EU MDR notified body submissions, hospital procurement records, and hyperscaler capex disclosures supplied secondary validation. Bottom-up triangulation across software licensing volumes and hardware shipment data converged with top-down spending estimates from health system IT budgets.
Scenario-bracketing framed low, base, and high cases across the projection horizon based on regulatory approval velocity and cloud adoption curves. Segmentation dimensions modeled include product type coupling, application vertical liability frameworks, technology maturity curves, and end-user procurement authority. CAGRs derived from fitted growth curves applied to base-year sizing, with cross-checks against GPU cluster deployment rates at academic medical centers and LiDAR processing demand from autonomous vehicle developers.
Sensitivities concentrate around FDA guidance shifts for AI-enhanced diagnostic tools, Taiwan foundry allocation disruptions, and EU AI Act risk classification finalization. Cross-checking against CMS Medicare reimbursement determinations for real-time 4D echocardiography is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Projector Screen Market
Display Technologies
Quantum Dot Display Market
Display Technologies
Graphic LCD Modules Market
Display Technologies
Vietnam Digital Signage Market
Display Technologies
Virtual Retinal Display (VRD) Market
Display Technologies
Touch Screen Film Market
Display Technologies
Surface-Conduction Electron-Emitter Display (SED) Market
Display Technologies
AMOLED Substrate Market
Display Technologies
Interactive Display Market
Display Technologies
Electronic Display Market
Display Technologies
Global Display Controllers Market
Display Technologies
Wireless Display Market
Display Technologies
Global Industrial Display System Market
Display Technologies
Tablets and Notebook Display Market
Display Technologies
Electronic Paper Display (EPD) Market
Display Technologies
Global Next Generation Display Market