
 Touch Screen Film Market | 2026-2036
Touch Screen Film Market Size, Share, and Industry Trends Forecast 2026-2036
Touch Screen Film Market Analytics
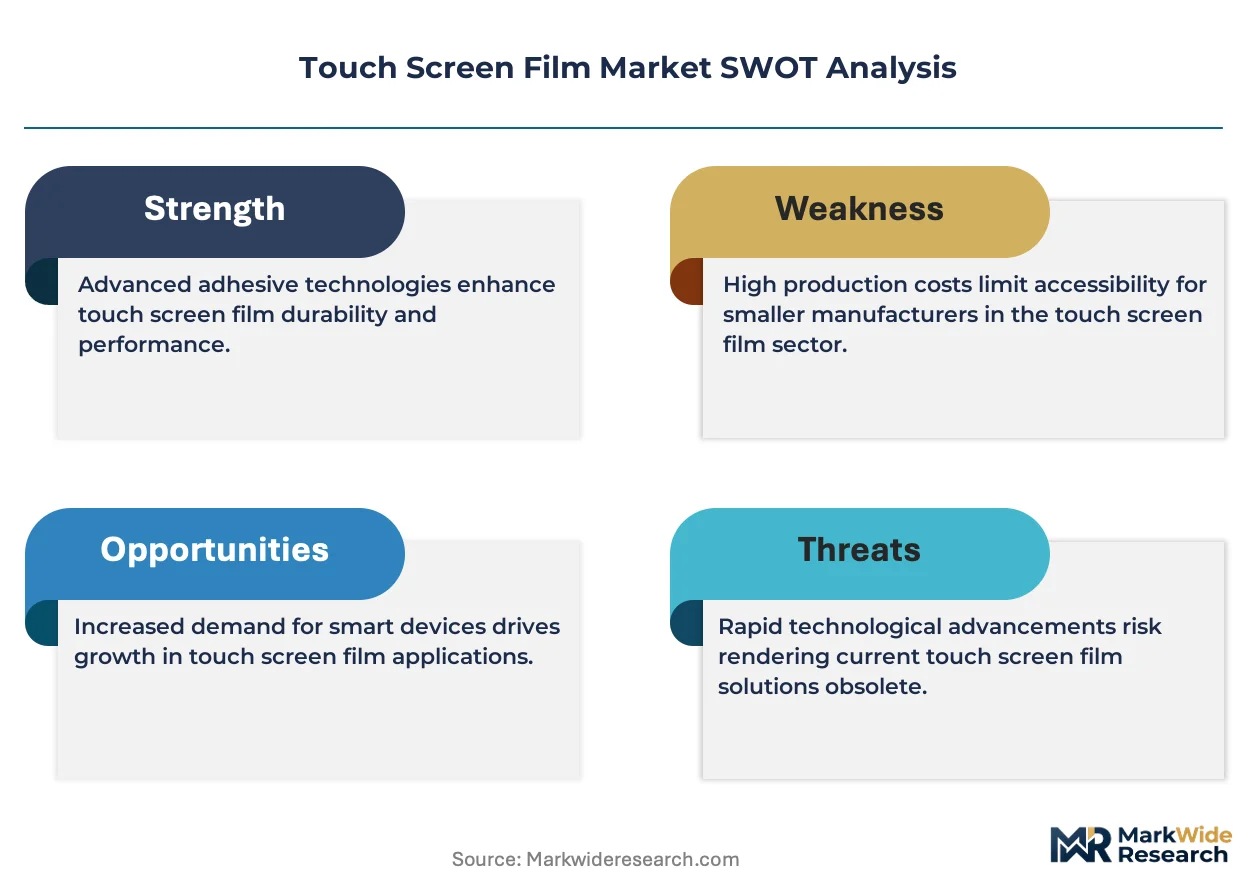
The capital-intensity divergence between vertically integrated substrate producers and specialized coating houses is unwinding competitive stability in touch screen film supply. Nitto Denko Corporation leverages its in-house polymer synthesis to control optical-grade PET supply chains from resin to finished film. DuPont anchors its position through fluoropolymer coating intellectual property that sustains premium pricing in anti-reflective and anti-fingerprint layers. Tesa SE competes by specializing in precision adhesive formulations that bond films to cover glass under automotive thermal cycling requirements.
Touch screen film comprises a multi-layer optoelectronic laminate, typically constructed from polyethylene terephthalate or cyclo olefin polymer substrates with sputtered indium tin oxide or silver nanowire conductive layers, engineered to transmit visible light while registering capacitive or resistive touch inputs. Capacitive films dominate volume shipments due to smartphone and tablet ubiquity, though resistive films retain niche industrial applications where gloved operation or stylus precision outweighs multi-touch capability. Optical films command margin concentration in automotive and premium display segments where haze specifications below 0.5% and transmission above 90% justify specialized coating processes.
FDA device classification for touchscreen healthcare interfaces, EPA TSCA reporting for nanomaterial-containing conductive inks, and EU REACH substance restrictions on phthalate plasticizers collectively elevate compliance costs while filtering out non-specialized film converters. These frameworks push manufacturers toward pre-certified material platforms and documented supply chain transparency. Stakeholders must monitor evolving automotive safety standards for distracted-driving mitigation, as regulators assess whether haptic feedback requirements will mandate thicker or structurally modified film stacks.
Market Dynamics
Automotive OEMs are forcing substrate suppliers to requalify film stacks for curved and free-form displays, compressing development cycles while tightening optical uniformity specifications beyond consumer electronics thresholds.
Growth Catalysts
- Infotainment Display Expansion:Automotive OEMs in Germany, Japan, and the US are mandating larger touch interfaces across center stacks and digital instrument clusters, pulling optical-grade film volumes into vehicle programs.
- REACH Substance Restrictions:ECHA's evolving SVHC candidate list is accelerating substitution of phthalate plasticizers with bio-based alternatives, creating certified-material premiums for compliant converters.
- Silver Nanowire Conductive Layers:Panel makers in China are adopting silver nanowire patterning for foldable and stretchable displays, opening film specifications beyond traditional ITO sputtering constraints.
Market Restraints
- Indium Supply Concentration:Refining capacity for indium tin oxide feedstock concentrates in Chinese smelters, exposing film coaters to price volatility and export license uncertainty.
- Optical PET Substrate Oligopoly:Biaxially oriented polyester film for touch applications sources from a handful of resin-to-film integrators, limiting second-source options during capacity tightness.
- ITO Patterning Resolution Ceiling:Sputtered indium tin oxide films face linewidth limits around 3 microns, constraining fine-pitch designs for micro-LED and high-PPI applications.
Strategic Opportunities
- Indian Display Fab Localization:PLI scheme incentives for semiconductor and display manufacturing are drawing module assembly investments, creating captive film slitting and coating demand near panel production.
- Antimicrobial Surface Coatings:FDA device classification pathways for healthcare touch interfaces are opening specification premiums for films with integrated copper-ion or photocatalytic surface treatments.
- Photovoltaic-Integrated Vehicle Surfaces:Solar roof and hood applications are converging with touch-sensitive controls, requiring optoelectronic laminates that combine conductivity with infrared transmission for cell efficiency.
Industry Challenges
- Cleanroom Coating Talent Scarcity:Precision roll-to-roll sputtering and wet coating operations require operators trained in particle control and thickness metrology, with limited vocational pipeline output.
- Automotive Qualification Timelines:AEC-Q100 and OEM-specific validation protocols demand 18-24 month pre-production cycles, locking working capital in inventory before volume shipments commence.
- Cross-Border Chemical Disclosure:TSCA reporting requirements for nanomaterial-containing conductive inks conflict with supplier confidentiality practices, complicating supply chain documentation.
Report Scope
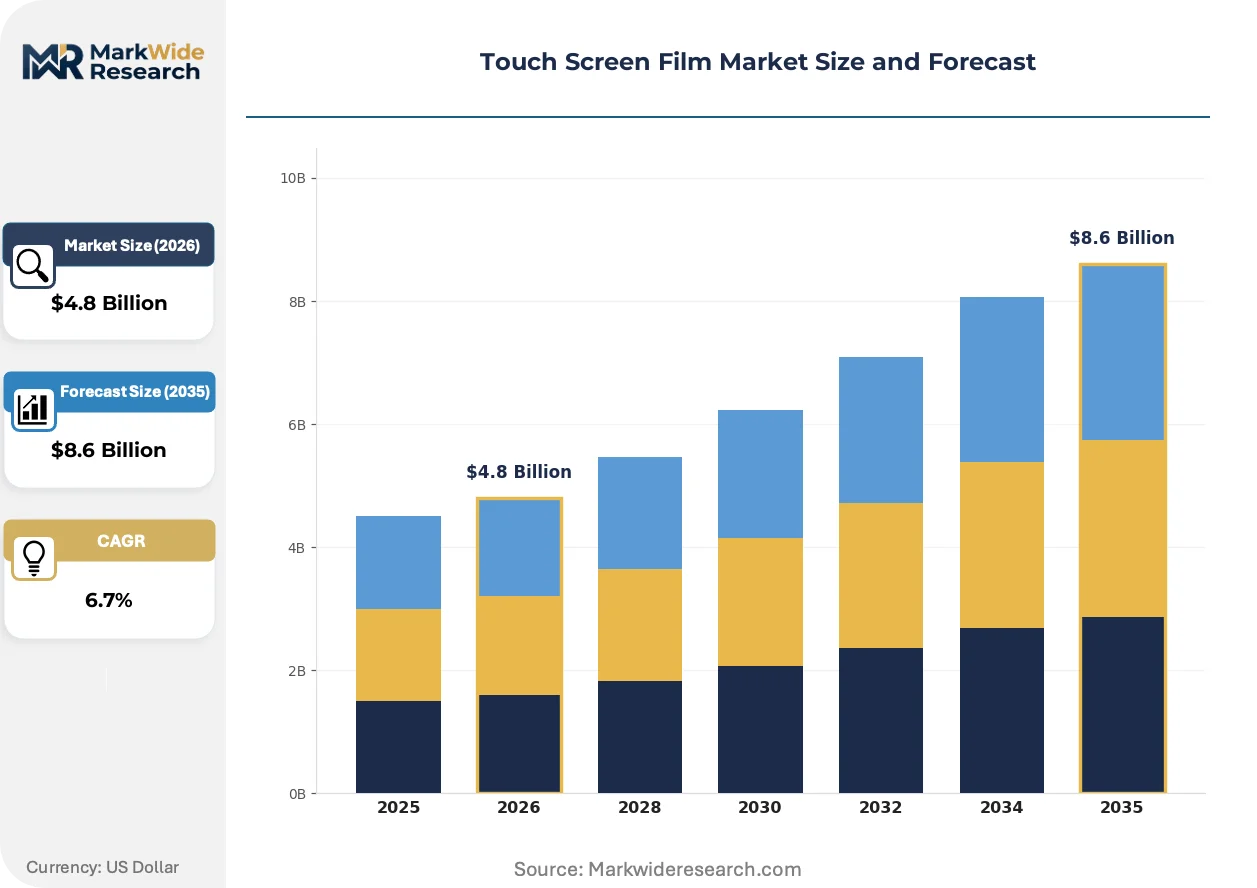
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Touch Screen Film Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive Films, Resistive Films, Optical Films, Protective Films Application: Smartphones, Tablets, Laptops, Kiosks Technology: Touch Sensing, Display Transparency, Anti-Glare, Anti-Reflective End User: Consumer Electronics, Automotive, Industrial Equipment, Healthcare |
| Companies Covered | 3M, Nitto Denko Corporation, DuPont, LG Chem, Tesa SE, Mitsubishi Plastics, Avery Dennison Corporation, Saint-Gobain, TPK Holding Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Touch Screen Film Market Evolving Landscape
Material science advances and regulatory disclosure mandates are restructuring how touch film specifications propagate from substrate resin through finished laminate qualification.
Metal mesh conductive patterns are displacing conventional ITO sputtering in automotive and large-format display applications. Tier-1 panel suppliers in Korea and Taiwan are qualifying copper-based mesh films for 15-inch and larger touch modules. This displacement is compressing capital requirements for coating equipment while enabling lower sheet resistance at equivalent optical transmission.
EU REACH substance restrictions on per- and polyfluoroalkyl substances are forcing reformulation of anti-fingerprint and anti-reflective topcoats. Film coaters must resubmit dossiers to ECHA for fluoropolymer alternatives, extending requalification timelines. Automotive and medical device segments are absorbing these compliance costs through material-grade pricing stratification.
Direct procurement relationships between automotive OEMs and film converters are shortening the value chain. Module integrators in Germany and Japan are losing specification control as vehicle manufacturers issue material approval documents directly to substrate coaters. This channel compression is most visible in electric vehicle platforms where display integration occurs earlier in vehicle architecture design.
Touch Screen Film Market Segmentation
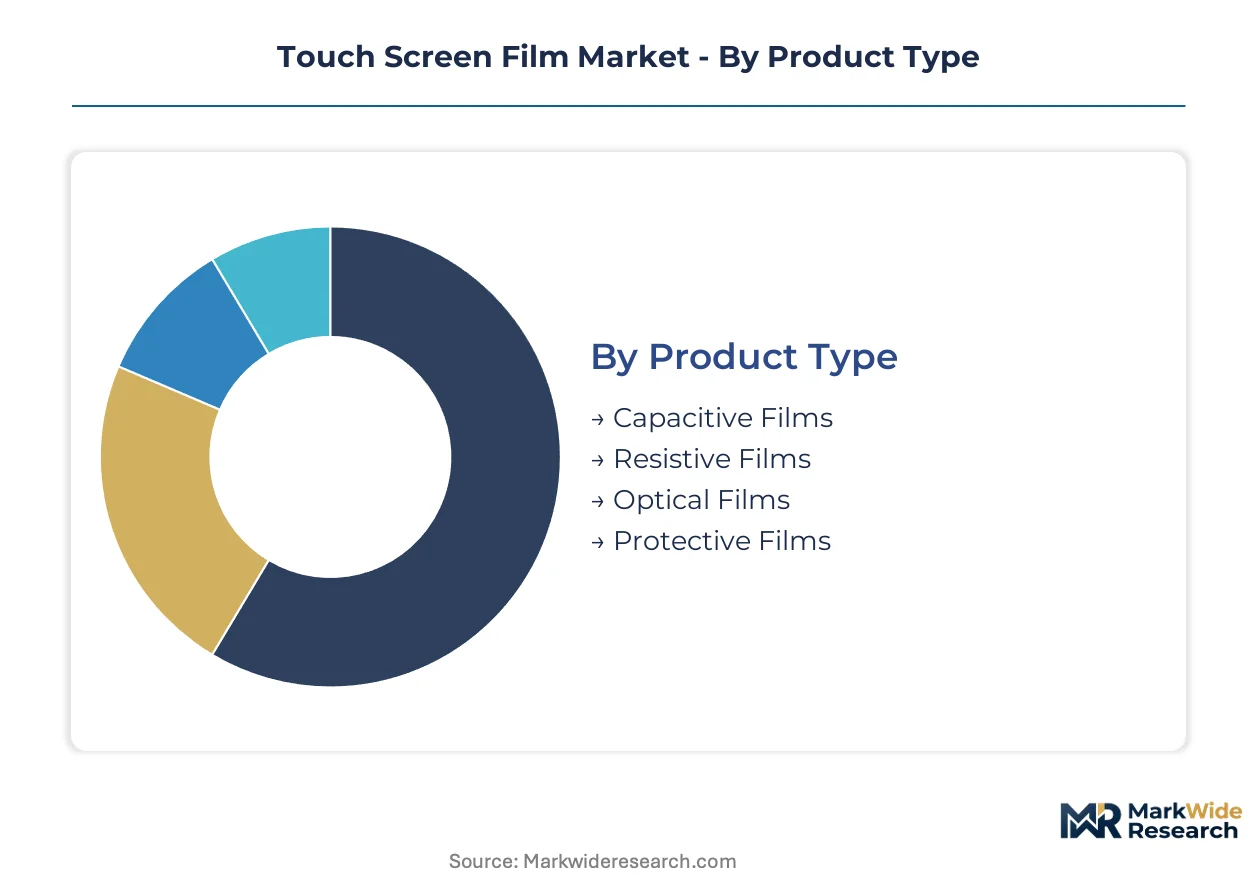
Touch screen film specifications diverge sharply across end-use environments, with automotive thermal cycling requirements and healthcare antimicrobial mandates creating incompatible certification pathways that fragment procurement strategies.
Product Type:
Capacitive and resistive architectures face divergent substitution pressures from metal mesh and silver nanowire alternatives that promise lower sheet resistance without ITO sputtering constraints.
- Capacitive Films:Multi-layer laminates employing sputtered indium tin oxide or silver nanowire conductive layers on PET or cyclo olefin polymer substrates, optimized for multi-touch registration. Smartphone and tablet manufacturers in China dominate procurement volumes, though automotive curved-display qualifications are compressing development cycles. ECHA REACH substance restrictions on phthalate plasticizers force reformulation of adhesive bonding layers.
- Optical Films:Precision-coated substrates engineered for haze specifications below 0.5% and visible light transmission above 90%, commanding margin concentration in premium display segments. German and Japanese automotive OEMs mandate these films for center-stack and digital instrument cluster applications where optical uniformity thresholds exceed consumer electronics benchmarks.
- Resistive Films:Pressure-sensitive conductive layers retaining niche industrial deployment where gloved operation or stylus precision outweighs multi-touch capability.
- Protective Films:Surface-hardened topcoats guarding against abrasion and chemical exposure in high-traffic kiosk and industrial deployments.
Capacitive films retain volume leadership; optical films hold the steepest expansion curve.
Application:
Cost tier stratification separates commodity smartphone procurement from automotive and industrial segments where qualification premiums justify specialized coating investments.
- Smartphones:High-volume capacitive film consumption driven by panel makers in China expanding captive film sourcing to reduce import dependency. Silver nanowire patterning adoption for foldable form factors is opening specifications beyond traditional ITO sputtering constraints.
- Automotive:Curved and free-form display deployments across center stacks and digital instrument clusters force substrate requalification with tightened optical uniformity specifications. German OEMs issue material approval documents directly to film converters, compressing module integrator influence.
- Tablets:Stagnant volume growth as enterprise refresh cycles extend and hybrid laptop-tablet devices capture marginal demand.
- Kiosks:Public-access touch interfaces requiring enhanced durability coatings and antimicrobial surface treatments under FDA device classification pathways.
Smartphone applications retain volume leadership; automotive applications hold the steepest expansion curve.
Technology:
Display transparency and anti-reflective coating specifications concentrate margin capture in automotive and medical device segments where performance premiums absorb compliance costs.
- Anti-Reflective:Fluoropolymer-based vacuum-deposited or wet-coated layers sustaining premium pricing through DuPont intellectual property positions. EU REACH restrictions on per- and polyfluoroalkyl substances force ECHA dossier resubmission, extending requalification timelines.
- Touch Sensing:Capacitive and resistive electrode patterning technologies facing displacement by metal mesh conductive layers in large-format and automotive applications.
- Display Transparency:Optical-grade substrate and coating integration for high-transmission, low-haze requirements in premium display stacks.
- Anti-Glare:Surface micro-structuring or particle-loaded coatings diffusing ambient light reflection in bright-environment deployments.
Touch sensing retains volume leadership; anti-reflective coatings hold the steepest expansion curve.
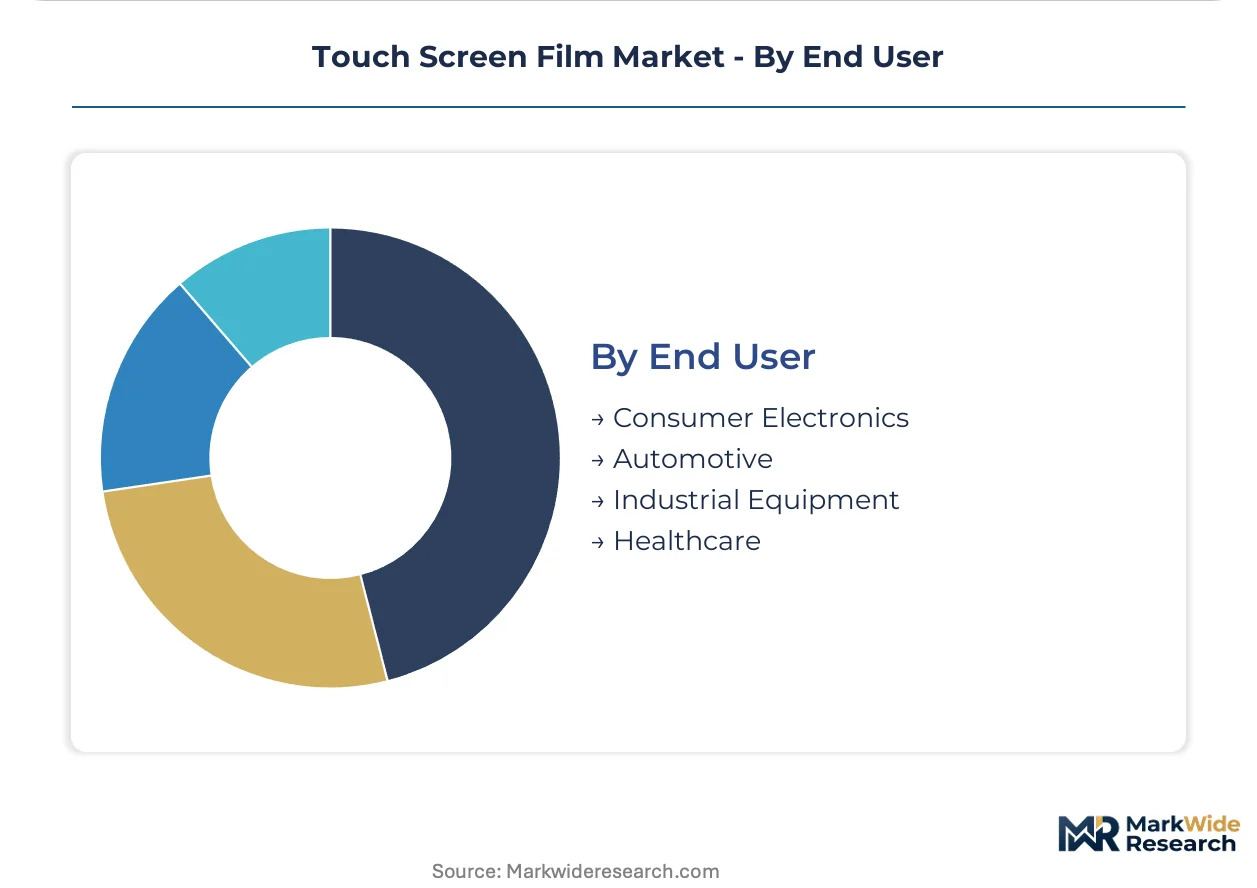
End User:
Customer type segmentation separates price-sensitive consumer electronics procurement from automotive and healthcare segments where regulatory compliance creates certified-material premiums.
- Automotive:OEMs in Germany, Japan, and the US mandate larger touch interfaces across vehicle programs, pulling optical-grade film volumes with 18-24 month AEC-Q100 qualification timelines. NHTSA distracted-driving mitigation assessments may mandate haptic feedback requirements affecting film stack thickness specifications.
- Healthcare:FDA device classification for touchscreen interfaces opens specification premiums for films with integrated copper-ion or photocatalytic antimicrobial surface treatments. EPA TSCA reporting requirements for nanomaterial-containing conductive inks complicate supply chain documentation.
- Consumer Electronics:Panel assembly concentration in China driving captive film sourcing strategies among domestic substrate coaters.
- Industrial Equipment:Gloved-operation and harsh-environment requirements sustaining resistive film demand despite capacitive technology advancement.
Consumer electronics retains volume leadership; automotive holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes touch screen films primarily for smartphone and tablet panel production, while Germany and the United States concentrate demand in automotive curved-display qualifications with stricter optical uniformity thresholds. This consumption-mix differential shapes divergent supply chain configurations across geographies.
China
Domestic panel makers in Shenzhen and Suzhou are expanding captive film coating capacity to reduce import dependency on Japanese and Korean substrate suppliers. MIIT guidelines on display industry localization incentivize backward integration into optical-grade PET resin production. The Yangtze River Delta cluster hosts concentrated silver nanowire patterning investments for foldable display applications.
Germany
Automotive OEMs in Munich and Stuttgart mandate direct material approval documents to film converters, bypassing traditional module integrators in procurement chains. KBA vehicle safety assessments intersect with ECHA REACH substance restrictions on phthalate plasticizers in adhesive layers. The Baden-Württemberg region anchors qualification laboratories for AEC-Q100 automotive film validation protocols.
United States
EPA TSCA reporting requirements for nanomaterial-containing conductive inks complicate supply chain documentation for healthcare touch interface deployments. NHTSA distracted-driving mitigation assessments may mandate haptic feedback specifications affecting film stack thickness. Michigan and Texas host automotive display integration engineering centers pulling optical film volumes.
Japan
Display component suppliers in Osaka and Nagoya maintain precision roll-to-roll sputtering operations for indium tin oxide conductive layers. METI industrial technology roadmaps prioritize substitution strategies for indium supply concentration risks. The Kanto region concentrates cleanroom coating talent pools trained in particle control metrology.
South Korea
Panel suppliers in Gyeonggi Province qualify copper-based metal mesh films for large-format automotive touch modules exceeding 15 inches. MFDS medical device regulations create parallel certification pathways for antimicrobial surface treatments in healthcare interfaces. The Seoul Capital Area hosts convergent R&D on photovoltaic-integrated vehicle surface applications.
Touch Screen Film Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with resin-to-film producers controlling substrate supply while coating houses compete on precision formulation capabilities. The market structure concentrates margin capture among optical-grade PET integrators and fluoropolymer coating intellectual property holders. Three archetypes dominate: vertically integrated polymer producers, precision adhesive specialists, and sputtered conductive layer coaters. Competitive moves center on automotive qualification pre-positioning and REACH-compliant material platform development.
Among integrated Japanese material producers, Nitto Denko Corporation exemplifies the resin-synthesis-to-finished-film archetype through captive optical-grade PET supply chain control. DuPont occupies a position within the fluoropolymer coating tier, anchoring premium pricing in anti-reflective and anti-fingerprint layer segments through specialized intellectual property positions. Tesa SE represents the precision adhesive specialist archetype, with German GmbH structure indicating European formulation engineering focused on automotive thermal cycling requirements.
| Leading Market Players |
|---|
| 3M |
| Nitto Denko Corporation |
| DuPont |
| LG Chem |
| Tesa SE |
| Mitsubishi Plastics |
| Avery Dennison Corporation |
| Saint-Gobain |
| TPK Holding Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Eighteen-to-twenty-four month automotive qualification timelines lock working capital in inventory before volume shipments commence, concentrating pricing power among resin-to-film integrators who control optical-grade PET substrate supply while compressing margins for specialized coating houses dependent on external resin sourcing.
Pricing Analysis
Long-term offtake contracts dominate procurement between automotive OEMs and film converters, though spot purchasing persists in consumer electronics segments where panel makers in China optimize working capital through just-in-time inventory. Three-tier pricing structure across premium, standard, and economy levels separates automotive AEC-Q100 certified films from industrial-grade and consumer electronics tiers, with certification premiums absorbing REACH compliance costs. Pricing pressure stems from indium supply concentration in Chinese smelters exposing coaters to export license uncertainty. Consumer electronics panel assemblers exhibit highest price sensitivity, while German automotive OEMs accept material-grade premiums for direct qualification pathways.
Supply Chain Analysis
Inventory cycles stretching across multiple quarters reflect the oligopolistic structure of biaxially oriented polyester film production, where resin-to-film integration concentrates in Japan, South Korea, and Germany. Raw material dependencies center on high-purity indium for ITO sputtering, optical-grade PET resin, and fluoropolymer precursors for anti-reflective coatings. Single-source vulnerability runs through indium refining capacity concentrated in Chinese state-controlled smelters. Distribution runs through direct procurement relationships between automotive OEMs and film converters, bypassing traditional module integrators in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive curved-display qualifications and healthcare antimicrobial mandates fragment procurement strategies, creating specialized niches for coating houses with precision formulation capabilities and certified-material platforms.
For Market Incumbents: Fortify resin-to-film integration positions through captive optical-grade PET supply chain control, as Nitto Denko Corporation exemplifies, while accelerating REACH-compliant material platform development to capture certified-material premiums as ECHA substance restrictions tighten. Silver nanowire patterning adoption for foldable displays threatens traditional ITO sputtering investments, demanding R&D pivot toward metal mesh and nanowire conductive layer capabilities. For New Entrants and Emerging Players: Differentiate on antimicrobial surface coating specialization for FDA-classified healthcare touch interfaces, where copper-ion and photocatalytic treatments command specification premiums absent from commodity consumer electronics procurement. Target Indian display fab localization under PLI scheme incentives, positioning captive film slitting and coating capacity near emerging panel assembly investments. Pursue direct qualification relationships with German automotive OEMs bypassing module integrators. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized precision roll-to-roll coating assets and dormant fluoropolymer intellectual property positions applicable to anti-fingerprint and anti-reflective layers. Five-to-ten year viability hinges on automotive electrification sustaining curved-display touch interface expansion. Signal to watch: NHTSA distracted-driving mitigation assessments mandating haptic feedback specifications that structurally modify film stack thickness requirements.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Platform Development | ECHA substance restrictions on phthalate plasticizers force reformulation investments that filter out non-specialized converters. |
| Silver Nanowire Patterning Capacity Addition | Panel makers in China adopt nanowire specifications for foldable displays beyond traditional ITO sputtering constraints. |
| Direct Automotive OEM Qualification Pathway | German and Japanese vehicle manufacturers issue material approval documents directly to film converters, compressing module integrator influence. |
| Antimicrobial Surface Coating Certification | FDA device classification pathways for healthcare interfaces open specification premiums for copper-ion integrated films. |
| Indian Display Fab Localization Partnership | PLI scheme incentives for semiconductor manufacturing create captive film slitting demand near panel assembly clusters. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, ECHA REACH dossier submissions, and automotive OEM supplier qualification documents, combining structured interviews with substrate coating plant managers, Tier 1 supplier procurement leads, and regulatory affairs specialists at film converters with bottom-up and top-down triangulation across product type, application, technology, and end user segmentation dimensions.
Segmentation dimensions modeled span product type, application, technology, and end user categories across the analysis window, with CAGRs derived from elasticity-adjusted demand projections incorporating automotive content-per-vehicle trajectories and healthcare device penetration rates. Forecast inputs include panel maker capacity expansion announcements, AEC-Q100 qualification pipeline visibility, and ECHA SVHC candidate list evolution.
The analysis sits within stated boundaries; outcomes outside sustained automotive electrification investment and stable indium supply flows would require recalibration. Forecasts reflect documented assumptions about regulatory timeline adherence and technology substitution rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Dot-Matrix LCD Modules Market
Display Technologies
Foldable Screens Market
Display Technologies
Smart Screen Market
Display Technologies
Global Industrial Display System Market
Display Technologies
Commercial Touch Display Market
Display Technologies
Automotive LCD Display Market
Display Technologies
TFT LCD Panel Market
Display Technologies
Global Monochrome Display Market
Display Technologies
Asia Pacific Computer Monitor Market
Display Technologies
Gaming Monitors Market
Display Technologies
Seven Segment Display Market
Display Technologies
Global Portable Monitor Market
Display Technologies
Display Fingerprint Technology Market
Display Technologies
Global 5K Display Resolution Market
Display Technologies
North America Head-Up Display Market
Display Technologies
Volumetric Display Market