
 Thin Display Technology Market | 2026-2036
Thin Display Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Thin Display Technology Market Analytics
Panel refurbishment and lifecycle extension services is reconfiguring margin pools away from virgin manufacturing. Samsung Electronics Co., Ltd. leverages its captive OLED capacity to dominate premium smartphone supply chains. LG Display Co., Ltd. anchors large-format OLED production for televisions while navigating competitive pressure from Chinese rivals. BOE Technology Group Co., Ltd. extends its position through massive Gen 10.5 fab scale in Hefei and Wuhan.
Thin display technology encompasses emissive and transmissive visual output devices with sub-3mm module thickness, typically fabricated on glass or polyimide substrates using photolithographic patterning, thin-film transistor backplanes, and precision vapor deposition for organic or quantum-dot emissive layers. These systems render high-resolution imagery for direct-view consumer and commercial interfaces where spatial constraints, luminance efficiency, and form-factor flexibility govern design. OLED panels command premium pricing in smartphones and wearables due to self-emissive architecture eliminating backlight bulk, while MicroLED remains nascent with manufacturing yield challenges constraining volume. LCD retains cost leadership in monitors and entry televisions though quantum-dot enhancement layers are displacing conventional phosphor-based color conversion.
The US FCC enforces electromagnetic emissions standards that shape backlight driver circuit design and wireless-integrated display modules. China's MIIT mandates GB standards for energy consumption and recyclability that influence panel architecture and factory certification. Korea's K-Display roadmap and the EU RoHS directive restrict hazardous substances in semiconductor deposition processes, compelling material substitutions across supply chains. Stakeholders must monitor which regulatory jurisdiction captures standard-setting authority as regional decarbonization timelines diverge and carbon-border adjustments threaten export competitiveness.
Market Dynamics
Automotive OEMs are accelerating curved OLED integration for instrument clusters, compressing design cycles and forcing fab reconfiguration toward flexible substrate capacity.
Growth Catalysts
- Automotive cockpit digitization:Curved instrument clusters and passenger entertainment screens are pulling OLED capacity away from consumer electronics. Tier-1 suppliers are qualifying flexible panels for 2026 model-year vehicles.
- Korea's K-Display roadmap:Government-backed targets for energy-efficient manufacturing are accelerating blue PHOLED commercialization and low-temperature polycrystalline silicon process refinement.
- Gen 10.5 glass substrate scale:3370mm × 2940mm motherglass economics in Hefei and Wuhan are collapsing cost-per-square-meter for 65-inch and larger television panels.
Market Restraints
- Input cost volatility:Indium tin oxide and high-purity rare-earth phosphor prices swing with mining output from Chinese separation facilities, squeezing margin predictability for LCD quantum-dot enhancement layers.
- Supply concentration risk:Canon Tokki vapor deposition equipment and Nippon Electric Glass substrate supply each flow from fewer than three qualified sources, creating single-point vulnerability for OLED expansion.
- MicroLED manufacturing yield:Mass transfer defect rates above 0.001% prevent cost-competitive television production, locking the technology in premium commercial signage niches.
Strategic Opportunities
- Vietnam fab consolidation:Panel assembly and module integration are migrating to Bac Ninh and Hai Phong to exploit tariff differentials and proximity to Chinese polarizer and driver IC supply.
- EU RoHS substance restrictions:Exemptions for cadmium-based quantum dots expire in 2025, creating first-mover advantage for indium phosphide and perovskite alternative formulations.
- Head-up display convergence:Waveguide optics and micro-OLED microdisplays are merging in augmented-reality automotive applications, opening new specification tiers beyond conventional dashboard screens.
Industry Challenges
- Deposition process engineering talent:Vapor-phase organic material precision and encapsulation layer defect control require specialists concentrated in Korean and Japanese equipment vendor ecosystems, constraining Chinese fab ramp speed.
- Carbon-border compliance documentation:EU CBAM phase-in demands granular Scope 1-3 emissions tracking from polysilicon refining through module assembly, forcing ERP system overhauls at vertically integrated suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin Display Technology Market |
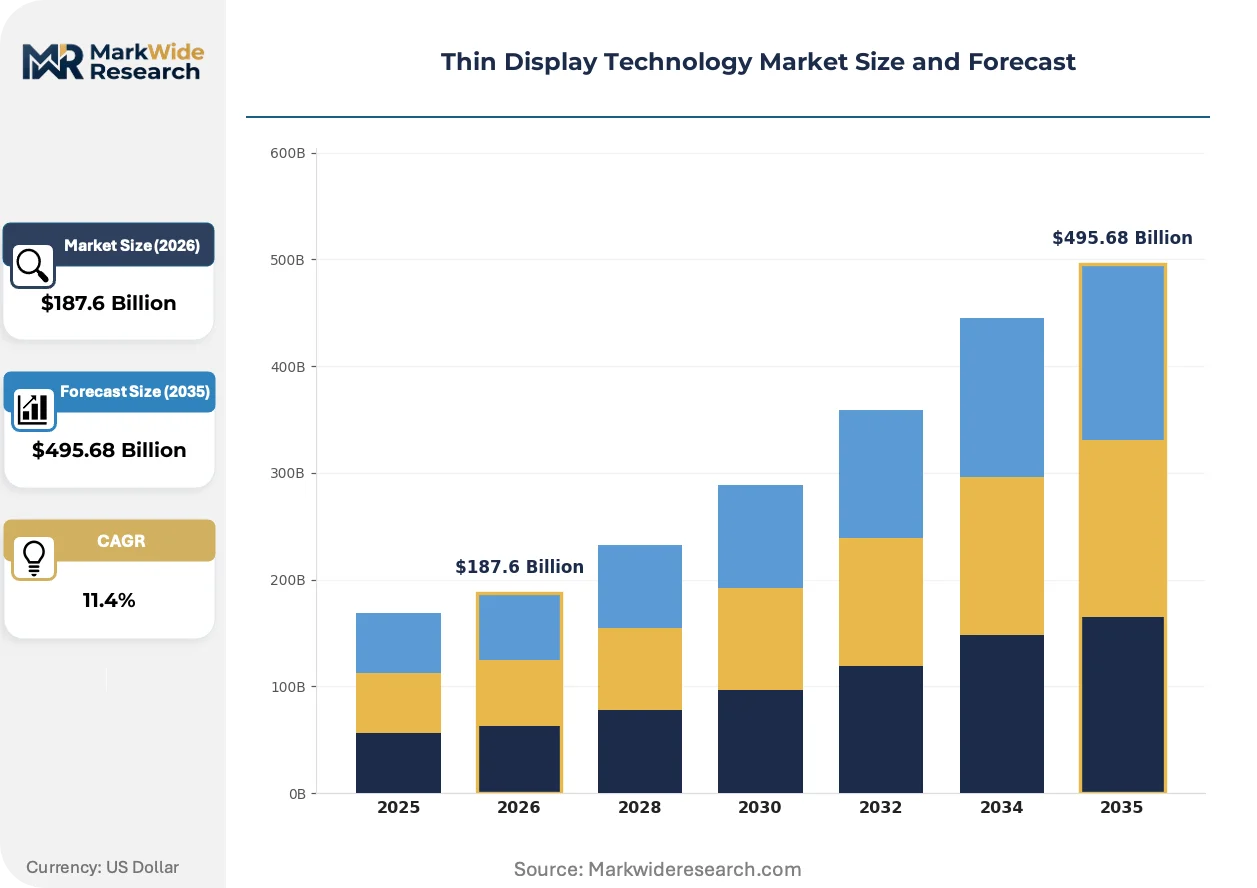
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $495.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, LCD, QLED Application: Smartphones, Monitors, Televisions, Wearables Technology: Active Matrix, Passive Matrix, Quantum Dot, MicroLED End User: Consumer Electronics, Automotive, Advertising, Gaming |
| Companies Covered | Samsung Electronics Co., Ltd., LG Display Co., Ltd., BOE Technology Group Co., Ltd., AUO Corporation, Innolux Corporation, Sharp Corporation, Japan Display Inc., Visionox, Royole Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin Display Technology Market Evolving Landscape
Photolithographic patterning resolution limits and emissive material stability constraints are simultaneously compressing technical roadmaps and opening substitution windows for quantum-dot and microLED architectures.
Hybrid OLED structures combining rigid glass substrates with thin-film encapsulation are collapsing the thickness and weight premiums that previously separated flexible from conventional panels. Automotive tier-1 suppliers are adopting these configurations for curved instrument clusters at volumes previously reserved for premium smartphones. The technology is collapsing the traditional segmentation between mobile and automotive specification tiers.
China's MIIT GB standards for display energy consumption and recyclability are tightening factory certification requirements and disqualifying older LCD phosphor-backlight architectures from government procurement. Panel makers are responding with mini-LED local dimming and quantum-dot color conversion to maintain eligibility. Television and monitor segments serving state-owned enterprise channels face the most acute compliance pressure.
Direct procurement relationships between automotive OEMs and panel fabs are displacing traditional tier-1 display module integrators. Hyundai Motor and BYD are negotiating annual volume commitments directly with BOE and Samsung Display, extracting price transparency and technical co-development terms previously mediated by Denso or Panasonic Automotive. This pattern is most advanced in Korea and China, where captive semiconductor and battery supply chain experience has normalized direct sourcing.
Thin Display Technology Market Segmentation
Thin display technology segments diverge sharply by emissive architecture, substrate flexibility, and power envelope. Each category channels capital toward distinct fab configurations and customer qualification cycles.
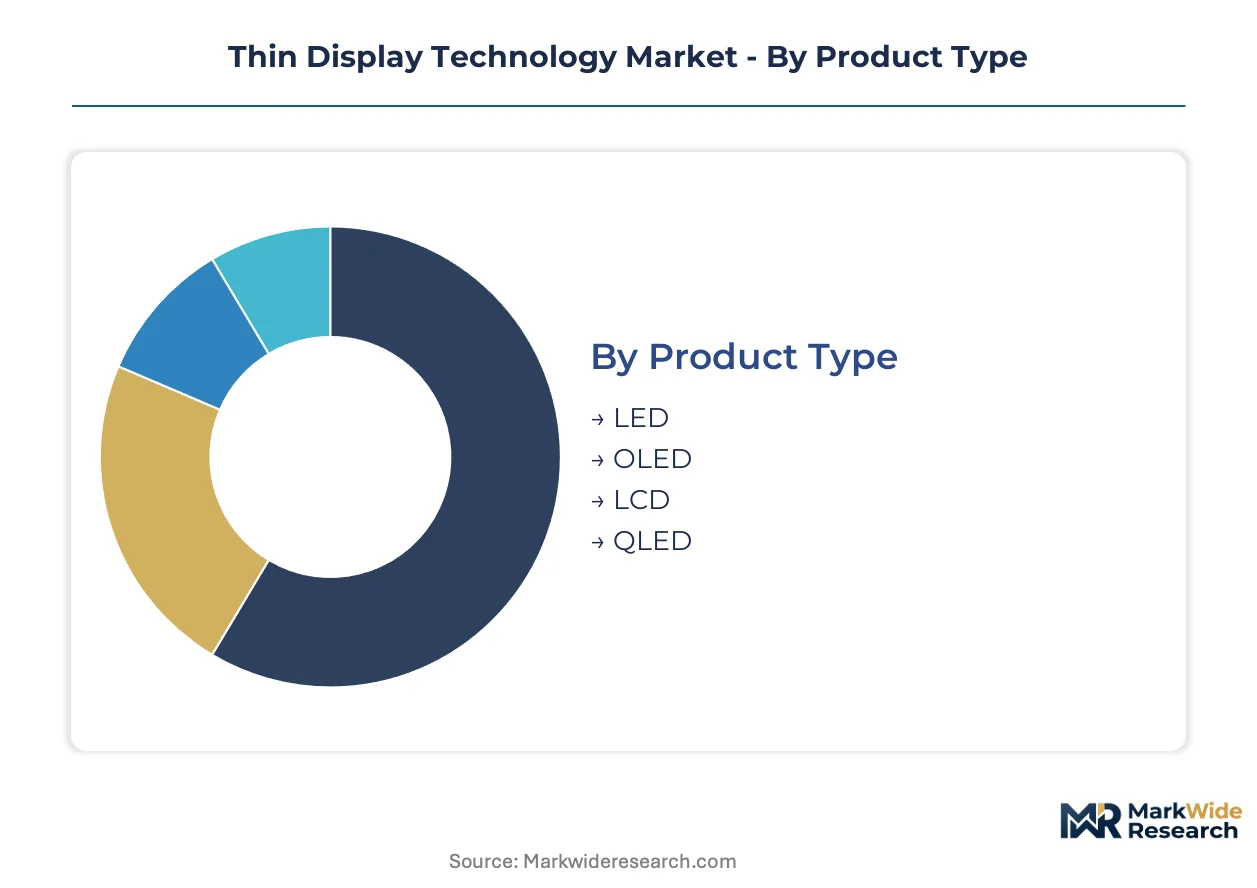
Product Type:
Use-case spectrum spans pocketable mobile devices through wall-mounted commercial signage, with emissive versus transmissive architectures dictating thickness, contrast ratio, and manufacturing cost structure.
- OLED:Self-emissive organic compound layers eliminate backlight assemblies, enabling sub-2mm modules with infinite contrast. Automotive instrument clusters and foldable smartphones in Korea and China absorb Gen 6 flexible capacity as tier-1 suppliers qualify curved panels for 2026 vehicle programs.
- LCD:Transmissive liquid-crystal cells with LED edge or direct backlighting retain cost leadership in monitors and entry televisions. China's MIIT GB energy standards are disqualifying conventional phosphor-backlight architectures from government procurement, forcing mini-LED local dimming retrofits.
- LED:Direct-view LED cabinets aggregate discrete diode packages for outdoor and large-venue applications where luminance and durability outweigh pixel density requirements.
- QLED:Quantum-dot enhancement films or electroluminescent layers boost color gamut and efficiency in premium television tiers, with indium phosphide formulations gaining traction as EU RoHS cadmium exemptions expire.
The dominant share belongs to LCD, while OLED is closing the gap fastest.
Application:
Volume distribution tracks device replacement cycles and ASP erosion curves, with automotive and wearable categories commanding premium pricing against commoditized television panels.
- Smartphones:OLED penetration exceeds two-thirds of flagship shipments, with Samsung Display and BOE capturing flexible substrate orders from Apple and Chinese OEMs. Panel thickness and under-display camera compatibility drive specification tiers.
- Televisions:65-inch and larger formats concentrate in Gen 10.5 fabs at Hefei and Wuhan, where motherglass economics collapse cost-per-square-meter. Mini-LED backlighting defends LCD share against OLED price convergence.
- Monitors:Gaming and professional color-critical segments sustain LCD dominance, though OLED is penetrating ultrawide and high-refresh categories.
- Wearables:Micro-OLED microdisplays and hybrid OLED on glass substrates enable always-on smartwatch faces and AR headset waveguide projection.
Television maintains volume leadership, though automotive applications are expanding most quickly.
Technology:
Backplane electron mobility and pixel drive architecture determine resolution scalability, refresh rate capability, and power efficiency across mobile and fixed installations.
- Active Matrix:Thin-film transistor arrays with LTPS or oxide semiconductors enable high-resolution addressing for OLED and advanced LCD. Korea's K-Display roadmap accelerates low-temperature polycrystalline silicon refinement for energy-efficient manufacturing.
- MicroLED:Chiplet-based emissive arrays promise luminance and lifetime advantages, though mass transfer defect rates above 0.001% constrain cost-competitive television production to premium commercial signage.
- Quantum Dot:Photoluminescent or electroluminescent nanocrystal layers enhance color conversion efficiency, with perovskite alternatives emerging as cadmium restrictions tighten.
- Passive Matrix:Simplified row-column addressing suffices for low-resolution, cost-constrained applications including simple wearables and industrial indicators.
Active Matrix commands the installed base, while MicroLED claims the steepest expansion trajectory despite yield constraints.
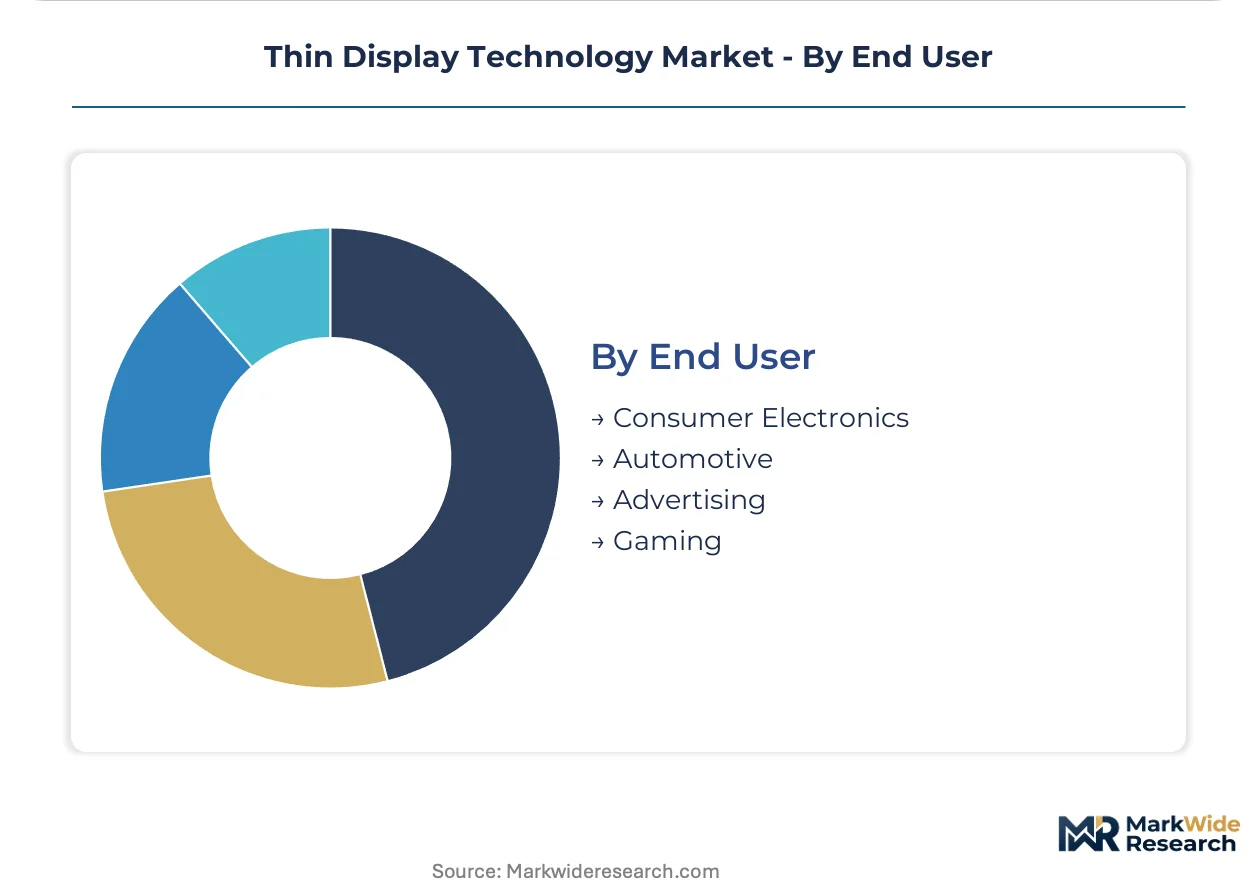
End User:
Customer procurement patterns separate high-volume consumer electronics from long-qualification automotive and specialized commercial applications.
- Consumer Electronics:Smartphone, tablet, and television OEMs drive annual panel demand measured in hundreds of millions of units, with direct fab relationships displacing traditional module integrators.
- Automotive:Curved instrument clusters and passenger entertainment screens pull flexible OLED capacity from consumer electronics, with Hyundai Motor and BYD negotiating annual volume commitments directly with BOE and Samsung Display.
- Advertising:Digital out-of-home networks prioritize luminance, thermal management, and service interval minimization over pixel density.
- Gaming:High-refresh monitors and immersive display walls demand low latency and wide color gamut, sustaining premium pricing for OLED and mini-LED LCD configurations.
Consumer Electronics retains the dominant share, while Automotive is gaining share fastest through cockpit digitization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Panel fabrication capacity clusters in East Asian metropolitan corridors where glass substrate supply chains and precision equipment vendors co-locate. Government industrial policies in Korea and China actively reshape investment flows through subsidy allocation and energy-efficiency mandates.
China
Gen 10.5 fabs in Hefei and Wuhan collapse cost-per-square-meter for 65-inch television panels through motherglass scale economics. MIIT GB standards for display energy consumption disqualify older LCD phosphor-backlight architectures from government procurement channels. Yangtze River Delta clusters concentrate polarizer and driver IC suppliers within 200 kilometers of panel assembly lines.
South Korea
Flexible OLED capacity serves automotive instrument cluster programs qualifying for 2026 vehicle launches. The K-Display roadmap accelerates blue PHOLED commercialization and low-temperature polycrystalline silicon process refinement. Seoul Capital Area fabs retain vapor deposition engineering specialists concentrated in Korean and Japanese equipment vendor ecosystems.
Japan
Precision vapor deposition equipment and high-purity glass substrate supply flow from fewer than three qualified sources, creating single-point vulnerability for OLED expansion. METI industrial policy supports next-generation display material development through consortium-based R&D funding. Chubu region equipment manufacturers supply Canon Tokki deposition systems to fabs across Asia.
Vietnam
Panel assembly and module integration migrate to Bac Ninh and Hai Phong to exploit tariff differentials and proximity to Chinese polarizer supply. Samsung Display and BOE module operations anchor foreign direct investment in northern industrial zones. Hai Phong port infrastructure supports just-in-time delivery to consumer electronics OEMs.
United States
FCC electromagnetic emissions standards shape backlight driver circuit design and wireless-integrated display modules for domestic OEM qualification. Automotive OEMs negotiate direct procurement relationships with Asian fabs, displacing traditional tier-1 display module integrators. California-based technology clusters drive specification requirements for augmented-reality microdisplay applications.
Thin Display Technology Market Competitive Landscape
Captive fab operators and independent panel specialists split the market between vertical integration advantages and customer diversification strategies. The vendor base organizes around three archetypes: Korean conglomerates with semiconductor-memory-display integration, Chinese state-supported scale players, and Taiwanese-Japanese specialists in niche applications. Dominant competitive moves include direct OEM relationship cultivation and substrate-size generation transitions.
Within the Korean conglomerate tier, Samsung Electronics Co., Ltd. and LG Display Co., Ltd. exemplify captive capacity deployment across consumer and automotive segments. BOE Technology Group Co., Ltd. represents the state-supported scale archetype through Gen 10.5 fab investments. These three entities anchor the competitive structure by occupying positions that span emissive and transmissive technology generations.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| LG Display Co., Ltd. |
| BOE Technology Group Co., Ltd. |
| AUO Corporation |
| Innolux Corporation |
| Sharp Corporation |
| Japan Display Inc. |
| Visionox |
| Royole Corporation |
| Others |
Value Network & Pricing Analysis
Canon Tokki vapor deposition equipment single-source dependency determines both the premium spread for flexible OLED substrates and the geographic clustering of Gen 6 fab investments in Korea and Vietnam. This equipment chokepoint compresses margin capture for Chinese entrants while reinforcing Korean incumbents' pricing power in automotive qualification programs.
Pricing Analysis
EU RoHS cadmium exemption expiry dictates the pricing tier structure across quantum-dot television architectures, separating indium phosphide premium formulations from legacy phosphor-backlight economy tiers. Price differentiation rests on energy-efficiency certification grade under China's MIIT GB standards and volume scale commitments from direct automotive OEM procurement. Cost compression in large-format LCD is intensifying because Gen 10.5 motherglass economics collapse cost-per-square-meter in Hefei and Wuhan. Government procurement channels show highest price sensitivity, while automotive tier-1 suppliers absorb premium pricing for curved instrument cluster qualification.
Supply Chain Analysis
Export controls on high-purity rare-earth separation technology limit phosphor precursor flows from Chinese facilities to Korean and Japanese quantum-dot enhancement layer manufacturers. Geographic supply concentration centers on China for indium tin oxide and polarizer films, South Korea for LTPS backplane wafers, and Japan for Canon Tokki deposition systems and Nippon Electric Glass substrates. Raw material dependencies draw from indium mining output, high-purity organic emitter compounds, and driver IC silicon. Single-source vulnerability for vapor deposition equipment creates systemic expansion risk. Distribution runs through direct fab-OEM relationships displacing traditional module integrators in automotive and premium smartphone tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive OEM consolidation into direct procurement relationships with BOE and Samsung Display has shifted buyer power decisively, fragmenting traditional tier-1 supplier influence over price and specification terms.
For Market Incumbents: Pre-empt MicroLED yield breakthroughs by locking automotive OEMs into long-term flexible OLED volume commitments before 2026 model-year qualification cycles complete. Defend against Chinese Gen 10.5 scale pressure through captive phosphorescent emitter material production and K-Display roadmap certification acceleration in blue PHOLED commercialization. For New Entrants and Emerging Players: Establish a beachhead in Vietnam module assembly operations serving tariff-sensitive consumer electronics OEMs with polarizer and driver IC proximity advantages. Target the underpenetrated head-up display waveguide optics segment where micro-OLED microdisplay specification tiers remain unsettled, leveraging direct automotive OEM relationship cultivation as primary go-to-market angle. For Investors and Strategic Acquirers: EU CBAM phase-in reshapes the acquisition landscape toward vertically integrated suppliers with granular Scope 1-3 emissions documentation systems already deployed. Long-term viability across the analysis window favors targets with captive LTPS backplane capacity and Korean or Japanese equipment vendor ecosystem relationships. Signal to monitor: mass transfer defect rate inflection below 0.001% unlocking MicroLED television cost competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Blue PHOLED Commercialization | K-Display roadmap acceleration reduces energy consumption in Korean flexible OLED fabs. |
| Gen 10.5 Fab Scale-Up | Hefei and Wuhan motherglass economics collapse cost-per-square-meter for 65-inch panels. |
| Direct OEM Procurement | Hyundai and BYD annual volume commitments displace Denso and Panasonic Automotive mediation. |
| Vietnam Module Migration | Bac Ninh and Hai Phong operations exploit tariff differentials and Chinese polarizer proximity. |
| Indium Phosphide QD Transition | RoHS cadmium exemption expiry creates first-mover advantage in premium television tiers. |
Research Methodology
Desk research of SEC 10-K filings, customs trade databases, and MIIT GB standard documentation preceded structured interviews with fab operations directors, automotive tier-1 procurement leads, vapor deposition equipment specialists, and OLED material R&D heads. Primary fieldwork across Seoul, Hefei, and Tokyo validated secondary estimates of capacity utilization and yield trajectories. Bottom-up panel shipment aggregation triangulated against top-down display industry revenue analysis.
Assumptions held fixed include current export control regimes on deposition equipment and rare-earth separation technology, while variables included automotive OLED penetration speed and MicroLED mass transfer yield improvement rates. The analytical framework modeled segmentation across emissive architecture, substrate flexibility, and end-use application throughout the forecast period. CAGRs derived from polynomial trend fitting of historical fab investment cycles and OEM procurement pattern shifts. Industry-specific inputs incorporated K-Display roadmap milestone achievement probabilities and EU CBAM carbon-border adjustment implementation scope.
Sensitivities concentrate around vapor deposition equipment delivery delays, indium price volatility from Chinese mining output fluctuations, and automotive qualification cycle acceleration. Forecasts reflect documented assumptions on technology substitution timelines and regulatory enforcement intensity. Material shifts in export control scope or blue PHOLED commercialization timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
TFT LCD Modules (11-Inch to 17-Inch) Market
Display Technologies
Industrial Display Market
Display Technologies
Ultra High Definition (UHD) Panel (4K) Market
Display Technologies
Quantum Dot Display Market
Display Technologies
Global Portable Monitor Market
Display Technologies
TPU Hydrogel Screen Protectors Market
Display Technologies
Europe Transparent Conductive Films Market
Display Technologies
Flexible Display Market
Display Technologies
Global Display Market
Display Technologies
PMOLED Display Market
Display Technologies
Display Mask Market
Display Technologies
Global Photonic Crystal Displays Market
Display Technologies
DLP Projector Market
Display Technologies
Privacy Screens Market
Display Technologies
OLED Panel Market
Display Technologies
Global LED Digital Signage Market