
 Display Semiconductor Components Market | 2026-2036
Display Semiconductor Components Market Size, Share, and Industry Trends Forecast 2026-2036
Display Semiconductor Components Market Analysis
Specialized photolithography and compound semiconductor process engineering talent is rotating from legacy LCD fabs toward OLED and Micro-LED pilot lines, tightening the labor pool for mature-node display driver production. Samsung Electronics leverages captive OLED capacity to dominate smartphone panel semiconductor procurement. TSMC sustains foundry leadership by anchoring advanced node wafer supply for fabless display IC designers. Qualcomm competes through integrated SoC-display bridge architectures that reduce board complexity for premium mobile OEMs.
Display semiconductor components encompass integrated circuits, LED drivers, LCD controllers, and CMOS sensors fabricated on silicon and compound semiconductor wafers, typically employing 28nm to 90nm process nodes with specialized analog-mixed signal design for high refresh rate and low power operation; these devices govern pixel addressing, brightness modulation, and image signal processing across emissive and transmissive panel technologies. Integrated circuits command the largest value share due to die size and complexity, while Micro-LED technology represents the fastest-growing segment as transfer yield improvements reduce cost barriers for commercialization. Consumer electronics absorbs the dominant volume of display semiconductor output, though automotive applications are expanding fastest as digital cockpit integration multiplies panel count per vehicle.
The US FCC regulates electromagnetic emissions from display modules, while the EU RoHS and REACH frameworks restrict hazardous substances in semiconductor packaging and substrate materials, compelling material substitutions that alter foundry chemical supply chains. China's MIIT enforces dual carbon goals that raise energy efficiency mandates for domestic wafer fabs, influencing capacity allocation decisions. Japan's METI coordinates JIS standards for display interface protocols that shape IC pinout and bandwidth specifications. Stakeholders must monitor which regulatory jurisdiction captures standard-setting authority for next-generation Micro-LED metrology and reliability testing.
Market Dynamics
LTPO backplane adoption is compressing OLED driver IC design cycles while China's MIIT dual carbon mandates force fab energy intensity recalibration, tightening wafer allocation for mature-node display semiconductors.
Growth Catalysts
- Automotive Digital Cockpit Expansion:Panel count per vehicle is multiplying as OEMs integrate cluster, infotainment, and passenger displays, multiplying semiconductor content per platform.
- EU RoHS Material Substitution Mandates:Lead-free solder and halogen-free substrate requirements are accelerating packaging technology upgrades that reduce defect rates and extend component lifecycles.
- Micro-LED Transfer Yield Improvements:Mass transfer process refinements are reducing cost barriers for commercialization in premium consumer electronics and commercial signage applications.
Market Restraints
- Specialized Photolithography Talent Scarcity:Compound semiconductor process engineers are rotating from legacy LCD fabs toward OLED and Micro-LED pilot lines, constraining mature-node display driver production capacity.
- Wafer Supply Geographic Concentration:Taiwan, South Korea, and Japan dominate silicon and compound semiconductor substrate supply, creating vulnerability to regional disruption.
- 28nm-90nm Node Capacity Competition:Analog-mixed signal display ICs compete for foundry allocation against automotive and industrial chips on identical process nodes.
Strategic Opportunities
- India Electronics Manufacturing Incentives:PLI scheme subsidies for semiconductor assembly and testing are attracting display module packaging investments from East Asian suppliers.
- SoC-Display Bridge Integration:Convergence of application processors and display timing controllers reduces board complexity and power consumption for premium mobile OEMs.
- Japan METI JIS Standard Coordination:Display interface protocol specifications are shaping IC pinout and bandwidth requirements for next-generation automotive and industrial panels.
Industry Challenges
- Analog-Mixed Signal Design Expertise Gap:High refresh rate and low power operation requirements demand specialized skill sets that outpace university pipeline output.
- Micro-LED Metrology Standardization Delays:Absence of unified reliability testing protocols across US, EU, and Asian regulators is prolonging qualification cycles for commercial deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Display Semiconductor Components Market |
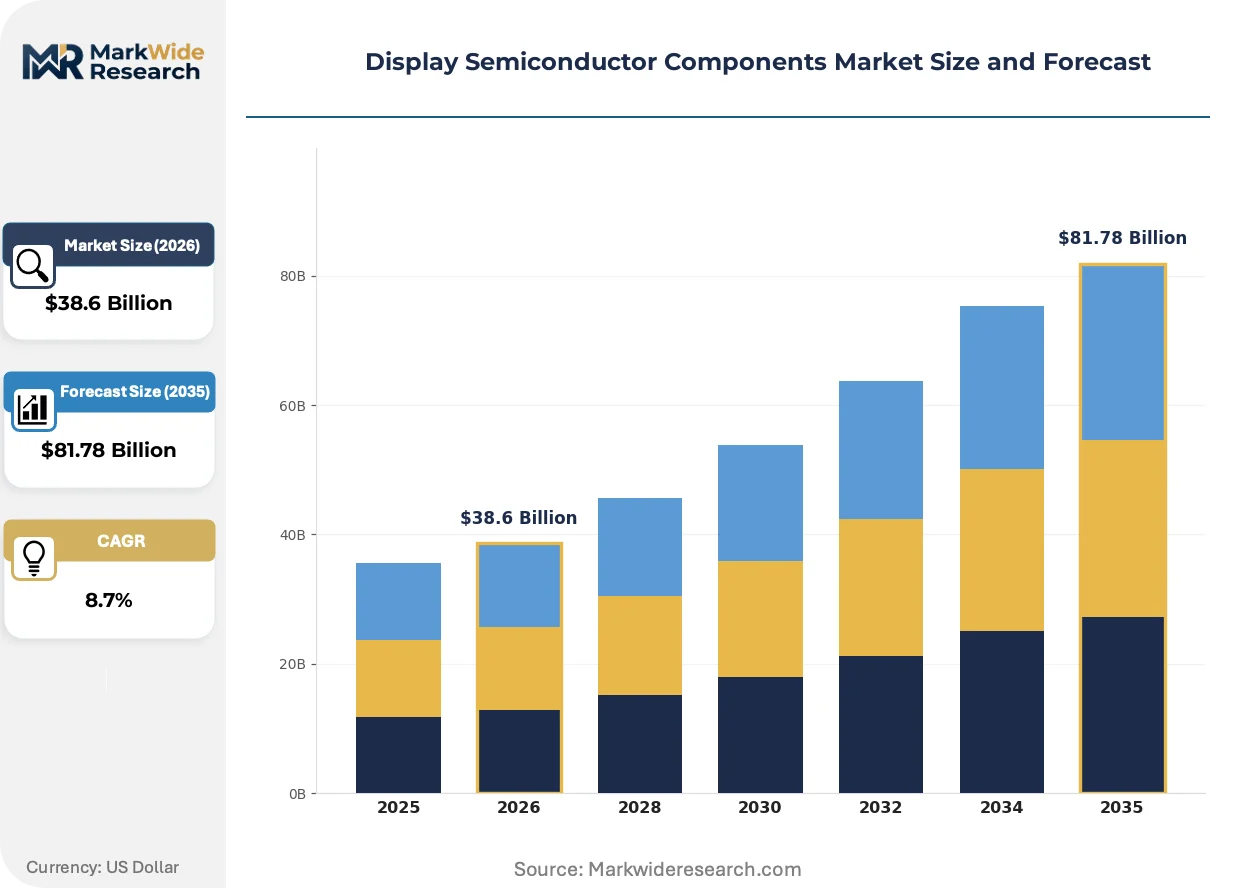
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Integrated Circuits, LED Drivers, LCD Controllers, CMOS Sensors Technology: OLED, Mini-LED, Micro-LED, Quantum Dot Application: Televisions, Monitors, Smartphones, Automobiles End User: Consumer Electronics, Industrial, Automotive, Healthcare |
| Companies Covered | Qualcomm, Micron Technology, Samsung Electronics, AMD, Texas Instruments, TSMC, Broadcom, Analog Devices, Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Display Semiconductor Components Market Emerging Trajectories
Process node specialization and backplane technology transitions are fragmenting competitive capabilities across the display semiconductor value chain, rewarding captive integration and punishing generic merchant suppliers.
LTPO OLED driver architecture is bifurcating the smartphone semiconductor procurement landscape. These circuits manage variable refresh rate operation from 1Hz to 120Hz for power optimization. Premium mobile OEMs are mandating LTPO compatibility for flagship tier sourcing decisions. The technology is bifurcating supplier tiers into those with captive OLED panel partnerships and those dependent on merchant panel supply.
China's MIIT dual carbon enforcement is tightening fab energy intensity standards for domestic wafer manufacturing. Domestic foundries must demonstrate kilowatt-hour per wafer reductions to maintain operating licenses. Display driver IC production on mature nodes faces capacity reallocation pressure toward more energy-efficient advanced node products.
Smartphone OEMs are consolidating display semiconductor procurement around panel-maker captive IC design houses. Direct negotiation with Samsung Electronics and BOE Technology for bundled panel-driver solutions is displacing traditional fabless IC vendor relationships. This concentration is most visible in South Korea and China, where vertical integration between panel fabrication and driver design is deepest.
Display Semiconductor Components Market Segmentation
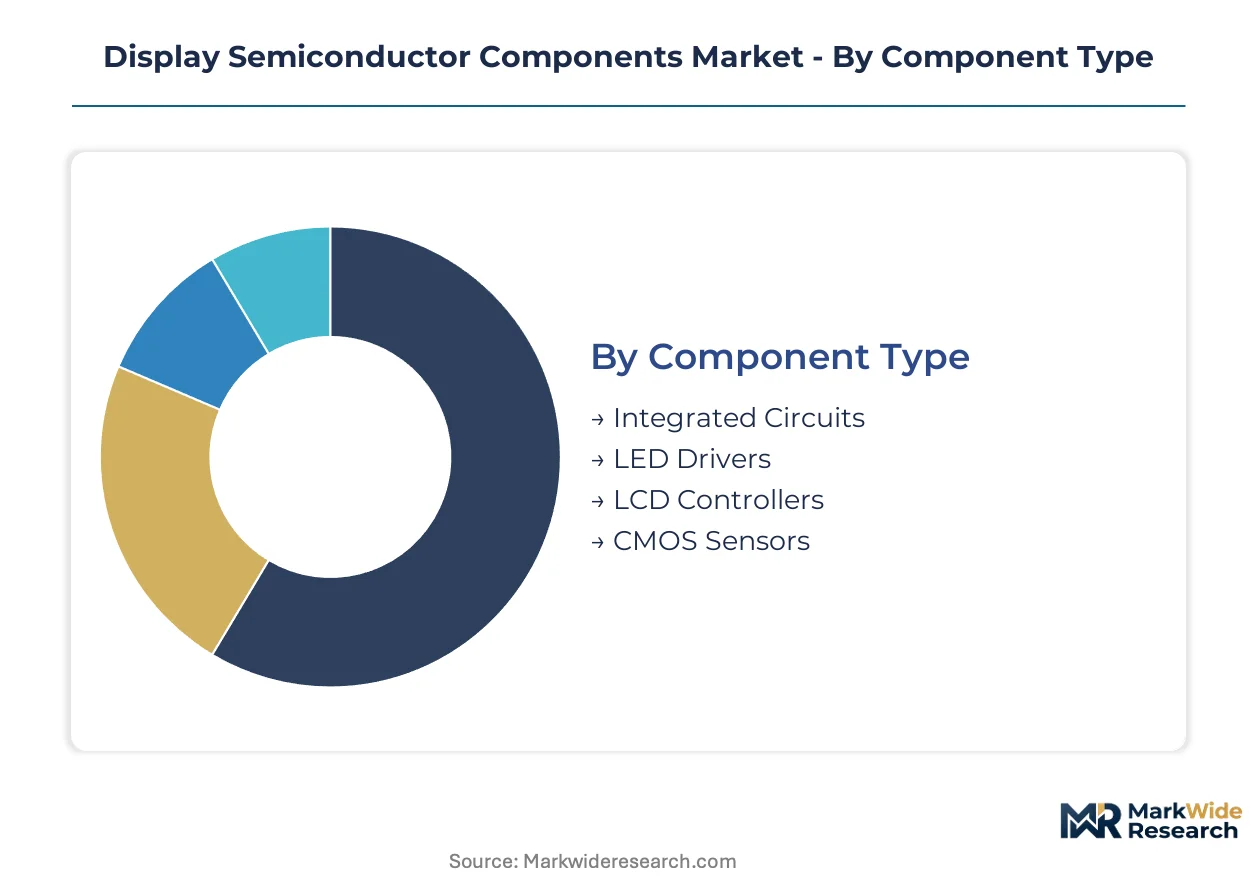
Segmentation in display semiconductors reveals how technology transitions and application requirements reshape procurement patterns. Component complexity, backplane technology, and end-use power constraints fragment supplier capabilities across the value chain.
Component Type:
Integrated circuits face the most acute substitution pressure as panel makers consolidate around captive OLED driver designs and SoC-display bridge architectures displace discrete timing controllers.
- Integrated Circuits:These devices combine pixel addressing, gamma correction, and power management on single dies using 28nm to 90nm analog-mixed signal processes. Smartphone OEM procurement concentrates in South Korea and China where Samsung Electronics and BOE Technology bundle panel-IC solutions, compressing merchant fabless vendor margins.
- LED Drivers:Constant-current regulators govern brightness uniformity across backlight arrays with precision voltage control. Automotive digital cockpit expansion in Germany and Japan multiplies channel count requirements per vehicle platform, stretching foundry capacity for automotive-grade reliability specifications.
- LCD Controllers:Legacy timing controllers for amorphous silicon backplanes face demand erosion as LTPO OLED penetration accelerates in premium mobile segments.
- CMOS Sensors:Image signal processors with integrated display bridge functions serve industrial and medical visualization systems requiring high dynamic range output.
Integrated circuits retain volume leadership; LED drivers hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium emissive technologies from legacy transmissive systems, with capital intensity and yield maturity determining accessible market segments.
- OLED:Organic emissive layers deposited on LTPO backplanes enable variable refresh rate operation from 1Hz to 120Hz. China's MIIT dual carbon mandates are reallocating domestic foundry capacity toward more energy-efficient advanced node production, tightening mature-node driver IC supply for OLED panels.
- Micro-LED:Inorganic III-V compound micro-emitters deliver superior luminance and lifetime for augmented reality and premium signage applications. Mass transfer yield improvements in Taiwan and the United States are reducing commercialization cost barriers fastest in this segment.
- Mini-LED:Chip-scale packaged LEDs serve as direct backlight sources for liquid crystal modulation, bridging cost-performance gaps between conventional LCD and full OLED.
- Quantum Dot:Photoluminescent nanocrystal films enhance color gamut in LCD architectures without requiring new semiconductor process development.
OLED dominates current revenue concentration; Micro-LED is gaining share fastest as transfer yields improve.
Application:
Customer type fragmentation splits procurement between volume-driven consumer electronics and specification-intensive automotive platforms with diverging qualification timelines.
- Smartphones:LTPO backplane adoption compresses OLED driver IC design cycles to 12-month refresh intervals. Panel maker captive IC houses in South Korea and China now capture the majority of premium tier procurement through bundled panel-driver negotiations.
- Automobiles:Digital cockpit integration multiplies panel count per vehicle with cluster, infotainment, and passenger displays each requiring dedicated semiconductor content. NHTSA and KBA safety regulations extend automotive qualification cycles to 24-36 months, favoring incumbent suppliers with proven reliability records.
- Televisions:Large-format OLED and Mini-LED backplanes drive high-channel-count driver IC requirements with emphasis on burn-in compensation algorithms.
- Monitors:Gaming and professional visualization segments prioritize high refresh rate controller specifications with adaptive sync protocol support.
Smartphones maintain the largest unit volume; automobiles show the most rapid content multiplication per platform.
End User:
Supply concentration varies sharply across end-use segments, with automotive and healthcare demanding geographic diversification that consumer electronics procurement often ignores.
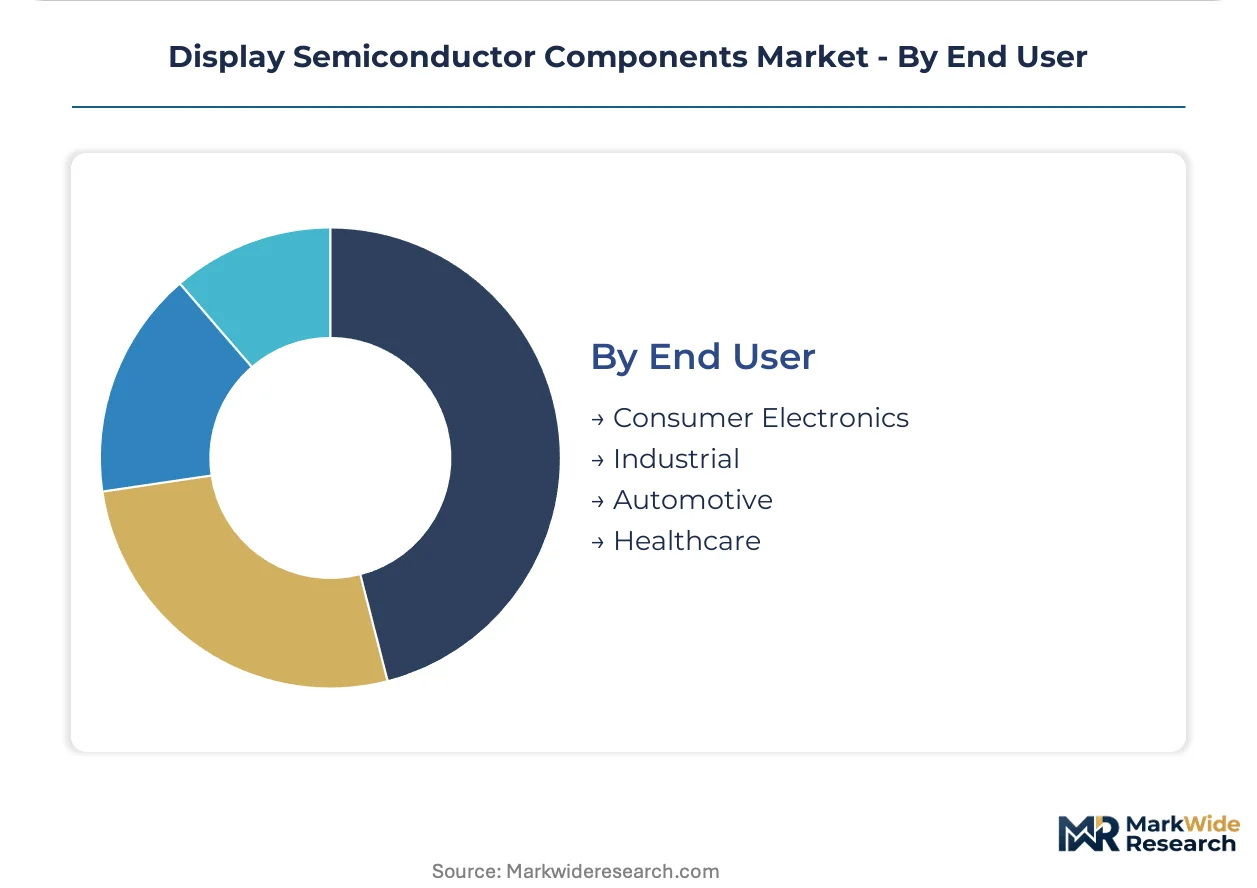
- Consumer Electronics:Smartphone, tablet, and television OEMs concentrate procurement in East Asian supply chains with limited qualification of alternative sources. Taiwan, South Korea, and Japan dominate silicon and compound semiconductor substrate supply for this segment.
- Automotive:Tier-1 display module suppliers must demonstrate dual-sourcing compliance with OEM geographic risk mandates, accelerating qualification of Indian and Southeast Asian assembly capacity under India's PLI scheme subsidies.
- Industrial:Harsh environment specifications drive demand for wide-temperature-range packaging and extended lifecycle guarantees.
- Healthcare:Diagnostic imaging and surgical visualization systems require FDA and PMDA compliance with electromagnetic immunity certifications.
Consumer electronics commands the dominant procurement volume; automotive is diversifying sourcing geography fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes display semiconductors through vertically integrated panel-IC bundles, while the United States and Germany prioritize discrete high-performance components for automotive and industrial systems with longer qualification cycles.
China
Domestic OLED panel production from BOE Technology and TCL CSOT drives captive driver IC procurement through in-house design houses. MIIT dual carbon enforcement tightens fab energy intensity standards, reallocating mature-node capacity toward advanced processes. The Yangtze River Delta cluster around Shanghai and Suzhou concentrates foundry and packaging investments for display semiconductor output.
South Korea
Samsung Electronics and LG Display anchor global OLED panel supply, creating captive demand for affiliated driver IC design capabilities. The country's national industrial regulator coordinates standards alignment with automotive export requirements. The Gyeonggi-Seoul corridor houses the densest concentration of display semiconductor R&D and pilot line investments.
Japan
Automotive digital cockpit demand from Toyota, Honda, and Nissan multiplies panel count per vehicle with stringent reliability specifications. METI coordinates JIS standards for display interface protocols that shape IC pinout and bandwidth requirements. The Kyushu region maintains specialized compound semiconductor foundry capacity for high-temperature automotive applications.
United States
Fabless IC designers concentrate in California and Texas, relying on TSMC and Samsung Foundry for wafer supply of advanced-node display bridge architectures. FCC electromagnetic emissions regulations govern display module certification for consumer electronics. Austin and San Jose host the primary design centers for smartphone and automotive display semiconductor development.
Taiwan
TSMC anchors global foundry supply for 28nm-90nm analog-mixed signal display ICs, competing for capacity against automotive and industrial chip demand. The country's science parks enforce energy efficiency benchmarks that influence process technology migration timelines. Hsinchu Science Park concentrates the world's most advanced display driver IC foundry and packaging ecosystem.
Display Semiconductor Components Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in display semiconductor supply. Samsung Electronics leverages captive OLED panel capacity to dominate smartphone procurement through bundled panel-driver negotiations. TSMC sustains foundry leadership by anchoring advanced node wafer supply for fabless designers. Two strategic archetypes predominate: vertically integrated panel-IC houses and pure-play foundry-dependent fabless vendors. Competitive moves center on strategic partnerships between panel makers and IC designers, plus capacity expansion in India under PLI scheme subsidies.
Within the integrated leader tier, Samsung Electronics exemplifies the captive panel-IC model through its display division's bundling power. TSMC occupies the foundational foundry position for merchant fabless vendors requiring analog-mixed signal process expertise. Qualcomm represents the convergence archetype, anchoring SoC-display bridge architectures that reduce board complexity for premium mobile OEMs.
| Leading Market Players |
|---|
| Qualcomm |
| Micron Technology |
| Samsung Electronics |
| AMD |
| Texas Instruments |
| TSMC |
| Broadcom |
| Analog Devices |
| Intel Corporation |
| Others |
Supply Flow & Price Mechanics
Wafer fab scale economies in Taiwan and South Korea compress unit costs for 28nm-90nm analog-mixed signal processes, concentrating pricing power among foundry leaders while forcing merchant IC vendors toward bundled panel-driver negotiations or niche automotive specifications. China's MIIT dual carbon mandates add energy intensity compliance costs that filter through to wafer quotes, reshaping procurement cost structures for display semiconductor buyers.
Pricing Analysis
Long-term offtake contracts dominate procurement between smartphone OEMs and captive panel-IC houses in South Korea and China, displacing spot market transactions for premium tier sourcing. Price differentiation rests on LTPO backplane compatibility certification and automotive-grade reliability specifications under NHTSA and KBA frameworks. Cost compression in mature-node driver ICs is intensifying because foundry capacity competition from automotive and industrial chips stretches allocation. Volume-scaled consumer electronics buyers exhibit highest price sensitivity, while automotive Tier-1 suppliers prioritize qualification stability over unit cost.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for display semiconductors, with Japan maintaining specialized compound semiconductor substrate production for high-temperature automotive applications. Raw material flows draw from silicon ingot suppliers in the United States and Germany, photoresist chemical producers in Japan, and high-purity gas specialists across the EU. Single-source vulnerability concentrates in advanced photolithography equipment anchored to Dutch and Japanese suppliers. Distribution runs through Hsinchu Science Park packaging ecosystems to module assembly clusters in the Yangtze River Delta and Gyeonggi-Seoul corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Display semiconductor demand sits in early-cycle expansion as automotive digital cockpit integration multiplies panel count per vehicle and Micro-LED transfer yield improvements unlock premium segment commercialization.
For Market Incumbents: Consolidate captive panel partnerships through exclusive LTPO driver IC design cycles, locking out merchant fabless competitors from flagship smartphone procurement. Deepen backward integration into 28nm-90nm analog-mixed signal foundry capacity or secure dedicated allocation agreements with TSMC and Samsung Foundry to defend against automotive chip demand crowding. Prioritize automotive qualification completion under NHTSA and KBA frameworks before Micro-LED metrology standardization settles. For New Entrants and Emerging Players: Lead with India PLI scheme subsidies for semiconductor assembly and testing, capturing display module packaging investments as East Asian suppliers diversify geographic risk. Target automotive digital cockpit segments where dual-sourcing mandates from German and Japanese OEMs create white-space for qualified second sources. Position around SoC-display bridge integration architectures that reduce board complexity for premium mobile OEMs seeking Qualcomm alternatives. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated panel-IC houses with demonstrated LTPO backplane compatibility and automotive qualification pipelines over pure-play fabless vendors exposed to foundry allocation volatility. Long-term viability over the next decade hinges on Micro-LED mass transfer yield inflection and regulatory capture of metrology standard-setting authority. Watch for JIS protocol specifications from Japan's METI as signal for interface bandwidth requirements reshaping IC pinout demand.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Capacity Expansion | Secures 28nm-90nm wafer allocation against automotive chip competition under MIIT energy mandates. |
| Automotive Qualification Completion | Unlocks 24-36 month NHTSA and KBA approval pipelines for digital cockpit semiconductor content. |
| Micro-LED Mass Transfer Partnership | Reduces commercialization cost barriers through Taiwan and United States process engineering collaboration. |
| SoC-Display Bridge Integration | Consolidates application processor and timing controller functions for Qualcomm-competitive mobile architectures. |
| India PLI Assembly Investment | Captures subsidy-backed packaging capacity for automotive dual-sourcing compliance requirements. |
Methodological Framework
Operator-level perspectives from foundry capacity planners, fabless IC design executives, smartphone OEM procurement directors, automotive Tier-1 display module engineers, and panel maker R&D heads anchored the qualitative base for this analysis. Primary interview insights combined with secondary validation from SEC 10-K filings, TSMC and Samsung Foundry capex disclosures, MIIT energy intensity compliance reports, and JIS standard draft specifications. Bottom-up wafer demand modeling and top-down panel shipment triangulation cross-verified segmentation outputs.
Sensitivity analysis across variable refresh rate adoption curves, Micro-LED transfer yield improvement trajectories, and automotive panel count per vehicle assumptions shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include component type complexity tiers, backplane technology generations, end-use power constraints, and regional regulatory cluster alignment. CAGRs derived from unit-volume buildups and value-per-unit erosion curves, with foundry utilization rates and dual carbon compliance cost pass-throughs as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained LTPO backplane penetration, Micro-LED yield inflection timelines, or MIIT enforcement intensity would require recalibration. Forecasts reflect assumptions on foundry capacity allocation priorities and automotive qualification cycle durations. Recalibration cycles align with material shifts in panel maker captive integration depth and regulatory standard-setting authority capture.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
E-Paper Display Market
Display Technologies
OLED Display Market
Display Technologies
Global LED Digital Signage Market
Display Technologies
Digital Holographic Display Market
Display Technologies
Flexible Display Market
Display Technologies
Global Center Stack Display Market
Display Technologies
Foldable Screens Market
Display Technologies
Head Up Display Market
Display Technologies
Europe E-Paper Display Market
Display Technologies
Global Industrial Display System Market
Display Technologies
Quantum Dot Display Market
Display Technologies
Asia-Pacific Industrial Display Market
Display Technologies
Middle East and Africa Industrial Display Market
Display Technologies
8K Display Resolution Market
Display Technologies
Electroluminescent Display Market
Display Technologies
Tablets and Notebook Display Market