
 Canine Arthritis Treatment Market | 2026-2036
Canine Arthritis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Canine Arthritis Treatment Market Intelligence
The EU Green Deal's focus on sustainable supply chains is decoupling the production of nutraceuticals from resource-intensive sourcing methods. Nutramax Laboratories Veterinary Sciences leverages its specialization in scientifically-backed supplements to meet this standard. Zoetis dominates the prescription drug segment with its extensive R&D pipeline in monoclonal antibodies. Elanco Animal Health competes through a broad portfolio spanning both pharmaceuticals and nutritional solutions.
Canine arthritis treatment refers to therapeutic interventions designed to manage joint inflammation and pain, often stemming from degenerative joint disease. These therapies, including NSAIDs, frequently work by inhibiting cyclooxygenase (COX) enzymes to alleviate symptoms and improve the animal's mobility and overall quality of life. Non-Steroidal Anti-Inflammatories represent the largest product segment, while newer Disease-Modifying Osteoarthritis Drugs show significant growth potential. Oral administration remains the dominant route, but injectable therapies are gaining share due to their long-acting profiles.
Market access is governed by stringent efficacy and safety reviews from regulatory bodies like the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA). These agencies' approval processes for new veterinary drugs, including novel biologics, directly influence development timelines and R&D investment. The key decision for manufacturers is whether to invest in incremental improvements to existing drug classes or pivot towards more disruptive, high-cost biologic therapies.
Market Dynamics
The strategic decision between investing in incremental improvements to established NSAIDs or pivoting to high-cost, disruptive biologic therapies defines the market's core tension. This choice shapes R&D pipelines, pricing models, and veterinary practice adoption patterns across the industry.
Growth Catalysts
- Monoclonal Antibody Therapies:The emergence of highly targeted pain management biologics, like nerve growth factor inhibitors, meets strong demand from pet owners in the United States seeking advanced, effective treatments.
- Specialty Veterinary Centers:Growth in orthopedic and rehabilitation specialty clinics provides the infrastructure and expertise necessary for advanced diagnostics and the administration of newer, complex injectable therapies.
- Humanization of Pets:A persistent trend of viewing pets as family members increases owner willingness to finance long-term, quality-of-life-improving treatments for chronic conditions like degenerative joint disease.
Market Restraints
- High Treatment Cost:The significant expense associated with novel biologic therapies, including monoclonal antibodies, limits their accessibility for a large segment of the pet-owning population.
- Regulatory Hurdles:Stringent efficacy and safety data requirements from bodies like the FDA and EMA lead to long and costly development timelines, delaying the introduction of new drugs.
- Incumbent Drug Dominance:The market's reliance on well-established, lower-cost Non-Steroidal Anti-Inflammatories (NSAIDs) creates a high barrier to entry for more expensive, innovative treatment alternatives.
Strategic Opportunities
- Geographic Expansion:There is significant opportunity in developed European markets, such as Germany and the UK, where high pet care standards can support the adoption of advanced arthritis therapies.
- Disease-Modifying Drugs:Development of Disease-Modifying Osteoarthritis Drugs (DMOADs) presents a major opportunity to move beyond symptom management and address the underlying progression of joint degeneration.
- Injectable Formulations:The development of long-acting injectable therapies offers a chance to capture value through improved compliance and convenience, appealing to both veterinarians and pet owners.
Industry Challenges
- Veterinary Training Gap:A shortage of veterinarians trained in advanced orthopedic diagnostics and the specific protocols for administering novel biologic therapies can slow adoption rates at the clinic level.
- Cold-Chain Logistics:The requirement for strict temperature control for many biologic treatments adds significant complexity and cost to the supply chain, creating distribution challenges.
- Owner and Vet Education:Overcoming inertia requires significant investment in educating veterinarians and pet owners on the benefits and proper use of new, high-cost therapies versus familiar NSAIDs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canine Arthritis Treatment Market |
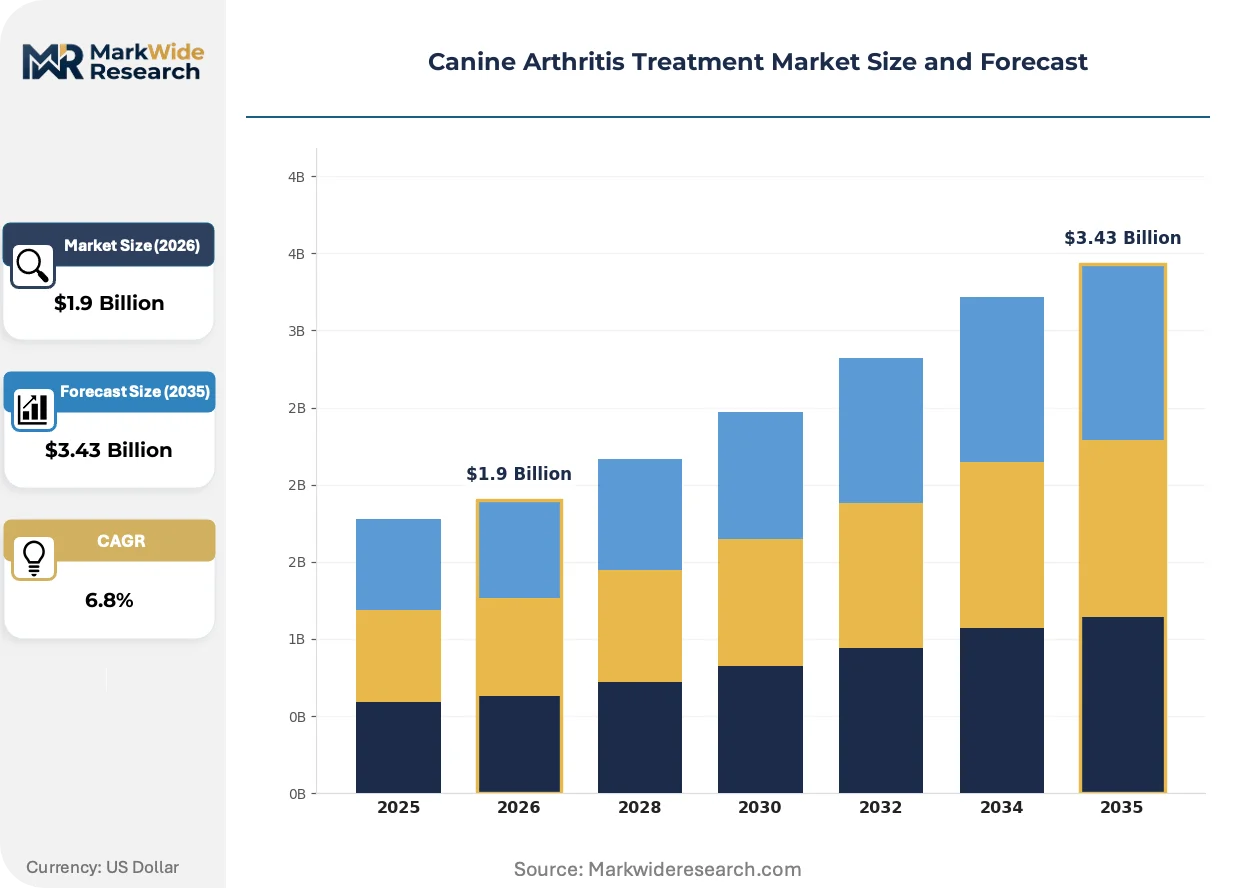
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $3.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Steroidal Anti-Inflammatories, Disease-Modifying Osteoarthritis Drugs, Nutraceuticals, Corticosteroids, Analgesics Therapy Area: Degenerative Joint Disease, Inflammatory Arthritis, Immune-Mediated Arthritis, Traumatic Arthritis, Infectious Arthritis End User: Veterinary Clinics, Animal Hospitals, Specialty Orthopedic Centers, Mobile Veterinary Services, Rehabilitation Facilities Administration Route: Oral, Injectable, Topical, Transdermal, Intra-Articular |
| Companies Covered | Dechra Pharmaceuticals, Vetoquinol, Zoetis, Bayer AG, Ceva Santé Animale, Elanco Animal Health, Virbac, Nutramax Laboratories Veterinary Sciences, Boehringer Ingelheim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canine Arthritis Treatment Market Strategic Shifts & Innovations
A fundamental reevaluation of chronic pain management is underway, shifting the therapeutic focus from generalized, daily symptom suppression toward targeted, long-interval biological interventions. This evolution impacts everything from drug development priorities to the structure of veterinary care delivery.
Monoclonal antibody (mAb) therapies for canines function by specifically neutralizing nerve growth factor (NGF), a primary mediator of osteoarthritis pain signals. Veterinary specialty hospitals and progressive general practices are the primary adopters of these monthly injectable treatments. The targeted mechanism and long-acting profile of mAbs is overtaking the daily oral dosing and systemic exposure associated with traditional NSAIDs for chronic pain management.
The European Medicines Agency (EMA) continues to refine its approval pathways for veterinary biologics, creating a more predictable framework for manufacturers. This regulatory clarity encourages investment in novel therapies by defining data requirements for demonstrating safety, quality, and efficacy for market authorization. The non-prescription nutraceutical segment, governed by less stringent standards under the EU Green Deal's sustainability focus, is also affected as consumers seek scientifically validated options.
Pet owner preferences are moving toward treatment regimens that minimize the burden of daily at-home administration. This behavioral change creates a strong preference for long-acting injectable therapies delivered periodically by a veterinarian over daily oral medications. The trend is most visible in North American markets, where convenience and demonstrated compliance are becoming key factors in treatment selection for chronic conditions.
Canine Arthritis Treatment Market Segmentation
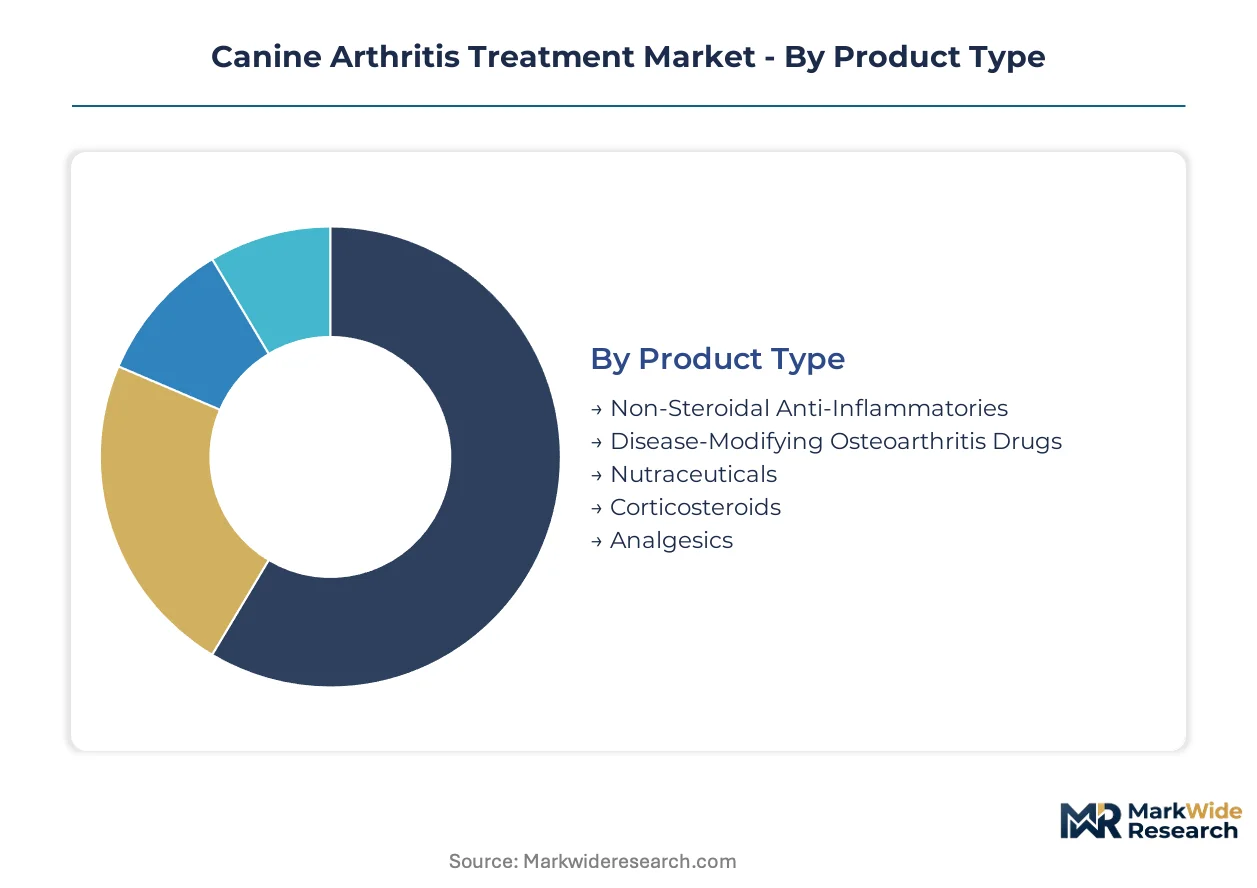
Understanding the varied approaches to canine arthritis treatment requires a detailed segmentation of the market. This analysis categorizes therapeutic options, treatment settings, and delivery methods, reflecting the diverse needs of canine patients and their owners. Market participants align their product development and distribution strategies with these distinct segments.
Product Type:
Pet owners prioritize treatment options based on their perceived efficacy and safety profile for their companion animals.
- Non-Steroidal Anti-Inflammatories:These drugs primarily inhibit cyclooxygenase (COX) enzymes, reducing pain and inflammation associated with joint disease. Demand for these well-established medications remains high in general veterinary practices across Europe, driven by their broad availability and proven symptomatic relief.
- Disease-Modifying Osteoarthritis Drugs:These therapies aim to slow or halt the progression of joint degeneration, moving beyond mere symptom management. Investment in these innovative treatments is concentrating in research-intensive pharmaceutical companies targeting the United States, where willingness to pay for long-term health solutions is strong.
- Nutraceuticals:These supplements provide adjunctive support for joint health, often containing ingredients like glucosamine and chondroitin.
- Corticosteroids:These potent anti-inflammatory agents are used for acute flare-ups or severe cases, though long-term use is limited by side effects.
- Analgesics:This category includes various pain-relieving medications, often used in conjunction with other treatments for comprehensive pain management.
Volume sits with Non-Steroidal Anti-Inflammatories; growth tilts toward Disease-Modifying Osteoarthritis Drugs.
Therapy Area:
The specific underlying cause of arthritis dictates the most appropriate therapeutic intervention and treatment protocol.
- Degenerative Joint Disease:This chronic condition involves the progressive breakdown of joint cartilage, leading to pain and reduced mobility. Treatment for this widespread condition is a primary focus for veterinarians in countries with aging pet populations, such as Germany and the UK.
- Inflammatory Arthritis:Characterized by joint inflammation often due to immune responses or infections, this area requires targeted anti-inflammatory or antimicrobial therapies. Advanced diagnostics for this condition are increasingly available in specialized veterinary centers across North America.
- Immune-Mediated Arthritis:This form involves the immune system attacking joint tissues, necessitating immunosuppressive treatments.
- Traumatic Arthritis:Resulting from injury or trauma to a joint, treatment focuses on pain management and rehabilitation.
- Infectious Arthritis:Caused by bacterial or fungal agents within the joint, requiring specific antimicrobial and supportive care.
Treatment for Degenerative Joint Disease commands the largest share, while solutions for Inflammatory Arthritis are also expanding quickly.
End User:
The infrastructure and expertise available at different veterinary facilities influence the type and complexity of treatments offered.
- Veterinary Clinics:These facilities serve as the primary point of contact for pet owners, offering routine diagnostics and dispensing common medications. These clinics represent the broadest access point for NSAIDs and basic pain management across all developed markets.
- Specialty Orthopedic Centers:Equipped with advanced imaging and surgical capabilities, these centers manage complex cases and administer novel biologic therapies. The adoption of monoclonal antibody treatments is particularly strong in these high-end facilities within the United States.
- Animal Hospitals:These larger facilities provide comprehensive medical and surgical services, including advanced diagnostics and overnight care.
- Mobile Veterinary Services:These services offer convenient at-home care, focusing on basic diagnostics and medication administration for less complex cases.
- Rehabilitation Facilities:These centers specialize in physical therapy and post-operative care, complementing pharmaceutical interventions.
Veterinary Clinics account for the majority of patient visits, with Specialty Orthopedic Centers demonstrating the steepest expansion trajectory for advanced treatments.
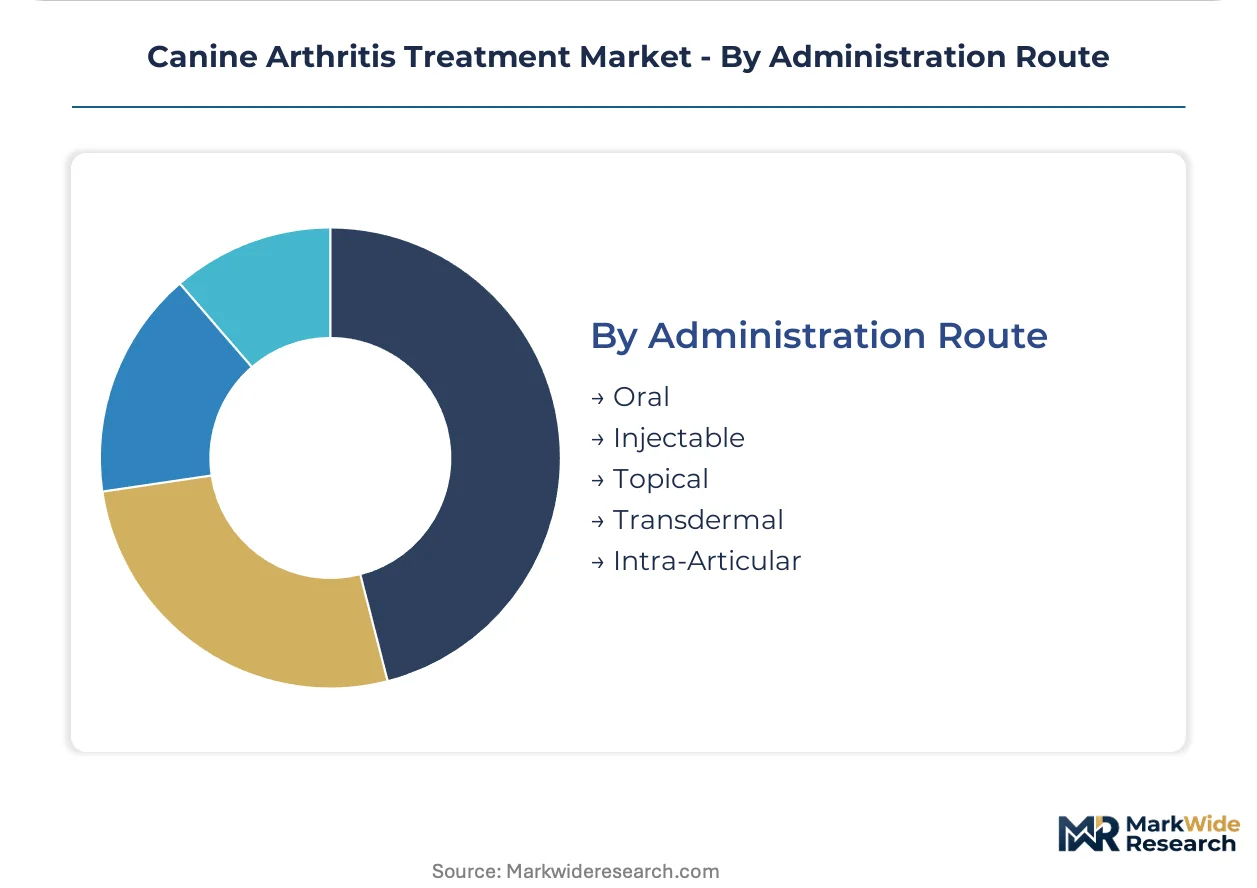
Administration Route:
Convenience for pet owners and compliance for patients are significant factors influencing the selection of drug delivery methods.
- Oral:Medications delivered orally are widely accepted due to ease of home administration, making them suitable for long-term daily management. This route dominates the market for established NSAIDs and nutraceuticals, particularly in regions with high pet ownership like the United Kingdom.
- Injectable:Long-acting injectable therapies offer improved compliance and reduced owner burden, with formulations lasting weeks or months. Demand for these advanced biologics is concentrating in North America, driven by pet owner preference for less frequent dosing.
- Topical:These formulations are applied directly to the skin over affected joints, providing localized pain relief with reduced systemic exposure.
- Transdermal:Medications delivered through the skin via patches offer a continuous release of active ingredients.
- Intra-Articular:Direct injection into the joint provides highly localized and potent therapeutic effects, typically performed by specialists.
Oral administration remains the most common method, while injectable therapies are gaining share due to their long-acting profiles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotech cluster drives innovation in canine arthritis treatments, particularly for novel biologics. This concentration of pharmaceutical research and development supports the emergence of advanced therapies. Demand for these innovative treatments is concentrating in developed markets globally, where pet owners exhibit high willingness to spend on veterinary care.
United States
Pet humanization trends in the United States drive significant demand for advanced canine arthritis treatments, including monoclonal antibody therapies. The US Food and Drug Administration (FDA) rigorously reviews novel biologic therapies, influencing development timelines. Specialty orthopedic centers across states like California are rapidly adopting complex injectable treatments.
Germany
Germany's aging pet population creates consistent demand for effective canine arthritis management, balancing established NSAIDs with newer options. The European Medicines Agency (EMA) refines approval pathways for veterinary biologics, encouraging investment. Veterinary clinics in urban centers like Berlin prioritize broad availability of proven symptomatic relief.
United Kingdom
High pet ownership in the United Kingdom sustains strong demand for accessible canine arthritis treatments, particularly convenient oral medications. European Medicines Agency (EMA) efficacy and safety reviews govern market access for new veterinary drugs. General veterinary practices throughout England prioritize well-established NSAIDs for widespread symptomatic relief.
Japan
Japanese pet owners seek advanced, long-term solutions for chronic conditions, driving interest in innovative injectable therapies. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures stringent safety and efficacy standards for veterinary biologics. Specialized animal hospitals in major cities like Tokyo increasingly offer complex diagnostics and novel treatments.
Canine Arthritis Treatment Market Key Industry Players
Premium-margin players sit above commodity-margin players across product innovation and specialized care within the canine arthritis treatment market. The market exhibits a tiered structure, with a distinct divide between high-cost biologic therapies and widely available, lower-cost NSAIDs and nutraceuticals. Key archetypes include specialized biologic developers, diversified animal health pharmaceutical companies, and scientifically-backed supplement providers. Companies are focusing on R&D investment in novel therapies and strategic geographic expansion.
Within the diversified animal health pharmaceutical segment, Zoetis, a US-based corporation, exemplifies leadership in monoclonal antibody development for canine pain management. Elanco Animal Health, another US-headquartered company, occupies a broad position across both pharmaceutical and nutritional solutions for companion animals. Nutramax Laboratories Veterinary Sciences, Inc., a US entity, anchors the scientifically-backed nutraceutical space, emphasizing specialized joint health supplements. These entities represent distinct strategic approaches, from high-cost biologics to established pharmaceuticals and adjunctive care.
| Leading Market Players |
|---|
| Dechra Pharmaceuticals |
| Vetoquinol |
| Zoetis |
| Bayer AG |
| Ceva Santé Animale |
| Elanco Animal Health |
| Virbac |
| Nutramax Laboratories Veterinary Sciences |
| Boehringer Ingelheim |
| Others |
Cost & Logistics Intelligence
Specialized veterinary expertise in advanced diagnostics and treatment protocols, concentrated in regions like the US biotech clusters, drives significant labor-cost differentials. This directly influences the premium pricing tiers for novel biologic therapies compared to established treatments.
Pricing Analysis
Value-based pricing for canine arthritis treatments anchors on improved animal mobility and quality of life outcomes. The market features a tiered pricing structure, with high-cost biologics and lower-cost symptomatic relief. Price differentiation stems from novel biologic efficacy and stringent regulatory approval. Pricing pressure stems from the market's reliance on well-established, lower-cost Non-Steroidal Anti-Inflammatories (NSAIDs), making general veterinary clinic patients highly price-sensitive compared to owners seeking advanced treatments.
Supply Chain Analysis
Strict regulatory certification, particularly from the US Food and Drug Administration (FDA) and European Medicines Agency (EMA), gates market entry and supply chain participation for novel biologics. Geographic supply concentrates manufacturing of advanced pharmaceuticals in the United States and Europe, while nutraceutical production relies on specialized ingredient sourcing. A key structural risk involves the cold-chain logistics required for many biologic treatments, adding complexity and cost. Distribution runs through a network of veterinary clinics and specialty orthopedic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The canine arthritis treatment market is fundamentally a cost-of-compliance story, where stringent US Food and Drug Administration (FDA) and European Medicines Agency (EMA) efficacy and safety reviews create a significant barrier-to-entry moat for compliant manufacturers.
For Market Incumbents: Lock in existing market share by investing heavily in Disease-Modifying Osteoarthritis Drugs (DMOADs) to counter the long-term threat of degenerative joint disease progression. Deepen relationships with specialty orthopedic centers through co-marketing and advanced veterinary training programs, leveraging established sales channels. This strategy defends against new entrants offering disruptive, high-cost biologic therapies by improving the value proposition of comprehensive care.
For New Entrants and Emerging Players: Targeted monoclonal antibody therapies represent a technology-first wedge into the canine arthritis market. Pursue unmet needs in Disease-Modifying Osteoarthritis Drugs (DMOADs) and develop next-generation long-acting injectable formulations. North American pet owners, prioritizing convenience and advanced care, form the most penetrable segment. A direct-to-veterinarian education and support model for complex administration protocols offers a strong go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized biologic developers given accelerated European Medicines Agency (EMA) approval pathways for novel therapies. The long-term viability, spanning the next 5-10 years, favors entities addressing chronic degenerative joint disease. Acquisition targets include firms with late-stage Disease-Modifying Osteoarthritis Drug (DMOAD) pipelines or established long-acting injectable platforms. Increased enrollment in advanced veterinary orthopedic training programs serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Advancing DMOADs through trials moves beyond symptom management for canine patients. |
| Regulatory Approval Pathway | Navigating FDA and EMA pathways accelerates market access for novel biologic therapies. |
| Manufacturing Scale-Up | Increasing production capacity for monoclonal antibodies meets rising US pet owner demand. |
| Strategic Partnership | Collaborating with specialty orthopedic centers enhances adoption of complex injectable treatments. |
| Pipeline Diversification | Expanding beyond NSAIDs into biologics and DMOADs strengthens long-term market positioning. |
Research Approach
Document review covered US Food and Drug Administration (FDA) filings, European Medicines Agency (EMA) submissions, and veterinary journal articles, complemented by interviews with industry stakeholders. Primary interviews involved veterinary clinicians, R&D executives, regulatory affairs leads, and specialty center managers. This approach ensured a robust understanding of market dynamics through both bottom-up and top-down triangulation.
Volume and value projections were generated using a comprehensive analytical framework across the analysis window. The model incorporated segmentation dimensions including product type, therapy area, end user, administration route, and regional adoption patterns. Compound annual growth rates were derived from historical growth rates, R&D pipeline progression, and regulatory timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under unforeseen regulatory shifts. These forecasts reflect documented assumptions regarding novel biologic development timelines and pet owner willingness to pay. A model refresh is warranted upon material changes in veterinary care policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Animal Health
US Companion Animal Health Market
Animal Health
Animal Healthcare Market
Animal Health
Animal Blood Plasma Products and Derivatives Market
Animal Health
Global Poultry Healthcare Market
Animal Health
Cattle Healthcare Market
Animal Health
Zoonotic Disease Treatment Market
Animal Health
Companion Animal Healthcare Market
Animal Health
US Military Animals Market
Animal Health
Companion Animal Ear Infection Treatment Market
Animal Health
China Companion Animal Health Market
Animal Health
Equine Fluid Therapy Market
Animal Health
Swine Healthcare Market
Animal Health
African Horse Sickness Treatment Market
Animal Health
Equine Healthcare Market
Animal Health
Canine Mammary Tumor Treatment Market
Animal Health
Rat Model Market