
 Global Poultry Healthcare Market | 2026-2036
Global Poultry Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Global Poultry Healthcare Market Foresight
Brazil is reshaping capacity dynamics across poultry healthcare as vertically integrated processors expand breeder and broiler operations. Zoetis leverages its vaccine portfolio to anchor supply relationships with large-scale integrators across Latin America. Merck & Co. sustains competitive intensity through R&D investment in recombinant vector vaccines for avian influenza. Boehringer Ingelheim dominates respiratory disease prophylaxis with its Mycoplasma gallisepticum franchise.
Poultry healthcare encompasses veterinary pharmaceuticals, biologicals, and nutritional interventions formulated to prevent, diagnose, and treat infectious and metabolic disorders in chickens, turkeys, and other domestic fowl raised for meat and egg production. These products typically require cold-chain distribution, specific antigenic matching for vaccines, and withdrawal period compliance to ensure food safety in derived protein products. Vaccines command the largest revenue share within product type segments due to mandatory national immunization programs against Newcastle disease and infectious bronchitis. Feed additives represent the fastest-expanding category as producers substitute antibiotic growth promoters with organic acids, phytogenics, and enzyme formulations under regulatory pressure. Disease prevention applications generate the highest margin pools compared to curative treatment, reflecting the economics of flock-level biosecurity versus individual bird therapy.
The FDA's Veterinary Feed Directive restricts medically important antibiotics in US poultry feed, redirecting investment toward alternative growth promotion modalities. EMA guidelines on antimicrobial resistance shape product registration pathways across European member states, while Brazil's MAPA enforces compartmentalization standards for avian health export certification. Stakeholders must monitor evolving residue tolerance harmonization between Codex Alimentarius and major importing jurisdictions to anticipate formulation reformulation cycles and market access conditions.
Market Dynamics
Antibiotic withdrawal mandates across major protein-importing jurisdictions are forcing flock-level biosecurity investments and alternative growth promoter adoption at commercial scale.
Growth Catalysts
- EMA antimicrobial resistance guidelines:European registration pathways now favor vaccine and phytogenic solutions, redirecting R&D budgets toward biological alternatives.
- Brazilian export certification requirements:MAPA compartmentalization standards for avian health create mandatory demand for veterinary compliance infrastructure in São Paulo and Paraná production zones.
- Recombinant vector platforms:Next-generation avian influenza vaccines reduce antigen-matching cycles and cold-chain dependency versus conventional attenuated formulations.
Market Restraints
- Feed-grade additive cost volatility:Organic acid and phytogenic raw material prices fluctuate with agricultural commodity markets, compressing integrator margins during input spikes.
- Vaccine antigen supply concentration:Specialist embryonated egg production for viral seed stock clusters in select biosecure facilities, creating single-source vulnerability.
- Withdrawal period compliance complexity:Harmonization gaps between Codex Alimentarius residue limits and national importing standards force redundant testing protocols.
Strategic Opportunities
- Southeast Asian backyard flock formalization:Vietnam and Indonesia's commercialization of smallholder operations opens demand for thermotolerant vaccine formulations and diagnostic services.
- Precision nutrition-microbiome convergence:Integration of metagenomic screening with enzyme supplementation enables customized feed additive protocols per genetic line and climate zone.
- US Veterinary Feed Directive enforcement gaps:Veterinary oversight requirements for medically important antibiotics create service revenue pools for diagnostic and prescription platforms.
Industry Challenges
- Veterinary epidemiology skill scarcity:Flock health management at integrated operations requires specialists trained in molecular diagnostics and compartment design, outpacing university program output.
- Multi-jurisdictional registration timelines:Separate dossier requirements for EMA, FDA-CVM, and national regulators delay product launches by 18-36 months.
- Cold-chain infrastructure capex:mRNA and vectored vaccine portfolios require -70°C to -20°C distribution networks that smaller distributors cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Poultry Healthcare Market |
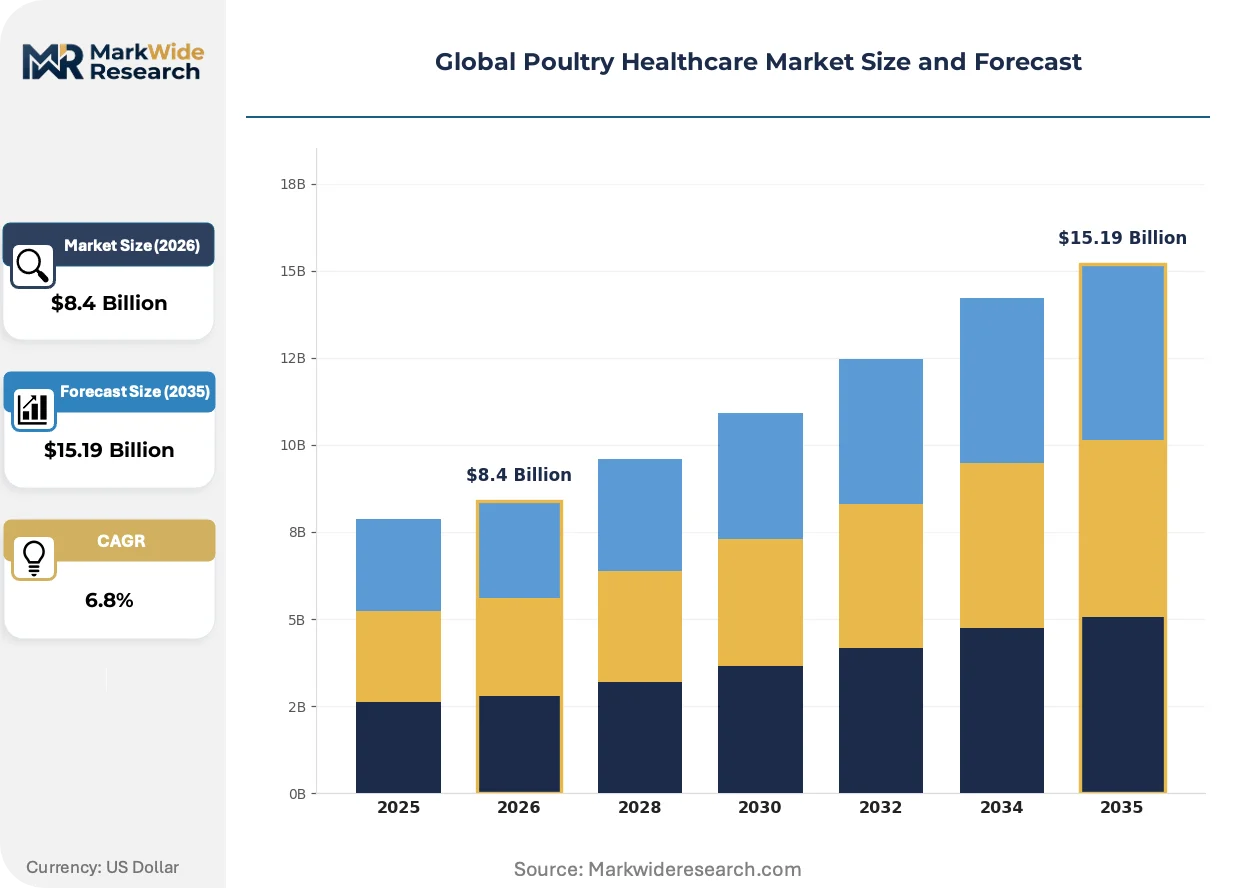
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antibiotics, Feed Additives, Antiparasitics, Vitamins Application: Disease Prevention, Growth Promotion, Disease Treatment, Immunomodulation, Nutritional Support End User: Commercial Farmers, Small-Scale Producers, Breeder Farms, Hatcheries, Contract Growers Distribution Channel: Veterinary Clinics, Feed Retailers, Online Platforms, Wholesalers, Farm Cooperatives |
| Companies Covered | Zoetis, Merck & Co., Boehringer Ingelheim, Ceva Santé Animale, Elanco Animal Health, Phibro Animal Health Corporation, Virbac, Bayer AG, Hester Biosciences Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Poultry Healthcare Market Shifts & Advancements
Real-time flock monitoring systems and predictive health analytics are compressing mortality response windows from days to hours across integrated operations.
Sensor-embedded environmental monitoring is digitizing early pathogen detection in broiler houses. Large-scale integrators in Brazil and the US are deploying IoT-enabled ammonia, temperature, and sound pattern recognition at barn level. This infrastructure is digitizing veterinary intervention timing, shifting from symptomatic treatment to pre-clinical isolation protocols.
REACH antimicrobial restrictions are eliminating zinc oxide and formaldehyde-based disinfectants from European supply chains. Manufacturers are reformulating around peracetic acid and chlorine dioxide alternatives. Feed additive suppliers serving Dutch and German integrators face accelerated re-registration cycles for existing product portfolios.
Buyer consolidation among protein processors is compressing supplier qualification timelines. Tyson Foods and JBS are unbundling after-sales technical service from product procurement, selecting veterinary partners on diagnostic capability rather than historical relationships. This pattern is most visible in the US Southeast, where integrators now demand real-time data sharing from vaccine and pharmaceutical vendors.
Global Poultry Healthcare Market Segmentation
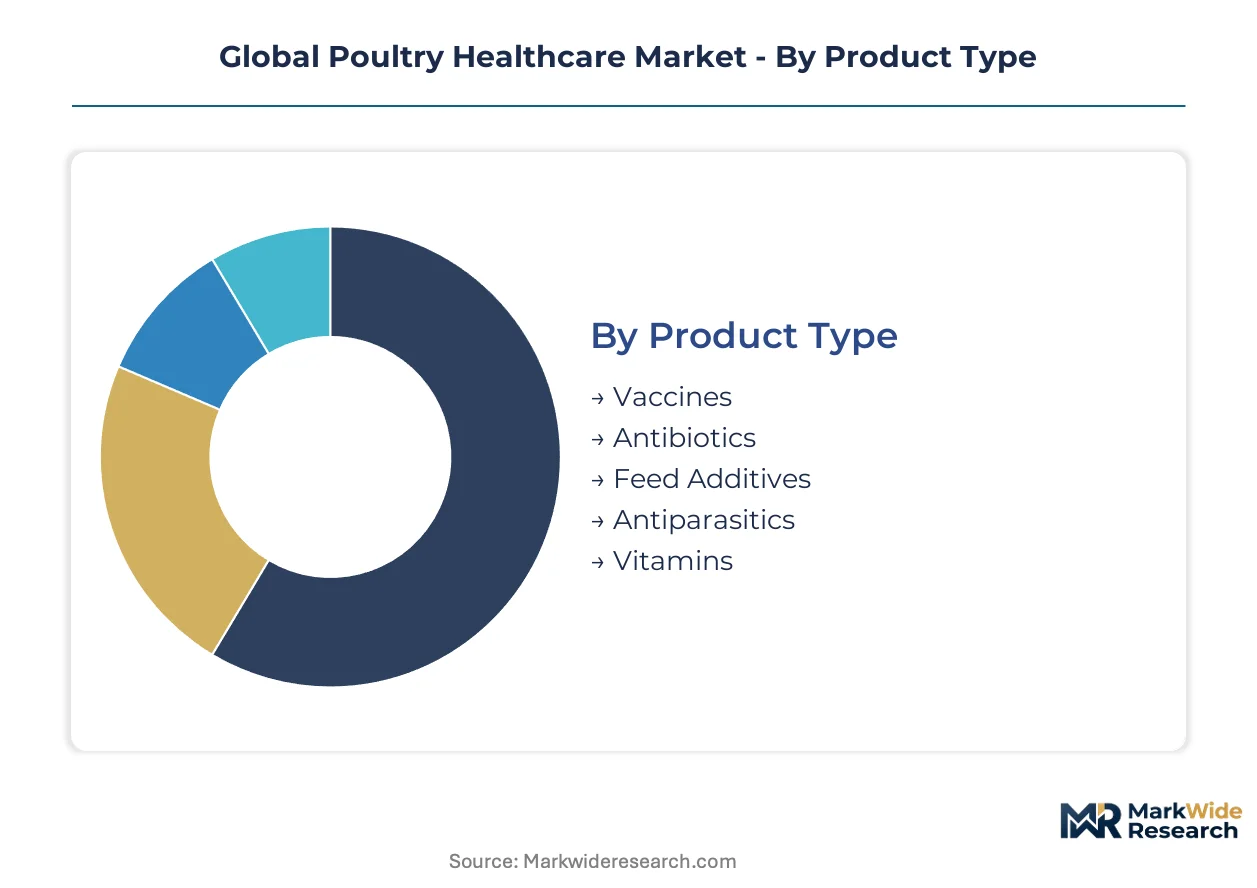
Poultry healthcare procurement splits across four structural dimensions. Product type determines cold-chain infrastructure and regulatory pathway requirements. Application focus shapes margin pools between preventive and curative modalities. End-user scale dictates service intensity and formulation packaging. Distribution channel selection reflects geographic density of veterinary infrastructure.
Product Type:
Cost tier stratification separates biologicals requiring capital-intensive manufacturing from chemical formulations with commodity input exposure.
- Vaccines:Attenuated live, inactivated, and recombinant vector formulations targeting Newcastle disease, infectious bronchitis, and avian influenza. Brazilian MAPA certification requirements and EU antibiotic withdrawal rules concentrate demand in São Paulo and Paraná integrators seeking export market access.
- Feed Additives:Organic acids, phytogenics, enzymes, and probiotic formulations substituting for antibiotic growth promoters. Dutch and German integrators facing REACH antimicrobial restrictions drive reformulation cycles toward peracetic acid-based alternatives.
- Antibiotics:Medically important antimicrobial agents subject to FDA Veterinary Feed Directive oversight and EMA resistance guidelines. Prescription requirements redirect procurement toward veterinary clinic channels.
- Antiparasitics:Coccidiostats and endectocides for protozoan and helminth control in intensive housing systems.
- Vitamins:Fat-soluble and water-soluble micronutrient premixes preventing metabolic disorders in high-performance genetic lines.
Vaccines hold installed capacity. Feed additives are rotating up the share rankings.
Application:
Margin concentration follows the economics of flock-level intervention versus individual bird therapy.
- Disease Prevention:Biosecurity protocols, vaccination programs, and prophylactic nutrition targeting pathogen exclusion before clinical onset. US Southeast integrators now demand real-time data sharing from vendors as Tyson Foods and JBS unbundle technical service from procurement.
- Growth Promotion:Feed additive and microbiome modulation strategies replacing antibiotic growth promoters. Vietnamese and Indonesian smallholder commercialization opens demand for thermotolerant formulations suited to tropical climates.
- Disease Treatment:Curative pharmaceutical intervention after clinical diagnosis, constrained by withdrawal period compliance and residue testing costs.
- Immunomodulation:Adjuvant and cytokine therapies enhancing vaccine response in immunosuppressive conditions.
- Nutritional Support:Metabolic correction during stress periods including transport, molting, and environmental extremes.
Disease prevention commands premium positioning. Growth promotion is climbing the fastest as regulatory pressure intensifies.
End User:
Customer scale determines service model viability and product formulation packaging economics.
- Commercial Farmers:Vertically integrated broiler and layer operations with in-house veterinary staff and centralized procurement. Brazil's export-oriented processors in São Paulo state anchor volume demand for compliance infrastructure.
- Contract Growers:Outgrower operations supplying integrators under fixed-price arrangements with limited input autonomy.
- Breeder Farms:Grandparent and parent stock operations requiring elevated biosecurity and specific pathogen-free certification.
- Hatcheries:In ovo vaccination and early chick nutrition service providers.
- Small-Scale Producers:Backyard and semi-commercial flocks in Southeast Asia requiring simplified administration protocols and ambient-stable formulations.
Commercial farmers hold installed capacity. Small-scale producers are gaining share fastest as formalization programs expand.
Distribution Channel:
Supply concentration reflects veterinary infrastructure density and cold-chain reach.
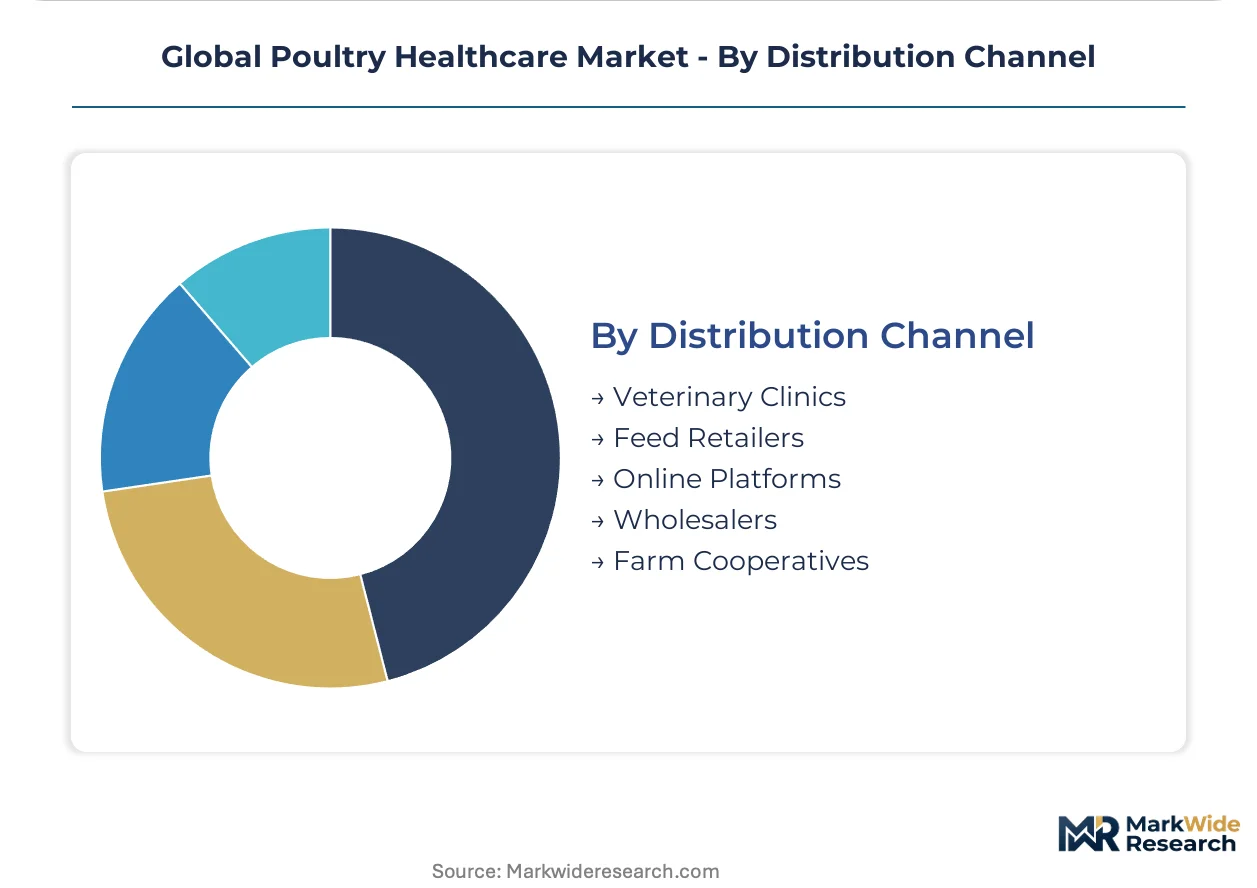
- Veterinary Clinics:Prescription-required pharmaceuticals and diagnostic services under FDA-CVM and EMA oversight. US Veterinary Feed Directive enforcement creates service revenue pools for diagnostic and prescription platforms.
- Feed Retailers:Nutritional and non-prescription additive distribution with technical consultation.
- Wholesalers:Bulk procurement intermediaries serving integrators with direct manufacturer relationships.
- Farm Cooperatives:Pooled purchasing for independent producers in European and Latin American markets.
- Online Platforms:Emerging direct-to-producer channels for generic pharmaceuticals and diagnostic equipment.
Veterinary clinics hold installed capacity. Online platforms are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil deploys poultry healthcare products for export certification compliance, while the United States emphasizes prescription veterinary oversight under FDA-CVM rules. Vietnam and Indonesia prioritize thermotolerant formulations for tropical smallholder conditions. Germany drives reformulation cycles around REACH antimicrobial restrictions.
Brazil
Export-oriented broiler operations in São Paulo and Paraná states anchor regional volume demand. MAPA enforces compartmentalization standards for avian health export certification to European and Middle Eastern markets. Vertically integrated processors across the southeastern production corridor are scaling preventive vaccination programs to maintain premium market access.
United States
Commercial integrators in the Southeast and Midwest concentrate procurement of prescription-required pharmaceuticals and diagnostic services. FDA-CVM Veterinary Feed Directive restrictions on medically important antibiotics redirect investment toward alternative growth promotion modalities. Tyson Foods and JBS operations in Arkansas, Georgia, and Alabama now mandate real-time data sharing from veterinary vendors.
Germany
Dutch and German integrators facing EMA antimicrobial resistance guidelines drive fastest-expanding demand for phytogenic and organic acid feed additives. REACH restrictions eliminate zinc oxide and formaldehyde-based disinfectants from supply chains. Manufacturers serving Lower Saxony and North Rhine-Westphalia production zones face accelerated re-registration cycles for reformulated product portfolios.
Vietnam
Backyard flock formalization programs in the Mekong Delta and Red River Delta generate demand for ambient-stable vaccine formulations. The national agricultural extension service promotes commercialization of smallholder operations through simplified administration protocols. Domestic feed mill clusters around Ho Chi Minh City and Hanoi are integrating probiotic and enzyme supplementation for tropical climate adaptation.
China
Large-scale layer and broiler operations in Shandong and Henan provinces concentrate biological procurement for Newcastle disease and avian influenza prevention. NMPA registration pathways for veterinary vaccines align with national immunization program mandates. Provincial agricultural departments in the Yangtze River Delta enforce biosecurity infrastructure standards for integrated processors supplying domestic retail chains.
Global Poultry Healthcare Market Competitive Landscape
Capability concentration sits with research-intensive biological manufacturers; scale advantage sits with diversified animal health conglomerates. The market structures around three tiers: integrated pharmaceutical-biological portfolios, specialized vaccine producers, and regional feed additive formulators. Competitive intensity manifests through recombinant vector platform licensing and cold-chain distribution partnerships rather than price-based rivalry.
Within the integrated pharmaceutical tier, Zoetis and Merck & Co. exemplify multinational scale positions anchored by vaccine development infrastructure and direct relationships with large-scale integrators. Boehringer Ingelheim occupies a specialized position in respiratory disease prophylaxis. These three companies represent distinct strategic postures: biological portfolio breadth, R&D-intensive platform development, and franchise concentration in specific pathogen categories.
| Leading Market Players |
|---|
| Zoetis |
| Merck & Co. |
| Boehringer Ingelheim |
| Ceva Santé Animale |
| Elanco Animal Health |
| Phibro Animal Health Corporation |
| Virbac |
| Bayer AG |
| Hester Biosciences Limited |
| Others |
Supply & Pricing Matrix
Single-source dependency on embryonated egg production for viral seed stock determines both pricing tier spreads and supply chain shape across poultry healthcare. Tariff exposure on organic acid and phytogenic raw materials compresses integrator margins during agricultural commodity spikes, forcing tiered procurement strategies between premium cold-chain biologicals and ambient-stable alternatives.
Pricing Analysis
Geographic price spreads separate Brazilian export-certified vaccines from Southeast Asian smallholder formulations by a factor reflecting cold-chain infrastructure investment. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales diagnostic bundling. Cost compression in feed additives is intensifying because REACH antimicrobial restrictions accelerate reformulation cycles. Contract growers exhibit highest price sensitivity; vertically integrated processors with in-house veterinary staff demonstrate lowest.
Supply Chain Analysis
Extended payment terms from Brazilian integrators strain working capital for regional distributors serving São Paulo and Paraná production zones. Manufacturing concentrates in the United States, Brazil, and Germany, with viral seed stock production drawing from biosecure embryonated egg facilities in the US Southeast and Lower Saxony. Supply chain risk centers on single-source vulnerability for specialist antigen production. Distribution runs through veterinary clinics and feed retailers with direct manufacturer relationships to large-scale integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
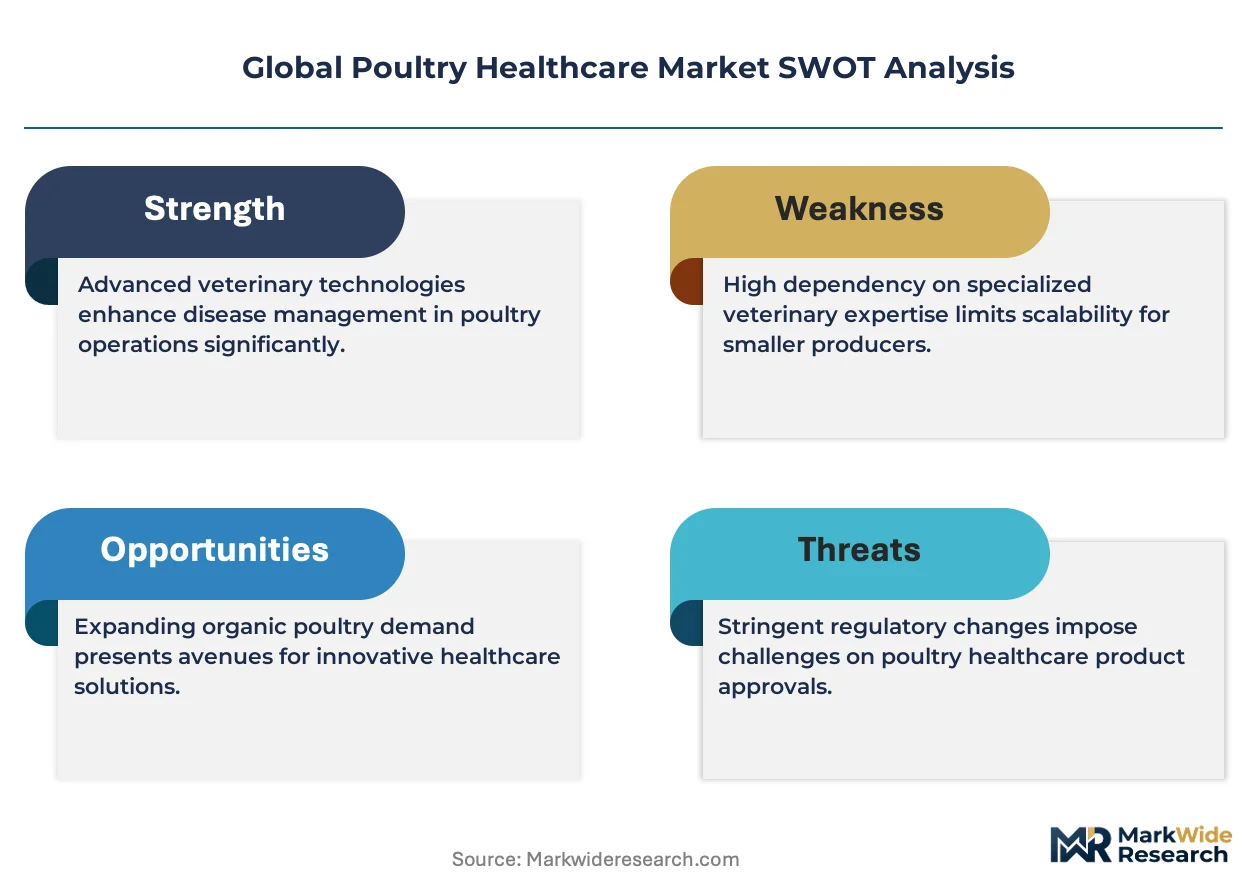
This market demands substitution defense as phytogenic and probiotic feed additives displace antibiotic growth promoters. Incumbents must navigate reformulation investments while maintaining biological portfolio margins against alternative growth promoter commoditization.
For Market Incumbents: Entrench cold-chain distribution partnerships with Brazilian MAPA-certified integrators to lock out regional challengers. Accelerate recombinant vector platform licensing to defend vaccine margins against conventional attenuated formulation price erosion. Prioritize diagnostic capability investments as Tyson Foods and JBS unbundle technical service from procurement. For New Entrants and Emerging Players: Vietnam's Mekong Delta smallholder formalization offers the most penetrable white-space for thermotolerant vaccine formulations. Indonesia's Red River Delta backyard flock commercialization creates parallel entry opportunity. Target farm cooperative channels with simplified administration protocols and ambient-stable packaging to bypass veterinary clinic infrastructure gaps. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors biological platform specialists over commodity additive formulators. Long-term viability hinges on recombinant vector patent estates and cold-chain distribution density across Latin American export corridors. Watch EMA-FDA residue harmonization progress as the inflection signal for reformulation cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Vector Platform Licensing | Merck & Co.'s avian influenza R&D investment reduces antigen-matching cycles versus conventional formulations. |
| Cold-Chain Distribution Partnership | Zoetis anchors supply relationships with São Paulo integrators through vaccine portfolio breadth and biosecurity compliance. |
| Diagnostic Capability Acquisition | Boehringer Ingelheim's Mycoplasma gallisepticum franchise extends into real-time flock monitoring service revenue pools. |
| Feed Additive Reformulation Investment | Dutch and German integrators facing REACH restrictions demand peracetic acid alternatives from regional formulators. |
| Smallholder Channel Development | Vietnam's agricultural extension service promotes thermotolerant formulations through farm cooperative penetration strategies. |
Research Methodology
Desk research of regulatory filing databases, customs trade records, and veterinary pharmaceutical registration precedents preceded structured interviews with poultry veterinary directors, integrator procurement leads, feed mill technical managers, and diagnostic platform specialists. Secondary validation drew from FDA-CVM Veterinary Feed Directive enforcement reports, EMA antimicrobial resistance guidelines, Brazilian MAPA compartmentalization standards, and Codex Alimentarius residue limit harmonization documents. Bottom-up segment sizing triangulated against top-down market consolidation estimates.
Assumptions held antibiotic withdrawal mandate timelines and cold-chain infrastructure capex requirements fixed across the analysis window, while organic acid raw material price volatility and recombinant vector adoption curves varied stochastically. Segmentation modeling incorporated product type, application focus, end-user scale, and distribution channel density dimensions alongside regional regulatory cluster differentiation. CAGRs derived from fitted growth curves applied to base-year estimates validated against historical biological and chemical formulation penetration patterns. Industry-specific inputs included flock-level biosecurity investment rates and export certification compliance cost trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by platform-technology entrants or regional feed additive consolidators would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Animal Health
Canine Arthritis Treatment Market
Animal Health
Canine Mammary Tumor Treatment Market
Animal Health
Equine Healthcare Market
Animal Health
China Companion Animal Health Market
Animal Health
Animal Healthcare Market
Animal Health
Swine Health Market
Animal Health
Canada Animal Health Care Market
Animal Health
Cattle Healthcare Market
Animal Health
Companion Animal Healthcare Market
Animal Health
Laboratory Animal Models Market
Animal Health
Cattle Health Market
Animal Health
Global Companion Animal Health Market
Animal Health
Animal Blood Plasma Products and Derivatives Market
Animal Health
Artificial Intelligence (AI) in Animal Health Market
Animal Health
Canine Influenza Treatment Market
Animal Health
Companion Animal Medicine Market