
 North America Dipeptide Peptidase 4 (Dpp-4) Inhibitors Market | 2026-2036
North America Dipeptide Peptidase 4 (Dpp-4) Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
North America Dipeptide Peptidase 4 (Dpp-4) Inhibitors Market Analytics
Market Context
Fixed-dose combination development with SGLT2 inhibitors and GLP-1 receptor agonists is tilting the Dpp-4 inhibitor technology stack toward multi-mechanism oral platforms. Merck & Co leverages its sitagliptin manufacturing scale to dominate the single-agent segment across U.S. pharmacy benefit formularies. Bristol Myers Squibb sustains competitive positioning through its saxagliptin cardiovascular outcomes data embedded in American College of Cardiology guidelines. Eli Lilly and Company anchors the combination therapy pipeline with integrated Dpp-4 and insulin secretagogue development programs.
Technical and Segment Structure
Dipeptide peptidase 4 inhibitors are oral small molecules that block the Dpp-4 enzyme, extending the half-life of endogenous incretin hormones GLP-1 and GIP to stimulate glucose-dependent insulin secretion and suppress glucagon release in Type 2 diabetes patients. Sitagliptin retains the largest revenue pool among product types due to generic erosion resistance in U.S. Medicare Part D formularies, while linagliptin captures premium positioning through its non-renal elimination profile benefiting elderly patients with chronic kidney disease. The oral administration mode commands structural dominance over subcutaneous and intravenous alternatives, though transdermal delivery research occupies a niche innovation track at select Canadian academic medical centers.
Regulatory Frame and Outlook
FDA cardiovascular outcomes trial mandates and Health Canada ICH E14 QT prolongation guidelines shape Dpp-4 inhibitor development timelines and label claims across North America. The U.S. IRA Medicare price negotiation provisions and provincial formulary management by Canadian Agency for Drugs and Technologies in Health constrain pricing flexibility for established agents. Stakeholders must monitor FDA guidance on combination therapy bioequivalence standards and provincial tiering decisions in Ontario and Quebec to anticipate access headwinds for next-generation formulations.
Market Dynamics
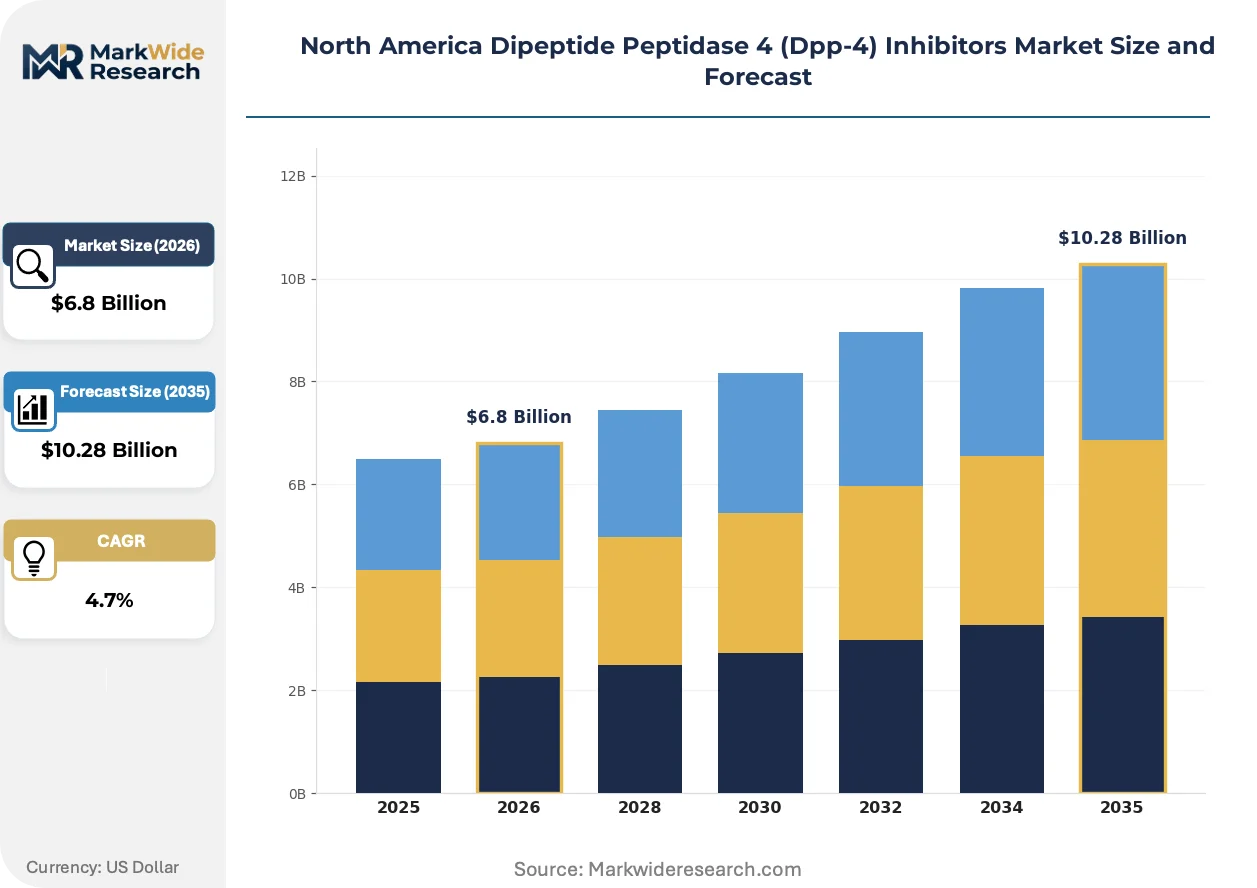
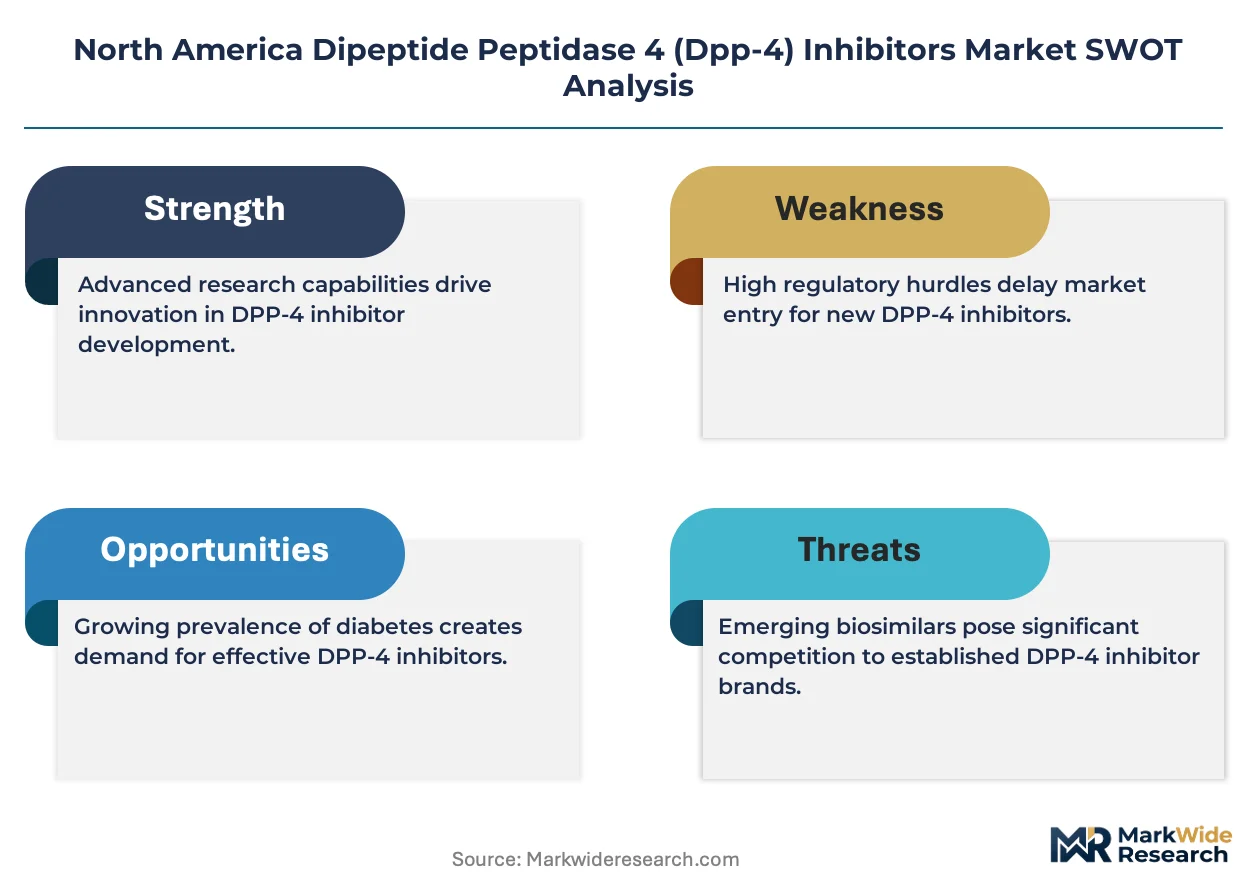
Fixed-dose combination therapies with SGLT2 inhibitors are compressing the standalone Dpp-4 inhibitor segment, forcing manufacturers to reconfigure development pipelines toward multi-mechanism oral platforms that preserve formulary access.
Growth Catalysts
- Cardiovascular outcomes data integration:FDA-mandated heart safety trials now embed Dpp-4 inhibitors within American College of Cardiology guidelines, expanding prescribing among cardiologist-endocrinologist co-managed patients.
- Chronic kidney disease alignment:Non-renal elimination profiles match Health Canada and FDA labeling for elderly diabetic populations with declining renal function, opening nephrology clinic channels.
- Medicare Part D formulary stability:Protected class status for diabetes therapies limits annual therapeutic substitution, preserving physician prescribing continuity across U.S. hospital systems.
Market Restraints
- GLP-1 receptor agonist substitution:Subcutaneous semaglutide and tirzepatide formulations capture oral-adjacent patient segments previously managed with Dpp-4 inhibitors alone.
- IRA price negotiation mechanics:U.S. Medicare selected drug provisions expose established Dpp-4 agents to federal price-setting, compressing margin structures for single-agent portfolios.
- Generic sitagliptin erosion:Patent expiry diffusion across U.S. pharmacy benefit managers triggers rapid price collapse for the largest volume segment.
Strategic Opportunities
- Transdermal delivery research:Canadian academic medical centers in Ontario and Quebec pioneer non-oral administration modes that bypass first-pass metabolism and gastrointestinal intolerance.
- Triple-combination oral platforms:Integration of Dpp-4 inhibition with SGLT2 blockade and metformin into single-tablet regimens addresses polypharmacy burden in U.S. federally qualified health centers.
- Provincial formulary tiering optimization:CADTH Common Drug Review process in Canada creates pathways for differentiated agents to secure preferred status through health technology assessment submissions.
Industry Challenges
- Cardiovascular outcomes trial recruitment:Patient enrollment for non-inferiority heart safety studies faces competition from GLP-1 trials with superior efficacy endpoints, extending development timelines.
- Biopharmaceutical manufacturing scale-up:Multi-mechanism combination tablets require synchronized active pharmaceutical ingredient sourcing across three distinct supply chains, complicating batch release protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Dipeptide Peptidase 4 (Dpp-4) Inhibitors Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sitagliptin, Saxagliptin, Linagliptin, Alogliptin Administration Mode: Oral, Subcutaneous, Intravenous, Transdermal Therapeutic Area: Diabetes Type 2, Obesity, Cardiovascular Diseases, Metabolic Syndrome End User: Hospitals, Clinics, Homecare, Pharmacies |
| Companies Covered | Merck & Co, AstraZeneca, Bristol Myers Squibb, Novartis, Takeda Pharmaceuticals, Eli Lilly and Company, Boehringer Ingelheim, Sanofi, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Dipeptide Peptidase 4 (Dpp-4) Inhibitors Market Evolving Landscape
Oral small-molecule engineering is converging with biologic delivery science, producing hybrid platforms that preserve patient adherence advantages while matching injectable efficacy benchmarks.
Transdermal patch technology for incretin hormone modulation is hybridizing with conventional oral Dpp-4 inhibition, enabling Montreal-based research hospitals to test glucose-dependent insulin secretion without gastrointestinal exposure. Dermatology and endocrinology departments at McGill University Health Centre pilot these systems for metformin-intolerant populations. The approach is hybridizing market segmentation by creating a procedural-administration category between daily pills and weekly injections.
FDA guidance on fixed-combination bioequivalence standards now requires pharmacokinetic bridging studies for each component proportion, extending New Drug Application review timelines for triple-therapy candidates. Health Canada aligns with ICH M13A guidelines on bioequivalence for highly variable drugs, adding clinical endpoint study requirements for certain Dpp-4 inhibitor formulations. U.S. generic manufacturers respond by prioritizing single-agent 505(b)(2) pathways over complex combination submissions.
Integrated diabetes management protocols in U.S. Northeast and Midwest hospital systems now bundle Dpp-4 inhibitor prescribing with continuous glucose monitor data review, compressing the traditional physician-pharmacist consultation cycle. Endocrinology clinics embed clinical pharmacists within electronic health record workflows to automate dose adjustments based on real-time glucose trends. Kaiser Permanente Northern California and Cleveland Clinic health systems demonstrate this operational model most visibly.
North America Dipeptide Peptidase 4 (Dpp-4) Inhibitors Market Segmentation
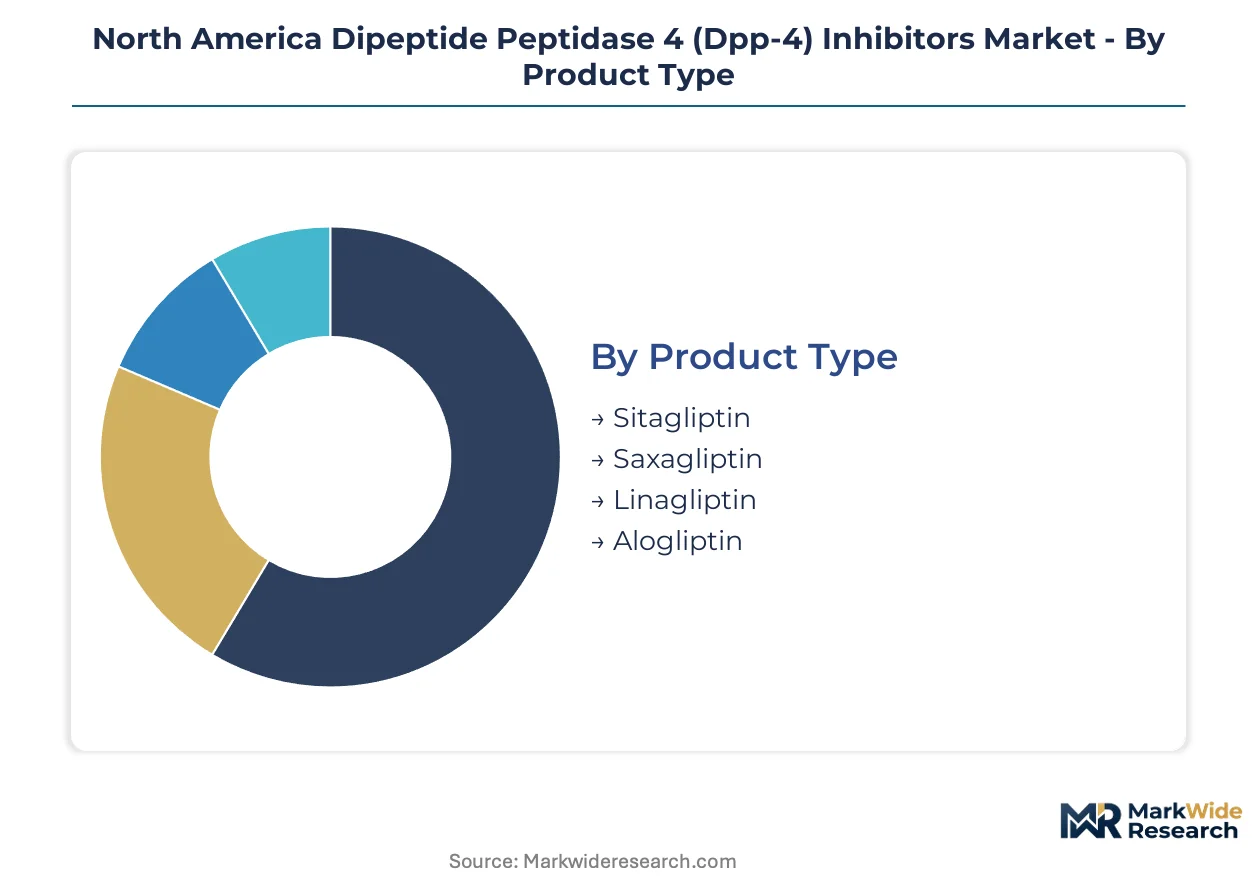
Dpp-4 inhibitor prescribing patterns diverge sharply across patient populations, delivery mechanisms, and care settings. Segmentation reveals where formulary access, renal function profiles, and cardiovascular comorbidity management concentrate commercial opportunity.
Product Type:
Cycle times vary from rapid generic erosion for mature agents to extended patent protection for differentiated molecules.
- Sitagliptin:The first-in-class Dpp-4 inhibitor with once-daily dosing and established renal dose-adjustment protocols. U.S. Medicare Part D formularies retain this agent as the preferred generic option across Midwest hospital systems, though price compression accelerates volume turnover.
- Linagliptin:A xanthine-based Dpp-4 inhibitor eliminated primarily through biliary excretion rather than renal clearance. Demand concentrates in Northeast academic medical centers managing elderly Type 2 diabetes patients with chronic kidney disease stages 3-5, where dose adjustment avoidance drives physician preference.
- Saxagliptin:A cyclopropyl-fused pyrrolidine derivative with documented cardiovascular outcomes data.
- Alogliptin:A pyrimidinedione-based selective Dpp-4 inhibitor with modest market presence.
Sitagliptin anchors the volume base while linagliptin gains share at the steepest rate.
Administration Mode:
Cost tiers separate high-volume oral generics from premium-priced investigational delivery systems.
- Oral:Small-molecule tablets and capsules dominating commercial prescribing. U.S. pharmacy benefit managers structure tiered copay incentives around oral Dpp-4 inhibitors, with preferred status contingent on prior metformin failure documentation.
- Subcutaneous:Investigational depot formulations and combination injectables in early-phase development. Canadian endocrinology research networks in Toronto and Vancouver evaluate weekly subcutaneous Dpp-4 inhibitor delivery for adherence-challenged populations.
- Intravenous:Hospital-only administration for perioperative glucose management.
- Transdermal:Patch-based delivery systems bypassing first-pass hepatic metabolism. McGill University Health Centre and University Health Network Toronto pilot microneedle array technology for metformin-intolerant patients requiring non-gastrointestinal incretin modulation.
Oral administration commands the volume base while transdermal systems climb the fastest toward regulatory evaluation.
Therapeutic Area:
Application intensity maps to disease prevalence and guideline positioning across North American healthcare systems.
- Diabetes Type 2:The primary approved indication encompassing glucose-dependent insulin secretion enhancement and glucagon suppression. FDA labeling and American Diabetes Association Standards of Care position Dpp-4 inhibitors as second-line therapy post-metformin across U.S. integrated delivery networks.
- Obesity:Off-label and investigational use for weight-neutral glucose lowering. Canadian obesity medicine clinics in Calgary and Montreal evaluate Dpp-4 inhibitors within multi-modal weight management protocols where GLP-1 agonist intolerance limits options.
- Cardiovascular Diseases:Secondary prevention applications leveraging heart safety trial data. The SAVOR-TIMI 58 and EXAMINE trials embed saxagliptin and alogliptin within American College of Cardiology diabetes-cardiology co-management pathways.
- Metabolic Syndrome:Emerging polypharmacy targeting insulin resistance clusters.
Diabetes Type 2 anchors the volume base while obesity applications expand most quickly through off-label utilization.
End User:
Customer type determines procurement scale, formulary control, and patient education requirements.
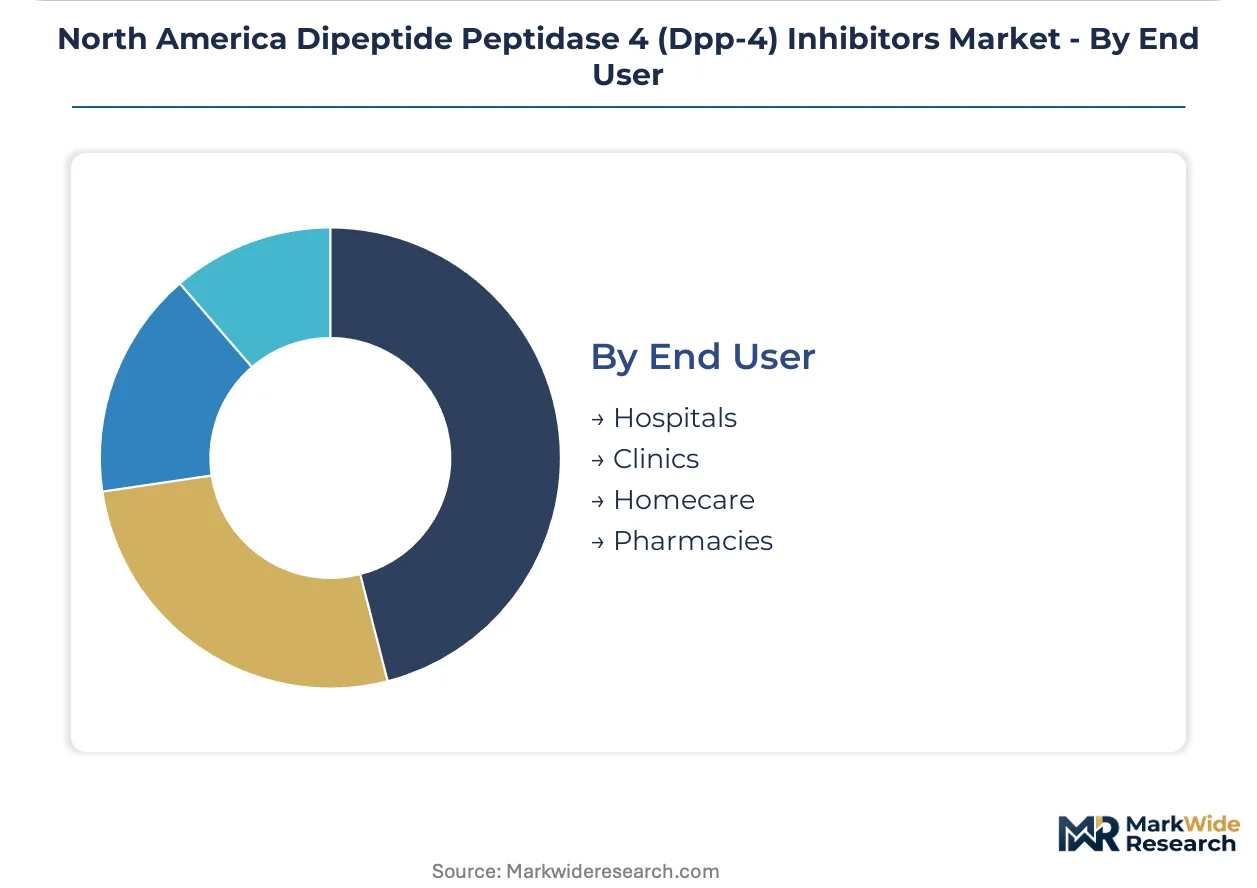
- Hospitals:Inpatient glucose management protocols and discharge prescribing programs. U.S. Northeast health systems including Cleveland Clinic and Mass General Brigham embed Dpp-4 inhibitors within computerized physician order entry sets for admission A1c thresholds above 7.5%.
- Clinics:Outpatient endocrinology and primary care prescribing with continuous glucose monitor integration. Kaiser Permanente Northern California deploys clinical pharmacists within clinic workflows to automate Dpp-4 inhibitor dose adjustments based on real-time ambulatory glucose profile data.
- Homecare:Long-term care facility medication administration for mobility-limited elderly.
- Pharmacies:Retail dispensing with adherence packaging and medication therapy management.
Hospitals anchor the volume base while clinics gain share at the steepest rate through integrated diabetes management protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems and endocrinology clinics concentrate Dpp-4 inhibitor procurement across the United States and Canada, with integrated diabetes management protocols driving formulary decisions in the Northeast and Midwest. Mexico represents an emerging access corridor for regional manufacturers seeking price-competitive positioning.
United States
Cleveland Clinic and Mass General Brigham anchor demand through computerized physician order entry protocols embedding Dpp-4 inhibitors for admission A1c thresholds above 7.5%. FDA cardiovascular outcomes trial mandates reshape prescribing toward agents with documented heart safety profiles. Kaiser Permanente Northern California deploys clinical pharmacists within electronic health record workflows to automate dose adjustments based on continuous glucose monitor data.
Canada
McGill University Health Centre and University Health Network Toronto pilot transdermal microneedle array technology for metformin-intolerant patients requiring non-gastrointestinal incretin modulation. Health Canada ICH E14 QT prolongation guidelines shape development timelines and label claims for new molecular entities. The Canadian Agency for Drugs and Technologies in Health manages provincial formulary tiering through Common Drug Review submissions, creating pathways for differentiated agents in Ontario and Quebec.
Mexico
Federal health institutions including Instituto Mexicano del Seguro Social expand oral diabetes therapy access through centralized procurement mechanisms. COFEPRIS regulatory alignment with FDA bioequivalence standards accelerates abbreviated new drug application reviews for fixed-dose combinations. Mexico City metropolitan hospitals and Guadalajara medical centers concentrate prescribing volume for second-line therapies post-metformin failure.
North America Dipeptide Peptidase 4 (Dpp-4) Inhibitors Market Competitive Landscape
Channel-controlling players compete with product-specialist players across pharmacy benefit manager formularies and hospital procurement systems. The market structure tilts toward consolidated manufacturing scale for single-agent portfolios alongside fragmented combination therapy development. Three archetypes dominate: large-cap pharmaceutical manufacturers with cardiovascular outcomes data, mid-tier firms with renal-elimination differentiated molecules, and generic entrants exploiting patent cliff erosion. Competitive moves center on fixed-dose combination portfolio diversification and Medicare Part D formulary access preservation.
Among established pharmaceutical manufacturers, Merck & Co, Bristol Myers Squibb, and Eli Lilly and Company occupy positions spanning the single-agent and combination therapy vectors. Merck & Co represents the manufacturing-scale archetype with sitagliptin production infrastructure. Bristol Myers Squibb exemplifies the cardiovascular-data-driven positioning through saxagliptin outcomes integration. Eli Lilly and Company anchors the combination pipeline development segment with integrated Dpp-4 and insulin secretagogue programs.
| Leading Market Players |
|---|
| Merck & Co |
| AstraZeneca |
| Bristol Myers Squibb |
| Novartis |
| Takeda Pharmaceuticals |
| Eli Lilly and Company |
| Boehringer Ingelheim |
| Sanofi |
| Pfizer |
| Others |
Value Network & Pricing Analysis
Overcapacity in U.S. generic sitagliptin manufacturing compresses supplier margins while simultaneously driving contract manufacturers toward higher-value combination therapy production. This utilization imbalance concentrates pricing power among branded portfolio holders with cardiovascular outcomes data while forcing pure-play generic suppliers into volume-dependent bidding wars for Medicare Part D formulary slots.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient indexation dominate procurement agreements between U.S. pharmacy benefit managers and Dpp-4 inhibitor manufacturers. Three-tier pricing structure across originator brands, authorized generics, and commodity generics separates reimbursement tiers by cardiovascular trial documentation and renal clearance profile. Cost compression in the generic sitagliptin segment is intensifying because patent cliff diffusion triggers rapid price collapse across Midwest hospital system formularies. Federally qualified health centers exhibit highest price sensitivity due to 340B drug pricing program constraints, while integrated delivery networks in the Northeast leverage scale for preferred brand access.
Supply Chain Analysis
Upstream feedstock concentration for Dpp-4 inhibitor active pharmaceutical ingredients centers on Indian and Chinese chemical synthesis facilities with U.S. and European finishing capabilities. Key inputs include fluorinated intermediates for sitagliptin, xanthine derivatives for linagliptin, and cyclopropyl-fused pyrrolidine cores for saxagliptin. Single-source vulnerability in biliary excretion-grade excipient supply creates formulation bottlenecks for non-renal elimination products. Distribution runs through wholesale distributors McKesson and Cardinal Health to U.S. retail pharmacies, with direct-to-hospital contracting gaining share in Canadian provincial procurement systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dpp-4 inhibitor commercialization increasingly hinges on service-attach revenue streams, with clinical pharmacist integration into electronic health record workflows expanding faster than standalone drug margins. Medication therapy management programs and continuous glucose monitor data interpretation services now generate recurring revenue layers that outpace hardware-like pill dispensing economics.
For Market Incumbents: Harden formulary access through cardiovascular outcomes trial data embedding within American College of Cardiology guideline updates. Consolidate manufacturing scale across sitagliptin and combination tablet production to capture authorized generic revenue streams before price collapse accelerates. Vertical integration into continuous glucose monitor data platforms creates defensive moats against GLP-1 receptor agonist substitution.
For New Entrants and Emerging Players: Canadian provincial formulary tiering through CADTH Common Drug Review submissions offers the most penetrable geographic entry point for differentiated renal-elimination profiles. Target transdermal delivery research partnerships with McGill University Health Centre and University Health Network Toronto to bypass oral administration commoditization. Pursue 505(b)(2) regulatory pathways leveraging existing bioequivalence standards rather than de novo clinical development.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across multi-mechanism combination tablet manufacturing as batch release protocols standardize. Five-to-ten year viability favors acquisition targets with Health Canada ICH E14 QT prolongation compliance documentation and existing provincial formulary listings in Ontario or Quebec. Monitor FDA guidance publication timing on triple-combination bioequivalence standards as the inflection signal for pipeline valuation resets.
| Strategic Initiative | Industry Significance |
|---|---|
| Cardiovascular Outcomes Trial Advancement | FDA-mandated heart safety studies embed agents within American College of Cardiology guidelines. |
| Fixed-Dose Combination Development | Integration with SGLT2 inhibitors preserves formulary access against standalone generic erosion. |
| Transdermal Delivery Research Partnership | Canadian academic medical centers pioneer non-oral administration for metformin-intolerant populations. |
| Provincial Formulary Tiering Optimization | CADTH Common Drug Review submissions secure preferred status in Ontario and Quebec. |
| Clinical Pharmacist Integration | Kaiser Permanente Northern California automates dose adjustments through EHR workflow embedding. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, Health Canada submissions, ClinicalTrials.gov records, and Medicare Part D formulary databases. Primary interviews engaged drug development executives at large-cap pharmaceutical manufacturers, regulatory affairs leads navigating ICH E14 QT prolongation guidelines, formulary directors at U.S. pharmacy benefit managers, and hospital procurement managers within Cleveland Clinic and Mass General Brigham systems. Bottom-up prescription volume modeling triangulates against top-down market sizing from payer claims data and wholesaler distribution records.
Forecast inputs include patient population epidemiology, treatment line positioning per American Diabetes Association Standards of Care, and regional regulatory cluster differentiation between FDA and Health Canada pathways. Segmentation dimensions span product type, administration mode, therapeutic area, and end user with cross-validation across the projection horizon. CAGRs derive from logistic diffusion modeling of generic penetration rates and combination therapy adoption curves. Key inputs incorporate IRA Medicare price negotiation mechanics and provincial tiering decisions by CADTH.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement rates or Canadian provincial health expenditure growth would shift the trajectory. Forecasts reflect assumptions around cardiovascular outcomes trial completion timelines and bioequivalence standard evolution without claiming certainty. Cross-checking against CMS Medicare Part D enrollment projections and Canadian Institute for Health Information drug expenditure trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
RNA-Targeted Small Molecules Market
Pharmaceuticals
Italy Opioids Market
Pharmaceuticals
Global Anesthesia Drugs Market
Pharmaceuticals
Global Nausea Medicine Market
Pharmaceuticals
Global Treatment-Resistant Depression Market
Pharmaceuticals
Bulbospinal Muscular Atrophy Drugs Market
Pharmaceuticals
Tenecteplase Drugs Market
Pharmaceuticals
Global Human Rabies Vaccine Market
Pharmaceuticals
Specialty Active Pharmaceutical Ingredients Market
Pharmaceuticals
Acne Therapeutics Market
Pharmaceuticals
Global Bendamustine Injection Market
Pharmaceuticals
Global Testosterone Replacement Therapy Market
Pharmaceuticals
Authorized Generics Market
Pharmaceuticals
Global Acyclovir Market
Pharmaceuticals
Anti-Radiation Drugs Market
Pharmaceuticals
Global Human Growth Hormone (HGH) Market