
 Rat Model Market | 2026-2036
Rat Model Market Size, Share, and Industry Trends Forecast 2026-2036
Rat Model Market Analysis
Genetically engineered rat strains is consolidating demand away from conventional outbred stocks in toxicology workflows. Charles River Laboratories leverages captive breeding infrastructure across North America and Europe to sustain contract research margins. Taconic Biosciences specializes in immunocompromised NOD-scid gamma rat lines, anchoring its position in oncology translational studies. Envigo competes on scale in standard outbred production, controlling cost-sensitive segments where pharmaceutical sponsors prioritize volume over customization.
A rat model constitutes a living laboratory organism of the species Rattus norvegicus, selectively bred or genetically modified to express specific phenotypes, disease states, or immunological profiles for controlled experimental study; CRISPR-Cas9 editing now achieves targeted knockouts with germline transmission rates exceeding 50 percent in optimized colonies. Genetic rat models command premium pricing due to intellectual property protection and breeding complexity, while spontaneous mutant lines retain entrenched positions in legacy cardiovascular protocols. Cancer research applications absorb the largest share of customized model demand, though neurobiology segments show accelerated interest in schizophrenia-relevant DISC1 mutants.
The FDA mandates Good Laboratory Practice standards for rat toxicology data submitted in New Drug Applications, directly shaping breeding documentation and colony health surveillance requirements. The NIH Office of Laboratory Animal Welfare enforces Assurance compliance for institutions receiving federal funding, conditioning market access on accreditation status. Stakeholders must monitor evolving EPA Endocrine Disruptor Screening Program protocols, as expanded testing mandates could redirect model specifications toward hormone-sensitive strains.
Market Dynamics
CRISPR-Cas9 gene editing is consolidating demand around precision-engineered rat strains, compressing development timelines from years to months and displacing conventional spontaneous mutant colonies in high-value therapeutic areas.
Growth Catalysts
- NIH Extramural Funding Expansion:The National Institutes of Health sustains the world's largest biomedical research budget, directly underwriting genetically modified rat procurement across academic medical centers and contract research organizations.
- Oncology Translation Imperative:Pharmaceutical sponsors require immunocompromised rat platforms for human tumor xenograft studies, accelerating adoption of NOD-scid gamma strains in immuno-oncology pipelines.
- CRISPR Protocol Maturation:Germline transmission rates exceeding 50 percent in optimized colonies have reduced model development costs and technical risk, enabling broader institutional access to custom knockouts.
Market Restraints
- Founder Animal Bottleneck:Generation of genetically modified founder rats requires specialized embryology infrastructure concentrated in fewer than twelve facilities worldwide, creating supply concentration risk.
- Colony Maintenance Economics:Specific-pathogen-free barrier housing consumes 40-60 percent of operational budgets at commercial breeding sites, with energy and veterinary labor costs subject to regional volatility.
- Legacy Protocol Lock-In:Decades of cardiovascular safety data generated on spontaneous hypertensive rat strains create regulatory friction against switching to genetically engineered alternatives in FDA submission packages.
Strategic Opportunities
- Neurobiology Application Expansion:Schizophrenia-relevant DISC1 mutant rats remain underutilized relative to mouse equivalents, presenting white space for preclinical CNS drug developers seeking translational validity.
- EPA Endocrine Disruptor Mandates:Expanded testing requirements under the Endocrine Disruptor Screening Program could redirect model specifications toward hormone-sensitive strains, creating demand for specialized breeding programs.
- Biobank Distribution Networks:Cryopreserved germplasm repositories enable remote reconstitution of rare strains, opening geographic markets previously excluded by live-animal shipping constraints.
Industry Challenges
- CRISPR Technical Talent Scarcity:Microinjection specialists capable of achieving high-efficiency rat embryo editing command premium compensation, constraining expansion timelines for new model development programs.
- Multi-Site Colony Synchronization:Maintaining genetic drift control across geographically distributed breeding sites requires continuous genotyping protocols that compress margins on standard outbred production.
- Intellectual Property Fragmentation:Patent thickets surrounding CRISPR-Cas9 delivery methods and specific gene targets complicate licensing negotiations for commercial model distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rat Model Market |
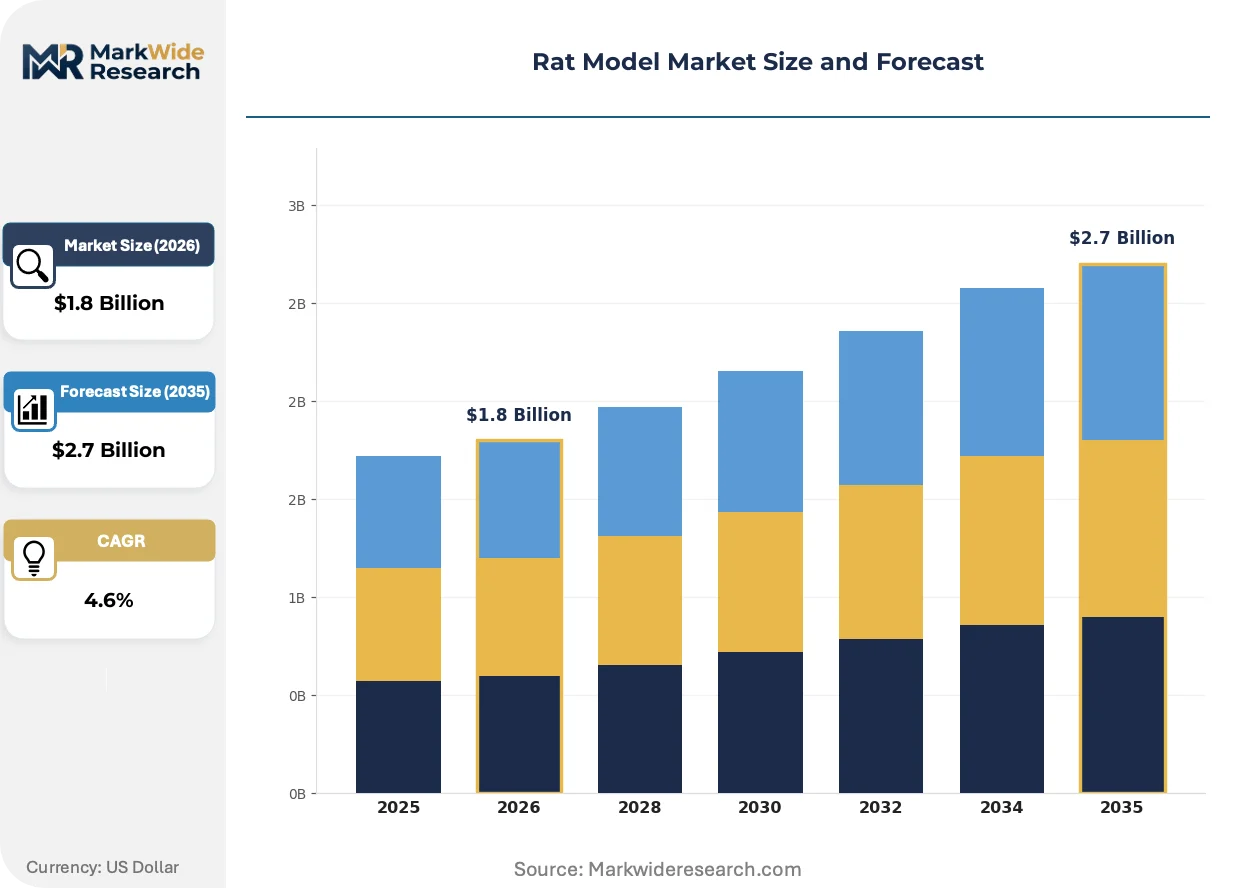
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genetic, Immunocompromised, Outbred, Spontaneous Application: Cancer Research, Neurobiology, Cardiovascular Studies, Toxicology Service Type: Breeding, Genetic Testing, Behavioral Assessment, Customized Models End User: Pharmaceutical Companies, Academic Institutions, Contract Research Organizations, Biotech Firms |
| Companies Covered | Charles River Laboratories, Taconic Biosciences, genOway, Envigo, Janvier Labs, Laboratory Corporation of America Holdings, Biomere, Horizon Discovery Group, Inotiv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rat Model Market Emerging Trajectories
Gene editing precision and regulatory data requirements are reshaping how pharmaceutical sponsors specify and procure rat models, with technology adoption curves diverging sharply between large contract research organizations and academic buyers.
CRISPR-Cas9 editing is consolidating technical workflows around single-guide RNA design platforms that enable multiplexed gene targeting. Large pharmaceutical sponsors now mandate CRISPR-derived models for all new target validation programs, displacing embryonic stem cell-based approaches. This consolidation is compressing the competitive window for service providers lacking in-house embryology capabilities.
The FDA's Good Laboratory Practice standards for toxicology data submission continue tightening documentation requirements for colony health surveillance and genetic background characterization. Breeding facilities must now maintain multi-generational pedigree records traceable to specific foundation stock. Contract research organizations serving FDA submission sponsors have responded by consolidating supplier relationships to reduce audit complexity.
Buyer concentration among the largest pharmaceutical sponsors is forcing pricing transparency and unbundling of model procurement from associated husbandry services. Mid-tier biotechnology companies now source genetically modified rats through specialized distributors rather than captive breeding programs. This shift is most visible in the United States, where sponsor consolidation has reduced the number of distinct procurement decision-makers by approximately one-third over the past decade.
Rat Model Market Segmentation

Rat model procurement decisions hinge on the trade-off between genetic precision and operational scalability. Pharmaceutical sponsors segment their supplier relationships across four distinct dimensions, each reflecting different technical requirements and budget authority structures.
Product Type:
Pharmaceutical buyers prioritize genetic fidelity over unit cost when selecting foundation stock for regulatory submission packages.
- Genetic:CRISPR-engineered strains with targeted knockouts or knock-ins achieve germline transmission rates exceeding 50 percent in optimized colonies. Demand concentrates among immuno-oncology developers at US academic medical centers seeking humanized immune system platforms.
- Immunocompromised:NOD-scid gamma rats enable human tumor xenograft engraftment with superior radiographic monitoring compared to murine alternatives. Growth tilts toward large contract research organizations running FDA-directed safety pharmacology studies.
- Outbred:Genetically heterogeneous stocks retain entrenched positions in legacy toxicology protocols where historical control data continuity matters.
- Spontaneous:Naturally occurring mutant lines such as spontaneously hypertensive rats sustain demand in cardiovascular safety assessment despite CRISPR displacement pressure elsewhere.
Volume sits with Outbred stocks; growth tilts toward Genetic strains.
Application:
Therapeutic area focus determines model specification complexity and pricing tolerance across sponsor organizations.
- Cancer Research:Human xenograft and patient-derived xenograft protocols require immunodeficient rat platforms with extended lifespan characteristics. US National Cancer Institute-designated centers drive procurement concentration.
- Neurobiology:Schizophrenia-relevant DISC1 mutants and autism spectrum disorder models remain underutilized relative to mouse equivalents, creating white space for CNS drug developers.
- Cardiovascular Studies:Spontaneous hypertensive and stroke-prone strains anchor legacy safety pharmacology workflows with decades of accumulated reference data.
- Toxicology:Regulatory submission requirements under FDA Good Laboratory Practice standards mandate specific-pathogen-free outbred stocks with multi-generational pedigree documentation.
Procurement volume clusters in Toxicology; Cancer Research exhibits the steepest expansion trajectory.
Service Type:
Service bundling decisions reflect internal embryology capability gaps and timeline pressure at buyer organizations.
- Breeding:Specific-pathogen-free expansion and timed-mating services consume the largest share of outsourced husbandry budgets.
- Genetic Testing:PCR-based zygosity confirmation and copy number variation analysis compress colony validation timelines for CRISPR-derived lines.
- Behavioral Assessment:Morris water maze and prepulse inhibition testing protocols support CNS target validation with standardized phenotyping outputs.
- Customized Models:De novo CRISPR design and microinjection services command premium pricing due to founder animal bottleneck constraints at fewer than twelve global facilities.
Revenue concentrates in Breeding; Customized Models is gaining share fastest.
End User:
Budget authority and technical sophistication diverge sharply across institutional categories.
- Pharmaceutical Companies:Large sponsors consolidate supplier relationships to reduce FDA audit complexity, mandating CRISPR-derived models for all new target validation programs.
- Academic Institutions:NIH extramural funding recipients prioritize cost-efficient outbred stocks and shared resource core facilities with Assurance compliance documentation.
- Contract Research Organizations:CROs serving FDA submission sponsors maintain captive breeding infrastructure to preserve margin control over high-volume toxicology studies.
- Biotech Firms:Venture-backed developers source genetically modified rats through specialized distributors rather than internal embryology programs.
Contract Research Organizations anchor current volume; Biotech Firms show the most rapid procurement scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical research budgets concentrate heavily in the United States, where federal funding and commercial R&D investment dwarf other national markets. This demand-side asymmetry shapes supplier infrastructure location decisions and regulatory compliance investments worldwide.
United States
The National Institutes of Health sustains the world's largest extramural research budget, directly underwriting genetically modified rat procurement across academic medical centers and contract research organizations. FDA Good Laboratory Practice standards mandate specific-pathogen-free breeding documentation for toxicology submissions. The Boston-Cambridge biotech corridor and Research Triangle Park in North Carolina anchor the densest concentrations of preclinical CRO facilities.
Germany
EMA regulatory requirements for pharmaceutical development sustain demand for standardized outbred stocks with multi-generational pedigree records. The country's national pharmaceutical regulator enforces strict colony health surveillance protocols for GLP-compliant facilities. Heidelberg and Munich host major breeding operations serving central European contract research networks.
United Kingdom
Historic leadership in cardiovascular research maintains demand for spontaneous hypertensive rat strains with decades of accumulated reference data. The Home Office regulates procedures under the Animals (Scientific Procedures) Act 1986, conditioning market access on establishment license compliance. Cambridge and Oxford university clusters drive specialized demand for neurobiology-relevant DISC1 mutant models.
Japan
PMDA guidelines for nonclinical safety studies align closely with FDA standards, facilitating cross-acceptance of rat toxicology data in new drug applications. METI funding programs support domestic breeding infrastructure for immunocompromised strains used in oncology translation. The Kansai region around Osaka concentrates pharmaceutical company captive breeding operations.
China
NMPA regulatory convergence toward ICH standards accelerates adoption of CRISPR-engineered rat models for international submission packages. The country's national pharmaceutical regulator now requires genetic background documentation comparable to FDA expectations. Shanghai and Suzhou biotech parks attract foreign breeding facility joint ventures targeting Asia-Pacific pharmaceutical sponsors.
Rat Model Market Vendor Landscape
Strategic partnerships dominate the current landscape as specialized embryology capabilities concentrate in fewer than twelve facilities worldwide. The vendor base organizes around three distinct tiers: integrated contract research organizations with captive breeding infrastructure, dedicated model suppliers with CRISPR development platforms, and regional distributors serving cost-sensitive volume segments. Two competitive moves define current positioning: technology licensing agreements that secure CRISPR-Cas9 delivery method access, and geographic expansion through cryopreserved germplasm distribution networks that bypass live-animal shipping constraints.
Within the integrated CRO tier, Charles River Laboratories and Laboratory Corporation of America Holdings exemplify scale-driven positioning through North American and European facility networks. Taconic Biosciences occupies a specialist position focused on immunocompromised NOD-scid gamma rat lines for oncology applications. These three entities represent contrasting strategic archetypes: captive infrastructure control, targeted therapeutic area specialization, and diversified service bundling respectively.
| Leading Market Players |
|---|
| Charles River Laboratories |
| Taconic Biosciences |
| genOway |
| Envigo |
| Janvier Labs |
| Laboratory Corporation of America Holdings |
| Biomere |
| Horizon Discovery Group |
| Inotiv |
| Others |
Supply Flow & Price Mechanics
CRISPR-Cas9 protocol maturation compresses development timelines from years to months while concentrating embryology capabilities in fewer than twelve facilities worldwide, simultaneously reducing per-model development costs and amplifying pricing power at specialized breeding sites. This technical transition feeds back into procurement patterns as pharmaceutical sponsors consolidate supplier relationships to reduce FDA audit complexity, accepting premium pricing for genetic precision in exchange for streamlined documentation.
Pricing Analysis
Volume sits with outbred stocks at economy tiers; margins concentrate in genetically engineered strains. Three-tier pricing structure across premium CRISPR-derived lines, standard immunocompromised platforms, and economy outbred stocks reflects genetic fidelity certification and breeding complexity. Price differentiation hinges on germline transmission rates and IP licensing overhead. Cost compression in standard outbred segments intensifies because Envigo and regional distributors compete on scale, while biotech firms show highest price sensitivity and large pharmaceutical sponsors tolerate premium pricing for regulatory submission packages.
Supply Chain Analysis
Single-source vulnerability sits with microinjection specialists capable of high-efficiency rat embryo editing, concentrated in the United States, Germany, and Japan. Founder animal production draws from specialized embryology infrastructure, specific-pathogen-free barrier housing components, and cryopreserved germplasm repositories. Supply chain risk centers on regulatory restriction as FDA Good Laboratory Practice standards tighten colony health surveillance documentation. Distribution runs through contract research organization captive breeding networks and specialized distributors serving academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as CRISPR technical talent scarcity and multi-site colony synchronization costs force weaker regional distributors toward exit or acquisition.
For Market Incumbents: Extend embryology platform capabilities through technology licensing agreements that secure CRISPR-Cas9 delivery method access, insulating against patent thicket fragmentation. Add capacity in the Boston-Cambridge corridor to capture NIH extramural funding concentration. Deepen backward integration into cryopreserved germplasm repositories to bypass live-animal shipping constraints and open geographic markets previously excluded by logistics barriers. For New Entrants and Emerging Players: Launch via cryopreserved germplasm distribution networks targeting Asia-Pacific pharmaceutical sponsors in Shanghai and Suzhou biotech parks where NMPA regulatory convergence accelerates demand. Neurobiology applications present the most penetrable white space, with schizophrenia-relevant DISC1 mutant rats underutilized relative to mouse equivalents. Position through specialized distributor relationships rather than captive breeding infrastructure to avoid founder animal bottleneck constraints. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated contract research organizations seeking embryology capability consolidation. The five-to-ten year viability window favors targets with NIH Assurance compliance documentation and established specific-pathogen-free barrier housing infrastructure. Watch EPA Endocrine Disruptor Screening Program expansion as the inflection signal that would redirect model specifications and strain demand profiles materially.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Platform Licensing Agreement | Secures delivery method access against patent thicket fragmentation threatening model development programs. |
| Cryopreserved Germplasm Repository Expansion | Enables remote strain reconstitution bypassing live-animal shipping constraints into Asia-Pacific markets. |
| NIH Assurance Compliance Investment | Conditions market access for academic medical center procurement under Office of Laboratory Animal Welfare enforcement. |
| Neurobiology Model Development Program | Captures white space in schizophrenia-relevant DISC1 mutants where translational validity exceeds mouse alternatives. |
| Multi-Site Colony Synchronization Protocol | Maintains genetic drift control across distributed breeding sites serving FDA submission sponsors. |
Methodological Framework
Independent corroboration across primary interviews with drug development executives, regulatory affairs leads at contract research organizations, biomedical procurement managers at academic medical centers, and CRISPR platform specialists underwrites the qualitative findings. Secondary validation drew from FDA New Drug Application filings, NIH Office of Laboratory Animal Welfare assurance databases, EPA Endocrine Disruptor Screening Program protocol documents, and EMA regulatory guidance publications. Bottom-up demand modeling across end-user segments triangulated against top-down pharmaceutical R&D budget allocation analysis.
Rate-of-change decomposition across the analysis window segmented volume and value trajectories by genetic model type, application area, service bundling configuration, and institutional buyer category. CAGRs were derived from fitted growth curves incorporating NIH extramural funding appropriation trends, pharmaceutical sponsor consolidation patterns, and CRISPR protocol efficiency improvement curves. Industry-specific forecast inputs included germline transmission rate assumptions and specific-pathogen-free barrier housing cost inflation factors.
Regulatory enforcement intensity, CRISPR technical talent availability, and pharmaceutical sponsor consolidation velocity are the dominant revision risks. Deviation in NIH funding appropriations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Animal Health
Companion Animal Ear Infection Treatment Market
Animal Health
Canine Mammary Tumor Treatment Market
Animal Health
Animal Health Market
Animal Health
Global Farm Animal Healthcare Market
Animal Health
US Companion Animal Health Market
Animal Health
Animal Health Software Market
Animal Health
Equine Healthcare Market
Animal Health
Canine Arthritis Treatment Market
Animal Health
US Military Animals Market
Animal Health
African Horse Sickness Treatment Market
Animal Health
Cattle Health Market
Animal Health
Equine Fluid Therapy Market
Animal Health
Canine Influenza Treatment Market
Animal Health
Global Companion Animal Health Market
Animal Health
China Companion Animal Health Market
Animal Health
Companion Animal Medicine Market