
 Equine Fluid Therapy Market | 2026-2036
Equine Fluid Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Equine Fluid Therapy Market Foresight
The equine fluid therapy supply base is rebalancing between premium colloid and blood product tiers and commodity crystalloid volumes. Zoetis Services LLC leverages its veterinary distribution network to dominate branded fluid portfolios across North American equine hospitals. Dechra Pharmaceuticals PLC anchors its position through specialized electrolyte formulations calibrated for endurance and racing applications. Boehringer Ingelheim International GmbH competes by extending its livestock anesthesia portfolio into perioperative fluid protocols.
Equine fluid therapy encompasses sterile parenteral solutions administered to horses for volume resuscitation, electrolyte correction, and nutritional support, with osmolarity typically ranging from 270 to 310 mOsm/L for isotonic crystalloids. These products serve critical therapeutic functions in colic surgery recovery, exertional rhabdomyolysis management, and neonatal foal stabilization. Crystalloid solutions occupy the highest volume tier but face margin compression from generic saline and lactated Ringer's alternatives. Blood products and colloids capture premium pricing due to production complexity and limited supplier pools. Intravenous delivery mode leads in revenue contribution as clinicians prefer rapid hemodynamic correction in critical care settings.
The FDA's Center for Veterinary Medicine enforces Current Good Manufacturing Practice standards for sterile fluid production, while the USDA monitors biologic-derived plasma and albumin products under veterinary biologics regulations. These frameworks elevate compliance costs for new entrants and sustain quality premiums among established manufacturers. Stakeholders should monitor evolving pharmacovigilance requirements and antimicrobial stewardship guidelines that could restrict adjunct therapy combinations in fluid protocols.
Market Dynamics
The equine fluid therapy market rebalances around EMA's tightened veterinary pharmacovigilance rules, which compress product registration timelines and favor manufacturers with established compliance infrastructure over new entrants.
Growth Catalysts
- Thoroughbred racing stables:Elite breeding operations in Kentucky's Bluegrass region prioritize performance recovery protocols, driving premium fluid consumption per horse above national veterinary spending averages.
- REACH-aligned manufacturing standards:European regulatory harmonization reduces cross-border compliance friction for sterile parenteral solution producers serving multiple EU veterinary markets.
- Neonatal foal stabilization protocols:Expanded critical care training at university veterinary hospitals elevates demand for isotonic crystalloids calibrated to 270-310 mOsm/L osmolarity ranges.
Market Restraints
- Plasma fractionation capacity:Blood product manufacturing requires USDA-licensed biologic facilities with limited supplier pools, constraining colloid volume expansion.
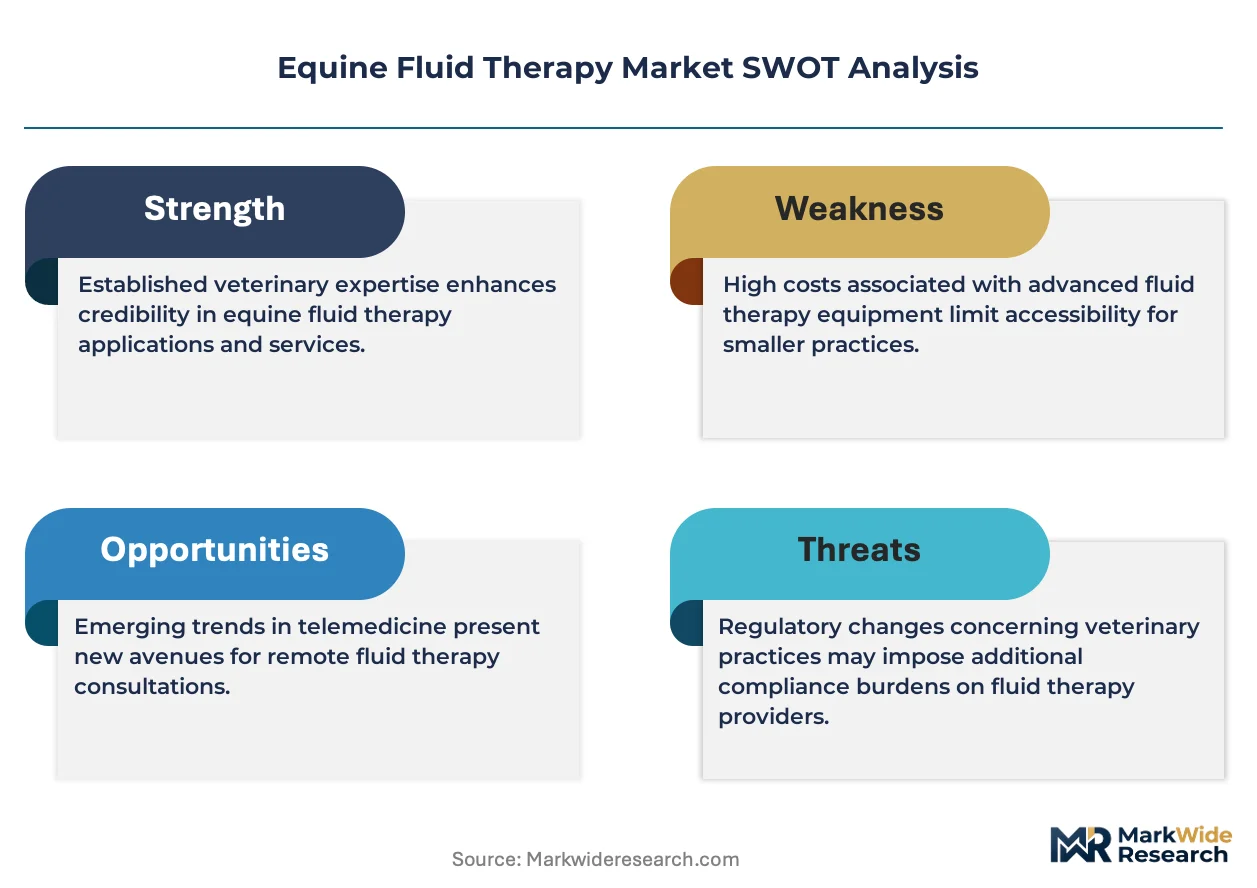
- Generic crystalloid substitution:Commodity saline and lactated Ringer's alternatives compress branded solution margins in price-sensitive ambulatory practice segments.
- Veterinary biologics inspection backlog:USDA facility certification delays extend product launch timelines for novel albumin formulations.
Strategic Opportunities
- Endurance racing electrolyte calibration:Specialized formulations for FEI-sanctioned events command premium positioning against standard replacement solutions.
- Perioperative fluid protocol integration:Anesthesia portfolio extensions into colic surgery recovery create bundled offering potential for livestock pharmaceutical suppliers.
- Telemedicine-enabled remote consultation:Digital veterinary platforms in rural Australia expand access to critical care fluid guidance beyond tertiary hospital catchments.
Industry Challenges
- Sterile manufacturing workforce scarcity:Current Good Manufacturing Practice certification requirements limit qualified production technician availability for 24/7 fluid manufacturing operations.
- Antimicrobial stewardship integration:Adjunct therapy restrictions in fluid protocols complicate protocol design for equine hospital pharmacy committees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Equine Fluid Therapy Market |
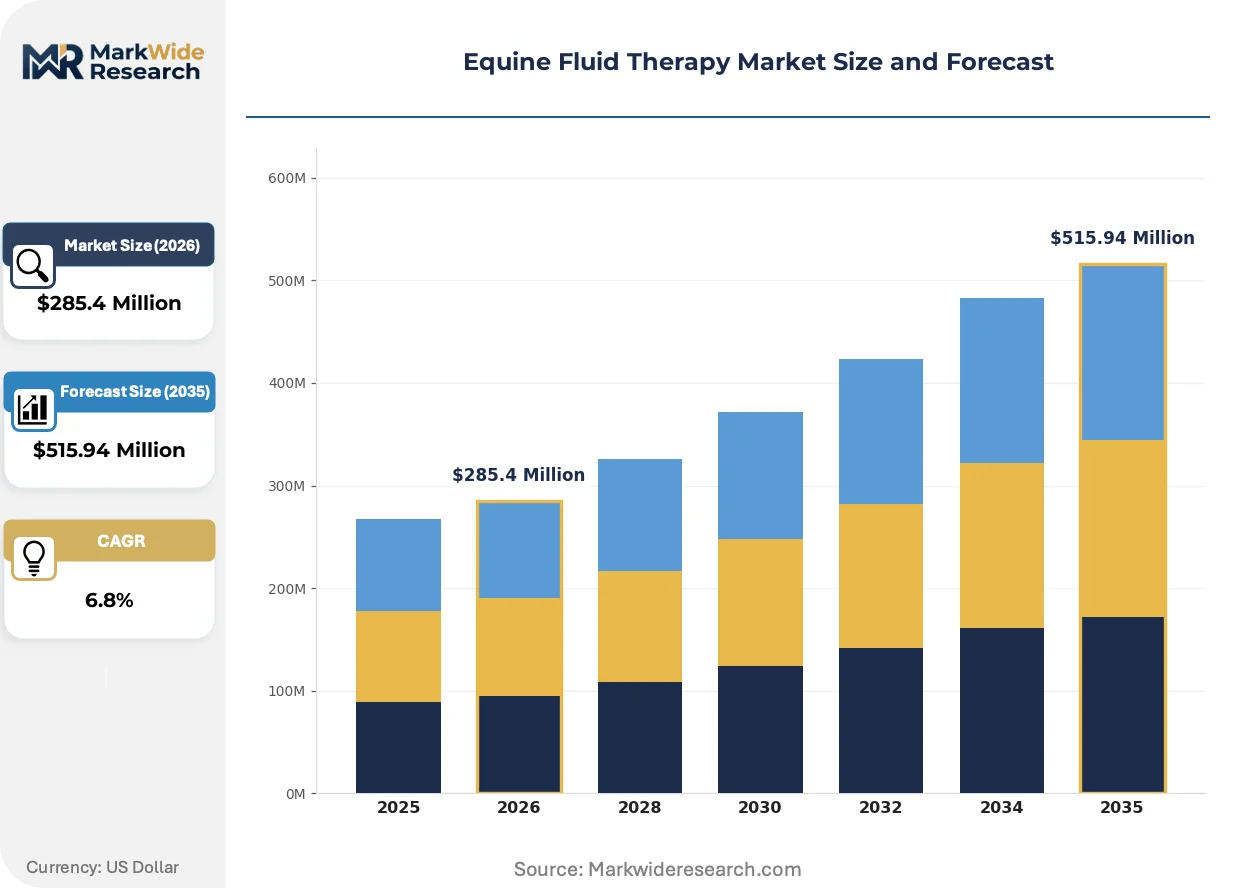
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystalloids, Colloids, Blood Products, Nutritional Solutions Application: Dehydration, Surgery, Critical Care, Performance Support Delivery Mode: Intravenous, Subcutaneous, Intraosseous, Oral End User: Veterinary Clinics, Research Institutions, Equine Hospitals, Private Owners |
| Companies Covered | MAI Animal Health, Dechra Pharmaceuticals PLC, Zoetis Services LLC, Merck Animal Health, Luitpold Pharmaceuticals, Inc, Hospira Inc., Vedco, Inc., Boehringer Ingelheim International GmbH, Ceva Santé Animale, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Equine Fluid Therapy Market Shifts & Advancements
Fluid therapy innovation clusters around point-of-care customization capabilities and regulatory compliance automation, reshaping how equine hospitals procure and administer parenteral solutions.
Closed-system fluid transfer technology is converging with automated compounding platforms to reduce contamination risk in equine hospital pharmacy operations. Large-animal referral centers in the United States adopt these systems faster than ambulatory practices due to higher case volumes. This convergence is compressing the gap between human and veterinary sterile manufacturing standards, forcing equipment suppliers to dual-certify platforms.
EMA's veterinary pharmacovigilance directive tightens adverse event reporting requirements for fluid manufacturers marketing across European Union member states. The regulation mandates real-time batch traceability and accelerates recall notification timelines. Plasma-derived product suppliers face the steepest compliance investment, while crystalloid producers leverage existing pharmaceutical manufacturing infrastructure.
Consolidated purchasing alliances among Thoroughbred racing consortia concentrate procurement decision-making with fewer veterinary directors. Kentucky-based breeding operations negotiate direct manufacturer contracts, bypassing traditional distributor markups. This concentration is most pronounced where equine hospital density supports volume commitments above 10,000 liters annually.
Equine Fluid Therapy Market Segmentation
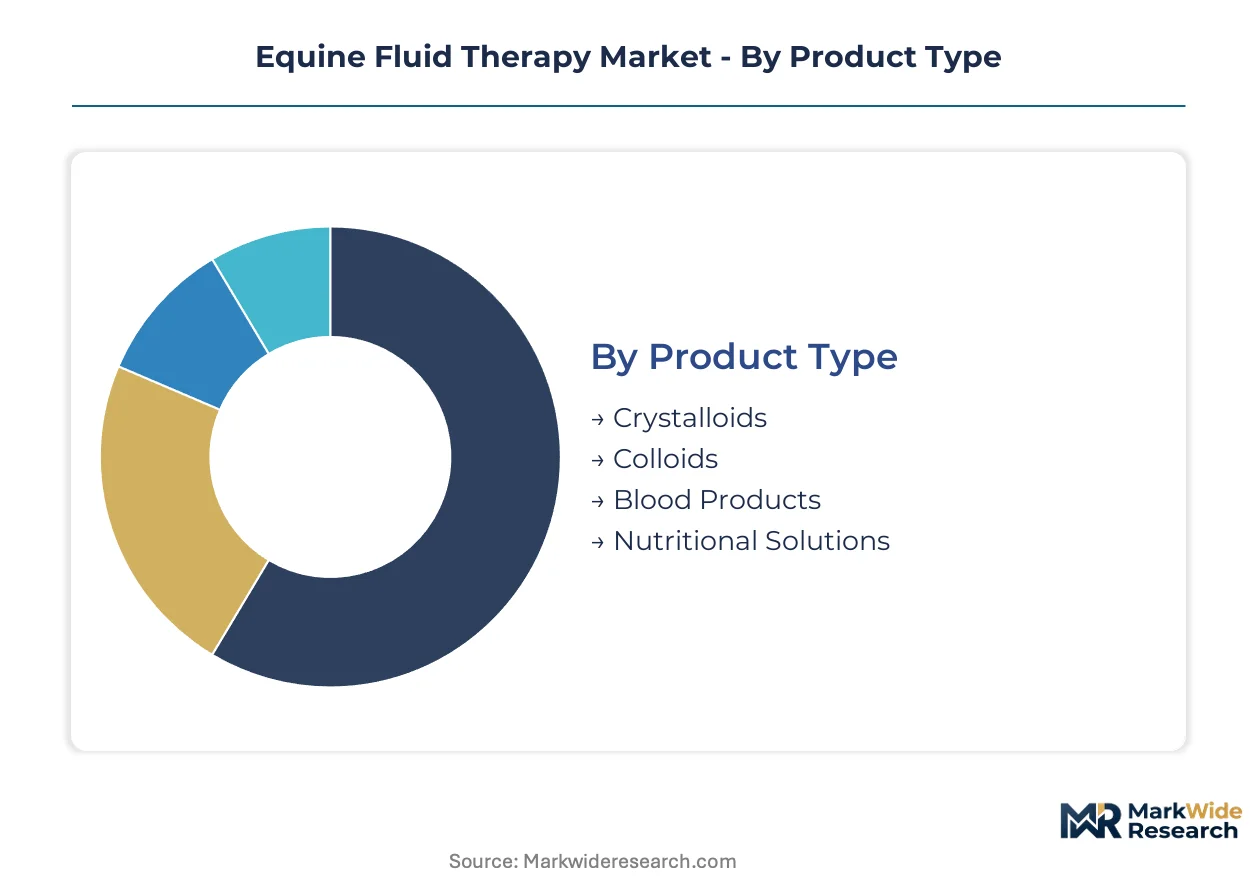
Equine fluid therapy segmentation reveals how technical specifications, clinical urgency, and facility infrastructure allocate demand across product tiers. Manufacturers configure production capacity around these divides, with crystalloid volume lines running parallel to colloid batch facilities.
Product Type:
Chemical composition and molecular weight distribution separate commodity manufacturing from specialized biologic production.
- Crystalloids:Isotonic solutions with 270-310 mOsm/L osmolarity dominate perioperative volume replacement. Kentucky's Bluegrass region veterinary hospitals consume the highest per-horse volumes due to intensive colic surgery caseloads and racing stable density.
- Colloids:Synthetic hydroxyethyl starches and natural plasma derivatives sustain oncotic pressure in hypoproteinemic states. Demand concentrates in university equine hospitals with 24-hour critical care capabilities where rapid hemodynamic stabilization protocols are standard.
- Blood Products:Fresh frozen plasma and albumin solutions require USDA-licensed biologic manufacturing facilities with limited supplier pools.
- Nutritional Solutions:Parenteral nutrition formulations combine glucose, amino acids, and lipids for foals with gastrointestinal dysfunction.
Mature deployment sits with crystalloid solutions in ambulatory practice. Newer deployment is concentrated in blood product protocols at tertiary referral centers.
Application:
Clinical indication severity determines whether fluids deploy in field settings or require hospital-based monitoring infrastructure.
- Dehydration:Oral and subcutaneous rehydration protocols address mild to moderate fluid deficits in endurance racing and transport stress. FEI-sanctioned event veterinary teams in Europe carry calibrated electrolyte formulations for rapid field administration.
- Surgery:Perioperative fluid management demands precise crystalloid-colloid ratios during colic procedures. University veterinary hospitals in the United States report the highest consumption per procedure due to extended anesthesia protocols and postoperative monitoring standards.
- Critical Care:Septic foals and exertional rhabdomyolysis cases require continuous-rate infusions with electrolyte monitoring.
- Performance Support:Pre- and post-competition hydration protocols target Thoroughbred racing stables with scheduled fluid administration regimens.
Established application volume rests with dehydration management in ambulatory settings. Performance support protocols are climbing the fastest as racing consortia professionalize recovery infrastructure.
Delivery Mode:
Speed of vascular access and clinician technical capability shape route selection across practice types.
- Intravenous:Jugular catheterization enables rapid volume delivery and continuous-rate infusion. Large-animal referral centers in the United States generate the highest revenue per case due to critical care staffing ratios and equipment depreciation costs.
- Subcutaneous:Interstitial absorption suits mild dehydration in field settings without catheterization requirements. Rural Australian equine practitioners favor this route for remote property visits where sterile intravenous access is impractical.
- Intraosseous:Tibial or sternal needle placement provides emergency vascular access in foals with circulatory collapse.
- Oral:Enteral rehydration via nasogastric tube avoids parenteral risks in cooperative patients with functional gastrointestinal motility.
Conventional deployment centers on intravenous delivery in hospital settings. Subcutaneous administration is gaining share fastest among mobile veterinary services serving dispersed breeding operations.
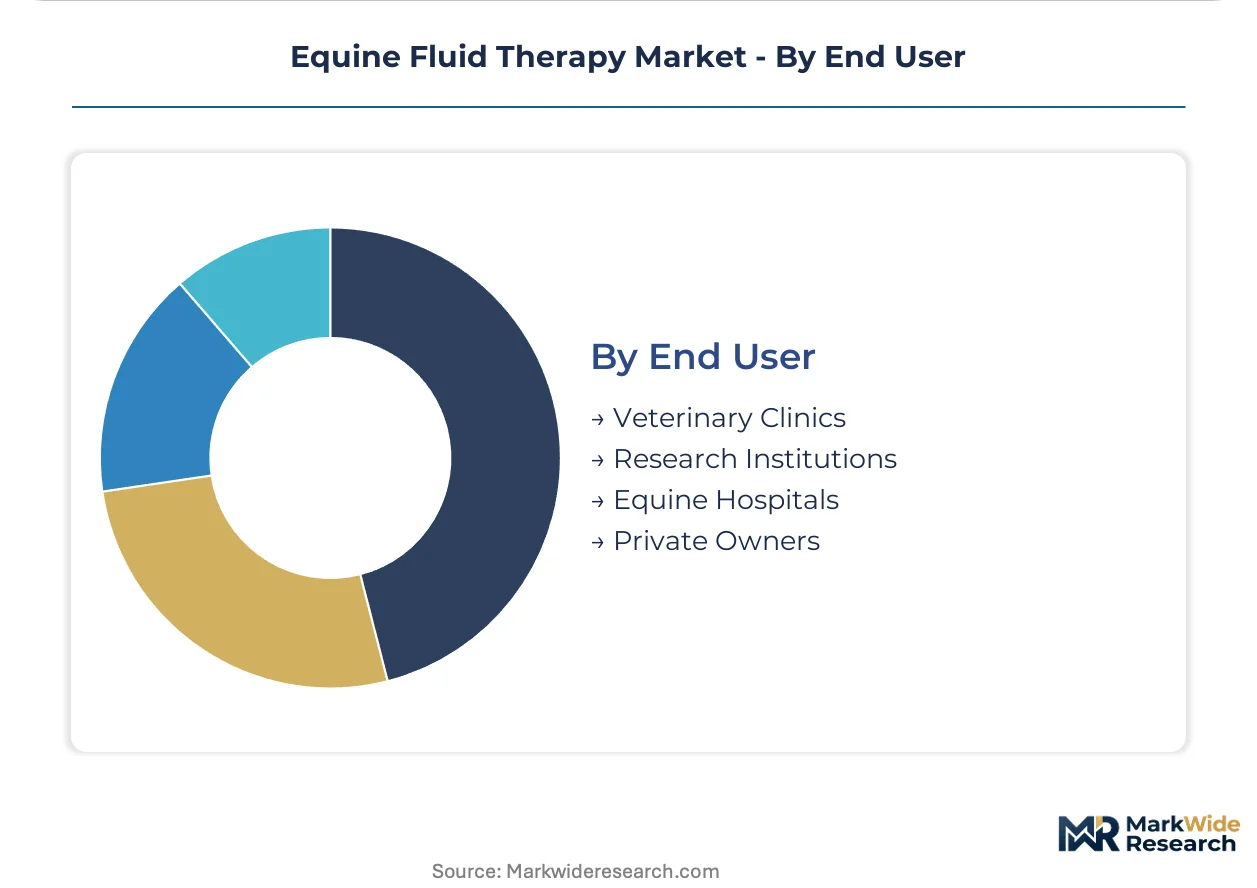
End User:
Capital investment and case volume stratify procurement patterns from individual owners to institutional purchasers.
- Equine Hospitals:24-hour critical care facilities maintain automated fluid pumps and in-house pharmacy compounding. Kentucky-based referral centers negotiate direct manufacturer contracts exceeding 10,000 liters annually, bypassing distributor markups.
- Veterinary Clinics:Ambulatory practices stock crystalloid volumes for field emergencies and routine procedures. Price-sensitive operations in the United States substitute generic lactated Ringer's for branded solutions.
- Research Institutions:University veterinary schools require fluid supplies for clinical trials and teaching hospital operations.
- Private Owners:Individual horse keepers purchase limited volumes for veterinarian-directed home care protocols.
Institutional procurement dominates in equine hospitals with consolidated purchasing alliances. Private owner segment is expanding most quickly as telemedicine platforms extend critical care guidance to rural properties.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kentucky's Bluegrass region anchors equine fluid therapy demand through its concentration of Thoroughbred breeding and racing operations. Veterinary spending per horse in this cluster exceeds national averages by significant margins. The report examines how regional veterinary infrastructure shapes procurement patterns across four key markets.
United States
Thoroughbred racing stables in Kentucky's Bluegrass region drive premium fluid consumption through performance recovery protocols. FDA's Center for Veterinary Medicine enforces Current Good Manufacturing Practice standards for sterile fluid production, elevating compliance costs for new entrants. Large-animal referral centers in Lexington negotiate direct manufacturer contracts exceeding 10,000 liters annually.
United Kingdom
Endurance racing electrolyte demand concentrates around FEI-sanctioned event circuits with specialized formulation requirements. EMA's tightened veterinary pharmacovigilance rules compress product registration timelines for fluid manufacturers. Newmarket's racing industry cluster supports veterinary hospitals with 24-hour critical care capabilities and automated fluid pump infrastructure.
Australia
Telemedicine-enabled remote consultation expands critical care fluid guidance to rural breeding operations beyond tertiary hospital catchments. The country's national pharmaceutical regulator maintains standards for sterile parenteral solution imports. Subcutaneous fluid administration gains share fastest among mobile veterinary services serving dispersed properties in Queensland and New South Wales.
Germany
REACH-aligned manufacturing standards reduce cross-border compliance friction for sterile parenteral solution producers serving EU veterinary markets. The country's federal pharmaceutical regulator enforces batch traceability requirements under EMA harmonized frameworks. Baden-Württemberg's veterinary equipment manufacturing corridor supplies automated compounding platforms to equine hospitals.
France
Neonatal foal stabilization protocols elevate demand for isotonic crystalloids calibrated to 270-310 mOsm/L osmolarity ranges at university veterinary hospitals. ANSM's pharmacovigilance coordination with EMA accelerates adverse event reporting timelines for plasma-derived products. The Normandy breeding region's equine hospital density supports volume commitments for direct manufacturer procurement.
Equine Fluid Therapy Market Competitive Landscape
Capital-heavy producers compete with asset-light formulation specialists across the equine fluid therapy supply base. The market structure consolidates around three tiers: multinational veterinary pharmaceutical conglomerates with integrated distribution networks, mid-sized regional manufacturers with specialized electrolyte portfolios, and commodity crystalloid suppliers facing margin compression from generic substitution. Strategic archetypes include anesthesia portfolio extenders seeking perioperative protocol integration, endurance racing formulation specialists commanding premium positioning, and biologic-derived product suppliers constrained by USDA-licensed facility scarcity. Dominant competitive moves encompass direct contracting with Thoroughbred racing consortia and backward integration into sterile manufacturing infrastructure.
Among multinational veterinary pharmaceutical conglomerates, Zoetis Services LLC, Dechra Pharmaceuticals PLC, and Boehringer Ingelheim International GmbH occupy positions representing distinct strategic archetypes. Zoetis exemplifies the distribution-integrated model leveraging North American veterinary hospital networks. Dechra represents specialized formulation capabilities calibrated for performance equine applications. Boehringer Ingelheim sits within the anesthesia-to-fluid extension archetype, bridging livestock pharmaceutical portfolios into perioperative protocols. These three anchors demonstrate how regulatory compliance infrastructure and manufacturing certification capabilities determine competitive positioning under tightened EMA and FDA frameworks.
| Leading Market Players |
|---|
| MAI Animal Health |
| Dechra Pharmaceuticals PLC |
| Zoetis Services LLC |
| Merck Animal Health |
| Luitpold Pharmaceuticals, Inc |
| Hospira Inc. |
| Vedco, Inc. |
| Boehringer Ingelheim International GmbH |
| Ceva Santé Animale |
| Others |
Supply & Pricing Matrix
Pharmaceutical-grade sodium chloride pricing indices cascade through equine fluid manufacturing tiers, compressing margins on commodity crystalloids while sustaining premiums for USDA-licensed plasma derivatives. Kentucky's Thoroughbred racing consortia exploit this bifurcation through direct volume contracts that bypass distributor markups on high-throughput crystalloid lines.
Pricing Analysis
Outcome-based pricing anchored to foal survival rates in neonatal critical care commands premium positioning against standard perioperative fluid bundles. Three-tier pricing structure across premium colloids, branded crystalloids, and generic saline segments reflects FDA certification grade and sterile manufacturing complexity. Cost compression in the generic lactated Ringer's tier is intensifying because of ambulatory practice substitution patterns. Price-sensitive ambulatory veterinarians in rural United States markets drive the steepest discounting, while university equine hospitals show minimal sensitivity due to bundled procurement alliances.
Supply Chain Analysis
Current Good Manufacturing Practice certification requirements gate sterile production capacity, concentrating supply among established veterinary pharmaceutical manufacturers with FDA-inspected facilities. Manufacturing gravity centers on the United States, Germany, and the United Kingdom, with each jurisdiction enforcing distinct pharmacovigilance reporting standards. Production rests on pharmaceutical-grade water systems, electrolyte precursor chemicals, and biologic source plasma as critical inputs. Single-source vulnerability in USDA-licensed plasma fractionation capacity constrains colloid expansion. Distribution runs through veterinary distribution networks for hospital segments and direct manufacturer contracts for high-volume racing consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Closed-system fluid transfer technology is displacing conventional pharmacy compounding methods, creating upgrade cycles across equine hospital infrastructure. This transition favors manufacturers with automated platform integration capabilities over legacy sterile filling operations.
For Market Incumbents: Lock in backward integration into pharmaceutical-grade water purification and electrolyte precursor supply to defend against generic crystalloid margin erosion. Secure FDA Center for Veterinary Medicine certification renewals ahead of tightened pharmacovigilance rule implementations. Channel control through exclusive distribution agreements with Kentucky Bluegrass region veterinary hospitals represents the priority defensive lever. For New Entrants and Emerging Players: Launch via telemedicine-integrated fluid guidance platforms targeting rural Australian breeding operations beyond tertiary hospital catchments. The subcutaneous administration segment in dispersed property markets offers the most penetrable white space. A go-to-market angle combining mobile veterinary service partnerships with calibrated electrolyte formulations for endurance racing applications bypasses entrenched hospital procurement barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-sized regional manufacturers with specialized electrolyte portfolios in European Union markets facing EMA compliance cost pressures. Long-term viability hinges on regulatory certification moats rather than commodity volume scale. Watch for USDA biologics facility certification backlog resolution as an inflection signal for plasma-derived product supply expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Perioperative Fluid Protocol Integration | Anesthesia portfolio extensions into colic surgery recovery create bundled offering potential for livestock pharmaceutical suppliers. |
| Automated Compounding Platform Deployment | Closed-system fluid transfer technology reduces contamination risk in equine hospital pharmacy operations. |
| Direct Manufacturer Contracting | Kentucky-based breeding operations negotiate volume commitments exceeding 10,000 liters annually, bypassing distributor markups. |
| EMA Pharmacovigilance Compliance Investment | Real-time batch traceability systems satisfy tightened adverse event reporting requirements across EU member states. |
| Telemedicine-Enabled Remote Consultation | Digital veterinary platforms extend critical care fluid guidance to rural Australian properties beyond tertiary hospital catchments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with equine hospital pharmacy directors, veterinary distribution channel managers, sterile manufacturing technicians, and Thoroughbred racing stable operations managers. FDA Center for Veterinary Medicine submission databases, EMA veterinary pharmacovigilance reports, USDA biologics facility inspection records, and FEI endurance racing veterinary protocol guidelines provided secondary validation. Bottom-up demand modeling from individual facility procurement data and top-down market sizing from manufacturer revenue disclosures were reconciled through triangulation.
Data-stream reconciliation across shipment volumes, facility capacity utilization rates, and end-user procurement surveys informed the analytical framework. Segmentation dimensions included product type, clinical application, delivery mode, and end-user facility tier across the projection horizon. CAGRs were derived from regression analysis of historical volume trends and elasticity-adjusted price trajectories. Forecast inputs incorporated university veterinary hospital caseload expansion rates and telemedicine platform penetration curves in rural markets.
Regulatory enforcement intensity shifts, plasma fractionation capacity additions, and antimicrobial stewardship guideline revisions are the dominant revision risks. Forecasts reflect assumptions about sterile manufacturing workforce availability and EMA harmonization timelines. A model refresh is warranted upon material change in USDA biologics facility certification processing rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Animal Health
Companion Animal Ear Infection Treatment Market
Animal Health
Global Poultry Healthcare Market
Animal Health
Animal Healthcare Market
Animal Health
Animal Blood Plasma Products and Derivatives Market
Animal Health
Canine Influenza Treatment Market
Animal Health
Canada Animal Health Care Market
Animal Health
Swine Healthcare Market
Animal Health
Animal Health Software Market
Animal Health
Companion Animal Healthcare Market
Animal Health
Artificial Intelligence (AI) in Animal Health Market
Animal Health
Swine Health Market
Animal Health
Companion Animal Medicine Market
Animal Health
Cattle Healthcare Market
Animal Health
US Companion Animal Health Market
Animal Health
Animal Health Market
Animal Health
China Companion Animal Health Market