
 China Companion Animal Health Market | 2026-2036
China Companion Animal Health Market Size, Share, and Industry Trends Forecast 2026-2036
China Companion Animal Health Market Intelligence
Market Context
Capital-intensity divergence between multinational and domestic players is rotating competitive dynamics sharply. Boehringer Ingelheim International GmbH leverages its integrated vaccine manufacturing footprint to dominate high-margin biologics. Zoetis anchors its position through deep veterinary clinic channel control across eastern provinces. Ceva Santé Animale differentiates via specialized avian and exotic pet portfolios that domestic rivals rarely match.
Technical and Structural Dimensions
China companion animal health encompasses pharmaceutical, biological, and diagnostic products formulated for disease prevention, treatment, and wellness management in privately owned pets, with specifications varying by species metabolism and regulatory bioequivalence requirements. The sector serves rising household expenditure on pet longevity and quality-of-life outcomes. Pharmaceuticals and vaccines together command the dominant value share, though nutritional supplements represent the fastest-expanding margin pool as owners shift from treatment to prevention. Canines generate the largest absolute revenue base, while feline-focused therapeutics and diagnostics emerge as the highest-growth sub-segment amid accelerating cat adoption rates.
Regulatory Environment and Outlook
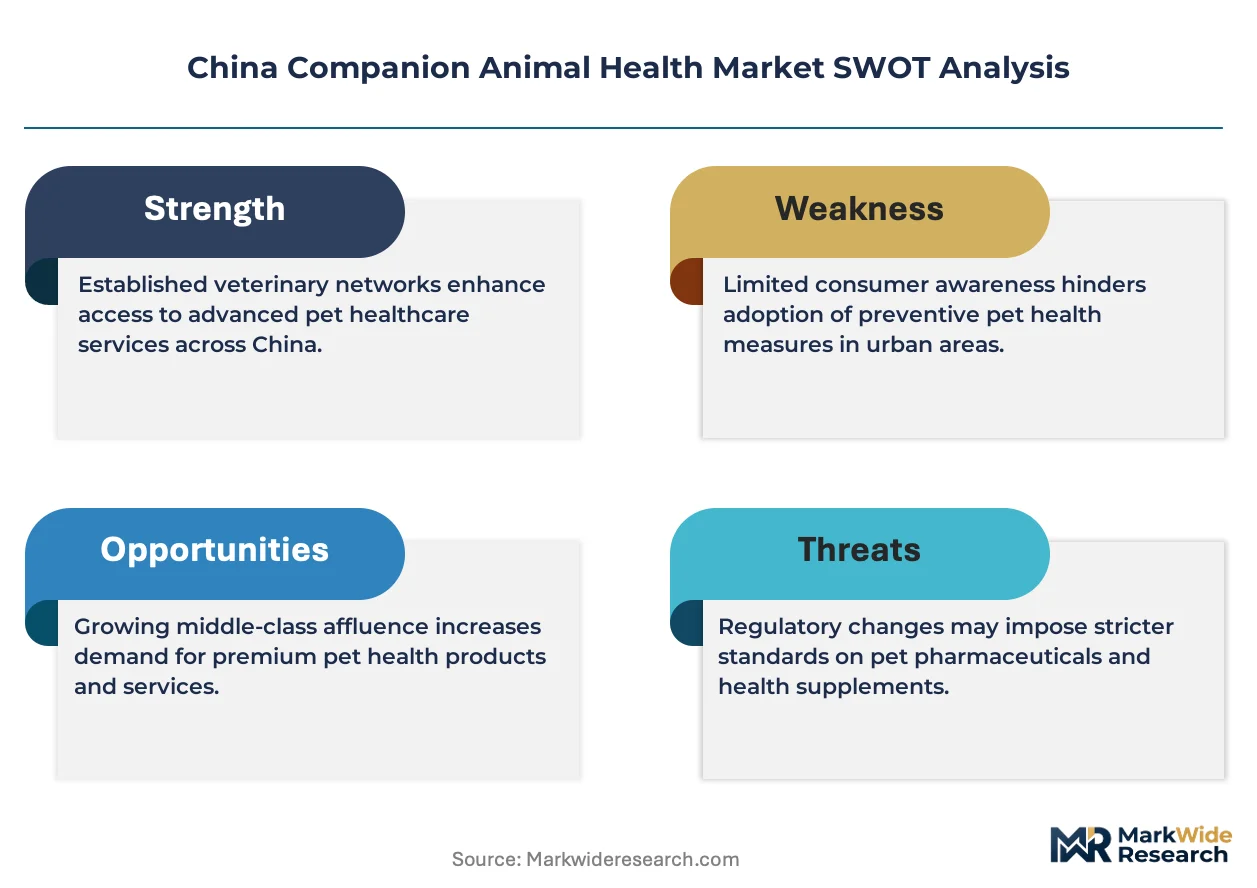
NMPA oversight of veterinary drug registration, coupled with evolving GB standards for feed additives and the Ministry of Agriculture's quarantine protocols, elevates compliance costs but simultaneously clears market access for certified domestic innovators. The country's national pharmaceutical regulator now mandates localized clinical trial data, reshaping how foreign firms structure China entry strategies. Stakeholders must monitor how provincial veterinary service network expansions and digital prescription platform authorizations reshape distribution economics ahead of the next regulatory cycle.
Market Dynamics
NMPA's localized clinical trial mandate is compressing foreign entry timelines while domestic vaccine manufacturers scale GMP-compliant bioreactor capacity. This regulatory pivot is redistributing competitive advantage toward firms with captive manufacturing footprints and indigenous R&D pipelines.
Growth Catalysts
- Urban Pet Demographics:Shanghai and Beijing household formation among professionals under 35 is concentrating premium veterinary expenditure. Tier-one municipal veterinary service networks are expanding clinic density to match this demand profile.
- NMPA Accelerated Review Pathways:The national pharmaceutical regulator's priority review designation for novel biologics is shortening domestic innovators' time-to-market. This framework rewards localized safety and efficacy data generation.
- Canine Preventive Care Protocols:Veterinary clinics are bundling vaccination schedules with wellness diagnostics. Pet owners in eastern provinces now allocate the largest budget share to disease prevention rather than reactive treatment.
Market Restraints
- Import API Dependency:Active pharmaceutical ingredient supply for companion animal therapeutics concentrates among a limited set of overseas manufacturers. Tariff and logistics volatility propagates directly into domestic formulation costs.
- GB Standards Compliance Burden:Feed additive and nutritional supplement producers face escalating testing and documentation requirements under evolving national standards. Small domestic formulators lack capital to maintain certification breadth.
- Veterinary Specialist Scarcity:Board-certified small animal practitioners remain concentrated in tier-one cities. Provincial and rural clinic networks operate with generalist staffing that limits advanced therapeutic delivery.
Strategic Opportunities
- Feline Therapeutic White Space:Accelerating cat adoption rates in Guangdong and Zhejiang are outpacing dedicated pharmaceutical development. Formulators with species-specific metabolic data can capture this underserved segment.
- Digital Prescription Platform Authorization:Ministry of Agriculture pilot programs for tele-veterinary consultations are creating new distribution channels. Early movers in prescription fulfillment logistics will shape platform economics.
- Domestic Vaccine Manufacturing Scale-Up:NMPA incentives for indigenous biologics production are aligning with provincial industrial policy. Firms with integrated antigen production and fill-finish capability can displace import-reliant competitors.
Industry Challenges
- Clinical Trial Site Accreditation:NMPA-mandated Good Clinical Practice certification for veterinary study centers is bottlenecking trial initiation. Domestic sponsors face 12-18 month queues for site qualification.
- Cold Chain Integrity for Biologics:Temperature-sensitive vaccine distribution through provincial veterinary networks requires capital-intensive storage infrastructure. Last-mile temperature excursion rates compromise product efficacy guarantees.
- Intellectual Property Enforcement:Biosimilar development pathways create ambiguity around reference product data exclusivity. Domestic innovators and multinational registrants are navigating overlapping patent and regulatory claim territories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Companion Animal Health Market |
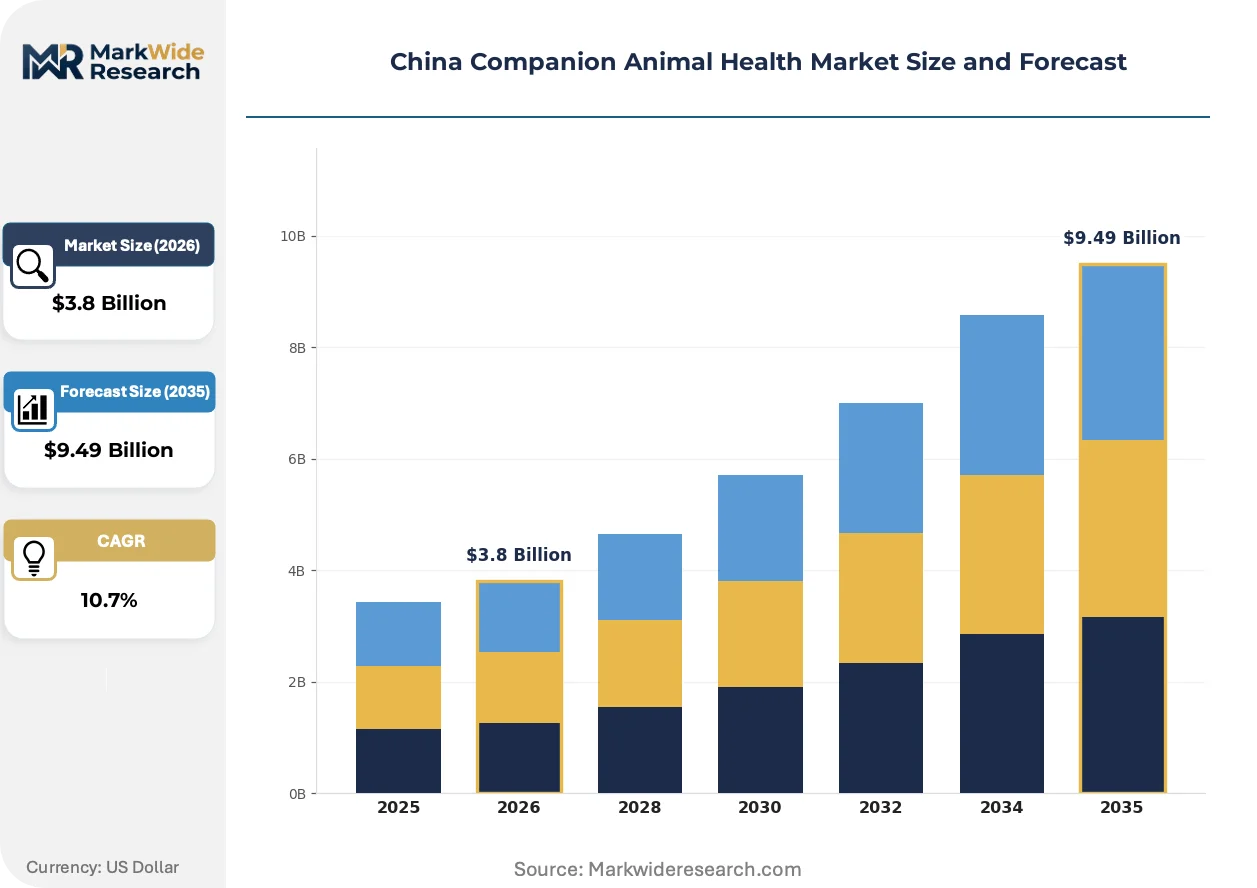
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $9.49 Billion |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Pharmaceuticals, Nutritional Supplements, Diagnostics, Therapeutics Animal Type: Canines, Felines, Avian Pets, Small Mammals, Exotic Pets Distribution Channel: Veterinary Clinics, Online Retailers, Specialty Pet Stores, Pharmacies, Mobile Clinics End User: Veterinarians, Pet Owners, Animal Shelters, Research Institutions |
| Companies Covered | Elanco Animal Health, Ceva Santé Animale, Boehringer Ingelheim International GmbH, Bimeda, Virbac, Zoetis, IDEXX Laboratories, Thermo Fisher Scientific, Merck & Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Companion Animal Health Market Strategic Shifts & Innovations
mRNA vaccine platforms are entering veterinary development pipelines, promising accelerated strain-matching for emerging infectious diseases. This technological infusion is compressing traditional inactivated vaccine development cycles while raising manufacturing complexity thresholds.
Recombinant subunit vaccines are decomposing the dominance of whole-cell inactivated formulations in canine core immunization protocols. Leading veterinary clinic chains in Jiangsu and Shandong are adopting these products for their improved safety profiles and reduced adverse event liability. The shift is compressing margins for legacy adjuvant-dependent manufacturers while rewarding firms with mammalian cell culture expertise.
NMPA's 2023 veterinary drug registration technical guidelines are mandating localized pharmacokinetic studies for all new molecular entities. This policy is forcing foreign sponsors to duplicate development expenditure across geographies rather than extrapolating foreign data. Domestic firms with established investigator networks and captive clinical operations are capturing accelerated approval timelines relative to import-dependent competitors.
Subscription-based preventive care memberships are displacing fee-for-service billing in tier-one city veterinary practices. Young professional pet owners in Shenzhen and Chengdu prefer predictable monthly expenditure over episodic high-ticket interventions. This behavioral pivot is concentrating patient volume among clinic groups with integrated wellness program infrastructure and digital payment platform integration.
China Companion Animal Health Market Segmentation
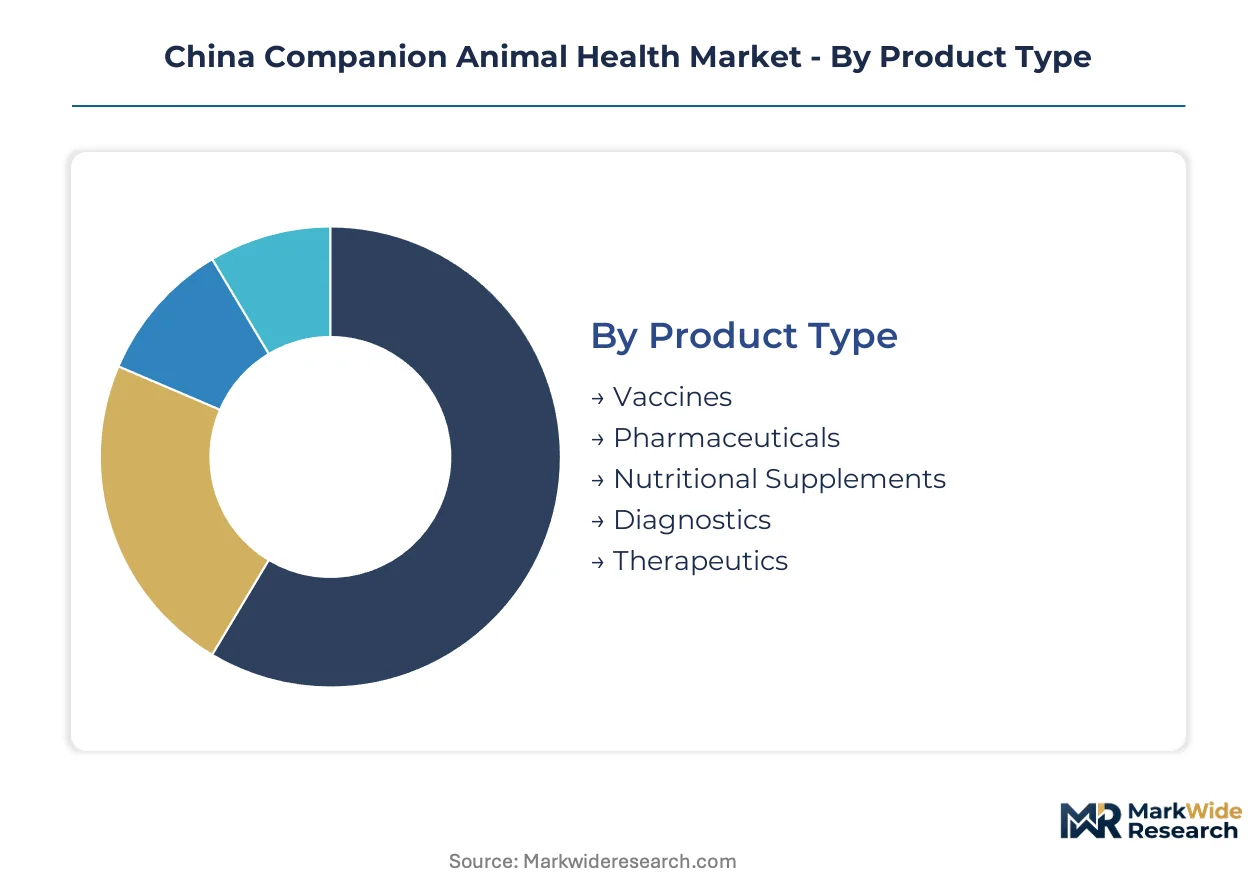
Product, species, and channel configurations in China's companion animal health market determine margin capture, regulatory pathway complexity, and manufacturing investment requirements. NMPA registration categories and provincial distribution licensing create divergent economics across segment combinations.
Product Type:
Veterinary clinics in Shanghai and Beijing channel the highest-margin biologics through bundled preventive care protocols, while online retailers concentrate volume in nutritional supplements and over-the-counter parasiticides.
- Vaccines:Inactivated and recombinant subunit formulations for canine core immunization dominate clinic procurement budgets. Eastern province veterinary networks are expanding cold chain capacity to support temperature-sensitive biologics distribution.
- Pharmaceuticals:Small molecule therapeutics for dermatology, cardiology, and pain management command prescription-controlled distribution. NMPA's localized pharmacokinetic mandate is extending development timelines for novel molecular entities.
- Nutritional Supplements:Probiotic and joint health formulations bypass veterinary prescription requirements through direct-to-consumer channels. GB standards compliance costs are squeezing small domestic formulators.
- Diagnostics:Point-of-care testing kits for infectious disease screening and wellness panels integrate into clinic subscription memberships. Shenzhen and Chengdu practices are adopting digital result platforms.
- Therapeutics:Monoclonal antibody and regenerative medicine products target refractory conditions in tier-one city specialty practices. Import API dependency elevates landed cost structures.
Vaccines dominate installed base. Nutritional supplements are where expansion concentrates.
Animal Type:
Species-specific metabolic differences dictate formulation bioequivalence requirements, with canine and feline therapeutics commanding distinct NMPA registration pathways and clinical trial designs.
- Canines:Large-breed and small-breed metabolic variation necessitates weight-tiered dosing protocols. Preventive care expenditure in Jiangsu and Shandong veterinary chains concentrates on vaccination and parasiticide bundles.
- Felines:Obligate carnivore physiology drives unique nutritional and pharmaceutical formulation requirements. Guangdong and Zhejiang cat adoption acceleration is outpacing dedicated therapeutic development pipelines.
- Avian Pets:Psittacine and passerine species demand specialized exotic veterinary expertise concentrated in tier-one cities. Ceva Santé Animale's portfolio depth captures this niche.
- Small Mammals:Rabbit, guinea pig, and hamster therapeutics rely on compounded formulations due to limited species-specific approved products. Generalist practitioners in provincial networks face dosing ambiguity.
- Exotic Pets:Reptile and amphibian health products represent minimal absolute revenue but highest per-treatment value. Specialist scarcity limits market development beyond Beijing and Shanghai.
Canines dominate installed base. Felines are climbing the fastest among companion species.
Distribution Channel:
Channel selection determines regulatory compliance burden, with veterinary clinics requiring NMPA prescription platform authorization while online retailers navigate SAMR e-commerce and feed additive labeling rules.
- Veterinary Clinics:Brick-and-mortar practices in tier-one cities control biologics and prescription pharmaceutical distribution through exclusive supplier relationships. Zoetis anchors position through eastern province channel density.
- Online Retailers:Tmall and JD Health platforms concentrate nutritional supplement and OTC product volume. Digital prescription pilot programs are reshaping fulfillment logistics for regulated therapeutics.
- Specialty Pet Stores:Premium nutrition and wellness product curation targets young professional pet owners in Shenzhen and Chengdu. Staff training limitations restrict pharmaceutical recommendation authority.
- Pharmacies:Human pharmacy chains are piloting companion animal OTC product placement in urban districts. Cross-selling economics remain subscale versus dedicated veterinary channels.
- Mobile Clinics:Vaccination and wellness service vans extend reach into suburban and emerging tier-two city markets. Cold chain integrity challenges limit biologics carriage.
Veterinary clinics dominate installed base. Online retailers are gaining share fastest.
End User:
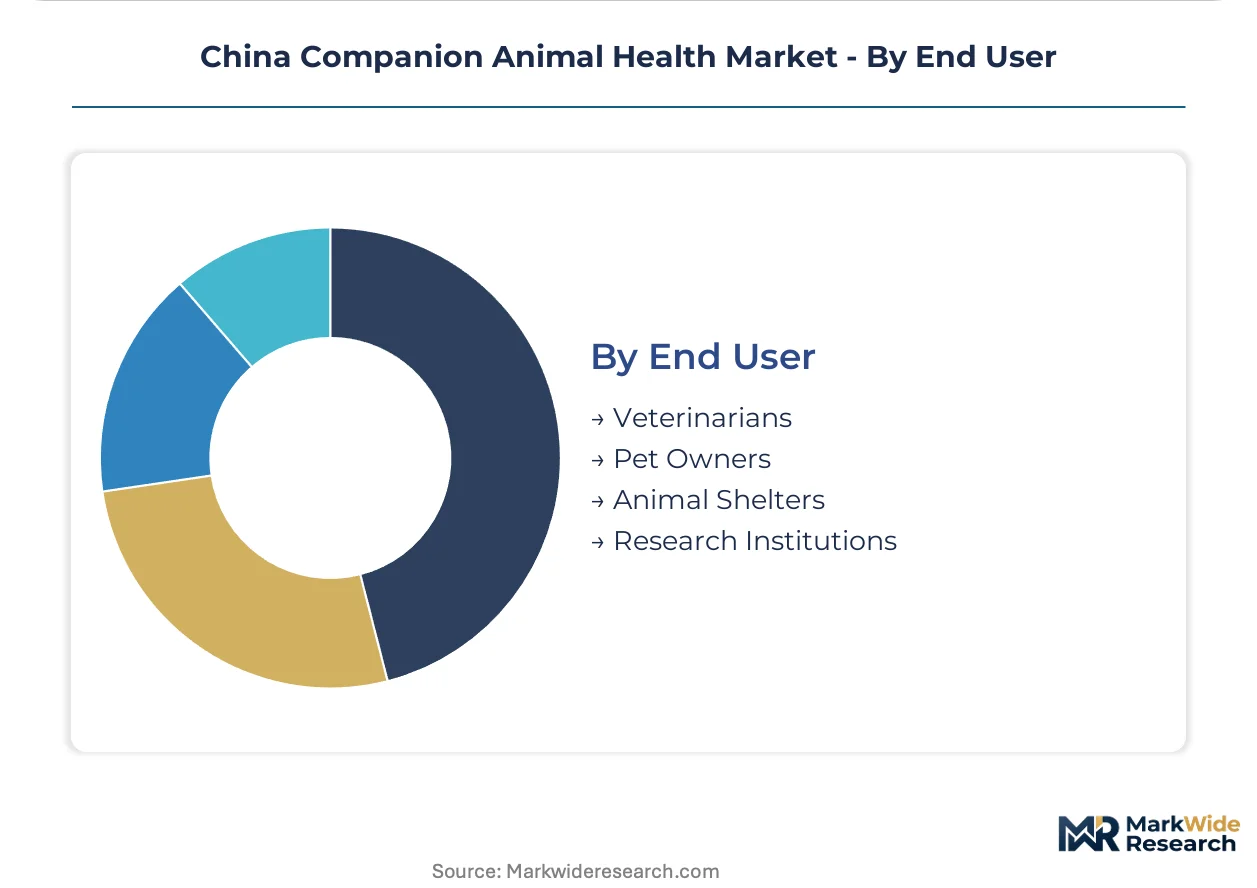
Budget authority and decision-making autonomy diverge sharply between institutional purchasers and individual pet owners, with veterinarians controlling prescription product selection while owners drive OTC and nutritional expenditure.
- Veterinarians:Board-certified small animal practitioners in tier-one cities command therapeutic protocol design and premium product recommendation. Specialist scarcity in provincial networks constrains advanced treatment adoption.
- Pet Owners:Young professionals under 35 in Beijing and Shanghai allocate largest budget share to preventive care subscriptions. Price sensitivity escalates for reactive treatment episodes.
- Animal Shelters:Municipal and private shelter networks prioritize cost-efficient vaccination and sterilization programs. Bulk procurement contracts favor domestic vaccine manufacturers.
- Research Institutions:Academic veterinary medical centers generate clinical trial demand for novel therapeutic candidates. NMPA Good Clinical Practice site accreditation queues bottleneck study initiation.
Veterinarians dominate installed base. Pet owners are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in China's companion animal health market varies sharply by city tier. Tier-one metropolitan pet owners absorb premium pricing for preventive care protocols, while provincial households demand cost-efficient alternatives. This elasticity gradient shapes regional competitive positioning.
Shanghai
Young professionals under 35 drive vaccination and wellness subscription expenditure. NMPA's localized clinical trial mandate accelerates approval timelines for domestic innovators establishing investigator networks. Pudong and Xuhui districts concentrate specialty veterinary practices bundling biologics with diagnostic panels.
Beijing
High disposable income households allocate largest budget shares to feline therapeutics and exotic pet portfolios. Municipal veterinary service network expansion targets suburban clinic density gaps. Chaoyang and Haidian districts anchor premium veterinary chains controlling prescription pharmaceutical distribution.
Guangdong Province
Accelerating cat adoption rates in Shenzhen and Guangzhou outpace dedicated pharmaceutical development pipelines. Provincial industrial policy aligns with NMPA incentives for indigenous vaccine manufacturing. Pearl River Delta cities attract bioreactor capacity investments from domestic biologics producers.
Jiangsu Province
Veterinary clinic chains in Nanjing and Suzhou adopt recombinant subunit vaccines for improved safety profiles. GB standards compliance costs squeeze small nutritional supplement formulators. Yangtze River Delta manufacturing clusters scale GMP-compliant antigen production to displace import-reliant competitors.
Sichuan-Chongqing
Emerging tier-two city demand concentrates in mobile vaccination and wellness service vans. Digital prescription platform pilots reshape fulfillment logistics for regulated therapeutics. Chengdu's young professional demographic mirrors tier-one preventive care subscription preferences at lower price points.
China Companion Animal Health Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes in China's companion animal health market. Multinational corporations anchor premium biologics through integrated vaccine manufacturing footprints and deep veterinary clinic channel control. Domestic manufacturers capture volume in nutritional supplements and cost-sensitive provincial markets through scaled production and regulatory proximity. Three strategic archetypes define competitive positioning: multinational innovators with captive R&D pipelines, domestic scale players with GMP-certified bioreactor capacity, and specialized formulators targeting species-specific metabolic requirements. Dominant competitive moves include strategic partnerships for localized clinical trial execution and portfolio diversification into feline and exotic pet therapeutics.
Among multinational innovators, Boehringer Ingelheim International GmbH and Zoetis exemplify archetypes with differentiated channel strategies. Ceva Santé Animale occupies a position within the specialized portfolio tier, representing focus on avian and exotic pet segments that domestic rivals rarely match. These three companies anchor competitive dynamics across eastern province veterinary networks and tier-one city specialty practices.
| Leading Market Players |
|---|
| Elanco Animal Health |
| Ceva Santé Animale |
| Boehringer Ingelheim International GmbH |
| Bimeda |
| Virbac |
| Zoetis |
| IDEXX Laboratories |
| Thermo Fisher Scientific |
| Merck & Co. |
| Others |
Cost & Logistics Intelligence
GMP-certified bioreactor capacity utilization among domestic vaccine manufacturers creates scale economies that compress unit production costs while elevating quality certification thresholds. This concentration of compliant manufacturing assets simultaneously hardens price floors for import-dependent competitors and rewards backward-integrated producers with captive antigen production.
Pricing Analysis
Preventive care subscription bundles now generate the dominant lifetime value stream, displacing episodic fee-for-service billing in tier-one city veterinary practices. Three-tier pricing structure across premium, standard, and economy levels stratifies by clinic certification grade and after-sales diagnostic integration. Pricing pressure stems from NMPA-mandated localized pharmacokinetic studies that duplicate development expenditure for foreign sponsors. Young professional pet owners in Beijing and Shanghai show lowest price sensitivity for bundled wellness protocols, while provincial households demand cost-efficient alternatives.
Supply Chain Analysis
Strategic stockpiling of temperature-sensitive biologics dominates inventory strategy given cold chain integrity risks through provincial veterinary networks. Active pharmaceutical ingredient supply concentrates in India, China, and select European manufacturers, with import dependency elevating landed cost structures for domestic formulators. Key inputs include mammalian cell culture media, recombinant protein antigens, and specialized adjuvant chemistries. Single-source vulnerability propagates through API supply concentration. Distribution runs through veterinary clinic networks with exclusive supplier relationships in eastern provinces, supplemented by emerging digital prescription platform pilots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's companion animal health market represents early-cycle expansion, with feline therapeutic underdevelopment and digital prescription authorization creating penetration tailwinds ahead of regulatory maturation.
For Market Incumbents: Secure channel control through exclusive veterinary clinic partnerships in Jiangsu and Shandong provinces before domestic biologics producers scale GMP-compliant capacity. Invest in captive cold chain infrastructure to guarantee temperature integrity through last-mile distribution. NMPA accelerated review pathways for novel biologics reward localized clinical data generation, threatening import-dependent market positions. For New Entrants and Emerging Players: Anchor in feline-specific therapeutic development given Guangdong and Zhejiang adoption acceleration outpacing dedicated pharmaceutical pipelines. Target mobile vaccination and wellness service vans for Sichuan-Chongqing tier-two city penetration. Digital prescription platform authorization offers regulatory-sanctioned distribution channel entry without traditional clinic network investment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic vaccine manufacturers with integrated antigen production and fill-finish capability over import-reliant formulation players. Long-term viability hinges on NMPA regulatory proximity and provincial industrial policy alignment. Watch domestic bioreactor capacity buildout rates as inflection indicator for competitive displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Clinical Trial Execution | NMPA-mandated pharmacokinetic studies accelerate approval timelines for domestic innovators with captive investigator networks. |
| Cold Chain Infrastructure Investment | Temperature-controlled distribution guarantees product efficacy through provincial veterinary network expansion. |
| Feline Therapeutic Pipeline Development | Species-specific metabolic data capture addresses underserved segment amid accelerating cat adoption rates. |
| Digital Prescription Platform Authorization | Ministry of Agriculture pilot programs create new fulfillment channels for regulated therapeutics distribution. |
| Domestic Vaccine Manufacturing Scale-Up | GMP-compliant bioreactor capacity aligns with NMPA incentives to displace import-reliant competitors. |
Research Approach
Cross-validation between primary interviews with veterinary clinic directors, pharmaceutical regulatory affairs leads, and domestic vaccine manufacturing executives anchors the qualitative findings against secondary validation. NMPA registration filings, Ministry of Agriculture quarantine protocols, and provincial veterinary service network expansion records provide regulatory trajectory inputs. Bottom-up demand modeling from clinic procurement data and top-down market sizing from GB standards compliance cost structures complete the triangulation.
Sensitivity analysis across product type, animal species, distribution channel, and end user configurations tests forecast robustness over the projection horizon. CAGRs derive from segmented adoption curve modeling and pricing trajectory assumptions. Modeled inputs include NMPA review pathway utilization rates, cold chain infrastructure investment flows, and feline adoption elasticity by province.
Decision-makers should treat outputs as directional under sustained NMPA regulatory tightening and domestic manufacturing policy alignment; material deviation would warrant model refresh. Specific risk factors include API supply disruption, veterinary specialist scarcity propagation, and biosimilar patent claim ambiguity. Revision becomes warranted when provincial clinic network expansion rates or digital prescription platform authorization scope crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Animal Health
Equine Healthcare Market
Animal Health
Canine Mammary Tumor Treatment Market
Animal Health
Rat Model Market
Animal Health
Animal Health Market
Animal Health
Swine Healthcare Market
Animal Health
Zoonotic Disease Treatment Market
Animal Health
Animal Blood Plasma Products and Derivatives Market
Animal Health
Companion Animal Healthcare Market
Animal Health
Equine Fluid Therapy Market
Animal Health
Artificial Intelligence (AI) in Animal Health Market
Animal Health
Cattle Health Market
Animal Health
Global Companion Animal Health Market
Animal Health
Canada Animal Health Care Market
Animal Health
Companion Animal Medicine Market
Animal Health
Cattle Healthcare Market
Animal Health
Animal Healthcare Market