
 Canine Arthritis Market | 2026-2036
Canine Arthritis Market Size, Share, and Industry Trends Forecast 2026-2036
Canine Arthritis Market Outlook
The FDA Center for Veterinary Medicine's tightened environmental assessment requirements for non-steroidal anti-inflammatory drugs is rebalancing formulation priorities toward biodegradable excipients and reduced-dose efficacy protocols. Zoetis Inc. leverages its vertically integrated biologics manufacturing to control costs across monoclonal antibody therapies for canine osteoarthritis. Elanco Animal Health anchors its position through sustained investment in long-acting injectable platforms that reduce dosing frequency for chronic conditions. Dechra Pharmaceuticals PLC specializes in topical transdermal delivery systems that bypass gastrointestinal side effects common in oral NSAID regimens.
Canine arthritis encompasses degenerative joint disease in domestic dogs, characterized by cartilage erosion, synovial inflammation, and subchondral bone remodeling, typically diagnosed through radiographic scoring systems and gait analysis protocols. The condition demands multimodal management combining pharmaceutical intervention, weight optimization, and physical rehabilitation to preserve locomotor function in geriatric and large-breed populations. Anti-inflammatory medications occupy the dominant revenue position due to established reimbursement pathways through pet insurance providers, while nutraceuticals represent the fastest-expanding category as preventive protocols gain traction among breeders and competitive sport dog handlers. Joint supplements concentrate margin pools through direct-to-consumer subscription models that bypass traditional veterinary distributor markups.
The USDA Animal and Plant Health Inspection Service oversees interstate movement of biological products, while the EPA regulates topical parasiticide formulations with overlapping anti-inflammatory claims under FIFRA guidelines. State veterinary medical boards enforce compounding pharmacy restrictions that limit customized NSAID preparations, channeling demand toward commercially approved dosage forms. Stakeholders must monitor evolving FDA guidance on abbreviated new animal drug applications for generic osteoarthritis therapies, as abbreviated pathways could reshape competitive dynamics between innovator and follow-on manufacturers.
Market Dynamics
Specialty veterinary hospitals are consolidating diagnostic imaging and biologic therapy capabilities into single-location service hubs, compressing referral timelines and redirecting patient volume away from general practice networks.
Growth Catalysts
- FDA Center for Veterinary Medicine abbreviated approval pathways:Streamlined review timelines for generic NSAID formulations accelerate follow-on manufacturer entry and expand therapeutic access across price-sensitive owner segments.
- Monoclonal antibody platform maturation:Targeted biologic therapies reduce corticosteroid dependency in geriatric large-breed populations with compromised renal function.
- Japan's aging dog demographic:Extended canine lifespans in metropolitan Tokyo and Osaka veterinary districts drive sustained demand for chronic pain management protocols.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for veterinary NSAIDs clusters in Zhejiang and Jiangsu provinces, exposing formulation pipelines to single-source disruption risk.
- FDA environmental assessment mandates:Tightened aquatic toxicity evaluation requirements for topical formulations extend development timelines and elevate preclinical expenditure thresholds.
- Glucosamine-chondroitin substitution:Human nutraceutical cross-over products capture preventive care spending before clinical symptom onset, diverting revenue from prescription therapeutic channels.
Strategic Opportunities
- Brazil's underserved interior states:Minas Gerais and Paraná veterinary networks lack specialty orthopedic capacity, creating whitespace for mobile diagnostic and injection service models.
- Telemedicine-triage integration:Remote gait assessment via smartphone video analysis filters appropriate candidates for in-clinic advanced imaging, reducing no-show rates in urban referral hospitals.
- EU Green Deal biodegradable excipient incentives:Reformulation grants for reduced-environmental-impact NSAID delivery systems align veterinary pharmaceutical portfolios with sustainability-linked procurement criteria.
Industry Challenges
- Veterinary orthopedic surgeon scarcity:Residency program output fails to match specialty hospital expansion rates, creating appointment backlogs and owner attrition to general practice.
- Cold chain integrity for biologics:Monoclonal antibody products require uninterrupted refrigerated distribution from manufacturing through administration, complicating rural and mobile service deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canine Arthritis Market |
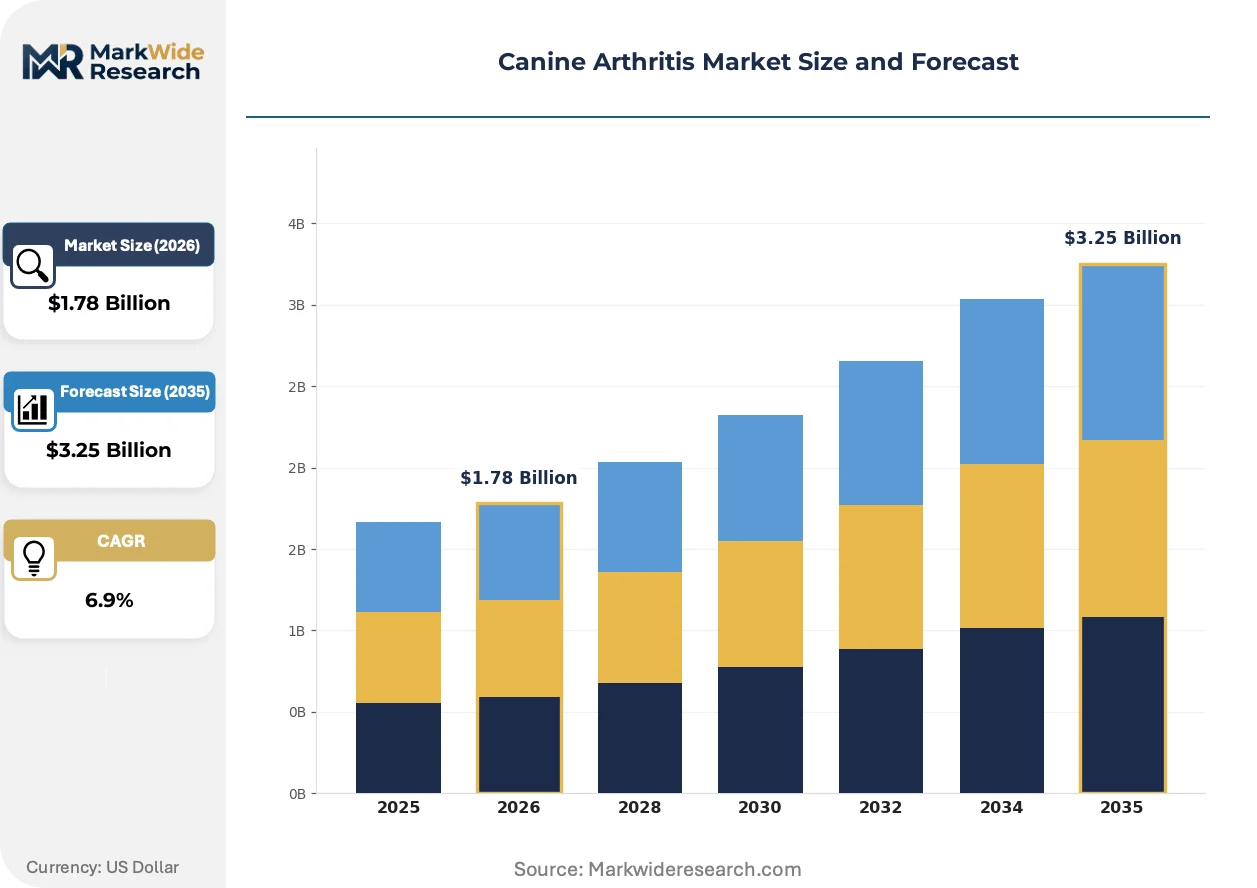
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-Inflammatory Medications, Nutraceuticals, Joint Supplements, Pain Management Products End User: Veterinary Clinics, Animal Hospitals, Pet Owners, Online Pharmacies Application: Pain Relief, Mobility Improvement, Joint Health Maintenance, Preemptive Therapy Distribution Channel: Retail Stores, E-Commerce, Direct Sales, Veterinary Distributors |
| Companies Covered | Zoetis Inc., Elanco Animal Health, Merck Animal Health, Boehringer Ingelheim, Dechra Pharmaceuticals PLC, Virbac, Vetoquinol SA, Ceva Santé Animale, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canine Arthritis Market Strategic Shifts
Biologic therapies are compressing the historical dominance of small-molecule NSAIDs, while regulatory pressure on environmental persistence accelerates formulation chemistry renovation across manufacturer portfolios.
Platelet-rich plasma intra-articular injection is overtaking hyaluronic acid viscosupplementation as the preferred biological joint therapy in competitive sport dog populations. Racing greyhound trainers and agility competition handlers in Florida and California veterinary districts have shifted procurement toward autologous blood-derived products. This transition is overtaking manufacturer revenue models built on repeated synthetic polymer purchases, forcing restructuring of veterinary distributor inventory commitments.
REACH restrictions on persistent organic pollutants are compelling European veterinary pharmaceutical manufacturers to eliminate certain polymer excipients from transdermal patch formulations. The ECHA authorization timeline pressures reformulation decisions before 2027 sunset dates for legacy compounds. German and French topical product specialists face compressed R&D cycles to maintain market access across the EU single market.
Subscription-based preventive joint supplement delivery is fragmenting traditional veterinary pharmacy revenue streams. Direct-to-consumer channels capture recurring payments from breeder networks and working dog handlers before clinical disease manifestation. This behavioral shift concentrates most visibly in Australia and the United Kingdom, where pet insurance penetration enables owners to self-direct preventive spending outside veterinary clinic influence.
Canine Arthritis Market Segmentation
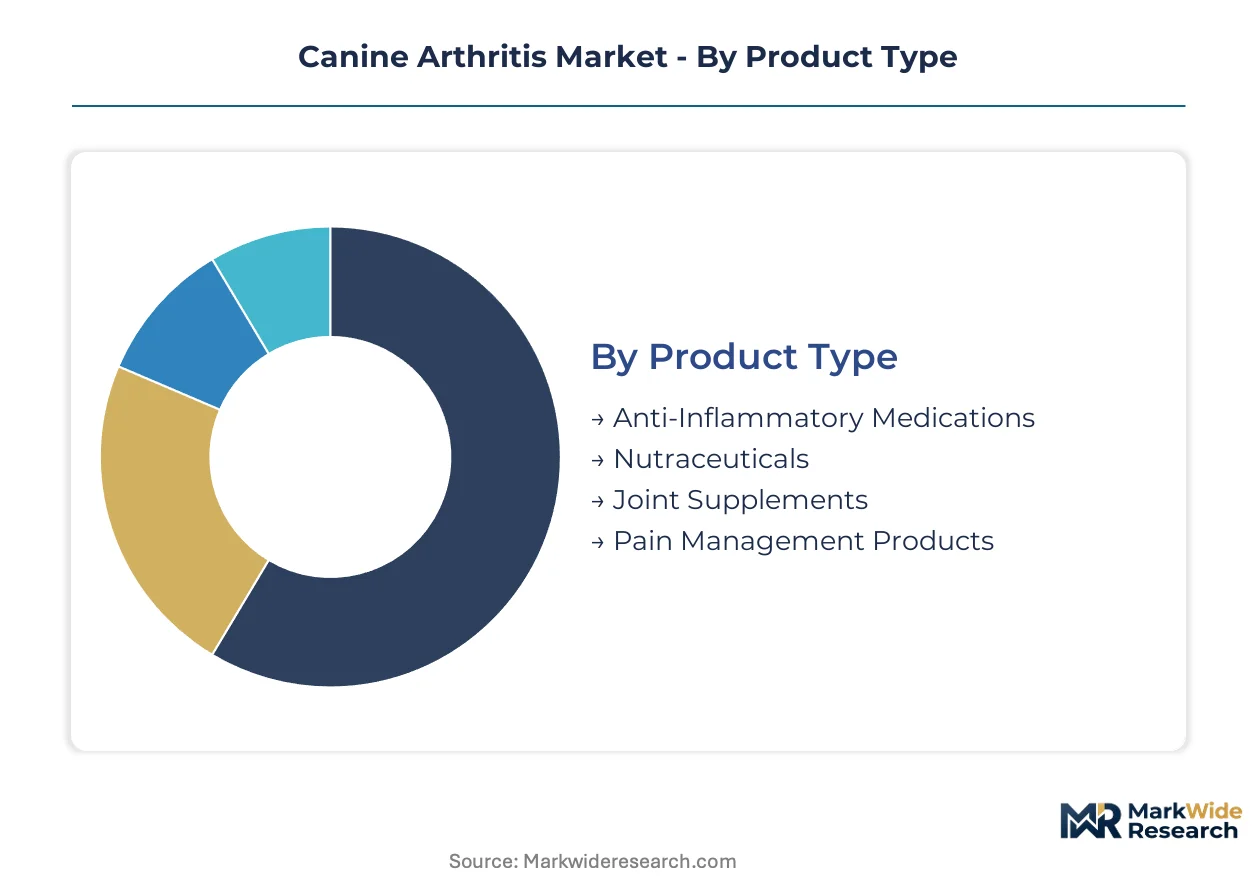
Veterinary arthritis therapeutics fragment across four intersecting dimensions that determine pricing power, channel control, and patient access. Product formulation dictates reimbursement pathways while distribution channel selection increasingly determines margin capture for manufacturers.
Product Type:
Standardization dominates prescription-grade therapeutics while nutraceuticals tolerate wider formulation variance across price tiers.
- Anti-Inflammatory Medications:Small-molecule NSAIDs and emerging monoclonal antibody formulations targeting NGF pathways. Demand concentrates in specialty referral hospitals across the United States, Germany, and Japan where board-certified surgeons prescribe biologics for geriatric large-breed cases with renal compromise. FDA Center for Veterinary Medicine approval pathways and EMA centralized procedures create divergent access timelines.
- Nutraceuticals:Glucosamine, chondroitin sulfate, and omega-3 fatty acid combinations with variable bioavailability profiles. Breeders and competitive sport dog handlers in Australia and the United Kingdom drive preventive protocol adoption through direct-to-consumer subscription models that bypass veterinary markups.
- Joint Supplements:Hyaluronic acid, collagen peptides, and polysulfated glycosaminoglycan formulations. Concentrated margin pools through recurring revenue arrangements with working dog organizations.
- Pain Management Products:Transdermal patches, long-acting injectables, and multimodal combination therapies. Growing traction in home-care settings for terminal palliation.
Leading the category by volume: Anti-Inflammatory Medications. Growing fastest: Nutraceuticals.
End User:
Service intensity and price elasticity diverge sharply between institutional purchasers and individual owners.
- Veterinary Clinics:General practice networks handling initial diagnosis and chronic medication management. Volume concentrates in suburban corridors of the United States and Western Europe where pet insurance penetration supports ongoing pharmaceutical expenditure.
- Animal Hospitals:Specialty referral centers with orthopedic surgery, advanced imaging, and interventional radiology capabilities. University veterinary medical centers in California, Texas, and Ontario anchor biologic therapy adoption curves.
- Pet Owners:Direct purchasers of over-the-counter supplements and preventive formulations. Digital-native demographics in metropolitan Tokyo and London favor subscription-based replenishment.
- Online Pharmacies:Aggregators capturing price-sensitive refill demand for chronic NSAID prescriptions. Regulatory fragmentation across state veterinary medical boards constrains interstate compounding.
Dominant by revenue: Animal Hospitals. Expanding most quickly: Online Pharmacies.
Application:
Clinical endpoints range from symptomatic relief to disease modification with corresponding reimbursement stratification.
- Pain Relief:Acute and chronic analgesia protocols using NSAIDs, opioids, and localized anesthetic blocks. Post-surgical orthopedic cases in German and French specialty clinics drive sustained demand.
- Mobility Improvement:Gait restoration through pharmacological intervention combined with physical rehabilitation. Racing greyhound and agility competition populations in Florida veterinary districts prioritize functional recovery metrics.
- Joint Health Maintenance:Long-term structural preservation in predisposed breeds. Breed-specific protocols for Labrador Retrievers and German Shepherds concentrate preventive spending before radiographic changes manifest.
- Preemptive Therapy:Early intervention in young large-breed dogs with genetic risk profiles. Emerging category gaining traction among competitive breeders seeking performance longevity.
Highest procedure volume: Pain Relief. Steepest expansion trajectory: Preemptive Therapy.
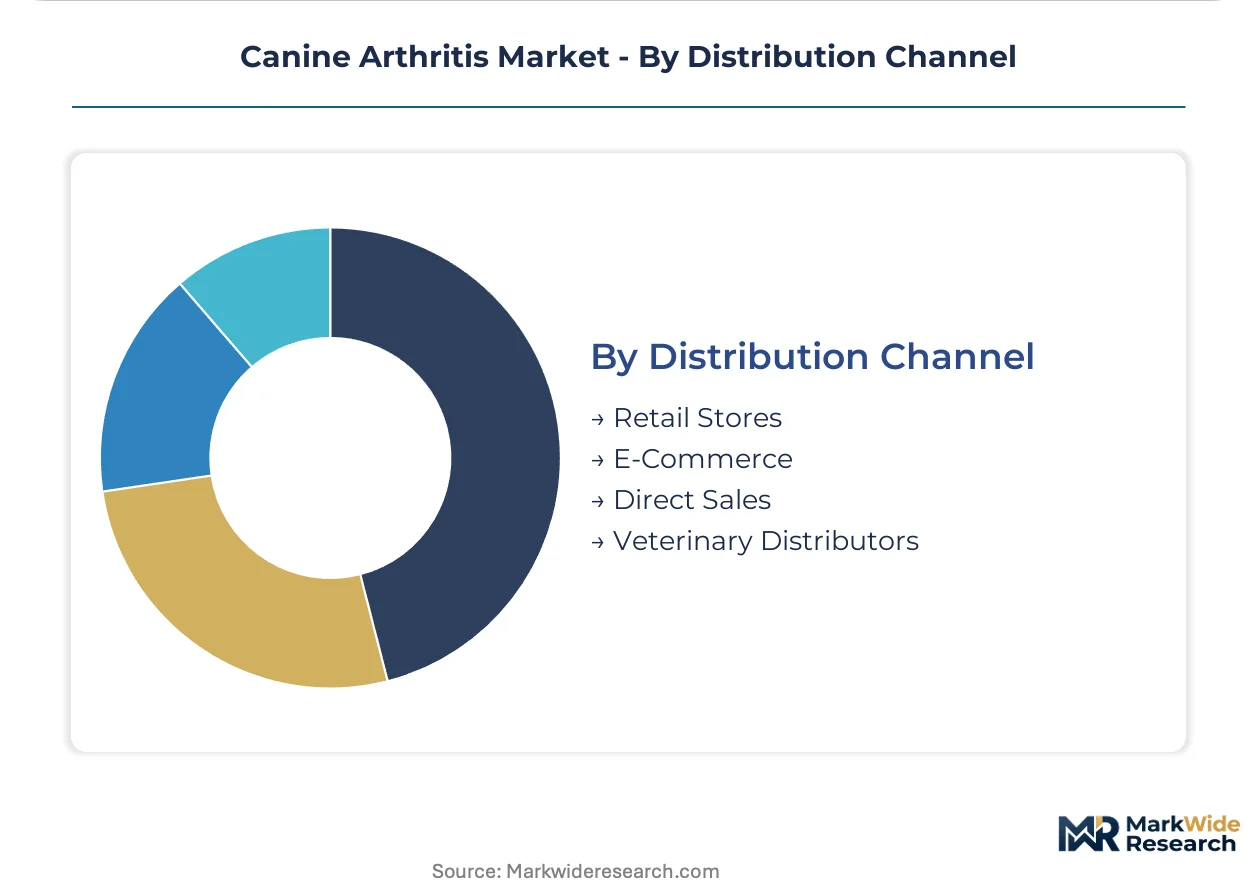
Distribution Channel:
Channel selection determines margin retention and customer data access for manufacturers.
- Retail Stores:Mass-market supplement sales through pet specialty chains. Shelf space competition favors established brands with veterinary endorsement.
- E-Commerce:Direct-to-consumer platforms capturing recurring nutraceutical subscriptions. Australian and UK markets show highest penetration among insured pet owners.
- Direct Sales:Manufacturer field representatives calling on specialty hospitals and university clinics. Critical for biologic therapy launch and surgeon education.
- Veterinary Distributors:Traditional wholesale networks serving general practice clinics. Inventory consolidation pressures from specialty hospital chains erode historical dominance.
Still commanding plurality share: Veterinary Distributors. Gaining share fastest: E-Commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty veterinary medical centers in California, Texas, and Ontario anchor biologic therapy adoption curves for canine osteoarthritis, while university hospital networks in Germany and Japan drive gait analysis protocol standardization.
United States
University veterinary medical centers in California and Texas concentrate monoclonal antibody therapy administration for geriatric large-breed populations. The FDA Center for Veterinary Medicine maintains stringent approval pathways for osteoarthritis therapeutics with tightened environmental assessment requirements. Specialty referral hospitals in suburban corridors leverage pet insurance penetration to sustain chronic pharmaceutical expenditure.
Germany
Post-surgical orthopedic cases in specialty clinics drive sustained demand for multimodal pain management protocols. REACH restrictions on persistent organic pollutants compel reformulation of transdermal patch excipients before 2027 sunset dates. Veterinary pharmaceutical manufacturers in Baden-Württemberg face compressed R&D cycles to maintain EU single market access.
Japan
Extended canine lifespans in metropolitan Tokyo and Osaka veterinary districts drive demand for chronic pain management. The PMDA oversees approval timelines for biologic therapies targeting NGF pathways. University hospitals in Kanto prefecture standardize radiographic scoring systems for early intervention protocols.
Australia
Pet insurance penetration enables owners to self-direct preventive spending through direct-to-consumer nutraceutical subscriptions. The TGA regulates veterinary therapeutic goods while state veterinary boards enforce compounding pharmacy restrictions. Breeder networks in New South Wales and Victoria concentrate recurring revenue arrangements for joint supplements.
Brazil
Veterinary networks in Minas Gerais and Paraná lack specialty orthopedic capacity, creating whitespace for mobile diagnostic services. ANVISA regulates pharmaceutical imports while state agricultural departments oversee biological product distribution. São Paulo specialty hospitals attract referral volume from underserved interior states.
Canine Arthritis Market Competitive Environment
The competitive structure tilts toward vertically integrated biologics manufacturers with captive supply chains. Consolidation pressures favor scale players with FDA-approved manufacturing facilities and long-acting injectable platforms. Two strategic archetypes dominate: diversified animal health conglomerates with cross-species therapeutic portfolios, and specialized orthopedic-focused developers with concentrated canine indications. Competitive moves center on backward integration into active pharmaceutical ingredient sourcing and geographic expansion into underserved interior veterinary markets.
Within the diversified conglomerate tier, Zoetis Inc. and Elanco Animal Health exemplify scale-driven positioning through vertically integrated manufacturing footprints. Dechra Pharmaceuticals PLC occupies a specialist position among UK-based developers with concentrated veterinary pharmaceutical focus. These three entities represent distinct competitive vectors: biologics platform maturation, long-acting formulation expertise, and transdermal delivery specialization respectively.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Elanco Animal Health |
| Merck Animal Health |
| Boehringer Ingelheim |
| Dechra Pharmaceuticals PLC |
| Virbac |
| Vetoquinol SA |
| Ceva Santé Animale |
| Bayer AG |
| Others |
Value Chain & Pricing Dynamics
Specialty veterinary hospital consolidation in suburban United States corridors and metropolitan Tokyo districts is compressing procurement leverage toward institutional purchasers, forcing manufacturers to absorb cold chain logistics costs for biologic therapies while maintaining margin through formulation chemistry differentiation.
Pricing Analysis
Value-based pricing anchors on functional mobility outcomes in competitive sport dog populations, with Florida greyhound trainers and California agility handlers paying premiums for demonstrable gait restoration. Three-tier pricing structure across premium biologics, standard NSAIDs, and economy nutraceuticals separates university hospital procurement from general practice networks from direct-to-consumer subscriptions. Pricing pressure stems from glucosamine-chondroitin human nutraceutical cross-over products capturing preventive spending before clinical symptom onset. Pet owners purchasing through Australian and United Kingdom direct-to-consumer channels exhibit highest price sensitivity, while Japanese university veterinary medical centers demonstrate lowest elasticity due to insured geriatric large-breed caseloads.
Supply Chain Analysis
Domestic-content mandates for biological product manufacturing under USDA Animal and Plant Health Inspection Service guidelines are reshaping sourcing toward captive North American production for monoclonal antibody therapies. Active pharmaceutical ingredient manufacturing clusters in Zhejiang and Jiangsu provinces of China, with secondary concentration in Indian pharmaceutical hubs and United States biologics corridors. Supply chains rest on cold chain refrigeration equipment, sterile fill-finish capacity, and biodegradable excipient feedstocks. Single-source vulnerability concentrates in monoclonal antibody platform manufacturing, where uninterrupted refrigerated distribution from production through administration complicates rural service deployment. Distribution runs through veterinary distributor networks serving general practice clinics, with direct sales channels gaining share in specialty hospital segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA Center for Veterinary Medicine environmental assessment mandates for NSAID aquatic toxicity evaluation create a cost-of-compliance moat that favors incumbent manufacturers with established preclinical infrastructure and regulatory affairs capabilities.
For Market Incumbents: Anticipate nutraceutical substitution pressure from human-grade glucosamine-chondroitin cross-over products by deepening formulation chemistry differentiation around biodegradable excipient platforms and long-acting injectable delivery systems. Consolidate backward integration into active pharmaceutical ingredient sourcing to mitigate Zhejiang and Jiangsu province supply concentration risks. Prioritize certification investment for abbreviated new animal drug application pathways to defend against generic manufacturer entry. For New Entrants and Emerging Players: Mobile diagnostic service partnerships offer whitespace penetration into Brazil's Minas Gerais and Paraná interior states, where specialty orthopedic capacity scarcity creates first-mover advantages for injection service models. Telemedicine-triage platforms represent the most penetrable channel, filtering appropriate candidates for in-clinic advanced imaging through smartphone video gait assessment. Pursue direct-to-consumer subscription models in Australian and United Kingdom markets, where pet insurance penetration enables self-directed preventive spending outside veterinary clinic influence. For Investors and Strategic Acquirers: The window for entry favors vertically integrated biologics manufacturers with captive cold chain distribution and FDA-approved manufacturing facilities. Long-term viability over the projection horizon rests on scale advantages in monoclonal antibody platform maturation and geographic expansion into underserved interior veterinary markets. Watch for FDA guidance publication on abbreviated new animal drug applications as the signal indicating competitive dynamics shift between innovator and follow-on manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Excipient Reformulation | REACH restrictions compel European manufacturers to eliminate persistent organic pollutants before ECHA authorization deadlines. |
| Long-Acting Injectable Platform Expansion | Reduced dosing frequency for chronic conditions anchors Elanco's positioning in geriatric large-breed populations with renal compromise. |
| Direct-to-Consumer Subscription Launch | Australian and UK breeder networks concentrate recurring revenue outside traditional veterinary distributor markups. |
| Mobile Diagnostic Service Deployment | Minas Gerais and Paraná whitespace enables first-mover capture of underserved interior Brazilian veterinary markets. |
| Monoclonal Antibody Manufacturing Scale-Up | Vertically integrated biologics production controls costs across NGF pathway therapies for specialty hospital networks. |
Study Parameters
Document review covered FDA Center for Veterinary Medicine approval filings, EMA centralized procedure submissions, EPA FIFRA registration databases, and state veterinary medical board compounding regulations, complemented by interviews with specialty veterinary hospital procurement directors, pharmaceutical regulatory affairs leads, biologic therapy manufacturing executives, and pet insurance formulary managers. Secondary validation drew from USDA biological product distribution records, university veterinary medical center caseload reports, and direct-to-consumer nutraceutical subscription platform data. Bottom-up patient volume modeling and top-down pharmaceutical expenditure triangulation anchored market size estimation.
Segmentation outputs reflect product type, end user, application, and distribution channel dimensions across the modeling period, with regional clusters disaggregated by regulatory framework and veterinary infrastructure development stage. CAGRs were derived from patient population growth projections, insurance penetration trajectories, and therapeutic adoption curve analysis. Forecast inputs incorporated monoclonal antibody platform maturation timelines and environmental assessment mandate compliance cost structures.
Caveats apply where FDA abbreviated approval pathway guidance publication, REACH persistent organic pollutant sunset date enforcement, or biologic cold chain logistics disruption could materially shift the outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Animal Microchip Implant Market
Veterinary
Pet Light Therapy Devices Market
Veterinary
Veterinary Faecal Filters Market
Veterinary
Global Animal Parasiticides Market
Veterinary
Europe Veterinary Vaccine Market
Veterinary
Global Veterinary MRI Market
Veterinary
Veterinary Healthcare Market
Veterinary
Companion Animal Arthritis Market
Veterinary
Pet Cremation Market
Veterinary
Veterinary Clostridium Vaccine Market
Veterinary
Companion Animal Vaccines Market
Veterinary
Veterinary CRO and CDMO Market
Veterinary
Asia-Pacific Veterinary Vaccine Market
Veterinary
Veterinary Supplements Market
Veterinary
Global Canine Influenza Vaccine Market
Veterinary
Veterinary Antimicrobial Susceptibility Testing Market