
 Companion Animal Healthcare Market | 2026-2036
Companion Animal Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Companion Animal Healthcare Market Intelligence
The traditional veterinary distribution channel, once dominated by direct-to-clinic sales, is fragmenting due to the rise of e-commerce and corporate clinic networks. Zoetis leverages its extensive R&D pipeline in vaccines and parasiticides to maintain a strong position with both independent veterinarians and large hospital groups. Elanco competes through a diversified portfolio that includes therapeutics and nutritional health products, targeting a broad spectrum of companion animal needs.
Companion animal healthcare encompasses the diagnosis, treatment, and prevention of diseases in domesticated animals, primarily dogs and cats. It involves a range of products from complex biologicals like monoclonal antibody therapies to advanced imaging diagnostics. Pharmaceuticals and vaccines constitute the largest product segments, driven by preventive care protocols and chronic condition management. Within therapy areas, dermatology and orthopedics show significant investment, addressing common ailments in an aging pet population.
Market access is governed by stringent regulatory bodies, including the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA). These agencies' requirements for clinical trial data and manufacturing standards dictate product development timelines and costs for new veterinary drugs and biologics. Stakeholders must navigate the challenge of bringing innovative, high-cost therapies to a market increasingly sensitive to out-of-pocket expenses for pet owners.
Market Dynamics
The central force shaping the companion animal healthcare market is the humanization of pets, which elevates owner expectations for care to parallel human medicine. This drives investment in advanced therapeutics and diagnostics for chronic and age-related conditions, fundamentally altering veterinary practice models.
Growth Catalysts
- Monoclonal Antibody Therapies:The development of targeted monoclonal antibody (mAb) treatments for conditions like atopic dermatitis and osteoarthritis provides highly effective, long-acting solutions, stimulating demand for premium pharmaceuticals among veterinarians and pet owners in developed markets.
- Regulatory Streamlining:Conditional approval pathways offered by the U.S. Food and Drug Administration (FDA) and similar frameworks from the European Medicines Agency (EMA) accelerate the market entry of innovative therapies for serious or life-threatening diseases, reducing time-to-revenue for developers.
- Wellness and Prevention Focus:A proactive shift toward preventive care, particularly in countries like Germany and Canada, expands the market for vaccines, parasiticides, and nutritional health products designed to maintain long-term animal well-being and prevent costly treatments.
Market Restraints
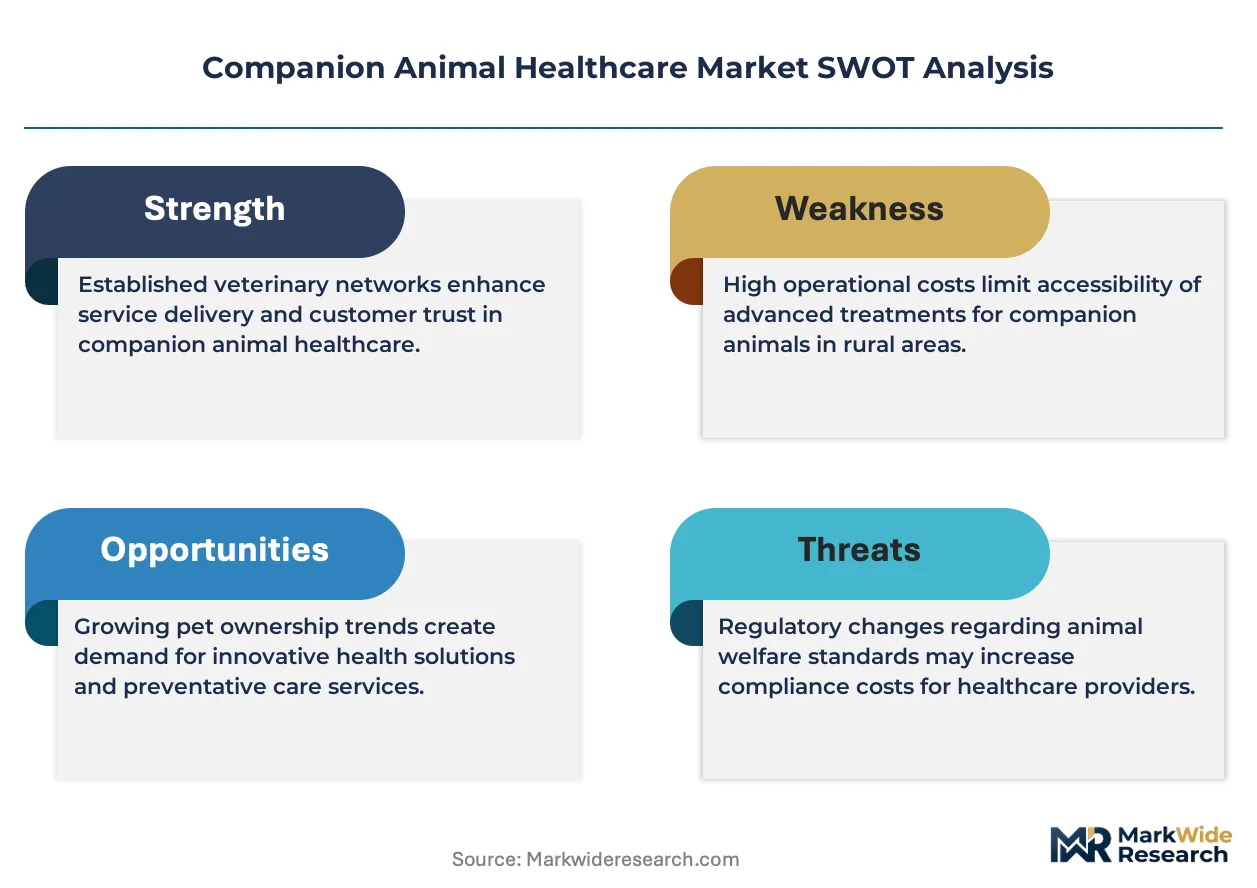
- High Treatment Costs:The significant out-of-pocket expense for advanced treatments, including biologics and specialized surgeries, creates a barrier to access for a large segment of pet owners, limiting the total addressable market for high-cost innovations.
- Stringent Efficacy and Safety Hurdles:Rigorous clinical trial data requirements imposed by the FDA and EMA for new veterinary drug approvals result in long and expensive R&D cycles, deterring investment in niche or less profitable therapeutic areas.
- API Supply Chain Concentration:The reliance on a limited number of suppliers, often concentrated in China, for critical active pharmaceutical ingredients (APIs) exposes the veterinary drug supply chain to significant geopolitical and logistical disruption risks.
Strategic Opportunities
- Telemedicine Platforms:The expansion of veterinary telehealth services creates a new distribution and consultation channel, enabling remote diagnosis, prescription management, and follow-up care, particularly for pets in rural or underserved areas.
- Underpenetrated Geographic Markets:Markets such as Brazil and Mexico, which feature large and growing pet populations but have lower penetration of advanced veterinary care, represent significant expansion opportunities for pharmaceutical and diagnostic companies.
- Microbiome-Based Diagnostics:Emerging science around the animal gut microbiome opens avenues for novel diagnostic tools and therapeutic probiotics that can address a range of health issues, from gastrointestinal disorders to immune system function.
Industry Challenges
- Veterinary Specialist Scarcity:A persistent shortage of board-certified specialists in fields like veterinary oncology, neurology, and internal medicine creates bottlenecks in the delivery of advanced care and limits the adoption of complex new therapies.
- Data Interoperability:The lack of standardization across veterinary practice management software, diagnostic lab systems, and wearable device data makes it difficult to create integrated health records and derive comprehensive clinical insights.
- Counterfeit Drug Proliferation:The growth of unregulated online pharmacies increases the risk of counterfeit veterinary pharmaceuticals entering the supply chain, posing a threat to animal health and eroding trust in established distribution channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Companion Animal Healthcare Market |
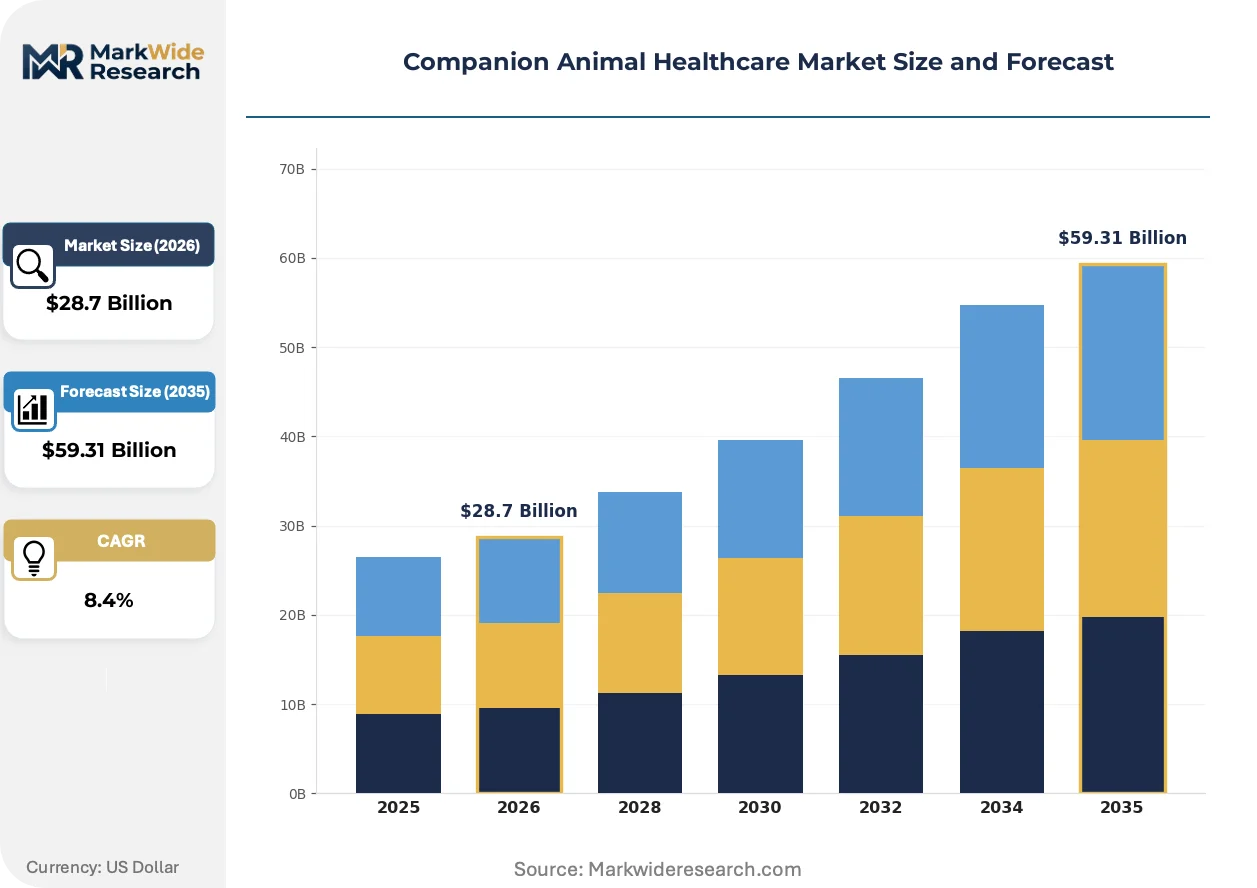
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Pharmaceuticals, Diagnostics, Surgical Equipment, Nutritional Supplements Therapy Area: Orthopedics, Dermatology, Cardiology, Internal Medicine, Behavioral Health End User: Veterinary Clinics, Animal Hospitals, Specialty Centers, Mobile Veterinary Services, Research Institutions Delivery Mode: In-person Consultation, Telemedicine, Home Care, Preventive Care Programs, Emergency Services |
| Companies Covered | Zoetis, Merck & Co., Inc., Elanco, Boehringer Ingelheim, Ceva Santé Animale, Virbac, IDEXX Laboratories, Inc., Bayer AG, Dechra Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Companion Animal Healthcare Market Strategic Shifts & Innovations
The convergence of data analytics and molecular biology is creating a new paradigm of personalized medicine in veterinary care. This shift moves treatment from generalized protocols toward therapies tailored to an individual animal's genetic makeup, lifestyle, and specific disease biomarkers.
Advanced diagnostic tools based on genomic sequencing and biomarker analysis enable the creation of highly specific treatment plans. Veterinary specialists, particularly in oncology and internal medicine, are increasingly adopting these technologies to guide therapeutic choices. This hyper-personalized approach is rendering obsolete the one-size-fits-all treatment protocols for complex diseases like cancer and autoimmune disorders.
New regulations in the European Union are designed to stimulate pharmaceutical development. The Veterinary Medicines Regulation (EU) 2019/6 simplifies the marketing authorization process and offers incentives for developing drugs for minor use and minor species (MUMS). This policy directly affects manufacturers by lowering barriers to entry for niche therapies, encouraging investment in previously underserved segments of the companion animal market.
A fundamental change in product acquisition is altering the market's structure, moving away from a reliance on manufacturer-direct sales to veterinarians. The rise of corporate clinic networks with centralized purchasing and the growth of consumer-facing online pharmacies are fragmenting the traditional distribution model. This trend is most visible in the United States and the United Kingdom, where e-commerce platforms command a significant share of non-prescription product sales.
Companion Animal Healthcare Market Segmentation
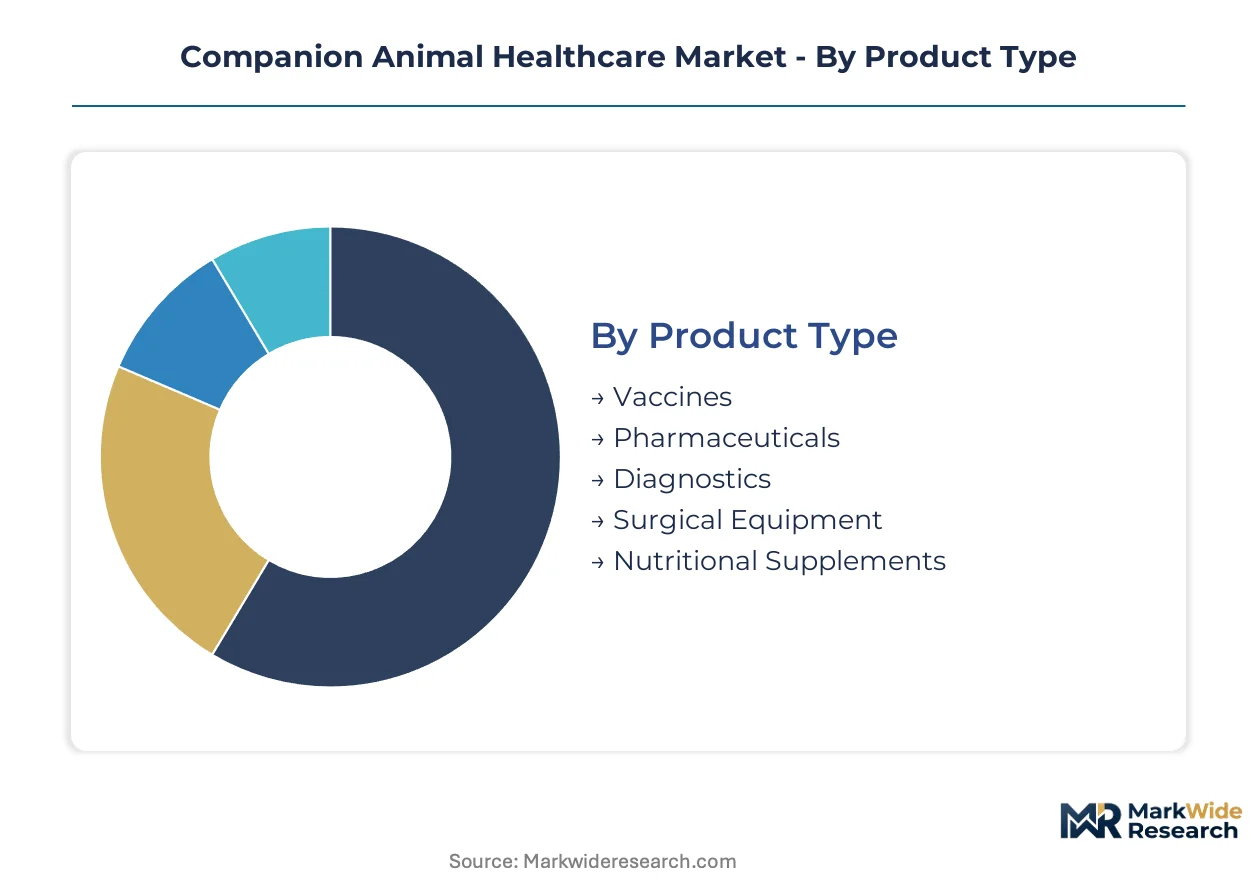
Understanding the companion animal healthcare market through segmentation reveals distinct demand patterns and operational models. These classifications highlight where veterinary services and product innovations are most effectively deployed, guiding strategic investment decisions. Each segment represents a unique pathway for delivering advanced care to pets globally.
Product Type:
The product type segmentation delineates the spectrum of solutions available for animal health, ranging from preventive measures to complex therapeutic interventions. This categorization helps stakeholders understand the specific needs addressed by various offerings within veterinary medicine.
- Pharmaceuticals:These include a broad range of prescription and over-the-counter medications for treating diseases, pain management, and behavioral issues in pets. Demand for novel pharmaceuticals is strong in developed markets like the United States, driven by owner willingness to invest in advanced treatments for chronic conditions.
- Diagnostics:This segment encompasses advanced imaging, laboratory tests, and point-of-care devices used to accurately identify and monitor animal health conditions. Demand for precise diagnostics is accelerating in Europe, where regulatory frameworks encourage early disease detection to improve treatment outcomes.
- Vaccines:Biological preparations stimulate immunity against infectious diseases, forming a cornerstone of preventive veterinary care protocols.
- Surgical Equipment:This includes instruments and devices necessary for various veterinary surgical procedures, from routine spays to complex orthopedic operations.
- Nutritional Supplements:Products like vitamins, probiotics, and specialized diets support overall pet health, addressing specific deficiencies or promoting wellness.
The dominant share belongs to Pharmaceuticals, while Diagnostics is closing the gap fastest.
Therapy Area:
Segmentation by therapy area illustrates the specific medical conditions and specialties that drive product development and service delivery in companion animal care. This helps prioritize research and resource allocation for prevalent pet ailments.
- Dermatology:This area focuses on the diagnosis and treatment of skin conditions, allergies, and parasitic infestations, which are common complaints among pet owners. Investment in targeted monoclonal antibody therapies for atopic dermatitis is significant, especially in North America.
- Orthopedics:This segment addresses musculoskeletal disorders, including arthritis, fractures, and joint diseases, prevalent in aging and large-breed pet populations. Advanced surgical techniques and pain management solutions are seeing increased adoption in Western Europe.
- Cardiology:This specialty manages heart conditions, including congenital defects and acquired heart diseases, often requiring long-term medication and monitoring.
- Internal Medicine:This broad category covers non-surgical diseases affecting internal organ systems, requiring complex diagnostic and treatment protocols.
- Behavioral Health:This area focuses on addressing anxiety, aggression, and other behavioral issues in pets through medication, training, and environmental modifications.
Dermatology treatments are expanding most quickly, driven by new biologic therapies.
End User:
The end-user segmentation identifies the primary settings where companion animal healthcare services and products are consumed. This highlights the diverse operational structures within the veterinary industry.
- Veterinary Clinics:These are local, general practice facilities providing routine check-ups, vaccinations, and basic medical and surgical services. These clinics form the backbone of primary pet care across the United States.
- Animal Hospitals:Larger facilities offering a wider range of services, including advanced diagnostics, specialized surgeries, and overnight care for complex cases. These institutions attract significant investment for advanced equipment in urban centers.
- Specialty Centers:These facilities focus on specific medical disciplines like oncology, neurology, or ophthalmology, providing advanced, referral-based care.
- Mobile Veterinary Services:These services offer convenient, on-site veterinary care directly at the pet owner's home, particularly popular in rural areas or for pets with travel anxiety.
- Research Institutions:These entities conduct studies on animal diseases, drug development, and veterinary science advancements, contributing to future healthcare solutions.
Veterinary Clinics remain the largest end-user segment, with Animal Hospitals climbing the fastest in terms of service expansion.
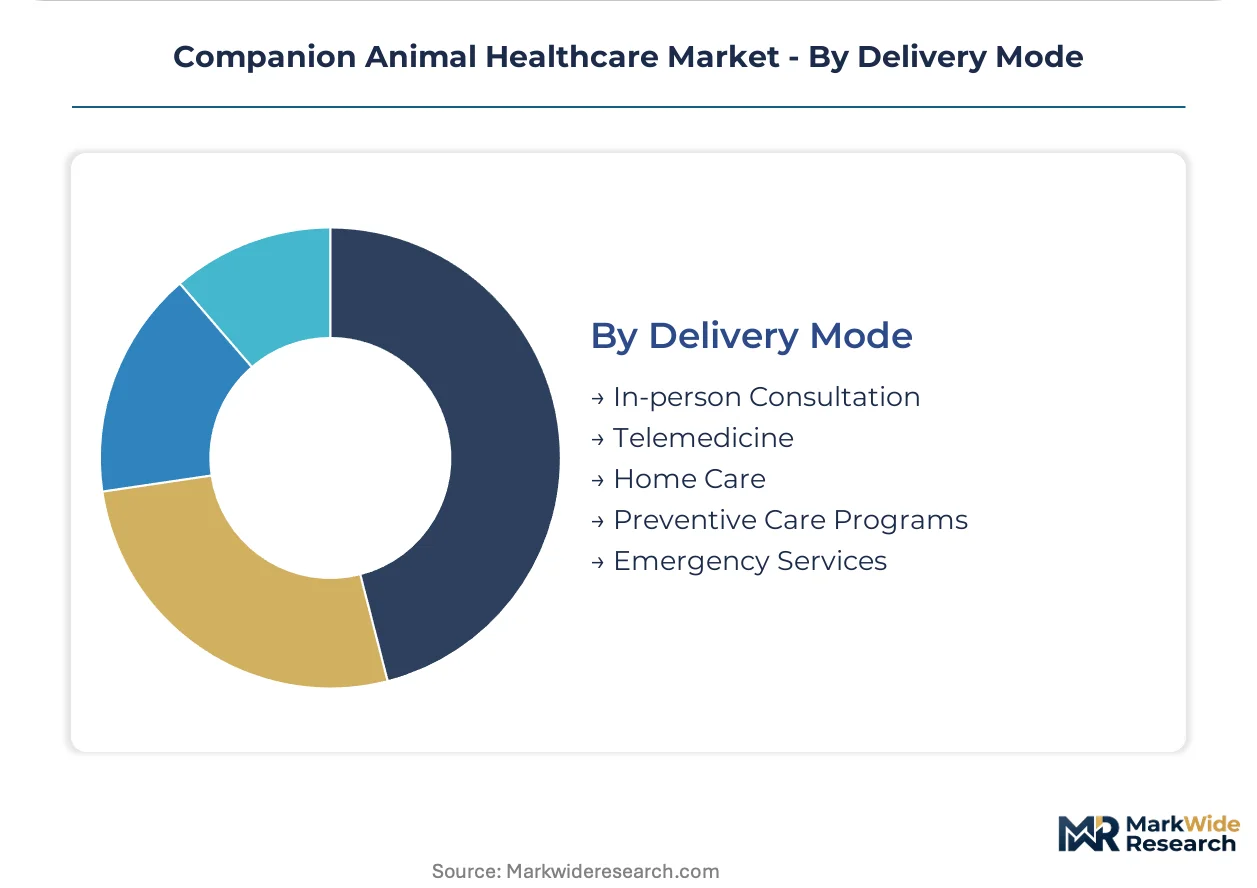
Delivery Mode:
Segmentation by delivery mode illustrates the various channels through which veterinary care and related services reach pet owners. This reflects evolving consumer preferences and technological advancements.
- In-person Consultation:This traditional mode involves direct physical visits to veterinary facilities for thorough examinations, treatments, and complex surgical procedures. It remains the foundational method for comprehensive diagnostic and interventional care, especially for critical or severe conditions.
- Telemedicine:This involves remote veterinary consultations, diagnosis, and follow-up care facilitated by digital platforms and communication technologies. Telemedicine platforms are gaining significant traction in Canada for routine check-ups and prescription management.
- Home Care:This includes veterinary visits conducted at the pet owner's residence for routine examinations, minor treatments, or end-of-life care.
- Preventive Care Programs:These structured programs focus on long-term wellness through regular vaccinations, parasite control, and nutritional guidance.
- Emergency Services:These services provide immediate medical attention for critical injuries or sudden severe illnesses outside regular operating hours.
In-person Consultation retains its primary position, while Telemedicine is gaining share fastest through remote access solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States market commands premium pricing for advanced companion animal therapies, contrasting with emerging economies like Brazil where cost sensitivity heavily influences treatment choices. This regional asymmetry reflects varying pet owner willingness to pay for specialized veterinary services. Demand concentration for high-value innovations primarily resides in developed nations.
United States
Pet humanization drives demand for sophisticated diagnostics and novel pharmaceuticals, particularly for chronic conditions. The U.S. Food and Drug Administration (FDA) approval process shapes product development pipelines, emphasizing efficacy and safety. Major veterinary pharmaceutical companies concentrate research and development in regions like the Northeast Corridor, focusing on advanced biologics.
Germany
Proactive wellness and prevention initiatives stimulate demand for vaccines and nutritional health products designed for long-term animal well-being. The European Medicines Agency (EMA) frameworks encourage early disease detection to improve treatment outcomes. Veterinary research clusters around cities like Munich, advancing personalized medicine approaches for companion animals.
Canada
Telemedicine platforms are gaining significant traction for routine check-ups and prescription management, expanding access to veterinary care. Health Canada's regulations support preventive care protocols, including robust vaccination schedules for common pet diseases. Urban centers such as Toronto are seeing increased adoption of advanced diagnostics for early disease intervention.
Brazil
A large and growing pet population presents significant expansion opportunities for pharmaceutical and diagnostic companies, despite lower penetration of advanced care. ANVISA, the national health surveillance agency, governs market access for veterinary drugs, influencing product availability. São Paulo's metropolitan area features increasing investment in specialized veterinary clinics.
Japan
Demand for advanced imaging and laboratory tests is increasing, driven by an aging pet population and owner willingness to invest in diagnostics. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures stringent quality control for veterinary pharmaceuticals and biologics. Research institutions in regions like Kanto focus on developing advanced biomarker analysis tools for precise treatment.
Companion Animal Healthcare Market Key Industry Players
Specialized pharmaceutical developers and diversified animal health conglomerates split the companion animal healthcare market, creating a dynamic competitive environment. This structure exhibits both consolidation among established players and fragmentation due to new distribution channels like e-commerce and corporate clinic networks. Companies prioritize extensive R&D pipelines in areas like vaccines and parasiticides, alongside strategic portfolio diversification to maintain market presence. Significant investment in advanced therapeutics and diagnostics also shapes competitive positioning across various therapy areas.
Among the established players, Zoetis exemplifies a strong focus on extensive R&D, particularly in vaccines and parasiticides, maintaining robust relationships with both independent veterinarians and large hospital groups. Elanco, another prominent entity, occupies a position characterized by a diversified portfolio that includes therapeutics and nutritional health products, addressing a broad spectrum of companion animal needs across various species. Merck & Co., Inc., a global pharmaceutical company, also represents a significant force, contributing to the market with its animal health division and leveraging its broader scientific expertise.
| Leading Market Players |
|---|
| Zoetis |
| Merck & Co., Inc. |
| Elanco |
| Boehringer Ingelheim |
| Ceva Santé Animale |
| Virbac |
| IDEXX Laboratories, Inc. |
| Bayer AG |
| Dechra Pharmaceuticals |
| Others |
Cost & Logistics Intelligence
Undercapacity in advanced biologics manufacturing drives supplier behavior and pricing posture for companion animal therapies. This utilization constraint influences investment decisions and market access strategies across developed nations.
Pricing Analysis
Configured-to-order pricing for specialized monoclonal antibody treatments contrasts with standard per-unit transactional models for vaccines. Brand premium and regulatory approval status serve as key differentiation drivers across the market. Pricing pressure stems from pet owner out-of-pocket expenses for advanced care, particularly in regions with lower pet insurance penetration. Pet owners seeking routine care exhibit high price sensitivity, while those with chronically ill pets show lower sensitivity for life-extending therapies.
Supply Chain Analysis
Export-control regimes limiting specific pharmaceutical precursors impact the companion animal healthcare supply chain. Geographic supply concentration for active pharmaceutical ingredients (APIs) in countries like China and India creates significant dependencies. Key raw material dependencies include specialized enzymes for biologics and excipients for oral medications. Single-source vulnerability for these critical inputs poses a structural risk. Downstream distribution primarily runs through established veterinary wholesalers and increasingly, direct-to-clinic corporate networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers a strong service-attach opportunity, as ongoing chronic disease management and wellness programs are expanding faster than initial product sales.
For Market Incumbents: Pre-empt emerging digital health platforms by investing in proprietary telemedicine solutions and data integration capabilities. Consolidate market share through strategic acquisitions of smaller, innovative diagnostic companies to counter the threat of fragmented data insights. Leverage extensive R&D pipelines in next-generation parasiticides to maintain a competitive edge against generic entrants. Certification investment in advanced manufacturing facilities in the United States reinforces supply chain resilience.
For New Entrants and Emerging Players: Pursue underpenetrated geographic markets like Brazil and Mexico by localizing product portfolios for cost-sensitive pet owners. Target the rapidly growing pet insurance segment with value-based product bundles for chronic conditions, offering a clear go-to-market angle. Focus on niche therapeutic areas, such as microbiome-based diagnostics, where established players have not yet fully invested. The rural veterinary clinic segment presents a penetrable opportunity for novel, cost-effective solutions.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among companies offering subscription-based wellness plans and chronic disease management platforms. Long-term viability depends on organizations capable of navigating stringent regulatory pathways while delivering high-value, outcome-based therapies. Acquisition targets should include specialist firms developing advanced diagnostics and biologics with strong intellectual property. The signal to watch is the expansion of pet insurance penetration, indicating increased willingness to pay for premium care.
| Strategic Initiative | Industry Significance |
|---|---|
| Pipeline Diversification into Biologics | Expands treatment options for chronic pet conditions, meeting rising owner expectations for advanced care. |
| Digital Health Platform Integration | Enhances remote consultation capabilities, improving market access and pet owner convenience. |
| Targeted M&A of Diagnostic Specialists | Strengthens in-house capabilities for personalized medicine and early disease detection in pets. |
| Investment in API Manufacturing Redundancy | Mitigates supply chain risks from geopolitical disruptions and single-source dependencies for key inputs. |
| Geographic Expansion into Emerging Economies | Captures new demand from growing pet populations in markets with lower penetration of advanced care. |
Research Approach
Operator-level perspectives from veterinary practitioners, clinic managers, pharmaceutical R&D scientists, and regulatory experts anchored the qualitative base for this analysis. Primary interviews were combined with extensive secondary validation from sources including FDA filings, EMA submissions, veterinary journal articles, and industry association reports. This approach facilitated both bottom-up and top-down triangulation of market insights.
Scenario-bracketing informed the analytical framework, projecting market trajectories across the analysis window under varying economic and regulatory conditions. Segmentation dimensions modeled included product type, therapy area, end user, delivery mode, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends and projected adoption rates, with pet ownership rates and chronic disease prevalence serving as key forecast inputs.
Sensitivities concentrate around shifts in pet owner spending patterns, unforeseen regulatory changes, and major disruptions in active pharmaceutical ingredient supply. Forecasts reflect assumptions documented through expert consensus and historical performance. Material shifts in economic stability or geopolitical factors would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Animal Health
Canine Influenza Treatment Market
Animal Health
Global Poultry Healthcare Market
Animal Health
Canada Animal Health Care Market
Animal Health
Equine Healthcare Market
Animal Health
Artificial Intelligence (AI) in Animal Health Market
Animal Health
Companion Animal Medicine Market
Animal Health
Animal Health Market
Animal Health
Companion Animal Ear Infection Treatment Market
Animal Health
African Horse Sickness Treatment Market
Animal Health
Cattle Healthcare Market
Animal Health
Animal Blood Plasma Products and Derivatives Market
Animal Health
Swine Healthcare Market
Animal Health
Zoonotic Disease Treatment Market
Animal Health
Global Farm Animal Healthcare Market
Animal Health
Duck Medicine and Vaccines Market
Animal Health
Animal Healthcare Market