
 Equine Healthcare Market | 2026-2036
Equine Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Equine Healthcare Market Intelligence
The gap between premium performance medicine and commodity-grade equine care is restructuring procurement patterns across the industry. Zoetis leverages its dominance in vaccines and parasiticides to anchor high-value contracts with large racing stables. Boehringer Ingelheim International GmbH sustains R&D intensity in respiratory and metabolic disease portfolios. Dechra Pharmaceuticals PLC specializes in niche therapeutic areas including ophthalmology and endocrinology, differentiating its position from volume-driven competitors.
Equine healthcare encompasses the medical, surgical, diagnostic, and nutritional management of horses across competitive sport, breeding, working, and companion roles; core technical specifications include titer-based vaccination protocols, pharmacokinetic profiles tailored to equine metabolism, and imaging modalities calibrated for 450–550 kg body mass. Veterinary drugs command the largest revenue pool due to recurring prescription patterns in chronic conditions, while diagnostic equipment represents the fastest-expanding segment as point-of-care ultrasound and digital radiography displace referral-only imaging. Nutritional supplements capture concentrated margin pools in performance and geriatric segments where owners demonstrate low price elasticity.
The US FDA Center for Veterinary Medicine and USDA APHIS regulate biologic approval and interstate movement, creating compliance barriers that favor established manufacturers with dedicated regulatory affairs infrastructure. The EU's EMA and national competent authorities enforce pharmacovigilance and MDR-aligned device standards that shape product development priorities for European market entry. Stakeholders must monitor evolving antimicrobial stewardship mandates and gene therapy regulatory frameworks to anticipate shifts in permissible therapeutic modalities and reimbursement conditions.
Market Dynamics
The US FDA Center for Veterinary Medicine and USDA APHIS are tightening antimicrobial stewardship mandates for equine pharmaceuticals, forcing manufacturers to reformulate product portfolios and racing stables to adopt diagnostic-driven treatment protocols that reduce prophylactic drug use.
Growth Catalysts
- Kentucky's Bluegrass concentration:Dense breeding and racing operations in this region sustain premium-tier veterinary service consumption and anchor demand for advanced imaging and preventive care protocols.
- EMA pharmacovigilance alignment:European regulatory harmonization creates streamlined pathways for biologic approvals, encouraging R&D investment in gene therapy and novel vaccine platforms.
- Point-of-care ultrasound diffusion:Portable imaging systems are displacing referral-only diagnostics, enabling immediate injury assessment at training facilities and competition venues.
Market Restraints
- Veterinarian supply constraint:Accredited equine specialists concentrate in racing hubs, leaving rural and recreational markets underserved and forcing owners toward telemedicine substitutes.
- Biologic cold chain fragility:Temperature-sensitive vaccines and regenerative therapies require specialized logistics infrastructure that fragments distribution economics outside metropolitan corridors.
- Antimicrobial resistance surveillance:Mandatory reporting to FDA CVM and state veterinary boards extends compliance timelines and elevates documentation burdens for practitioners.
Strategic Opportunities
- Geriatric companion horse segment:Aging recreational horse populations in Germany and France generate underexploited demand for chronic disease management and nutritional therapeutics.
- Telemedicine platform integration:Remote consultation tools paired with wearable biometric monitors create new service revenue streams for practices serving dispersed ownership bases.
- Gene therapy regulatory tailwind:USDA APHIS guidance on veterinary biologics is clarifying approval pathways for CRISPR-based treatments targeting hereditary conditions in Thoroughbred lines.
Industry Challenges
- Imaging technician certification bottlenecks:Specialized training for equine musculoskeletal ultrasound interpretation limits deployment speed of point-of-care systems.
- Legacy practice management software:Veterinary clinics struggle to integrate diagnostic device data streams with existing electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Equine Healthcare Market |
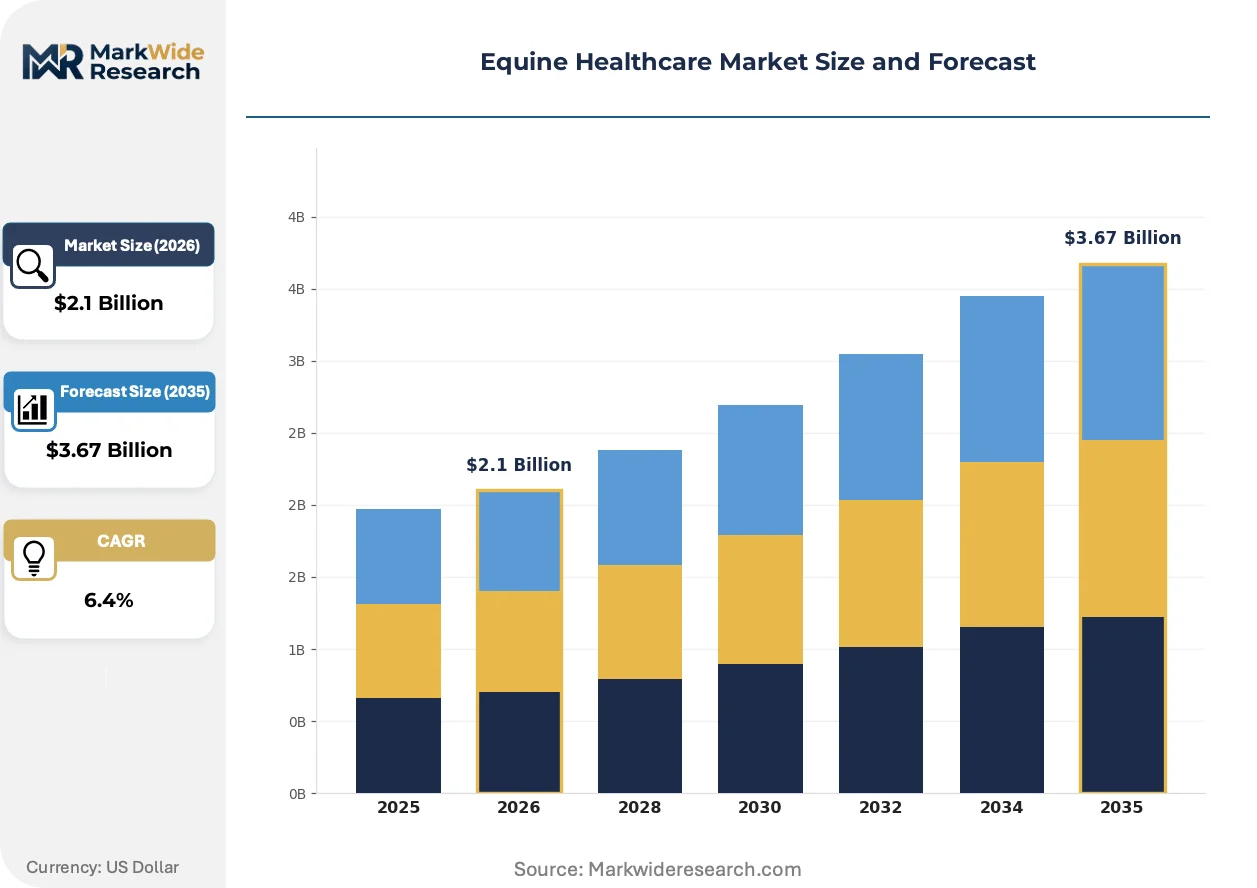
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
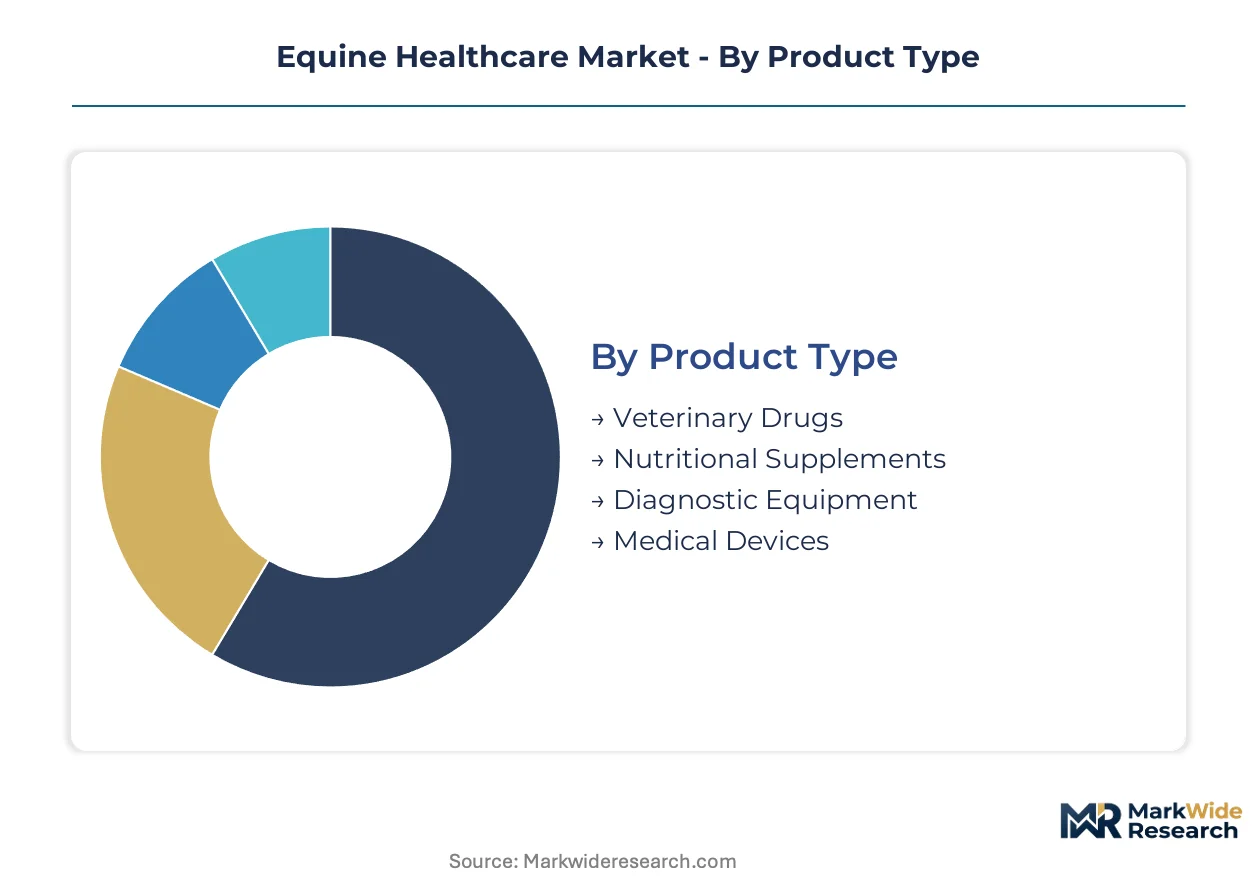
| Segmentation | Product Type: Veterinary Drugs, Nutritional Supplements, Diagnostic Equipment, Medical Devices Therapy Area: Infectious Diseases, Reproductive Health, Pain Management, Vaccination End User: Veterinary Clinics, Horse Owners, Research Institutions, Animal Hospitals Application: Preventive Care, Emergency Care, Routine Check-ups, Rehabilitation |
| Companies Covered | Zoetis, Boehringer Ingelheim International GmbH, Dechra Pharmaceuticals PLC, Merck & Co., Inc., Ceva, Vetoquinol S.A., IDEXX Laboratories, Inc., ESAOTE SPA, Elanco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Equine Healthcare Market Strategic Shifts & Innovations
Digital diagnostic platforms and regenerative medicine modalities are compressing treatment timelines and reshaping how racing stables and breeding operations allocate veterinary budgets across preventive and reactive care categories.
Artificial intelligence-powered radiographic interpretation is electrifying diagnostic workflows in equine sports medicine. Leading Thoroughbred training centers in Kentucky and California are deploying machine learning algorithms that flag subtle bone lesions within minutes of image capture. This compression of diagnostic latency is enabling same-day treatment decisions that previously required 48-hour specialist turnaround.
The EU's MDR-aligned device standards are elevating certification requirements for equine diagnostic equipment entering European markets. Manufacturers must now demonstrate clinical validation across diverse breeds and performance categories, extending product development cycles by 12–18 months. German and French veterinary distributors are prioritizing suppliers with established MDR technical documentation to minimize import friction.
Subscription-based preventive care packages are displacing fee-for-service billing in high-value racing stables. Kentucky-based operations now contract annual diagnostics, vaccination, and emergency response coverage through unified service agreements. This bundling concentrates purchasing authority with head veterinarians and compresses vendor margins on individual product categories while locking in multi-year supply relationships.
Equine Healthcare Market Segmentation
Equine healthcare procurement patterns diver sharply across product categories, therapy areas, and end-user settings. Understanding these fault lines reveals where premium pricing power concentrates and which segments face commoditization pressure.
Product Type:
Cost tier separates recurring prescription revenue from capital-intensive equipment sales and discretionary supplement purchases.
- Veterinary Drugs:Formulations span antimicrobials, anti-inflammatories, and metabolic therapeutics with pharmacokinetic profiles calibrated for equine hepatic metabolism. Kentucky racing stables and German breeding operations drive concentrated demand for prescription renewals in chronic conditions like equine metabolic syndrome and osteoarthritis.
- Nutritional Supplements:Targeted formulations address joint health, gastric ulcer prevention, and electrolyte replacement with bioavailability-optimized delivery systems. Performance horse owners in California and Florida demonstrate low price elasticity for premium-tier products endorsed by veterinary specialists.
- Diagnostic Equipment:Portable ultrasound and digital radiography systems enable point-of-care musculoskeletal assessment.
- Medical Devices:Surgical instruments, wound care systems, and regenerative therapy delivery platforms support intervention procedures.
Volume sits with veterinary drugs; growth tilts toward diagnostic equipment.
Therapy Area:
Application urgency shapes margin structures across acute intervention versus scheduled preventive protocols.
- Infectious Diseases:Antimicrobial and antiviral therapeutics target bacterial respiratory infections, viral neurologic conditions, and parasitic burdens with resistance-monitoring protocols mandated by FDA CVM. Racing jurisdictions in Kentucky and Louisiana require documented treatment records that elevate compliance costs for stable operations.
- Vaccination:Titer-based protocols for equine influenza, herpesvirus, and West Nile virus anchor preventive care schedules. USDA APHIS interstate movement regulations sustain mandatory vaccination demand across competitive and breeding populations.
- Reproductive Health:Fertility management, artificial insemination support, and neonatal intensive care serve breeding farm economics.
- Pain Management:NSAIDs, opioids, and local anesthetics address acute trauma and chronic degenerative conditions under tightening stewardship oversight.
Revenue concentrates in infectious disease therapeutics; vaccination protocols are expanding most quickly as regulatory compliance tightens.
End User:
Customer sophistication determines service bundling preferences and technology adoption thresholds.
- Veterinary Clinics:Full-service practices combine diagnostic, surgical, and pharmacy capabilities with ambulatory emergency response. Kentucky's Bluegrass region supports premium-tier clinic networks with dedicated equine specialists and advanced imaging infrastructure.
- Horse Owners:Individual and small-group ownership spans recreational riders, amateur competitors, and investment syndicates with divergent spending willingness. Telemedicine platforms are penetrating this dispersed base in rural France and Germany where specialist access remains limited.
- Animal Hospitals:Referral centers concentrate complex surgical and intensive care capacity.
- Research Institutions:Universities and pharmaceutical development facilities drive demand for experimental therapeutics and controlled study populations.
Transaction volume flows through veterinary clinics; technology adoption rates climb fastest among horse owners leveraging remote consultation tools.
Application:
Service delivery timing dictates staffing models and equipment utilization patterns across the care continuum.
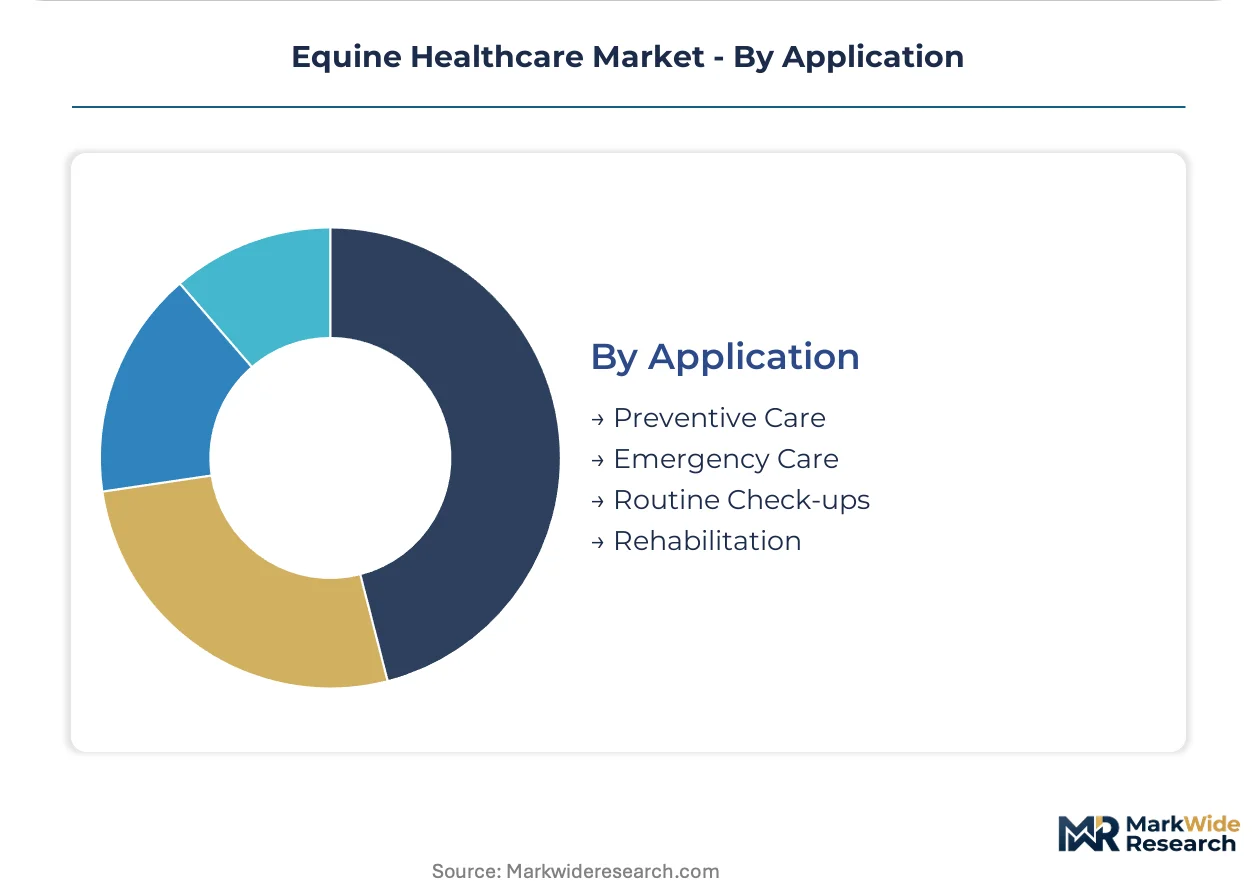
- Preventive Care:Scheduled vaccination, dental prophylaxis, and wellness screening programs generate recurring revenue streams with predictable cash flow. Subscription-based annual contracts are displacing fee-for-service billing in Kentucky racing stables.
- Emergency Care:Colic surgery, laceration repair, and acute neurologic intervention demand 24-hour specialist availability with high fixed-cost infrastructure. California training centers sustain dedicated emergency response teams with on-site surgical capability.
- Routine Check-ups:Lameness evaluation, pre-purchase examinations, and regulatory health certificates support commerce and competition entry.
- Rehabilitation:Post-surgical recovery, injury convalescence, and performance conditioning programs extend treatment timelines.
Emergency care commands premium pricing; preventive care packages are gaining share fastest as purchasing authority concentrates with head veterinarians.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kentucky's Bluegrass region anchors concentrated equine healthcare demand through dense Thoroughbred breeding and racing operations. This cluster sustains premium-tier veterinary service consumption and anchors procurement patterns for advanced diagnostic imaging and preventive vaccination protocols across the industry.
United States
The Kentucky Bluegrass and California training corridors drive concentrated demand for point-of-care ultrasound and digital radiography systems. FDA Center for Veterinary Medicine and USDA APHIS regulate biologic approvals and interstate movement, creating compliance infrastructure that favors established manufacturers. Florida's Ocala breeding district sustains high-margin preventive care contract adoption among performance horse operations.
Germany
Aging recreational horse populations in Lower Saxony and Bavaria generate expanding demand for chronic disease management and geriatric nutritional therapeutics. EMA pharmacovigilance alignment with national competent authorities enforces MDR-aligned device standards that shape product development priorities. The Baden-Württemberg veterinary distributor network prioritizes suppliers with established technical documentation to minimize import friction.
France
Normandy's breeding heartland and the Parisian equestrian periphery sustain premium-tier service consumption with low price elasticity for endorsed nutritional supplements. ANSM enforces pharmacovigilance reporting that extends compliance timelines for antimicrobial use. Telemedicine platforms penetrate dispersed rural ownership bases where specialist veterinary access remains limited.
United Kingdom
Newmarket's racing concentration and the Home Counties recreational belt anchor demand for emergency surgical capacity and lameness evaluation services. The Veterinary Medicines Directorate enforces antimicrobial stewardship mandates that reshape procurement toward diagnostic-driven treatment protocols. Scottish and Welsh rural markets remain underserved, accelerating telemedicine substitution for specialist consultation.
Japan
Hokkaido's breeding operations and the Tokyo metropolitan racing circuit sustain demand for advanced reproductive health services and neonatal intensive care. PMDA and METI frameworks regulate veterinary pharmaceutical approvals with emphasis on pharmacokinetic profiles calibrated for equine metabolism. The Kansai region's veterinary clinic networks are adopting portable imaging systems to displace referral-only diagnostic workflows.
Equine Healthcare Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the equine healthcare landscape, with pharmaceutical incumbents bearing R&D and regulatory infrastructure costs while diagnostic equipment specialists outsource manufacturing to contract fabricators. The market structure tilts toward consolidation in vaccines and parasiticides, where recurring prescription patterns and USDA APHIS registration barriers protect incumbent positions, while fragmentation persists in nutritional supplements and point-of-care devices. Three archetypes dominate: diversified animal health conglomerates with dedicated equine divisions, mid-cap specialists concentrated in ophthalmology or endocrinology, and regional distributors with regulatory affairs capabilities. Competitive moves center on portfolio diversification into gene therapy platforms and strategic partnerships to secure MDR-aligned device certification for European market entry.
Among diversified animal health conglomerates, Zoetis and Boehringer Ingelheim International GmbH exemplify the scale-driven archetype with established USDA APHIS registration infrastructure and high-value contract anchoring with large racing stables. Dechra Pharmaceuticals PLC occupies a specialist position within the mid-cap tier, differentiating through niche therapeutic concentration rather than volume-driven portfolio breadth. These three entities represent the competitive spectrum from broad-based vaccine and parasiticide dominance through targeted R&D intensity in metabolic and respiratory disease portfolios.
| Leading Market Players |
|---|
| Zoetis |
| Boehringer Ingelheim International GmbH |
| Dechra Pharmaceuticals PLC |
| Merck & Co., Inc. |
| Ceva |
| Vetoquinol S.A. |
| IDEXX Laboratories, Inc. |
| ESAOTE SPA |
| Elanco |
| Others |
Cost & Logistics Intelligence
Backward integration into vaccine manufacturing by Zoetis and Boehringer Ingelheim anchors both supply security and pricing power for premium-tier biologics, while contract fabrication of diagnostic equipment fragments margin capture among portable ultrasound specialists. This structural split concentrates margin pools in USDA-registered biologics while commoditizing point-of-care hardware.
Pricing Analysis
Outcome-based pricing for regenerative therapies and subscription bundling for preventive care packages anchor the dominant pricing structures, with Kentucky racing stables contracting annual diagnostics and emergency coverage through unified service agreements. Price differentiation stems from USDA APHIS registration tier and after-sales veterinary specialist endorsement, with antimicrobial stewardship mandates compressing margins on legacy pharmaceutical formulations. Cost pressure runs through commodity-grade nutritional supplements as direct-to-consumer channels proliferate. Performance horse owners in California and Florida demonstrate lowest price sensitivity, while recreational owners in rural Germany and France exhibit highest elasticity.
Supply Chain Analysis
Freight cost sensitivity for temperature-sensitive biologics fragments distribution economics outside metropolitan corridors, elevating landed costs for regenerative therapies and mRNA vaccines in dispersed markets. Manufacturing concentrates in the United States, Germany, and Ireland for pharmaceutical active ingredients, while diagnostic equipment assembly draws from China, South Korea, and Taiwan. Critical dependencies include equine-specific cell culture media, sterile injection components, and rare-earth elements for imaging sensors. Single-source vulnerability in cold-chain logistics creates exposure to capacity constraints. Distribution runs through veterinary distributor networks with regulatory affairs capabilities in each national market.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point-of-care ultrasound and AI-powered radiographic interpretation are displacing referral-only diagnostic workflows, compressing treatment timelines and restructuring how veterinary budgets allocate across preventive and reactive care categories.
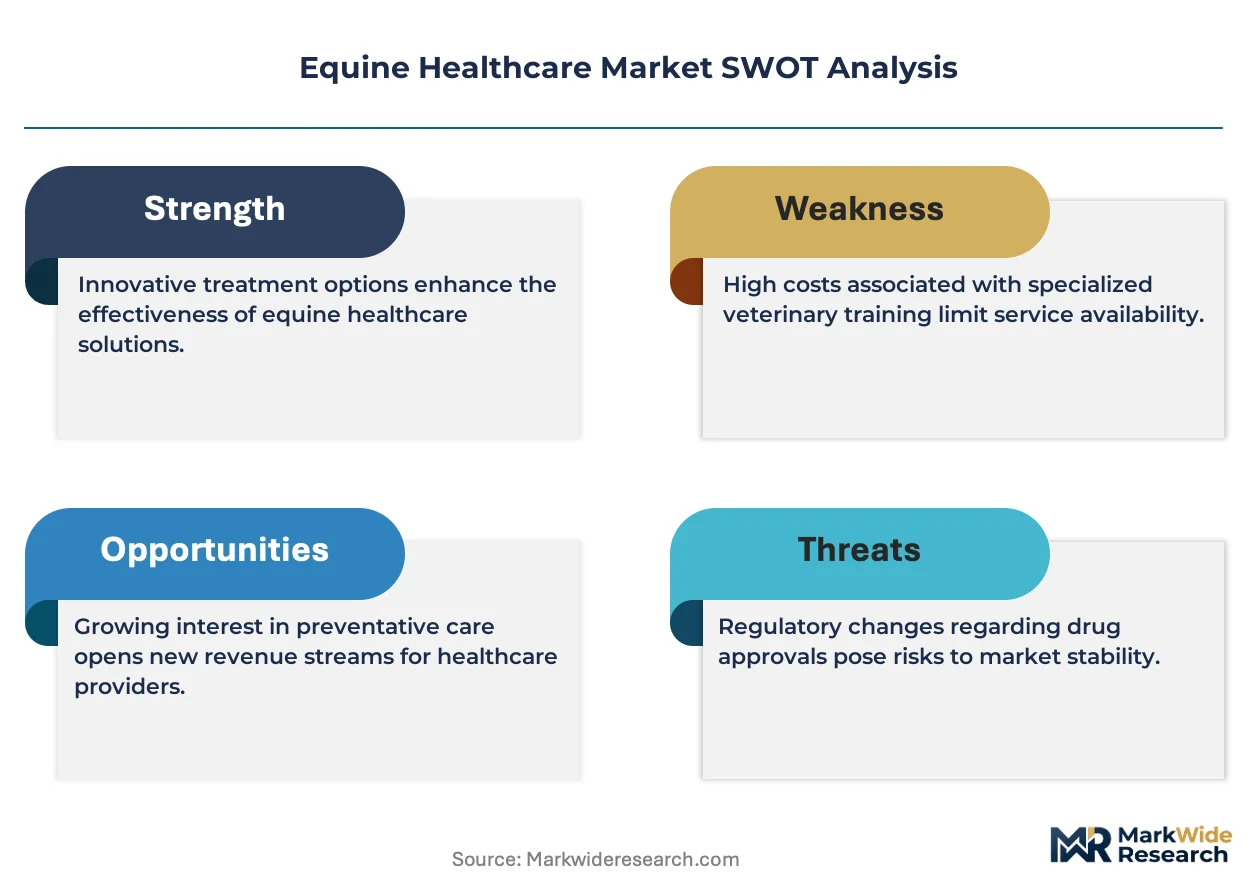
For Market Incumbents: To counter telemedicine platform substitution in dispersed rural markets, anchor high-value contracts with head veterinarians at Kentucky and California racing stables through multi-year preventive care bundles, and deepen backward integration into gene therapy manufacturing to capture regulatory tailwinds from USDA APHIS biologic guidance. For New Entrants and Emerging Players: Launch via telemedicine platform partnerships targeting aging recreational horse populations in Lower Saxony and Normandy where specialist veterinary access remains limited, with portable imaging system distribution as the primary go-to-market angle for penetrating underserved rural ownership bases. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified animal health conglomerates seeking gene therapy platform capabilities, with long-term viability favoring mid-cap specialists with established MDR-aligned device certification and USDA APHIS registration infrastructure. Watch for antimicrobial stewardship mandate acceleration as the inflection signal for portfolio rebalancing toward diagnostic-driven treatment protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Platform Development | USDA APHIS guidance on veterinary biologics clarifies approval pathways for CRISPR-based treatments targeting hereditary Thoroughbred conditions. |
| MDR-Aligned Device Certification | EMA pharmacovigilance alignment extends product development cycles but minimizes import friction for German and French distributor networks. |
| Telemedicine Platform Integration | Wearable biometric monitors paired with remote consultation tools create service revenue streams for practices serving dispersed French and German ownership bases. |
| Preventive Care Subscription Bundling | Annual contracts for diagnostics, vaccination, and emergency response concentrate purchasing authority with Kentucky head veterinarians. |
| Cold Chain Logistics Infrastructure | Temperature-sensitive vaccine and regenerative therapy distribution requires specialized capacity that fragments economics outside metropolitan corridors. |
Research Approach
Multi-period observation of antimicrobial stewardship mandate implementation, point-of-care imaging adoption rates, and preventive care contract penetration anchored the trend analysis, supplemented by interviews with equine veterinary specialists, racing stable operations managers, pharmaceutical regulatory affairs directors, diagnostic equipment procurement leads, and nutritional supplement brand managers. Secondary validation drew from FDA Center for Veterinary Medicine filings, USDA APHIS biologic registration databases, EMA pharmacovigilance reports, and European MDR technical documentation repositories. Bottom-up segment sizing triangulated against top-down market aggregation.
Input-output matrices mapped veterinary drug prescription volumes, diagnostic equipment unit shipments, and nutritional supplement revenue flows across product type, therapy area, end user, and application dimensions throughout the forecast period. CAGRs derived from regression analysis of historical adoption curves adjusted for regulatory inflection points. Industry-specific forecast inputs included Thoroughbred foal crop registrations, racing jurisdiction medication rule changes, and MDR implementation timelines.
Antimicrobial resistance surveillance expansion, gene therapy regulatory framework evolution, and telemedicine reimbursement policy shifts are the dominant revision risks that could alter trajectory assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Animal Health
US Companion Animal Health Market
Animal Health
Zoonotic Disease Treatment Market
Animal Health
Global Farm Animal Healthcare Market
Animal Health
Canine Arthritis Treatment Market
Animal Health
Global Companion Animal Health Market
Animal Health
Canine Influenza Treatment Market
Animal Health
China Companion Animal Health Market
Animal Health
Equine Fluid Therapy Market
Animal Health
Canada Animal Health Care Market
Animal Health
Cattle Healthcare Market
Animal Health
Cattle Health Market
Animal Health
African Horse Sickness Treatment Market
Animal Health
Swine Health Market
Animal Health
Animal Health Software Market
Animal Health
US Military Animals Market
Animal Health
Companion Animal Medicine Market