
 Canine Mammary Tumor Treatment Market | 2026-2036
Canine Mammary Tumor Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Canine Mammary Tumor Treatment Market Outlook
AAHA accreditation standards for oncology service capabilities is bifurcating the competitive landscape between full-service veterinary hospital networks and standalone general practices. Zoetis leverages its vertically integrated manufacturing of canine chemotherapy agents to sustain supply security across North American distribution channels. Boehringer Ingelheim anchors its position through deep relationships with veterinary teaching hospitals, while Virbac differentiates via specialized oncology portfolios tailored to European regulatory requirements.
Canine mammary tumor treatment encompasses surgical excision, systemic chemotherapy, radiation therapy, and emerging immunological interventions targeting malignant epithelial neoplasms of the mammary gland, with treatment selection governed by tumor staging, histological grading, and hormone receptor status. The primary purpose centers on extending disease-free survival and maintaining quality of life in intact and spayed female dogs. Surgery and chemotherapy together capture the dominant share of treatment protocols, though immunotherapy represents the fastest-expanding segment as monoclonal antibody platforms advance through clinical validation. Diagnostic Kits command concentrated margin pools where histopathology and molecular profiling guide therapeutic decision-making.
FDA Center for Veterinary Medicine, USDA APHIS, and state veterinary medical boards collectively govern drug approval, biologics oversight, and practice standards that determine which therapies achieve commercial accessibility. These frameworks create compliance thresholds that favor established pharmaceutical developers with dedicated regulatory affairs infrastructure. Stakeholders must monitor pipeline progression of conditional approval pathways for novel oncology agents, as these regulatory mechanisms will reshape competitive dynamics without reference to specific calendar milestones.
Market Dynamics
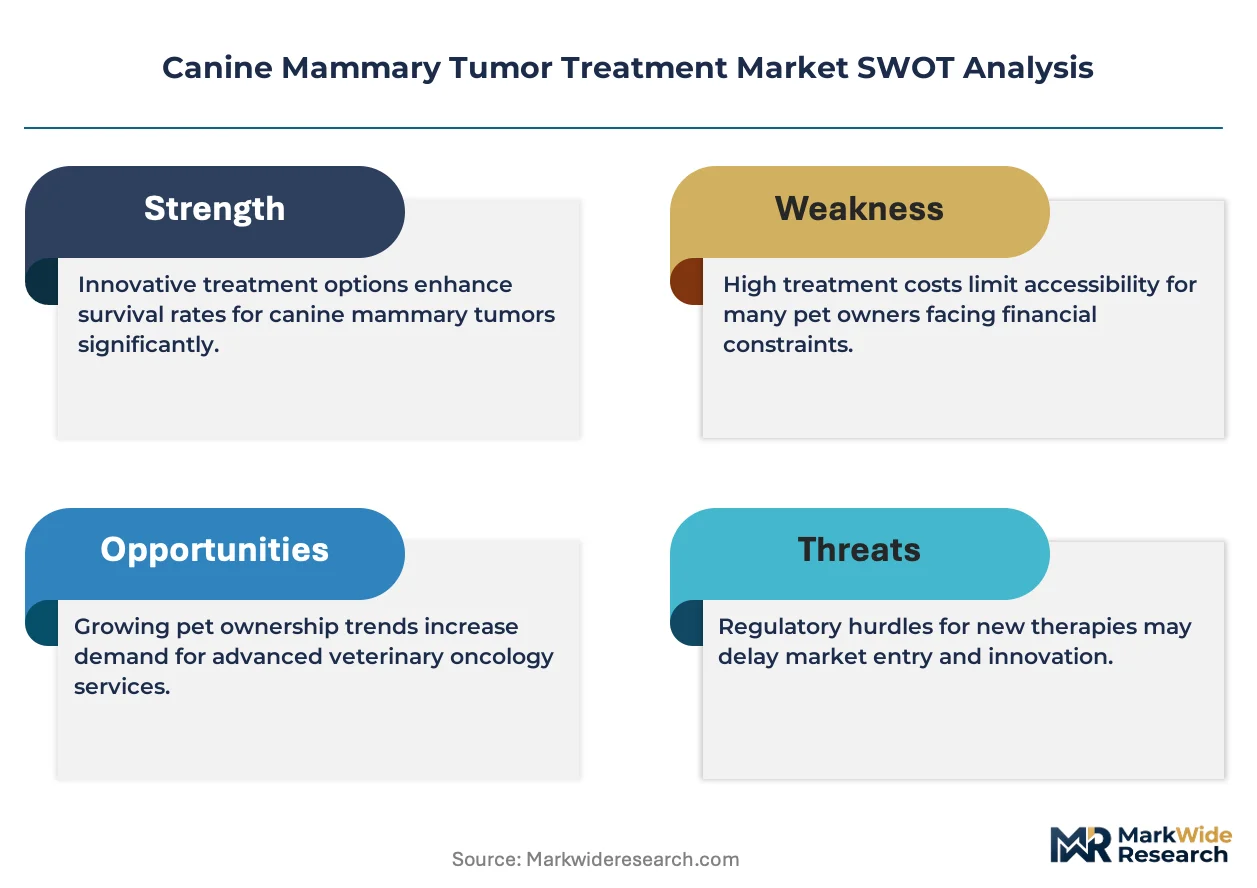
The central structural force in canine mammary tumor treatment is the concentration of advanced oncology capability within university-affiliated veterinary teaching hospitals, which is compressing referral patterns and marginalizing general practice competitors unable to meet AAHA accreditation thresholds for chemotherapy administration and radiation therapy protocols.
Growth Catalysts
- Pet Insurance Penetration:The United States has achieved substantial coverage density for companion animal health policies, which removes cost barriers for owners considering adjuvant chemotherapy and specialist surgical oncology interventions.
- FDA Center for Veterinary Medicine Conditional Approval Pathways:Accelerated regulatory mechanisms for novel oncology biologics are compressing development timelines and enabling earlier commercial access to monoclonal antibody platforms.
- Veterinary Specialist Referral Networks:Dense geographic coverage of board-certified veterinary oncologists in metropolitan clusters facilitates rapid case escalation from primary care to definitive treatment centers.
Market Restraints
- Chemotherapeutic Agent Supply Concentration:Manufacturing of canine-specific chemotherapy formulations concentrates among a limited cohort of pharmaceutical suppliers, creating vulnerability to batch shortages and distribution disruptions.
- Technical Limitation in Early Detection:Fine-needle aspiration cytology exhibits diagnostic ambiguity for distinguishing benign from malignant mammary masses, delaying definitive intervention and compressing therapeutic windows.
- Regulatory Friction from State Veterinary Medical Boards:Jurisdiction-specific restrictions on telemedicine consultations and prescription authority create compliance complexity for multi-state veterinary hospital networks.
Strategic Opportunities
- Liquid Biopsy Integration:Circulating tumor DNA assays are converging with traditional histopathology workflows to enable non-invasive monitoring of treatment response and minimal residual disease detection.
- Underpenetrated European Markets:France, Germany, and Italy exhibit lower specialist referral density relative to pet population, creating whitespace for accredited oncology service expansion.
- Outcome-Based Reimbursement Pilots:Pet insurance carriers are piloting episode-of-care payment models for oncologic surgery, aligning provider incentives with disease-free survival metrics rather than procedure volume.
Industry Challenges
- Veterinary Oncologist Workforce Scarcity:Residency training program capacity constrains board-certified specialist supply, creating recruitment bottlenecks for expanding hospital networks.
- Cold Chain Integrity for Biologics:Temperature-sensitive monoclonal antibody therapies require capital-intensive storage infrastructure that fragments distribution capability between academic centers and community practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canine Mammary Tumor Treatment Market |
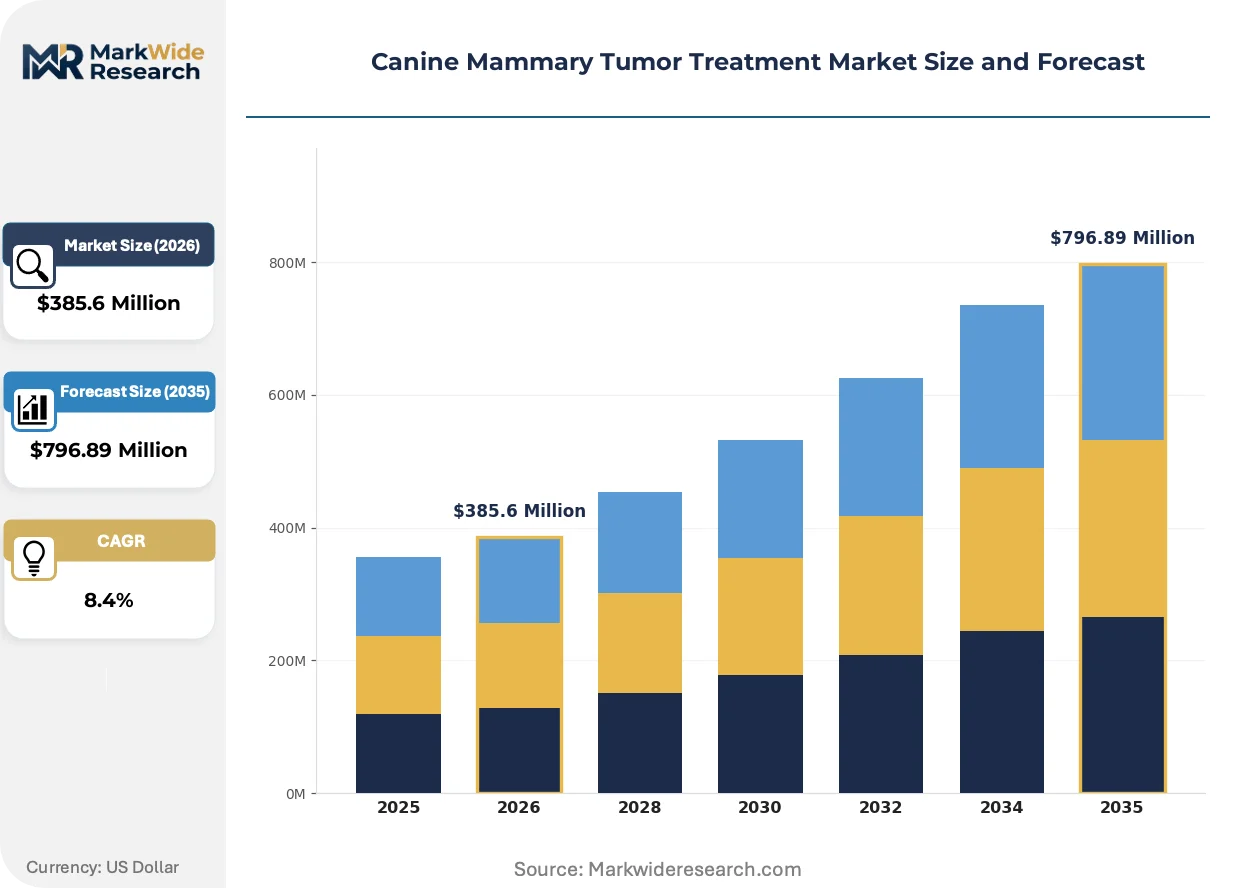
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Surgery, Chemotherapy, Radiation, Immunotherapy Product Type: Therapeutics, Surgical Instruments, Diagnostic Kits, Supportive Care Products End User: Veterinary Clinics, Animal Hospitals, Research Laboratories, Pet Owners Formulation: Injectables, Oral Tablets, Topical Solutions, Others |
| Companies Covered | Zoetis, Elanco Animal Health, Boehringer Ingelheim, AB Science, VetDC, Oasmia Pharmaceuticals AB, Virbac, Karyopharm Therapeutics, Aratana Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canine Mammary Tumor Treatment Market Strategic Shifts
Active transformation in canine mammary tumor treatment stems from the intersection of precision diagnostic platforms, adaptive regulatory frameworks, and evolving owner expectations for companion animal longevity.
Next-generation sequencing panels for canine mammary tumors are decomposing the historical reliance on histologic grade alone for prognostication. Veterinary oncologists at tertiary referral centers are adopting multi-gene profiling to stratify chemotherapy protocols by molecular subtype. This decomposition of staging methodology is compressing the market for empirical treatment selection and elevating margin capture for integrated diagnostic-therapeutic service lines.
REACH registration requirements for veterinary pharmaceuticals are tightening substance authorization timelines across European manufacturing operations. The European Chemicals Agency's expanded data demands for carcinogenicity and environmental fate assessments are extending pre-market dossier preparation. Small-molecule chemotherapy suppliers serving EU markets are responding by consolidating regulatory affairs functions and prioritizing existing actives over novel chemical entities.
Owner-initiated second-opinion consultations via telemedicine platforms are disrupting traditional referral channel economics. Digital pathology networks enable remote case review by boarded specialists, compressing geographic loyalty to individual hospital systems. This behavioral shift is most visible in the United States, where pet insurance pre-authorization workflows increasingly mandate specialist concurrence before high-cost intervention approval.
Canine Mammary Tumor Treatment Market Segmentation
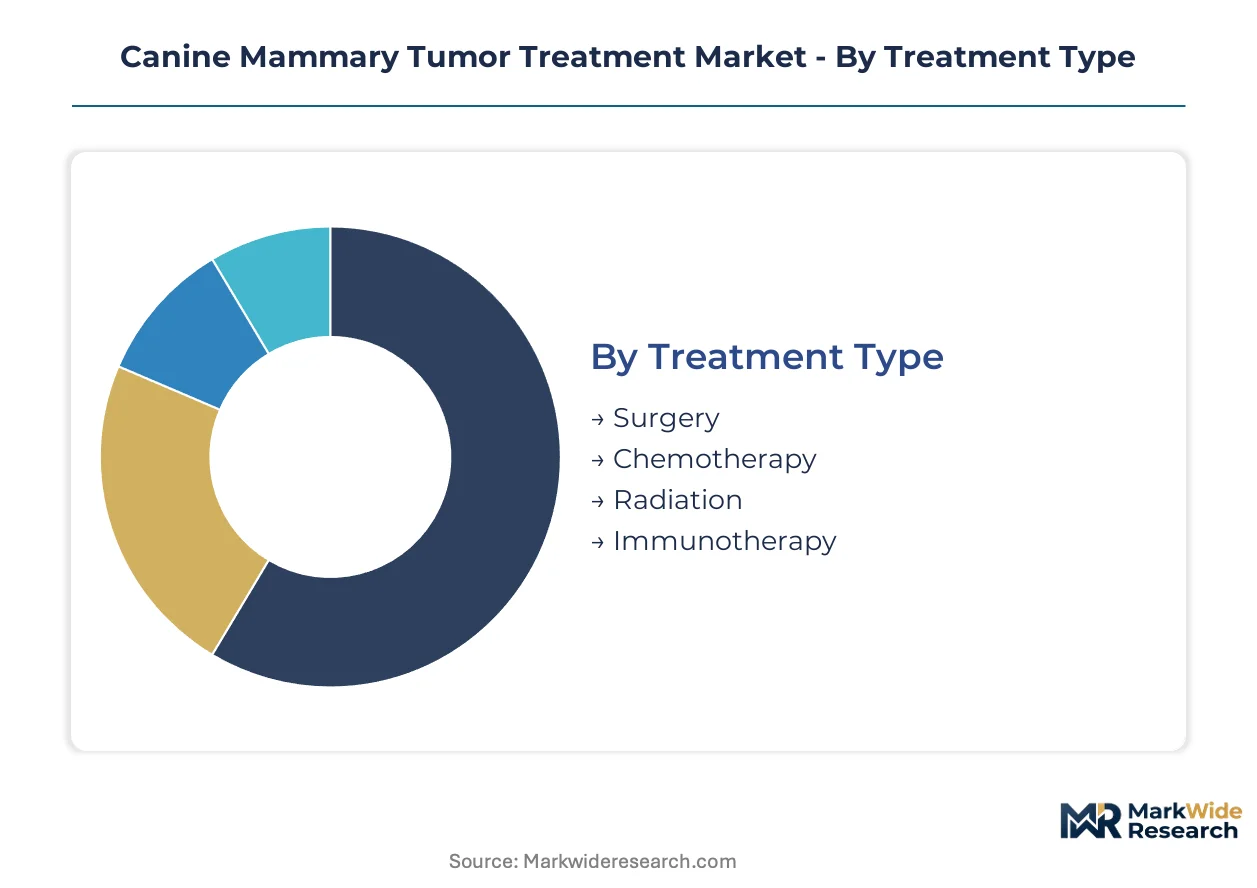
Treatment selection for canine mammary tumors follows distinct channel pathways, with surgical and chemotherapeutic interventions concentrating in tertiary referral centers while primary care settings manage early-stage diagnostics and post-operative monitoring. Channel mix dynamics determine margin capture and inventory requirements across the value chain.
Treatment Type:
Surgical oncology flows through university-affiliated teaching hospitals and AAHA-accredited specialty networks, while systemic therapies distribute through compounding pharmacies and hospital-based infusion centers.
- Surgery:Lumpectomy, mastectomy, and radical chain resection procedures require sterile surgical suites and board-certified veterinary surgeons. Demand clusters at Colorado State University, University of Pennsylvania, and UC Davis veterinary medical centers where complex reconstruction cases escalate from regional primary care networks.
- Chemotherapy:Adjuvant and neoadjuvant protocols employ carboplatin, doxorubicin, and vincristine formulations with established safety profiles in canine patients. Administration concentrates in facilities with chemotherapy biosafety infrastructure certified by state veterinary medical boards.
- Radiation:External beam and stereotactic protocols target residual microscopic disease post-surgery. Access remains geographically constrained to approximately 50 North American facilities with linear accelerator capability.
- Immunotherapy:Checkpoint inhibitors and monoclonal antibody platforms are advancing through conditional approval pathways at FDA Center for Veterinary Medicine. Clinical trial enrollment at Angell Animal Medical Center and Morris Animal Foundation sites is expanding access beyond academic centers.
Surgery dominates installed base. Immunotherapy is where expansion concentrates.
Product Type:
Cost tier stratification separates capital-intensive surgical platforms from consumable diagnostics and recurring pharmaceutical revenues.
- Therapeutics:Cytotoxic agents, hormonal therapies, and targeted small molecules constitute recurring revenue streams with formulary-dependent prescribing patterns. Boehringer Ingelheim and Zoetis control distribution through exclusive veterinary channel agreements.
- Surgical Instruments:Electrosurgical units, specialized mammary retractors, and thermal ablation devices require capital expenditure cycles tied to hospital expansion timelines.
- Diagnostic Kits:Histopathology staining panels, immunohistochemistry assays, and PCR-based molecular profiling command premium pricing where definitive diagnosis precedes treatment authorization. Antech Diagnostics and Idexx Laboratories maintain reference laboratory dominance.
- Supportive Care Products:Antiemetics, appetite stimulants, and wound management supplies generate repeat purchase velocity through veterinary e-commerce platforms.
Therapeutics capture volume share. Diagnostic Kits concentrate margin expansion.
End User:
Customer type determines service intensity, with specialist referral hospitals managing complex multimodal protocols while general practices handle screening and surveillance.
- Veterinary Clinics:Primary care settings conduct initial mass palpation, fine-needle aspiration, and owner education. These sites represent the entry point for 70% of cases before specialist referral.
- Animal Hospitals:Tertiary centers with boarded oncologists perform definitive staging, surgery, and chemotherapy administration. Accreditation by AAHA or ACVIM residency training status differentiates competitive positioning.
- Research Laboratories:Morris Animal Foundation, Flint Animal Cancer Center, and pharmaceutical contract research organizations conduct interventional trials generating data for regulatory submissions.
- Pet Owners:Direct-to-consumer telemedicine consultations and at-home palliative care products are expanding through Chewy, Figo, and other pet health platforms.
Animal Hospitals dominate case complexity. Veterinary Clinics anchor case volume.
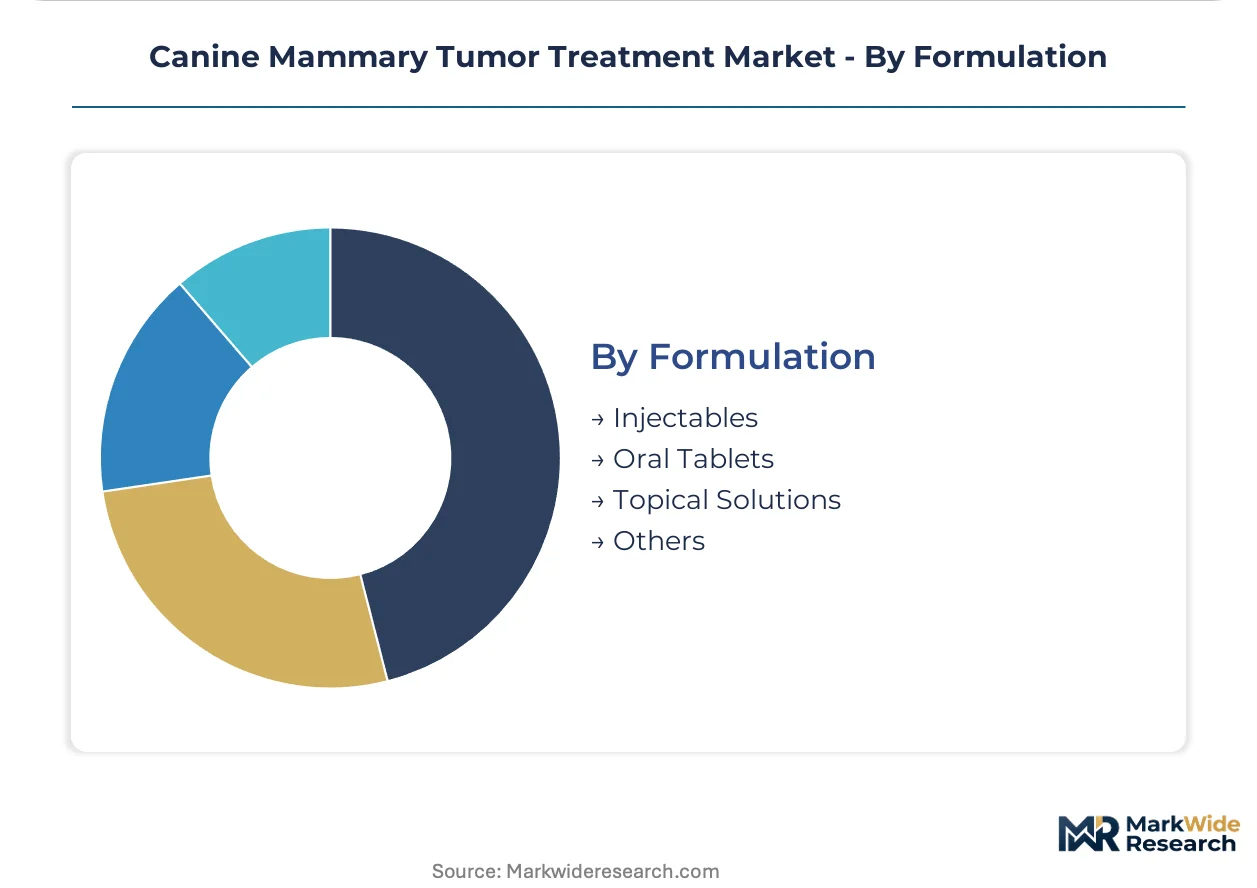
Formulation:
Supply concentration varies by delivery mechanism, with cold-chain biologics fragmenting distribution capability relative to stable small-molecule tablets.
- Injectables:Intravenous chemotherapy and subcutaneous biologics require compounding pharmacy relationships or in-house preparation under USP 797 guidelines. Temperature excursion risk limits community practice adoption.
- Oral Tablets:Palatable formulations of chlorambucil, cyclophosphamide, and toceranib phosphate enable owner-administered metronomic protocols with veterinary supervision.
- Topical Solutions:Wound care and transdermal drug delivery systems address localized treatment needs with lower technical barriers to administration.
- Others:Implantable depot formulations and intralesional therapies remain experimental with limited commercial availability.
Injectables dominate hospital revenue. Oral Tablets are gaining share fastest in home-care settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pet owners with comprehensive insurance coverage and established relationships with specialist referral networks drive treatment uptake in concentrated metropolitan clusters. Veterinary teaching hospitals anchor advanced oncology service delivery, while regulatory frameworks governing drug approval and practice standards shape commercial accessibility across jurisdictions.
United States
Board-certified veterinary oncologists cluster in metropolitan corridors linking Boston, New York, Philadelphia, and Washington DC, with satellite density in California's Bay Area and Southern California corridor. FDA Center for Veterinary Medicine conditional approval pathways for novel biologics accelerate commercial access to emerging monoclonal antibody platforms. Colorado State University's Flint Animal Cancer Center and the University of Pennsylvania's Ryan Veterinary Hospital anchor multimodal treatment protocols that draw referral cases from regional primary care networks across multiple states.
Germany
University veterinary faculties in Munich, Hannover, and Leipzig maintain dense specialist referral networks serving Central European pet populations with advanced surgical and chemotherapeutic capabilities. REACH registration requirements through the European Chemicals Agency extend dossier preparation timelines for novel veterinary pharmaceuticals, favoring established actives over new chemical entities. The Munich metropolitan area concentrates reference laboratory capacity where Antech Diagnostics and Idexx Laboratories process histopathology and molecular profiling for treatment stratification.
France
Paris and Lyon metropolitan areas host the primary concentration of ACVIM-certified oncologists, though specialist density remains lower relative to pet population than in North American markets. ANSM oversight of veterinary drug marketing authorizations aligns with centralized EU regulatory frameworks while maintaining national pharmacovigilance requirements. The Maisons-Alfort veterinary school and affiliated hospital networks in the Île-de-France region perform complex reconstructive surgeries that attract cross-border referral cases from Belgium and Switzerland.
United Kingdom
London's Royal Veterinary College and the University of Edinburgh's Hospital for Small Animals anchor specialist oncology services with radiation therapy capacity concentrated at fewer than ten facilities nationwide. The Veterinary Medicines Directorate operates within the UK regulatory framework post-EU transition, maintaining parallel approval processes with mutual recognition agreements. The Southeast England corridor linking London, Cambridge, and Bristol exhibits the highest pet insurance penetration rates in Europe, removing cost barriers for adjuvant chemotherapy protocols.
Japan
Metropolitan Tokyo and Osaka-Kobe corridors concentrate board-certified veterinary oncologists within university-affiliated hospitals and JAVMA-accredited specialty practices. PMDA veterinary drug approval pathways require domestic clinical trial data, extending timelines for novel oncology agents developed primarily in North American or European markets. The Hokkaido University Veterinary Teaching Hospital and Azabu University Veterinary Medical Center in Kanagawa Prefecture perform complex surgical oncology cases with molecular staging capabilities that guide chemotherapy selection.
Canine Mammary Tumor Treatment Market Competitive Environment
Player mix skews toward vertically integrated pharmaceutical developers with dedicated veterinary regulatory affairs infrastructure and established distribution through exclusive channel agreements. The competitive structure concentrates among multinational animal health divisions of human pharmaceutical conglomerates, with mid-tier specialists occupying niche therapeutic segments. Three archetypes dominate: integrated human-animal health conglomerates with captive manufacturing, pure-play veterinary pharmaceutical developers with conditional approval expertise, and reference laboratory networks with diagnostic-therapeutic bundling capability. M&A activity targets molecular diagnostics platforms and regional veterinary hospital networks, while portfolio diversification extends into companion animal oncology biologics.
Within the integrated pharmaceutical tier, Zoetis and Boehringer Ingelheim exemplify archetypes combining captive manufacturing of chemotherapy agents with deep relationships at veterinary teaching hospitals. Elanco Animal Health occupies a position bridging traditional pharmaceutical development with emerging biologics platforms. Among specialized developers, Virbac represents European regulatory specialization, while AB Science and VetDC sit within the conditional approval pathway segment targeting accelerated market entry for novel oncology mechanisms.
| Leading Market Players |
|---|
| Zoetis |
| Elanco Animal Health |
| Boehringer Ingelheim |
| AB Science |
| VetDC |
| Oasmia Pharmaceuticals AB |
| Virbac |
| Karyopharm Therapeutics |
| Aratana Therapeutics |
| Others |
Value Chain & Pricing Dynamics
Monoclonal antibody platforms substituting for conventional cytotoxic chemotherapy are redrawing supply geography toward North American biologics manufacturing while compressing pricing economics for small-molecule formulations. This substitution dynamic concentrates margin capture in cold-chain infrastructure holders and fragments pricing power among legacy chemotherapy suppliers.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient indexation dominate procurement between veterinary hospital networks and chemotherapy suppliers. Three-tier pricing structure across premium biologics, standard cytotoxics, and economy generics reflects ACVIM accreditation status and formulary tier placement. Pricing pressure stems from pet insurance pre-authorization workflows mandating generic substitution where clinically equivalent. General practice clinics exhibit highest price sensitivity due to limited pass-through capability, while university-affiliated teaching hospitals leverage volume commitment for preferential tier access.
Supply Chain Analysis
The United States and Germany anchor sterile injectable manufacturing for veterinary oncology actives, with India supplying API intermediates for oral metronomic protocols. Carboplatin and doxorubicin draw from platinum-group metal refiners in South Africa and anthracycline fermentation capacity in Italy. Single-source vulnerability concentrates in canine-specific formulation sites certified under FDA Center for Veterinary Medicine and EMA GMP standards. Distribution runs through exclusive veterinary channel agreements with Boehringer Ingelheim and Zoetis controlling hospital-direct fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against human-oncology biologics repurposed through conditional approval pathways, requiring portfolio repositioning toward companion-animal-specific mechanisms.
For Market Incumbents: Shield formulation exclusivity by deepening captive supply of cold-chain biologics through backward integration into North American fill-finish capacity. Accelerate conditional approval dossiers at FDA Center for Veterinary Medicine to preempt human-pharma entrants repurposing checkpoint inhibitors. Channel control through exclusive teaching hospital relationships remains the priority defensive lever against emerging pure-play biologics developers.
For New Entrants and Emerging Players: FDA Center for Veterinary Medicine conditional approval fast-tracks offer compressed regulatory timelines relative to full NADA pathways, enabling earlier revenue capture for novel monoclonal antibody platforms. Underpenetrated French and Italian specialist referral networks present whitespace for accredited oncology service partnerships. Go-to-market positioning through telemedicine-integrated diagnostic platforms addresses geographic oncologist scarcity.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed veterinary hospital networks consolidating regional referral patterns. Long-term viability hinges on molecular diagnostic-therapeutic bundling capability across the analysis window. Acquisition targets include reference laboratories with histopathology-automated staining integration. The signal to watch is pet insurance carrier formulary inclusion decisions for biologics versus cytotoxics.
| Strategic Initiative | Industry Significance |
|---|---|
| Conditional Approval Pathway Navigation | FDA Center for Veterinary Medicine accelerated mechanisms compress commercialization timelines for monoclonal antibody platforms. |
| Reference Laboratory Acquisition | Antech Diagnostics and Idexx Laboratories dominance in histopathology creates diagnostic-therapeutic bundling leverage. |
| Teaching Hospital Partnership Expansion | Colorado State University and University of Pennsylvania anchor referral networks that shape prescribing patterns. |
| Cold Chain Infrastructure Investment | Temperature-sensitive biologics require capital-intensive storage that fragments distribution between academic and community settings. |
| European Regulatory Affairs Consolidation | REACH registration requirements through ECHA favor established actives over novel chemical entities in EU markets. |
Study Parameters
A standing panel of veterinary oncologists, pharmaceutical regulatory affairs directors, pet insurance formulary managers, and reference laboratory operations executives provided ongoing calibration across primary interview waves. Secondary validation drew from FDA Center for Veterinary Medicine submission databases, EMA veterinary product registers, ACVIM residency program directories, and state veterinary medical board licensing records. Bottom-up case flow modeling at tertiary referral centers triangulated against top-down pharmaceutical shipment data from exclusive channel distributors.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include treatment modality, product category, end-user facility type, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating pet insurance penetration trajectories, specialist workforce expansion rates, and conditional approval pathway progression. Forecast inputs encompassed fine-needle aspiration cytology accuracy improvements and monoclonal antibody clinical trial enrollment velocity.
Decision-makers should treat outputs as directional under assumptions of stable FDA regulatory frameworks and continued pet insurance coverage expansion; material deviation in conditional approval timelines or workforce training capacity would warrant model refresh. Recalibration cycles align with material shifts in payer reimbursement policy and biologics manufacturing scale-up milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Animal Health
Canada Animal Health Care Market
Animal Health
Artificial Intelligence (AI) in Animal Health Market
Animal Health
Duck Medicine and Vaccines Market
Animal Health
Swine Health Market
Animal Health
Global Poultry Healthcare Market
Animal Health
Animal Health Market
Animal Health
Laboratory Animal Models Market
Animal Health
Animal Blood Plasma Products and Derivatives Market
Animal Health
Animal Healthcare Market
Animal Health
Cattle Health Market
Animal Health
US Military Animals Market
Animal Health
China Companion Animal Health Market
Animal Health
Swine Healthcare Market
Animal Health
Canine Arthritis Treatment Market
Animal Health
US Companion Animal Health Market
Animal Health
Zoonotic Disease Treatment Market