
 Animal Blood Plasma Products and Derivatives Market | 2026-2036
Animal Blood Plasma Products and Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Blood Plasma Products and Derivatives Market Intelligence
Veterinary hematology specialists is bifurcating the competitive landscape between plasma fractionators serving pharmaceutical-grade markets and commodity suppliers feeding nutrition applications. Grifols S.A. leverages its human plasma expertise to extend quality systems into animal-derived immunoglobulin production. CSL Limited anchors its position through captive bovine sourcing networks across Australia and New Zealand. Thermo Fisher Scientific Inc. competes by supplying diagnostic-grade plasma proteins to third-party assay developers.
Animal blood plasma products and derivatives comprise processed biological materials extracted through centrifugation and chromatographic separation of whole blood, yielding protein fractions with defined purity grades above 90% for immunoglobulin concentrates and albumin isolates. These materials function as growth-promoting feed additives, passive immunity transfer agents, and cell culture media supplements across veterinary and biopharmaceutical manufacturing chains. Spray-dried plasma dominates volume flows into swine and poultry nutrition, while plasma concentrates command premium positioning within veterinary therapeutics for neonatal calf and piglet scours prevention. Immunoglobulins represent the fastest-expanding product category as diagnostic laboratories adopt species-specific antibody reagents for pathogen detection panels.
FDA Center for Veterinary Medicine oversight of veterinary biologics and USDA Animal and Plant Health Inspection Service regulations on animal-derived ingredient traceability shape product registration pathways and interstate commerce requirements for US manufacturers. EMA veterinary medicines guidelines and EU feed hygiene regulations impose comparable batch-release and origin-documentation standards across European production facilities. Stakeholders must monitor evolving species-origin labeling mandates and alternative protein validation protocols that could redefine competitive qualification thresholds for plasma-derived inputs.
Market Dynamics
Antibiotic residue tightening across major protein-exporting nations is redirecting livestock producer procurement toward plasma-derived passive immunity solutions, compressing substitution timelines for ionophore growth promoters.
Growth Catalysts
- USDA traceability mandates:Federal origin-documentation requirements for animal-derived feed ingredients are consolidating supplier qualification pools toward fractionators with validated chain-of-custody systems.
- Neonatal scours prevention:Swine and cattle producers facing post-weaning mortality pressures are expanding immunoglobulin concentrate inclusion rates in colostrum replacer formulations.
- Cell culture media expansion:Biopharmaceutical manufacturers require serum-free alternatives, driving demand for recombinant protein production using plasma-derived growth factors.
Market Restraints
- Bovine raw material volatility:Abattoir consolidation in Brazil and Argentina concentrates slaughterhouse plasma supply under three dominant meatpacking groups.
- FDA veterinary biologics pathway friction:Immunoglobulin product licensing requires multi-year efficacy trials against specific pathogen strains, extending commercialization timelines.
- Plant-based protein substitution:Fermentation-derived antibodies from precision biotechnology platforms threaten premium positioning of animal-sourced immunoglobulins in diagnostic reagent applications.
Strategic Opportunities
- China diagnostic laboratory buildout:Provincial CDC network expansion creates concentrated demand for species-specific antibody panels in poultry and aquaculture pathogen detection.
- EU Green Deal protein transition incentives:Research funding for reduced-antibiotic livestock systems indirectly subsidizes plasma fractionation pilot facilities in Denmark and the Netherlands.
- Direct-to-producer digital channels:E-commerce platforms connecting fractionators with mid-sized swine operations bypass traditional feed distributor markups in North American markets.
Industry Challenges
- Fractionation biochemistry expertise scarcity:Chromatographic purification specialists command premium compensation, constraining capacity expansion at emerging market facilities.
- ISO 17025 diagnostic-grade certification timelines:Analytical validation protocols for immunoglobulin potency assays extend quality system implementation by 18-24 months.
- Cold chain integrity across emerging markets:Lyophilized plasma protein stability requirements clash with intermittent refrigeration infrastructure in Southeast Asian distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Blood Plasma Products and Derivatives Market |
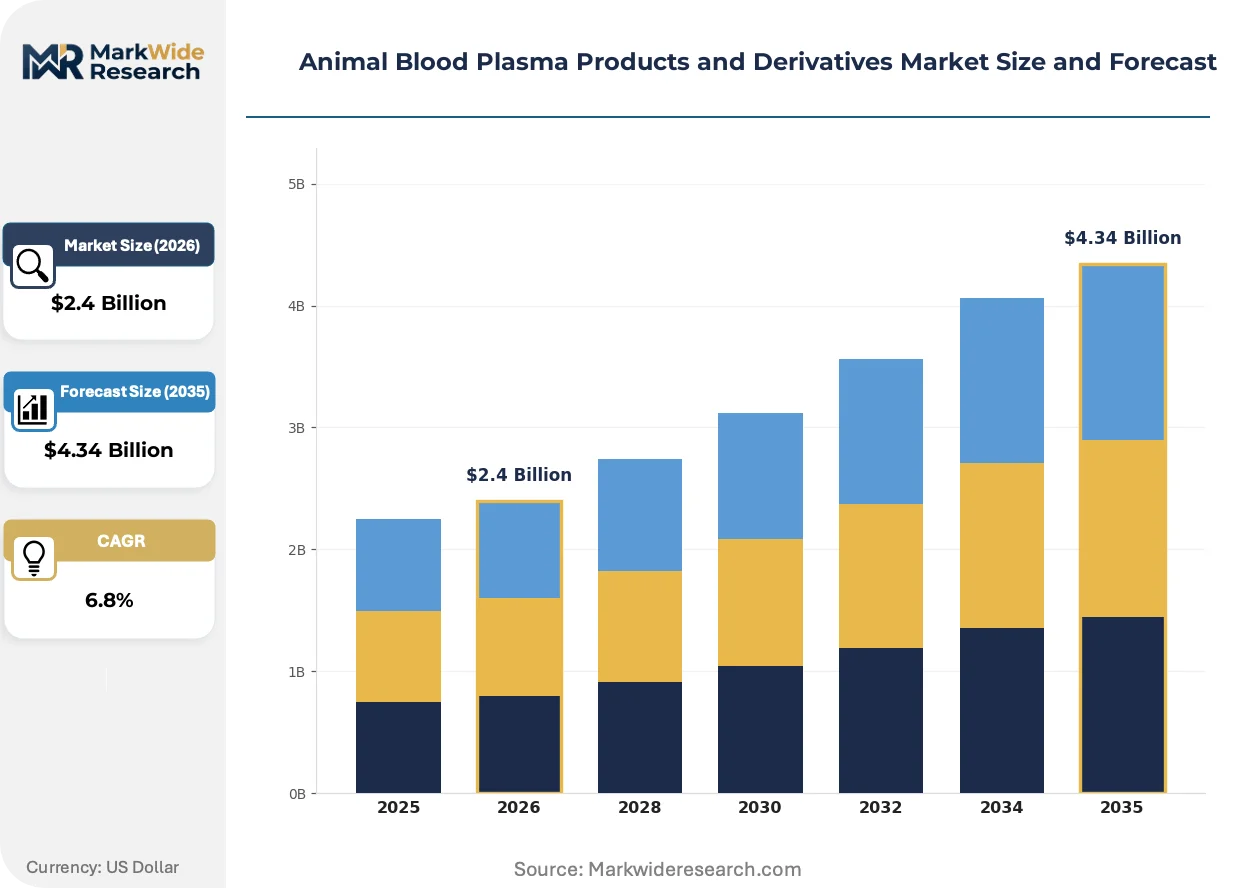
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray-Dried Plasma, Liquid Plasma, Plasma Concentrates, Immunoglobulins, Albumin Application: Feed Additives, Veterinary Therapeutics, Diagnostic Reagents, Nutritional Supplements, Biopharmaceuticals Source Animal: Pig Plasma, Bovine Plasma, Equine Plasma, Avian Plasma, Ovine Plasma End User: Animal Nutrition Companies, Veterinary Clinics, Diagnostic Laboratories, Pharmaceutical Manufacturers, Biotech Firms |
| Companies Covered | Grifols S.A., CSL Limited, Takeda Pharmaceutical Company Limited, Thermo Fisher Scientific Inc., Merck KGaA, Kedrion S.p.A., Octapharma AG, Lake Immunogenics Inc., Proliant Biologicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Blood Plasma Products and Derivatives Market Strategic Shifts & Innovations
Fractionation technology advances and diagnostic platform evolution are compressing product development cycles while fragmenting end-use specifications across nutrition versus pharmaceutical-grade tiers.
Membrane filtration systems with tangential flow configuration are replacing batch centrifugation in mid-scale plasma processing facilities. Contract manufacturers serving regional feed compounders adopt these systems to reduce albumin fraction loss during immunoglobulin concentration. This hardware transition is bifurcating the equipment supply base between pharmaceutical-grade chromatography specialists and commodity membrane suppliers.
EMA veterinary medicines guidelines now mandate species-of-origin labeling for all immunoglobulin-containing products marketed in EU member states. Manufacturers must maintain separate production lines for bovine versus porcine source materials to prevent cross-contamination claims. Diagnostic reagent producers targeting European reference laboratories have reconfigured supply agreements to specify geographic sourcing down to individual abattoir codes.
Consolidated livestock operations with internal veterinary departments now specify immunoglobulin potency certificates tied to specific pathogen neutralization titers rather than generic protein concentration metrics. Feed procurement managers at these integrated protein companies negotiate direct supply contracts with fractionators, displacing traditional distributor relationships. This specification escalation concentrates most acutely in US Midwest and Danish swine production belts where unit economics support premium ingredient premiums.
Animal Blood Plasma Products and Derivatives Market Segmentation
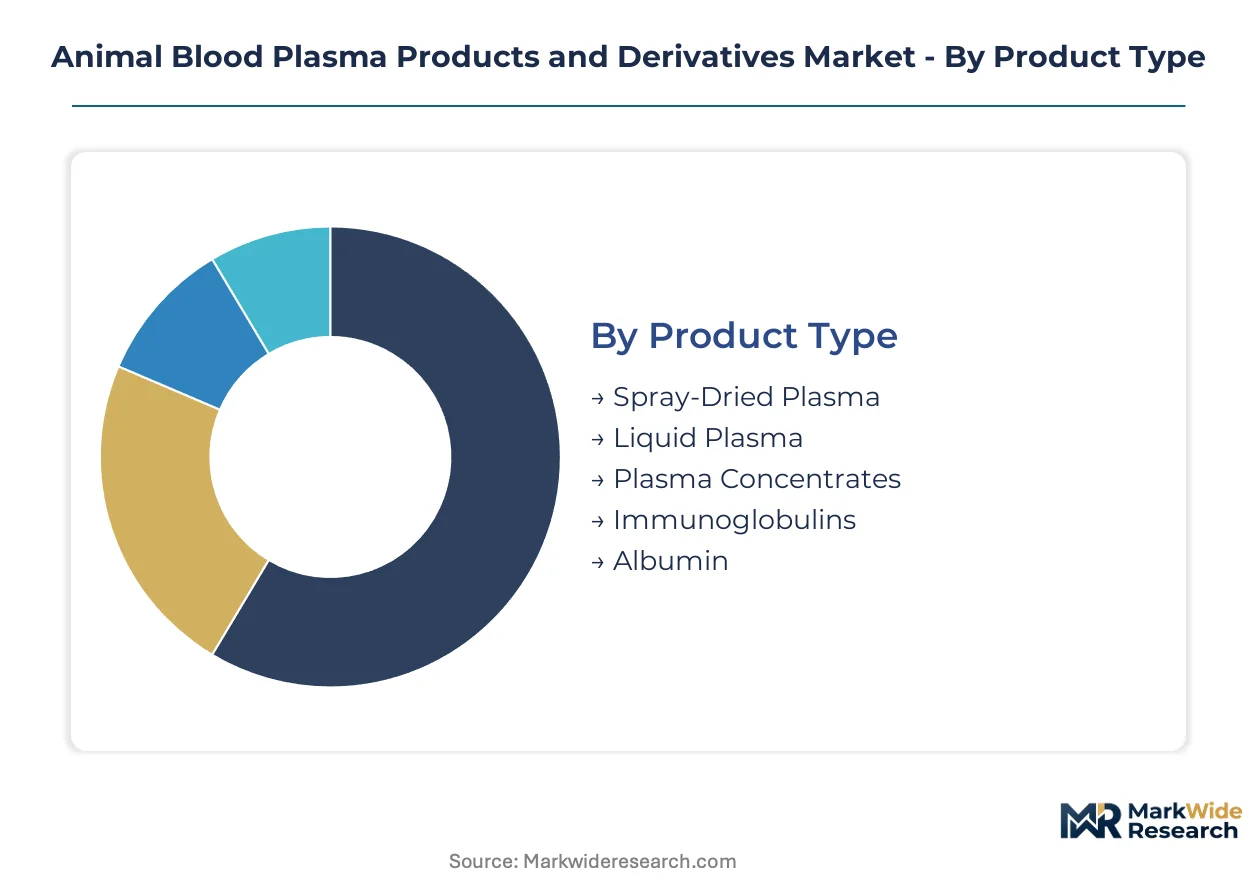
Plasma fractionators must navigate divergent purity requirements across feed-grade and pharmaceutical-grade tiers, with substitution threats from plant-based proteins reshaping investment priorities. Segment boundaries harden as spray-dried plasma commoditizes while immunoglobulin concentrates command diagnostic-grade premiums.
Product Type:
Substitution pressure from fermentation-derived proteins weighs most heavily on albumin isolates and standard plasma concentrates, forcing fractionators to differentiate through pathogen-specific potency certification.
- Spray-Dried Plasma:Heat-processed porcine and bovine plasma with residual moisture below 8%, standardized to 70% crude protein content. Swine integrators in Iowa and North Carolina specify this material for nursery diet inclusion at 4-6% by weight to reduce post-weaning mortality. Volume flows concentrate through regional feed compounders with direct abattoir sourcing contracts.
- Immunoglobulins:Chromatographically purified IgG fractions exceeding 90% purity with defined neutralizing titers against rotavirus and coronavirus strains. Diagnostic laboratories in China and Germany drive species-specific antibody panel procurement for poultry and aquaculture pathogen detection. EMA species-origin labeling mandates now require separate production lines for bovine versus porcine source materials.
- Liquid Plasma:Refrigerated plasma with 14-21 day shelf life, used in specialized veterinary formulations requiring bioactive protein preservation.
- Plasma Concentrates:Partially purified protein fractions serving intermediate applications between feed-grade and pharmaceutical-grade tiers.
- Albumin:Highly purified plasma protein fraction facing displacement risk from recombinant alternatives in cell culture media applications.
Spray-dried plasma retains volume leadership; immunoglobulins hold the steepest expansion curve.
Application:
Cost tier stratification separates commodity nutrition applications from premium therapeutic and diagnostic segments, with biopharmaceutical manufacturers demanding serum-free validation protocols.
- Feed Additives:Spray-dried plasma inclusion in swine and poultry starter diets at 3-8% formulation rates, displacing antibiotic growth promoters under tightening residue regulations. USDA traceability mandates consolidate supplier qualification toward fractionators with validated chain-of-custody systems. Brazilian and Argentine abattoir consolidation concentrates raw material supply under three dominant meatpacking groups.
- Diagnostic Reagents:Species-specific antibody production for ELISA and lateral flow pathogen detection platforms. Chinese provincial CDC network expansion creates concentrated demand for poultry and aquaculture disease surveillance panels. ISO 17025 certification timelines extend quality system implementation by 18-24 months for new market entrants.
- Veterinary Therapeutics:Immunoglobulin concentrates for neonatal calf and piglet scours prevention, requiring FDA Center for Veterinary Medicine efficacy trials against specific pathogen strains.
- Nutritional Supplements:Pet food and specialty animal formulations utilizing plasma protein for palatability and digestibility enhancement.
- Biopharmaceuticals:Cell culture media supplements and recombinant protein production inputs, with serum-free alternatives driving plasma-derived growth factor demand.
Feed additives dominate volume throughput; diagnostic reagents command the highest margin expansion trajectory.
Source Animal:
Supply concentration in bovine and porcine channels creates sourcing vulnerability, while niche species offer differentiation for specialized therapeutic applications.
- Bovine Plasma:Abundant slaughterhouse byproduct from Brazil, Argentina, Australia, and New Zealand beef processing chains. CSL Limited anchors supply security through captive sourcing networks across Oceania. EU feed hygiene regulations impose batch-release and origin-documentation standards that fragment supplier qualification pools.
- Pig Plasma:Concentrated supply from integrated pork production systems in Denmark, Iowa, and North Carolina. Swine integrators with internal veterinary departments now specify immunoglobulin potency certificates tied to specific pathogen neutralization titers.
- Equine Plasma:Specialized sourcing from veterinary blood collection programs for hyperimmune serum production.
- Avian Plasma:Emerging supply channel for poultry-specific diagnostic antibody production.
- Ovine Plasma:Niche sourcing from sheep processing facilities for specialized research applications.
Bovine plasma retains supply dominance; porcine plasma gains share fastest through integrated production system contracts.
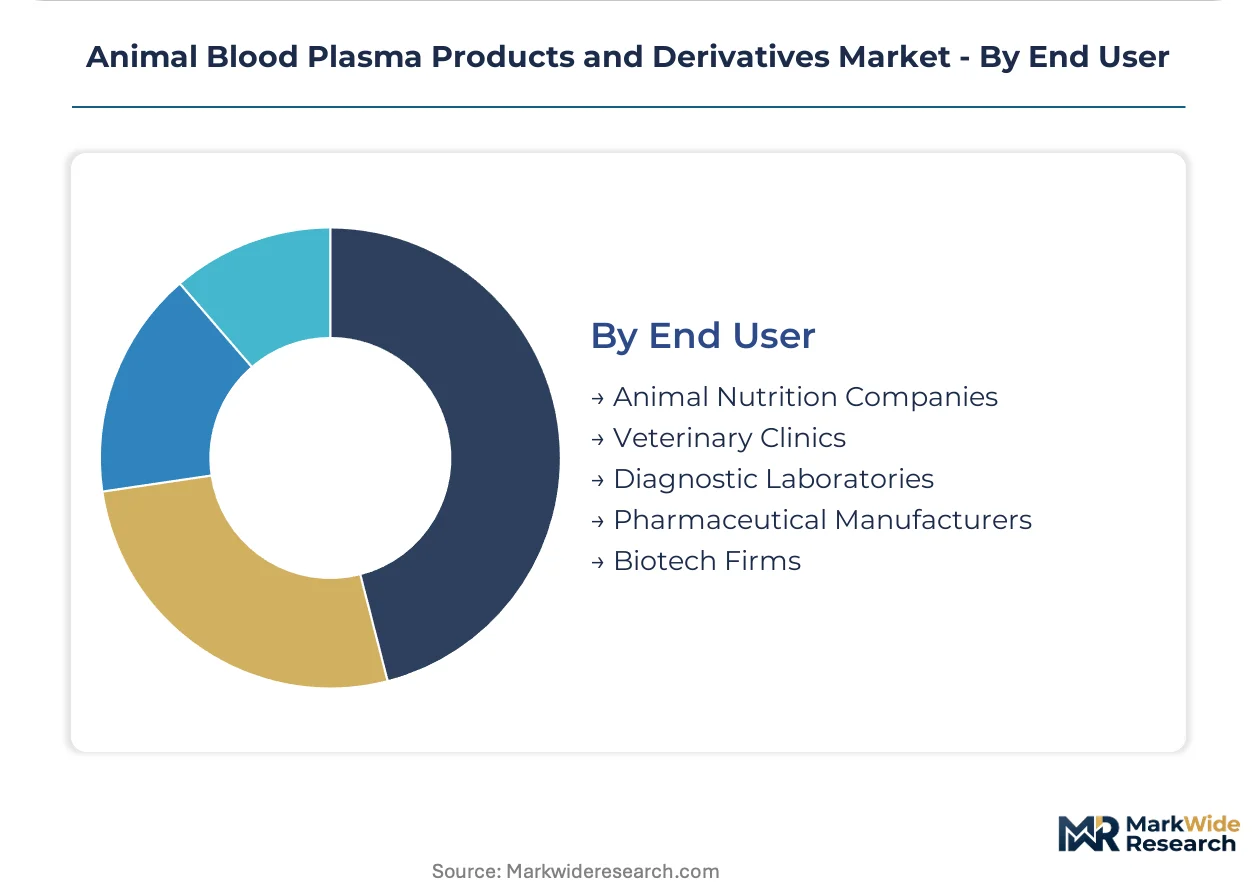
End User:
Customer type fragmentation accelerates as direct-to-producer digital channels displace traditional feed distributor relationships, particularly among mid-sized North American swine operations.
- Animal Nutrition Companies:Formulation houses specifying plasma protein inclusion rates, crude protein minimums, and microbiological safety thresholds. Consolidated livestock operations negotiate direct supply contracts, bypassing traditional distributor markups.
- Diagnostic Laboratories:Reference laboratories and provincial CDC networks requiring species-specific antibody panels with documented geographic sourcing to individual abattoir codes.
- Veterinary Clinics:Neonatal scours prevention protocols driving immunoglobulin concentrate procurement for colostrum replacer formulations.
- Pharmaceutical Manufacturers:Cell culture media and veterinary biologic producers demanding serum-free validation and recombinant protein production inputs.
- Biotech Firms:Precision fermentation and alternative protein developers threatening premium positioning of animal-sourced immunoglobulins.
Animal nutrition companies maintain volume leadership; diagnostic laboratories show the steepest procurement growth curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Danish and Dutch plasma fractionation clusters while Brazilian abattoir consolidation erodes supplier margins across Latin American sourcing corridors. Regional regulatory divergence on species-origin documentation and veterinary biologics approval timelines fragments competitive positioning across major production belts.
United States
Midwest swine integrators in Iowa and North Carolina drive spray-dried plasma procurement for nursery diet formulations at 4-6% inclusion rates. FDA Center for Veterinary Medicine oversight of immunoglobulin product licensing extends commercialization timelines through multi-year efficacy trial requirements. Greater Omaha and Sioux City meatpacking corridors concentrate captive plasma supply under vertically integrated pork production systems.
China
Provincial CDC network expansion creates concentrated procurement of species-specific antibody panels for poultry and aquaculture pathogen detection. NMPA veterinary biologics registration pathways and dual carbon goals reshape manufacturing facility energy compliance standards. Yangtze River Delta diagnostic laboratory clusters in Shanghai and Suzhou anchor immunoglobulin reagent demand growth.
Germany
Reference laboratories in Munich and Hamburg specify immunoglobulin potency certificates with geographic sourcing documentation to individual abattoir codes. EMA veterinary medicines guidelines mandate species-of-origin labeling for all immunoglobulin-containing products marketed across EU member states. Baden-Württemberg biopharmaceutical manufacturing belts require serum-free validation protocols for plasma-derived growth factors in cell culture media.
Brazil
Abattoir consolidation in São Paulo and Mato Grosso concentrates slaughterhouse plasma supply under three dominant meatpacking groups. ANVISA feed hygiene regulations and export-oriented residue compliance standards shape supplier qualification requirements for EU and US-bound protein shipments. Southern beef processing corridors face raw material volatility as cattle cycle fluctuations compress plasma collection windows.
Australia
CSL Limited anchors supply security through captive bovine sourcing networks across Queensland and New South Wales beef processing chains. TGA veterinary biologics oversight and EU-equivalent batch-release standards enable export qualification for European diagnostic reagent manufacturers. Oceania plasma fractionation capacity concentrates in Melbourne-adjacent processing facilities serving Asia-Pacific biopharmaceutical demand.
Animal Blood Plasma Products and Derivatives Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with pharmaceutical-grade chromatography specialists commanding premium positioning while commodity membrane suppliers serve regional feed compounders. The vendor base stratifies across three tiers: human plasma fractionators extending quality systems into animal-derived production, captive-source integrators with abattoir network control, and diagnostic-grade suppliers targeting reference laboratory certification. Dominant competitive moves include M&A consolidation of abattoir sourcing contracts and capacity expansion of membrane filtration systems for mid-scale regional processors.
Within the human plasma expertise tier, Grifols S.A. and CSL Limited exemplify archetypes leveraging pharmaceutical-grade quality infrastructure for veterinary biologics crossover. Thermo Fisher Scientific Inc. occupies a position among diagnostic-grade suppliers targeting third-party assay developers with species-specific antibody reagents. These three entities anchor competitive positioning across the technology-credentialing spectrum that separates pharmaceutical-grade from commodity nutrition applications.
| Leading Market Players |
|---|
| Grifols S.A. |
| CSL Limited |
| Takeda Pharmaceutical Company Limited |
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Kedrion S.p.A. |
| Octapharma AG |
| Lake Immunogenics Inc. |
| Proliant Biologicals |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between Brazilian abattoir operators and North American feed compounders lock in both plasma supply access and eighteen-month price visibility against cattle cycle volatility. These arrangements concentrate procurement power among three dominant São Paulo meatpacking groups while insulating Iowa swine integrators from spot market fluctuations in immunoglobulin concentrate pricing.
Pricing Analysis
Customization-premium spreads separate pharmaceutical-grade chromatographic purification from commodity spray-dried plasma tiers. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 17025 certification status, pathogen-neutralization potency tiers, and geographic sourcing documentation depth. Cost compression in feed-grade plasma intensifies because Brazilian abattoir consolidation restricts raw material competition. Mid-sized North American swine operations exhibit highest price sensitivity, while German reference laboratories tolerate substantial premiums for abattoir-code traceability.
Supply Chain Analysis
Brazil, Argentina, and Australia anchor global bovine plasma collection through beef processing byproduct recovery. Fractionation biochemistry expertise draws from Spanish and Swiss human plasma processing heritage, while chromatography resin supply rests on German and Japanese specialty chemical production. Single-source vulnerability concentrates in São Paulo meatpacking corridors where three groups control eighty percent of export-oriented plasma collection. Distribution runs through regional feed compounders with direct abattoir contracts, bypassing traditional agricultural distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antibiotic residue tightening across major protein-exporting nations creates a high-growth disruption as plasma-derived passive immunity substitutes for ionophore growth promoters within compressed regulatory timelines.
For Market Incumbents: Consolidate captive sourcing networks across Oceania and South America to defend against fermentation-derived antibody substitution threats. Secure ISO 17025 certification for diagnostic-grade production lines before EMA species-origin labeling mandates harden competitive barriers. Backward integration into membrane filtration equipment supply reduces dependence on pharmaceutical chromatography specialists. For New Entrants and Emerging Players: Anchor in Chinese provincial CDC network expansion for species-specific antibody panel supply, where diagnostic laboratory buildout outpaces domestic fractionation capacity. Target mid-scale Southeast Asian aquaculture operations with lyophilized plasma protein formulations engineered for intermittent cold chain infrastructure. Deploy direct-to-producer digital channels to bypass entrenched feed distributor markups in North American markets. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors human plasma fractionators extending veterinary crossover capabilities. Long-term viability hinges on regulatory credentialing depth rather than commodity scale, positioning pharmaceutical-grade quality infrastructure as the scarcest asset class. Watch FDA veterinary biologics pathway friction as the signal indicating whether immunoglobulin concentrate margins sustain or compress.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Abattoir Sourcing Network | CSL Limited's Queensland and New South Wales control secures raw material priority against Brazilian supply volatility. |
| Membrane Filtration Capacity Expansion | Regional feed compounders adopt tangential flow systems to reduce albumin fraction loss during immunoglobulin concentration. |
| ISO 17025 Diagnostic-Grade Certification | Eighteen-month analytical validation timelines erect quality system barriers against commodity membrane suppliers. |
| Direct-to-Producer Digital Channel | E-commerce platforms connecting fractionators with Iowa swine operations displace traditional feed distributor markups. |
| Species-Origin Labeling Compliance | EMA mandates force separate production lines for bovine versus porcine materials, fragmenting supplier qualification pools. |
Research Approach
Cross-validation between plasma fractionator procurement managers and diagnostic laboratory quality directors anchors the qualitative findings against customs data and USDA traceability filings. Primary interviews with veterinary hematology specialists, feed formulation chemists, abattoir operations directors, and EMA regulatory affairs leads combined with FDA Center for Veterinary Medicine guidance documents, ANVISA feed hygiene regulations, and EU feed hygiene directive implementations. Bottom-up plasma volume modeling from abattoir throughput statistics triangulates against top-down immunoglobulin market value estimates.
Sensitivity analysis around cattle cycle fluctuations and antibiotic regulation tightening scenarios stress-tests projection robustness across the analysis window. Segmentation dimensions include product purity tier, application endpoint, source animal species, and end-user customer type. CAGRs derive from spline-interpolated annual growth rates fitted to disclosed capacity expansions and provincial CDC procurement announcements. Forecast inputs incorporate chromatography resin cost trajectories and bovine raw material availability indices.
Material uncertainties — regulatory pathway delays, precision biotechnology substitution acceleration, emerging market cold chain failures — sit outside the modeled envelope. Forecasts reflect assumptions about EMA labeling implementation timelines and Chinese diagnostic laboratory buildout cadence. Recalibration cycles align with material shifts in antibiotic residue enforcement stringency and fermentation-derived antibody technical performance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Animal Health
US Military Animals Market
Animal Health
Companion Animal Ear Infection Treatment Market
Animal Health
Animal Health Market
Animal Health
Companion Animal Healthcare Market
Animal Health
Swine Healthcare Market
Animal Health
Canine Arthritis Treatment Market
Animal Health
Cattle Health Market
Animal Health
Cattle Healthcare Market
Animal Health
Rat Model Market
Animal Health
Canine Mammary Tumor Treatment Market
Animal Health
Animal Healthcare Market
Animal Health
Global Poultry Healthcare Market
Animal Health
Equine Fluid Therapy Market
Animal Health
Laboratory Animal Models Market
Animal Health
Global Companion Animal Health Market
Animal Health
Canada Animal Health Care Market