
 US Companion Animal Health Market | 2026-2036
US Companion Animal Health Market Size, Share, and Industry Trends Forecast 2026-2036
US Companion Animal Health Market Intelligence
The FDA Center for Veterinary Medicine's expanded guidance on veterinary biologics is rebalancing investment toward preventive and therapeutic innovation. Zoetis leverages its vertically integrated manufacturing network to sustain domestic supply chain control for core vaccines and parasiticides. Merck & Co., Inc. anchors its position through R&D intensity in oncology and dermatology pipelines. Boehringer Ingelheim GmbH differentiates via channel depth across both veterinary clinics and direct-to-practice distribution networks.
US companion animal health encompasses pharmaceuticals, biologics, nutritional supplements, and diagnostic tools formulated for dogs, cats, and other household pets, with products typically requiring species-specific pharmacokinetic validation and veterinary oversight for dispensing. Its primary purpose centers on disease prevention, chronic condition management, and life extension in privately owned animals. Pharmaceuticals and vaccines together occupy the largest value share, reflecting recurring vaccination protocols and chronic medication use in aging pet populations. Diagnostics represents the fastest-expanding segment as point-of-care testing and molecular platforms penetrate veterinary clinics. E-commerce channels are gaining structural importance as pet owners seek prescription refills and supplements outside traditional clinic dispensing.
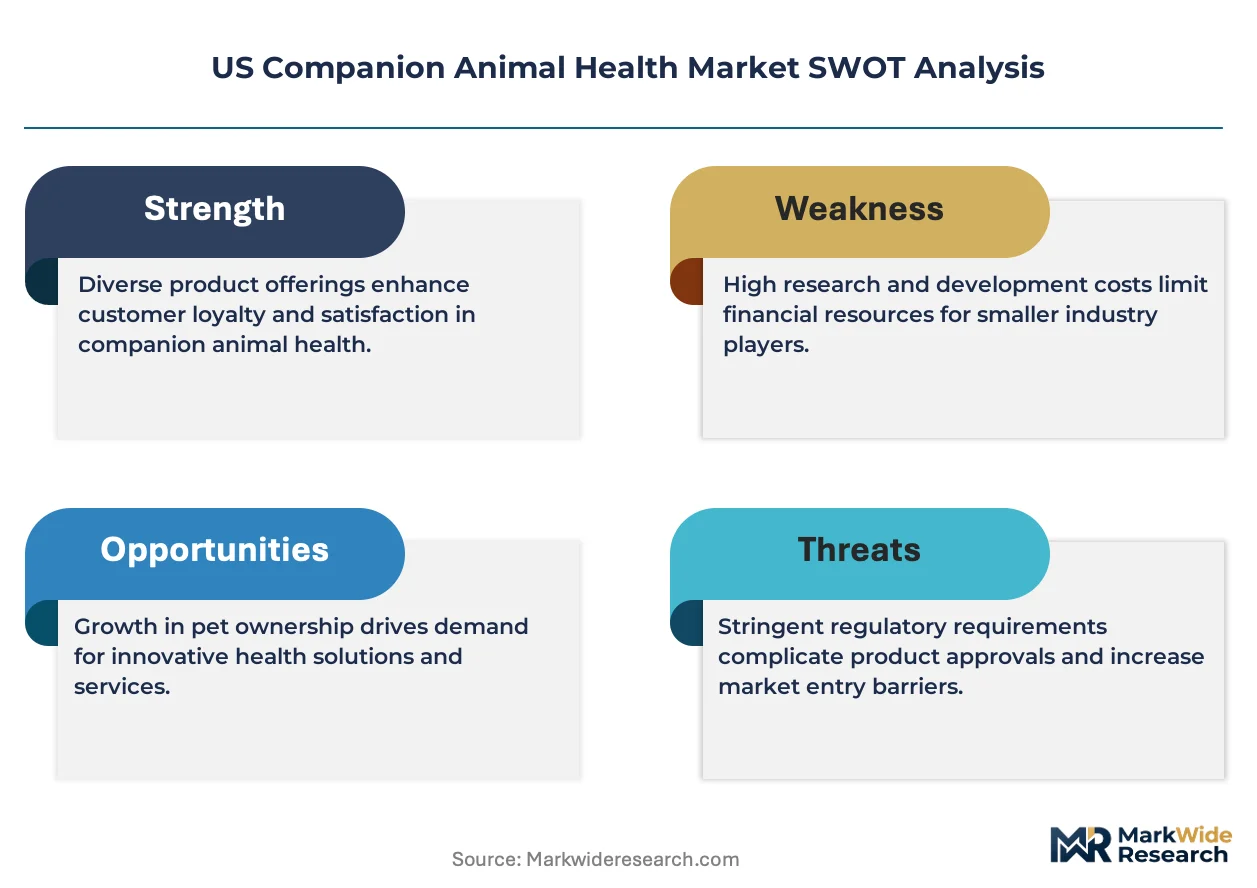
FDA CVM oversight governs new animal drug approvals, while USDA APHIS regulates veterinary biologics manufacturing and safety standards; state veterinary medical boards additionally control dispensing authority and telemedicine scope. These layered requirements shape product development timelines, label claims, and market access pathways for manufacturers. Stakeholders must monitor evolving state telemedicine regulations and FDA guidance on compounded medications as these frameworks determine competitive positioning in direct-to-consumer channels.
Market Dynamics
The FDA Center for Veterinary Medicine's accelerated biologics pathway is compressing development timelines for preventive therapeutics, while pet owner demand for at-home diagnostics redistributes care delivery away from clinic-centric models.
Growth Catalysts
- Telemedicine scope expansion:State veterinary medical boards in California, Texas, and Florida have broadened telehealth prescribing authority, enabling remote chronic disease management for aging pet populations.
- Point-of-care molecular platforms:Veterinary clinics are adopting PCR-based pathogen detection systems that deliver same-day diagnostic results, reducing referral delays and treatment initiation times.
- Aging pet demographics:Extended lifespans among dogs and cats are generating recurring revenue streams for chronic condition pharmaceuticals, particularly in oncology and dermatology categories.
Market Restraints
- Active pharmaceutical ingredient concentration:Domestic manufacturing of veterinary APIs remains limited, creating import dependency on Chinese and Indian chemical suppliers subject to FDA warning letter actions.
- Compounded medication regulatory friction:FDA CVM draft guidance on veterinary compounding pharmacies threatens to restrict customized formulation access for exotic species and dose-adjusted therapies.
- Specialist veterinarian scarcity:Board-certified practitioners in veterinary oncology and internal medicine cluster in coastal metropolitan areas, leaving interior states underserved.
Strategic Opportunities
- Direct-to-consumer channel development:E-commerce platforms for prescription refills and nutritional supplements are capturing pharmacy margin that previously accrued to clinic dispensing.
- USDA APHIS streamlined biologics approval:Revised guidance on veterinary vaccine master files reduces regulatory burden for platform technologies applied across multiple species indications.
- Wearable monitoring convergence:Integration of continuous glucose monitors with cloud-based veterinary practice management software enables remote chronic disease surveillance.
Industry Challenges
- Veterinary technician workforce gaps:Training program capacity constraints limit clinic expansion in high-growth Sun Belt metropolitan areas.
- Legacy practice management system integration:Cloud-native diagnostic platforms face interoperability barriers with installed on-premise software at established multi-site hospital groups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Companion Animal Health Market |
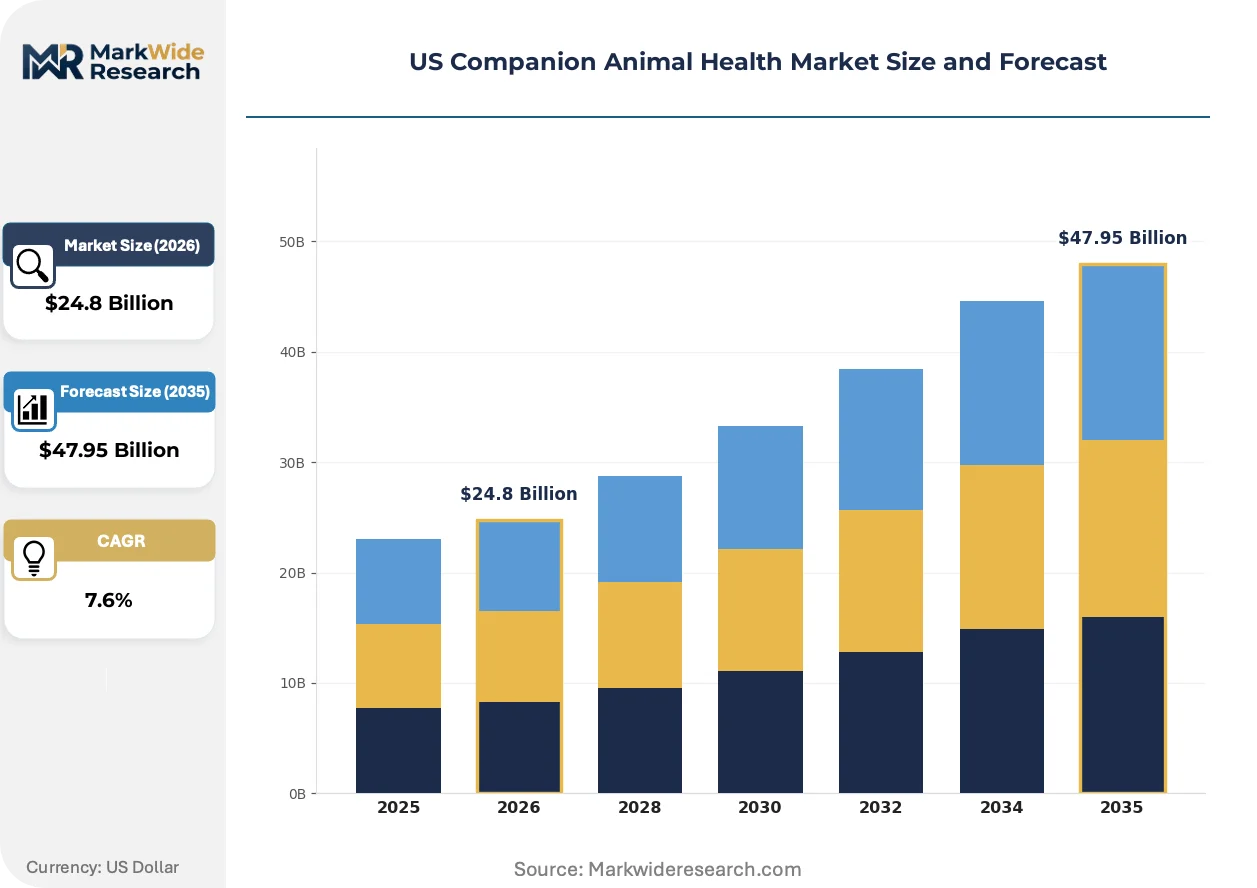
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $47.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Vaccines, Supplements, Diagnostics End User: Veterinary Clinics, Animal Hospitals, Pet Owners, Research Laboratories Therapy Area: Infectious Diseases, Dermatology, Orthopedics, Oncology Distribution Channel: Retail Pharmacies, E-commerce, Distributors, Wholesalers |
| Companies Covered | Zoetis, Merck & Co., Inc., Boehringer Ingelheim GmbH, Elanco, IDEXX Laboratories, Inc., Ceva Santé Animale, Virbac, Dechra Pharmaceuticals Plc, Vetoquinol S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Companion Animal Health Market Strategic Shifts & Innovations
Digital health technologies are fragmenting the traditional veterinary visit, enabling asynchronous care models that separate diagnostic data collection from clinician interpretation. This shift compresses the care cycle while expanding addressable touchpoints between pet owners and health providers.
Point-of-care PCR and immunoassay systems are decentralizing infectious disease diagnosis from reference laboratories to general practice settings. Primary care veterinarians in suburban and rural markets now perform pathogen identification previously requiring multi-day send-out workflows. This capability compression is reducing specialist referral rates for undifferentiated clinical presentations while elevating diagnostic revenue capture at the generalist level.
FDA CVM's expanded guidance on real-world evidence for veterinary drug approvals is compressing post-market study requirements for novel therapeutics. Manufacturers can now leverage electronic health record data from practice management networks to supplement traditional controlled trials. This regulatory evolution most directly affects chronic disease categories where long-term safety databases accumulate naturally through routine care documentation.
Subscription-based preventive care plans are displacing fee-for-service billing in multi-site veterinary hospital groups. Pet owners in Florida and Texas markets increasingly prefer predictable monthly payments covering examinations, core vaccines, and parasiticide prophylaxis. This model shift locks in patient retention while smoothing revenue seasonality for practice operators exposed to weather-driven demand fluctuations.
US Companion Animal Health Market Segmentation
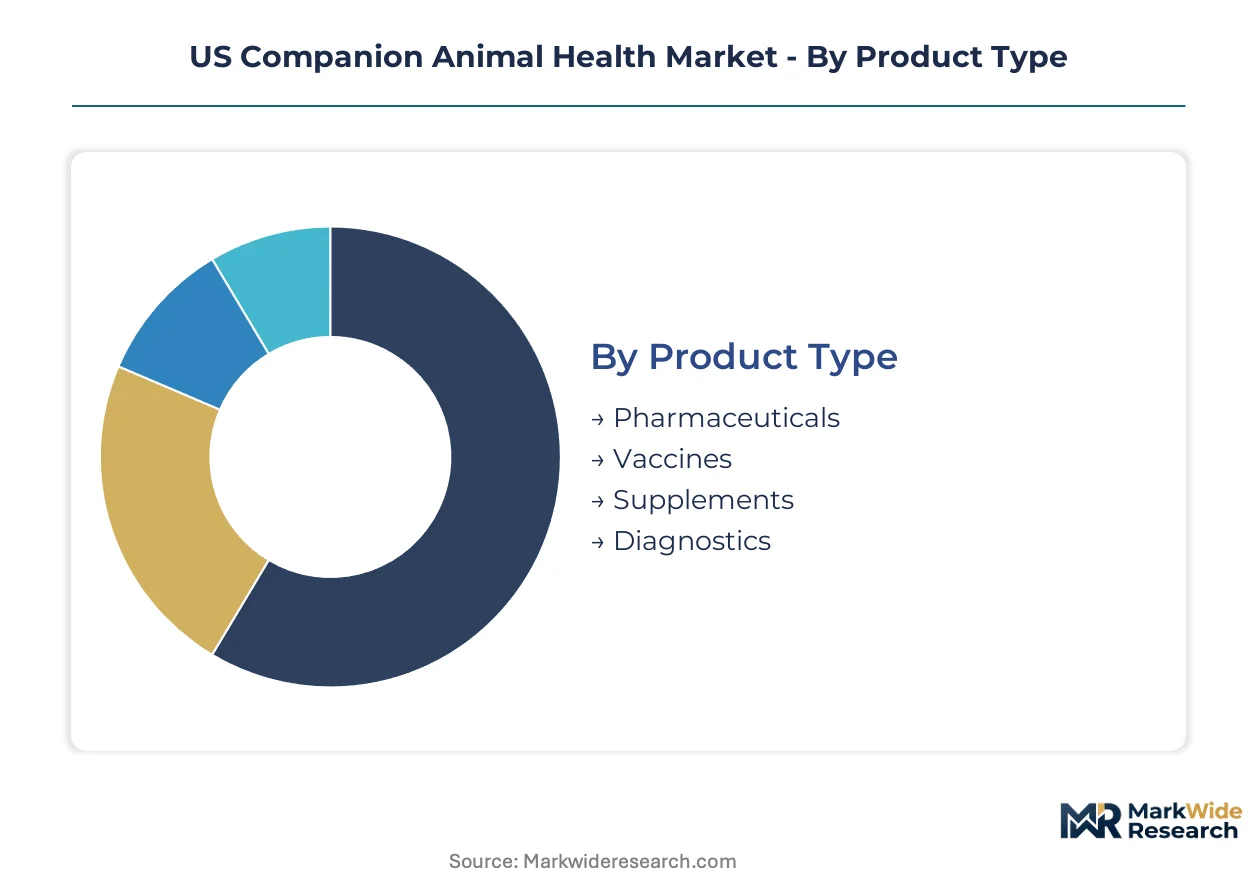
Segmentation in US companion animal health reveals how capital deployment, regulatory pathways, and care delivery models diverge across product categories and customer channels. Understanding these divisions clarifies where FDA CVM oversight intensifies, where telemedicine is redistributing demand, and where specialty veterinary services concentrate geographically.
Product Type:
Capital intensity varies sharply across this category, with biologics manufacturing demanding the heaviest upfront facility investment and molecular diagnostics platforms requiring substantial R&D commitment before commercialization.
- Pharmaceuticals:Chronic condition therapeutics for oncology and dermatology command sustained R&D spend due to species-specific pharmacokinetic validation requirements. Demand clusters in California and Florida specialty practices serving aging pet populations with recurring medication needs.
- Vaccines:USDA APHIS-regulated biologics production requires dedicated viral seed stock facilities and cold-chain infrastructure. Core vaccination protocols generate recurring revenue through annual revaccination schedules, with manufacturing concentrated in vertically integrated networks.
- Supplements:Nutraceutical formulations face lighter regulatory burden under FDA CVM enforcement discretion, attracting private-label entrants with lower capital barriers.
- Diagnostics:Point-of-care PCR and immunoassay systems are penetrating general practice settings, reducing reference laboratory dependency.
Pharmaceuticals absorb the bulk of installed manufacturing capacity; diagnostics is expanding most quickly as clinics adopt same-day pathogen detection.
End User:
Customer concentration patterns reveal where purchasing authority resides and how telemedicine regulations are fragmenting traditional clinic-centric models.
- Veterinary Clinics:Primary care practices in suburban Texas and Florida markets represent the volume anchor for preventive therapeutics and core vaccines. These facilities are adopting point-of-care diagnostics to capture revenue previously lost to reference laboratory send-outs.
- Animal Hospitals:Multi-site specialty groups in California concentrate demand for advanced oncology and orthopedic procedures, driving pharmaceutical procurement at scale.
- Pet Owners:Direct purchasing through e-commerce channels is capturing supplement and parasiticide refill volume, enabled by state veterinary board telehealth prescribing expansions.
- Research Laboratories:Academic and contract research organizations support preclinical validation studies for novel therapeutics, representing a specialized procurement segment with distinct compliance requirements.
Veterinary clinics retain the dominant share of prescription dispensing; pet owner direct channels are climbing the fastest as state telemedicine scope broadens.
Therapy Area:
Disease category selection determines R&D portfolio allocation and whether treatments address acute episodic care or chronic lifetime management.
- Infectious Diseases:Vaccine-preventable conditions and antimicrobial therapies constitute the foundational revenue base, with FDA CVM antimicrobial stewardship guidance reshaping prescribing patterns.
- Dermatology:Chronic allergic and autoimmune skin conditions generate recurring pharmaceutical demand, particularly in breeds with genetic predispositions concentrated in purebred populations.
- Orthopedics:Joint supplements and surgical interventions address mobility impairment in large-breed dogs, with demand correlating to pet owner willingness to fund restorative procedures.
- Oncology:Specialty veterinary hospitals in metropolitan California and Texas are expanding chemotherapy and targeted therapy protocols, attracting board-certified practitioners and concentrated pharmaceutical procurement.
Infectious diseases command the largest installed treatment infrastructure; oncology is gaining share fastest as specialty referral networks mature.
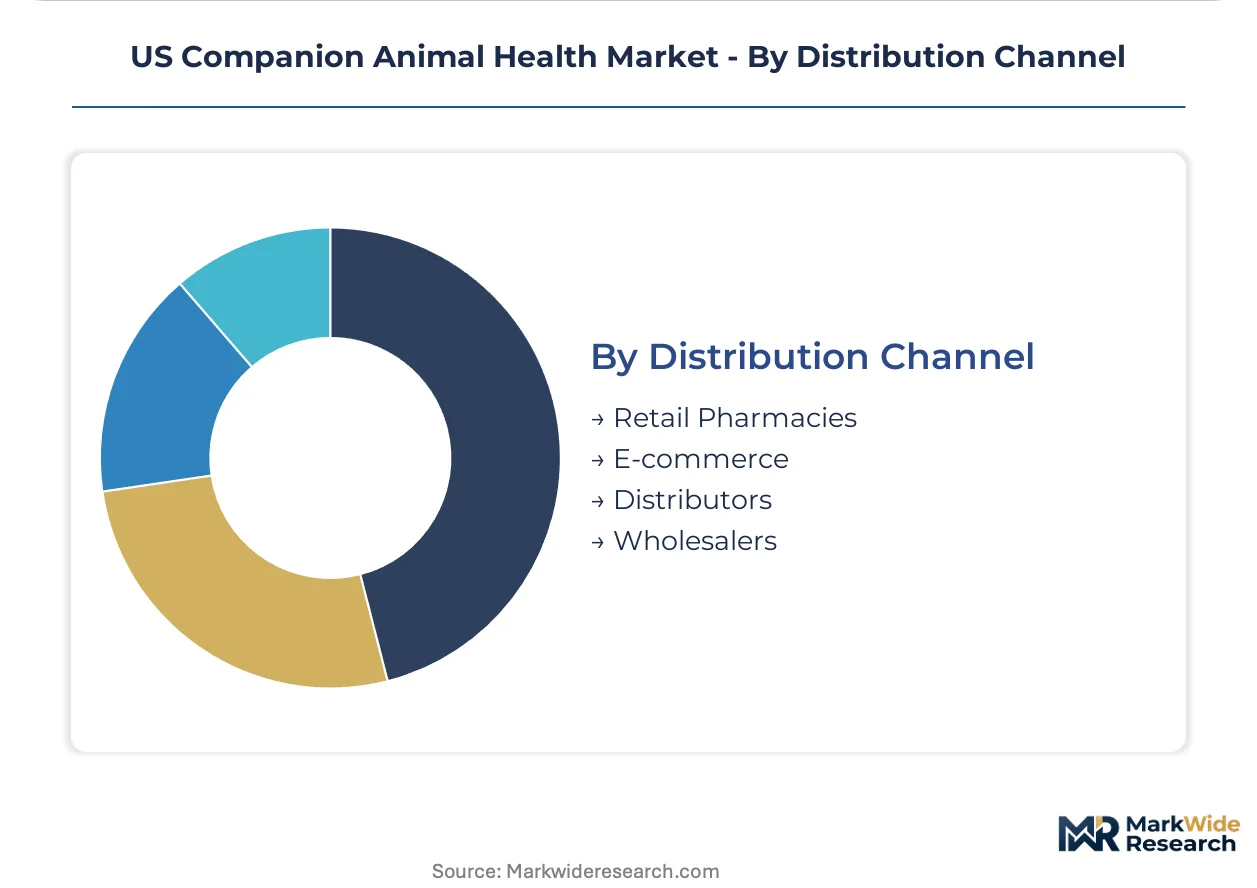
Distribution Channel:
Channel structure determines margin capture, inventory velocity, and regulatory compliance burden across the product journey from manufacturer to end user.
- Retail Pharmacies:Human pharmacy chains with veterinary prescription capabilities are capturing chronic medication refills, particularly in markets with limited specialty clinic density.
- E-commerce:Direct-to-consumer platforms for supplements and parasiticides are displacing clinic dispensing margins, with fulfillment infrastructure concentrated in distribution hubs serving Sun Belt metropolitan areas.
- Distributors:Veterinary-specific wholesalers maintain cold-chain capabilities for biologics and provide credit terms that support clinic inventory management.
- Wholesalers:Broad-line pharmaceutical distributors serve mixed human-animal health customers, leveraging scale economies in logistics and procurement.
Distributors retain the dominant position in biologics delivery; e-commerce is expanding most quickly in supplement and parasiticide categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of veterinary biologics and pharmaceuticals clusters in the Midwest and Mid-Atlantic, while demand concentrates in Sun Belt metropolitan areas with aging pet populations and expanded specialty hospital networks.
California
Specialty veterinary hospitals in Los Angeles and San Francisco Bay Area drive concentrated demand for oncology and dermatology therapeutics. FDA CVM oversight of compounded medications shapes dispensing protocols for exotic species practices. The San Diego corridor anchors contract research organizations supporting preclinical pharmacokinetic studies for novel therapeutics.
Texas
Primary care clinics in Dallas-Fort Worth and Houston metropolitan areas generate volume demand for core vaccines and parasiticide prophylaxis. State veterinary medical board telehealth expansions enable remote chronic disease management across sprawling suburban markets. The Austin corridor attracts veterinary technology startups developing practice management software integrations.
Florida
Subscription-based preventive care plans penetrate deeply in Miami and Tampa markets, smoothing revenue seasonality for multi-site hospital groups. USDA APHIS-regulated biologics distribution relies on cold-chain infrastructure radiating from Orlando logistics hubs. The state's exotic animal practices create niche demand for customized compounded formulations.
Northeast Corridor
Legacy veterinary schools in Philadelphia and Boston metropolitan areas supply board-certified specialists to national referral networks. FDA CVM's accelerated biologics pathway compresses development timelines for preventive therapeutics validated through regional academic medical centers. The corridor's reference laboratories perform molecular diagnostics for general practices across interior states.
Pacific Northwest
Telemedicine-native practice models in Seattle and Portland metropolitan areas pioneer asynchronous care delivery separating diagnostic data collection from clinician interpretation. State veterinary boards in Washington and Oregon have expanded prescribing authority for remote consultations. The region's technology workforce sustains early adoption of wearable monitoring devices integrated with cloud-based practice management platforms.
US Companion Animal Health Market Key Industry Players
The competitive structure tilts toward vertically integrated pharmaceutical manufacturers with captive vaccine production networks. Market concentration remains elevated in biologics and chronic therapeutics, while diagnostics and supplements attract specialized entrants with lower capital barriers. Two strategic archetypes dominate: diversified animal health conglomerates with human pharma heritage, and focused veterinary specialists with deep channel relationships. Competitive moves center on M&A to acquire molecular diagnostics capabilities and strategic partnerships to secure API supply chains.
Among diversified conglomerates, Zoetis and Merck & Co., Inc. exemplify the vertically integrated archetype with historical roots in human pharmaceutical development. Boehringer Ingelheim GmbH occupies a position bridging European biologics expertise with North American distribution depth. These three entities anchor the premium-tier infrastructure for USDA APHIS-regulated vaccine production and FDA CVM-approved chronic therapeutics, representing distinct geographic origins—American, American, and German respectively—while converging on similar strategic postures around manufacturing control and specialty veterinary channel penetration.
| Leading Market Players |
|---|
| Zoetis |
| Merck & Co., Inc. |
| Boehringer Ingelheim GmbH |
| Elanco |
| IDEXX Laboratories, Inc. |
| Ceva Santé Animale |
| Virbac |
| Dechra Pharmaceuticals Plc |
| Vetoquinol S.A. |
| Others |
Cost & Logistics Intelligence
API import price volatility from Indian and Chinese chemical suppliers cascades through veterinary pharmaceutical manufacturing into tiered pricing structures separating branded therapeutics from compounded alternatives.
Pricing Analysis
Outcome-based pricing anchors oncology and dermatology therapeutics to treatment response metrics rather than unit doses. Three-tier pricing structure across premium, standard, and economy levels separates USDA APHIS-licensed biologics from FDA CVM-approved pharmaceuticals and unregulated supplements. Pricing pressure stems from e-commerce parasiticide discounting and direct-to-consumer supplement competition. General practice clinics exhibit highest price sensitivity for diagnostic platforms, while California specialty hospitals absorb premium therapeutics with minimal procurement friction.
Supply Chain Analysis
Dual-sourcing requirements for active pharmaceutical ingredients compel manufacturers to qualify secondary suppliers in India alongside primary Chinese chemical producers. Veterinary biologics production draws from viral seed stock facilities concentrated in the Midwest and Mid-Atlantic, with cold-chain distribution radiating from Orlando and Dallas-Fort Worth hubs. Tariff exposure on imported APIs creates margin vulnerability for non-vertically integrated formulators. Finished goods distribution runs through veterinary-specific wholesalers maintaining temperature-controlled logistics for USDA APHIS-regulated vaccines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialist veterinarian scarcity and concentrated biologics manufacturing capacity prop pricing power for incumbents controlling captive production networks.
For Market Incumbents: Extend manufacturing control through backward integration into API synthesis or captive viral seed stock facilities to offset import dependency on Chinese and Indian chemical suppliers. Deepen specialty veterinary channel penetration in Texas and Florida to lock in recurring vaccine and parasiticide revenue against e-commerce erosion. For New Entrants and Emerging Players: Launch via direct-to-consumer telehealth platforms in Florida and Texas markets where state veterinary board prescribing expansions enable remote chronic disease management. Target point-of-care diagnostics for general practice clinics in suburban Sun Belt metropolitan areas underserved by reference laboratory infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor molecular diagnostics specialists with FDA CVM pre-submission pathways in the Pacific Northwest technology corridor. Five-to-ten year viability hinges on cloud-based practice management integration capabilities. Watch for FDA warning letter actions against overseas API suppliers as inflection indicator for domestic manufacturing premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Point-of-Care Diagnostics Platform Launch | PCR-based pathogen detection in general practice clinics reduces reference laboratory dependency and referral delays. |
| Telehealth Prescribing Infrastructure Buildout | State veterinary board expansions in California, Texas, and Florida enable remote chronic disease management revenue capture. |
| USDA APHIS Biologics Master File Submission | Streamlined vaccine approval pathways reduce regulatory burden for platform technologies across multiple species indications. |
| API Supply Chain Dual-Qualification | Secondary supplier validation in India mitigates FDA warning letter exposure from concentrated Chinese chemical imports. |
| Wearable Monitoring Device Integration | Continuous glucose monitors linked to cloud-based practice management software enable asynchronous chronic disease surveillance. |
Research Approach
Multi-period observation of FDA CVM approval timelines, USDA APHIS biologics licensing patterns, and state veterinary board telehealth regulations anchored the trend analysis, supplemented by interviews with veterinary practice owners, pharmaceutical regulatory affairs leads, specialty hospital procurement managers, and distribution channel partners. Secondary validation drew from FDA CVM drug approval databases, USDA APHIS veterinary biologics reports, state veterinary medical board regulatory filings, and American Veterinary Medical Association workforce surveys. Bottom-up clinic-level demand modeling and top-down manufacturer revenue triangulation cross-verified segment estimates.
Segment-weighting approaches distributed value across pharmaceuticals, vaccines, diagnostics, and supplements according to installed manufacturing capacity and adoption velocity. Therapy area, end user channel, and distribution pathway dimensions structured the analytical framework across the projection horizon. CAGRs derived from regression analysis of historical FDA CVM approval rates correlated with pet owner expenditure surveys and specialty veterinarian density metrics.
Regulatory guidance revisions on compounded medications, API import inspection intensity, and telemedicine scope expansions are the dominant revision risks to demand and pricing assumptions. Deviation in FDA CVM enforcement posture would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Animal Health
Companion Animal Ear Infection Treatment Market
Animal Health
Equine Fluid Therapy Market
Animal Health
Equine Healthcare Market
Animal Health
Artificial Intelligence (AI) in Animal Health Market
Animal Health
China Companion Animal Health Market
Animal Health
African Horse Sickness Treatment Market
Animal Health
Canine Influenza Treatment Market
Animal Health
Canada Animal Health Care Market
Animal Health
Animal Blood Plasma Products and Derivatives Market
Animal Health
Companion Animal Healthcare Market
Animal Health
Cattle Health Market
Animal Health
Animal Health Market
Animal Health
Global Farm Animal Healthcare Market
Animal Health
Rat Model Market
Animal Health
Animal Health Software Market
Animal Health
Swine Healthcare Market