
 US Military Animals Market | 2026-2036
US Military Animals Market Size, Share, and Industry Trends Forecast 2026-2036
US Military Animals Market Insights
Performance-based handler training subscriptions is recalibrating how vendors package military animal capabilities. K2 Solutions, Inc leverages its North Carolina training campus to sustain long-term service contracts with federal agencies. Worldwide Canine anchors its competitive position through deep specialization in patrol and detection dog procurement. Shultz K9 Enforcement Inc differentiates by controlling breeder-to-deployment channels for law enforcement and military buyers.
US military animals comprise trained canines, equines, and other species selected for olfactory acuity, stamina, or terrain mobility, then conditioned through operant conditioning protocols to perform detection, tracking, or patrol functions under combat stress. Dogs dominate procurement volume across the animal type dimension, while explosive detection commands premium investment within the application category due to asymmetric threat environments. The deployment mode segment tilts toward forward operating base assignments where force protection requirements intensify handler-animal pairing frequency.
The Department of Defense and USDA Animal and Plant Health Inspection Service jointly govern procurement standards, veterinary protocols, and quarantine requirements for military animals entering federal service. The Animal Welfare Act and DOD Directive 6400.04 establish baseline care thresholds that shape vendor qualification and facility inspection schedules. Stakeholders must monitor congressional appropriations language for military working dog program line items and track handler-to-canine ratio mandates that directly determine contract sizing.
Market Dynamics
The National Defense Authorization Act's handler-to-canine ratio mandates are compressing vendor contract sizing while forcing training providers to restructure service delivery around embedded personnel rather than discrete animal sales.
Growth Catalysts
- Asymmetric threat proliferation:Improvised explosive device deployment in contested zones sustains explosive detection canine procurement volumes across forward operating bases.
- DOD Directive 6400.04:Federal veterinary care standards expand recurring service contract opportunities for qualified animal health providers.
- Texas-Virginia training cluster:Concentration of major installations generates localized vendor ecosystem density and referral network effects.
Market Restraints
- Breeding stock scarcity:USDA quarantine protocols limit foreign-sourced canine genetics, constraining supply elasticity.
- Specialized veterinary labor:Board-certified military veterinary practitioners concentrate in specific duty stations, creating regional service gaps.
- Operational tempo volatility:Deployment cycle fluctuations complicate handler-animal pairing continuity and training amortization.
Strategic Opportunities
- Performance-based subscriptions:Federal agencies are piloting outcome-linked handler training contracts that shift revenue from capital to recurring models.
- Equine mobility segments:Mountain warfare and special operations units show renewed interest in pack animal capabilities for terrain-inaccessible zones.
- Biometric-integrated wearables:Convergence of animal physiological monitoring with handler communications systems opens dual-use product pathways.
Industry Challenges
- Operant conditioning standardization:Inconsistent methodology certification across military branches complicates vendor qualification and interoperability.
- Handler retention cycles:Military personnel rotation schedules disrupt animal bonding continuity and degrade operational readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Military Animals Market |
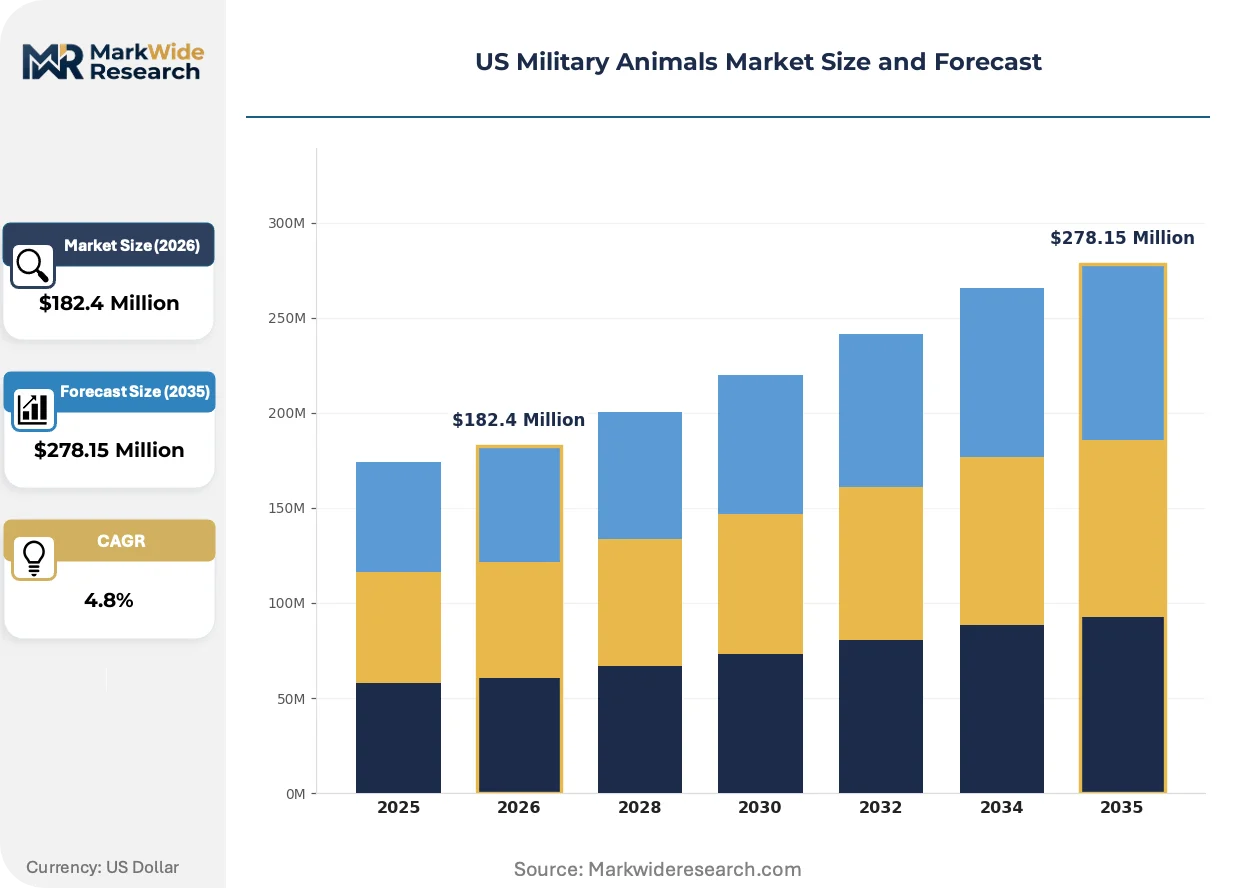
| Market Size in 2026 | $182.4 Million |
| Market Size in 2035 | $278.15 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Animal Type: Dogs, Horses, Mules, Rats Application: Search and Rescue, Explosive Detection, Patrol, Messenger Deployment Mode: On-base, Forward Operating Base, Battlefield, Training Ground Handler Type: Military Personnel, Civilian Trainers, Canine Handlers, Specialized Units |
| Companies Covered | Pond & Company, Shultz K9 Enforcement Inc, K9 Partners for Patriots, ExcelsiorK9, TWG Group, Us K9 Unlimited, Worldwide Canine, Cobra Canine, K2 Solutions, Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Military Animals Market Trends and Innovations
Sensor augmentation and data-driven conditioning protocols are restructuring how military animals integrate into networked force protection systems, with implications for vendor capability packaging and contract structures.
Wearable biometric monitors for military working dogs is unifying physiological stress indicators with real-time handler alerts. Special operations units are adopting these systems for extended patrol missions. The technology is unifying veterinary oversight with tactical decision-making, compressing response times to heat exhaustion and exhaustion-related performance degradation.
The Animal Welfare Act enforcement amendments are tightening facility inspection frequencies and documentation requirements for vendors supplying federal agencies. Commercial breeding operations face elevated compliance costs and facility upgrade mandates. Detection dog procurement categories show the most pronounced adjustment, with buyers prioritizing pre-certified vendors to accelerate acquisition timelines.
Federal buyers are consolidating vendor relationships around full-lifecycle service providers capable of delivering breeder selection through deployment support. Discrete animal sales are losing share to integrated program management contracts. Texas and Virginia installations exhibit the most concentrated shift, with procurement officers favoring single-source accountability over multi-vendor coordination.
US Military Animals Market Segmentation
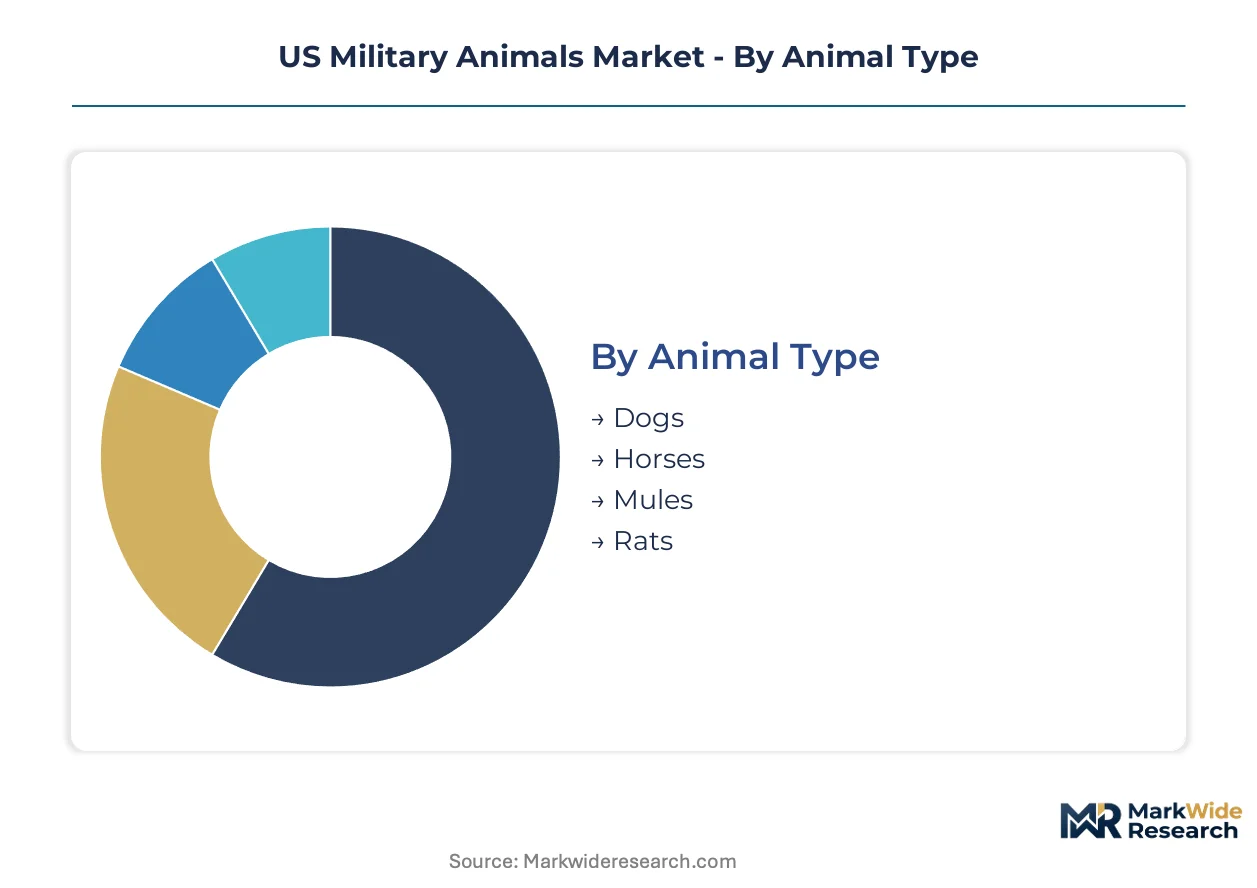
Segmentation in the US military animals market reveals how procurement priorities diverge across operational contexts. Handler-to-animal pairing protocols and deployment environment constraints shape which segments command premium investment versus commodity procurement.
Animal Type:
Dogs operate as standalone detection and patrol assets requiring discrete handler assignment, while equines and smaller mammals embed within specialized mobility or confined-space reconnaissance systems.
- Dogs:Olfactory conditioning produces explosive detection and patrol capabilities unmatched by mechanical sensors. Procurement concentrates at Lackland Air Force Base and Fort Belvoir facilities where the Department of Defense maintains breeding evaluation protocols.
- Horses:Terrain mobility in mountain warfare units demands animals with load-bearing stamina above 120 kilograms. Special operations commands in Colorado and California drive replacement procurement for aging stock.
- Mules:Pack animal applications persist in terrain-inaccessible zones where motorized transport fails.
- Rats:Confined-space mine detection programs utilize smaller mammals for tunnel and urban clearance operations.
Volume placements concentrate in Dogs; the faster expansion belongs to Horses.
Application:
Application segments separate by operational tempo intensity, with sustained-deployment functions commanding recurring service contracts versus discrete training events.
- Explosive Detection:Asymmetric threat environments sustain the highest per-unit procurement investment. Forward operating base force protection requirements in CENTCOM areas of operation drive handler-animal pairing density.
- Patrol:Perimeter security and area denial functions integrate canines into layered defense architectures. Texas and Virginia installations generate concentrated demand for patrol-certified animals.
- Search and Rescue:Combat search and rescue operations require animals conditioned for helicopter deployment and rapid extraction protocols.
- Messenger:Communication relay functions persist in electromagnetic-denied environments where radio silence is mandatory.
Contract value clusters in Explosive Detection; Search and Rescue climbs the fastest as special operations units expand technical rescue capabilities.
Deployment Mode:
Deployment mode determines handler-animal separation tolerance and veterinary support infrastructure requirements, with isolated assignments demanding higher conditioning investment.
- Forward Operating Base:Extended patrol missions in contested zones require animals with combat stress conditioning and heat tolerance certification. CENTCOM and AFRICOM operational theaters sustain procurement priority.
- On-base:Domestic installation security functions operate with stable veterinary infrastructure and predictable handler rotation schedules.
- Battlefield:Direct combat zone deployment demands rapid acclimation protocols and casualty evacuation integration.
- Training Ground:Initial conditioning and certification programs concentrate at federal training installations with standardized evaluation metrics.
Procurement volume tilts toward On-base assignments; Forward Operating Base shows the steepest expansion trajectory as force protection requirements intensify.
Handler Type:
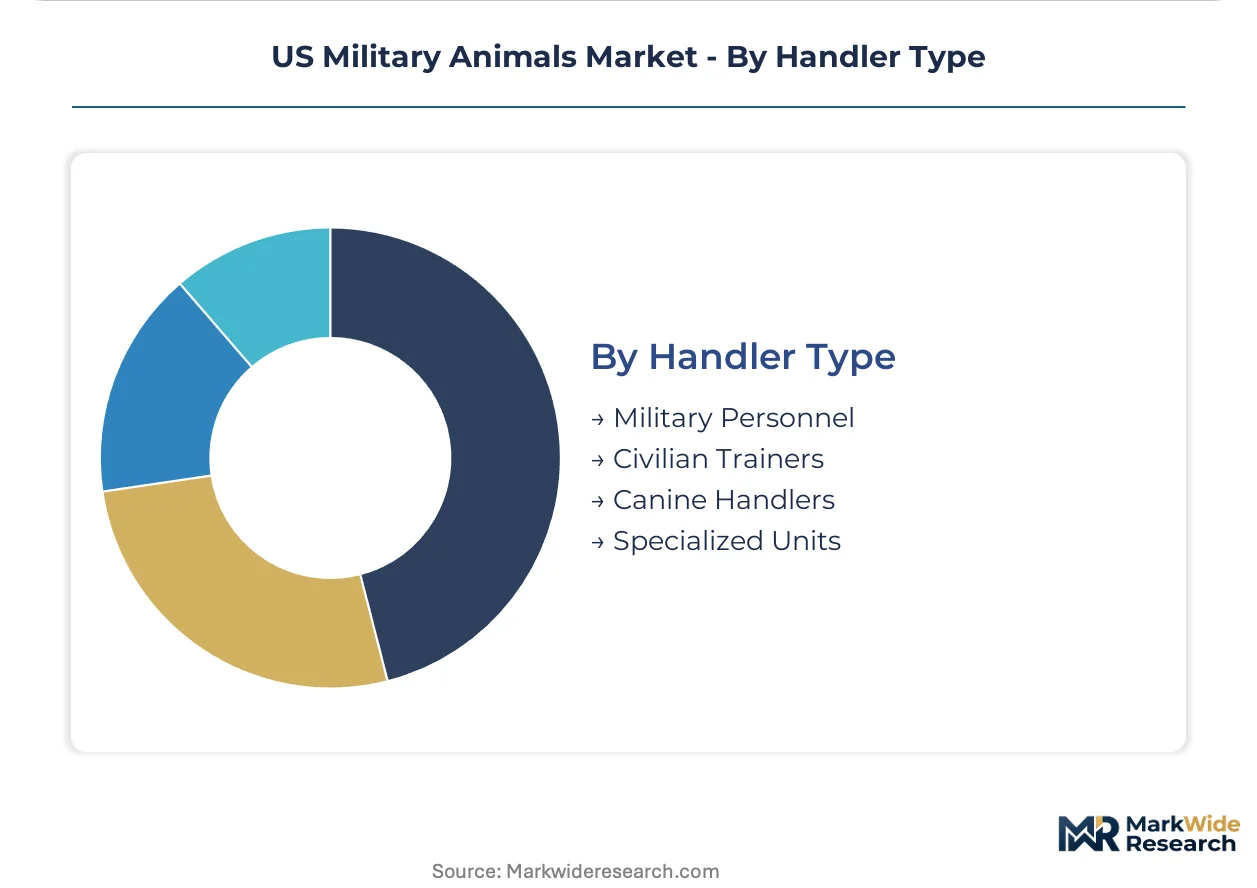
Handler classification shapes contract structure, with military personnel requiring embedded training support versus civilian trainers operating through service agreements.
- Military Personnel:Active-duty handlers rotate through standardized military occupational specialty pipelines with defined assignment durations. Personnel retention challenges disrupt animal bonding continuity.
- Canine Handlers:Specialized certification programs produce dedicated handler cadres with extended animal pairing timelines.
- Civilian Trainers:Contracted instruction services deliver initial conditioning without permanent federal employment obligations.
- Specialized Units:Special operations and explosive ordnance disposal teams require handlers with mission-specific tactical qualifications.
Program scale concentrates in Military Personnel; Specialized Units gain share fastest as tier-one forces expand working dog integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lackland Air Force Base in San Antonio anchors federal procurement concentration for military working dogs, with training infrastructure density shaping vendor ecosystem formation across three distinct state clusters.
Texas
Joint Base San Antonio-Lackland operates the Department of Defense's sole military working dog breeding and training program under 341st Training Squadron command. USDA Animal and Plant Health Inspection Service quarantine protocols govern all canine imports entering federal service through this installation. The San Antonio-Austin corridor hosts the densest concentration of private-sector training vendors supplying explosive detection and patrol certification services.
Virginia
Fort Belvoir and Marine Corps Base Quantico sustain specialized handler training pipelines for explosive ordnance disposal and special operations units. DOD Directive 6400.04 veterinary care standards apply across all National Capital Region installations. Northern Virginia procurement officers favor integrated full-lifecycle contracts over discrete animal purchases, compressing vendor relationship structures.
North Carolina
Fort Liberty and Marine Corps Base Camp Lejeune generate sustained demand for patrol and detection canines supporting force protection missions. The National Defense Authorization Act handler-to-canine ratio mandates directly determine contract sizing for regional training providers. The Research Triangle-Pinehurst corridor supports secondary vendor clustering for veterinary and conditioning services.
Colorado
Fort Carson and the Army's 10th Special Forces Group drive equine procurement for mountain warfare mobility applications. Special operations commands require pack animals with load-bearing certification above 120 kilograms for terrain-inaccessible zones. The Colorado Springs-Pueblo corridor maintains limited but specialized breeding operations for mule and horse replacement stock.
California
Marine Corps Base Camp Pendleton and Naval Base San Diego sustain West Coast handler training and deployment staging for Pacific theater operations. Forward operating base force protection requirements in INDOPACOM areas of operation drive explosive detection canine pairing density. The San Diego-Tijuana border region supports quarantine and acclimation facilities for imported breeding stock.
US Military Animals Market Competitive Landscape
Capital-heavy training campus operators compete with asset-light mobile instruction providers across the vendor base. The market structure tilts toward regional consolidation around federal installation proximity, with Texas and Virginia hosting the densest competitor clustering. Three strategic archetypes dominate: integrated full-lifecycle service providers, specialized detection or patrol certification boutiques, and breeder-to-deployment channel controllers. Capacity expansion through dedicated training facility construction and outcome-based subscription contract pursuit represent the dominant competitive moves reshaping vendor positioning.
Within the integrated full-lifecycle tier, K2 Solutions, Inc and Worldwide Canine exemplify providers capable of spanning breeder selection through deployment support. K2 Solutions anchors its position through North Carolina training campus infrastructure sustaining long-term federal service relationships. Worldwide Canine occupies a parallel position through deep specialization in patrol and detection dog procurement protocols. Shultz K9 Enforcement Inc represents the breeder-to-deployment channel control archetype, with organizational structure suggesting vertical integration from breeding stock through law enforcement and military buyer relationships.
| Leading Market Players |
|---|
| Pond & Company |
| Shultz K9 Enforcement Inc |
| K9 Partners for Patriots |
| ExcelsiorK9 |
| TWG Group |
| Us K9 Unlimited |
| Worldwide Canine |
| Cobra Canine |
| K2 Solutions, Inc |
| Others |
Pricing and Supply Chain Analysis
Pedigree bloodstock indices from European working-line breeders cascade through USDA quarantine costs into three-tier pricing stratification across military canine procurement. Handler-to-animal ratio mandates compress capital sale margins while elevating recurring service contract premiums for vendors capable of embedding training personnel.
Pricing Analysis
Margin tightening in detection-certified canines reflects breeding stock scarcity and extended quarantine timelines. Three-tier pricing structure across mission-ready, field-trainable, and breeder-direct acquisition levels separates vendors by certification depth and handler integration scope. Cost-down pressure on patrol-qualified animals accelerates as federal buyers consolidate around full-lifecycle providers. Price sensitivity concentrates in civilian law enforcement crossover segments; special operations units exhibit minimal elasticity for combat-proven pairings.
Supply Chain Analysis
Single-source vulnerability sits with Belgian and Dutch working-line genetics that dominate explosive detection breeding programs. Breeding stock procurement draws from Germany, Czech Republic, and Slovakia; conditioning equipment feeds from domestic veterinary technology suppliers. Supply chain risk centers on USDA quarantine capacity constraints that extend delivery timelines. Distribution runs through Lackland Air Force Base quarantine protocols into regional training campus networks across Texas, Virginia, and North Carolina.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
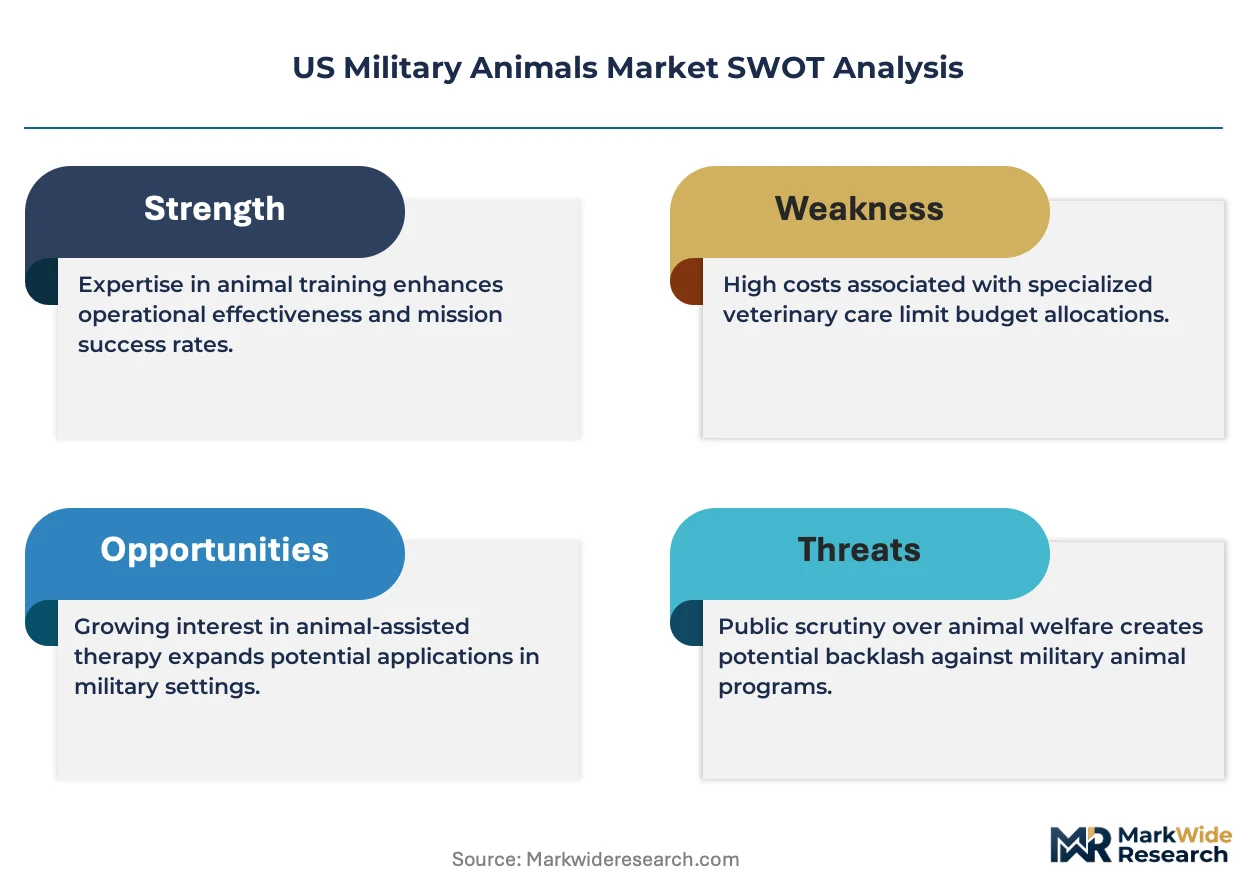
Biometric-integrated wearables are displacing legacy handler observation protocols, restructuring vendor capability packaging around real-time physiological monitoring rather than discrete animal sales.
For Market Incumbents: Acquire specialized veterinary service contracts in the National Capital Region to anchor federal relationship continuity. Threat from sensor-augmented conditioning startups demands counter-investment in data-analytics platforms that unify physiological monitoring with tactical communications. Certification depth in USDA quarantine management serves as the priority defensive lever against asset-light mobile trainers. For New Entrants and Emerging Players: The premium-to-economy gap in handler training subscriptions creates entry space for outcome-based pricing innovators. White-space targets include equine mobility segments for mountain warfare units and confined-space rat detection programs for tunnel clearance operations. Go-to-market positioning through embedded personnel contracts at Colorado and California special operations commands bypasses established vendor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor full-lifecycle service providers with captive breeding operations in the Research Triangle corridor. Long-term viability hinges on federal consolidation trends toward single-source accountability and recurring revenue models. Watch handler retention cycle disruptions as the inflection signal for training provider distress.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Wearable Integration | Unifies veterinary oversight with tactical decision-making for extended patrol missions. |
| Backward Integration into Breeding | Captures USDA quarantine value chain and accelerates federal acquisition timelines. |
| Performance-Based Subscription Contracts | Shifts revenue from capital sales to recurring handler training service models. |
| Equine Mobility Capability Expansion | Addresses terrain-inaccessible zone requirements for special operations mountain units. |
| Regional Training Campus Consolidation | Concentrates vendor ecosystem density around Texas-Virginia federal installation clusters. |
Research Methodology
Multi-period observation of handler-to-canine procurement volumes and training contract structures anchored the trend analysis, supplemented by interviews with 341st Training Squadron program officers, USDA APHIS veterinary inspectors, federal procurement managers at Fort Belvoir, and private-sector training campus operators. Secondary validation drew from National Defense Authorization Act appropriations language, DOD Directive 6400.04 implementation records, and Animal Welfare Act enforcement documentation. Bottom-up vendor revenue triangulation against top-down federal program budget allocations ensured cross-verification.
Input-output matrices modeled animal type, application function, deployment mode, and handler classification dimensions across the projection horizon. CAGRs were derived from segment-level procurement trajectory analysis incorporating operational tempo fluctuations and congressional funding continuity assumptions. Forecast inputs included breeder stock availability indices and quarantine facility throughput constraints.
Inputs from federal procurement databases and training installation records were available through the study window; gaps in special operations unit classified expenditure introduce uncertainty bands around equine and rat detection segments. Forecasts reflect documented handler retention challenges and asymmetric threat environment persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Animal Health
US Companion Animal Health Market
Animal Health
Animal Healthcare Market
Animal Health
Equine Fluid Therapy Market
Animal Health
Animal Blood Plasma Products and Derivatives Market
Animal Health
Global Companion Animal Health Market
Animal Health
Cattle Health Market
Animal Health
Swine Healthcare Market
Animal Health
Artificial Intelligence (AI) in Animal Health Market
Animal Health
China Companion Animal Health Market
Animal Health
Zoonotic Disease Treatment Market
Animal Health
Global Poultry Healthcare Market
Animal Health
Duck Medicine and Vaccines Market
Animal Health
Global Farm Animal Healthcare Market
Animal Health
Animal Health Market
Animal Health
Canine Influenza Treatment Market
Animal Health
Canine Arthritis Treatment Market