
 Animal Healthcare Market | 2026-2036
Animal Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Healthcare Market Analysis
Asset-light contract manufacturing and royalty-based licensing is rewriting competitive entry barriers for mid-tier animal health firms. Zoetis leverages captive biologics production across multiple continents to sustain margin capture on complex vaccines. Boehringer Ingelheim anchors its position through deep R&D integration in parasiticide development. Merck Animal Health competes by controlling distribution networks that reach farm-level veterinary channels directly.
Animal healthcare encompasses the prevention, diagnosis, and treatment of disease in domestic and production animals through pharmaceuticals, biologicals, nutritional interventions, and diagnostic modalities, with formulations typically requiring species-specific pharmacokinetic profiling and cold-chain stability between two and eight degrees Celsius. The primary commercial purpose centers on maintaining animal productivity, welfare compliance, and food safety across protein supply chains. Vaccines and pharmaceuticals command the largest revenue pools within product type segments, reflecting recurring herd health protocols and patent-protected biologics. Molecular diagnostics represents the fastest-expanding technology category as point-of-care PCR platforms displace centralized laboratory workflows. Companion animals generate premium pricing multiples compared to livestock applications, though livestock volumes dominate absolute unit consumption.
The FDA Veterinary Feed Directive restricts medically important antimicrobial use in feed, compelling pharmaceutical reformulation toward ionophores and vaccines. The EU Green Deal and F-Gas Regulation pressure inhalant anesthetic sourcing, while REACH compliance raises registration costs for imported active ingredients. India's CDSCO and BIS standards create parallel pathways for generic veterinary drug approval that diverge from OECD harmonization. Stakeholders must monitor how antimicrobial stewardship mandates in major protein-exporting nations reshape product portfolios and geographic licensing priorities.
Market Dynamics
Antimicrobial stewardship mandates across major protein-exporting nations are forcing pharmaceutical reformulation toward vaccines and ionophores, compressing legacy antibiotic revenue pools while expanding biologicals registration queues.
Growth Catalysts
- FDA Veterinary Feed Directive:The 2017 restriction on medically important antimicrobial use in feed compels livestock producers toward preventive health protocols, expanding vaccine and nutritional intervention demand.
- Point-of-care PCR platforms:Molecular diagnostics hardware is displacing centralized laboratory workflows in companion animal clinics, accelerating test turnaround and treatment initiation.
- Brazilian export certification requirements:Tightened herd health documentation for European and Asian meat import standards drives systematic vaccination programs among beef and poultry operations.
Market Restraints
- Cold-chain infrastructure gaps:Temperature-controlled distribution between two and eight degrees Celsius remains underdeveloped in sub-Saharan Africa and parts of South Asia, limiting biologics market penetration.
- REACH compliance costs:The EU's chemical registration requirements raise active ingredient approval expenses, disproportionately affecting generic veterinary drug entrants.
- Active pharmaceutical ingredient concentration:Sourcing of key antibiotic precursors and vaccine adjuvants concentrates in Chinese and Indian manufacturing clusters, creating supply vulnerability.
Strategic Opportunities
- Indian generic veterinary pathways:CDSCO and BIS standards create parallel registration routes diverging from OECD harmonization, enabling faster market entry for reformulated therapeutics.
- EU Green Deal veterinary incentives:Sustainable production mandates and F-Gas Regulation compliance pressures create premium positioning for low-carbon anesthetic and inhalant alternatives.
- Telemedicine-diagnostics convergence:Remote consultation platforms integrated with at-home testing kits open subscription-based chronic disease management for companion animals in suburban United States markets.
Industry Challenges
- Veterinary biologics manufacturing talent:Cell culture and aseptic fill-finish expertise scarcity constrains expansion of captive vaccine production capacity.
- Species-specific pharmacokinetic profiling:Regulatory dossiers require distinct efficacy and safety data across bovine, porcine, and avian species, multiplying clinical trial costs and timelines.
- Legacy practice management system integration:Diagnostic data from new PCR platforms often lacks interoperability with established veterinary clinic software, complicating workflow adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Healthcare Market |
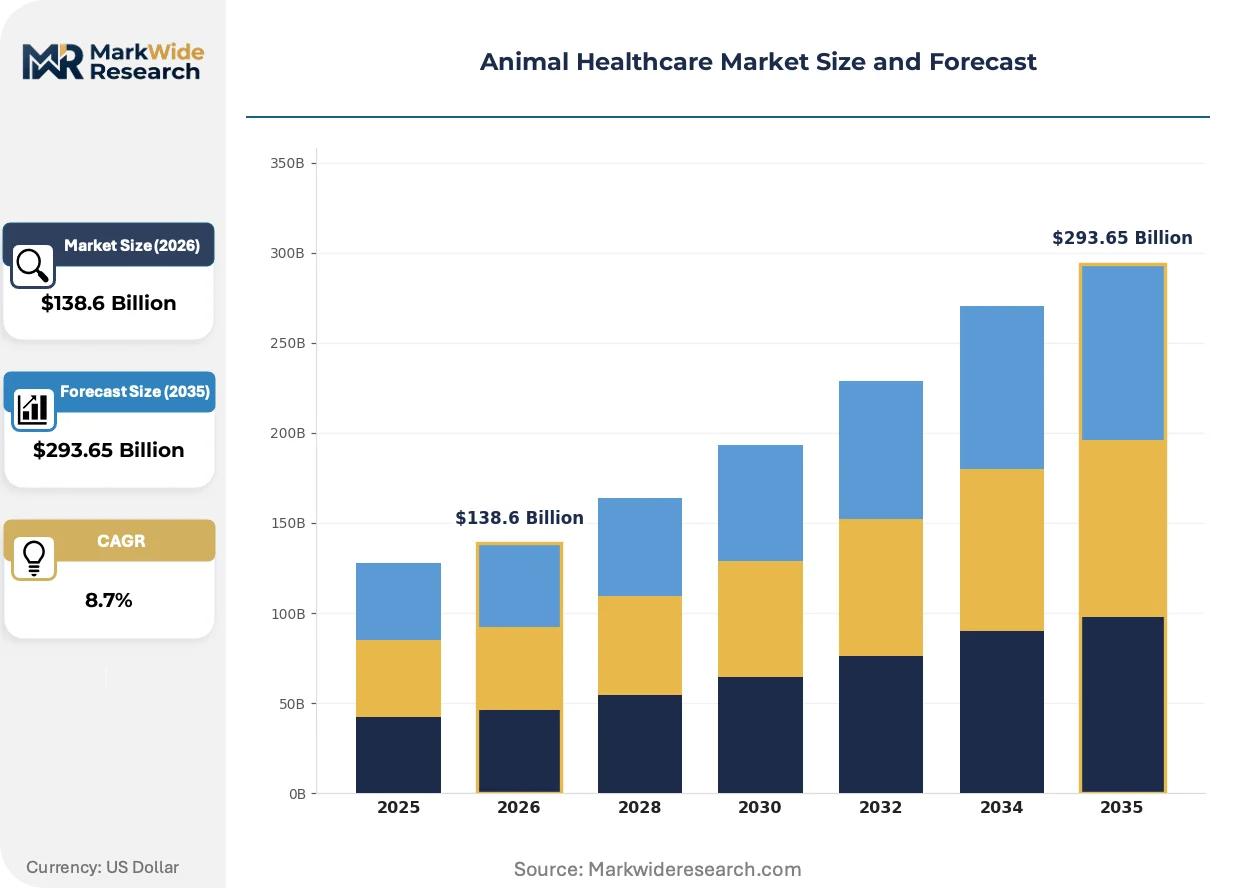
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $293.65 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Pharmaceuticals, Feed Additives, Diagnostics End User: Veterinary Clinics, Animal Hospitals, Farm Owners, Research Institutions Technology: Analytical Techniques, Molecular Diagnostics, Medical Imaging, Biotechnology Application: Companion Animals, Livestock, Aquaculture, Wildlife Conservation |
| Companies Covered | Zoetis, Merck Animal Health, Boehringer Ingelheim, Elanco Animal Health, Ceva Santé Animale, Virbac, Vetoquinol, IDEXX Laboratories, Phibro Animal Health Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Healthcare Market Emerging Trajectories
Digital health infrastructure and biologicals manufacturing advances are restructuring how animal health products reach end-users, with implications for pricing power and channel control.
Recombinant vector vaccines are migrating from experimental platforms to commercial livestock protocols. Major poultry integrators in the United States and Brazil now specify these products in contract grower requirements. The technology is migrating from premium companion animal applications toward cost-sensitive production animal segments, compressing margins on conventional attenuated vaccines.
The EU's F-Gas Regulation and parallel EPA phase-down schedules for hydrofluorocarbon anesthetics are forcing veterinary clinics to evaluate isoflurane and sevoflurane alternatives. Equipment retrofit costs and retraining requirements burden small-practice veterinarians most heavily. Western European markets are responding fastest through incentive programs for desflurane conversion and total intravenous anesthesia adoption.
Pet owners in metropolitan United States and United Kingdom markets now demand diagnostic transparency before consenting to treatment. This behavior compresses the traditional veterinarian-as-gatekeeper model, with pet insurance portals and direct-to-consumer reference labs capturing patient data relationships. The shift is most visible in oncology and chronic renal disease management, where second-opinion remote pathology services proliferate.
Animal Healthcare Market Segmentation
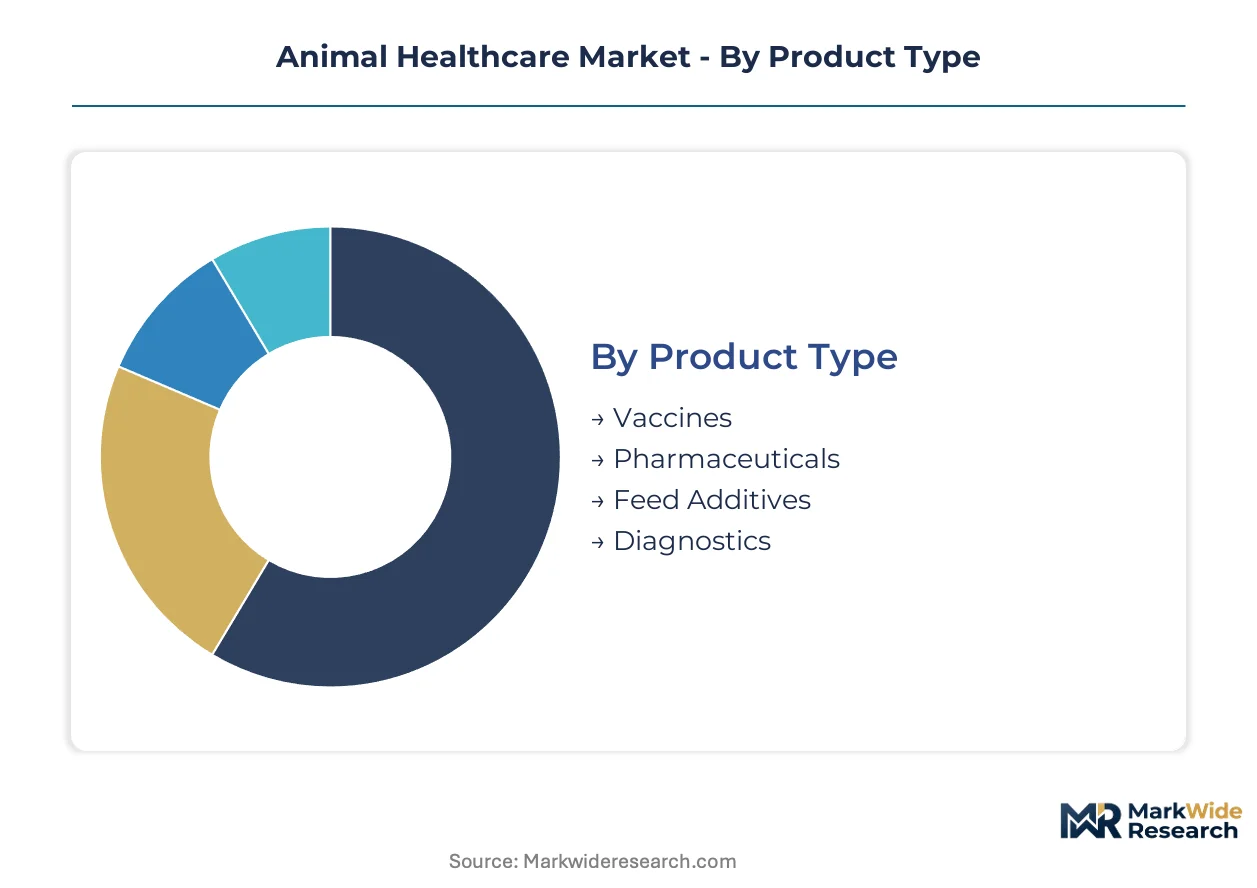
Animal healthcare segmentation reveals divergent margin structures across species applications and technology platforms. Product portfolios must reconcile cold-chain biologics infrastructure with point-of-care diagnostic economics. End-user channel control determines pricing power more than formulation differentiation alone.
Product Type:
Mature categories anchor revenue stability while emerging platforms reshape competitive entry barriers.
- Vaccines:Attenuated and recombinant vector formulations require aseptic fill-finish capacity and two-to-eight-degree Celsius distribution networks. Brazilian beef integrators and United States poultry operators now mandate systematic vaccination protocols under tightened export certification standards.
- Pharmaceuticals:Small-molecule therapeutics span antimicrobials, parasiticides, and anti-inflammatories with species-specific pharmacokinetic dossiers. FDA Veterinary Feed Directive restrictions on medically important antibiotics compel reformulation toward ionophores and vaccines.
- Feed Additives:Nutritional interventions include probiotics, enzymes, and acidifiers for gut health optimization.
- Diagnostics:Point-of-care PCR platforms displace centralized laboratory workflows in companion animal clinics.
Vaccines retain volume leadership; diagnostics holds the steepest expansion curve.
End User:
Channel concentration varies sharply between institutional procurement and fragmented farm-level purchasing.
- Veterinary Clinics:Small-practice veterinarians in suburban United States and Western Europe markets drive premium diagnostic adoption. Pet insurance penetration and direct-to-consumer lab portals compress traditional gatekeeper economics.
- Animal Hospitals:Referral centers concentrate advanced imaging, oncology protocols, and surgical anesthesia. EU F-Gas Regulation compliance pressures retrofit isoflurane and sevoflurane equipment toward desflurane alternatives.
- Farm Owners:Livestock producers in India and Brazil expand herd health programs as protein export requirements tighten.
- Research Institutions:Contract research organizations and academic veterinary schools support regulatory dossier development.
Farm owners dominate absolute unit consumption; animal hospitals capture the highest pricing multiples.
Technology:
Platform maturity determines capital intensity and regulatory pathway complexity.
- Molecular Diagnostics:PCR and sequencing platforms enable pathogen identification at point-of-care. United Kingdom and metropolitan United States pet owners now demand diagnostic transparency before treatment consent.
- Biotechnology:Recombinant vector vaccines and monoclonal antibody production require cell culture expertise. Major poultry integrators specify these products in contract grower requirements.
- Analytical Techniques:Immunoassays and chromatography support reference laboratory confirmation.
- Medical Imaging:Digital radiography and ultrasound systems penetrate companion animal referral networks.
Biotechnology commands the deepest R&D investment; molecular diagnostics is climbing the fastest.
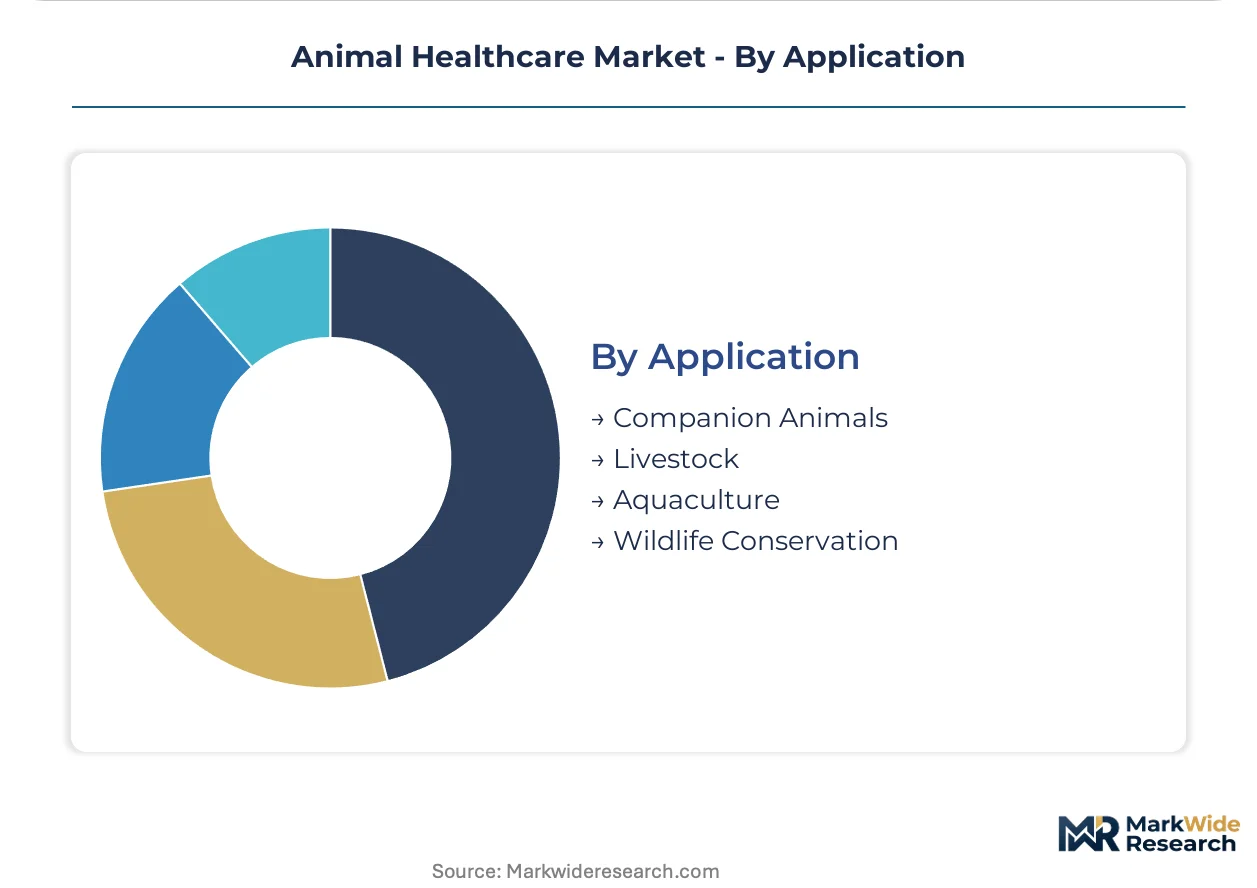
Application:
Species economics separate premium pricing environments from volume-driven commodity markets.
- Livestock:Cattle, swine, and poultry operations consume the majority of vaccine and pharmaceutical volumes. Export certification requirements in Brazil and India drive systematic health protocol adoption.
- Companion Animals:Canine and feline applications generate pricing multiples several times livestock equivalents. Chronic disease management in suburban United States markets opens subscription-based telemedicine-diagnostic convergence.
- Aquaculture:Fish health products face distinct cold-chain and water-borne delivery challenges.
- Wildlife Conservation:Translocation medicine and endangered species breeding programs represent niche demand.
Livestock retains volume leadership; companion animals holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Livestock integrators in Brazil and companion animal clinics in the United States concentrate procurement authority, while export certification requirements in India and antimicrobial regulations across the European Union reshape product registration priorities.
United States
Suburban companion animal clinics drive premium diagnostic adoption as pet insurance penetration climbs. The FDA Veterinary Feed Directive restricts medically important antimicrobial use in feed, compelling reformulation toward vaccines and ionophores. Kansas and Iowa host major livestock pharmaceutical distribution hubs serving integrated poultry and swine operations.
Brazil
Beef and poultry integrators mandate systematic vaccination protocols under tightened European and Asian meat import standards. ANVISA registration pathways govern veterinary pharmaceutical approval timelines. São Paulo and Paraná concentrate contract grower operations specifying recombinant vector vaccines in health protocols.
Germany
Small-practice veterinarians face EU F-Gas Regulation compliance pressures for anesthetic equipment retrofit. REACH chemical registration requirements raise active ingredient approval costs for imported generics. Baden-Württemberg and Bavaria anchor reference laboratory networks supporting centralized diagnostic workflows.
India
Livestock producers expand herd health programs as protein export certification requirements tighten. CDSCO and BIS standards create parallel registration routes diverging from OECD harmonization. Maharashtra and Gujarat concentrate generic veterinary drug manufacturing clusters serving domestic and African markets.
China
Domestic vaccine production scales to reduce import dependency for avian and porcine biologics. The national pharmaceutical regulator enforces cold-chain distribution standards between two and eight degrees Celsius. Shandong and Jiangsu provinces concentrate active pharmaceutical ingredient manufacturing for antibiotic precursors and vaccine adjuvants.
Animal Healthcare Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a consolidated top tier and fragmented mid-market. Three strategic archetypes dominate: captive biologics manufacturers with multi-continent production networks, parasiticide-focused R&D integrators, and diagnostic platform specialists with point-of-care hardware. Competitive moves concentrate on distribution network control and asset-light contract manufacturing partnerships.
Among the integrated pharmaceutical tier, Zoetis and Merck Animal Health exemplify channel-controlling archetypes with direct farm-level veterinary reach. Boehringer Ingelheim occupies a position representing deep R&D integration in parasiticide development. These three entities anchor the premium tier where margin capture depends on cold-chain biologics infrastructure and species-specific pharmacokinetic dossiers.
| Leading Market Players |
|---|
| Zoetis |
| Merck Animal Health |
| Boehringer Ingelheim |
| Elanco Animal Health |
| Ceva Santé Animale |
| Virbac |
| Vetoquinol |
| IDEXX Laboratories |
| Phibro Animal Health Corporation |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Chinese and Indian active pharmaceutical ingredient clusters determines both margin compression in generic veterinary antibiotics and the geographic shape of cold-chain biologics distribution. Tariff exposure on vaccine adjuvant imports feeds directly into pricing tier spreads between captive-manufactured biologics and outsourced formulations.
Pricing Analysis
Cost-plus contracts with API price indexation dominate generic pharmaceutical procurement between Indian manufacturers and Brazilian livestock integrators. Price differentiation rests on cold-chain certification grade and species-specific pharmacokinetic dossier completeness. Pricing pressure stems from REACH compliance cost pass-through in European generic registrations. Small-practice veterinarians in Western Europe exhibit highest price sensitivity; companion animal referral centers in the United States show lowest.
Supply Chain Analysis
Export-control restrictions on recombinant vector vaccine technology limit flow of cell culture platforms from OECD nations to emerging manufacturing hubs. Supply concentrates in China for antibiotic precursors, India for generic API synthesis, and the United States for biologics fill-finish. Key inputs include porcine trypsin, bovine serum albumin, and specialized plastic primary packaging. Single-source vulnerability concentrates in adjuvant sourcing. Distribution runs through veterinary distribution cooperatives reaching farm-level channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell culture and aseptic fill-finish expertise scarcity constrains expansion plans across the competitive tier, making captive biologics manufacturing capability the decisive asset for margin defense.
For Market Incumbents: Entrench position by deepening backward integration into vaccine adjuvant production and securing multi-continent fill-finish redundancy. The threat of recombinant vector vaccine margin compression from Brazilian contract grower procurement mandates demands preemptive capacity addition in São Paulo state. Channel control through direct farm-level veterinary relationships remains the priority lever against generic entrants. For New Entrants and Emerging Players: Pursue white-space opportunity in point-of-care PCR platform software interoperability for United States suburban clinics. The most penetrable segment sits in telemedicine-diagnostics convergence for chronic companion animal disease management. A subscription-based go-to-market angle bypasses incumbent distribution lock-in. For Investors and Strategic Acquirers: The FDA Veterinary Feed Directive implementation reshapes the acquisition landscape toward preventive health protocol enablers. Long-term viability across the analysis window favors targets with captive biologics infrastructure and species-specific dossier libraries. Watch for antimicrobial stewardship mandate acceleration in major protein-exporting nations as the signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Temperature-controlled distribution networks unlock biologics penetration in sub-Saharan African markets. |
| Regulatory Dossier Harmonization | CDSCO and BIS alignment accelerates generic veterinary drug entry into Indian livestock channels. |
| Point-of-Care Platform Integration | PCR hardware and software bundling displaces centralized laboratory workflows in companion animal clinics. |
| Recombinant Vector Vaccine Scale-Up | Cell culture capacity additions meet Brazilian poultry integrator contract specifications. |
| Telemedicine-Diagnostic Convergence | Remote consultation platforms capture subscription revenue from United States suburban pet owners. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA Veterinary Feed Directive filings, EMA regulatory submissions, ANVISA registration databases, and OECD veterinary pharmaceutical harmonization protocols. Interviews with livestock pharmaceutical distribution managers, veterinary clinic procurement leads, biologics manufacturing operations directors, and generic API sourcing specialists informed demand-side validation. Trade data from Indian DGFT export records and Brazilian beef integrator contract specifications anchored supply-side triangulation. Bottom-up product-type volume builds and top-down macroeconomic cross-checks ensured consistency.
Forecast inputs span species application splits, technology platform adoption curves, and regulatory pathway timelines across the projection horizon. Segmentation dimensions include product type, end-user channel, technology platform, and species application. CAGRs derive from weighted average of historical trajectory and forward-looking regulatory inflection points. Veterinary biologics manufacturing capacity expansion schedules and antimicrobial stewardship mandate implementation pace serve as industry-specific forecast inputs.
Sensitivities concentrate around cold-chain infrastructure buildout pace in emerging markets and export certification requirement tightening in major protein-exporting nations. Forecasts reflect assumptions on regulatory harmonization progress and API sourcing concentration stability. Material shifts in FDA antimicrobial restriction scope or EU F-Gas Regulation enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Animal Health
Equine Fluid Therapy Market
Animal Health
Global Farm Animal Healthcare Market
Animal Health
Swine Health Market
Animal Health
Laboratory Animal Models Market
Animal Health
Animal Health Software Market
Animal Health
Companion Animal Ear Infection Treatment Market
Animal Health
Companion Animal Healthcare Market
Animal Health
Canine Mammary Tumor Treatment Market
Animal Health
Animal Blood Plasma Products and Derivatives Market
Animal Health
Canine Influenza Treatment Market
Animal Health
Cattle Health Market
Animal Health
Global Companion Animal Health Market
Animal Health
China Companion Animal Health Market
Animal Health
Equine Healthcare Market
Animal Health
Artificial Intelligence (AI) in Animal Health Market
Animal Health
Canine Arthritis Treatment Market