
 Cattle Healthcare Market | 2026-2036
Cattle Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Cattle Healthcare Market Intelligence
The market for advanced biologics, including genomic-based vaccines, is consolidating around R&D-intensive firms, while the commodity segment for basic parasiticides remains fragmented. Zoetis Inc. leverages its extensive portfolio and direct-to-farmer channels to command the premium vaccine space. In contrast, Elanco Animal Health competes effectively through a balanced offering of both innovative and essential health products. Boehringer Ingelheim differentiates with its strong focus on preventative care and biosecurity solutions for large herds.
Cattle healthcare encompasses the suite of pharmaceuticals, biologics, and medicated feed additives used to prevent and treat diseases in bovine species. These products, such as recombinant protein vaccines or long-acting injectable antibiotics, are formulated to ensure herd productivity and food safety. Within the product landscape, vaccines represent the fastest-growing category, driven by a shift towards disease prevention. Meanwhile, demand from commercial farmers for comprehensive parasite control programs continues to anchor the parasiticides segment, which remains a significant revenue contributor.
Regulatory frameworks set by the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) heavily influence product development, particularly concerning antibiotic withdrawal times and residue limits. These standards, often adopted by importing nations, create stringent market access requirements for all manufacturers. Consequently, navigating the evolving landscape of animal welfare and antimicrobial resistance regulations is a critical strategic imperative for stakeholders.
Market Dynamics
The central dynamic shaping the cattle healthcare market is the global regulatory clampdown on antimicrobial use, exemplified by policies from the US FDA and EMA. This pressure is forcing a structural pivot from reactive antibiotic treatments toward preventative care, fundamentally altering product development priorities and farmer purchasing behavior.
Growth Catalysts
- Intensification of Livestock Farming:Increased demand for beef and dairy in nations like Brazil and India necessitates higher-density farming, which in turn requires more sophisticated disease prevention and control programs to maintain herd health and productivity.
- Advancements in Biotechnology:The development of genomic tools and CRISPR-based diagnostics allows for the creation of highly specific vaccines and therapies, addressing previously untreatable conditions and improving intervention efficacy.
- Food Safety and Traceability Mandates:Regulations such as the EU's Farm to Fork Strategy are compelling producers to adopt higher health standards, boosting demand for products that support auditable and transparent food supply chains.
Market Restraints
- High Development and Regulatory Costs:The significant capital investment and lengthy timelines required for clinical trials and approvals from bodies like the EMA and FDA limit the entry of new, innovative products, particularly from smaller companies.
- Pathogen Resistance:The evolution of resistance to existing classes of parasiticides and antimicrobials diminishes product effectiveness over time, requiring continuous and costly research to develop new modes of action.
- Limited Cold Chain Infrastructure:In key emerging markets across Africa and parts of Asia, inadequate refrigerated transport and storage facilities constrain the distribution and viability of sensitive biologics like vaccines.
Strategic Opportunities
- Expansion in Underserved Geographies:There is significant opportunity to introduce modern biologics and diagnostics into the rapidly professionalizing dairy and beef sectors of countries in Southeast Asia and Eastern Europe.
- Digital Herd Management Integration:Developing health products that integrate with digital platforms, sensors, and data analytics offers a pathway to provide outcome-based, precision medicine solutions for large-scale farming operations.
- Antibiotic-Alternative Development:Growing regulatory restrictions on antibiotics create a clear market for novel non-antibiotic treatments, including bacteriophages, prebiotics, and immunomodulators, to manage common bovine diseases.
Industry Challenges
- Veterinary Professional Shortage:A persistent lack of qualified veterinarians and animal health technicians in many rural cattle-producing regions globally hinders the proper administration and adoption of advanced healthcare products.
- Complex Global Product Registration:Navigating disparate and evolving regulatory requirements for product registration across multiple jurisdictions, such as the US, EU, and China, creates significant operational burdens and delays market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cattle Healthcare Market |
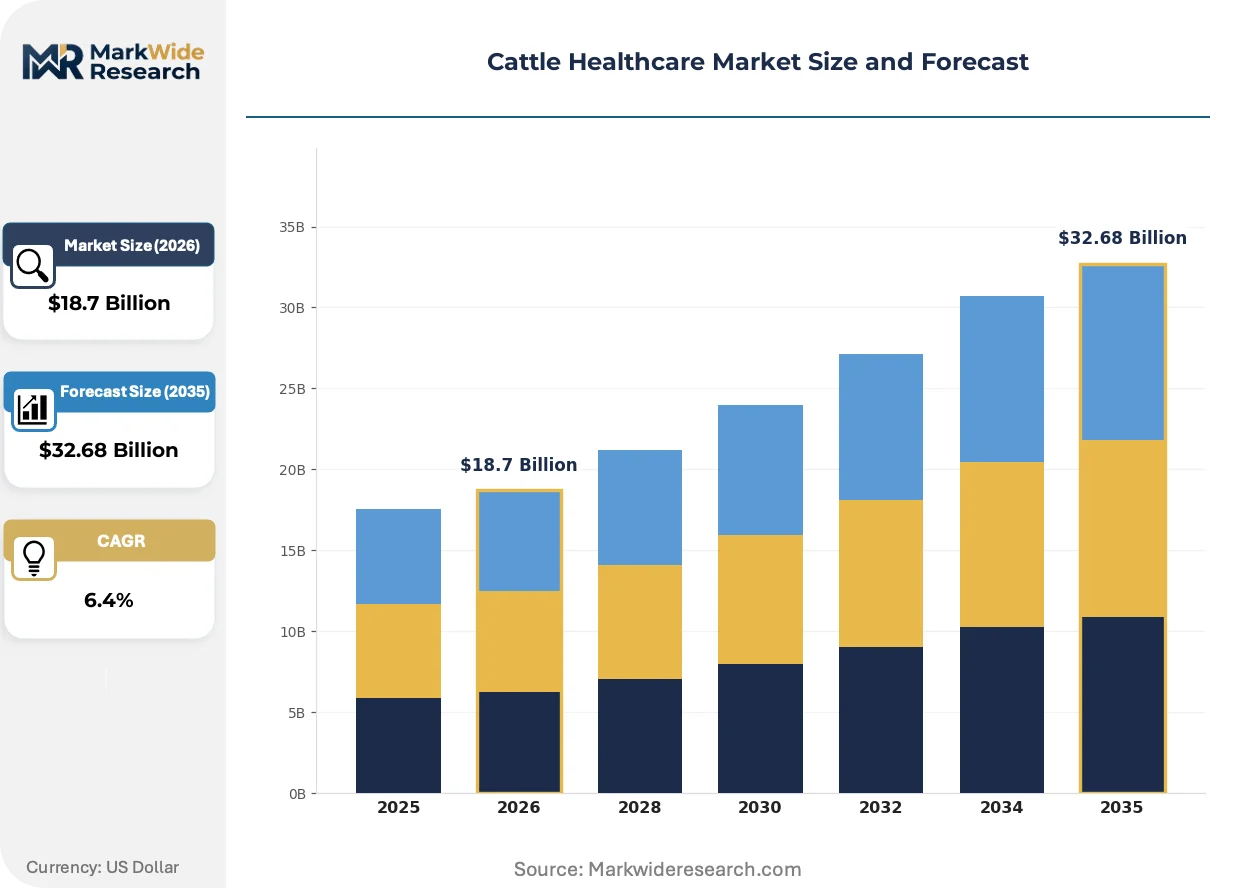
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antibiotics, Feed Additives, Parasiticides, Disinfectants Application: Disease Prevention, Growth Promotion, Parasite Control, Reproductive Health End User: Commercial Farmers, Smallholders, Veterinary Clinics, Animal Husbandry Cooperatives Delivery Method: Injectable, Oral, Topical, Inhalation |
| Companies Covered | Zoetis Inc., Elanco Animal Health, Boehringer Ingelheim, Merck Animal Health, Ceva Animal Health, Bayer AG, Virbac, IDEXX Laboratories, Intas Pharmaceuticals Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cattle Healthcare Market Strategic Shifts & Innovations
The convergence of biotechnology and data analytics is actively reshaping the market, shifting the focus from treating individual sick animals to managing population health with precision. This movement is underpinned by innovations in diagnostics, evolving regulatory landscapes, and new producer-supplier relationships.
Genomic sequencing is a key diagnostic tool that identifies specific pathogens and genetic markers for disease susceptibility. Large commercial dairy farms and feedlots in North America and Australia are leading the adoption of this technology for herd screening. This data-driven approach is consolidating herd health strategies around targeted, preventative protocols rather than broad-spectrum, reactive treatments.
Regulatory frameworks are increasingly harmonized around antimicrobial stewardship. For instance, policies from the US Food and Drug Administration (FDA) restricting the over-the-counter sale of medically important antibiotics are being mirrored by similar initiatives from the European Medicines Agency (EMA). The biologics segment, particularly vaccines, is the primary beneficiary of this shift as producers seek compliant preventative measures.
A notable behavioral shift is occurring as large-scale producers move from simple transactional purchases to adopting comprehensive herd health programs. This model often involves direct consultation and service agreements with manufacturers, bypassing traditional distribution channels for routine products. This trend is most advanced in the highly consolidated beef feedlot sector in the United States, where health outcomes are directly linked to financial performance.
Cattle Healthcare Market Segmentation

The cattle healthcare market segments across product types, applications, end users, and delivery methods, reflecting the diverse needs of bovine health management. Understanding these distinct segments reveals where innovation is concentrating and how farmer purchasing behaviors are evolving.
Product Type:
Supply concentration in product types is evident in the specialized manufacturing of advanced biologics and pharmaceuticals for cattle. These products target specific health challenges across various farming systems.
- Vaccines:These biologics stimulate immune responses to prevent infectious diseases like Bovine Viral Diarrhea. Demand from commercial farmers in Brazil and the United States is high, driven by stringent herd health standards and disease prevention mandates.
- Parasiticides:These compounds control internal and external parasites in cattle, including dewormers and pour-ons. The segment remains a significant revenue contributor, with demand anchored by comprehensive parasite control programs for high-density feedlots.
- Antibiotics:These pharmaceutical agents treat bacterial infections, often administered as long-acting injectables. Regulatory frameworks from the US FDA and EMA are increasingly restricting their use, shifting focus to prevention.
- Feed Additives:These supplements are incorporated into feed to enhance digestion, immunity, or growth performance. They are widely used in intensive farming operations to optimize productivity.
- Disinfectants:Chemical agents used to sanitize farm environments and equipment, preventing pathogen spread. Biosecurity protocols on large commercial farms drive consistent demand for these solutions.
Vaccines absorb the bulk of installed capacity; feed additives are expanding most quickly.
Application:
The application segments delineate the primary health objectives that cattle healthcare products serve, from preventative measures to specific therapeutic interventions. Each application addresses distinct challenges in bovine management.
- Disease Prevention:This category encompasses products and strategies aimed at averting illness before it occurs, such as vaccinations and biosecurity measures. The global regulatory clampdown on antimicrobial use is accelerating demand for preventative solutions.
- Parasite Control:Products and programs designed to manage and eliminate internal and external parasites, which can severely impact animal health and productivity. Commercial farmers in Australia and North America actively implement comprehensive parasite control strategies.
- Growth Promotion:Products, including specific feed additives and hormones, that enhance the growth rate and feed conversion efficiency of cattle. This application is particularly relevant in beef production systems seeking to maximize output.
- Reproductive Health:Solutions focused on improving fertility, managing breeding cycles, and addressing reproductive disorders in cattle. Dairy operations and breeding farms utilize these products to optimize herd reproduction rates.
Disease prevention commands the largest share of farmer spending; reproductive health solutions are gaining traction.
End User:
Customer type defines the scale and operational characteristics of the purchasers, influencing product formulation, packaging, and distribution channels. Each end-user group has unique requirements for cattle healthcare solutions.
- Commercial Farmers:Large-scale operations managing extensive herds for beef or dairy production, characterized by high volume purchases and a demand for advanced, integrated health management systems. These farmers prioritize productivity and regulatory compliance.
- Veterinary Clinics:Professional healthcare providers that diagnose, treat, and administer a wide range of cattle health products directly to individual animals or small herds. They serve as key intermediaries for product distribution and expert advice.
- Smallholders:Farmers managing smaller herds, often for subsistence or local markets, who typically require more accessible and cost-effective healthcare solutions. Their purchasing decisions are often influenced by local availability and basic needs.
- Animal Husbandry Cooperatives:Organizations that pool resources for collective purchasing and often provide shared veterinary services to member farmers. These cooperatives facilitate access to healthcare products for a broader base of producers.
Commercial farmers drive the majority of product demand; veterinary clinics represent a critical distribution channel.
Delivery Method:
The delivery method segment categorizes how cattle healthcare products are administered, impacting efficacy, ease of use, and farmer compliance. Different methods suit varying product types and operational needs.
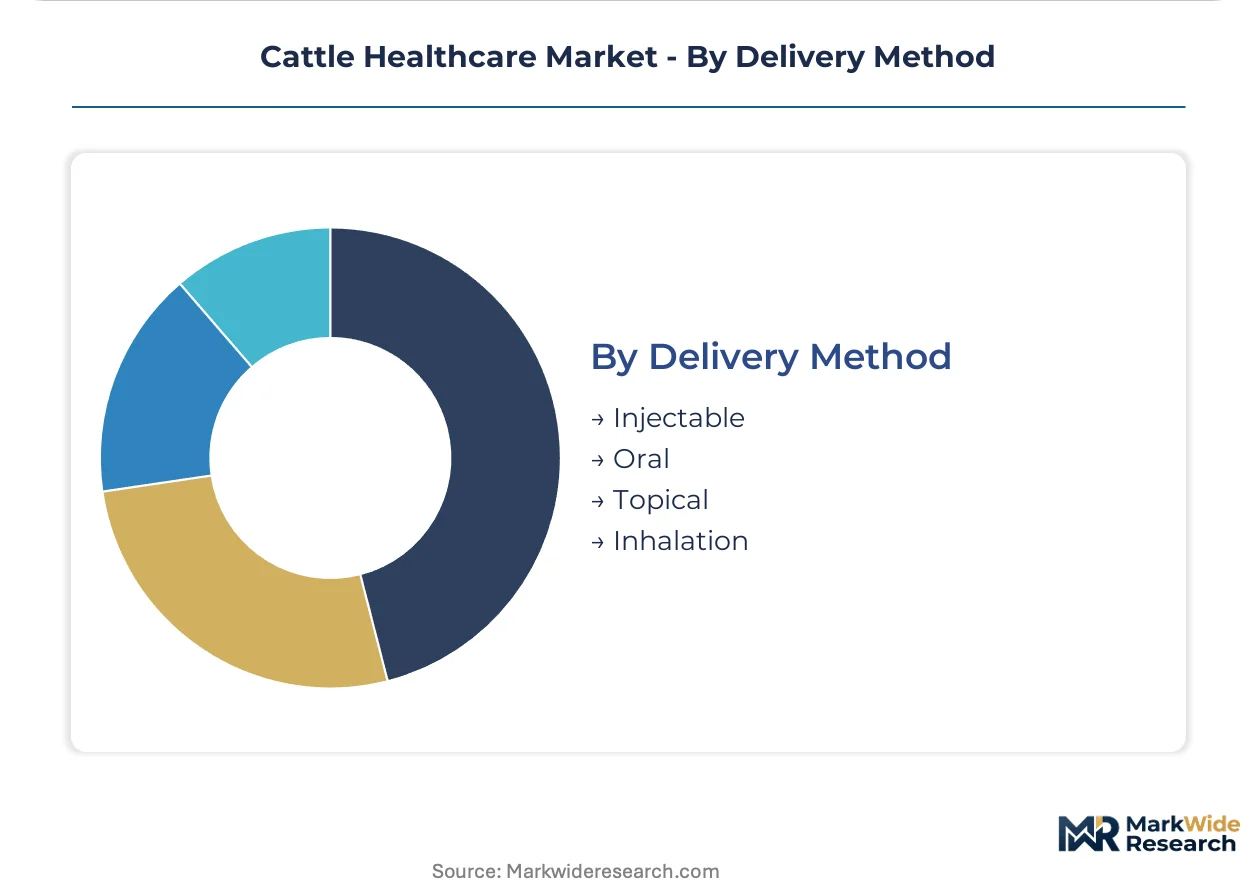
- Injectable:Products administered via injection, including many vaccines and long-acting antibiotics, offering precise dosing and systemic action. This method is common for rapid absorption and sustained release formulations.
- Oral:Products given by mouth, such as medicated feed additives, drench formulations, or boluses, providing convenient mass treatment or daily supplementation. Oral delivery is often preferred for ease of administration in large herds.
- Topical:Applications directly to the skin surface, commonly used for parasiticides like pour-ons or wound treatments. This method provides localized action and minimizes systemic exposure.
- Inhalation:Products delivered through the respiratory tract, primarily for treating respiratory diseases, though less common than other methods for general cattle healthcare. Inhalation requires specialized equipment for effective administration.
Injectable methods dominate product administration; oral delivery is experiencing significant adoption growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's extensive cattle farming regions drive significant demand for advanced biologics and preventative health solutions. The city serves as a hub for veterinary pharmaceutical distribution and research, supporting Brazil's large beef and dairy export industries. This concentration ensures robust market activity for cattle healthcare products.
Brazil
Brazilian cattle producers demand high-quality vaccines and parasiticides to maintain herd health for global beef exports. The Ministry of Agriculture, Livestock, and Food Supply (MAPA) enforces strict animal health regulations, boosting product demand. The Mato Grosso region, with its vast cattle ranches, actively adopts advanced health protocols to ensure export compliance.
United States
Commercial feedlots in the United States require comprehensive disease prevention programs, particularly for respiratory and digestive ailments. The US Food and Drug Administration (FDA) regulations on antibiotic use are accelerating the shift towards vaccines and non-antibiotic alternatives. The Texas Panhandle, a major feedlot concentration, sees high adoption of precision health management technologies.
Germany
European dairy and beef operations, particularly in Germany, prioritize preventative care to meet stringent animal welfare and food safety standards. The European Medicines Agency (EMA) influences product development, focusing on reduced antibiotic dependency and residue limits. Bavaria's intensive dairy farms frequently engage with veterinary practices for advanced health monitoring and vaccination schedules.
India
India's growing dairy sector, driven by domestic milk consumption, necessitates improved reproductive health and disease control solutions. The country's national animal health policies are promoting vaccination campaigns against prevalent bovine diseases. The Gujarat region, with its large cooperative dairies, increasingly invests in feed additives and diagnostics to enhance productivity.
Australia
Australian beef producers, focused on export markets, require robust parasite control and vaccine programs for herd resilience. The Australian Pesticides and Veterinary Medicines Authority (APVMA) regulates product approvals, emphasizing efficacy and environmental safety. The Queensland beef industry, a major export hub, employs extensive health management for large-scale grazing operations.
Cattle Healthcare Market Key Industry Players
Premium-margin players sit above commodity-margin players across product innovation and R&D investment. The market exhibits a tiered structure, with R&D-intensive firms dominating advanced biologics while commodity segments remain fragmented. Strategic archetypes include innovation-driven specialists, diversified portfolio providers, and essential product suppliers. Companies primarily engage in strategic partnerships for technology co-development and targeted geographic expansion.
On the premium-tier vector, Zoetis Inc. occupies a position as a leader in advanced vaccine solutions, leveraging its extensive portfolio. Elanco Animal Health exemplifies a diversified provider, balancing innovative and essential health products across its offerings. Boehringer Ingelheim sits within the innovation-driven specialist archetype, emphasizing preventative care and biosecurity solutions for large herds.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Elanco Animal Health |
| Boehringer Ingelheim |
| Merck Animal Health |
| Ceva Animal Health |
| Bayer AG |
| Virbac |
| IDEXX Laboratories |
| Intas Pharmaceuticals Ltd. |
| Others |
Cost & Logistics Intelligence
Genomic sequencing and advancements in biotechnology are driving up R&D costs for novel biologics, simultaneously concentrating supply among specialized firms. This shift reconfigures pricing power towards innovation-intensive players.
Pricing Analysis
Outcome-based pricing models are gaining traction, especially for advanced biologics and integrated herd health programs. Price differentiation stems from product efficacy, regulatory compliance (e.g., US FDA approval), and bundled service agreements with manufacturers. Pricing pressure stems from the commodity segment, where basic parasiticides face intense competition from fragmented suppliers. Commercial farmers prioritize long-term value, making them less price-sensitive for premium solutions, while smallholders remain highly sensitive to upfront costs.
Supply Chain Analysis
Brazil's Ministry of Agriculture, Livestock, and Food Supply (MAPA) regulations, alongside US FDA standards, increasingly influence sourcing decisions for pharmaceutical ingredients. Supply concentration for advanced biologics centers in the United States and Europe, drawing from specialized manufacturing capabilities. Raw material dependencies include recombinant proteins, specific excipients, and sterile packaging components. Logistics chokepoints, particularly cold chain infrastructure in emerging markets, present a significant supply chain risk. Distribution runs through direct-to-farmer channels and veterinary clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cattle healthcare market is evolving into a consolidation play, as stringent regulatory frameworks from the US FDA and EMA force smaller, less compliant players to exit. This pressure favors R&D-intensive firms capable of navigating complex product development.
For Market Incumbents:Anticipate further regulatory shifts, such as stricter antimicrobial resistance guidelines, by investing heavily in non-antibiotic alternatives and vaccine platforms. Consolidate market share through strategic acquisitions of specialized biotech firms, securing intellectual property in genomic diagnostics. Strengthen direct-to-farmer channels to counter emerging digital health platforms and maintain customer loyalty. Leverage R&D in genomics to develop next-generation preventative solutions.
For New Entrants and Emerging Players:Smallholders in emerging economies represent an underserved buyer archetype for accessible, cost-effective preventative solutions. Target the rapidly professionalizing dairy and beef sectors in Southeast Asia with basic diagnostic kits and affordable vaccine lines. Focus on digital integration for herd management, offering precision medicine solutions for large-scale operations. A partnership-based go-to-market angle with local veterinary cooperatives can accelerate market penetration.
For Investors and Strategic Acquirers:Exit pathways concentrate in R&D-intensive firms developing novel biologics and digital health platforms for cattle. The long-term viability of the market remains strong, driven by sustained global demand for protein and increasingly stringent food safety standards. Target acquisition profiles include companies with patented antibiotic alternatives or advanced genomic diagnostic capabilities. A signal to watch is the accelerated regulatory approval of non-antibiotic treatments, indicating a market inflection point.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Biologics R&D Investment | Drives innovation in preventative care, crucial for navigating stricter US FDA and EMA regulations. |
| Digital Herd Management Integration | Offers precision medicine solutions, enhancing productivity for commercial farmers in North America. |
| Geographic Expansion into Southeast Asia | Taps into professionalizing dairy and beef sectors, addressing unmet demand for modern biologics. |
| Non-Antibiotic Alternative Development | Addresses global regulatory clampdown on antimicrobial use, creating new market segments. |
| Strategic Partnerships with Biotech Firms | Accelerates access to genomic tools and CRISPR-based diagnostics, enhancing intervention efficacy. |
Research Approach
Independent corroboration across regulatory filings, industry association reports, and academic journals underwrites the qualitative findings. Primary interviews with veterinary practitioners, commercial farmers, and R&D executives provided granular market insights. Secondary validation involved analyzing US FDA and EMA guidelines, alongside publications from the World Organisation for Animal Health. A rigorous bottom-up and top-down triangulation process ensured data accuracy and consistency.
Rate-of-change decomposition underpins the analytical framework, projecting market evolution across the analysis window. Segmentation dimensions modeled include product type, application, end-user, delivery method, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical trends and projected demand shifts, factoring in technological advancements. Key forecast inputs included livestock population growth and evolving antimicrobial stewardship policies.
Revisions become necessary when significant shifts in global trade policies or unforeseen disease outbreaks materialize. Forecasts reflect assumptions regarding regulatory enforcement and adoption rates for new biologics. Geopolitical instability and economic downturns represent additional risk factors for the cattle healthcare market. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Animal Health
US Military Animals Market
Animal Health
Animal Healthcare Market
Animal Health
Global Poultry Healthcare Market
Animal Health
China Companion Animal Health Market
Animal Health
US Companion Animal Health Market
Animal Health
Duck Medicine and Vaccines Market
Animal Health
Artificial Intelligence (AI) in Animal Health Market
Animal Health
Equine Healthcare Market
Animal Health
Canada Animal Health Care Market
Animal Health
Companion Animal Healthcare Market
Animal Health
Swine Healthcare Market
Animal Health
Companion Animal Medicine Market
Animal Health
Swine Health Market
Animal Health
Rat Model Market
Animal Health
Companion Animal Ear Infection Treatment Market
Animal Health
Laboratory Animal Models Market