
 Swine Healthcare Market | 2026-2036
Swine Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Swine Healthcare Market Analysis
Preventive vaccine programs is reconfiguring margin pools away from reactive antimicrobial treatments across commercial pork operations. Zoetis Inc. leverages its portfolio of swine-specific biologics to dominate preventive care segments. Boehringer Ingelheim anchors its position through integrated respiratory disease management platforms. Merck & Co., Inc. competes with reproductive health solutions that sustain sow productivity metrics.
Swine healthcare encompasses veterinary pharmaceuticals, biological products, nutritional interventions, and diagnostic tools formulated for porcine physiology, including temperature-stable vaccine formulations and species-specific pharmacokinetic dosing protocols designed to maintain herd immunity and optimize feed conversion ratios. Vaccines command the largest share of product type revenues as African swine fever preparedness drives biosecurity investment, while feed additives represent the fastest-expanding delivery vector for gut health and growth promotion applications. Injectable delivery modes retain premium positioning for acute therapeutic interventions despite oral administration gaining share in preventive protocols.
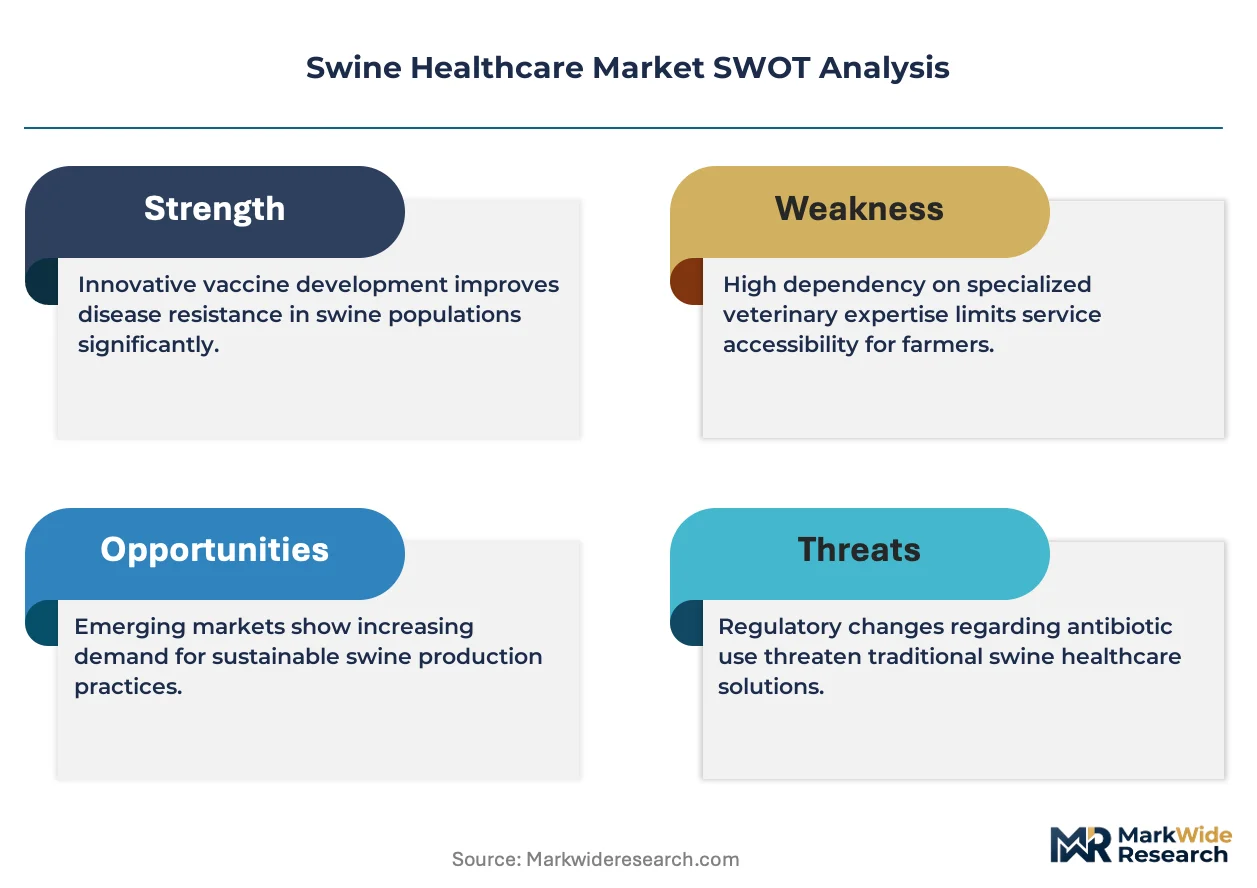
The FDA's Veterinary Feed Directive and EPA antimicrobial discharge guidelines constrain product development pathways and reshape prescribing behaviors among swine veterinarians. China's NMPA and SAMR enforce dual carbon-aligned manufacturing standards that elevate compliance costs for imported pharmaceutical inputs. Stakeholders must monitor evolving residue tolerance thresholds and alternative protein feed additive approvals to align R&D pipelines with regulatory trajectories.
Market Dynamics
The FDA's Veterinary Feed Directive has fundamentally altered prescribing authority for swine veterinarians, transferring feed medication decisions from producers to licensed practitioners and compressing margins for legacy antimicrobial suppliers.
Growth Catalysts
- African swine fever preparedness protocols:Commercial farms in China are accelerating biosecurity infrastructure deployment to prevent catastrophic herd losses. Mandatory vaccination programs are expanding across provincial agricultural departments.
- Carbon-aligned manufacturing mandates:China's SAMR dual carbon standards are redirecting procurement toward low-emission pharmaceutical inputs. This regulatory pressure is stimulating domestic production capacity for temperature-stable vaccine formulations.
- Precision livestock farming sensors:IoT-enabled health monitoring systems are reducing mortality detection lag times. Early disease identification is cutting treatment costs and improving feed conversion ratios across integrated pork operations.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for veterinary applications clusters in eastern China provinces. Geographic concentration creates vulnerability to regional lockdowns and export permit delays.
- Residue tolerance harmonization gaps:Mismatched maximum residue limits between FDA, EMA, and NMPA standards complicate multi-territory product registrations. Formulation adjustments for each jurisdiction inflate development timelines.
- Phytogenic additive substitution:Plant-derived growth promoters are displacing synthetic antibiotic growth promoters in weaner diets. This substitution threat compresses demand for traditional medicated feed additives.
Strategic Opportunities
- Underpenetrated Vietnamese commercial sector:Smallholder-to-industrial transition in the Mekong Delta is creating demand for integrated health management platforms. Foreign veterinary service providers face limited domestic competition.
- mRNA vaccine platform convergence:Human health mRNA manufacturing infrastructure is being repurposed for rapid-response swine pathogen vaccines. Platform flexibility enables accelerated variant-specific formulation.
- Veterinary telemedicine channel expansion:Remote consultation platforms are bypassing traditional distributor networks for prescription delivery. This channel innovation reduces geographic veterinary coverage gaps in rural Iowa and North Carolina production zones.
Industry Challenges
- Swine veterinary workforce shortage:Specialized large-animal practitioners are declining across US land-grant university programs. Recruitment pipelines cannot match commercial farm expansion rates.
- Biologics cold chain capex intensity:Temperature-stable formulation requirements demand substantial capital investment in lyophilization capacity. Smaller manufacturers face barriers to mRNA vaccine production entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Swine Healthcare Market |
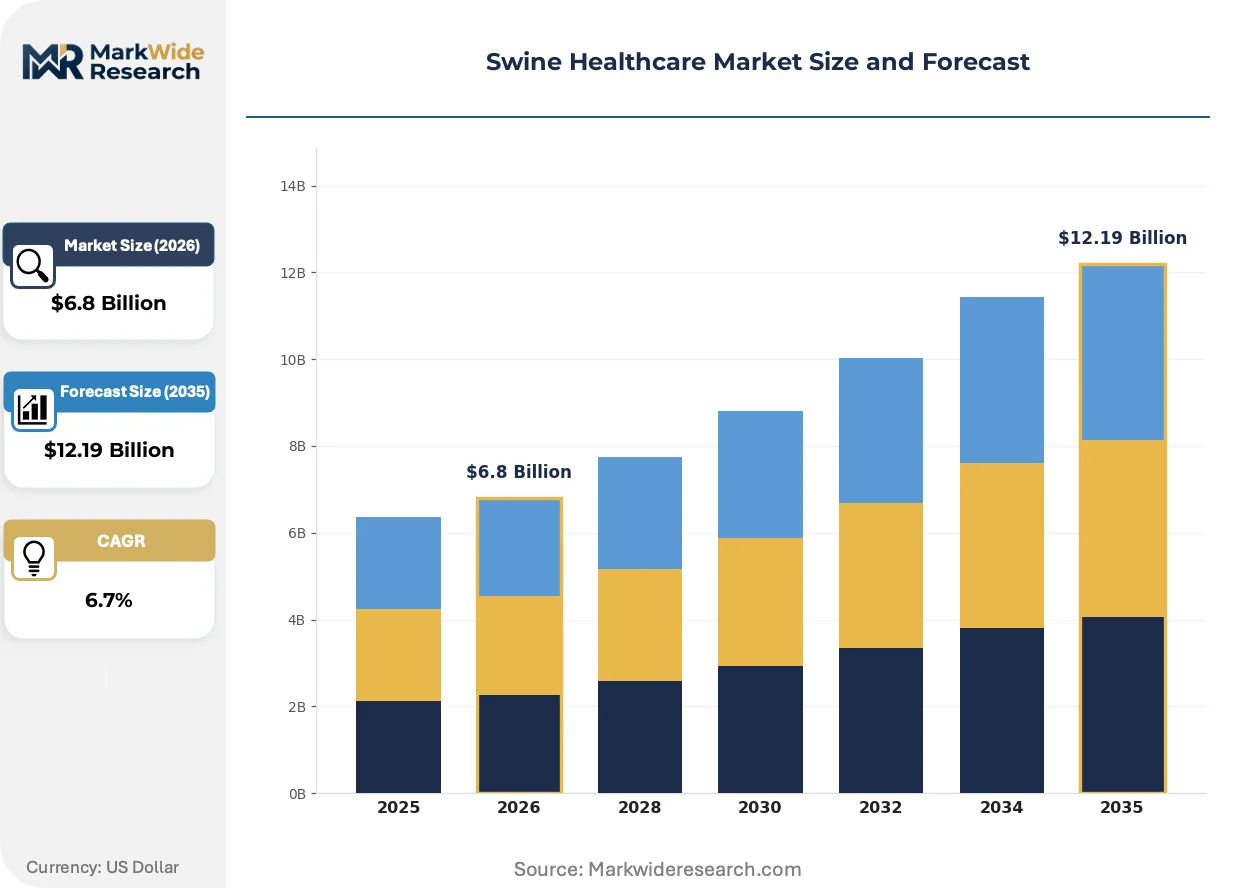
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antimicrobials, Hormones, Feed Additives Delivery Mode: Oral, Injectable, Inhalation, Topical End User: Veterinary Clinics, Farms, Research Institutes, Laboratories Application: Disease Prevention, Growth Promotion, Reproductive Health, Diagnostics |
| Companies Covered | Zoetis Inc., Boehringer Ingelheim, Merck & Co., Inc., Elanco Animal Health, Phibro Animal Health, Orion Pharma, Norbrook Laboratories, Ceva Santé Animale, Virbac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Swine Healthcare Market Emerging Trajectories
Swine healthcare is pivoting toward predictive intervention models that compress disease response windows and eliminate reactive treatment dependencies.
Temperature-stable vaccine formulations are migrating from liquid cold-chain dependence to ambient-stable lyophilized presentations. Large integrated pork producers in Brazil and Thailand are adopting these formats to eliminate refrigeration infrastructure in remote finishing facilities. This migration from cold-chain to ambient-stable delivery is compressing distribution costs and enabling direct-to-farm vaccination programs previously uneconomical.
The EPA's antimicrobial discharge guidelines are tightening effluent standards for concentrated animal feeding operations. Facilities exceeding discharge thresholds now face mandatory veterinary oversight of all therapeutic interventions. Swine operations in the Chesapeake Bay watershed are responding by installing advanced manure treatment systems and shifting preventive vaccine ratios.
Outcome-based health contracts are displacing traditional product procurement across US commercial sow farms. Veterinary service providers now guarantee reproductive performance metrics rather than selling individual pharmaceutical units. This contracting shift is most visible in the Carolina pork production corridor where integrators are consolidating supplier relationships.
Swine Healthcare Market Segmentation
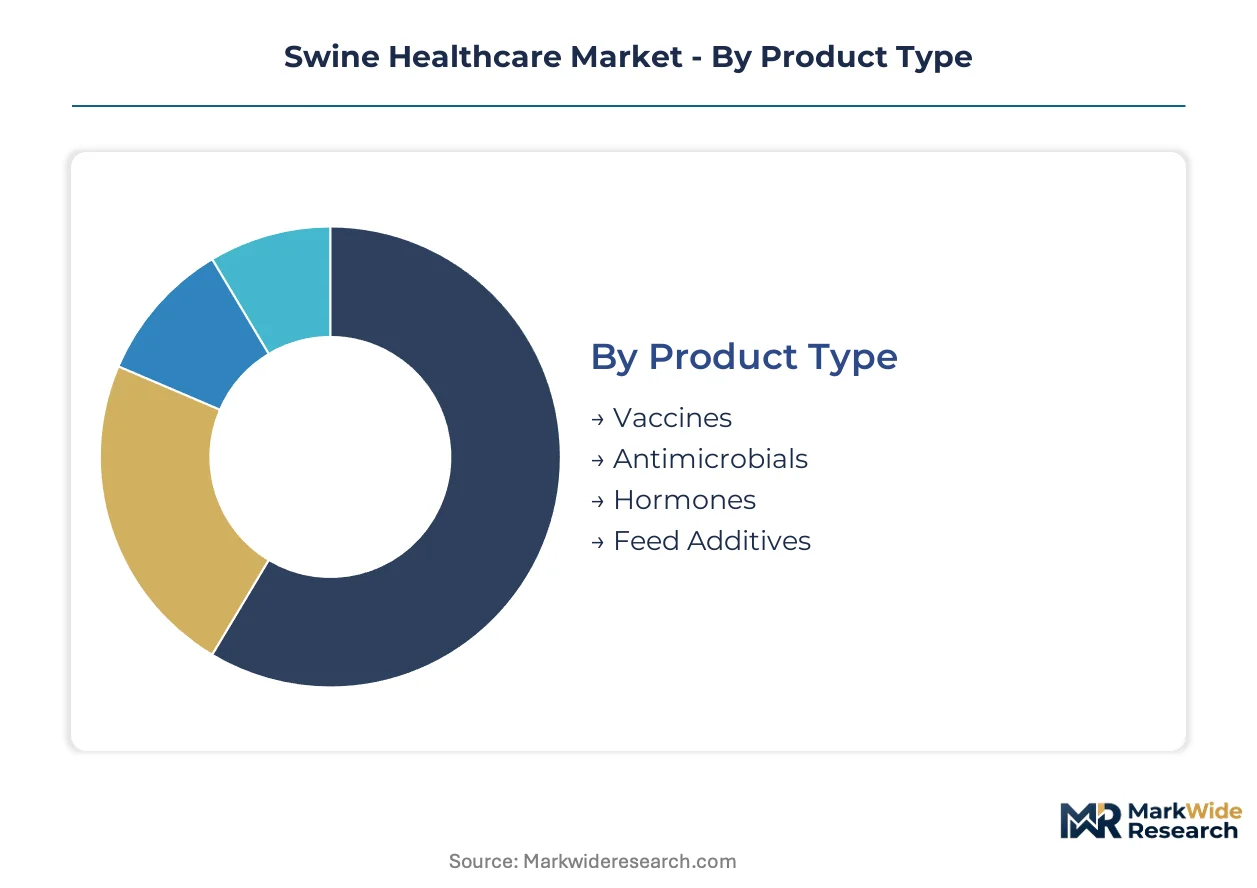
Swine healthcare procurement splits across four dimensions that reshape margin capture and service intensity. Product type determines R&D capital requirements, while delivery mode governs cold-chain infrastructure investments. End-user concentration in integrated pork operations compresses distributor margins. Application focus separates preventive from reactive revenue pools.
Product Type:
After-sales service intensity peaks with biological products requiring cold-chain monitoring and batch traceability, while feed additives demand minimal technical support beyond formulation guidance.
- Vaccines:Temperature-stable and lyophilized formulations eliminate refrigeration dependencies in remote finishing facilities. Demand concentrates in Chinese provincial agricultural departments rebuilding sow inventories after disease outbreaks, with mandatory vaccination programs driving procurement volume.
- Feed Additives:Phytogenic growth promoters and gut health modulators displace synthetic antibiotic growth promoters in weaner diets. Brazilian and Thai integrated producers are expanding additive budgets fastest as carbon-aligned manufacturing mandates elevate input costs.
- Antimicrobials:Injectable therapeutics for acute respiratory and enteric infections face FDA Veterinary Feed Directive prescription constraints.
- Hormones:Reproductive synchronization products sustain sow productivity metrics in large commercial operations.
By volume, vaccines lead. By growth pace, feed additives are expanding most quickly.
Delivery Mode:
Cost tier separation is pronounced: injectable formats command premium pricing for acute interventions, while oral administration gains share in preventive protocols through labor cost advantages.
- Injectable:Intramuscular and subcutaneous delivery ensures rapid therapeutic plasma concentration for critical disease episodes. US commercial sow farms in the Carolina corridor rely on injectable reproductive hormones for precise estrus synchronization.
- Oral:Medicated feeds and water-soluble treatments reduce labor requirements for mass medication. Vietnamese commercial sector transition from smallholder to industrial systems is accelerating oral delivery adoption.
- Inhalation:Nebulized vaccines target respiratory pathogen colonization in nursery pigs.
- Topical:Pour-on parasiticides address external parasite burdens in breeding stock.
By volume, oral administration leads. By growth pace, inhalation delivery is climbing the fastest.
End User:
Customer type determines contract structure: integrated pork operations demand outcome-based performance guarantees, while independent farms purchase individual product units.
- Farms:Commercial pork operations with veterinary staff on payroll drive bulk procurement of vaccines and feed additives. Chinese large-scale producers are consolidating supplier relationships around integrated health management platforms.
- Veterinary Clinics:Independent practitioners serve smaller operations with prescription authority under FDA Veterinary Feed Directive compliance. Rural Iowa and North Carolina production zones face geographic coverage gaps that telemedicine platforms are beginning to address.
- Research Institutes:Academic and government facilities conduct field efficacy trials for novel vaccine candidates.
- Laboratories:Diagnostic service providers process serological surveillance for herd health monitoring.
By volume, farms lead. By growth pace, veterinary clinics are gaining share fastest.
Application:
Maturity varies sharply: disease prevention commands established budgets, while diagnostics represents nascent technology adoption with unproven ROI in commercial settings.
- Disease Prevention:Vaccination programs and biosecurity protocols dominate capital allocation. African swine fever preparedness is redirecting investment toward infrastructure hardening across Chinese commercial operations.
- Growth Promotion:Nutritional interventions optimizing feed conversion ratios attract margin-focused integrators. Phytogenic additive substitution is compressing synthetic antibiotic demand in this application.
- Reproductive Health:Synchronization protocols and fertility monitoring sustain sow herd productivity metrics.
- Diagnostics:PCR and serological testing enables early pathogen detection. IoT-enabled health monitoring sensors are reducing mortality detection lag times in precision livestock farming deployments.
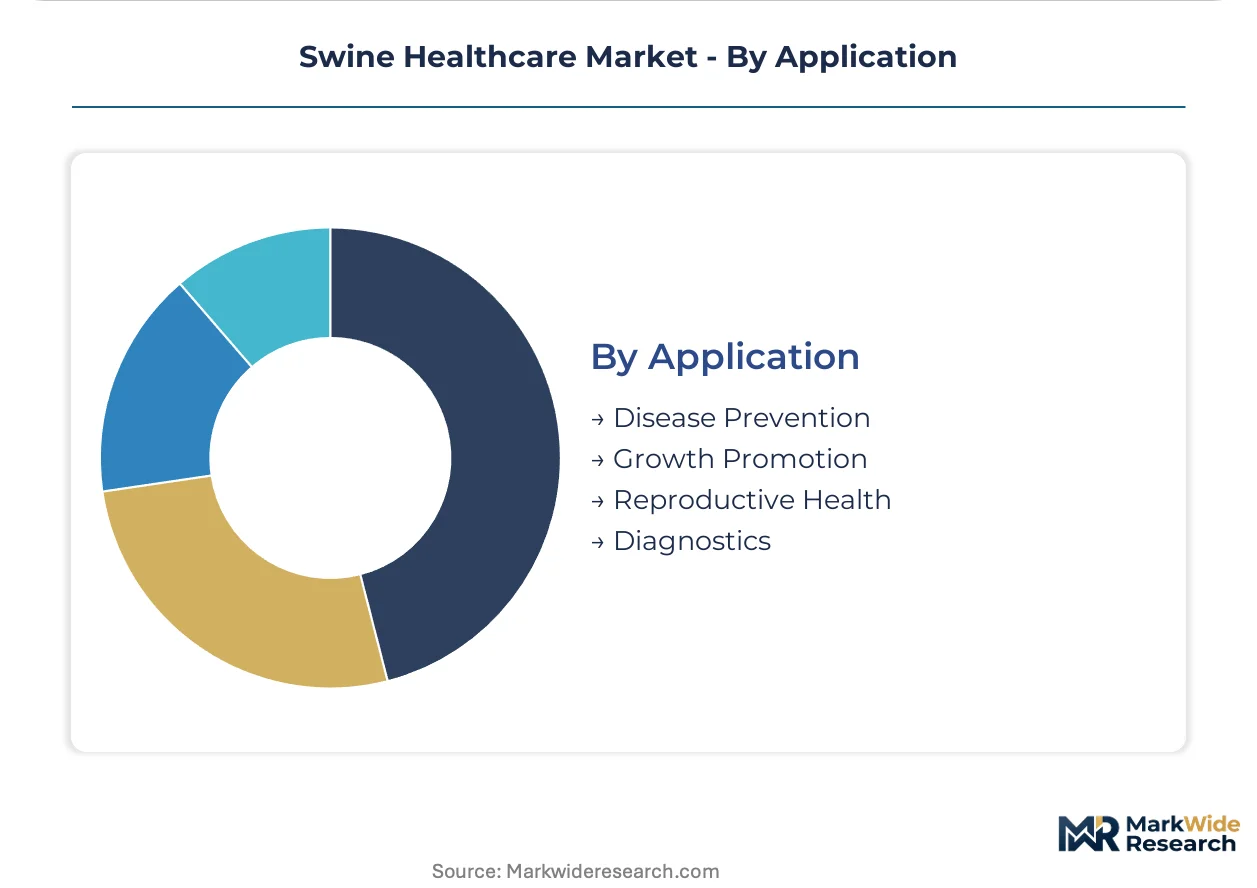
By volume, disease prevention leads. By growth pace, diagnostics shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys swine healthcare products for disease containment at scale, while the United States emphasizes prescription-controlled therapeutics and Brazil prioritizes ambient-stable vaccines for remote logistics.
China
Provincial agricultural departments are mandating vaccination programs as sow inventory rebuilding accelerates following previous disease outbreaks. SAMR enforces dual carbon-aligned manufacturing standards that elevate compliance costs for imported pharmaceutical inputs. Large-scale producers in Guangdong and Sichuan provinces are consolidating supplier relationships around integrated health management platforms.
United States
Commercial farms in Iowa and North Carolina are expanding herd health protocols to reduce antibiotic dependency under veterinary oversight. The FDA's Veterinary Feed Directive continues to reshape prescription requirements for medicated feeds, transferring feed medication decisions from producers to licensed practitioners. Rural production zones face geographic veterinary coverage gaps that telemedicine platforms are beginning to address.
Brazil
Integrated pork producers in Mato Grosso and Santa Catarina are adopting ambient-stable lyophilized vaccine formats to eliminate refrigeration infrastructure in remote finishing facilities. ANVISA regulates veterinary pharmaceutical registrations with residue tolerance standards that influence formulation decisions. The country's commercial sector is expanding additive budgets fastest as carbon-aligned manufacturing mandates elevate input costs.
Germany
Large sow operations in Lower Saxony and North Rhine-Westphalia are shifting toward outcome-based health contracts that guarantee reproductive performance metrics. EMA standards on maximum residue limits complicate multi-territory product registrations for suppliers serving both German and export markets. Precision livestock farming sensor deployments are reducing mortality detection lag times across integrated operations.
Vietnam
The Mekong Delta's smallholder-to-industrial transition is creating demand for integrated health management platforms as commercial sector penetration deepens. The country's national pharmaceutical regulator maintains import permit requirements that create lead time uncertainty for foreign veterinary service providers. Foreign suppliers face limited domestic competition in veterinary service provision as local capacity remains underdeveloped.
Swine Healthcare Market Vendor Landscape
Capability concentration sits with biologics specialists commanding lyophilization expertise and temperature-stable formulation science; scale advantage sits with diversified animal health conglomerates leveraging cross-species manufacturing infrastructure. The market structures around three archetypes: human-health-derived platform repurposers, species-specific biologics pure-plays, and feed-additive-anchored nutrition integrators. Consolidation pressure intensifies through backward integration into active pharmaceutical ingredient sourcing and strategic partnerships for mRNA manufacturing infrastructure access.
Within the biologics pure-play tier, Zoetis Inc. and Boehringer Ingelheim exemplify capability concentration through swine-specific preventive care portfolios, while Merck & Co., Inc. anchors the reproductive health specialization vector. These entities represent divergent strategic postures: one emphasizes respiratory disease management platforms, another prioritizes sow productivity metrics, and the third spans multiple therapeutic categories without species-exclusive focus. Their collective positioning illustrates how scale and specialization trade off in procurement decisions by integrated pork operations.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Boehringer Ingelheim |
| Merck & Co., Inc. |
| Elanco Animal Health |
| Phibro Animal Health |
| Orion Pharma |
| Norbrook Laboratories |
| Ceva Santé Animale |
| Virbac |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese API manufacturing provinces is compressing supplier margins and forcing consolidation among veterinary pharmaceutical intermediaries. This utilization squeeze simultaneously elevates bargaining power for large integrated pork operations while squeezing smaller feed additive formulators.
Pricing Analysis
Long-term offtake contracts dominate vaccine procurement by Chinese provincial agricultural departments rebuilding sow inventories. Three-tier pricing structure across premium lyophilized formulations, standard liquid vaccines, and economy-grade feed additives separates procurement tiers. Pricing pressure stems from SAMR dual carbon compliance costs elevating imported pharmaceutical input expenses. Independent Vietnamese farms show highest price sensitivity, while US commercial sow operations in the Carolina corridor prioritize outcome-based performance guarantees over unit cost.
Supply Chain Analysis
Upstream fermentation capacity for veterinary antibiotics clusters in eastern China provinces, with secondary concentrations in India and limited European specialty production. Active pharmaceutical ingredient manufacturing draws from corn-derived feedstocks, petrochemical solvents, and lyophilization excipients. Single-source vulnerability runs through geographic concentration of temperature-stable vaccine formulation capacity. Distribution runs through veterinary distributor networks consolidating around telemedicine-enabled prescription platforms in rural Iowa and North Carolina production zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment around FDA Veterinary Feed Directive prescription authority creates substantial switching costs for commercial pork operations.
For Market Incumbents: Pre-empt phytogenic additive substitution by accelerating backward integration into fermentation capacity for gut health modulators. Lock in exclusive lyophilization partnerships with mRNA platform repurposers before human-health infrastructure pivots to veterinary applications. Channel control through telemedicine platform acquisition addresses geographic veterinary coverage gaps threatening prescription volume.
For New Entrants and Emerging Players: Vietnamese commercial sector underpenetration offers lowest competitive density for integrated health management platforms. Target Mekong Delta smallholder-to-industrial transition with ambient-stable vaccine formats eliminating cold-chain infrastructure requirements. Partner with provincial agricultural departments on mandatory vaccination program tenders to bypass established distributor relationships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across mRNA vaccine manufacturing infrastructure as temperature-stable formulation requirements demand lyophilization capacity expansion. Long-term viability favors acquisition targets with captive API sourcing and species-specific biologics portfolios. Monitor EPA antimicrobial discharge guideline enforcement intensity as signal for preventive vaccine demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilization Capacity Expansion | Enables ambient-stable vaccine distribution to remote Brazilian finishing facilities without refrigeration infrastructure. |
| Telemedicine Platform Acquisition | Bypasses traditional veterinary distributor networks in rural Iowa and North Carolina coverage gaps. |
| Phytogenic Additive Formulation Partnership | Secures gut health modulator supply chain as synthetic antibiotic growth promoters face FDA prescription constraints. |
| mRNA Manufacturing Infrastructure Licensing | Repurposes human-health platform flexibility for rapid-response African swine fever variant vaccines. |
| Provincial Agricultural Department Contracting | Locks in mandatory vaccination program volumes across Chinese sow inventory rebuilding efforts. |
Methodological Framework
Cross-validation between veterinary pharmaceutical procurement databases and provincial agricultural department tender records anchors the qualitative findings on Chinese demand concentration. Primary interviews with swine veterinarians, feed mill procurement managers, and regulatory affairs specialists at animal health conglomerates combined with secondary validation against FDA Veterinary Feed Directive compliance filings, EPA antimicrobial discharge monitoring reports, and SAMR carbon-aligned manufacturing standards. Bottom-up sow inventory rebuilding trajectories and top-down pharmaceutical input trade flows complete the triangulation.
Calibration against historical vaccine adoption curves and feed additive penetration rates shapes the analytical framework across product type, delivery mode, end user, and application segmentation. Modeled dimensions include preventive versus reactive revenue pools, cold-chain versus ambient-stable logistics requirements, and integrated versus independent farm procurement structures. CAGRs derive from regression analysis of biosecurity investment intensity correlated with disease outbreak frequency. African swine fever preparedness protocol deployment and precision livestock farming sensor adoption serve as industry-specific demand inflection inputs.
Practitioners should monitor NMPA import permit delays and EPA effluent standard tightening for early signals of supply constraint or demand acceleration. Forecasts reflect assumptions on veterinary workforce availability, lyophilization capacity expansion timelines, and phytogenic additive substitution rates. Cross-checking against USDA swine inventory reports and Chinese provincial agricultural department vaccination procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Animal Health
Swine Health Market
Animal Health
Equine Fluid Therapy Market
Animal Health
Cattle Healthcare Market
Animal Health
Global Poultry Healthcare Market
Animal Health
Rat Model Market
Animal Health
US Companion Animal Health Market
Animal Health
Companion Animal Healthcare Market
Animal Health
Animal Health Software Market
Animal Health
Equine Healthcare Market
Animal Health
Laboratory Animal Models Market
Animal Health
Global Companion Animal Health Market
Animal Health
US Military Animals Market
Animal Health
Artificial Intelligence (AI) in Animal Health Market
Animal Health
Zoonotic Disease Treatment Market
Animal Health
Cattle Health Market
Animal Health
Canine Arthritis Treatment Market