
 Tattoo Numbing Cream Market | 2026-2036
Tattoo Numbing Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Tattoo Numbing Cream Market Analytics
Aftercare product bundling is reshaping margin-pool migration between standalone numbing cream sales and integrated session kits in the tattoo services ecosystem. Dr. Numb leverages its brand recognition across North American professional channels to sustain premium positioning without direct retail dilution. Zensa Skin Care anchors its portfolio on clean-label formulations that compete effectively in the consumer-direct segment. Aspen Pharmacare Australia Pty Ltd dominates distribution across Oceania through pharmacy-aligned regulatory pathways.
Tattoo numbing cream constitutes a topical anesthetic formulation typically containing lidocaine, prilocaine, benzocaine, or tetracaine at concentrations between 4% and 5%, designed to block sodium channels in dermal nerve endings prior to needle penetration during cosmetic or medical tattooing procedures. Cream-based formulations lead the product type landscape due to established occlusion techniques and predictable onset timing, while gel variants represent the fastest-growing format among mobile artists prioritizing rapid absorption and non-greasy residue. Lidocaine-based active ingredient segments occupy the largest share of current volume given its FDA monograph status and extensive clinical documentation, though prilocaine combinations gain traction in European markets where EMA guidelines permit broader compounding flexibility.
The FDA's OTC monograph system for external analgesics and the EPA's manufacturing facility registration requirements jointly govern product legality and production geography for numbing creams distributed in the United States. EMA's Medical Device Regulation and REACH compliance obligations in Europe create divergent formulation standards that fragment cross-border product portability. Stakeholders must monitor evolving state-level tattoo parlor licensing boards that increasingly mandate specific anesthetic disclosure protocols, as these local rules will determine which ingredient portfolios retain commercial viability across fragmented jurisdictional landscapes.
Market Dynamics
Session duration extension in professional tattoo studios is compressing product efficacy thresholds, forcing formulators to engineer longer-duration lidocaine delivery systems that maintain nerve blockade across multi-hour procedures without reapplication.
Growth Catalysts
- FDA OTC Monograph Expansion:The FDA's external analgesic monograph pathway permits 4% lidocaine formulations without prescription requirements, accelerating professional channel penetration in the United States.
- Full-Body Tattoo Normalization:Consumer acceptance of extensive torso and limb coverage in North American studios extends average session lengths beyond traditional numbing cream duration limits.
- Occlusion Technique Standardization:Plastic wrap occlusion methods developed in Australian professional parlors reduce onset time variability, improving artist workflow predictability.
Market Restraints
- Active Ingredient Concentration Ceilings:FDA monograph limits cap lidocaine at 5%, constraining efficacy differentiation for high-pain procedures against compounded pharmacy alternatives.
- Raw Material Supply Concentration:Pharmaceutical-grade lidocaine base production concentrates among Chinese and Indian API manufacturers, exposing formulators to import tariff volatility.
- Vasoconstrictor Interaction Complexity:Epinephrine co-formulation restrictions in cosmetic applications limit duration extension options compared to medical dermatology protocols.
Strategic Opportunities
- Brazilian Regulatory Alignment:ANVISA's emerging cosmetic anesthetic classification framework creates first-mover advantage for compliant formulations in Latin America's largest tattoo market.
- Mobile Artist Channel Development:Single-use sachet formats address sanitation requirements for convention and private-session artists operating outside fixed studio infrastructure.
- Post-Procedure Analgesic Bundling:Integration with healing balms and aftercare kits captures margin migration from standalone numbing sales toward comprehensive session packages.
Industry Challenges
- State Licensing Board Disclosure Mandates:California and New York tattoo parlor regulations now require ingredient list posting, forcing reformulation of proprietary blends to maintain competitive secrecy.
- Cross-Border REACH Compliance:European ECHA substance notification requirements for prilocaine-containing products fragment formulation portfolios between US and EU production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tattoo Numbing Cream Market |
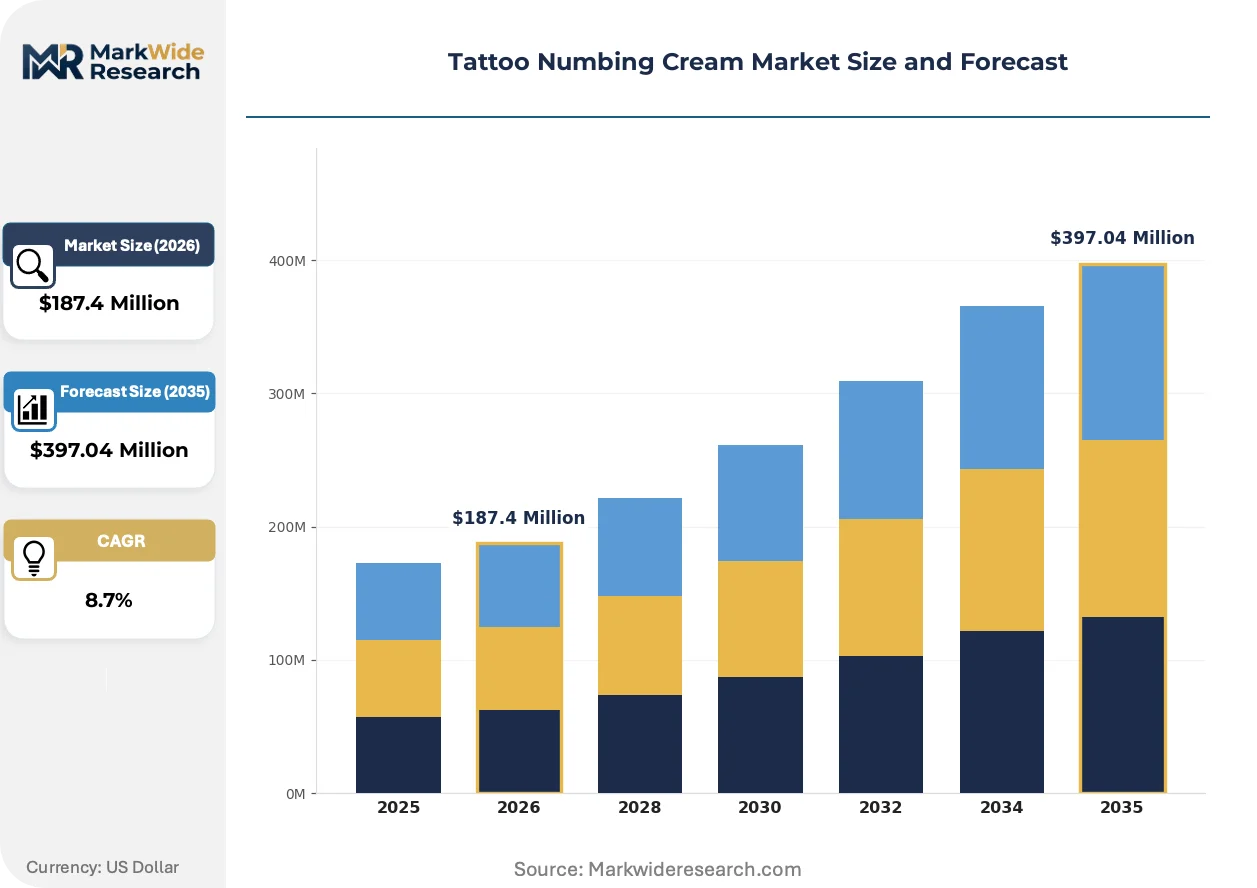
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cream, Spray, Gel, Ointment Active Ingredient: Lidocaine, Prilocaine, Benzocaine, Tetracaine End User: Tattoo Artists, Consumers, Clinics, Studios Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Zensa Skin Care, Dr. Numb, Hera Beauty Ltd, Tattoo Numbing Cream Co., Aspen Pharmacare Australia Pty Ltd, Centura Pharmaceuticals, TattooNumbx, Painless Topical Anaesthetic Cream, Toochi Tattoo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tattoo Numbing Cream Market Evolving Landscape
Formulation chemistry and regulatory geography are diverging simultaneously, with delivery mechanism innovation running ahead of harmonized safety standards across major markets.
Liposomal encapsulation technology is rendering obsolete conventional oil-in-water emulsion bases by extending lidocaine release duration from 90 minutes to four hours. Full-session artists in Los Angeles and Miami studios have adopted these advanced formulations at premium price points. The technology is compressing reapplication frequency requirements, reducing artist workflow interruption and improving client throughput economics.
EMA's Medical Device Regulation reclassification of certain topical anesthetic delivery systems is forcing manufacturers to pursue CE marking pathways previously reserved for surgical equipment. German and French regulators now interpret tattoo numbing applications as borderline medical devices when marketed with specific pain-reduction claims. Formulators targeting European distribution are bifurcating product lines between cosmetic and medical-grade positioning to navigate divergent conformity assessment routes.
Consumer-direct subscription models for pre-tattoo preparation kits are displacing studio-based point-of-sale procurement in metropolitan markets. Younger demographic segments in Australian and Canadian cities prefer advance online ordering with telehealth consultation add-ons. This channel rotation concentrates brand loyalty with e-commerce-native suppliers rather than studio-affiliated distributors.
Tattoo Numbing Cream Market Segmentation
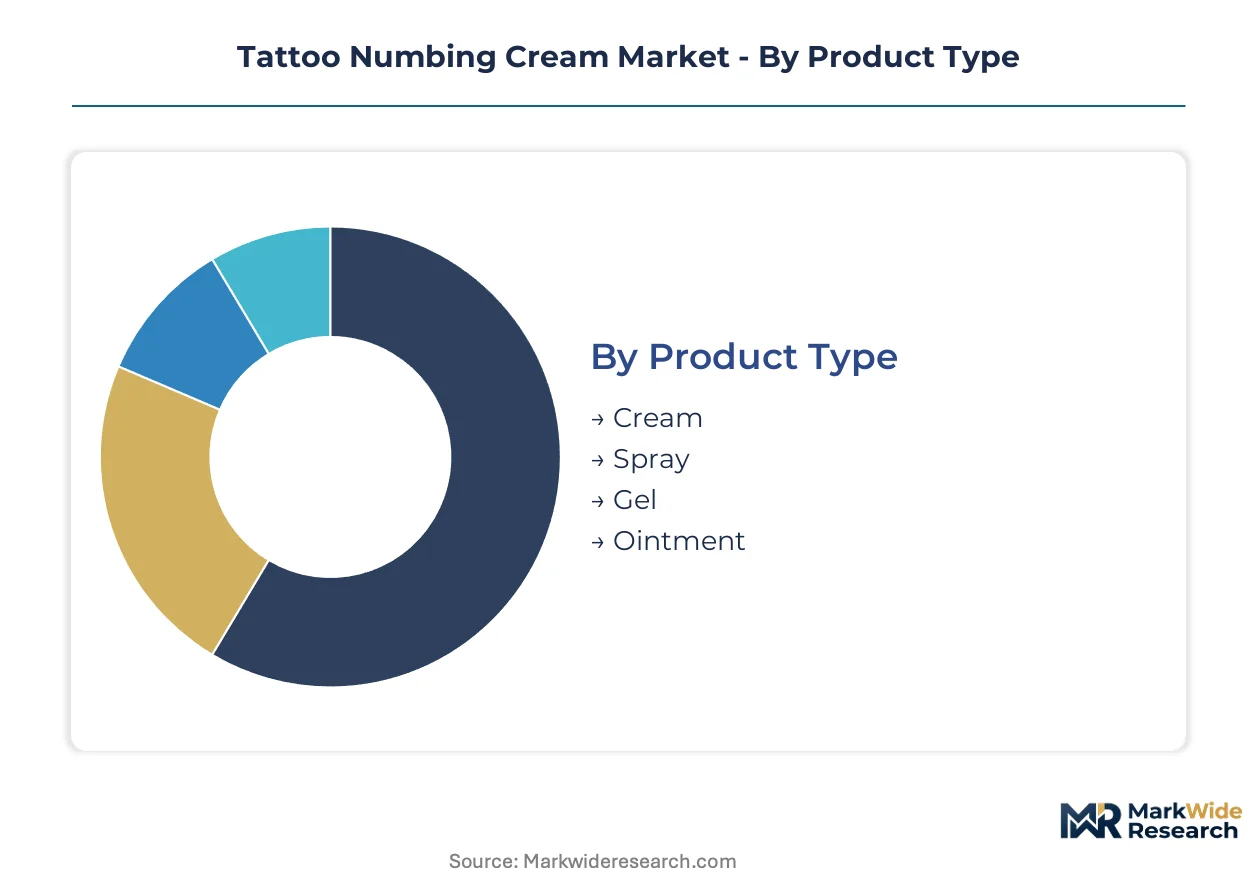
Tattoo numbing cream segmentation reflects divergent workflow requirements between fixed studio infrastructure and mobile practitioner environments. Formulators must balance occlusion timing, absorption rates, and regulatory compliance across distinct end-use scenarios.
Product Type:
The use-case spectrum spans prolonged occlusion protocols in professional studios to rapid-onset applications for convention artists.
- Cream:Oil-in-water emulsion bases enable standardized plastic wrap occlusion techniques with predictable 30-45 minute onset windows. Los Angeles and Miami studios favor these formulations for full-session back pieces requiring sustained nerve blockade across multiple hours.
- Gel:Rapid-absorption polymer matrices eliminate greasy residue and reduce artist cleanup time between clients. Mobile practitioners operating at Australian tattoo conventions prioritize this format for its workflow efficiency and sanitation compatibility.
- Spray:Aerosolized delivery systems target hard-to-reach anatomical areas with minimal product waste. The format appeals to self-application consumers preparing for smaller cosmetic procedures.
- Ointment:Petrolatum-based carriers provide extended skin contact duration for medical tattooing applications in dermatology clinics.
The dominant share belongs to Cream, while Gel is closing the gap fastest.
Active Ingredient:
Regulatory approval pathways determine geographic commercial viability more than pharmacological efficacy differentials.
- Lidocaine:Amide-class anesthetic with established FDA OTC monograph status at 4-5% concentrations. US distributors leverage this regulatory clarity to bypass prescription requirements, concentrating volume in North American professional channels.
- Prilocaine:EMA guidelines permit broader compounding flexibility for this amide derivative, enabling higher-concentration formulations in German and French markets where medical device classification rules apply.
- Benzocaine:Ester-class compound faces FDA scrutiny regarding methemoglobinemia risk, limiting its deployment primarily to consumer-direct cosmetic applications with shorter duration claims.
- Tetracaine:Potent ester anesthetic restricted to clinical settings in most jurisdictions due to toxicity profile, finding niche use in medical tattooing procedures.
Lidocaine commands the largest installed base, though Prilocaine combinations are expanding most quickly in European compounding pharmacies.
End User:
Procurement authority and volume scale separate institutional buyers from individual consumers.
- Tattoo Artists:Independent practitioners purchasing through wholesale distributors represent the volume anchor, with session kit bundling driving recurring order patterns.
- Consumers:Direct-to-patient sales concentrate in metropolitan markets where telehealth consultation add-ons validate pre-procedure preparation purchases.
- Clinics:Medical tattooing facilities in dermatology and reconstructive surgery settings require documentation-heavy procurement with lot traceability mandates.
- Studios:Multi-artist parlors negotiate bulk supply agreements with formulation houses, capturing margin through integrated aftercare package sales.
Studios retain the dominant procurement volume, while Consumers are gaining share fastest through subscription model adoption.
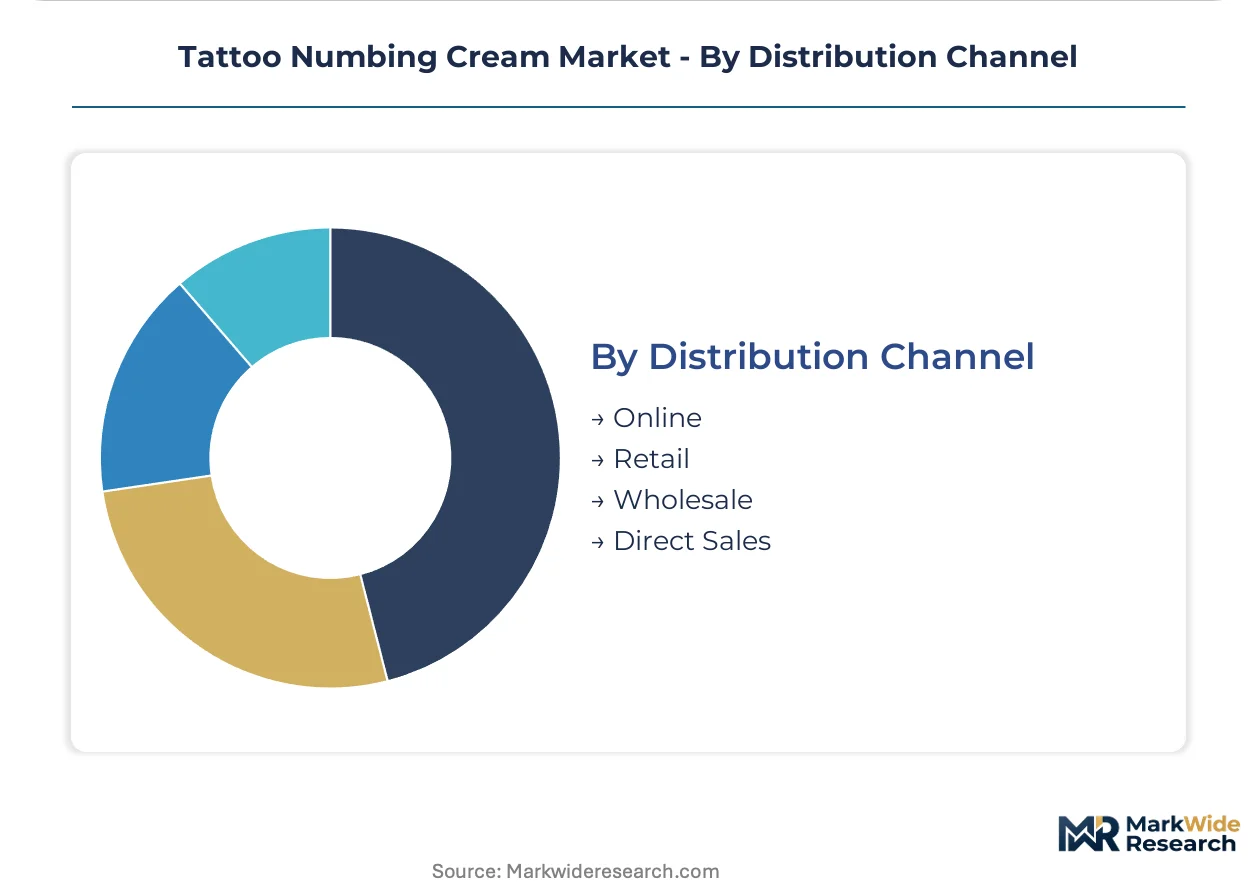
Distribution Channel:
Channel selection determines margin capture and brand control positioning.
- Online:E-commerce-native suppliers concentrate customer loyalty through pre-tattoo kit subscriptions with automated replenishment scheduling.
- Retail:Pharmacy-aligned pathways in Australia and Canada require regulatory compliance documentation that filters out smaller formulation houses.
- Wholesale:Studio-focused distributors maintain inventory depth for same-day replenishment in dense urban tattoo districts.
- Direct Sales:Manufacturer-to-artist relationships preserve margin for premium liposomal formulations with proprietary delivery technology.
Wholesale channels hold the dominant position, though Online is climbing the fastest among younger demographic segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between North American studio-centric procurement and European pharmacy-aligned distribution, with Latin American markets emerging as a regulatory frontier where first-mover compliance advantages concentrate.
United States
Full-body tattoo normalization in Los Angeles and Miami studios extends average session lengths beyond conventional numbing cream duration thresholds. The FDA's OTC monograph system for external analgesics permits 4% lidocaine formulations without prescription requirements, channeling volume through professional wholesale distributors. California and New York state licensing boards now mandate ingredient disclosure protocols, forcing reformulation of proprietary blends.
Germany
EMA's Medical Device Regulation reclassification treats certain topical anesthetic delivery systems as borderline medical devices when marketed with specific pain-reduction claims. Berlin and Hamburg studios navigate bifurcated product lines between cosmetic and medical-grade positioning. REACH compliance obligations for prilocaine-containing products fragment formulation portfolios relative to US production lines.
Australia
Plastic wrap occlusion techniques developed in Sydney and Melbourne professional parlors reduce onset time variability, improving artist workflow predictability. TGA registration pathways for pharmacy-aligned distribution dominate procurement channels. Subscription models for pre-tattoo preparation kits concentrate brand loyalty with e-commerce-native suppliers in metropolitan markets.
Brazil
ANVISA's emerging cosmetic anesthetic classification framework creates first-mover advantage for compliant formulations in Latin America's largest tattoo market. São Paulo and Rio de Janeiro studios drive demand for longer-duration formulations as full-torso work gains popularity. Import tariff exposure on pharmaceutical-grade lidocaine base concentrates margin pressure on local formulators.
United Kingdom
London's dense urban tattoo districts sustain same-day replenishment demand through wholesale distributors with inventory depth. Post-Brexit regulatory divergence from EU REACH standards complicates cross-border product portability for Northern Ireland studios. Consumer-direct telehealth consultation add-ons validate pre-procedure preparation purchases in metropolitan markets.
Tattoo Numbing Cream Market Competitive Landscape
Capability concentration sits with formulation specialists possessing liposomal encapsulation expertise; scale advantage sits with distributors commanding pharmacy-aligned regulatory pathways. The vendor base separates into three tiers: premium liposomal innovators, clean-label consumer-direct brands, and pharmacy-channel incumbents with regional regulatory lock-in. Competitive moves center on geographic regulatory arbitrage and aftercare kit bundling to capture margin migration from standalone numbing sales.
Within the premium professional tier, Dr. Numb leverages brand recognition across North American channels, while Zensa Skin Care anchors clean-label positioning in consumer-direct segments. Aspen Pharmacare Australia Pty Ltd exemplifies pharmacy-aligned regulatory pathway dominance through Oceania distribution infrastructure. These three occupy distinct archetype positions without direct segment overlap.
| Leading Market Players |
|---|
| Zensa Skin Care |
| Dr. Numb |
| Hera Beauty Ltd |
| Tattoo Numbing Cream Co. |
| Aspen Pharmacare Australia Pty Ltd |
| Centura Pharmaceuticals |
| TattooNumbx |
| Painless Topical Anaesthetic Cream |
| Toochi Tattoo |
| Others |
Value Network & Pricing Analysis
Shanghai-to-Los Angeles container rates directly compress margin pools for Chinese API-dependent formulators while amplifying price spreads between pharmacy-channel incumbents and direct-import consumer brands. This freight corridor's volatility feeds into both supply concentration effects and downstream tiering strategies across the tattoo services ecosystem.
Pricing Analysis
Long-term offtake contracts between Australian pharmacy distributors and domestic compounding houses anchor pricing stability for TGA-registered products, while spot-market procurement dominates mobile artist channels in North American convention circuits. Price differentiation rests on FDA monograph compliance tier and liposomal delivery technology certification, with premium formulations commanding substantial spreads over commodity lidocaine creams. Cost compression in the consumer-direct segment is intensifying as subscription models displace studio point-of-sale procurement. Tattoo studios with integrated aftercare bundling show the lowest price sensitivity; self-application consumers purchasing single-unit formats exhibit the highest.
Supply Chain Analysis
Tariff exposure between China and the United States dominates risk calculus for pharmaceutical-grade lidocaine base procurement, forcing formulators to diversify toward Indian and German API sources. Active ingredient production draws from concentrated chemical manufacturing corridors in Shandong Province, Mumbai's pharmaceutical belt, and the Rhine-Ruhr industrial region. Regulatory notification requirements under REACH and state-level disclosure mandates in California and New York fragment formulation portfolios and multiply compliance costs. Distribution runs through three distinct pathways: pharmacy-aligned regulatory channels in Australia and Canada, professional wholesale distributors serving dense urban studio districts, and direct-to-consumer e-commerce platforms with telehealth consultation add-ons.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tattoo numbing cream sits in an early-cycle expansion phase as full-body tattoo normalization extends session durations beyond conventional efficacy thresholds. Liposomal encapsulation technology adoption represents the primary penetration tailwind reshaping competitive positioning.
For Market Incumbents: Entrench pharmacy-channel relationships through exclusive TGA and FDA monograph compliance investments that emerging entrants cannot replicate quickly. Deepen backward integration into liposomal delivery technology R&D to defend margin pools against clean-label consumer-direct challengers. State licensing board disclosure mandates threaten proprietary blend secrecy; respond with patent-protected delivery mechanisms rather than undisclosed ingredient combinations.
For New Entrants and Emerging Players: Establish a beachhead in Brazilian studio markets where ANVISA's emerging cosmetic anesthetic classification creates first-mover regulatory advantages before incumbent pharmacy-channel players pivot. Target mobile artist segments with single-use sachet formats addressing sanitation requirements outside fixed studio infrastructure. Deploy consumer-direct subscription models with telehealth consultation add-ons to bypass wholesale distributor gatekeeping in metropolitan Australian and Canadian markets.
For Investors and Strategic Acquirers: Formulation specialists possessing liposomal encapsulation expertise and existing CE marking pathways represent the most defensible acquisition archetype as EMA Medical Device Regulation reclassification raises compliance barriers. Long-term viability hinges on regulatory geography diversification across FDA, EMA, and TGA jurisdictions rather than single-market concentration. Watch ANVISA classification finalization and California state disclosure mandate expansion as inflection signals for portfolio rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Liposomal Encapsulation R&D Investment | Extends lidocaine release duration from 90 minutes to four hours, enabling full-session coverage without reapplication. |
| Pharmacy-Channel Regulatory Alignment | TGA and FDA OTC monograph compliance creates distribution moats that filter out smaller formulation competitors. |
| Single-Use Sachet Format Development | Addresses mobile artist sanitation requirements at Australian tattoo conventions and private-session environments. |
| Consumer-Direct Subscription Launch | Captures brand loyalty with younger demographics in metropolitan Sydney and Toronto through automated replenishment. |
| Aftercare Kit Bundling Integration | Migrates margin capture from standalone numbing sales toward comprehensive session packages in Los Angeles studios. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with formulation chemists, tattoo studio owners, pharmacy procurement managers, and regulatory affairs specialists; and secondary validation through FDA OTC monograph filings, EMA Medical Device Regulation guidance documents, TGA registration databases, and customs trade records for pharmaceutical-grade lidocaine base imports. Bottom-up demand modeling across product type, active ingredient, end user, and distribution channel segments was triangulated against top-down market sizing from API production volumes and wholesale distributor shipment data.
Forecast inputs included session duration extension trends in professional studios, liposomal technology adoption curves, and regulatory pathway divergence across FDA, EMA, and TGA jurisdictions. Segmentation dimensions spanned formulation chemistry, active ingredient regulatory status, procurement authority, and channel structure. CAGRs were derived from penetration rate trajectories within each segment, with cross-validation against tattoo industry growth indicators and topical anesthetic prescription volume trends.
Stress conditions across API import tariff volatility, state-level disclosure mandate expansion, and EMA medical device reclassification timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology adoption rates and regulatory implementation schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Spine Pain Market
Pain Management
Advanced Cancer Pain Management Market
Pain Management
Medical Morphine Market
Pain Management
Neuropathic Pain Market
Pain Management
Visceral Pain Market
Pain Management
Bone Pain Treatment Market
Pain Management
Global Analgesic Infusion Pumps Market
Pain Management
Asia-Pacific Chronic Disease Management Market
Pain Management
Companion Animal Postoperative Pain Management Therapeutics Market
Pain Management
Painkillers Market
Pain Management
Pain Patches Market
Pain Management
Plantar Fasciitis Treatment Market
Pain Management
Global Visceral Pain Treatment Market
Pain Management
Pain Therapeutic Injectables Market
Pain Management
Cancer Pain Market
Pain Management
Ketorolac Market