
 OTC Painkiller Market | 2026-2036
OTC Painkiller Market Size, Share, and Industry Trends Forecast 2026-2036
OTC Painkiller Market Insights
Younger self-medicating consumers is redrawing demand patterns away from physician-directed purchases. Johnson & Johnson leverages its retail pharmacy shelf presence and pediatric positioning to sustain household brand loyalty across multiple continents. Haleon PLC anchors the analgesics category through specialized joint and muscle pain formulations. Bayer AG competes through its heritage aspirin franchise and cardiovascular co-positioning.
OTC painkillers comprise non-prescription analgesic compounds formulated for temporary relief of mild to moderate pain, fever, and inflammation, typically manufactured through direct compression, wet granulation, or hot-melt extrusion processes yielding tablets with defined dissolution profiles. These products serve commercial purposes across retail pharmacy, grocery, and digital channels where consumers make autonomous health decisions without clinical intermediation. Tablet formulations dominate volume due to manufacturing economies and dosing precision, while liquid and gel formats capture premium positioning among pediatric and topical application segments. Online retailers represent the fastest-growing distribution channel as pharmacy chains and supermarket operators invest in last-mile delivery infrastructure.
The FDA's OTC monograph reform process, alongside EMA's self-care medication guidelines and Health Canada's Natural and Non-prescription Health Products Directorate, collectively elevate manufacturing documentation, label clarity, and post-market surveillance obligations. These frameworks compel reformulation investments and restrict market access for manufacturers lacking validated quality management systems. Stakeholders must monitor pending monograph finalizations and channel-specific compliance requirements to preserve distribution breadth.
Market Dynamics
The FDA's ongoing OTC monograph reform is compressing approval timelines for new active ingredients while elevating documentation burdens, forcing manufacturers to reallocate R&D budgets toward compliance infrastructure rather than novel formulation development.
Growth Catalysts
- Aging Demographics:Self-medication prevalence among adults over 65 is expanding the addressable consumer base for non-prescription analgesics across retail pharmacy networks.
- EMA Self-Care Guidelines:Harmonized labeling standards across European Union member states are reducing cross-border regulatory friction and enabling centralized manufacturing strategies.
- Direct Compression Technology:Continuous manufacturing methods are shortening production cycles and reducing batch-to-batch variability for tablet formulations.
Market Restraints
- API Supply Concentration:Bulk ibuprofen and acetaminophen production concentrates in Chinese and Indian chemical manufacturing clusters, exposing formulators to geopolitical disruption risk.
- Environmental Compliance Costs:REACH registration requirements for solvent-based extraction processes are elevating operational expenditures for European manufacturing facilities.
- Topical Substitution Threat:Prescription-strength diclofenac gels and lidocaine patches are capturing moderate pain cases that previously defaulted to oral OTC options.
Strategic Opportunities
- Pediatric Liquid Formulations:Underpenetrated demand for alcohol-free, precise-dose suspensions in emerging markets offers whitespace for specialized manufacturers.
- Last-Mile Delivery Infrastructure:Pharmacy chain investments in same-day fulfillment are opening direct-to-consumer channels that bypass traditional wholesale distribution.
- Dual-Indication Positioning:Cardiovascular co-benefit claims for aspirin are creating regulatory pathways to expand usage among preventive health segments.
Industry Challenges
- Quality Management Talent Scarcity:Validated documentation expertise for FDA cGMP compliance remains concentrated among a limited pool of specialized consultants and in-house professionals.
- Legacy System Integration:Serialization requirements for track-and-trace compliance are forcing costly upgrades to packaging lines originally deployed before 2015.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OTC Painkiller Market |
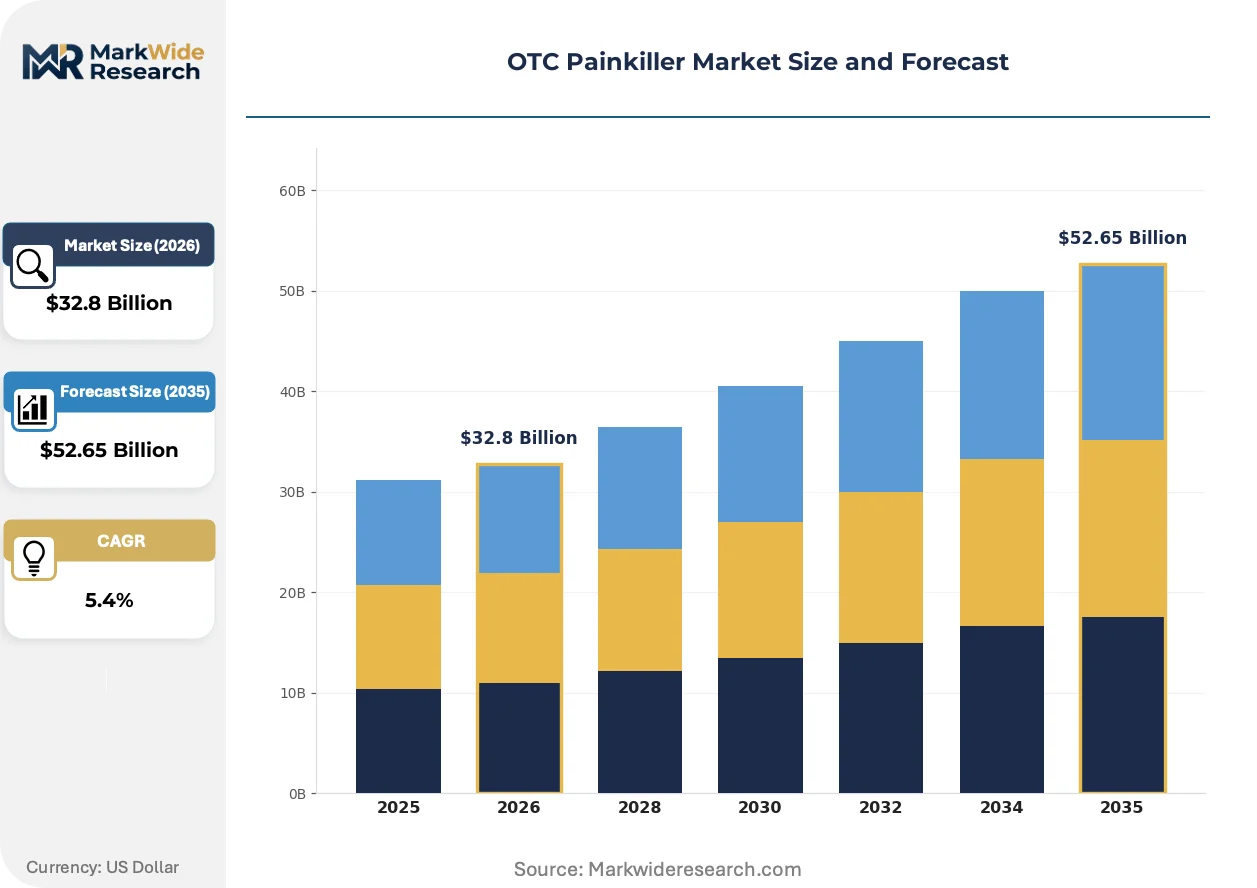
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $52.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetaminophen, Ibuprofen, Aspirin, Naproxen Formulation: Tablet, Liquid, Gel, Powder End User: Adults, Children, Seniors, Athletes Distribution Channel: Pharmacies, Supermarkets, Online Retailers, Convenience Stores |
| Companies Covered | Johnson & Johnson, Haleon PLC, Bayer AG, Reckitt Benckiser Group PLC, Sanofi SA, Viatris Inc., GSK plc, Pfizer Inc., Sun Pharmaceutical Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OTC Painkiller Market Trends and Innovations
Formulation science and distribution infrastructure are undergoing parallel transformation, with manufacturing precision and channel accessibility converging to redefine how consumers access pain relief without clinical intermediation.
Solubility-enhanced active ingredient delivery is bifurcating the tablet market between rapid-dissolve formulations for acute pain episodes and extended-release matrices for chronic conditions. Younger self-medicating consumers are adopting fast-melt formats at three times the rate of traditional coated tablets. This technology is bifurcating shelf space allocation, with retail pharmacies dedicating premium positioning to speed-of-onset claims while relegating conventional tablets to economy tiers.
Health Canada's Natural and Non-prescription Health Products Directorate is tightening evidence requirements for homeopathic and natural health product pain claims, forcing manufacturers to conduct randomized controlled trials or withdraw inflammatory positioning. The industrial consequence is a consolidation of substantiated claims among established pharmaceutical manufacturers with clinical research capabilities. Topical analgesic categories are most affected, with menthol and capsaicin products facing reformulation to meet new monograph standards.
Subscription-based replenishment models are displacing episodic pharmacy visits for chronic pain sufferers, with automated delivery services capturing household loyalty through algorithmic dosing reminders. Traditional supermarket and convenience channels are losing traffic to integrated pharmacy apps that bundle diagnostics with product fulfillment. This behavioral shift is most visible in United States metropolitan markets where pharmacy chains have invested in predictive inventory systems tied to consumer purchase histories.
OTC Painkiller Market Segmentation
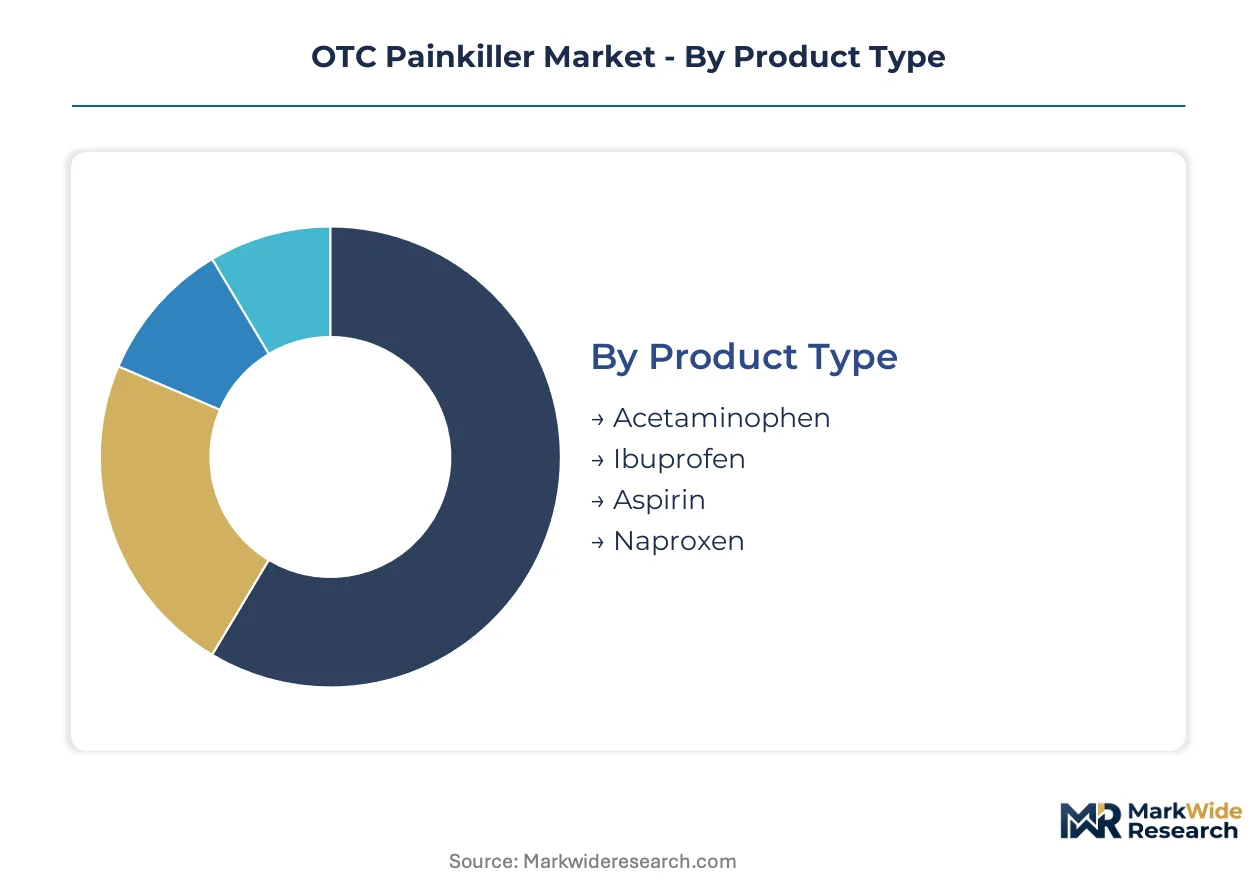
Segmentation in the OTC painkiller market reveals distinct margin architectures across molecular compounds, delivery formats, and channel economics. Manufacturers optimize portfolio mix by calibrating production scale against regulatory complexity and consumer self-selection behavior.
Product Type:
Margin pools concentrate in compounds with established safety profiles and manufacturing scale, where formulation familiarity reduces quality assurance overhead and accelerates batch release.
- Acetaminophen:This paracetamol-based analgesic commands shelf dominance through liver-metabolized fever reduction and broad pediatric acceptance. United States households favor acetaminophen for multi-symptom cold formulations, though FDA liver toxicity labeling has compressed dosing flexibility in combination products.
- Ibuprofen:A propionic acid derivative delivering anti-inflammatory action alongside analgesia, ibuprofen captures preference among arthritis self-managers and menstrual pain sufferers. German pharmacy chains report sustained volume for 400mg film-coated variants where EMA cardiovascular warnings have shifted demand toward lower chronic dosing regimens.
- Aspirin:Salicylic acid compound with antiplatelet co-positioning for cardiovascular prevention. Bayer AG maintains heritage positioning through enteric-coated formulations targeting gastric tolerance.
- Naproxen:Longer half-life NSAID favored for sustained relief in chronic musculoskeletal conditions. Prescription-to-OTC switch pathways in Canada have expanded access under Health Canada monograph revisions.
The dominant share belongs to acetaminophen, while ibuprofen is closing the gap fastest through anti-inflammatory positioning in aging populations.
Formulation:
Cost tier differentiation separates high-throughput solid dose manufacturing from specialized liquid and topical production requiring dedicated containment and cleaning validation.
- Tablet:Direct compression and wet granulation processes yield bioequivalent solid doses with dissolution profiles validated against USP monographs. United States retail pharmacies allocate prime shelf positioning to rapid-dissolve variants where younger consumers prioritize speed-of-onset claims over economy pricing.
- Liquid:Suspension formulations with precise dosing instrumentation serve pediatric and geriatric swallowing limitations. Alcohol-free suspensions in emerging markets command manufacturing premiums due to excipient sourcing complexity and stability testing burdens.
- Gel:Topical NSAID delivery bypasses first-pass hepatic metabolism for localized musculoskeletal relief. REACH compliance for penetration enhancers elevates European production costs relative to oral alternatives.
- Powder:Effervescent and bulk powder formats capture travel and occupational segments requiring portable dosing flexibility. Japanese convenience retail channels favor single-sachet packaging for on-the-go consumption patterns.
Tablet formulations retain volume leadership, yet liquid formats are expanding share most quickly through pediatric precision-dose demand.
End User:
Application intensity varies sharply across demographic cohorts, with chronic pain prevalence and self-medication confidence determining purchase frequency and brand loyalty.
- Adults:Working-age consumers aged 18-64 drive episodic purchase patterns tied to acute injury and tension headache management. Occupational health programs in United States manufacturing sectors stock combination analgesics for first-aid station replenishment.
- Children:Weight-calibrated dosing requirements and palatability engineering dominate formulation priorities. Health Canada tightened evidence standards for pediatric pain claims, forcing manufacturers toward clinical trial investment or indication narrowing.
- Seniors:Polypharmacy awareness and renal function monitoring shape NSAID selection among adults over 65. German statutory health insurance funds now reimburse pharmacist consultations for analgesic appropriateness reviews.
- Athletes:Anti-inflammatory preference and rapid recovery positioning drive premium pricing for sports-specific packaging and electrolyte co-formulation. Professional team procurement contracts in North American leagues specify lot-level documentation for anti-doping compliance.
Adult segments anchor current revenue, though senior-targeted formulations are gaining share fastest through aging demographics and pharmacy consultation integration.
Distribution Channel:
Customer type stratification separates professional-intermediated purchases from autonomous retail selection, with fulfillment speed emerging as the decisive loyalty determinant.
- Pharmacies:Licensed dispensaries with trained personnel provide contra-indication screening and generic substitution counseling. CVS Health and Walgreens Boots Alliance in the United States deploy predictive inventory systems tying shelf allocation to neighborhood demographic profiles.
- Supermarkets:Mass merchandisers capture impulse and pantry-stocking purchases through promotional pricing and aisle placement proximity to complementary health categories. Kroger and Tesco leverage loyalty card data to target analgesic coupons toward reported illness incidence in trading areas.
- Online Retailers:Algorithmic replenishment and subscription bundling capture chronic pain sufferers seeking doorstep convenience. Amazon Pharmacy and Capsule in United States metropolitan markets offer same-day fulfillment for Prime members, displacing emergency convenience store visits.
- Convenience Stores:Extended hours and travel-oriented packaging address urgent unplanned need, though unit economics compress margin through high-rent locations and limited SKU breadth. 7-Eleven Japan and Lawson emphasize compact blister packs for commuter rail station traffic.
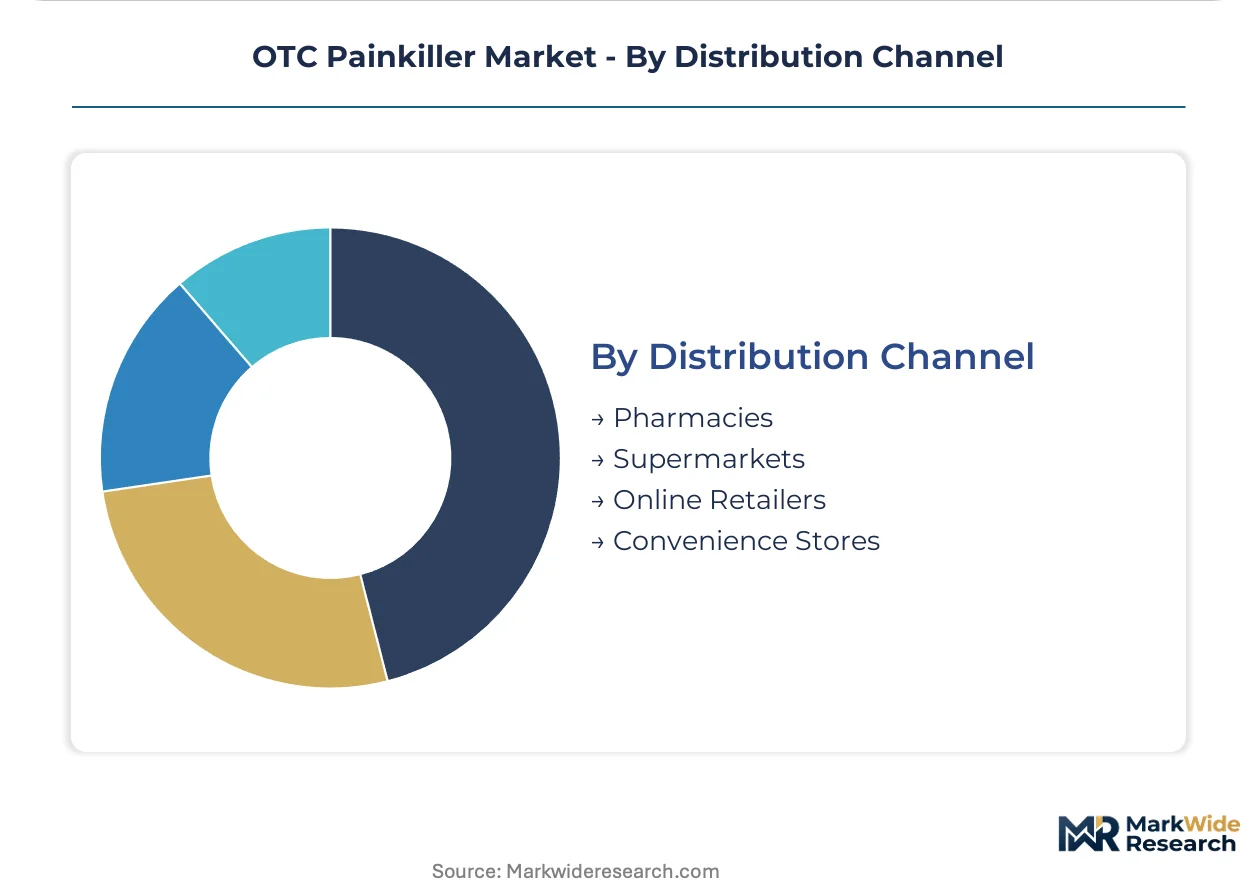
Pharmacy channels hold dominant position, while online retailers are climbing the fastest through last-mile infrastructure investment and predictive replenishment algorithms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active ingredient manufacturing clusters in China and India supply bulk ibuprofen and acetaminophen to formulators worldwide, creating geographic interdependence that shapes regional market dynamics. Formulation and packaging operations concentrate in developed markets where regulatory compliance infrastructure supports finished goods distribution. Consumer access patterns diverge sharply between pharmacy-dominated European systems and retail-integrated North American channels.
United States
Direct-to-consumer pharmacy chains and wellness retail formats command the largest volume share globally, with CVS Health and Walgreens Boots Alliance deploying predictive inventory systems tied to neighborhood demographic profiles. The FDA's evolving OTC monograph system continues to reshape product approval pathways and label requirements for domestic manufacturers. New Jersey and Pennsylvania host concentrated formulation facilities serving East Coast distribution networks.
Germany
Statutory health insurance funds now reimburse pharmacist consultations for analgesic appropriateness reviews among adults over 65, integrating professional intermediation into self-medication behavior. EMA self-care guidelines harmonize labeling standards across European Union member states, enabling centralized manufacturing strategies from German production bases. The Rhine-Main region anchors continental distribution for film-coated ibuprofen variants.
China
Domestic chemical manufacturing clusters supply bulk API to global formulators, though environmental compliance costs under MEE regulations are elevating operational expenditures for solvent-based extraction processes. NMPA alignment with international GMP standards is compressing approval timelines for new active ingredients while elevating documentation burdens. Zhejiang and Jiangsu provinces concentrate paracetamol precursor production.
India
Sun Pharmaceutical Industries and domestic competitors leverage cost-optimized manufacturing for export-oriented generic analgesic supply, though CDSCO quality management requirements are forcing reformulation investments. BIS standards for pharmaceutical excipients restrict market access for manufacturers lacking validated quality management systems. Hyderabad and Ahmedabad clusters specialize in contract formulation for European and North American markets.
Japan
Convenience retail channels favor single-sachet powder packaging for commuter rail station traffic, reflecting distinct consumption patterns in metropolitan markets. METI pharmaceutical division guidelines emphasize stability testing burdens for alcohol-free pediatric suspensions. The Kanto region around Tokyo concentrates domestic formulation capacity for rapid-dissolve tablet technologies.
OTC Painkiller Market Competitive Landscape
Concentration sits with diversified consumer health conglomerates and specialized pharmaceutical manufacturers that combine regulatory expertise with retail pharmacy shelf presence. Three archetypes dominate: heritage brand owners leveraging decades of household recognition, science-driven formulators emphasizing clinical substantiation, and private-label suppliers capturing economy-tier volume through retail chain partnerships. Competitive moves center on pediatric formulation specialization and last-mile delivery infrastructure partnerships.
Among heritage-brand conglomerates, Johnson & Johnson and Bayer AG exemplify archetypes built on pediatric positioning and cardiovascular co-benefit claims respectively, while Haleon PLC occupies a position emphasizing specialized joint and muscle pain formulations. These entities anchor competitive dynamics through distinct therapeutic positioning rather than undifferentiated commodity supply.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Haleon PLC |
| Bayer AG |
| Reckitt Benckiser Group PLC |
| Sanofi SA |
| Viatris Inc. |
| GSK plc |
| Pfizer Inc. |
| Sun Pharmaceutical Industries Ltd |
| Others |
Pricing and Supply Chain Analysis
FDA cGMP certification gates both supplier qualification and price differentiation simultaneously, separating validated manufacturers from economy-tier competitors while compressing margins for facilities lacking serialized track-and-trace infrastructure.
Pricing Analysis
FDA OTC monograph compliance dictates the pricing tier structure across the market, with three-tier pricing separating rapid-dissolve premium formats from standard coated tablets and economy private-label alternatives. Price differentiation rests on dissolution speed certification and pediatric formulation complexity, with alcohol-free suspensions commanding manufacturing premiums. Pricing pressure stems from REACH registration costs elevating European production expenses against Asian imports. Pharmacy chains exhibit highest price sensitivity through generic substitution programs, while direct-to-consumer subscription models absorb modest premiums for convenience.
Supply Chain Analysis
Container availability on Asia-Europe trade lanes constrains API inbound logistics, with bulk ibuprofen and acetaminophen precursors drawing from Zhejiang and Jiangsu chemical clusters in China alongside Hyderabad and Ahmedabad pharmaceutical manufacturing zones in India. Raw material dependencies center on paracetamol precursor chemicals, propionic acid derivatives, and specialized film-coating polymers. Single-source vulnerability concentrates in Chinese environmental compliance enforcement disrupting solvent-based extraction capacity. Distribution runs through wholesale pharmaceutical distributors serving retail pharmacy networks, with last-mile delivery infrastructure expanding through chain-owned fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
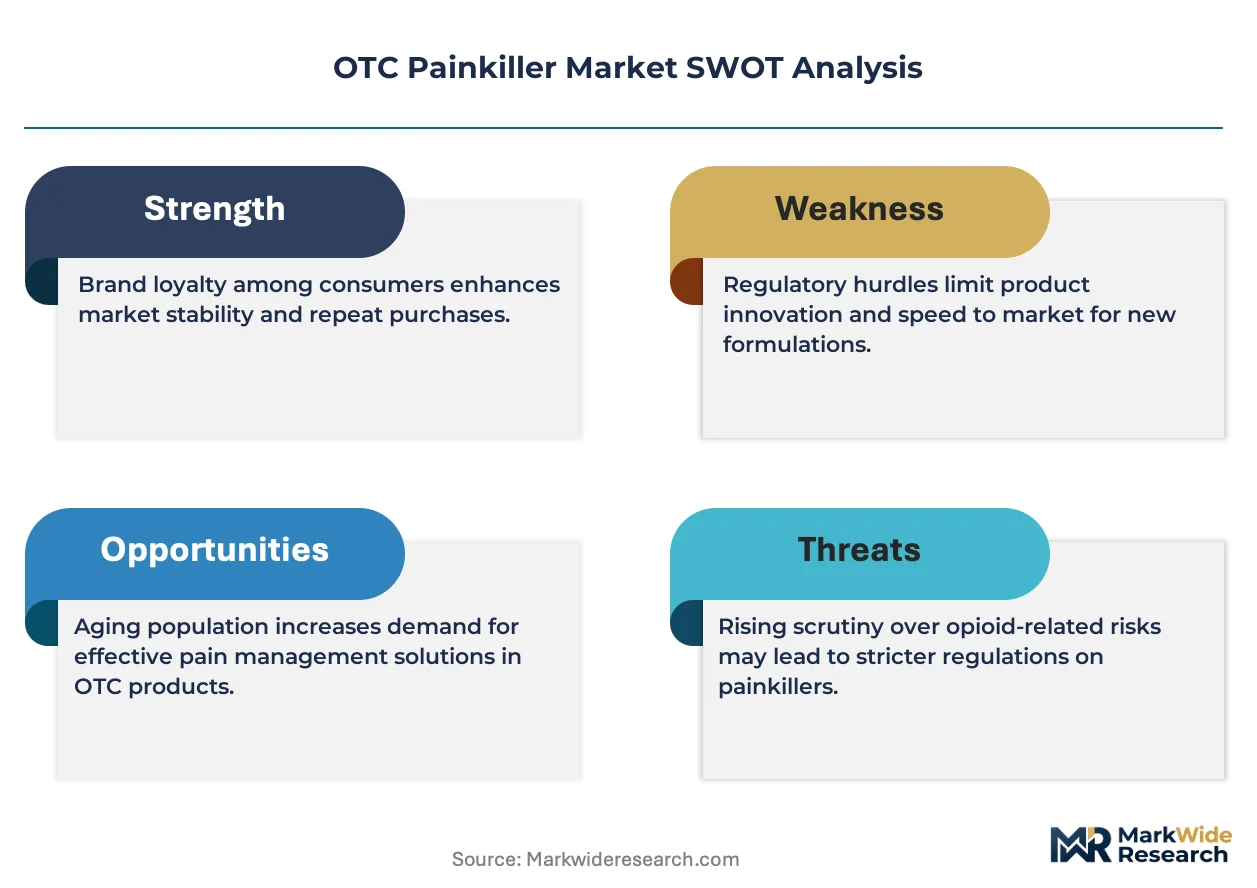
Buyer power is concentrating through pharmacy chain consolidation and supermarket loyalty program integration, shifting procurement leverage toward centralized formulary decisions and private-label sourcing mandates.
For Market Incumbents: Secure backward integration into API precursor supply through captive manufacturing partnerships in Indian chemical clusters, insulating against Chinese environmental enforcement disruptions. Reinforce pediatric formulation specialization to defend shelf positioning against generic substitution pressures from private-label competitors. Prioritize serialization infrastructure investment to maintain FDA distribution eligibility as track-and-trace deadlines tighten. For New Entrants and Emerging Players: Subscription-based replenishment services represent the most penetrable service-layer gap, with algorithmic dosing reminders and automated delivery capturing chronic pain sufferer loyalty outside incumbent pharmacy relationships. Target alcohol-free pediatric suspensions in emerging markets where formulation complexity deters commodity competitors. Pursue direct-to-consumer channel partnerships bypassing traditional wholesale distribution entirely. For Investors and Strategic Acquirers: FDA OTC monograph finalization reshapes the acquisition landscape, elevating valuations for manufacturers with completed clinical trial portfolios and validated quality management systems. Long-term viability favors vertically integrated specialists controlling API supply through Indian manufacturing footprints. Watch Health Canada evidence standard enforcement as the signal indicating consolidation timing for natural health product pain claim portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Formulation Specialization | Alcohol-free suspensions with precise dosing instrumentation capture emerging market premiums and regulatory preference. |
| Backward Integration into API Supply | Captive paracetamol precursor production in Indian chemical clusters reduces Chinese environmental compliance exposure. |
| Last-Mile Delivery Infrastructure | Pharmacy chain same-day fulfillment networks displace convenience store traffic through predictive inventory systems. |
| Dual-Indication Cardiovascular Positioning | Aspirin antiplatelet claims expand usage among preventive health segments under FDA label guidance. |
| Serialization Compliance Investment | Track-and-trace infrastructure preserves distribution breadth as FDA deadlines eliminate non-compliant packaging lines. |
Research Methodology
The analysis maps acetaminophen, ibuprofen, aspirin, and naproxen product categories, each validated through regulatory affairs directors, pharmacy chain procurement managers, and contract manufacturing executives alongside FDA filing databases, EMA submission records, Health Canada monograph revisions, and customs trade data. Primary interviews with formulation scientists and pediatric dosing specialists combined with secondary validation through USP dissolution monographs and clinical trial registries. Bottom-up volume estimates triangulated against top-down market sizing from retail audit data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled molecular compound, dosage form, end-user demographic, and distribution channel dimensions. CAGRs derived from regression analysis of historical volume trends adjusted for demographic shifts and regulatory timeline impacts. Forecast inputs incorporated FDA monograph finalization schedules and EMA self-care guideline implementation pacing.
Underlying assumptions cover stable API supply from Indian and Chinese manufacturing clusters, with deviation risk concentrated in environmental enforcement disruptions and geopolitical trade restrictions. Forecasts reflect these baseline conditions with acknowledged sensitivity to regulatory acceleration or delay. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Visceral Pain Market
Pain Management
Chronic Pain Market
Pain Management
Chronic Lower Back Pain Treatment Market
Pain Management
Cluster Headache Market
Pain Management
Dyspareunia Market
Pain Management
Heat Therapy Market
Pain Management
Axial Spondyloarthritis Management Market
Pain Management
Global Morphine Market
Pain Management
Global Analgesic Infusion Pumps Market
Pain Management
Chemotherapy Induced Pain Market
Pain Management
Pain Relief Oil Market
Pain Management
Over-The-Counter Pain Medication Market
Pain Management
Global Post Herpetic Neuralgia Treatment Market
Pain Management
Topical Pain Relief Cream Market
Pain Management
Provoked Vestibulodynia Treatment Market
Pain Management
Global Pain Management Market