
 India Opioids Market | 2026-2036
India Opioids Market Size, Share, and Industry Trends Forecast 2026-2036
India Opioids Market Insights
Fixed-dose combination packaging is shifting how Indian hospitals procure opioids, moving away from single-agent vials toward bundled analgesic kits that reduce pharmacy handling steps. Sun Pharmaceutical Industries Ltd. dominates injectable morphine supply to government procurement chains. Pfizer Inc. leverages its established hospital sales infrastructure to sustain premium positioning in fentanyl patches. Hikma Pharmaceuticals PLC competes on cost-engineered oral oxycodone formulations for tier-two city hospitals.
Opioids constitute semi-synthetic and synthetic alkaloid derivatives that bind to mu, kappa, and delta receptors in the central nervous system, typically formulated as hydrochloride salts with specified purity grades exceeding 99.5% for pharmaceutical use, primarily indicated for moderate-to-severe pain management where non-opioid analgesics prove inadequate. The therapy area dimension shows cancer care commanding the deepest margin pools due to reimbursement guarantees under government health schemes, while palliative care registers the fastest expansion as hospice infrastructure spreads beyond metro centers. Among administration routes, transdermal patches attract concentrated R&D investment because they address chronic pain compliance gaps in home care settings.
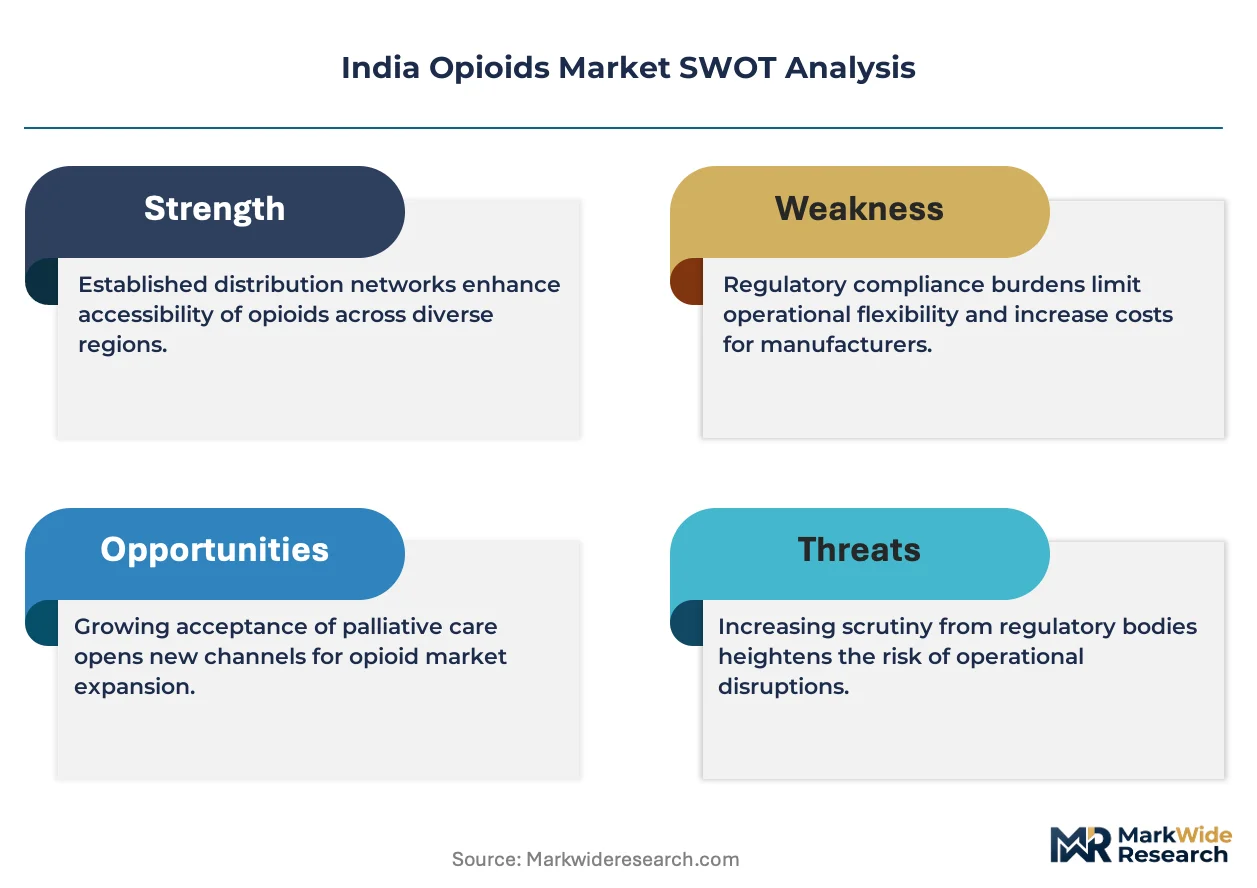
CDSCO mandates bioequivalence documentation and batch-specific narcotic tracking for all opioid manufacturers, while the Narcotic Drugs and Psychotropic Substances Act imposes strict production quotas and interstate movement permits that constrain distribution flexibility. State-level FDA authorities in Maharashtra and Tamil Nadu enforce additional cold-chain verification for injectable opioids, creating compliance layering that favors scaled manufacturers over regional entrants. Stakeholders must monitor whether proposed amendments to the NDPS Act will liberalize controlled-release formulation categories or tighten prescription surveillance mechanisms.
Market Dynamics
CDSCO's batch-specific narcotic tracking mandate and NDPS Act production quotas are concentrating manufacturing authority among scaled producers capable of absorbing layered compliance costs across multiple state FDA jurisdictions.
Growth Catalysts
- Cancer care reimbursement guarantees:Government health schemes in Delhi and Mumbai tertiary networks lock in demand volume for injectable morphine and fentanyl formulations, insulating procurement from price volatility.
- NDPS Act amendments:Proposed controlled-release category liberalization would expand formulary access for chronic non-cancer pain, opening new prescriber segments beyond oncologists.
- Hospice infrastructure spread:Palliative care unit expansion into tier-two cities across Maharashtra and Karnataka is generating pull-through for transdermal patch and oral oxycodone demand.
Market Restraints
- Active pharmaceutical ingredient concentration:Import dependence on Chinese morphine alkaloid feedstock exposes formulators to customs clearance delays and currency fluctuation at Mumbai and Chennai ports.
- Cold-chain verification layering:Maharashtra and Tamil Nadu state FDA mandates for injectable opioid temperature documentation add 12-18% logistics overhead compared to oral solid distribution.
- Non-opioid analgesic substitution:Regional medical colleges are expanding tramadol and tapentadol protocols for moderate pain, compressing entry-level morphine prescription rates.
Strategic Opportunities
- Home care channel development:Transdermal fentanyl patch dispensing through retail pharmacy networks in Bangalore and Hyderabad bypasses hospital procurement bottlenecks for chronic pain patients.
- PLI scheme alignment:Domestic manufacturing incentives for critical APIs could reduce import exposure for morphine sulfate and oxycodone hydrochloride precursors.
- Telemedicine-enabled prescription:Digital health platforms linking oncologists to district hospital networks are streamlining refill authorization for palliative care patients in rural Karnataka.
Industry Challenges
- Narcotic licensing specialist scarcity:Qualified personnel capable of navigating CDSCO and state FDA concurrent approval pathways command 40-60% salary premiums, constraining regional manufacturer expansion.
- Legacy ERP integration:Batch tracking systems mandated under NDPS Act amendments require retrofitting of manufacturing execution software at mid-scale facilities, extending compliance timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Opioids Market |
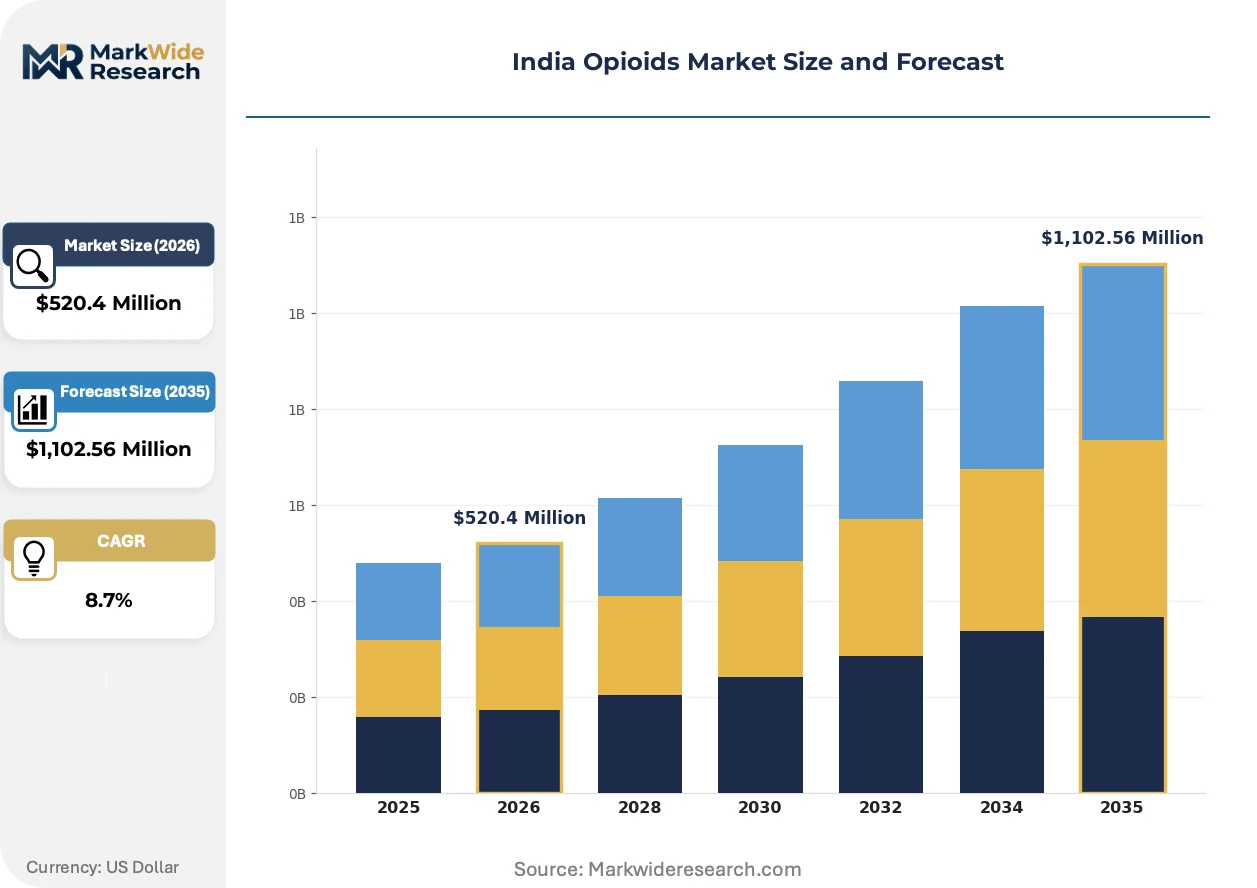
| Market Size in 2026 | $520.4 Million |
| Market Size in 2035 | $1,102.56 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Morphine, Oxycodone, Fentanyl, Hydromorphone Therapy Area: Chronic Pain, Postoperative Pain, Palliative Care, Cancer Care Administration Route: Injection, Oral, Transdermal, Intranasal End User: Hospitals, Ambulatory Surgical Centers, Home Care, Pain Management Clinics |
| Companies Covered | Pfizer Inc., Johnson & Johnson, Purdue Pharma L.P., Teva Pharmaceutical Industries Ltd., Mallinckrodt Pharmaceuticals, Endo International plc, Hikma Pharmaceuticals PLC, Sun Pharmaceutical Industries Ltd., AbbVie Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Opioids Market Trends and Innovations
Automation of pharmacy handling workflows and regulatory documentation is compressing dispensing error rates while reshaping procurement relationships between hospital networks and opioid suppliers.
Intelligent dispensing cabinets with biometric access control and real-time inventory logging are automating the reconciliation of controlled substances in tertiary hospital pharmacies across Delhi and Mumbai. Oncology departments in these networks are deploying these systems at 15-20 bed increments to satisfy joint commission accreditation requirements. This technology is automating the audit trail generation that CDSCO inspectors now demand during unannounced facility reviews, reducing manual documentation labor by approximately half.
CDSCO's tightened bioequivalence documentation requirements for generic opioid formulations are extending abbreviated new drug application review timelines by four to six months. Manufacturers must now submit dissolution profile comparisons against innovator products for all extended-release categories. The oral solid segment faces the steepest compliance burden, with several regional applicants withdrawing pending filings rather than commissioning additional clinical pharmacokinetic studies.
Fixed-dose combination kits bundling opioids with antiemetics and laxatives are displacing single-agent vial procurement in government hospital tenders across Maharashtra. These pre-configured analgesic protocols reduce pharmacy compounding steps and standardize palliative care order sets. Tier-two city hospitals in Nagpur and Pune are adopting this model fastest, where nursing staff shortages make simplified dispensing workflows operationally critical.
India Opioids Market Segmentation
Opioid procurement patterns in India diverge sharply across clinical settings, with tertiary hospital networks demanding injectable formulations while home care channels pull toward patient-administered alternatives. Understanding these segment boundaries clarifies where manufacturers must build distinct distribution capabilities and regulatory dossiers.
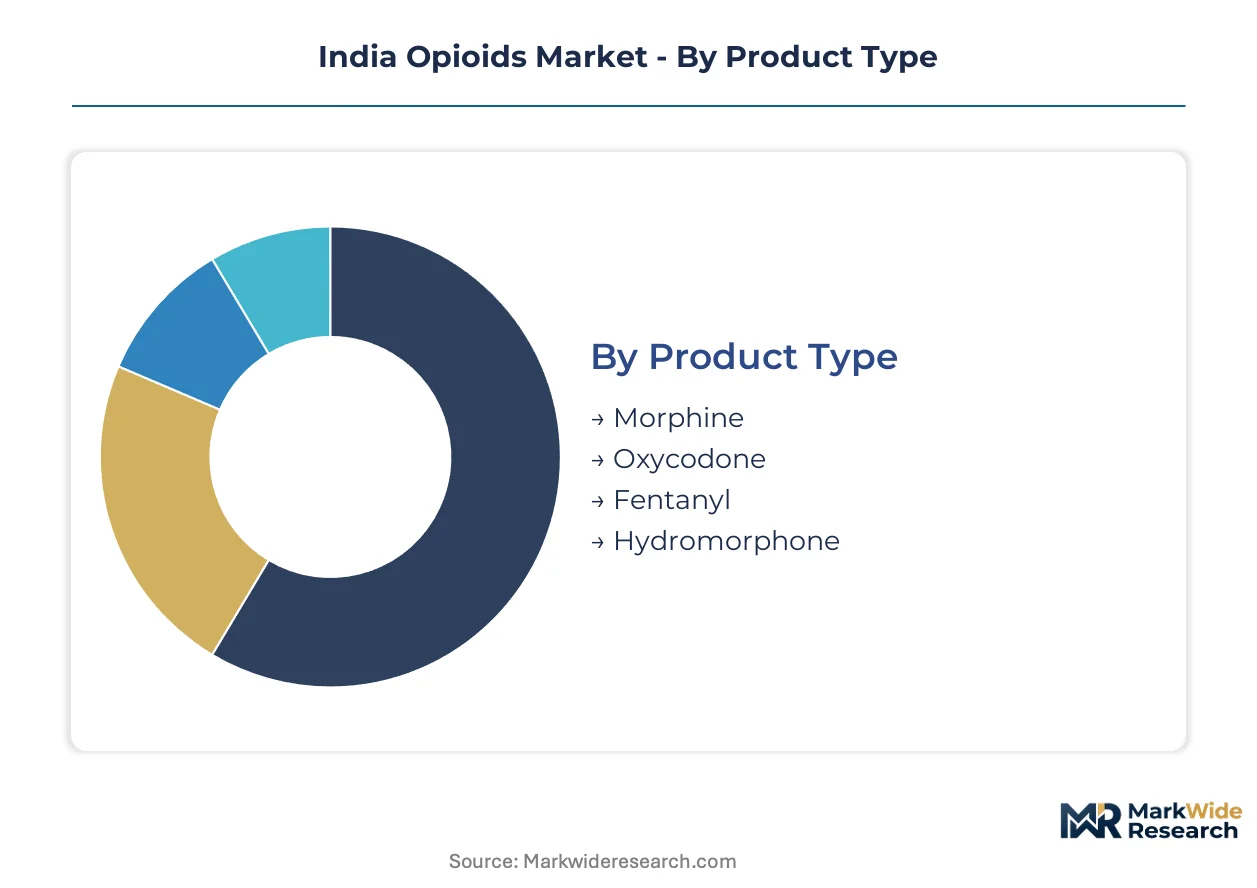
Product Type:
Morphine formulations span the widest customization spectrum, from immediate-release oral tablets to sterile injectable ampoules requiring distinct stability testing protocols.
- Morphine:The foundational opioid alkaloid, typically formulated as sulfate or hydrochloride salts with purity grades exceeding 99.5% for pharmaceutical use. Government procurement chains in Delhi and Mumbai lock in volume demand through cancer care reimbursement guarantees, insulating this segment from price volatility seen in private channels.
- Oxycodone:Semi-synthetic derivative with higher oral bioavailability than morphine, enabling tablet and capsule formulations for outpatient dispensing. Tier-two city hospitals in Nagpur and Pune are expanding oxycodone protocols as nursing staff shortages make simplified oral regimens operationally critical.
- Fentanyl:Synthetic phenylpiperidine with 50-100x morphine potency, driving concentrated R&D investment in transdermal matrix technology.
- Hydromorphone:Hydrogenated ketone derivative of morphine with rapid onset characteristics suited to acute breakthrough pain management.
Most installed capacity flows through Morphine. Expansion is steepest in Fentanyl.
Therapy Area:
Reimbursement mechanics create stark margin differentiation across clinical applications, with government-guaranteed schemes concentrating purchasing power in specific therapeutic domains.
- Cancer Care:The deepest margin pool in Indian opioid demand, anchored by tertiary hospital networks in Delhi and Mumbai where government health schemes lock in procurement volume for injectable morphine and fentanyl formulations. CDSCO's batch-specific narcotic tracking mandate applies most stringently here due to high-dose requirements.
- Palliative Care:Hospice infrastructure spreading beyond metro centers into tier-two cities across Maharashtra and Karnataka generates pull-through for transdermal patches and oral oxycodone, climbing the fastest as district-level facilities gain accreditation.
- Chronic Pain:Long-duration non-cancer indications where proposed NDPS Act amendments could liberalize controlled-release formulary access.
- Postoperative Pain:Acute surgical recovery applications concentrated in ambulatory surgical centers with preference for short-acting injectable formulations.
Revenue concentrates in Cancer Care. Accreditation expansion drives Palliative Care most aggressively.
Administration Route:
Cold-chain requirements and handling complexity stratify distribution economics, with parenteral forms demanding specialized logistics that oral solids bypass entirely.
- Injection:Sterile aqueous solutions requiring temperature-controlled distribution and documented chain-of-custody protocols. Maharashtra and Tamil Nadu state FDA mandates add 12-18% logistics overhead compared to oral distribution, favoring scaled manufacturers with captive cold-chain infrastructure.
- Transdermal:Matrix or reservoir patch systems enabling 72-hour continuous delivery, addressing compliance gaps in home care settings across Bangalore and Hyderabad retail pharmacy networks.
- Oral:Immediate-release and extended-release tablet and capsule formulations with simpler storage requirements.
- Intranasal:Spray formulations for rapid absorption in emergency breakthrough pain scenarios.
Hospital procurement channels favor Injection. Retail pharmacy bypass strategies target Transdermal.
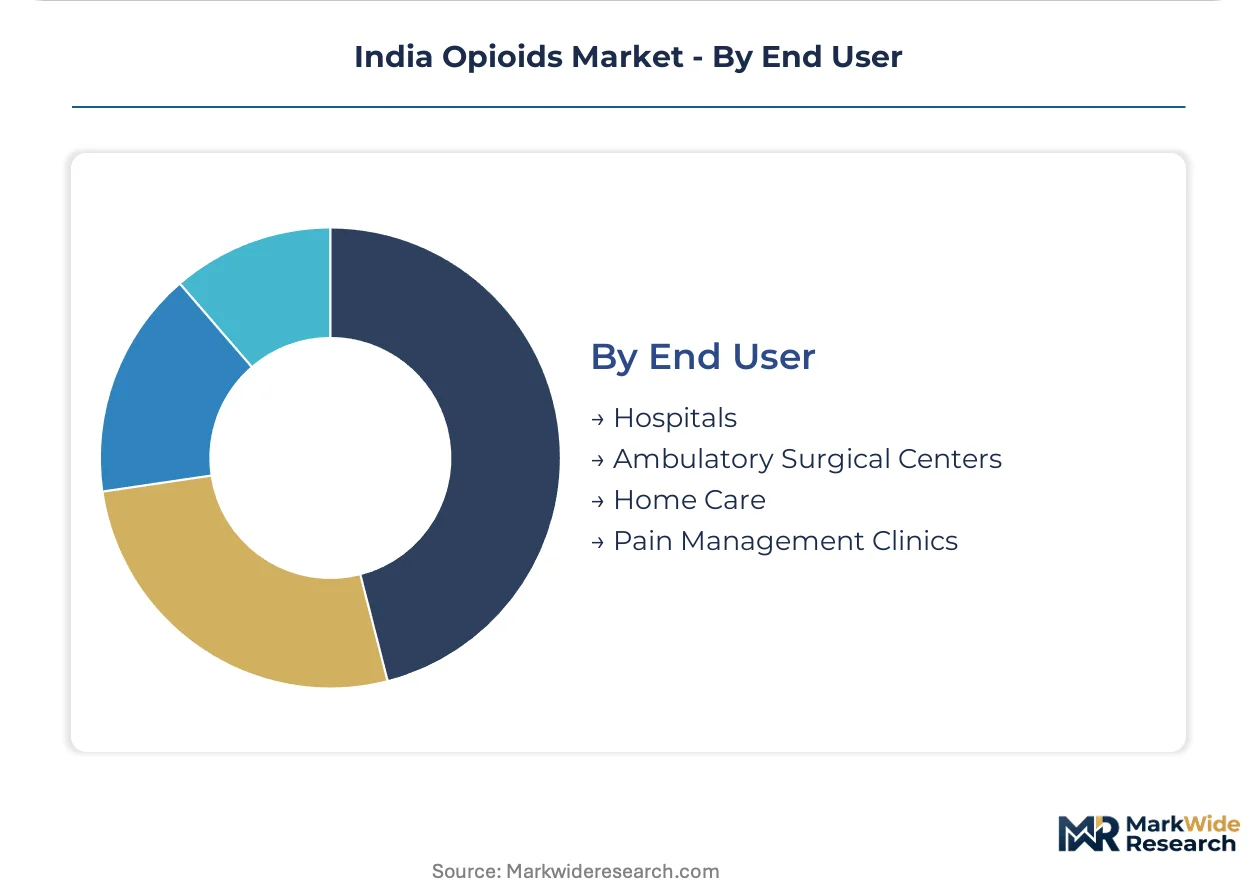
End User:
Institutional scale and procurement autonomy determine contract structures, with government hospital tenders operating on fundamentally different timelines than private ambulatory chains.
- Hospitals:Tertiary and secondary care institutions dominating injectable opioid volume through centralized pharmacy operations. Fixed-dose combination kits bundling opioids with antiemetics are displacing single-agent vials in Maharashtra government tenders, reducing compounding steps for nursing staff.
- Home Care:Dispensing through retail networks for chronic pain patients with established tolerance, bypassing hospital procurement bottlenecks. Telemedicine platforms linking oncologists to district hospital networks are streamlining refill authorization in rural Karnataka.
- Ambulatory Surgical Centers:Day-procedure facilities with preference for rapid-onset, short-duration formulations.
- Pain Management Clinics:Specialized outpatient facilities with protocol-driven prescribing authority.
Volume aggregates at Hospitals. Channel development investment targets Home Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's opioid manufacturing base traces its modern scale to the 1980s when state-owned alkaloid extraction facilities in Uttar Pradesh and Madhya Pradesh supplied domestic morphine requirements. These operations established the regulatory and technical foundations that private formulators later leveraged for commercial expansion.
Maharashtra
Mumbai anchors the highest concentration of tertiary hospital networks consuming injectable morphine and fentanyl formulations. CDSCO's batch-specific narcotic tracking mandate applies with particular stringency here due to the volume of high-dose cancer care protocols. Pune and Nagpur are seeing accelerated palliative care unit accreditation, driving demand for fixed-dose combination kits that bundle opioids with antiemetics.
Karnataka
Bangalore's retail pharmacy networks are pioneering transdermal fentanyl patch dispensing for chronic pain patients bypassing hospital procurement bottlenecks. The state FDA enforces cold-chain verification protocols that add logistics overhead for injectable formulations. Telemedicine platforms linking oncologists to district hospitals in rural Karnataka are streamlining refill authorization workflows.
Tamil Nadu
Chennai's government medical college hospitals are expanding tramadol and tapentadol protocols for moderate pain, compressing entry-level morphine prescription rates. State FDA mandates require temperature documentation for injectable opioids that favors scaled manufacturers with captive distribution infrastructure. The city's hospice infrastructure is spreading into tier-two locations like Coimbatore and Madurai.
Delhi-NCR
Delhi's All India Institute of Medical Sciences and associated tertiary networks lock in procurement volume through government health scheme reimbursement guarantees. The Narcotic Drugs and Psychotropic Substances Act production quotas are administered through zonal offices here, creating compliance layering for interstate distribution permits. Noida and Gurugram are emerging as logistics hubs for cold-chain opioid distribution to northern states.
Gujarat
Ahmedabad's pharmaceutical manufacturing belt hosts API synthesis operations for morphine sulfate and oxycodone hydrochloride precursors. The PLI scheme for critical APIs could reduce import dependence on Chinese morphine alkaloid feedstock currently clearing through Mumbai and Chennai ports. State industrial incentives are attracting investment in controlled-substance manufacturing execution systems compliant with NDPS Act amendments.
India Opioids Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with established hospital sales infrastructure and captive narcotic licensing expertise. Three to four scaled manufacturers absorb the layered compliance costs across multiple state FDA jurisdictions, while regional entrants face specialist scarcity and extended approval timelines. Strategic archetypes include government procurement specialists, premium hospital channel players, and cost-engineered oral solid formulators. Dominant competitive moves center on fixed-dose combination kit development and telemedicine-enabled prescription platform partnerships.
Among multinational pharmaceutical corporations, Pfizer Inc. and Johnson & Johnson occupy positions reflecting premium-tier hospital channel strategies. Purdue Pharma L.P. represents the specialized controlled-release formulation archetype. Teva Pharmaceutical Industries Ltd., Mallinckrodt Pharmaceuticals, and Endo International plc exemplify diversified generic opioid portfolios. Hikma Pharmaceuticals PLC and Sun Pharmaceutical Industries Ltd. anchor cost-competitive positioning for tier-two city hospital procurement. AbbVie Inc. sits within the diversified therapeutic conglomerate tier with hospital infrastructure leverage.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson |
| Purdue Pharma L.P. |
| Teva Pharmaceutical Industries Ltd. |
| Mallinckrodt Pharmaceuticals |
| Endo International plc |
| Hikma Pharmaceuticals PLC |
| Sun Pharmaceutical Industries Ltd. |
| AbbVie Inc. |
| Others |
Pricing and Supply Chain Analysis
Family-owned pharmaceutical conglomerates with decades of hospital sales infrastructure anchor India's opioid supply base, translating captive narcotic licensing expertise into pricing discipline that resists commoditization despite government tender pressures. Their embedded relationships with CDSCO zonal offices and state FDA authorities create switching costs that protect margin structures across formulation tiers.
Pricing Analysis
Contract-based long-term offtake agreements with government procurement chains lock in volume commitments for injectable morphine, while private hospital channels negotiate spot premiums for fentanyl patches based on cold-chain reliability guarantees. Price differentiation hinges on bioequivalence certification tier and captive distribution infrastructure scale. Cost compression in oral oxycodone generics is intensifying as Hikma Pharmaceuticals PLC and regional formulators compete for tier-two city hospital tenders. Government hospital buyers exhibit highest price sensitivity, whereas tertiary cancer care networks in Delhi and Mumbai prioritize supply security over unit cost.
Supply Chain Analysis
Domestic-content mandates under the PLI scheme for critical APIs are reshaping sourcing patterns for morphine sulfate and oxycodone hydrochloride precursors, incentivizing backward integration into alkaloid extraction. Manufacturing concentration spans India, China, and limited European specialty chemical suppliers. Raw material dependencies include Chinese morphine alkaloid feedstock, specialized solvent systems for salt formation, and transdermal adhesive polymers. Single-source vulnerability runs through Mumbai and Chennai port clearance bottlenecks for imported feedstock. Distribution runs through government medical stores depots, captive hospital pharmacies, and emerging retail pharmacy networks in Bangalore and Hyderabad.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's opioid market compounds steadily as cancer care reimbursement guarantees under government health schemes lock in demand inelasticity regardless of pricing cycles in adjacent therapeutic categories.
For Market Incumbents: To counter margin erosion from oral oxycodone generic competition, Sun Pharmaceutical Industries Ltd. and scaled manufacturers should deepen captive cold-chain infrastructure across Maharashtra and Tamil Nadu state FDA jurisdictions while securing PLI scheme alignment for API synthesis of morphine sulfate precursors in Gujarat's pharmaceutical belt. For New Entrants and Emerging Players: The premium-to-economy gap in transdermal fentanyl patch dispensing offers white-space capture through retail pharmacy partnerships in Bangalore and Hyderabad home care channels, bypassing hospital procurement bottlenecks. District-level palliative care accreditation in rural Karnataka presents the most penetrable geography. A telemedicine-enabled prescription platform linking oncologists to refill authorization workflows provides the critical go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale formulators with pending CDSCO abbreviated new drug applications facing extended bioequivalence documentation timelines. The five-to-ten year viability window favors manufacturers with demonstrated narcotic licensing specialist retention and legacy ERP retrofit completion for NDPS Act batch tracking compliance. The signal to watch is proposed NDPS Act amendment passage liberalizing controlled-release formulation categories.| Strategic Initiative | Industry Significance |
|---|---|
| Fixed-Dose Combination Kit Development | Bundled analgesic protocols reduce pharmacy compounding steps for nursing staff shortages in Maharashtra government tenders. |
| Telemedicine-Enabled Prescription Platform | Digital health linkages between oncologists and district hospitals streamline refill authorization in rural Karnataka palliative care. |
| PLI Scheme API Manufacturing Alignment | Domestic incentives for morphine sulfate precursors reduce import exposure to Chinese feedstock customs delays. |
| Intelligent Dispensing Cabinet Deployment | Biometric access control systems automate CDSCO audit trail generation in Delhi and Mumbai tertiary hospital pharmacies. |
| Retail Pharmacy Channel Bypass Strategy | Transdermal patch dispensing through Bangalore and Hyderabad networks reaches chronic pain patients outside hospital procurement. |
Research Methodology
Multiple input streams — regulatory filing analysis, hospital procurement database review, and manufacturer compliance documentation — were reconciled against primary interviews with CDSCO regulatory affairs leads, state FDA narcotic licensing officers, tertiary hospital pharmacy directors, and palliative care unit administrators. Secondary validation drew from CDSCO bioequivalence submission records, NDPS Act amendment tracking, government health scheme reimbursement schedules, and PLI scheme beneficiary disclosures. Bottom-up demand modeling across administration routes and therapy areas was triangulated with top-down market sizing.
Historical consumption patterns for injectable morphine, oral oxycodone, and transdermal fentanyl were cross-referenced against panel input from formulary directors regarding protocol adoption timelines. Segmentation dimensions modeled encompass product type, therapy area, administration route, and end-user channel across the projection horizon. CAGRs were derived from elasticity-adjusted demand projections incorporating cancer incidence trajectories, hospice infrastructure accreditation rates, and regulatory pathway liberalization scenarios. Forecast inputs included CDSCO review timeline distributions and state FDA cold-chain verification cost structures.
The model assumes a particular technology adoption path for intelligent dispensing cabinet deployment; alternative pathways for automated narcotic reconciliation would alter the outlook for pharmacy labor cost savings and compliance timeline compression. Forecasts reflect assumptions regarding NDPS Act amendment passage timing and PLI scheme API manufacturing scale-up rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
North America Analgesics Market
Pharmaceuticals
Hard Empty HPMC Capsule Market
Pharmaceuticals
Antiplatelet Drugs Market
Pharmaceuticals
Fast Melt Tablets Market
Pharmaceuticals
Global Antipsychotic Drugs Market
Pharmaceuticals
Estonia Pharmaceutical Market
Pharmaceuticals
Germany Pharmaceutical 3PL Market
Pharmaceuticals
Demerol (Meperidine) Market
Pharmaceuticals
China Plasma Protein Therapeutics Market
Pharmaceuticals
Nuclear Medicines Radioisotopes Market
Pharmaceuticals
Global Janus Kinase Inhibitor (JAK) Market
Pharmaceuticals
Global Pulmonary Drugs Market
Pharmaceuticals
Ceftriaxone Market
Pharmaceuticals
Global Urothelial Cancer Drugs Market
Pharmaceuticals
Nesiritide Market
Pharmaceuticals
Nefopam Hydrochloride Injection Market