
 Over-The-Counter Pain Medication Market | 2026-2036
Over-The-Counter Pain Medication Market Size, Share, and Industry Trends Forecast 2026-2036
Over-The-Counter Pain Medication Market Intelligence
Subscription-based delivery models for chronic pain management is decoupling the single-transaction purchase from long-term consumer loyalty. Bayer AG leverages its strong brand recognition in traditional retail channels to counter this shift. Johnson & Johnson Services Inc. invests in digital platforms to engage consumers directly. Sanofi S.A. differentiates through its focus on combination medications for specific pain types.
Over-the-counter pain medication encompasses non-prescription drugs formulated to alleviate pain, reduce fever, and decrease inflammation. These products, such as non-steroidal anti-inflammatory drugs (NSAIDs), function by inhibiting the cyclooxygenase (COX) enzyme. The active ingredient segment shows ibuprofen and acetaminophen holding dominant volume share due to established safety profiles. Within dosage forms, tablets remain the mature category, while liquid formulations target pediatric and geriatric consumer types.
Regulatory frameworks established by the US FDA and the European Medicines Agency (EMA) dictate strict guidelines for product labeling, dosage limits, and marketing claims. In parallel, China's NMPA oversees market access and enforces GB standards for active pharmaceutical ingredients. Navigating the divergent pathways for prescription-to-OTC switching across these key jurisdictions remains a central strategic challenge for manufacturers.
Market Dynamics
The central structural force shaping the market is the regulatory reclassification of established prescription drugs to over-the-counter status. This dynamic, led by agencies like the US FDA, fundamentally alters product portfolios and expands consumer access without medical consultation.
Growth Catalysts
- Demographic Shifts:A growing global geriatric population, particularly in developed nations like Japan and Germany, presents a sustained demand base for chronic pain management solutions, especially for conditions like arthritis.
- Rx-to-OTC Switching:Regulatory frameworks, such as the pathway defined by the European Medicines Agency, that permit the switch of proven prescription medications to OTC status unlock new revenue streams from established molecules.
- Emerging Market Health Literacy:Rising disposable incomes and health awareness in countries like China and Brazil are expanding the consumer base for self-medication, supported by improving retail pharmacy infrastructure.
Market Restraints
- Stringent Regulatory Scrutiny:The high bar for demonstrating safety and efficacy for new active ingredients, set by bodies like the US FDA, creates significant R&D costs and extends time-to-market, limiting novel product introductions.
- Private Label Competition:The proliferation of store-brand equivalents offered by large retailers erodes brand loyalty and puts significant downward pressure on the pricing power of established national brands.
- Substitution by Non-Pharmacological Therapies:Growing consumer interest in physical therapy, acupuncture, and wellness practices as alternatives for pain management presents a non-chemical substitution threat to the core OTC drug market.
Strategic Opportunities
- Digital Health Integration:Developing companion mobile applications for dosage tracking, symptom monitoring, and telehealth consultations offers a channel to build direct consumer relationships and enhance product value beyond the pill.
- Targeted Formulation Development:There is significant white space for creating combination products and novel delivery systems, such as fast-dissolving tablets or topical patches, designed for specific pain types or patient groups.
- Geographic Expansion in Southeast Asia:Markets such as Indonesia and Vietnam, with their large populations and developing healthcare systems, represent significant untapped regions for market entry and expansion.
Industry Challenges
- Navigating Divergent Regulations:Manufacturers face operational complexity in aligning product formulations, labeling, and marketing claims with the disparate requirements of the US FDA, EMA, and China's NMPA.
- Combating Counterfeit Products:Ensuring supply chain integrity to prevent the infiltration of fake and substandard medications is a persistent operational challenge, particularly in developing economies with less-regulated distribution channels.
- Product Differentiation in a Mature Market:Communicating a unique value proposition for well-established active ingredients like ibuprofen and acetaminophen requires sophisticated marketing and innovation in dosage form or branding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Over-The-Counter Pain Medication Market |
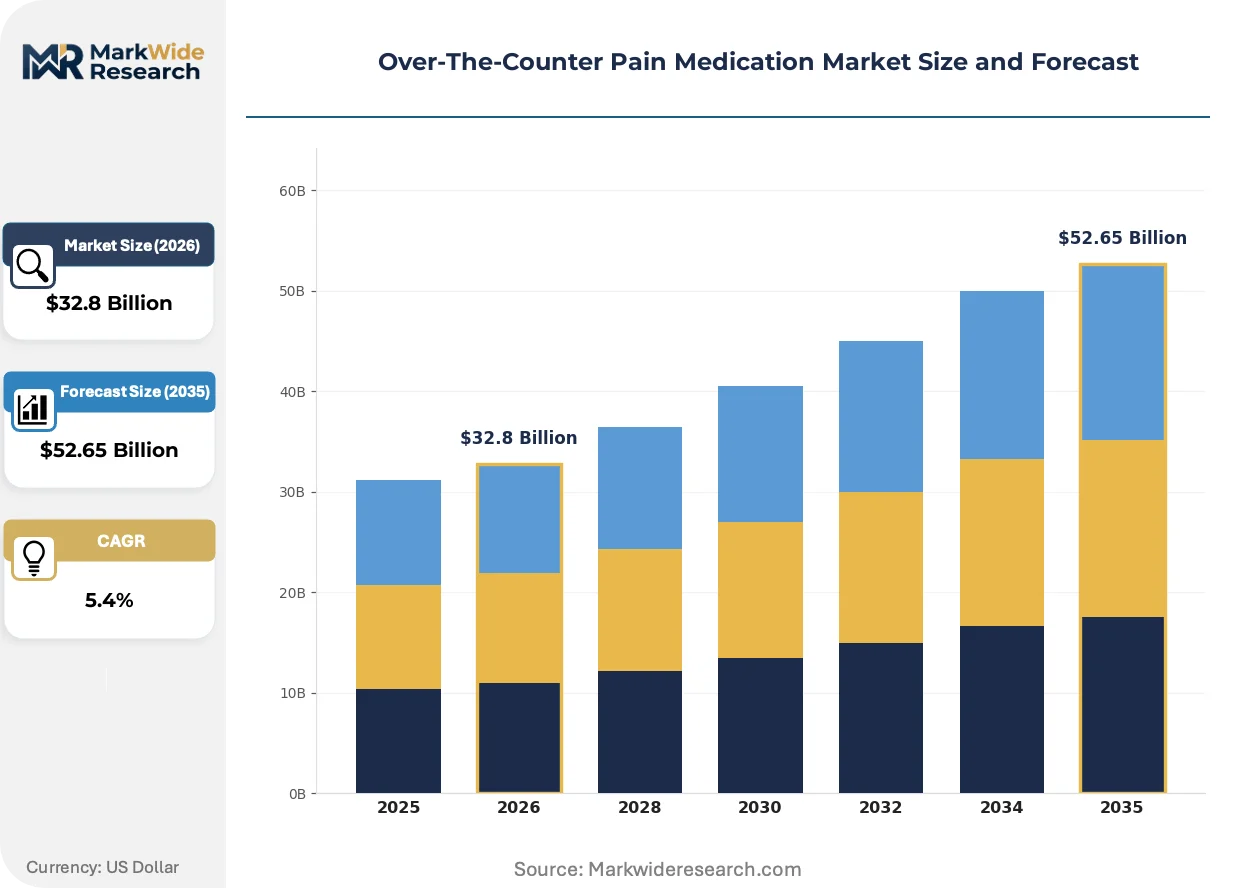
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $52.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Antipyretics, NSAIDs, Combination Medications Active Ingredient: Aspirin, Acetaminophen, Ibuprofen, Naproxen Dosage Form: Tablets, Capsules, Liquid, Powders Consumer Type: Adults, Children, Seniors, Healthcare Professionals |
| Companies Covered | Johnson & Johnson Services Inc., Pfizer Inc., Bayer AG, Sanofi S.A., GlaxoSmithKline plc, Teva Pharmaceutical Industries Ltd, Sun Pharmaceutical Industries Ltd, Novartis AG, Boehringer Ingelheim International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Over-The-Counter Pain Medication Market Strategic Shifts & Innovations
Personalization is reshaping consumer expectations in pain management, moving the focus from broad-spectrum analgesics to solutions tailored for specific pain types, user demographics, and lifestyle needs. This evolution is driven by a convergence of digital tools and formulation science.
Digital companion apps provide functionalities like dosage reminders, pain journaling, and educational content. Younger, digitally-fluent consumer segments are the earliest adopters of these integrated health management tools. The OTC medication category is absorbing this technology to build brand ecosystems that extend beyond the single transaction, fostering long-term consumer engagement.
The established Rx-to-OTC switch pathway, governed by agencies like the US FDA and Australia's TGA, continues to be a primary innovation channel. This regulatory mechanism enables proven prescription-strength ingredients to become accessible to the mass market after rigorous safety reviews. The process most impacts mature therapeutic classes, requiring manufacturers to invest heavily in consumer behavior studies to ensure proper self-selection and use.
Heightened consumer scrutiny over ingredient lists is compelling brands to reformulate products with fewer inactive additives and more transparent labeling. This demand for "clean label" products is disrupting purchasing habits, especially in the pediatric and women's health categories. The shift is most visible in North American and Western European markets, where wellness-conscious consumers actively seek products perceived as more natural.
Over-The-Counter Pain Medication Market Segmentation
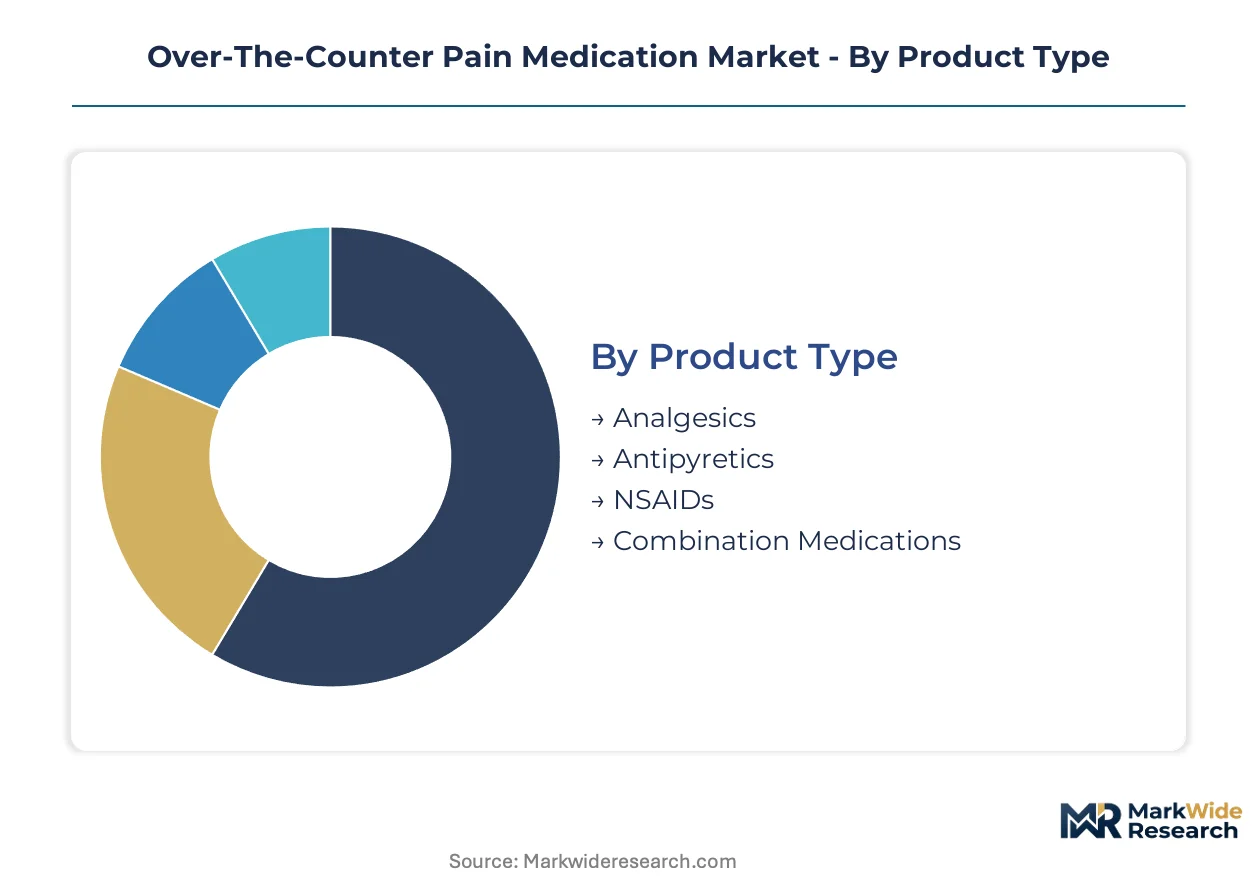
The Over-The-Counter Pain Medication Market segments reveal distinct consumer needs and product development priorities. Understanding these divisions allows manufacturers to align product portfolios with specific pain profiles, demographic requirements, and evolving regulatory landscapes. This granular view is essential for strategic market entry and sustained commercial success.
Product Type:
Product type segmentation highlights varying investment requirements for R&D and regulatory approval processes.
- Analgesics:These medications primarily target pain relief, often without significant anti-inflammatory effects. Demand concentrates in general self-medication contexts across all geographies, driven by accessibility and broad efficacy.
- NSAIDs:Non-steroidal anti-inflammatory drugs reduce pain, inflammation, and fever by inhibiting cyclooxygenase enzymes. Demand is particularly strong in markets with high incidence of chronic inflammatory conditions like arthritis, such as Japan and Germany.
- Antipyretics:These medications specifically reduce fever, often used for symptomatic relief during infections.
- Combination Medications:These products combine two or more active ingredients to address multiple symptoms simultaneously.
Most installed capacity flows through Analgesics. Expansion is steepest in Combination Medications.
Active Ingredient:
Active ingredient categories reflect different stages of market maturity and volume dominance.
- Ibuprofen:A widely used non-steroidal anti-inflammatory drug known for its anti-inflammatory, analgesic, and antipyretic properties. Demand is robust across developed markets like the United States and the United Kingdom, supported by its established safety profile and broad application.
- Acetaminophen:Primarily an analgesic and antipyretic, often preferred for its lower gastrointestinal side effects. Demand is high in pediatric and geriatric segments globally, owing to its perceived gentleness and established use.
- Aspirin:An older non-steroidal anti-inflammatory drug still used for pain, fever, and its antiplatelet effects.
- Naproxen:A longer-acting non-steroidal anti-inflammatory drug, often chosen for sustained pain relief, particularly for chronic conditions.
Acetaminophen and Ibuprofen collectively hold the largest volume share. Naproxen is gaining share fastest in specific chronic pain indications.
Dosage Form:
Dosage form differentiation directly addresses varied consumer preferences and specific application needs.
- Tablets:This is the most traditional and widely available dosage form, offering convenience and precise dosing. Demand remains foundational across all consumer types, especially in mature markets like the United States and France due to cost-effectiveness.
- Liquid:Formulations designed for ease of swallowing, particularly beneficial for pediatric and geriatric populations. Demand is concentrated in markets with aging demographics and high birth rates, such as China and Brazil, supporting specific consumer types.
- Capsules:Often preferred for faster absorption or to mask unpleasant tastes, providing an alternative to tablets.
- Powders:These forms can offer quick dissolution and absorption, sometimes mixed with beverages for consumption.
Tablets represent the most widespread distribution. Liquid formulations are expanding most quickly.
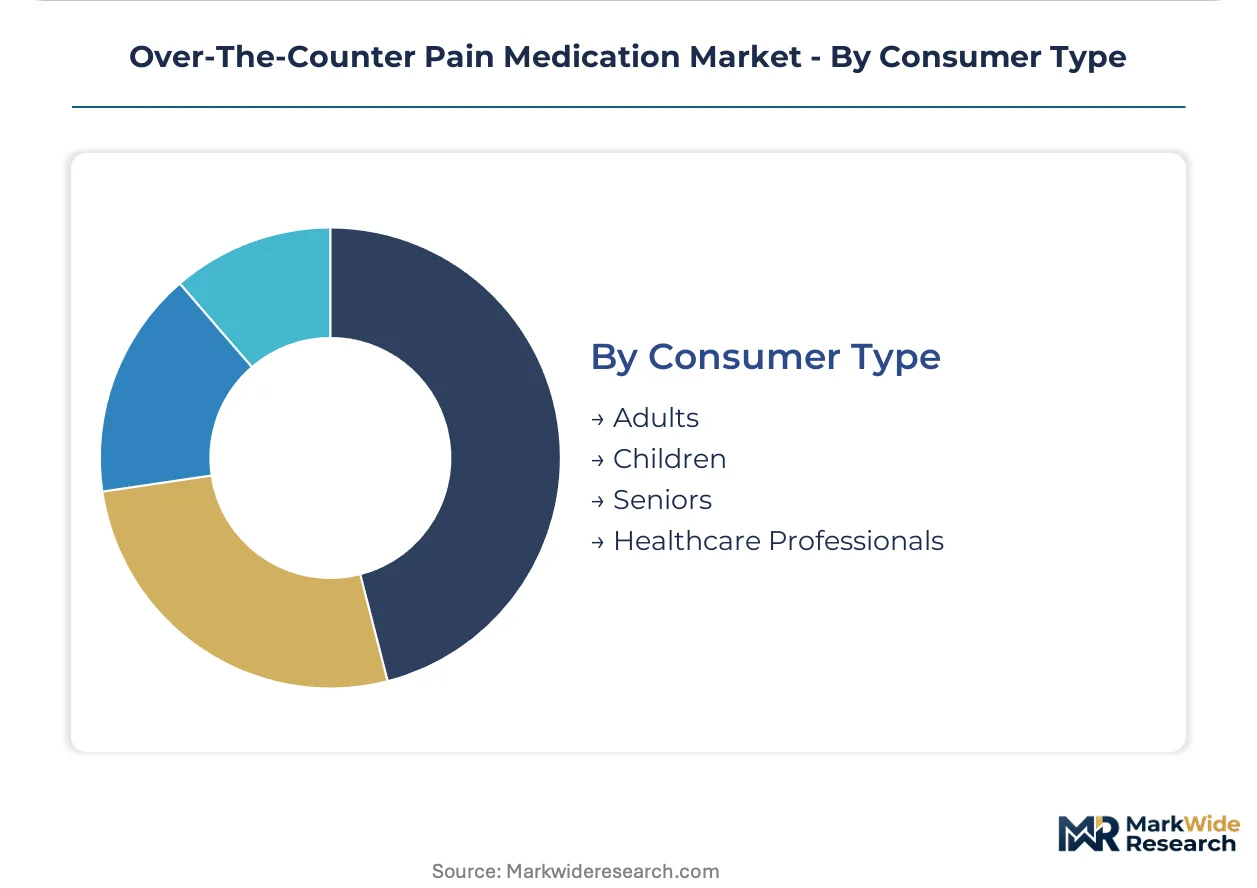
Consumer Type:
Consumer type segmentation influences product formulation, packaging, and pricing strategies.
- Adults:This is the largest consumer segment, requiring a broad range of pain relief options for acute and chronic conditions. Demand is ubiquitous, with specific product innovations targeting lifestyle-related pain points.
- Seniors:This demographic often requires specialized formulations due to comorbidities and polypharmacy considerations. Demand is significantly increasing in developed nations like Japan and Germany, driven by demographic shifts and prevalence of age-related pain.
- Children:This segment requires precise dosing and palatable formulations, often with specific active ingredient restrictions.
- Healthcare Professionals:Though not direct consumers, this segment influences recommendations and formulary choices for Over-The-Counter products.
Adults constitute the primary consumer base by volume. The seniors segment shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Over-The-Counter Pain Medication Market displays varied growth trajectories, with the United States driving innovation in Rx-to-OTC switching while China experiences significant expansion due to emerging health literacy. These regional differences highlight distinct market drivers and regulatory environments influencing product availability and consumer adoption across diverse economies.
United States
Demand for OTC pain medication in the United States benefits from a large adult consumer base and the continuous reclassification of prescription drugs. The US FDA's rigorous pathway for Rx-to-OTC switching expands product availability without medical consultation. Pharmaceutical R&D hubs in New Jersey and Boston actively innovate new formulations and delivery systems for the market.
China
China's market expansion is fueled by rising disposable incomes and increasing health awareness among its vast population. The China NMPA oversees market access and enforces GB standards, ensuring product quality and safety. Major urban centers like Shanghai and Beijing drive retail pharmacy infrastructure improvements, enhancing product accessibility for consumers.
Germany
Germany presents a sustained demand base for chronic pain management solutions, driven by its aging population and high incidence of conditions like arthritis. The European Medicines Agency (EMA) provides regulatory frameworks that permit the switch of proven prescription medications to OTC status. Pharmaceutical manufacturing in regions like Bavaria focuses on producing NSAIDs and other analgesics for both domestic and export markets.
Japan
Japan's significant senior consumer segment drives consistent demand for pain relief, particularly for age-related conditions. The PMDA ensures stringent safety reviews for new OTC products, maintaining high consumer trust. Tokyo's research institutions and pharmaceutical companies collaborate on developing novel analgesic formulations and delivery technologies.
India
India's market for OTC pain medication is expanding due to a growing consumer base for self-medication and improving retail infrastructure. The CDSCO regulates product approvals and monitors quality standards for pharmaceutical products across the country. Pharmaceutical clusters in Hyderabad and Mumbai are increasing production capacities for various OTC pain medications to meet domestic demand.
Over-The-Counter Pain Medication Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the Over-The-Counter Pain Medication Market. The market structure exhibits a tiered consolidation, with established pharmaceutical giants dominating core segments while smaller, agile players target niche formulations. Strategic archetypes include global diversified healthcare companies, specialized consumer health divisions, and regional generic manufacturers. Dominant competitive moves involve investment in digital platforms for direct consumer engagement and geographic expansion into emerging markets.
Global diversified healthcare companies like Johnson & Johnson Services Inc. leverage extensive brand portfolios and robust distribution networks to maintain market leadership. Bayer AG, a German multinational, occupies a strong position through its brand recognition in traditional retail channels. Sanofi S.A., a French pharmaceutical company, exemplifies product differentiation through its focus on combination medications for specific pain types, catering to evolving consumer needs.
| Leading Market Players |
|---|
| Johnson & Johnson Services Inc. |
| Pfizer Inc. |
| Bayer AG |
| Sanofi S.A. |
| GlaxoSmithKline plc |
| Teva Pharmaceutical Industries Ltd |
| Sun Pharmaceutical Industries Ltd |
| Novartis AG |
| Boehringer Ingelheim International GmbH |
| Others |
Cost & Logistics Intelligence
Product differentiation across branded and private-label offerings creates a clear divergence in pricing power, directly influencing supply chain configurations for active pharmaceutical ingredients and finished goods. This bifurcation shapes investment in manufacturing capacity and distribution network sophistication globally.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for generic active pharmaceutical ingredients, intensifying competition across the market. The dominant pricing model remains per-unit transactional, though subscription-based delivery models for chronic pain management are emerging. Price differentiation stems from brand premium and specific FDA or EMA certification levels for Rx-to-OTC switched products. Pricing softness reflects the proliferation of store-brand equivalents, particularly in mature markets. Consumers seeking specialized combination medications exhibit lower price sensitivity than those purchasing basic analgesics.
Supply Chain Analysis
Workforce availability and skilled labor pools in India and China underpin a significant portion of global active pharmaceutical ingredient (API) manufacturing for OTC pain medications. The supply chain sources heavily from these regions for key inputs like ibuprofen and acetaminophen, alongside excipients and specialized packaging materials. Regulatory divergence across jurisdictions, including the US FDA, EMA, and China NMPA, presents a structural supply chain risk, necessitating localized compliance efforts. Distribution runs primarily through established retail pharmacy chains, supplemented by expanding e-commerce platforms and institutional procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Over-The-Counter Pain Medication Market presents a margin-expansion story, driven by strategic shifts towards premium combination medications and integrated digital health solutions.
For Market Incumbents: Acquire digital health platforms to deepen consumer engagement and build brand ecosystems beyond the pill. Invest heavily in Rx-to-OTC switch candidates to counter private label competition eroding market share. Reinforce channel control through strategic partnerships with major retail pharmacy chains, ensuring prominent product placement and consumer access. Expand R&D into novel delivery systems for established active ingredients, maintaining product differentiation.
For New Entrants and Emerging Players: Enter via targeted formulation development for specific pain types or underserved consumer segments, such as fast-dissolving tablets for seniors. Focus geographic expansion efforts on high-growth regions like Southeast Asia, leveraging improving retail pharmacy infrastructure. Implement a direct-to-consumer digital marketing strategy emphasizing clean label ingredients and transparent sourcing, appealing to wellness-conscious consumers. Prioritize pediatric or geriatric liquid formulations in emerging markets like Indonesia.
For Investors and Strategic Acquirers: Asymmetric upside sits with consumer health divisions possessing strong Rx-to-OTC pipelines and robust digital health integration capabilities. Focus long-term viability on companies positioned to capitalize on demographic shifts and increasing health literacy over the next decade. Acquisition targets should include innovative digital health startups offering companion apps or specialized consumer health brands with strong regional penetration. The signal to watch is increased regulatory approvals for Rx-to-OTC switches in major markets like the US and Europe.
| Strategic Initiative | Industry Significance |
|---|---|
| Rx-to-OTC Switch Investment | Secures new revenue streams from proven molecules with regulatory backing. |
| Digital Platform Integration | Enhances consumer engagement and builds brand loyalty beyond product purchase. |
| Combination Medication Development | Addresses specific pain types, differentiating products in a mature market. |
| Geographic Expansion in Southeast Asia | Taps into large, underserved populations with growing health awareness. |
| Clean Label Reformulation | Meets rising consumer demand for transparent ingredient lists and perceived naturalness. |
Research Approach
Direct dialogue with regulatory affairs leads, R&D directors, and retail pharmacy managers provided crucial qualitative insights into market dynamics. This primary research was rigorously validated through secondary data sources including US FDA filings, European Medicines Agency (EMA) submissions, China NMPA announcements, and various industry association reports. A comprehensive bottom-up and top-down triangulation approach ensured the accuracy and consistency of market sizing and segmentation across all data points.
The quantitative model produced volume and value projections across the analysis window, integrating historical trends and projected market dynamics. Segmentation dimensions modeled included product type, active ingredient, dosage form, consumer type, and regional regulatory cluster. Compound Annual Growth Rates (CAGRs) were derived from historical growth patterns and anticipated shifts in consumer behavior and regulatory frameworks. Key industry-specific forecast inputs included the Rx-to-OTC switch pipeline and global aging population demographics.
Inputs from public health databases and regulatory filings were available through the study window; gaps in real-time consumer purchasing data introduce uncertainty bands. Forecasts reflect assumptions regarding regulatory stability and sustained consumer preference for self-medication. Material deviation in unforeseen regulatory changes or rapid shifts in consumer self-medication preferences warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Bone Pain Treatment Market
Pain Management
Pain Management Devices Market
Pain Management
Advanced Cancer Pain Management Market
Pain Management
Global Fibromyalgia Treatment Market
Pain Management
Erythromelalgia Treatment Market
Pain Management
Pain Management Therapeutics Market
Pain Management
Pain Management Software Market
Pain Management
Palliative Care Market
Pain Management
Provoked Vestibulodynia Treatment Market
Pain Management
Visceral Pain Market
Pain Management
Neuralgia Treatment Market
Pain Management
Cold Pain Therapy Market
Pain Management
Pain Relief Oil Market
Pain Management
Global Non-Opioid Pain Patch Market
Pain Management
Medicated Pain Relieving Plasters Market
Pain Management
Intravenous (IV) Ibuprofen Market