
 Global Postoperative Pain Management Market | 2026-2036
Global Postoperative Pain Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Postoperative Pain Management Market Foresight
Multimodal analgesia protocols are redrawing competitive requirements across the postoperative pain landscape. Pfizer Inc. leverages its manufacturing scale to sustain supply security for hospital-formulated NSAID combinations. Johnson & Johnson anchors its position through specialized epidural delivery systems and sustained-release local anesthetic platforms. Pacira BioSciences differentiates via liposomal bupivacaine technology and targeted infiltration techniques for orthopedic procedures.
Postoperative pain management encompasses pharmacological and interventional therapies administered following surgical incision to attenuate nociceptive signaling, maintain respiratory and cardiovascular stability, and enable early mobilization through agents with defined half-lives, receptor selectivity profiles, and delivery precision. Opioids retain the largest revenue footprint yet face structural pressure from REMS-mandated prescribing limits, while local anesthetics and patient-controlled analgesia devices capture accelerated growth as hospitals adopt ERAS protocols demanding opioid-sparing regimens. Ambulatory surgery centers represent the fastest-expanding end-user channel, driven by same-day discharge mandates and portable infusion pump miniaturization.
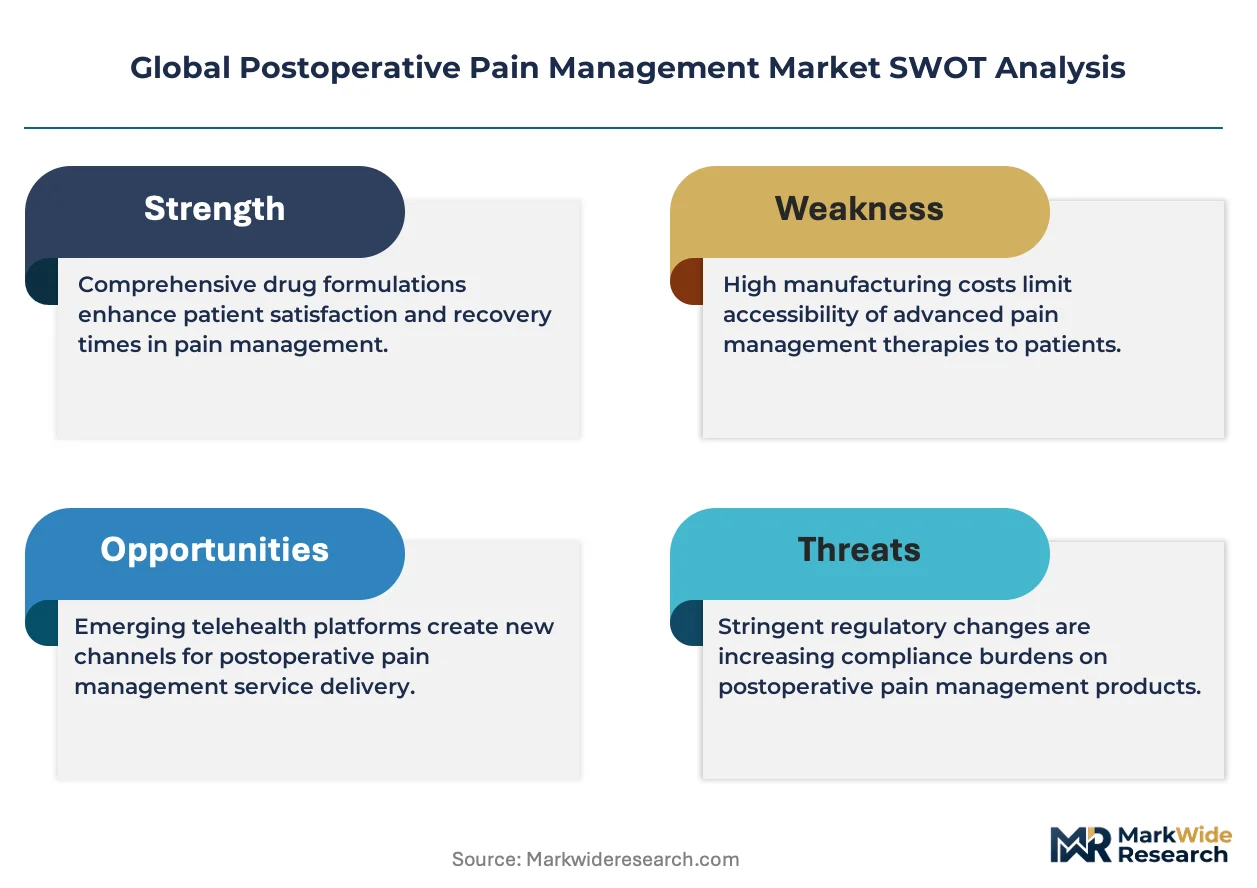
The FDA's REMS framework for extended-release opioids and the EMA's pharmacovigilance requirements for tramadol-containing products reshape formulation development priorities, forcing manufacturers toward abuse-deterrent technologies and non-scheduled alternatives. Japan's PMDA accelerated review pathways for novel regional anesthesia devices create asymmetric market access advantages for technology holders. Stakeholders must monitor evolving reimbursement thresholds for outpatient nerve block catheters and the shifting liability landscape surrounding opioid stewardship mandates.
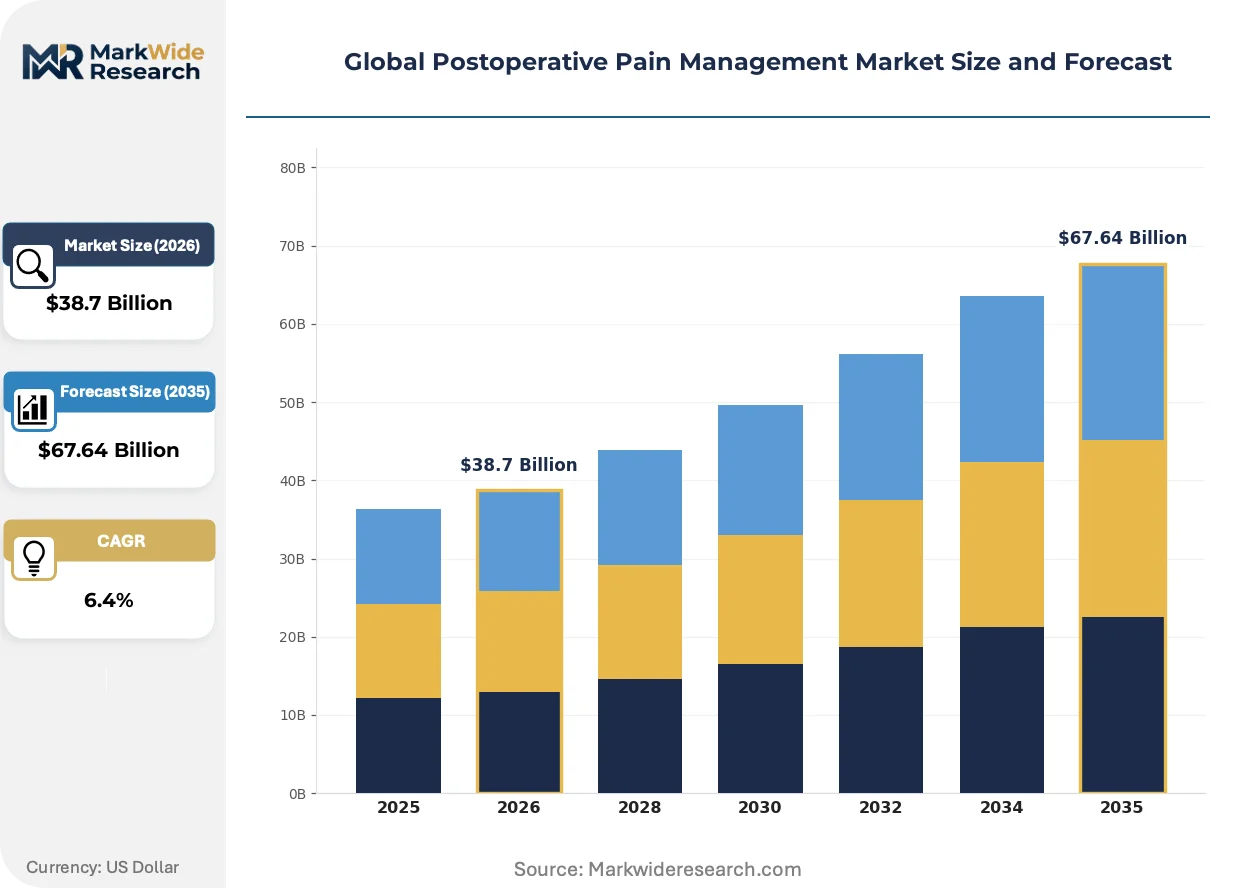
Market Dynamics
The FDA's REMS framework for extended-release opioids is compressing prescribing volumes and forcing hospital systems toward multimodal protocols that integrate regional anesthesia with non-opioid pharmacology. This regulatory pressure is redrawing procurement priorities across surgical service lines.
Growth Catalysts
- ERAS Protocol Mandates:Enhanced Recovery After Surgery pathways in Germany and Japan now require documented opioid-sparing regimens, accelerating adoption of liposomal local anesthetics and nerve block catheters in orthopedic and colorectal procedures.
- Ambulatory Surgery Expansion:Same-day discharge requirements in the United States are driving demand for portable infusion pumps and long-acting regional anesthesia formulations that enable safe home transition without oral opioid prescriptions.
- PMDA Accelerated Review:Japan's Pharmaceuticals and Medical Devices Agency has established priority pathways for novel regional anesthesia devices, creating faster market access for catheter systems and sustained-release formulations compared to standard pharmaceutical approvals.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Bupivacaine and ropivacaine raw material supply concentrates among three specialty chemical manufacturers in India and China, creating vulnerability to export restriction shocks or quality enforcement actions.
- REMS Compliance Burden:The FDA's mandatory prescriber certification and patient counseling requirements for extended-release opioids impose fixed administrative costs that disproportionately burden smaller ambulatory surgery centers with limited pharmacy infrastructure.
- Catheter-Related Infection Liability:Indwelling peripheral nerve block catheters carry documented infection risk profiles that elevate malpractice insurance premiums and constrain adoption in outpatient settings despite analgesic efficacy.
Strategic Opportunities
- Untapped Oncology Surgery:Thoracic and major abdominal cancer resections in France and Italy remain underpenetrated by regional anesthesia techniques, presenting white space for catheter-based analgesia protocols that reduce postoperative pulmonary complications.
- Biodegradable Depot Formulations:Convergence of polymer chemistry with local anesthetic pharmacokinetics is enabling single-injection formulations providing 72-96 hour analgesia, eliminating catheter management burden and expanding candidacy for outpatient joint replacement.
- India's PLI Scheme:The country's Production Linked Incentive scheme for medical devices is attracting contract manufacturing investment for infusion pumps and disposable regional anesthesia kits, creating localized supply bases for Asia-Pacific distribution.
Industry Challenges
- Regional Anesthesia Skill Scarcity:Ultrasound-guided catheter placement requires specialized training that anesthesiology residency programs in the United States and Germany are struggling to scale, creating bottlenecks for ERAS protocol rollout.
- Legacy EHR Integration:Patient-controlled analgesia pumps from incumbent manufacturers utilize proprietary data protocols that resist integration with modern hospital electronic health record systems, forcing manual documentation workflows that increase nursing burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Postoperative Pain Management Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Opioids, Non-Steroidal Anti-Inflammatory Drugs, Local Anesthetics, Patient-Controlled Analgesia Devices Application: Orthopedic Surgery, Cardiothoracic Surgery, General Surgery, Cosmetic Surgery End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Home Healthcare Providers Delivery Method: Intravenous, Oral, Epidural, Transdermal, Peripheral Nerve Blocks |
| Companies Covered | Pfizer Inc., Johnson & Johnson, AbbVie, Teva Pharmaceuticals, Hikma Pharmaceuticals, Pacira BioSciences, Heron Therapeutics, Novartis AG, Mallinckrodt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Postoperative Pain Management Market Shifts & Advancements
Device miniaturization and pharmacological depot engineering are converging to enable opioid-free ambulatory discharge, while regulatory frameworks on three continents simultaneously tighten stewardship requirements and accelerate novel technology review.
Portable elastomeric infusion pumps are miniaturizing to sub-100 gram form factors with programmable flow rates and Bluetooth-enabled dose tracking. Ambulatory surgery centers in the United States and Germany are adopting these devices for same-day total joint replacement, enabling continuous local anesthetic delivery without hospital admission. The technology is miniaturizing the physical footprint of postoperative analgesia, collapsing the distinction between inpatient and outpatient pain management infrastructure.
REACH regulation amendments in the European Union are imposing new disclosure requirements on medical device polymers and lubricants used in catheter manufacturing. Manufacturers serving the European market must now document substance safety profiles across extended supply chains, adding 12-18 month certification timelines for new product introductions. The regulation is compressing formulation flexibility for regional anesthesia delivery systems and favoring established suppliers with pre-validated material portfolios.
Hospital procurement committees are consolidating vendor relationships for multimodal analgesia bundles that span pharmaceuticals, devices, and training support. Integrated delivery networks in the United States are displacing fragmented purchasing of opioids, local anesthetics, and pumps separately, instead contracting with single-source regional anesthesia platform providers. This concentration is most visible in California and Texas health systems where value-based surgical contracts create incentive alignment for total episode cost reduction.
Global Postoperative Pain Management Market Segmentation
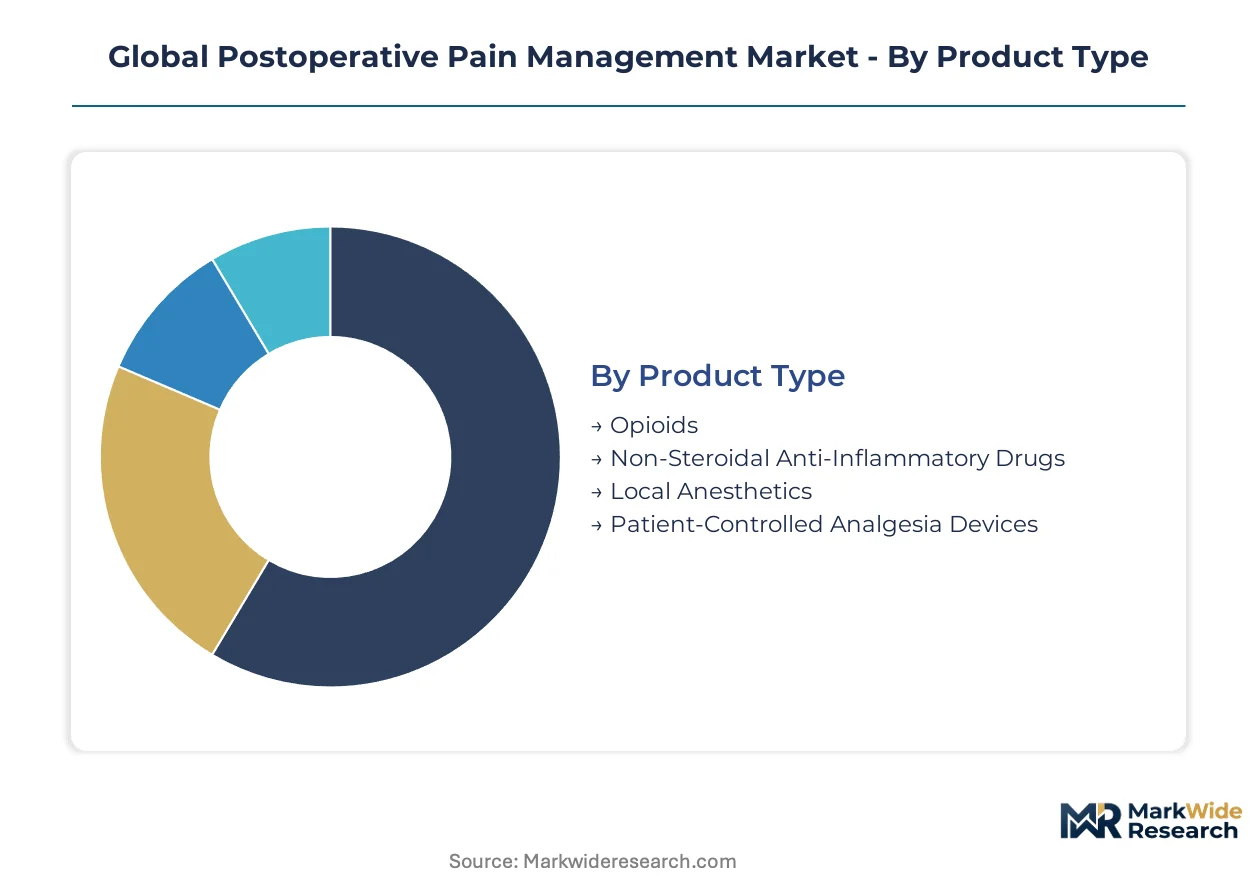
Postoperative pain management segments diverge sharply across regulatory exposure and care setting economics. Product type stratification reflects opioid liability pressures versus device-enabled regional anesthesia expansion. Application and end-user splits track surgical volume migration from inpatient to ambulatory environments.
Product Type:
Geographic demand concentration varies dramatically: opioids face contracting prescription volumes in US and German hospital systems under REMS and EMA pharmacovigilance mandates, while local anesthetics and PCA devices capture export-led expansion into Japanese and Indian markets prioritizing ERAS adoption.
- Opioids:Extended-release and immediate-release formulations retain substantial revenue footprint despite structural headwinds. Demand concentrates in US inpatient settings where REMS compliance infrastructure exists, though prescribing volumes face mandatory certification burdens and patient counseling requirements that disproportionately burden smaller surgical centers.
- Local Anesthetics:Liposomal bupivacaine and sustained-release ropivacaine formulations enable multimodal protocols. Japanese hospitals and German orthopedic centers drive fastest uptake as PMDA accelerated review pathways and statutory ERAS documentation requirements create procurement priority for single-injection depot formulations.
- Non-Steroidal Anti-Inflammatory Drugs:Hospital-formulated IV combinations sustain procurement in US integrated delivery networks seeking opioid-sparing alternatives for colorectal and thoracic procedures.
- Patient-Controlled Analgesia Devices:Portable elastomeric pumps with Bluetooth tracking miniaturize to sub-100 gram form factors for ambulatory discharge. Indian PLI scheme incentives attract contract manufacturing investment for Asia-Pacific distribution.
Opioids hold the largest share; momentum sits with local anesthetics.
Application:
Procedure complexity and reimbursement economics stratify adoption depth: high-volume orthopedic interventions in ambulatory settings drive device-intensive protocols, while cardiothoracic and major abdominal procedures retain inpatient infrastructure requirements.
- Orthopedic Surgery:Joint replacement and spine procedures generate highest absolute demand for regional anesthesia. US ambulatory surgery centers in Texas and California health systems adopt same-day total joint protocols with continuous peripheral nerve block catheters, though catheter-related infection liability constrains outpatient candidacy.
- Cardiothoracic Surgery:Sternotomy and thoracotomy pain management requires epidural or paravertebral techniques with respiratory complication reduction as primary outcome. French and Italian oncology resections remain underpenetrated by regional anesthesia, presenting expansion opportunity for catheter-based protocols.
- General Surgery:Colorectal resections in German hospitals mandate documented opioid-sparing regimens under ERAS protocols, accelerating liposomal local anesthetic infiltration adoption.
- Cosmetic Surgery:Outpatient facial and body contouring procedures favor oral NSAID combinations with limited device penetration due to procedure brevity and aesthetic practice economics.
Orthopedic surgery commands dominant volume; cosmetic surgery climbs fastest on ambulatory expansion.
End User:
Capital intensity and regulatory compliance capacity separate institutional tiers: hospitals absorb multimodal protocol training costs and EHR integration burdens, while ambulatory and home settings demand portable, nurse-efficient delivery systems.
- Hospitals:Academic medical centers in the United States and university hospitals in Germany anchor procurement for complex multimodal bundles spanning pharmaceuticals, pumps, and anesthesiology training support. Value-based surgical contracts in California and Texas create incentive alignment for total episode cost reduction.
- Ambulatory Surgery Centers:Same-day discharge mandates drive fastest expansion for portable infusion pumps and long-acting regional formulations. REMS administrative burdens for extended-release opioids disproportionately constrain smaller centers with limited pharmacy infrastructure.
- Specialty Clinics:Orthopedic-focused facilities in Japan leverage PMDA priority pathways for novel regional anesthesia devices, creating faster technology access than standard pharmaceutical approvals.
- Home Healthcare Providers:Discharge with indwelling catheters requires nursing visit infrastructure and infection monitoring protocols that limit geographic penetration to urban US markets with established home infusion networks.
Hospitals retain dominant spend; ambulatory surgery centers gain share fastest on discharge compression.
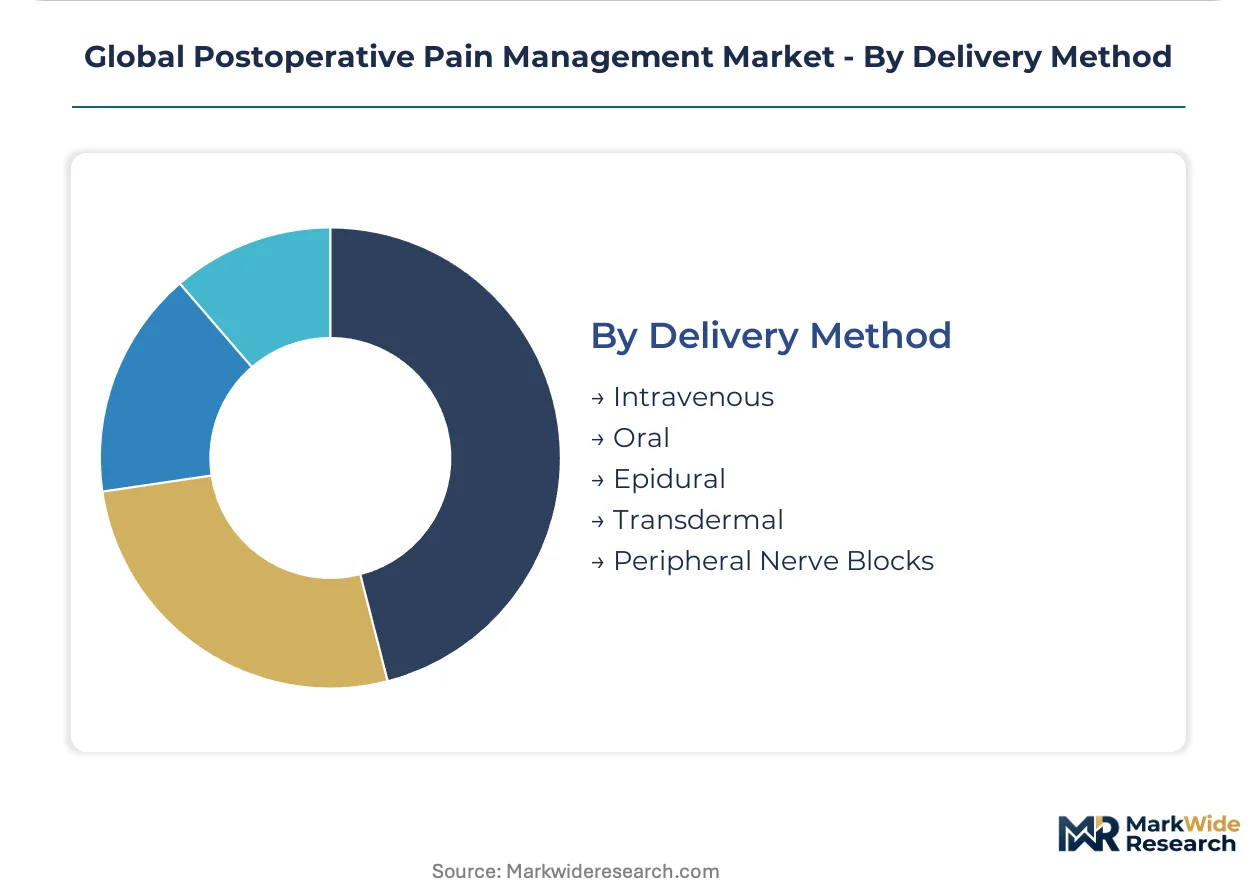
Delivery Method:
Technical sophistication and anesthesiology workforce availability determine regional penetration: ultrasound-guided catheter placement requires specialized training that US and German residency programs struggle to scale, creating adoption bottlenecks for advanced techniques.
- Peripheral Nerve Blocks:Continuous catheter techniques with programmable elastomeric pumps enable opioid-free ambulatory discharge. REACH regulation amendments impose 12-18 month certification timelines for European catheter polymers, favoring established suppliers with pre-validated material portfolios.
- Epidural:Specialized delivery systems with sustained-release local anesthetic platforms sustain inpatient orthopedic and obstetric demand. Johnson & Johnson anchors position through catheter technology and pump integration.
- Intravenous:Patient-controlled opioid and NSAID administration retains legacy infrastructure across hospital surgical floors, though proprietary pump data protocols resist EHR integration and force manual nursing documentation.
- Oral:Immediate-release formulations face prescribing compression under REMS frameworks, shifting toward abuse-deterrent technologies and non-scheduled alternatives in development pipelines.
- Transdermal:Fentanyl patches encounter EMA pharmacovigilance restrictions for tramadol-containing products, limiting formulation flexibility and redirecting investment toward non-opioid transdermal platforms.
Intravenous delivery holds installed base dominance; peripheral nerve blocks expand most quickly on ambulatory protocol adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for active pharmaceutical ingredients concentrate supply vulnerability in South Asian manufacturing clusters, while finished device and formulation demand gravitates toward markets with stringent ERAS adoption mandates and reimbursement frameworks favoring outpatient transition.
United States
Hospital systems in California and Texas anchor procurement for multimodal analgesia bundles under value-based surgical contracts. FDA REMS certification requirements for extended-release opioids compress prescribing volumes and redirect procurement toward regional anesthesia platforms. Same-day discharge mandates in ambulatory surgery centers across the Southwest and Southeast drive portable elastomeric pump adoption.
Germany
University hospitals in Bavaria and North Rhine-Westphalia mandate documented opioid-sparing regimens under statutory ERAS protocols for colorectal and orthopedic procedures. EMA pharmacovigilance requirements for tramadol-containing products reshape hospital formulary priorities. Catheter-based regional anesthesia training programs in Baden-Württemberg face workforce scaling constraints.
Japan
Metropolitan hospitals in Tokyo and Osaka leverage PMDA accelerated review pathways for novel regional anesthesia devices, creating faster market access than standard pharmaceutical approvals. Aging demographics and surgical volume expansion in Kansai drive demand for single-injection depot formulations. Specialty orthopedic clinics in Chubu adopt sustained-release local anesthetic platforms ahead of national reimbursement revisions.
India
Specialty chemical manufacturers in Gujarat and Maharashtra concentrate global supply of bupivacaine and ropivacaine raw materials, creating exposure to export restriction shocks. The PLI scheme for medical devices attracts contract manufacturing investment for infusion pumps in Karnataka and Tamil Nadu. Domestic hospital chains in Delhi-NCR and Hyderabad pilot ERAS protocols for orthopedic and oncologic procedures.
France
Thoracic and major abdominal cancer resections in Île-de-France and Auvergne-Rhône-Alpes remain underpenetrated by regional anesthesia techniques. REACH regulation amendments impose 12-18 month certification timelines for catheter polymers, favoring established suppliers with pre-validated material portfolios. Public hospital procurement in Provence-Alpes-Côte d'Azur consolidates vendor relationships for multimodal bundles.
Global Postoperative Pain Management Market Competitive Landscape
Concentration sits with diversified pharmaceutical conglomerates possessing hospital formulary access and manufacturing scale for active pharmaceutical ingredients. The vendor base spans three functional tiers: multinational conglomerates with integrated device-pharmaceutical portfolios, mid-cap specialists in sustained-release formulation technologies, and regional generic manufacturers serving price-sensitive institutional procurement. Dominant competitive moves include strategic partnerships for catheter-pump integration and geographic licensing arrangements for liposomal delivery technologies.
Within the diversified pharmaceutical tier, Pfizer Inc. and Johnson & Johnson occupy positions reflecting manufacturing scale and hospital channel depth. Pacira BioSciences exemplifies the formulation-specialist archetype, anchoring technology-driven positioning in depot-based local anesthetic delivery. Among regional manufacturers, Hikma Pharmaceuticals and Teva Pharmaceuticals represent generic-focused strategies targeting institutional procurement with cost-optimized alternatives.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson |
| AbbVie |
| Teva Pharmaceuticals |
| Hikma Pharmaceuticals |
| Pacira BioSciences |
| Heron Therapeutics |
| Novartis AG |
| Mallinckrodt |
| Others |
Supply & Pricing Matrix
Liposomal bupivacaine substitution for conventional local anesthetic formulations is redrawing supply geography toward depot-technology manufacturers while compressing per-procedure pricing economics for standard bupivacaine vials in hospital procurement.
Pricing Analysis
Hospital procurement committees anchor pricing negotiations through multimodal bundle contracts that span pharmaceuticals, devices, and training support. Three-tier pricing structure across premium, standard, and economy levels separates liposomal depot formulations from conventional local anesthetics and commodity generic opioids. Cost compression in the opioid tier stems from REMS-mandated administrative burdens and prescribing volume caps. Ambulatory surgery centers demonstrate highest price sensitivity due to limited pharmacy infrastructure and same-day discharge economics.
Supply Chain Analysis
India and China anchor global production of bupivacaine and ropivacaine active pharmaceutical ingredients, with specialty chemical manufacturers in Gujarat and Maharashtra concentrating raw material supply. Finished formulation and device assembly draws from United States, Germany, and Japan for regional anesthesia platforms and elastomeric pump manufacturing. Single-source vulnerability concentrates in the three Indian and Chinese API suppliers, exposing the chain to export restriction shocks or quality enforcement actions. Distribution runs through hospital procurement committees and integrated delivery network contracts rather than wholesale pharmaceutical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surgical volume cyclicality tied to elective procedure deferral patterns during respiratory infection surges positions this market for recovery-phase expansion as backlogs clear and ERAS protocol investment resumes.
For Market Incumbents: Compound formulary access advantages through backward integration into liposomal formulation manufacturing and captive supply of sustained-release local anesthetic platforms. Expand training infrastructure partnerships with anesthesiology residency programs in the United States and Germany to alleviate ultrasound-guided catheter placement bottlenecks. Defend against mid-cap depot-technology specialists by securing exclusive GPO contracts with California and Texas health systems under value-based surgical arrangements. For New Entrants and Emerging Players: PMDA accelerated review pathways for novel regional anesthesia devices offer fastest regulatory access among major markets, enabling earlier commercialization than FDA or EMA routes. Target thoracic and major abdominal oncology resections in France and Italy as underpenetrated white space for catheter-based analgesia protocols. Establish go-to-market positioning through biodegradable depot formulations that eliminate catheter management burden and expand outpatient joint replacement candidacy. For Investors and Strategic Acquirers: The market sits at a capacity-expansion phase that favors formulation-technology specialists with differentiated depot platforms over commodity generic manufacturers. Long-term viability centers on opioid-sparing regimen mandates hardening across German statutory ERAS protocols and Japanese PMDA reimbursement revisions. Acquisition target archetype: mid-cap regional anesthesia device holders with pre-validated polymer portfolios under REACH certification. Watch PMDA reimbursement revision timing in Japan as inflection indicator for depot formulation adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Abuse-Deterrent Opioid | REMS compliance infrastructure requirements favor sponsors with existing prescriber certification platforms. |
| CE Marking Pathway for Regional Anesthesia Catheter | REACH polymer certification timelines favor established suppliers with pre-validated material portfolios. |
| Hospital System Partnership for ERAS Training | Integrated delivery networks in California and Texas consolidate vendor relationships for multimodal bundles. |
| Software Companion Development for PCA Pump | Bluetooth-enabled dose tracking resolves legacy EHR integration failures that force manual nursing documentation. |
| Reimbursement Strategy for Outpatient Nerve Block | CMS and commercial payer threshold shifts determine ambulatory surgery center adoption of indwelling catheter protocols. |
Research Methodology
Initial hypotheses were tested against primary input from anesthesiology department chairs, hospital procurement managers, GPO contracts specialists, and regional anesthesia device engineers and refined through secondary validation against FDA REMS documentation, EMA pharmacovigilance filings, PMDA accelerated review pathway records, and hospital formulary databases. Bottom-up procedure volume modeling and top-down pharmaceutical expenditure triangulation converged on segment-level estimates.
Variance decomposition across product type, application, end user, and delivery method dimensions structured the analytical framework over the projection horizon. CAGRs were derived from surgical volume growth rates, ERAS protocol penetration assumptions, and ambulatory surgery expansion trajectories. Forecast inputs incorporated REMS compliance cost burdens, PMDA review timeline differentials, and REACH certification lag effects for catheter polymer introductions.
Underlying assumptions cover sustained ERAS mandate enforcement, stable API export flows from Indian and Chinese manufacturers, and gradual PMDA reimbursement expansion for depot formulations, with deviation risk concentrated in regulatory restriction shocks to raw material supply and anesthesiology workforce scaling constraints. Recalibration cycles align with material shifts in FDA REMS enforcement intensity and PMDA national reimbursement revision announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Pain Management Therapeutics Market
Pain Management
Ketorolac Market
Pain Management
Asia-Pacific Chronic Disease Management Market
Pain Management
Visceral Pain Market
Pain Management
Cancer Pain Market
Pain Management
Axial Spondyloarthritis Management Market
Pain Management
Cancer Pain Management Market
Pain Management
Topical Pain Relief Market
Pain Management
Over-The-Counter Pain Medication Market
Pain Management
Heat Therapy Market
Pain Management
Palliative Care Market
Pain Management
Global Post Herpetic Neuralgia Treatment Market
Pain Management
OTC Painkiller Market
Pain Management
Pain Management Devices Market
Pain Management
Cold Pain Therapy Market
Pain Management
Neuropathic Pain Market