
 Opioid-Induced Respiratory Depression Market | 2026-2036
Opioid-Induced Respiratory Depression Market Size, Share, and Industry Trends Forecast 2026-2036
Opioid-Induced Respiratory Depression Market Analytics
Anesthesiologist staffing shortages across perioperative units is collapsing the margin for manual respiratory surveillance, forcing health systems toward automated capnography and pulse oximetry platforms. Medtronic plc leverages its distributed critical care monitoring infrastructure to sustain installed-base loyalty in surgical suites. Masimo Corporation differentiates through signal-processing algorithms that reduce false alarms in high-noise clinical environments. Nihon Kohden Corporation anchors its position in Asian hospital networks with localized regulatory certifications and regional service density.
Opioid-induced respiratory depression denotes the pathological suppression of ventilatory drive triggered by mu-opioid receptor agonism in the brainstem respiratory centers, clinically manifesting as reduced respiratory rate, diminished tidal volume, and elevated end-tidal carbon dioxide exceeding 50 mmHg. The condition demands continuous multi-parameter monitoring because arterial oxygen desaturation often lags behind ventilatory compromise by several minutes. Postoperative care applications dominate therapy area demand as enhanced recovery after surgery protocols mandate stricter respiratory surveillance during opioid analgesia. Intravenous delivery mode segments carry elevated monitoring intensity requirements due to rapid plasma concentration changes with bolus dosing. Home healthcare represents the fastest-growing end user category as ambulatory surgical discharge timelines compress and remote patient monitoring reimbursement stabilizes.
FDA premarket notification requirements for capnography monitors under 21 CFR 870.2300 shape hardware design standards and clinical validation burdens for device manufacturers entering the US market. The Drug Enforcement Administration's production quota system for Schedule II opioids indirectly constrains prescribing volumes that drive downstream monitoring device demand. Stakeholders must weigh the capital allocation trade-off between disposable sensor recurring revenue and integrated platform subscription models as purchasing authority shifts from biomedical engineering to health system value-analysis committees.
Market Dynamics
Anesthesiologist staffing shortages across perioperative units are collapsing the margin for manual respiratory surveillance, forcing health systems toward automated capnography and pulse oximetry platforms. This structural pressure accelerates capital deployment into continuous multi-parameter monitoring infrastructure.
Growth Catalysts
- FDA capnography guidance:The agency's monitoring recommendations for procedural sedation under 21 CFR 870.2300 mandate respiratory surveillance upgrades across US ambulatory surgical centers.
- Enhanced Recovery After Surgery protocols:Postoperative care standards in tertiary hospitals now require continuous ventilatory monitoring during opioid analgesia administration.
- Remote patient monitoring reimbursement:CMS payment stability for home-based respiratory surveillance accelerates device deployment outside traditional facility settings.
Market Restraints
- Disposable sensor cost structure:Recurring consumable expenses for single-use etCO2 nasal cannulas strain capital-constrained community hospital budgets.
- Signal-processing technical limitations:Motion artifact and ambient noise interference in high-acuity environments generate false alarm fatigue among nursing staff.
- DEA opioid quota constraints:The Drug Enforcement Administration's Schedule II production limits indirectly suppress downstream monitoring device demand volumes.
Strategic Opportunities
- Home healthcare channel expansion:Compressed ambulatory surgical discharge timelines create white space for portable capnography devices in post-acute settings.
- Electronic medical record integration:Automated early-warning platforms that stream respiratory data directly into Epic and Cerner systems capture health system purchasing authority.
- Artificial intelligence convergence:Machine learning algorithms layered atop pulse oximetry waveforms enable predictive respiratory depression alerts before clinical decompensation.
Industry Challenges
- Biomedical engineering talent scarcity:Health systems lack specialized personnel to maintain and calibrate multi-parameter monitoring fleets across distributed surgical suites.
- Legacy device interoperability:Proprietary communication protocols between incumbent monitoring platforms and new cloud-based analytics layers create integration friction.
- 510(k) certification timelines:FDA premarket notification requirements for algorithm-augmented capnography monitors extend product launch schedules by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Opioid-Induced Respiratory Depression Market |
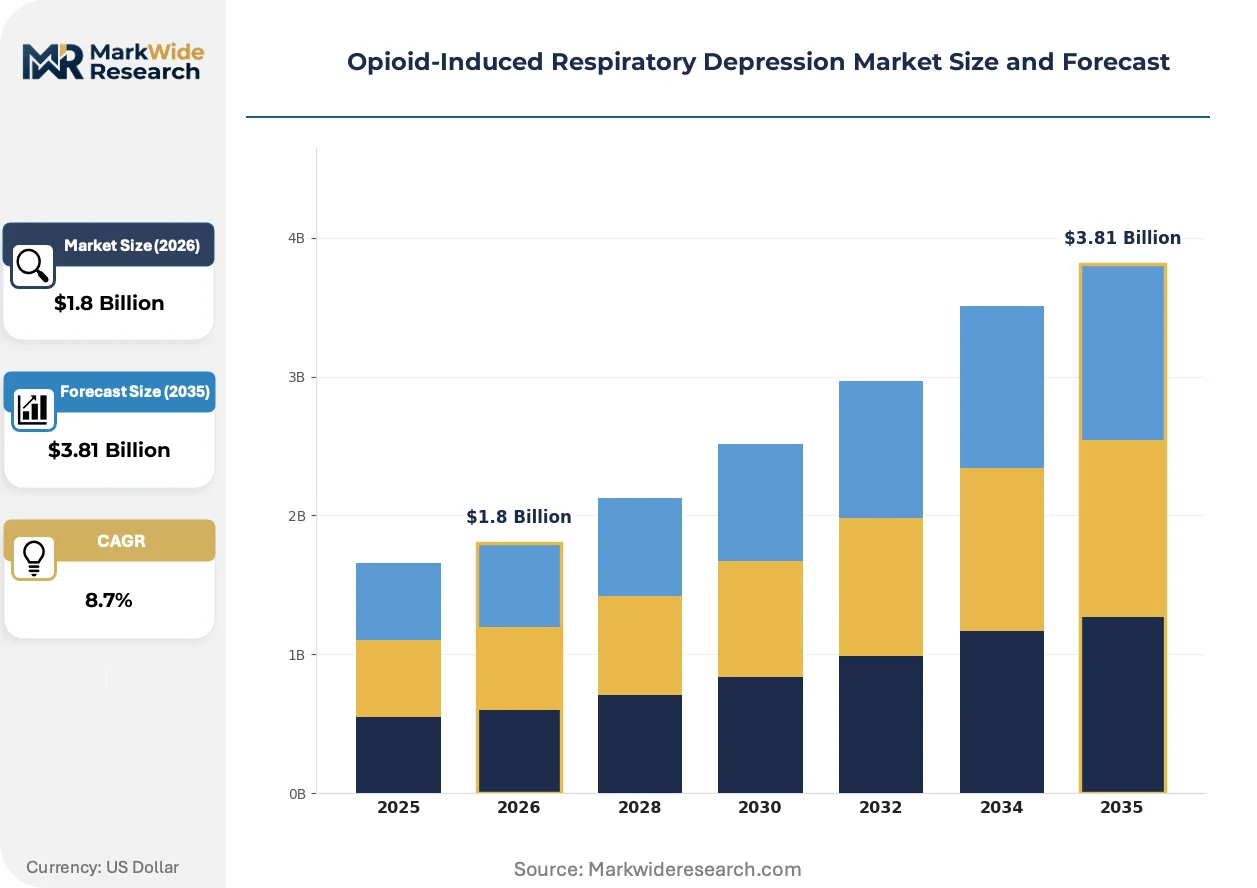
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxycodone, Hydromorphone, Fentanyl, Morphine Therapy Area: Chronic Pain, Postoperative Care, Cancer Pain Management, Palliative Care Delivery Mode: Intravenous, Oral, Transdermal, Inhalation End User: Hospitals, Clinics, Home Healthcare, Rehabilitation Centers |
| Companies Covered | Medtronic plc, Masimo Corporation, Nihon Kohden Corporation, Smiths Group, GE Healthcare, Covidien, Pfizer Inc., Teva Pharmaceutical Industries Ltd., Atelerix Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Opioid-Induced Respiratory Depression Market Evolving Landscape
Signal-processing algorithms and disposable sensor miniaturization are compressing the form factor and cost structure of respiratory monitoring, enabling deployment beyond traditional critical care boundaries.
Microstream capnography technology using low-flow sidestream sampling is supplanting mainstream infrared benchtop systems in procedural sedation applications. Ambulatory surgical centers in the United States adopt these compact units at accelerating pace to comply with tightened monitoring mandates. The structural consequence is a compression in capital equipment footprints and a shift toward disposable-heavy revenue models that favor high-volume sensor manufacturers.
The FDA's evolving guidance on physiological monitoring alarm systems under 21 CFR 870.2300 is tightening clinical validation requirements for capnography devices entering the US market. Manufacturers must demonstrate reduced false-positive rates in motion-rich environments to secure premarket clearance. High-acuity surgical segments respond by demanding integrated platforms that combine etCO2, SpO2, and respiratory rate into unified alarm management architectures.
Health system value-analysis committees have displaced biomedical engineering departments as primary purchasing authorities for respiratory monitoring infrastructure. This shift compels vendors to construct total-cost-of-ownership arguments spanning capital, consumables, and integration services. The phenomenon is most visible in United States integrated delivery networks consolidating procurement across previously autonomous facility footprints.
Opioid-Induced Respiratory Depression Market Segmentation
Respiratory monitoring requirements diverge sharply across opioid formulations and care settings. FDA 21 CFR 870.2300 mandates capnography integration for specific delivery modes, creating tiered compliance burdens that reshape procurement patterns.
Product Type:
FDA scheduling tiers under the Controlled Substances Act differentiate monitoring intensity by abuse potential and pharmacokinetic profile.
- Fentanyl:Synthetic mu-agonist with rapid onset and narrow therapeutic index demands continuous capnography in procedural sedation. Hospital surgical suites in the United States deploy multi-parameter platforms for patient-controlled analgesia pumps dispensing this agent.
- Morphine:Natural opiate alkaloid with active metabolite accumulation in renal impairment requires extended respiratory surveillance in palliative settings. Tertiary care institutions integrate automated early-warning systems for prolonged infusions.
- Oxycodone:Semisynthetic oral formulation dominates ambulatory prescribing volumes with moderate monitoring requirements.
- Hydromorphone:High-potency semisynthetic agent triggers targeted surveillance protocols in acute pain services.
Established volume favors morphine; emerging adoption favors fentanyl.
Therapy Area:
Clinical setting determines surveillance technology selection and staffing ratios for respiratory monitoring deployment.
- Postoperative Care:Enhanced Recovery After Surgery protocols mandate continuous ventilatory monitoring during opioid analgesia in tertiary hospitals. CMS reimbursement stability for post-acute surveillance accelerates platform deployment across United States integrated delivery networks.
- Cancer Pain Management:Chronic opioid exposure with escalating tolerance thresholds requires sophisticated titration monitoring in oncology units. Academic medical centers deploy algorithm-augmented pulse oximetry for early respiratory depression detection.
- Chronic Pain:Long-term outpatient prescribing generates demand for portable home monitoring devices with cloud connectivity.
- Palliative Care:Comfort-focused settings balance surveillance intensity against quality-of-life considerations in hospice facilities.
Postoperative applications command capital allocation priority; home-based cancer pain management climbs fastest.
Delivery Mode:
Plasma concentration kinetics dictate monitoring frequency and sensor configuration for respiratory surveillance systems.
- Intravenous:Bolus dosing with rapid peak concentrations necessitates real-time capnography in perioperative units. United States ambulatory surgical centers upgrade to microstream technology to comply with tightened procedural sedation mandates.
- Transdermal:Sustained-release patches with delayed peak and prolonged half-life require extended monitoring in skilled nursing facilities. Delayed respiratory depression risk 12-24 hours post-application drives overnight surveillance protocols.
- Oral:Variable gastrointestinal absorption creates unpredictable pharmacokinetics in general medical wards.
- Inhalation:Rapid pulmonary uptake demands immediate-response monitoring in emergency departments.
Intravenous delivery anchors installed base value; transdermal applications expand sensor recurring revenue fastest.
End User:
Purchasing authority and reimbursement pathways fragment procurement behavior across facility types and care continuums.
- Home Healthcare:Compressed ambulatory surgical discharge timelines create demand for portable capnography devices with remote monitoring capabilities. CMS payment stability for post-acute respiratory surveillance accelerates deployment outside traditional facility boundaries.
- Hospitals:Value-analysis committees consolidate capital procurement across multi-facility systems, favoring integrated platform subscriptions over discrete device purchases. Epic and Cerner EMR integration determines vendor selection in United States health systems.
- Clinics:Lower-acuity settings prioritize cost-minimized pulse oximetry for oral opioid prescribing.
- Rehabilitation Centers:Subacute recovery facilities balance surveillance needs against limited biomedical engineering staffing.
Hospitals retain capital concentration; home healthcare gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health systems deploy capnography at substantially higher intensity than counterparts elsewhere, driven by FDA-mandated procedural sedation surveillance and CMS reimbursement for remote patient monitoring. European markets emphasize portable pulse oximetry for ambulatory pain management. Asian hospital networks prioritize cost-optimized multi-parameter platforms.
United States
Ambulatory surgical centers upgrade to microstream capnography systems under tightened 21 CFR 870.2300 mandates for procedural sedation. The Drug Enforcement Administration's Schedule II production quotas indirectly constrain prescribing volumes that drive downstream monitoring demand. Greater Boston's academic medical cluster deploys algorithm-augmented early-warning platforms integrated with Epic electronic medical records.
Germany
Tertiary hospitals integrate continuous respiratory surveillance into Enhanced Recovery After Surgery protocols for postoperative opioid analgesia. The European Medical Device Regulation (MDR) imposes stricter clinical validation requirements on capnography manufacturers seeking CE marking. Baden-Württemberg's medical technology corridor concentrates pulse oximetry sensor fabrication for distribution across European Union member states.
Japan
Oncology units in academic medical centers deploy sophisticated titration monitoring for cancer pain management with escalating opioid tolerance thresholds. The Pharmaceuticals and Medical Devices Agency (PMDA) reviews premarket submissions for multi-parameter monitoring platforms under accelerated assessment pathways. The Kansai region's Osaka-Kobe medical device cluster specializes in miniaturized disposable sensors for high-noise clinical environments.
China
Provincial hospital networks expand capnography deployment in perioperative units amid anesthesiologist staffing shortages across surgical suites. The National Medical Products Administration (NMPA) aligns technical review standards with international norms under 2021 medical device regulation reforms. The Yangtze River Delta's Shanghai-Suzhou corridor hosts domestic manufacturers developing localized respiratory monitoring platforms for tier-one hospital procurement.
India
Private hospital chains in metropolitan centers adopt automated early-warning systems as postoperative opioid protocols tighten in tertiary care institutions. The Central Drugs Standard Control Organization (CDSCO) regulates capnography devices under Medical Device Rules 2017 with risk-based classification. Maharashtra's Mumbai-Pune pharmaceutical corridor attracts contract manufacturing for disposable etCO2 nasal cannulas serving South Asian markets.
Opioid-Induced Respiratory Depression Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper stratum controlling platform-level respiratory monitoring infrastructure and the lower tier competing on discrete sensor innovation and regional service density. The upper tier commands health system value-analysis committees through total-cost-of-ownership arguments spanning capital equipment, consumables, and electronic medical record integration. Three archetypes populate this structure: diversified critical care conglomerates with distributed monitoring fleets; signal-processing specialists with algorithmic differentiation; and regional champions with localized regulatory certifications and dense service networks. Competitive dynamics center on strategic partnerships for artificial intelligence convergence and backward integration into disposable sensor manufacturing to capture recurring revenue streams.
Within the diversified critical care tier, Medtronic plc and GE Healthcare occupy positions anchored by installed-base loyalty across perioperative units and intensive care infrastructure. Masimo Corporation exemplifies the signal-processing specialist archetype, with algorithmic approaches to false-alarm reduction in motion-rich clinical environments. Nihon Kohden Corporation represents the regional champion model, leveraging density in Asian hospital networks against global competitors.
| Leading Market Players |
|---|
| Medtronic plc |
| Masimo Corporation |
| Nihon Kohden Corporation |
| Smiths Group |
| GE Healthcare |
| Covidien |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Atelerix Life Sciences |
| Others |
Value Network & Pricing Analysis
Scale economies in microstream capnography sensor fabrication concentrate manufacturing capacity among three dominant suppliers, compressing unit economics for disposable etCO2 nasal cannulas while elevating price floors for integrated monitoring platforms. This concentration rewards high-volume producers with FDA 510(k) clearance under 21 CFR 870.2300 and penalizes regional challengers lacking automated cleanroom assembly lines.
Pricing Analysis
Long-term offtake agreements between integrated delivery networks and platform vendors dominate hospital procurement, with subscription models bundling capital equipment, disposable sensors, and EMR integration services displacing per-unit transactional purchasing. Price differentiation rests on FDA clearance tier and algorithmic sophistication, with motion-artifact-resistant systems commanding premium positioning against basic pulse oximetry. Cost compression in the standard-equipment tier intensifies as value-analysis committees consolidate purchasing across multi-facility systems. Community hospitals exhibit acute price sensitivity, while academic medical centers prioritize integration depth over unit cost.
Supply Chain Analysis
Inventory buffers for single-use etCO2 sensors stretch to 90-120 days given sterilization validation requirements and just-in-time delivery constraints to ambulatory surgical centers. Manufacturing concentrates in the United States, Ireland, and Japan, with specialized optical components sourced from German precision optics suppliers and medical-grade polymers drawn from South Korean petrochemical producers. Single-source vulnerability in infrared detector chips creates exposure to semiconductor foundry allocation decisions. Distribution runs through group purchasing organizations and direct health system contracts, bypassing traditional medical device distributors for high-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating in United States integrated delivery networks as value-analysis committees disperse procurement authority across previously autonomous surgical suites, fragmenting vendor access and intensifying price negotiation leverage.
For Market Incumbents: Fortify installed-base loyalty through backward integration into disposable sensor manufacturing, capturing recurring revenue streams that offset capital equipment margin compression. Deepen Epic and Cerner EMR integration to raise switching costs for hospital customers evaluating platform migrations. Defend against algorithm specialists by accelerating FDA submissions for AI-augmented respiratory depression prediction. For New Entrants and Emerging Players: Anchor in the home healthcare channel where reimbursement stability under CMS remote patient monitoring codes creates white space for portable capnography devices outside incumbent hospital footprints. Target ambulatory surgical centers with microstream technology offerings that comply with tightened procedural sedation mandates without requiring full platform replacement. Pursue partnership-based go-to-market models with established GPOs to bypass direct health system sales force requirements. For Investors and Strategic Acquirers: Signal-processing specialists with proprietary motion-artifact reduction algorithms represent the most attractive acquisition archetype, offering differentiation that incumbent platform vendors cannot replicate through internal development. Monitor FDA 510(k) clearance timelines for algorithm-augmented devices as an inflection indicator for competitive positioning shifts. Long-term viability favors vendors with dual revenue streams spanning capital platforms and high-margin disposable consumables.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for AI-Augmented Monitoring | Algorithmic respiratory depression prediction secures premium reimbursement tier under evolving CMS guidance. |
| EMR Integration Partnership | Direct Epic and Cerner data streaming captures value-analysis committee purchasing authority in IDNs. |
| Disposable Sensor Manufacturing Scale-Up | Captive etCO2 nasal cannula production locks in recurring revenue margins against commoditization pressure. |
| Home Healthcare Channel Expansion | Portable capnography deployment outside hospital walls accesses CMS remote monitoring reimbursement stability. |
| Group Purchasing Organization Contract | Consolidated procurement access across multi-facility systems reduces customer acquisition cost per bed. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) premarket notification databases, CMS Medicare reimbursement schedules, and hospital procurement contract disclosures. Interviews with biomedical engineering directors, anesthesia department chiefs, GPO contracts managers, and value-analysis committee members informed demand-side dynamics. Secondary validation drew from SEC 10-K filings of listed device manufacturers, patent assignment records for signal-processing algorithms, and trade data for medical sensor components. Bottom-up unit demand estimates triangulated against top-down health system capital expenditure surveys.
Segmentation dimensions modeled span product type, therapy area, delivery mode, and end user, with geographic regulatory clusters capturing FDA, CE marking, and PMDA pathway differences. CAGRs derive from installed base expansion rates, replacement cycles for monitoring platforms, and disposable sensor consumption per patient bed day. Forecast inputs incorporate anesthesiologist staffing shortage projections, ambulatory surgical center construction permits, and CMS reimbursement rulemaking timelines across the analysis window.
Material uncertainties — DEA opioid quota revisions, FDA alarm system guidance updates, and semiconductor supply allocation shocks — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and reimbursement continuity without guaranteeing specific outcomes. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Respiratory Trainer Market
Respiratory Therapy
Alpha-1 Antitrypsin Deficiency (AATD) Augmentation Therapy Market
Respiratory Therapy
Pediatric Respiratory Syncytial Virus Infection Market
Respiratory Therapy
Lung (Pulmonary) Airway Disease Treatment Market
Respiratory Therapy
Oscillating Positive Expiratory Pressure (OPEP) Devices Market
Respiratory Therapy
Pediatric Respiratory Disease Therapeutics Market
Respiratory Therapy
Breathing Disorders Treatment Market
Respiratory Therapy
Global Dyspnea Treatment Market
Respiratory Therapy
Pediatric Respiratory Disease Treatment Market
Respiratory Therapy
Diaphragm Pacing Therapy System Market
Respiratory Therapy
Global Pneumonia Therapeutics Market
Respiratory Therapy
Endobronchial Valve Market
Respiratory Therapy
Severe Acute Respiratory Syndrome Treatment Market
Respiratory Therapy
US Respiratory Assist Devices EUA Market
Respiratory Therapy
Interventional Pulmonology Market
Respiratory Therapy
Global Oxygen Therapy Market