
 Toxic Epidermal Neurolysis Market | 2026-2036
Toxic Epidermal Neurolysis Market Size, Share, and Industry Trends Forecast 2026-2036
Toxic Epidermal Neurolysis Market Analytics
Hospital procurement channels for severe dermatological emergencies is tilting toward consolidated purchasing agreements with integrated health networks. Pfizer leverages its established hospital formulary relationships to sustain access for critical care pharmaceuticals. Novartis anchors its position through specialized distribution to burn centers and intensive care units. Johnson & Johnson competes across wound care adjacencies with bundled product offerings for TEN supportive management.
Toxic epidermal neurolysis constitutes a rare, life-threatening mucocutaneous reaction characterized by full-thickness epidermal necrosis exceeding 30% body surface area, requiring immediate intervention with intravenous immunoglobulin, cyclosporine, or etanercept to halt keratinocyte apoptosis. Biologics command premium positioning within the product type landscape as targeted cytokine inhibition demonstrates superior outcomes in controlled protocols. Injectable solutions lead formulation demand due to the imperative for rapid systemic bioavailability in acute presentation, while specialty hospitals capture concentrated margin pools through bundled critical care reimbursement structures.
The FDA Orphan Drug program and EMA's rare disease designation framework accelerate clinical trial incentives and extended exclusivity for TEN therapeutics, directly shaping developer pipelines and market access timelines. ISO 14155 clinical investigation standards and ICH-GCP guidelines govern trial integrity across jurisdictions, elevating compliance costs for entrants. Stakeholders must monitor evolving health technology assessment methodologies for rare disease interventions as payors recalibrate value frameworks for ultra-orphan indications.
Market Dynamics
The Toxic Epidermal Neurolysis market pivots on the tension between orphan drug incentives and the extreme cost concentration of biologic manufacturing. FDA's Orphan Drug Designation compresses clinical timelines while simultaneously locking in premium pricing structures that strain hospital pharmacy budgets across tertiary care networks.
Growth Catalysts
- Orphan Drug Exclusivity:The FDA's seven-year market exclusivity provision for TEN therapeutics accelerates venture capital deployment into rare disease pipelines. Developers recoup R&D investments through protected pricing corridors.
- Burn Center Infrastructure:Specialized intensive care units in the United States deploy standardized TEN protocols that institutionalize biologic procurement. Hospital formulary committees increasingly mandate evidence-based cytokine inhibition as first-line intervention.
- Plasma Fractionation Advances:Recombinant protein engineering is reducing immunoglobulin production costs. Contract manufacturers in Germany and Switzerland are expanding viral inactivation capacity to meet intravenous immunoglobulin demand.
Market Restraints
- Plasma Supply Concentration:Source plasma collection concentrates in the United States and Germany, exposing immunoglobulin manufacturers to geopolitical disruption and donor pool volatility.
- EMA Regulatory Friction:The European Medicines Agency's divergent rare disease assessment criteria create parallel approval pathways that delay market access for TEN therapeutics by 18-24 months versus FDA clearance.
- Technical Limitation:Current cytokine inhibitors demonstrate incomplete epidermal stabilization in patients with body surface area involvement exceeding 50%, creating residual mortality risk that limits payer willingness to expand coverage.
Strategic Opportunities
- Japan's Rare Disease Framework:The Pharmaceuticals and Medical Devices Agency's Sakigake designation offers priority review and extended reimbursement pricing for TEN therapeutics entering the Japanese market.
- Subcutaneous Formulation Innovation:Biosimilar developers are engineering depot-injection alternatives to intravenous delivery. This convergence of formulation science and patient mobility requirements opens outpatient administration models.
- Health Canada Accelerated Pathway:The Priority Review program for drugs treating serious conditions with unmet medical needs compresses regulatory timelines for TEN candidates targeting the Canadian hospital sector.
Industry Challenges
- Specialized Immunology Talent Scarcity:Clinical investigators with TEN trial experience concentrate at fewer than 40 academic medical centers globally, creating site activation bottlenecks that extend enrollment timelines.
- ISO 14155 Compliance Burden:Burn center trials require adaptive protocol designs that conflict with traditional GCP documentation standards, forcing sponsors to deploy redundant monitoring infrastructure.
- Legacy EHR Integration:Hospital systems running decade-old Epic or Cerner installations lack structured fields for mucocutaneous adverse event tracking, complicating real-world evidence generation for post-market studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toxic Epidermal Neurolysis Market |
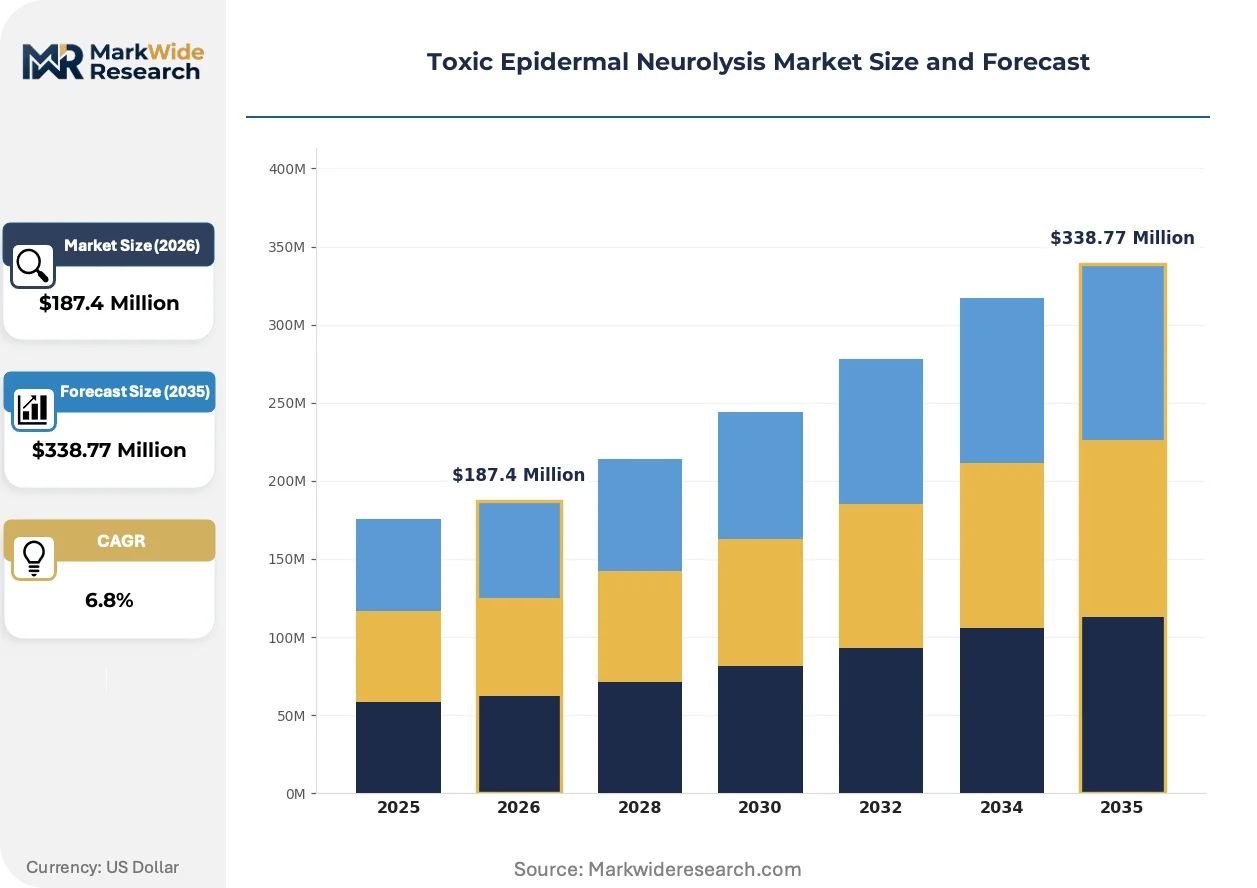
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Agents, Systemic Medications, Immunosuppressants, Biologics Treatment Setting: Inpatient Care, Outpatient Clinics, Home Care, Specialty Hospitals Formulation: Liquid Formulations, Injectable Solutions, Tablets, Creams End User: Dermatology Clinics, Hospitals, Research Institutions, Pharmacies |
| Companies Covered | Pfizer, Novartis, Sanofi, Merck & Co., Johnson & Johnson, Abbott Laboratories, Amgen, 3M, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toxic Epidermal Neurolysis Market Evolving Landscape
Digital biomarker platforms are compressing the diagnostic window between drug exposure and epidermal detachment onset. These technologies promise to shift intervention timing from reactive crisis management toward predictive stratification of high-risk patients.
Machine learning algorithms trained on dermatological imaging datasets are virtualizing the initial assessment of body surface area involvement. Burn center triage nurses at tertiary hospitals in the United States and Germany are deploying tablet-based applications that reduce inter-rater variability in epidermal necrosis measurement. This virtualization of clinical assessment is compressing the time-to-treatment interval and reducing unnecessary ICU admissions for Stevens-Johnson syndrome misclassified as TEN.
The European Medicines Agency's 2023 revision to orphan drug maintenance criteria now requires post-authorization efficacy studies for TEN indications granted conditional approval. Manufacturers must demonstrate sustained mortality benefit against historical controls rather than placebo. Biologic sponsors with EU market authorization are responding by embedding registry-based outcome tracking into hospital contracting structures, particularly in France and Italy where national rare disease networks facilitate longitudinal follow-up.
Consolidated purchasing agreements between integrated delivery networks and specialty distributors are displacing traditional wholesaler relationships in the United States. Hospital systems managing multiple burn centers are negotiating multi-year immunoglobulin supply contracts that bundle inventory management with clinical pharmacist consultation services. This channel concentration is most visible in Texas and California, where state-level Medicaid reimbursement reforms have incentivized vertical integration between acute care hospitals and outpatient wound care facilities.
Toxic Epidermal Neurolysis Market Segmentation
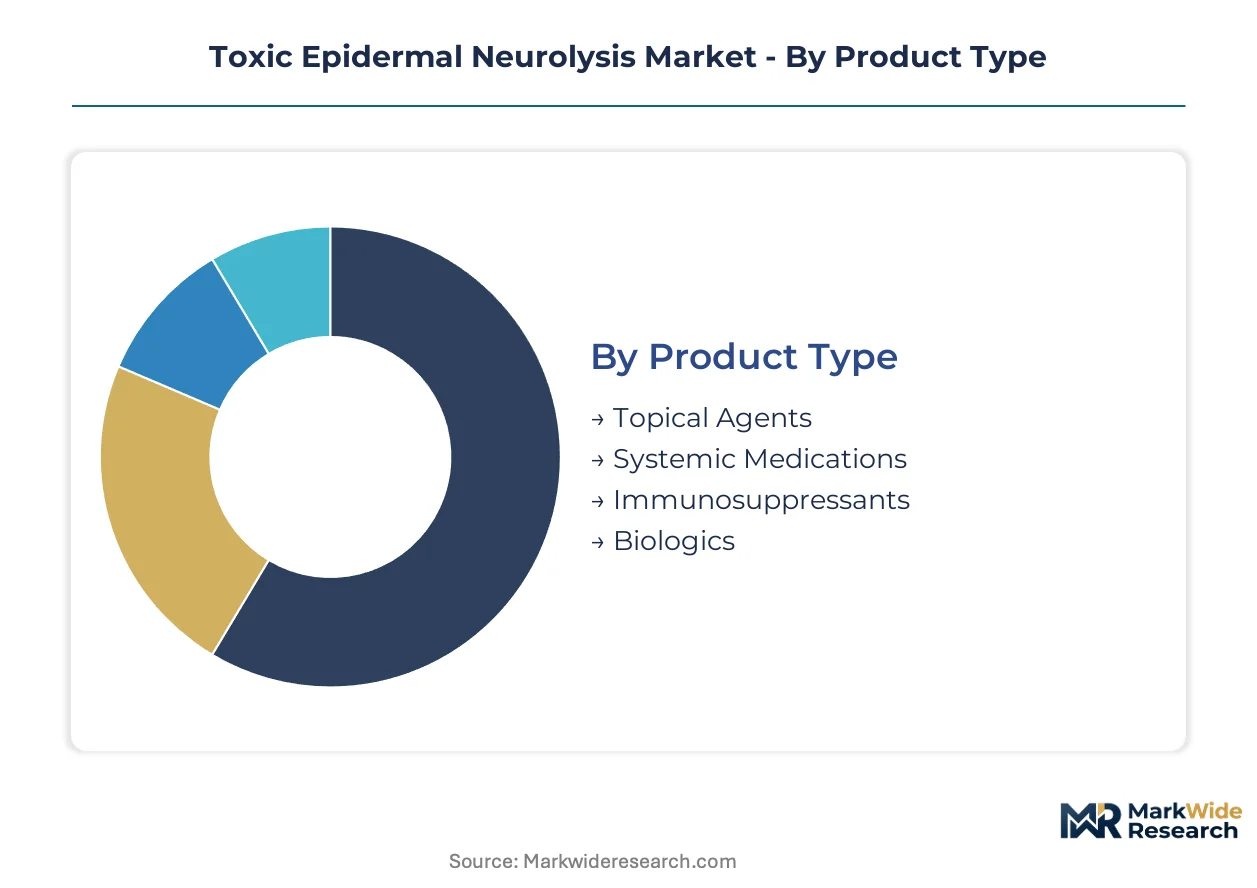
TEN therapeutics fragment across acute intervention modalities and chronic management pathways. Product positioning hinges on severity stratification, with biologics commanding ICU formulary placement while supportive agents sustain outpatient recovery protocols.
Product Type:
The use-case spectrum spans immediate epidermal stabilization to long-term immune modulation, with severity of body surface area involvement dictating therapeutic escalation.
- Biologics:Engineered cytokine inhibitors such as etanercept and infliximab demonstrate targeted interruption of keratinocyte apoptosis cascades. Hospital burn centers in the United States and Germany institutionalize these agents as first-line intervention for body surface area involvement exceeding 30%, though manufacturing complexity sustains premium procurement costs.
- Systemic Medications:Cyclosporine and corticosteroid protocols remain foundational for moderate presentations without extensive epidermal detachment. Demand concentrates in tertiary care networks where formulary committees balance mortality outcomes against immunosuppression risks in sepsis-prone patients.
- Immunosuppressants:Azathioprine and mycophenolate mofetil bridge acute-to-chronic transition phases.
- Topical Agents:Silicone-based dressings and antimicrobial preparations manage wound bed preparation in supportive care settings.
Established volume favors systemic medications; emerging adoption favors biologics.
Treatment Setting:
Cost tier stratification separates intensive resource deployment from ambulatory recovery management, with reimbursement structures reinforcing site-of-care boundaries.
- Inpatient Care:ICU admission mandates continuous hemodynamic monitoring, fluid resuscitation, and infection surveillance for patients with epidermal necrosis exceeding 30% body surface area. United States burn centers capture concentrated margin pools through bundled critical care reimbursement codes that incorporate biologic procurement.
- Specialty Hospitals:Dedicated dermatology and burn units in France and Italy leverage national rare disease networks for longitudinal outcome tracking. These facilities command premium episode-based payments through demonstrated mortality reduction against historical benchmarks.
- Outpatient Clinics:Post-discharge wound management and immunosuppression tapering occur in dermatology-focused ambulatory settings.
- Home Care:Subcutaneous formulation advances enable selected patients to complete recovery protocols outside institutional settings.
Revenue concentration favors inpatient care; patient mobility requirements favor home care expansion.
Formulation:
Application urgency dictates bioavailability requirements, with parenteral routes dominating acute presentation and oral forms sustaining maintenance phases.
- Injectable Solutions:Intravenous immunoglobulin and biologic infusions achieve rapid systemic exposure necessary for apoptosis interruption. Plasma fractionation capacity in Germany and Switzerland constrains global supply availability for this critical formulation category.
- Liquid Formulations:Oral suspensions facilitate precise dose titration in patients with compromised gastrointestinal absorption.
- Tablets:Solid oral dosage forms support outpatient immunosuppression maintenance and corticosteroid tapering protocols.
- Creams:Topical corticosteroid and antimicrobial preparations address localized mucosal involvement and wound bed management.
Clinical imperative favors injectable solutions; patient convenience favors tablet migration in maintenance phases.
End User:
Customer type determines procurement sophistication, with institutional purchasers deploying evidence-based protocols and retail channels managing supportive care continuity.
- Hospitals:Integrated delivery networks negotiate multi-year supply agreements that bundle biologic inventory with clinical pharmacist consultation. Texas and California health systems demonstrate the most advanced formulary standardization for TEN protocols.
- Dermatology Clinics:Academic medical centers concentrate clinical trial enrollment and specialist referral networks for complex case management.
- Research Institutions:Fewer than 40 global sites possess investigator expertise for TEN protocol activation.
- Pharmacies:Specialty distributors manage post-acute medication access and patient education for outpatient recovery.
Therapeutic decision-making favors hospitals; longitudinal data generation favors research institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's Orphan Drug Designation anchors the United States as the dominant geography for TEN therapeutic development, with specialized burn center infrastructure and premium reimbursement structures driving adoption velocity across tertiary care networks.
United States
Hospital formulary committees at integrated delivery networks in Texas and California institutionalize biologic procurement through bundled critical care reimbursement codes. The FDA's seven-year market exclusivity provision accelerates venture capital deployment into rare disease pipelines. Academic medical centers in Boston and Houston concentrate clinical trial enrollment for TEN protocols.
Germany
Plasma fractionation capacity in Germany constrains global intravenous immunoglobulin supply availability for acute TEN intervention. The national pharmaceutical regulator enforces ISO 14155 clinical investigation standards that elevate compliance costs for trial sponsors. Burn centers in Munich and Berlin leverage national rare disease networks for longitudinal outcome tracking.
Switzerland
Contract manufacturers in Basel and Zurich are expanding viral inactivation capacity to meet immunoglobulin demand for European hospital networks. Swissmedic maintains alignment with EMA orphan drug maintenance criteria requiring post-authorization efficacy studies. The country's specialized hospital procurement channels favor consolidated purchasing agreements with integrated health networks.
Japan
The Pharmaceuticals and Medical Devices Agency's Sakigake designation offers priority review and extended reimbursement pricing for TEN therapeutics entering Japanese markets. Burn center infrastructure in Tokyo and Osaka deploys standardized protocols that institutionalize cytokine inhibition as first-line intervention. METI coordinates rare disease framework implementation across prefectural health systems.
Canada
Health Canada's Priority Review program for drugs treating serious conditions with unmet medical needs compresses regulatory timelines for TEN candidates. Hospital systems in Ontario and British Columbia manage multi-year immunoglobulin supply contracts that bundle inventory management with clinical pharmacist consultation. Provincial reimbursement reforms incentivize vertical integration between acute care hospitals and outpatient wound care facilities.
Toxic Epidermal Neurolysis Market Competitive Landscape
Multinational pharmaceutical conglomerates and specialized biologic manufacturers split the market across acute intervention and supportive care domains. The vendor base concentrates around established hospital formulary relationships and plasma fractionation capabilities. Two archetypes dominate: integrated healthcare conglomerates with wound care adjacencies, and pure-play biologic developers with orphan drug portfolios. Competitive moves center on strategic partnerships with burn center networks and geographic expansion through regulatory pathway optimization.
Within the integrated healthcare tier, Pfizer and Johnson & Johnson occupy positions anchored by established hospital procurement channels and bundled product offerings for TEN supportive management. Novartis exemplifies the specialized biologic archetype through distribution relationships with burn centers and intensive care units. These three entities represent the concentration of commercial infrastructure capable of serving ultra-orphan indication requirements.
| Leading Market Players |
|---|
| Pfizer |
| Novartis |
| Sanofi |
| Merck & Co. |
| Johnson & Johnson |
| Abbott Laboratories |
| Amgen |
| 3M |
| Cardinal Health |
| Others |
Value Network & Pricing Analysis
Plasma supply concentration in the United States and Germany determines both the premium spread for intravenous immunoglobulin and the geographic shape of TEN therapeutic distribution. Single-source dependency on North American and Central European plasma collection networks creates pricing tier compression when donor pool volatility disrupts fractionation capacity.
Pricing Analysis
Configured-to-order pricing for patient-specific immunoglobulin dosing commands substantial premiums over standard hospital formulary contracts. Three-tier pricing structure across premium biologic cytokine inhibitors, standard intravenous immunoglobulin, and economy corticosteroid protocols reflects mortality outcome differentiation and manufacturing complexity. Cost compression in the immunoglobulin tier is intensifying because recombinant protein engineering advances are reducing plasma dependency. Academic medical centers demonstrate lowest price sensitivity due to bundled critical care reimbursement, while community hospitals face tightening pharmacy budgets.
Supply Chain Analysis
Contract manufacturing concentration at Basel and Zurich facilities controls viral inactivation capacity for European immunoglobulin demand. Plasma fractionation draws from United States and German source collection networks, with recombinant protein production resting on Swiss and German biologics infrastructure. Single-source vulnerability concentrates in plasma-derived inputs, exposing manufacturers to geopolitical disruption. Distribution runs through specialty distributors serving integrated delivery networks, displacing traditional wholesaler relationships in Texas and California health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
TEN therapeutics are recovering from cyclical plasma supply constraints as recombinant engineering expands manufacturing alternatives. Orphan drug exclusivity renewals and burn center infrastructure investments sustain the upward trajectory.
For Market Incumbents: Build regulatory exclusivity moats through FDA Orphan Drug Designation maintenance and EMA post-authorization efficacy study commitments. Defend against biosimilar entrants by securing multi-year immunoglobulin supply contracts with integrated delivery networks. Invest in subcutaneous formulation R&D to capture outpatient administration migration. For New Entrants and Emerging Players: Pursue Japan's Sakigake designation pathway and Health Canada Priority Review to compress regulatory timelines versus EMA parallel approval delays. Target Canadian hospital systems in Ontario and British Columbia where provincial reimbursement reforms incentivize vertical consolidation. Deploy clinical pharmacist consultation bundling as the primary go-to-market mechanism. For Investors and Strategic Acquirers: The market sits at a capacity-expansion phase that favors plasma fractionation specialists with recombinant diversification. Long-term viability hinges on manufacturing technology transitions reducing donor pool dependency. Acquisition targets should demonstrate viral inactivation capabilities and established burn center distribution relationships. Monitor plasma collection volume reports from the United States and Germany as the inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA Orphan Drug Designation compresses clinical timelines and locks premium pricing corridors. |
| Manufacturing Scale-Up | Recombinant protein engineering at Swiss facilities reduces plasma dependency and expands supply security. |
| Hospital System Partnership | Multi-year immunoglobulin contracts with Texas and California IDNs bundle inventory with clinical consultation. |
| Formulation Innovation | Subcutaneous depot-injection development enables outpatient administration and patient mobility. |
| Geographic Expansion | Sakigake designation entry into Japanese burn centers captures priority review and extended reimbursement. |
Research Methodology
A standing panel of burn center directors, hospital formulary committee chairs, plasma fractionation executives, and regulatory affairs specialists provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from FDA Orphan Drug Designation filings, EMA submission databases, ClinicalTrials.gov protocols, and hospital procurement records. Bottom-up demand modeling across treatment settings and top-down supply capacity assessments were triangulated for convergence.
Scenario bracketing anchored the analytical framework across base, optimistic, and conservative plasma supply assumptions throughout the forecast period. Segmentation dimensions modeled include product type, treatment setting, formulation route, and regional regulatory cluster. CAGRs were derived from weighted average growth across these segments, with inputs from burn center admission trends and biologic procurement velocity at tertiary care networks.
Sensitivities concentrate around plasma collection disruption, regulatory timeline divergence between FDA and EMA, and cytokine inhibitor efficacy thresholds in high body surface area involvement cases. Forecasts reflect documented assumptions regarding recombinant protein adoption curves and orphan drug exclusivity maintenance criteria. Quarterly review of plasma fractionation capacity utilization and burn center protocol standardization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Immunoglobulin (Igg) Replacement Therapy Market
Specialty Medicine
Peptide-Based Metabolic Disorders Therapeutics Market
Specialty Medicine
Gingivostomatitis Market
Specialty Medicine
Global Gastrointestinal Stromal Tumors Market
Specialty Medicine
Dry Eye Disease Market
Specialty Medicine
Gouty Arthritis Market
Specialty Medicine
Acute Hepatic Porphyria (APH) Market
Specialty Medicine
Fascioliasis Treatment Market
Specialty Medicine
Narcolepsy Market
Specialty Medicine
Global Chronic Idiopathic Constipation Market
Specialty Medicine
ADHD Therapeutics Market
Specialty Medicine
Oral Cancer Treatment Market
Specialty Medicine
Prostate Cancer Therapeutics Market
Specialty Medicine
Necrotizing Fasciitis Market
Specialty Medicine
Pulmonary Arterial Hypertension (PAH) Market
Specialty Medicine
Idiopathic Pulmonary Fibrosis (IPF) Market