
 Spine Pain Market | 2026-2036
Spine Pain Market Size, Share, and Industry Trends Forecast 2026-2036
Spine Pain Market Analytics
Outpatient clinics is unwinding hospital-centric purchasing patterns as ambulatory surgical centers gain procedure share. Medtronic leverages its neuromodulation portfolio to sustain leadership in spinal cord stimulation. Boston Scientific anchors its position through radiofrequency ablation systems for chronic back pain. Stryker Corporation competes across minimally invasive decompression tools and interbody fusion devices.
Spine pain encompasses mechanical, neuropathic, and inflammatory disorders affecting the cervical, thoracic, and lumbar regions, with clinical management ranging from pharmacological intervention to implantable neurostimulation systems delivering targeted electrical pulses to dorsal column fibers. Prescription medications leads product type revenue due to chronic opioid and non-opioid analgesic utilization, while medical devices represents the fastest-expanding category as spinal cord stimulation and minimally invasive surgical tools displace conventional open procedures. Oral delivery mode still occupies the largest volume share, though injectable routes including epidural steroid and nerve block formulations are gaining traction in outpatient settings.
FDA breakthrough device designations compress neuromodimation approval timelines, while the EU MDR imposes stricter clinical evidence requirements on implantable spine devices. ISO 14155 governs clinical investigation standards that manufacturers must satisfy for CE marking and global market access. Stakeholders should monitor reimbursement parity shifts between inpatient and ambulatory settings as site-of-care migration reconfigures purchasing authority and pricing power across the value chain.
Market Dynamics
Site-of-care migration from inpatient to ambulatory settings is compressing purchasing timelines and redistributing pricing power across the spine pain value chain.
Growth Catalysts
- FDA breakthrough device pathway:Compressed approval timelines for neuromodulation systems accelerate patient access to spinal cord stimulation therapies.
- Ambulatory surgical center expansion:Hospital systems are building captive outpatient spine programs to capture procedure volume shifting away from traditional inpatient settings.
- Epidural steroid formulations:Injectable delivery routes for chronic back pain management are gaining traction in outpatient clinics as alternatives to oral opioid regimens.
Market Restraints
- EU MDR clinical evidence requirements:Stricter documentation mandates for implantable spine devices extend CE marking timelines and increase regulatory compliance costs.
- Neurostimulator battery supply concentration:Dependence on specialized lithium-ion cell manufacturers creates vulnerability in spinal cord stimulation device production.
- Radiofrequency ablation reimbursement gaps:Inconsistent coverage policies across payers limit adoption of thermal lesioning procedures for facet joint pain.
Strategic Opportunities
- Closed-loop adaptive stimulation:Convergence of artificial intelligence algorithms with implantable pulse generators enables real-time pain signal modulation personalized to patient physiology.
- Japan's aging demographic:Expanding elderly population with degenerative spine conditions creates sustained demand for minimally invasive decompression procedures.
- Digital health integration:Remote patient monitoring platforms paired with neuromodulation devices open recurring revenue streams through subscription-based pain management services.
Industry Challenges
- Interventional pain physician training pipelines:Shortage of fellowship-trained specialists limits expansion of advanced neuromodulation implantation capacity.
- ISO 14155 clinical investigation compliance:Multinational trial coordination for CE marking and FDA submissions demands specialized regulatory affairs expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spine Pain Market |
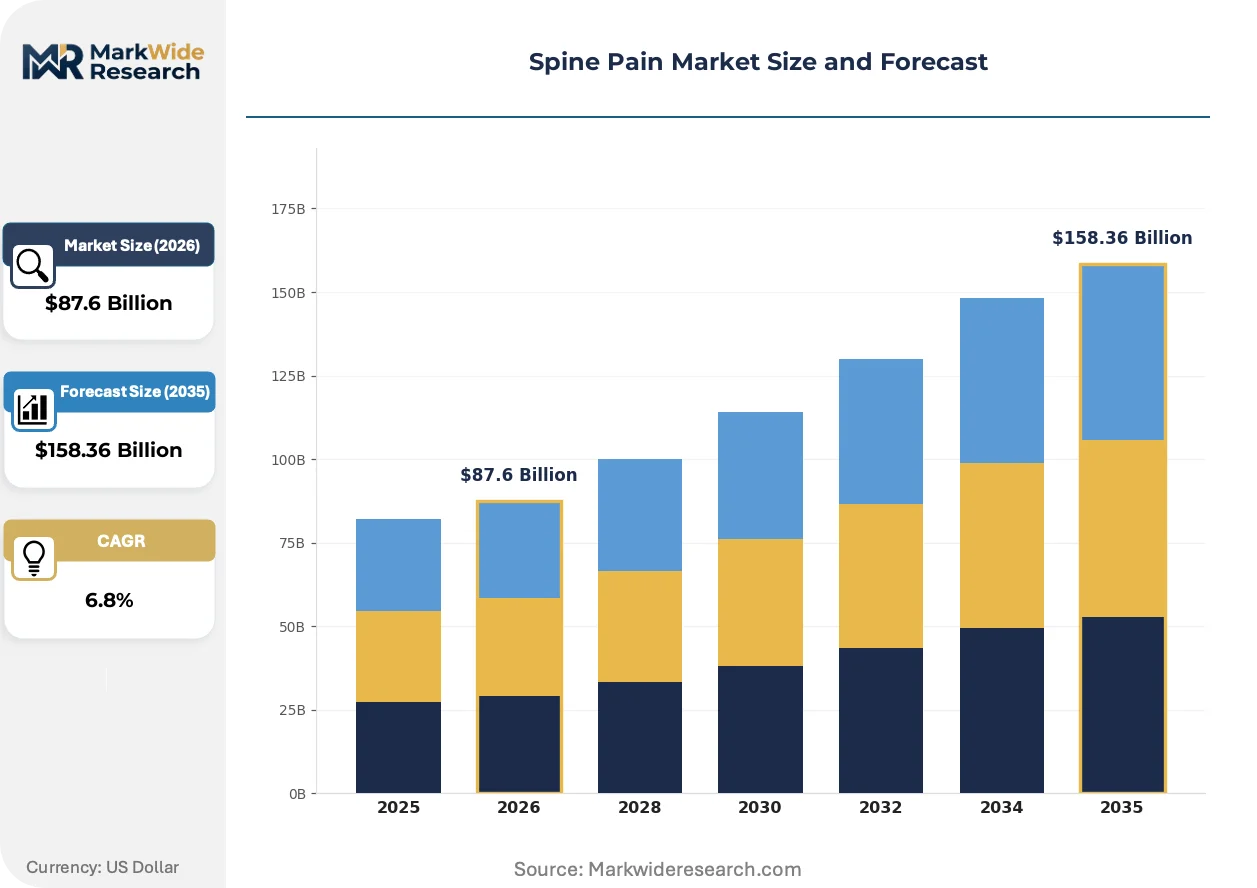
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Over-the-Counter Medications, Prescription Medications, Medical Devices, Physical Therapy Equipment Delivery Mode: Oral, Topical, Injectable, Surgical End User: Hospitals, Rehabilitation Centers, Home Care, Outpatient Clinics Therapy Area: Chronic Pain Management, Post-Surgical Recovery, Injury Treatment, Preventive Care |
| Companies Covered | Medtronic, Boston Scientific, Stryker Corporation, Abbott Laboratories, Zimmer Biomet, Globus Medical, NuVasive, Nevro Corp., Alphatec Spine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spine Pain Market Evolving Landscape
Digital therapeutics and implantable neurotechnology are converging to reshape how chronic spine pain is diagnosed, monitored, and treated across care settings.
Minimally invasive surgical tools are supplanting conventional open decompression and fusion procedures in lumbar and cervical applications. Ambulatory surgical centers now account for the majority of elective spine cases in the United States. This shift compresses hospital revenue per procedure while elevating demand for disposable instrument kits and navigation systems optimized for same-day discharge.
MDR imposes heightened clinical evidence standards on implantable spine devices seeking CE marking renewal. Manufacturers must generate prospective data or leverage equivalent device pathways to maintain European market access. High-risk neuromodulation systems face the steepest compliance burden, driving some portfolio rationalization among mid-tier device firms.
Patient self-referral to specialized spine clinics is bypassing traditional primary care gatekeeping in urban markets. Direct-to-consumer marketing of minimally invasive procedures accelerates consultation volume at independent ambulatory centers. Germany and Japan exhibit similar patterns where statutory health insurance reforms have loosened specialist access requirements.
Spine Pain Market Segmentation
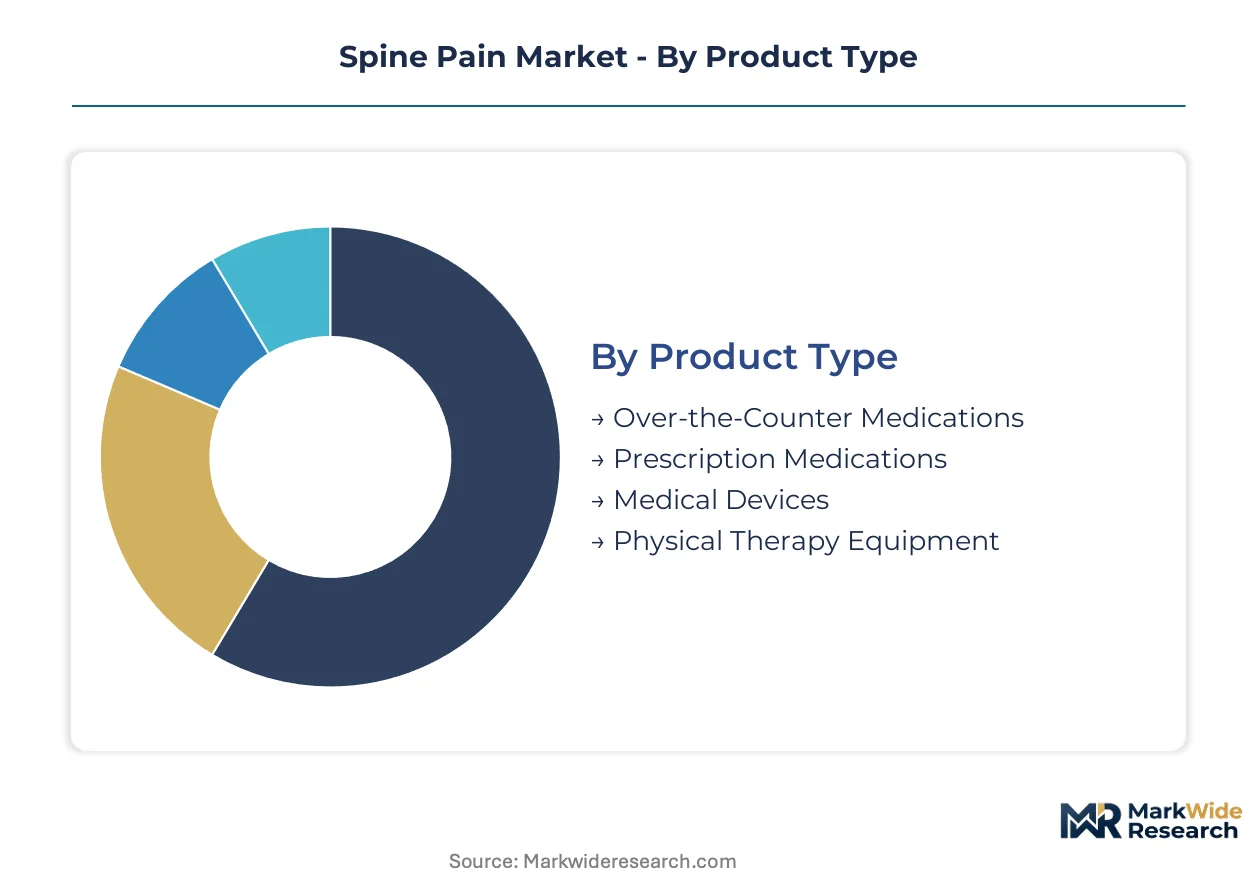
Segmentation in spine pain markets reveals how reimbursement pathways and site-of-care migration reshape demand patterns across product categories. Understanding these divides helps manufacturers align R&D portfolios with where clinical decision-making and purchasing authority are concentrating.
Product Type:
Prescription medications draw concentrated demand from United States and German hospital systems with established chronic pain protocols, while medical devices show stronger export-led growth into Japan's aging surgical markets.
- Prescription Medications:Opioid and non-opioid analgesics formulated for chronic spine conditions dominate hospital formularies. Demand concentrates in United States ambulatory surgery centers where pre- and post-procedure pain protocols drive volume, constrained by FDA REMS requirements for extended-release formulations.
- Medical Devices:Implantable spinal cord stimulators and minimally invasive surgical instruments deliver targeted electrical modulation or mechanical decompression. Japanese orthopedic hospitals are absorbing neuromodulation systems fastest as PMDA breakthrough pathways compress approval timelines for closed-loop adaptive technologies.
- Over-the-Counter Medications:NSAID and acetaminophen-based oral and topical formulations for mild-to-moderate mechanical back pain.
- Physical Therapy Equipment:TENS units, traction systems, and thermal modalities for conservative management in rehabilitation settings.
Prescription medications commands the established base. The steepest expansion runs through medical devices.
Delivery Mode:
Oral routes still capture the highest procedure volumes, though margin structures favor injectable and surgical modalities where formulation complexity and device-implant bundling elevate pricing power.
- Injectable:Epidural steroid formulations and nerve block solutions delivered via fluoroscopic guidance. Outpatient clinics in Germany are adopting these routes fastest as statutory health insurance reforms expand specialist access and same-day procedure reimbursement.
- Surgical:Implantable pulse generators, leads, and minimally invasive access systems for neuromodulation and decompression. United States ambulatory surgical centers are driving volume as hospital systems build captive outpatient spine programs to retain procedure share.
- Oral:Immediate-release and extended-release tablets, capsules, and liquids for systemic pain management across all care settings.
- Topical:Transdermal patches, gels, and creams for localized delivery with reduced systemic exposure.
Oral delivery retains volume leadership. Injectable applications are climbing the fastest as site-of-care migration accelerates.
End User:
Hospital purchasing remains concentrated domestically in mature markets, while outpatient clinics and home care show cross-border equipment demand as telehealth-integrated pain management spreads.
- Outpatient Clinics:Independent ambulatory centers and hospital-affiliated same-day surgery units performing minimally invasive decompression and neuromodulation implants. United States metropolitan markets are seeing patient self-referral bypass traditional primary care gatekeeping, compressing consultation-to-procedure timelines.
- Hospitals:Inpatient surgical departments and academic medical centers handling complex revision surgeries and high-risk patient populations. Japanese tertiary hospitals maintain strong demand for advanced fusion systems as aging demographics expand degenerative spine case complexity.
- Rehabilitation Centers:Post-acute facilities delivering physical therapy, TENS-based modalities, and interventional pain procedures.
- Home Care:Patient-directed TENS units, topical therapies, and remote-monitored neuromodulation systems for chronic management.
Hospitals command the established base. Outpatient clinics are gaining share fastest as purchasing authority migrates from inpatient settings.
Therapy Area:
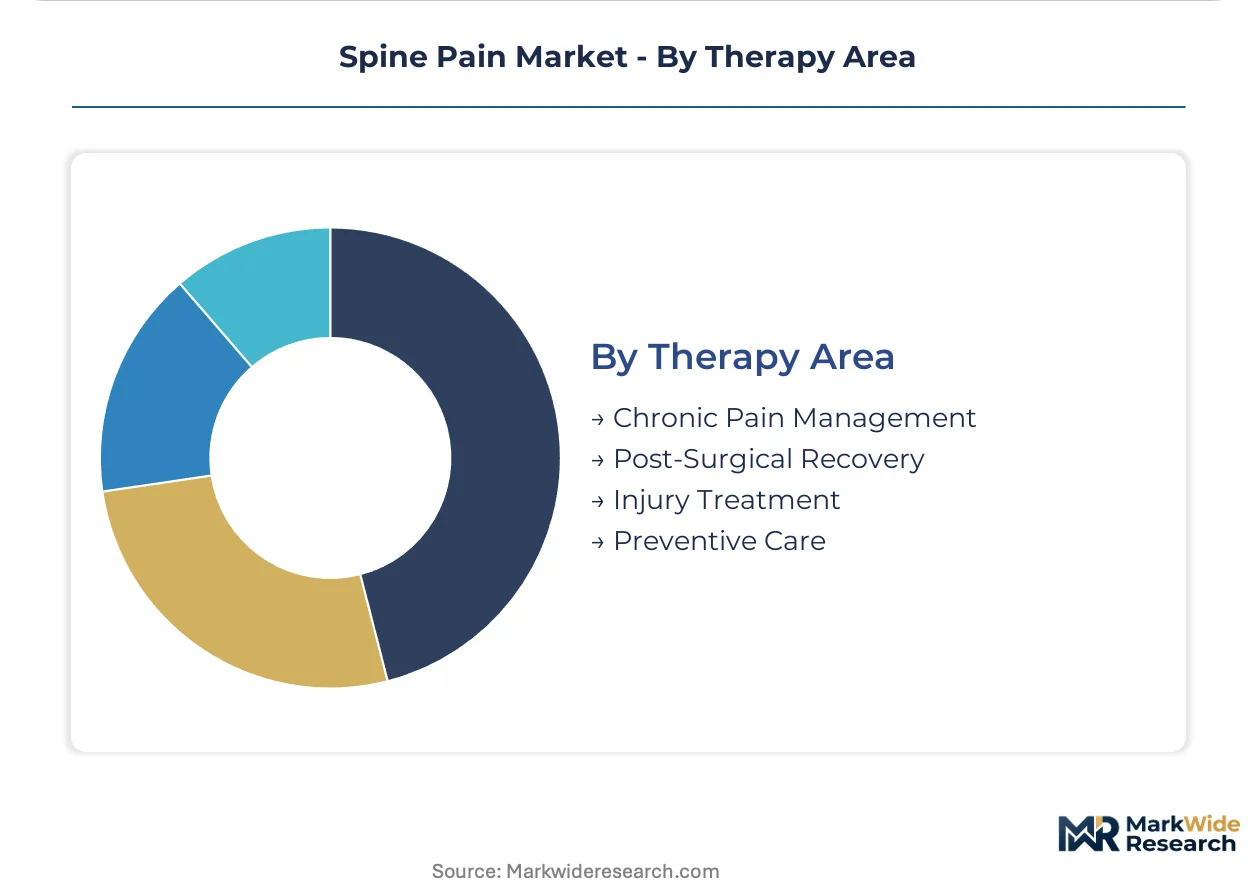
Chronic pain management absorbs the majority of pharmaceutical and device spending, while post-surgical recovery protocols are standardizing fastest across German and Japanese reimbursement frameworks.
- Chronic Pain Management:Long-term pharmacological and neuromodulation interventions for persistent neuropathic and mechanical spine conditions. United States pain clinics are consolidating demand as fellowship-trained interventional specialists concentrate in urban markets, though training pipeline constraints limit expansion capacity.
- Post-Surgical Recovery:Multimodal analgesia protocols and rehabilitation regimens following decompression, fusion, or disc replacement procedures. German statutory health insurers are driving standardization through outcome-based reimbursement pilots for lumbar fusion outcomes.
- Injury Treatment:Acute interventions for traumatic spine injuries including pharmacological stabilization and emergency surgical decompression.
- Preventive Care:Ergonomic interventions, early physical therapy, and lifestyle modifications to delay degenerative progression.
Chronic pain management commands the established base. Post-surgical recovery is expanding most quickly as enhanced recovery after surgery protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach anchors trans-Pacific distribution for neuromodulation devices entering the United States, while Frankfurt Airport's pharma cargo terminals expedite European supply chains for implantable spine systems.
United States
Medicare reimbursement parity for ambulatory surgical centers drives procedure volume migration from inpatient settings. FDA breakthrough device designations compress spinal cord stimulator approval timelines by months. The Dallas-Fort Worth metroplex hosts concentrated pain management clinic networks expanding neuromodulation implantation capacity.
Germany
Statutory health insurance reforms loosen specialist access requirements and expand same-day procedure coverage. EU MDR imposes stricter clinical evidence standards on implantable devices seeking CE marking renewal. The Rhine-Ruhr corridor clusters orthopedic hospitals adopting minimally invasive decompression protocols fastest.
Japan
Aging demographics expand degenerative spine case complexity and sustain demand for fusion systems. PMDA breakthrough pathways accelerate approvals for closed-loop adaptive stimulation technologies. Tokyo's tertiary medical centers concentrate the country's interventional pain specialist training programs.
United Kingdom
NHS outcome-based procurement pilots reshape purchasing authority for spinal surgery devices. MHRA post-Brexit regulatory autonomy creates divergent approval timelines from EU MDR processes. The Oxford-Cambridge arc anchors medical device R&D clusters focused on next-generation neuromodulation.
Australia
Private health insurance penetration supports elective spine procedure volumes in urban markets. TGA convergence with FDA standards streamlines market entry for US-manufactured implantable systems. Melbourne's hospital networks lead adoption of enhanced recovery after surgery protocols for lumbar fusion.
Spine Pain Market Competitive Landscape
Concentration sits with diversified medtech conglomerates commanding integrated neuromodulation and surgical portfolios. Three archetypes dominate: full-stack implantable device manufacturers, interventional pain specialists, and orthopedic surgery platform companies. Competitive moves center on ambulatory surgical center partnership programs and adaptive stimulation algorithm acquisitions.
Among US-based diversified medtech firms, Medtronic, Boston Scientific, and Stryker Corporation exemplify the full-stack archetype spanning implantable pulse generators through minimally invasive access systems. These entities occupy positions where device-implant bundling and site-of-care migration strategies concentrate purchasing influence.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific |
| Stryker Corporation |
| Abbott Laboratories |
| Zimmer Biomet |
| Globus Medical |
| NuVasive |
| Nevro Corp. |
| Alphatec Spine |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles for implantable pulse generators concentrate purchasing leverage among United States hospital systems while compressing margin structures for neuromodulation manufacturers serving ambulatory surgical centers.
Pricing Analysis
Three-tier pricing structure across premium adaptive stimulation, standard fixed-output, and economy single-lead systems governs spinal cord stimulator procurement. Price differentiation hinges on FDA breakthrough designation status and closed-loop algorithm sophistication. Cost compression in the economy tier is intensifying because GPO contract consolidation favors volume-commitment purchasing. Ambulatory surgical centers exhibit highest price sensitivity due to bundled payment constraints, while Japanese tertiary hospitals show lowest sensitivity given statutory reimbursement floors.
Supply Chain Analysis
Inbound logistics costs through the Port of Long Beach fluctuate with trans-Pacific container availability, affecting lead times for lithium-ion cells bound for implantable pulse generator assembly. Manufacturing concentrates in United States, Ireland, and Costa Rica for final device sterilization and packaging. Raw material dependencies include specialized lithium-ion battery cells, platinum-iridium electrodes, and medical-grade silicone sheathing. Single-source vulnerability sits with Korean battery cell suppliers. Distribution runs through specialty medical device distributors and direct hospital system contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital system consolidation into mega-GPOs shifts buyer power toward procurement committees, fragmenting pricing authority previously held by individual physicians.
For Market Incumbents: Secure captive supply agreements for lithium-ion battery cells before Korean supplier allocation constraints tighten. Deepen backward integration into lead electrode manufacturing to defend margin position against emerging neuromodulation entrants exploiting CE marking equivalence pathways. For New Entrants and Emerging Players: Differentiate on adaptive stimulation algorithms that reduce programming burden for interventional pain physicians. Target German outpatient clinics where statutory insurance reforms created fastest same-day procedure reimbursement expansion. Pursue hospital system partnership programs that bundle device placement with remote monitoring subscriptions. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medtech conglomerates rationalizing mid-tier implantable spine portfolios under EU MDR compliance cost pressure. Long-term viability centers on adaptive stimulation IP and ambulatory surgical center channel control. Watch FDA breakthrough designation grants to closed-loop systems as inflection signal for neuromodulation competitive restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Algorithm Development | FDA breakthrough pathway compresses approval timelines for adaptive stimulation systems targeting dorsal column fibers. |
| Ambulatory Surgical Center Partnership | Hospital system captive outpatient programs retain procedure volume migrating from inpatient settings. |
| EU MDR Clinical Evidence Investment | Prospective trial data satisfies CE marking renewal requirements for high-risk neuromodulation implants. |
| Remote Patient Monitoring Platform | Telehealth-integrated pain management opens recurring subscription revenue alongside device sales. |
| Japanese PMDA Breakthrough Submission | Aging demographics and compressed approval timelines accelerate market entry for adaptive technologies. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, PMDA approval databases, hospital GPO contract disclosures, and EU MDR notified body documentation. Interviews with interventional pain physicians, biomedical engineers, hospital purchasing committee members, and neuromodulation regulatory affairs specialists inform demand-side validation. Secondary sources include CMS Medicare reimbursement data, statutory health insurance procedure volumes, and implantable device customs records. Bottom-up procedure volume estimates triangulate against top-down manufacturer revenue disclosures.
Segmentation dimensions modeled span product type, delivery mode, end user, and therapy area across the analysis window. CAGRs derive from procedure volume trajectories, reimbursement parity shifts, and technology substitution curves for closed-loop versus fixed-output systems. Forecast inputs incorporate PMDA breakthrough pathway approval velocity, EU MDR implementation timelines, and site-of-care migration rates from inpatient to ambulatory settings.
The analysis sits within stated boundaries; outcomes outside sustained Medicare ASC reimbursement parity, Korean battery supply stability, or fellowship-trained physician pipeline expansion would require recalibration. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and ambulatory surgical center capacity buildout. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Cancer Pain Management Market
Pain Management
Pain Management Devices Market
Pain Management
Companion Animal Postoperative Pain Management Therapeutics Market
Pain Management
Global Morphine Market
Pain Management
Neuropathic Pain Market
Pain Management
Pain Therapeutic Solutions Market
Pain Management
Intravenous (IV) Ibuprofen Market
Pain Management
Pain Therapeutic Injectables Market
Pain Management
Chronic Pain Treatment Market
Pain Management
Topical Pain Relief Market
Pain Management
Postoperative Pain Market
Pain Management
Radiofrequency Ablation Devices for Pain Management Market
Pain Management
Global Analgesic Infusion Pumps Market
Pain Management
Pain Patches Market
Pain Management
Global Chiropractic Care Market
Pain Management
Chinese Fibromyalgia Market