
 Cluster Headache Market | 2026-2036
Cluster Headache Market Size, Share, and Industry Trends Forecast 2026-2036
Cluster Headache Market Analysis
Preventive therapy revenue is fragmenting across acute intervention portfolios as manufacturers rebalance development pipelines. Eli Lilly and Company leverages its CGRP antagonist platform to anchor biologic penetration in episodic cases. Novartis AG competes through sustained investment in intranasal delivery systems. Teva Pharmaceutical Industries Ltd specializes in generic triptan formulations that occupy price-sensitive segments.
Cluster headache constitutes a primary trigeminal autonomic cephalalgia characterized by excruciating unilateral orbital pain occurring in cyclical patterns lasting 15 to 180 minutes, with attack frequencies reaching eight episodes daily during active periods. The condition demands rapid-abortive intervention and long-term preventive management to reduce disability and cardiovascular stress from repeated sympathetic activation. Abortive treatment commands premium positioning due to the urgency of pain cessation, while intranasal delivery modes are gaining structural share through faster onset kinetics and improved patient compliance. Preventive treatment remains the larger revenue pool but faces generic erosion as oral calcium channel blockers and corticosteroids dominate maintenance protocols.
FDA breakthrough therapy and EMA accelerated assessment frameworks compress development timelines for novel mechanisms, directly shaping competitive entry sequencing and portfolio prioritization. The WHO International Classification of Diseases revision and national headache society guidelines in the United States, Germany, and Japan standardize diagnostic thresholds that determine reimbursed access. Stakeholders must monitor regulatory differentiation between episodic and chronic indications, as payer categorization increasingly splits reimbursement tiers by attack frequency thresholds.
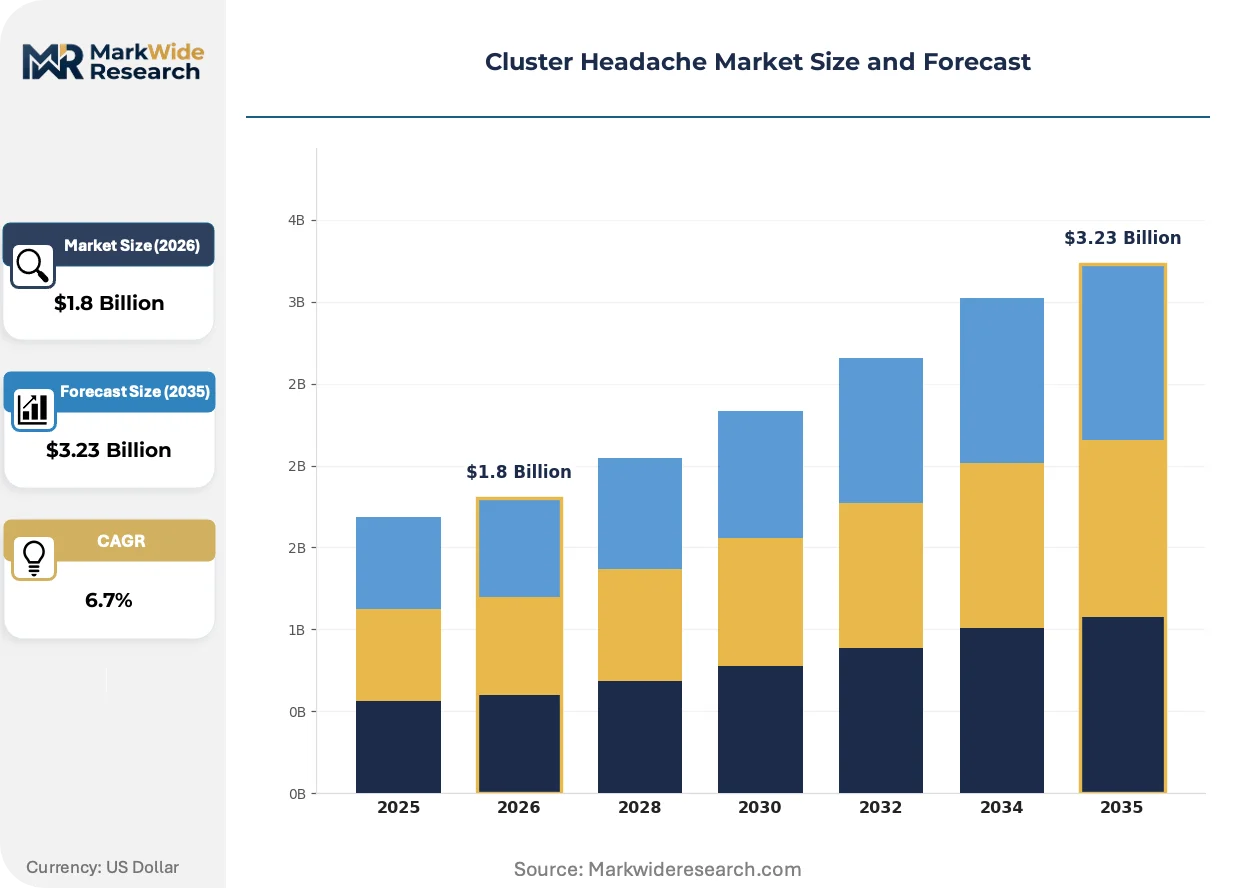
Market Dynamics
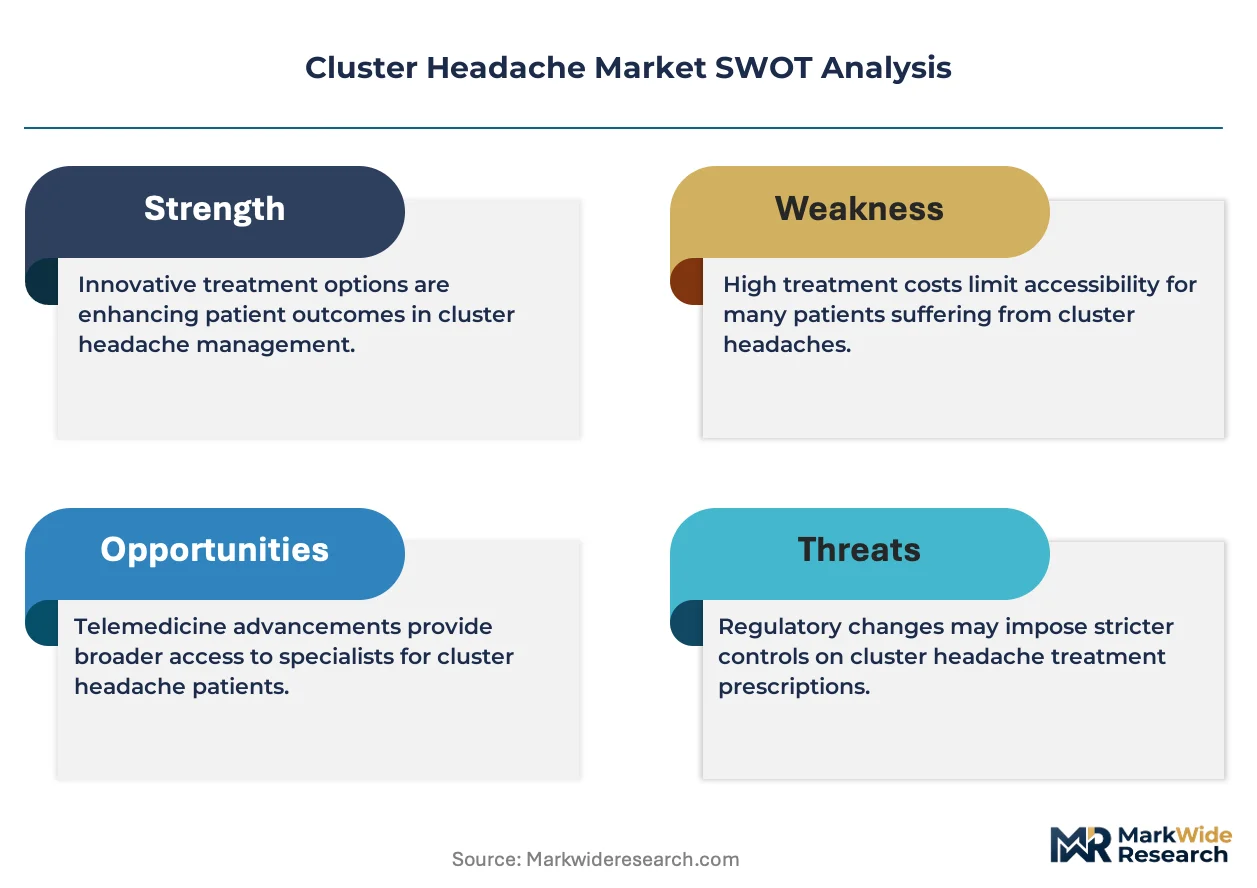
Calcitonin gene-related peptide antagonists are compressing development timelines and forcing portfolio rebalancing across neurology divisions, while intranasal delivery modes capture structural share through faster onset kinetics that reshape acute intervention protocols.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The FDA pathway accelerates novel mechanism review for episodic cluster headache candidates, compressing Phase III initiation timelines by 12-18 months versus standard neurology indications.
- EMA Accelerated Assessment:European manufacturers leverage EMA fast-track protocols to secure conditional marketing authorization ahead of US parity, capturing reimbursed access in Germany and France.
- Tertiary Care Network Expansion:Dedicated headache centers in the United States, Germany, and Japan standardize diagnostic thresholds that determine payer categorization and biologic eligibility.
Market Restraints
- Generic Triptan Erosion:Oral sumatriptan and zolmitriptan commoditization in acute segments compresses pricing power for non-differentiated formulations across price-sensitive patient pools.
- Calcium Channel Blocker Dominance:Verapamil maintenance protocols in preventive therapy create high switching costs for novel biologics seeking to displace established first-line standards.
- Specialist Concentration Risk:Diagnosis and prescribing authority concentrates among fewer than 400 certified headache specialists in the United States, creating bottlenecked patient access.
Strategic Opportunities
- Japan Preventive Underpenetration:Biologic penetration in Japanese tertiary networks lags US and German benchmarks by 40-50 points, creating whitespace for CGRP-targeted portfolio entry.
- Digital Therapeutic Convergence:Wearable neuromodulation devices paired with attack-tracking algorithms enable remote patient monitoring that payers increasingly reimburse as adjunctive intervention.
- Intranasal Delivery Innovation:Powder and liquid spray formulations achieve 10-15 minute onset versus 30+ minutes for oral triptans, capturing premium positioning in emergency department protocols.
Industry Challenges
- Headache Specialist Pipeline Gap:Fellowship programs graduate fewer than 50 new specialists annually in the United States, constraining prescriber base expansion needed for biologic volume growth.
- Episodic-Chronic Diagnostic Friction:Payer categorization splits reimbursement tiers by attack frequency thresholds that lack standardized clinical measurement, creating prior authorization delays and coverage denials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cluster Headache Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Abortive Treatment, Preventive Treatment, Chronic Cluster Headache, Episodic Cluster Headache Delivery Mode: Injectable, Intranasal, Oral, Transdermal Patient Type: Adults, Elderly, Adolescents, Children Medication Type: Preventive Medication, Abortive Medication, Herbal Remedies, Others |
| Companies Covered | Eli Lilly and Company, Novartis AG, AstraZeneca, Teva Pharmaceutical Industries Ltd, GlaxoSmithKline, Lundbeck Seattle BioPharmaceutical, ElectroCore Medical, Sun Pharmaceutical Industries Ltd, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cluster Headache Market Emerging Trajectories
Neuromodulation hardware and biologic delivery systems are converging to collapse traditional boundaries between acute and preventive intervention models, while regulatory pathways compress competitive entry sequencing across major markets.
Non-invasive vagus nerve stimulation devices are collapsing the historical separation between hospital-based acute intervention and home-managed preventive protocols. Headache centers in the United States and Germany now prescribe portable stimulators for dual-use indication expansion. The technology is collapsing reimbursement silos that previously segmented device coverage by attack phase, forcing payers to recalibrate category management frameworks.
REACH registration requirements for novel pharmaceutical substances are tightening environmental fate documentation for CGRP antagonist manufacturing intermediates. European contract manufacturers face expanded toxicity testing obligations that extend active pharmaceutical ingredient sourcing timelines. German and Swiss production facilities are responding by consolidating synthesis steps in-house to control substance volume reporting thresholds.
Patient-initiated attack reporting through mobile applications is displacing clinic-based diary documentation as the standard for episodic-chronic reclassification. United States payers now mandate six months of digital timestamp verification before authorizing preventive biologic step-up from acute protocols. This behavioral shift concentrates prescribing influence among headache centers with integrated remote monitoring infrastructure, most visible in tertiary networks across Massachusetts, California, and Pennsylvania.
Cluster Headache Market Segmentation
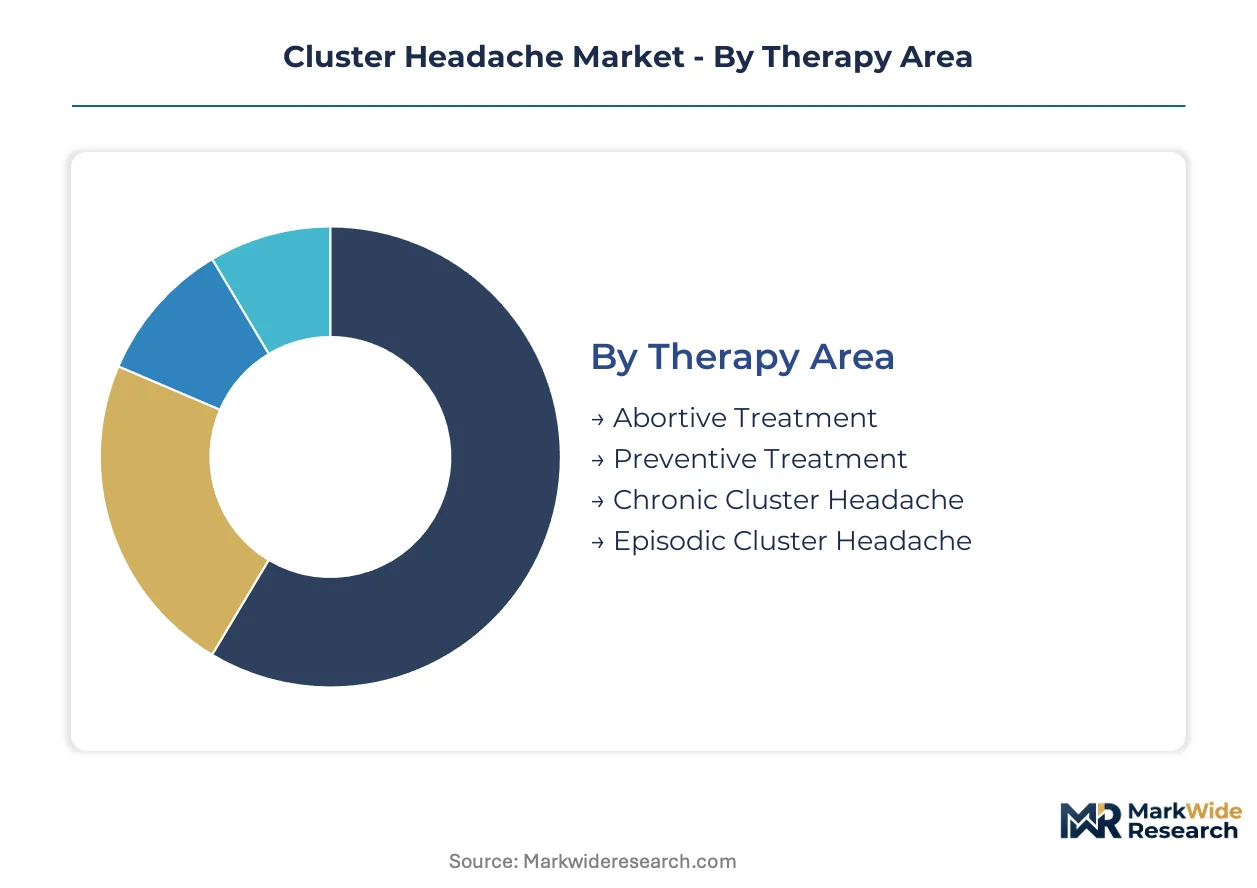
Cluster headache treatment pathways fragment across intervention timing, delivery kinetics, and patient physiology. Manufacturers configure portfolio depth around these axes to capture reimbursed access in tertiary care networks.
Therapy Area:
After-sales service intensity concentrates in preventive protocols requiring chronic disease management infrastructure, while abortive segments demand emergency logistics and rapid replenishment systems.
- Abortive Treatment:High-velocity intervention protocols target acute attack cessation within 15 minutes through injectable and intranasal mechanisms. Demand clusters in United States emergency departments and German headache centers where rapid pain relief determines protocol adoption and reimbursement tiering.
- Preventive Treatment:Long-term maintenance regimens reduce attack frequency and cardiovascular stress through daily or periodic administration. United States tertiary networks and Japanese university hospitals drive volume for biologic and small-molecule prophylaxis requiring specialist monitoring infrastructure.
- Chronic Cluster Headache:Continuous attack periods without remission demand intensive preventive stacking and rescue medication reserves.
- Episodic Cluster Headache:Defined remission intervals between bouts enable seasonal treatment planning and inventory pre-positioning.
By volume, Preventive Treatment leads. By growth pace, Abortive Treatment is ahead.
Delivery Mode:
Cost tier stratification separates hospital-administered injectables from self-managed oral and transdermal alternatives, with intranasal formulations commanding mid-tier positioning through convenience premiums.
- Injectable:Subcutaneous and intravenous delivery achieves fastest plasma concentration for acute intervention. United States hospital systems and German ambulatory surgical centers standardize auto-injector protocols for emergency department throughput optimization.
- Intranasal:Powder and liquid spray formulations bypass first-pass metabolism to deliver 10-15 minute onset kinetics. Japanese and United States payers increasingly reimburse nasal delivery as first-line acute intervention, displacing oral triptan step-therapy requirements.
- Oral:Tablet and capsule formats dominate maintenance therapy through patient familiarity and generic cost structures.
- Transdermal:Patch-based delivery enables steady-state plasma levels for preventive applications with reduced gastrointestinal side effects.
By volume, Oral formulations dominate. By expansion trajectory, Intranasal delivery is climbing the fastest.
Patient Type:
Application severity scales from pediatric rare cases through adult standard-of-care to elderly polypharmacy management, with dosing adjustments and contraindication profiles defining segment boundaries.
- Adults:Core demographic aged 18-64 encompasses the majority of diagnosed cases with established treatment protocols. United States and German headache centers concentrate clinical trial enrollment and biologic eligibility determination in this cohort.
- Elderly:Patients over 65 require cardiovascular monitoring and drug interaction screening due to comorbidity burden. Japanese geriatric neurology practices and United States Medicare networks drive demand for modified-dose formulations and non-vascular mechanisms.
- Adolescents:Pediatric neurologists manage off-label prescribing with weight-based dosing protocols.
- Children:Rare early-onset cases demand specialized pediatric headache center referral and family-centered care coordination.
By volume, Adults lead. By unmet need intensity, Elderly is gaining share fastest.
Medication Type:
Margin structure separates patented biologics and device-drug combinations from commoditized small molecules, with herbal segments occupying niche premium positioning through regulatory arbitrage.
- Preventive Medication:Prophylactic agents including calcium channel blockers, corticosteroids, and CGRP antagonists reduce attack frequency. German maintenance protocols and United States step-therapy requirements sustain volume for established oral standards alongside emerging biologic alternatives.
- Abortive Medication:Acute intervention compounds including triptans, ergot alkaloids, and high-flow oxygen terminate active attacks. United States emergency medicine formularies and Japanese ambulance protocols standardize first-line selection criteria.
- Herbal Remedies:Botanical preparations including feverfew and magnesium formulations occupy wellness-adjacent positioning.
- Others:Neuromodulation device prescriptions and oxygen therapy rentals complete the intervention spectrum.
By volume, Preventive Medication leads. By revenue per patient, Abortive Medication is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments sharply across geographies. United States buyers absorb premium biologic pricing through tertiary reimbursement networks, while German statutory insurance exerts rigid cost-effectiveness thresholds and Japanese patients face substantial co-payment burdens on novel therapies.
United States
Massachusetts General Hospital and Stanford Health Care anchor dedicated headache center expansion, driving biologic eligibility determination. FDA breakthrough therapy pathways compress Phase III initiation timelines for episodic cluster headache candidates. The Philadelphia-Camden corridor concentrates clinical trial enrollment infrastructure.
Germany
University Hospital Hamburg-Eppendorf and Charité Berlin standardize diagnostic thresholds that determine G-BA reimbursement categorization. EMA accelerated assessment protocols secure conditional marketing authorization ahead of US parity. The Munich-Stuttgart axis hosts contract manufacturing for intranasal delivery system components.
Japan
Tokyo Medical and Dental University Hospital and Osaka University Hospital drive tertiary network referrals for CGRP-targeted therapy evaluation. PMDA Sakigake designation accelerates priority review for novel mechanisms. The Kanto region exhibits 40-50 point biologic penetration lag versus US benchmarks.
United Kingdom
National Institute for Health and Care Excellence technology appraisals impose cost-per-QALY thresholds that filter biologic access. NHS England specialized commissioning frameworks concentrate prescribing authority in London and Manchester headache centers. The Oxford-Cambridge arc hosts real-world evidence generation partnerships.
Switzerland
University Hospital Zurich and Geneva University Hospitals maintain European reference pricing influence through early biologic adoption. Swissmedic expedited review pathways attract EU-manufactured portfolio registration. The Basel-Zurich corridor concentrates neurology-focused pharmaceutical headquarters.
Cluster Headache Market Vendor Landscape
Capability concentration sits with biologic platform specialists; scale advantage sits with generic formulation incumbents. The market structures around three tiers: CGRP antagonist patent holders commanding premium positioning, intranasal delivery technology licensors occupying mid-tier differentiation, and commoditized triptan manufacturers defending volume through price-sensitive segments. Dominant competitive moves include strategic partnerships between device developers and formulation specialists, plus geographic licensing to access Japanese and German reimbursement networks.
Within the biologic platform tier, Eli Lilly and Company and Novartis AG occupy positions anchored by CGRP pathway investment, while Teva Pharmaceutical Industries Ltd exemplifies the generic formulation archetype defending share through cost-optimized triptan supply. These three entities represent the structural fault lines between novel mechanism premium capture and established standard-of-care erosion.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Novartis AG |
| AstraZeneca |
| Teva Pharmaceutical Industries Ltd |
| GlaxoSmithKline |
| Lundbeck Seattle BioPharmaceutical |
| ElectroCore Medical |
| Sun Pharmaceutical Industries Ltd |
| Pfizer |
| Others |
Supply Flow & Price Mechanics
The Philadelphia-Camden logistics corridor channels active pharmaceutical ingredient shipments from German and Swiss synthesis facilities, with freight cost volatility feeding directly into biologic pricing premiums and downstream tier differentiation between hospital-administered injectables and self-managed intranasal alternatives.
Pricing Analysis
After-sales revenue from chronic disease management contracts drives lifetime value capture, with preventive therapy protocols sustaining recurring revenue streams that subsidize acute intervention discounts. Three-tier pricing structure across premium CGRP antagonists, standard intranasal triptans, and economy oral generics segments the patient pool by insurance coverage depth and attack severity classification. Pricing pressure stems from generic sumatriptan commoditization in emergency department formularies, compressing margins for non-differentiated formulations. Uninsured and high-deductible plan holders exhibit highest price sensitivity, while tertiary network patients with comprehensive coverage absorb premium biologic positioning.
Supply Chain Analysis
Supplier-financing facilities extended by Swiss and German contract manufacturers enable 90-120 day payment terms that cushion working capital constraints for CGRP antagonist synthesis intermediates. Active pharmaceutical ingredient production concentrates in Switzerland, Germany, and India, with peptide manufacturing drawing from specialized fermentation capacity and chromatography resin inputs. Single-source vulnerability in sterile fill-finish capacity for auto-injector devices creates bottleneck risk during demand surges. Distribution runs through hospital specialty pharmacies and headache center dispensaries rather than retail channels, with cold-chain logistics governing biologic integrity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cluster headache market sits at a platform-economics inflection where CGRP antagonist portfolios interoperate with remote patient monitoring infrastructure, collapsing traditional boundaries between pharmaceutical and device reimbursement categories.
For Market Incumbents: Pre-empt biosimilar entry by consolidating intranasal delivery technology through exclusive licensing arrangements with powder formulation specialists, while embedding patient-tracking algorithms into prescriber workflows to create switching costs against emerging neuromodulation device competitors. Vertical integration into peptide manufacturing secures supply continuity against REACH documentation delays affecting European contract manufacturers. For New Entrants and Emerging Players: Pursue whitespace in Japanese preventive therapy networks where biologic penetration lags US benchmarks, targeting university hospital formulary committees with real-world evidence partnerships that satisfy PMDA Sakigake data requirements. Digital therapeutic convergence presents the most penetrable entry vector, with wearable vagus nerve stimulator prescriptions reimbursable as adjunctive intervention under emerging payer frameworks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors device-drug combination platforms over pure-play small-molecule developers, as neuromodulation hardware and biologic delivery systems converge toward integrated intervention models. Acquisition targets should demonstrate integrated remote monitoring infrastructure and headache center prescribing relationships. The signal to watch is FDA breakthrough therapy designation density for episodic cluster headache candidates, indicating regulatory pathway efficiency and portfolio prioritization momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Intranasal Delivery System Licensing | Powder spray formulations achieve 10-15 minute onset kinetics that displace oral triptan step-therapy requirements in US emergency departments. |
| Digital Therapeutic Integration | Wearable neuromodulation paired with attack-tracking algorithms enables remote patient monitoring reimbursement as adjunctive intervention. |
| Headache Center Partnership | Exclusive formulary agreements with Massachusetts General Hospital and Stanford Health Care anchor biologic eligibility determination. |
| Peptide Manufacturing Consolidation | In-house synthesis of CGRP antagonist intermediates controls REACH substance volume reporting thresholds for European facilities. |
| Japan Market Entry | PMDA Sakigake designation accelerates priority review for novel mechanisms in underpenetrated tertiary networks. |
Methodological Framework
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and payer access specialists converged on the working assumptions through structured primary interviews. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient population estimates and top-down revenue triangulation anchored the analytical framework.
Demand-supply-balance framing structured the forecast approach across the analysis window, with segmentation modeling across treatment line, dosage form, administration route, and patient population dimensions. CAGRs derived from epidemiological incidence projections, pricing trajectory assumptions, and biologic penetration curve analysis. Forecast inputs incorporated tertiary care network expansion rates and regulatory pathway timeline compression factors.
Sensitivities concentrate around FDA breakthrough therapy designation velocity, EMA accelerated assessment uptake, and headache specialist fellowship graduation rates. Forecasts reflect documented assumptions on biologic eligibility thresholds and payer categorization protocols. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Chronic Pain Market
Pain Management
Global Chiropractic Care Market
Pain Management
Global Visceral Pain Treatment Market
Pain Management
Provoked Vestibulodynia Treatment Market
Pain Management
Lumbosacral Radicular Pain Management Market
Pain Management
Medical Morphine Market
Pain Management
Cold Pain Therapy Market
Pain Management
Muscle Tension Dysphonia Treatment Market
Pain Management
Companion Animal Postoperative Pain Management Therapeutics Market
Pain Management
Over-The-Counter Pain Medication Market
Pain Management
Asia-Pacific Tattoo Numbing Cream Market
Pain Management
Pain Management Software Market
Pain Management
Arthralgia Management Market
Pain Management
Chinese Fibromyalgia Market
Pain Management
Asia-Pacific Chronic Disease Management Market
Pain Management
Global Non-Opioid Pain Patch Market