
 Pediatric Growth Hormone Deficiency Market | 2026-2036
Pediatric Growth Hormone Deficiency Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric Growth Hormone Deficiency Market Outlook
Market Overview
Aftermarket service revenue from patient monitoring and adherence programs is narrowing toward integrated digital platforms that tie therapy outcomes to continued reimbursement. Novo Nordisk A/S leverages its diabetes care infrastructure to extend into pediatric endocrinology support services. Eli Lilly and Company anchors its position through long-acting somatropin formulations that reduce injection frequency.
Pediatric growth hormone deficiency denotes a clinical condition of insufficient growth hormone secretion from the anterior pituitary, diagnosed via stimulation testing and insulin-like growth factor-1 measurement, treated primarily with recombinant human growth hormone (rhGH) produced through E. coli or mammalian cell expression systems. Recombinant hormones dominate the product landscape due to established biosafety profiles and decades of clinical validation, while biosimilars are gaining structural traction as patent cliffs open reference product markets. Delivery mode segmentation reveals injection as the incumbent standard, though transdermal and oral formulations represent the fastest-growing development pipelines where patient compliance drives margin pool migration.
FDA, EMA, and PMDA frameworks govern rhGH approval pathways, with each regulator mandating distinct pediatric study designs and post-market surveillance for growth velocity endpoints. The EU AI Act and GDPR increasingly shape how connected delivery devices collect and transmit adherence data across European markets. Stakeholders must monitor how real-world evidence requirements for label expansion are converging across FDA and EMA guidance documents.
Market Dynamics
Long-acting recombinant somatropin formulations are compressing treatment protocols from daily to weekly injections, fundamentally restructuring adherence economics and shifting margin pools toward device-integrated delivery systems.
Growth Catalysts
- FDA Pediatric Study Requirements:Streamlined approval pathways for rhGH in pediatric indications accelerate label expansions and reduce time-to-market for novel formulations.
- Digital Adherence Platforms:Connected injection devices with real-time monitoring capabilities improve treatment persistence rates and unlock value-based reimbursement contracts.
- Japan PMDA Fast-Track Designation:Accelerated review timelines for rare pediatric endocrine disorders stimulate pipeline investment in long-acting delivery technologies.
Market Restraints
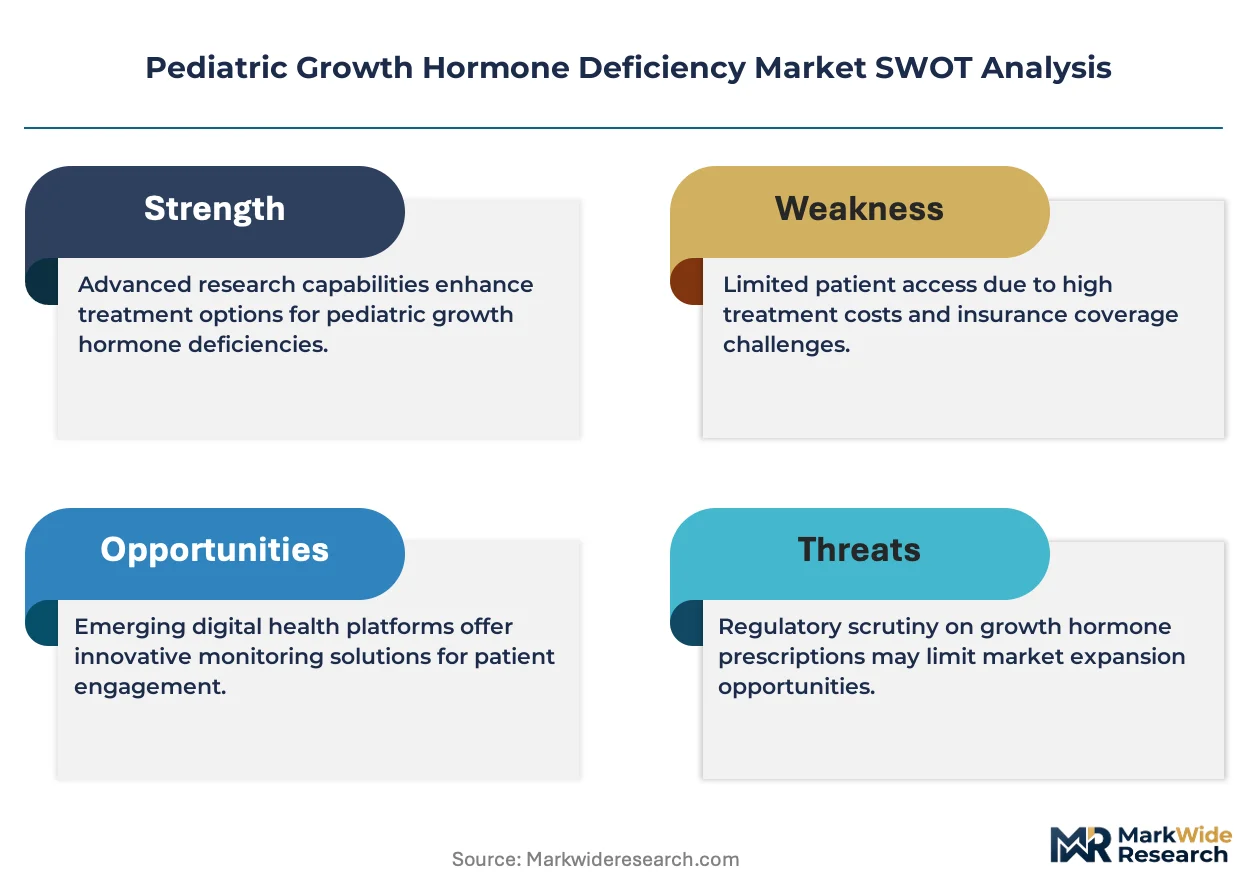
- Recombinant Protein Production Costs:Mammalian cell culture requirements for certain rhGH variants create persistent manufacturing cost premiums versus E. coli expression systems.
- EMA Post-Market Surveillance Burden:Extended growth velocity tracking mandates impose multi-year follow-up obligations that inflate commercialization expenses.
- Oral Peptide Bioavailability Ceiling:Gastrointestinal degradation limits systemic absorption of non-injectable growth hormone alternatives below therapeutic thresholds.
Strategic Opportunities
- Sub-Saharan Africa Diagnostic Gap:Underserved pediatric endocrinology infrastructure presents first-mover potential for portable stimulation testing and telemedicine protocols.
- EU AI Act Compliance Services:Algorithmic transparency requirements for connected delivery devices create adjacent revenue streams in clinical decision support software.
- Transdermal Microneedle Convergence:Combination of dissolvable microarray technology with sustained-release formulations addresses needle phobia in pediatric populations.
Industry Challenges
- Pediatric Endocrinologist Workforce Scarcity:Fellowship program bottlenecks in the United States and Germany constrain patient throughput at specialized referral centers.
- Multi-Jurisdiction Label Harmonization:Divergent growth velocity endpoints across FDA, EMA, and PMDA frameworks complicate global clinical trial design and dossier preparation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric Growth Hormone Deficiency Market |
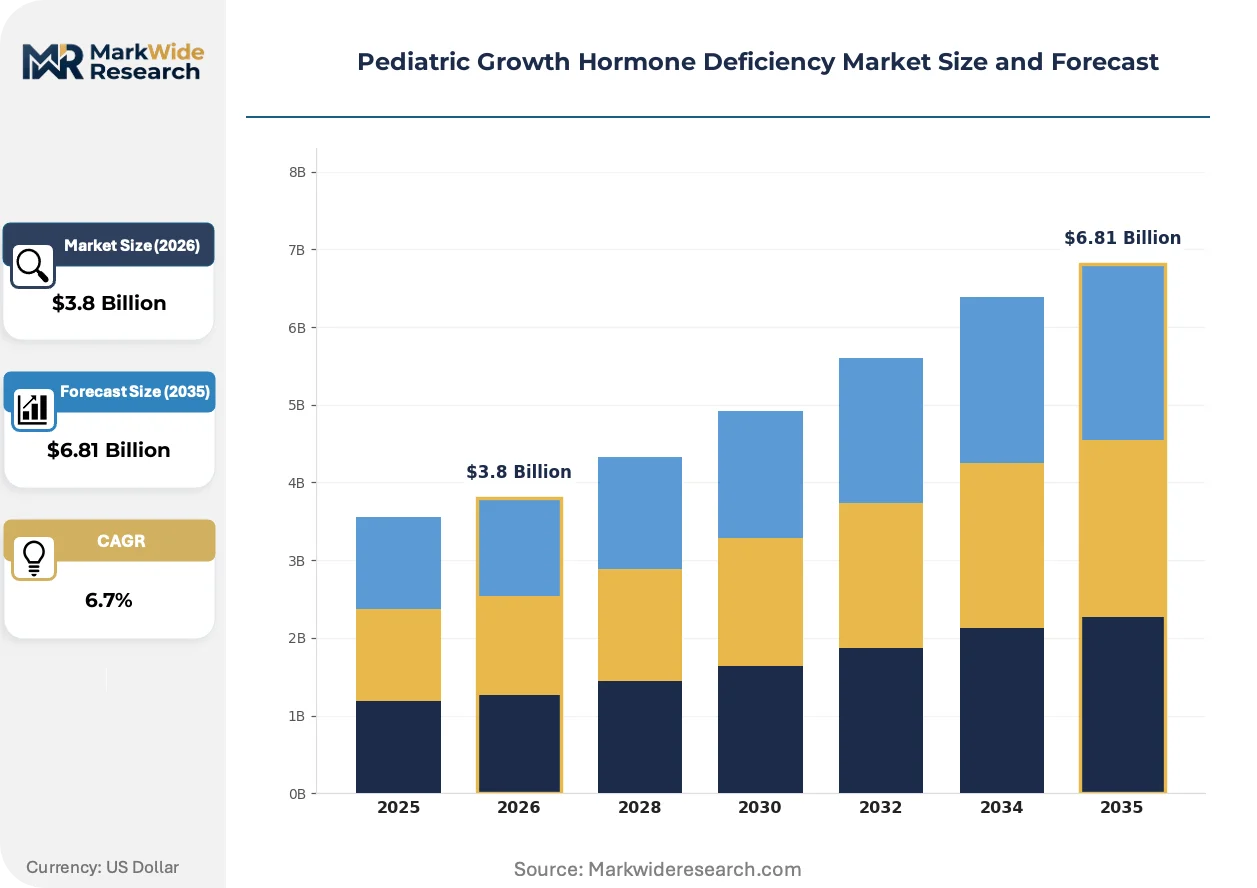
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant Hormones, Synthetic Hormones, Biosimilars, Combination Therapies Therapy Area: Endocrinology, Growth Disorders, Pediatrics, Hormonal Imbalances Delivery Mode: Injection, Oral, Infusion, Transdermal End User: Hospitals, Clinics, Homecare, Pediatric Practices |
| Companies Covered | Pfizer Inc., Novo Nordisk A/S, Eli Lilly and Company, Merck KGaA, Genentech Inc., Sandoz International GmbH, Ferring Pharmaceuticals, Ipsen Pharma, Ascendis Pharma A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric Growth Hormone Deficiency Market Strategic Shifts
Delivery modality innovation sits at the center of competitive differentiation, with device manufacturers and formulation specialists converging on patient-centric designs that minimize injection burden while capturing adherence data for payer negotiations.
Connected autoinjector platforms equipped with Bluetooth-enabled dose tracking and mobile application integration are digitizing the relationship between patients, caregivers, and clinical teams. Pediatric endocrinology clinics in the United States and Germany are deploying these systems to document real-world treatment persistence. The resulting data streams enable outcome-based contracting with private insurers and Medicaid programs.
EMA guidance on real-world evidence for pediatric indications is tightening evidentiary standards for label expansion claims. Sponsors must now demonstrate sustained growth velocity improvements across broader age cohorts than previously required. Long-acting somatropin developers are responding by extending post-approval study commitments and integrating European registry data into regulatory submissions.
Caregiver procurement preferences are gravitating toward pharmacy benefit managers that bundle medication with adherence coaching and remote monitoring. This unbundling of traditional clinical services from hospital-based endocrinology departments redirects patient flow toward specialty pharmacy channels. The shift is most pronounced in United States markets where vertical integration between payers and pharmacy networks accelerates channel consolidation.
Pediatric Growth Hormone Deficiency Market Segmentation
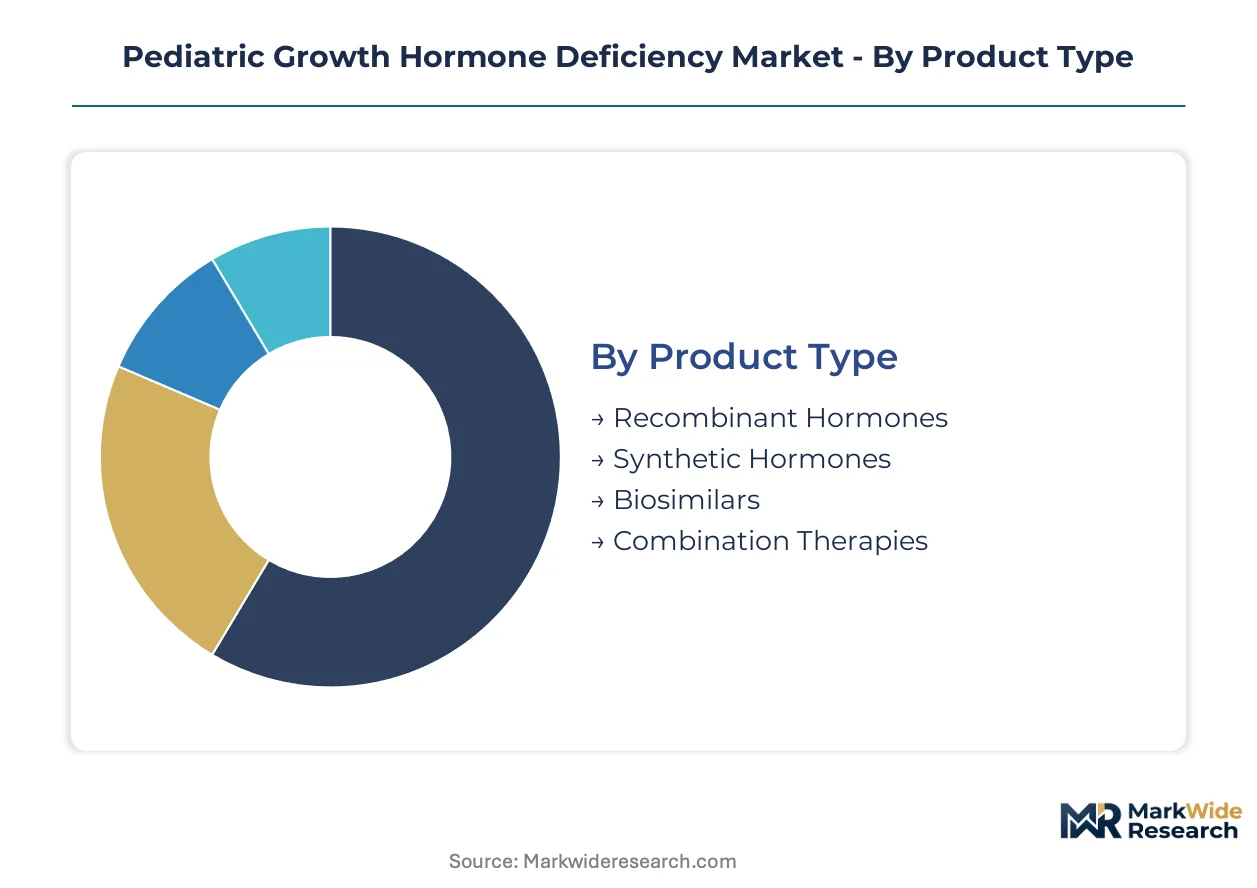
Segmentation in the pediatric growth hormone deficiency market determines where service revenue concentrates and which patient cohorts drive formulation innovation. Distinct delivery preferences across care settings create divergent margin structures for device-integrated versus conventional therapies.
Product Type:
After-sales service intensity varies sharply across expression systems and manufacturing platforms, with mammalian cell-derived products demanding specialized cold-chain support and patient training programs that E. coli-based alternatives do not require.
- Recombinant Hormones:Produced via E. coli or mammalian cell expression systems with established biosafety profiles validated through decades of pediatric clinical use. Demand concentrates in the United States and Germany where specialized pediatric care networks and reimbursement frameworks for growth disorder therapies are most developed, with long-acting formulations displacing daily injection regimens.
- Biosimilars:Structurally similar alternatives gaining traction as patent cliffs open reference product markets, requiring rigorous immunogenicity surveillance and pharmacovigilance infrastructure. European markets show strongest uptake where EMA frameworks provide clearer interchangeability guidance than FDA pathways.
- Synthetic Hormones:Chemically manufactured analogs with distinct pharmacokinetic profiles suited for specific pediatric metabolic phenotypes.
- Combination Therapies:Co-formulated regimens integrating growth hormone with adjunctive endocrine modulators for complex deficiency presentations.
By volume, recombinant hormones lead. By growth pace, biosimilars are climbing the fastest.
Therapy Area:
Cost tier stratification separates acute intervention protocols from chronic management programs, with endocrinology commanding premium pricing due to diagnostic complexity and long-term monitoring obligations.
- Endocrinology:Specialized pituitary-targeted interventions requiring stimulation testing and insulin-like growth factor-1 measurement protocols. Pediatric endocrinology clinics in North America and Europe are expanding patient intake protocols while deploying connected autoinjector platforms to document real-world treatment persistence.
- Growth Disorders:Constitutional delay and idiopathic short stature indications where growth velocity endpoints determine reimbursement continuation. United States Medicaid programs increasingly require digital adherence verification for sustained coverage.
- Pediatrics:Age-specific dosing algorithms and developmental milestone integration distinguish this cohort from adult hormone replacement.
- Hormonal Imbalances:Multi-axis deficiencies requiring coordinated thyroid, adrenal, and gonadal assessment alongside growth hormone therapy.
Endocrinology captures the highest per-patient service revenue. Growth disorders show the steepest expansion trajectory as diagnostic thresholds broaden.
Delivery Mode:
Application context dictates device selection, with hospital-based initiation favoring precision infusion systems while homecare maintenance drives demand for patient-operated platforms with minimal training requirements.
- Injection:Incumbent standard encompassing daily and weekly recombinant somatropin administration via conventional syringes or autoinjectors. Long-acting formulations are compressing treatment protocols from daily to weekly injections, fundamentally restructuring adherence economics and shifting margin pools toward device-integrated delivery systems.
- Transdermal:Microneedle arrays and dissolvable microarray technology addressing needle phobia in pediatric populations. Development pipelines in Japan and Germany are advancing sustained-release transdermal formulations where PMDA fast-track designations accelerate rare pediatric endocrine disorder reviews.
- Oral:Peptide formulations constrained by gastrointestinal degradation limiting systemic absorption below therapeutic thresholds.
- Infusion:Pump-based delivery reserved for complex multi-hormone regimens in tertiary care settings.
Injection maintains volume dominance. Transdermal development is gaining share fastest as compliance-driven margin migration accelerates.
End User:
Customer type determines procurement authority and reimbursement pathway, with hospital pharmacy committees negotiating bulk contracts while homecare channels capture recurring adherence service revenue.
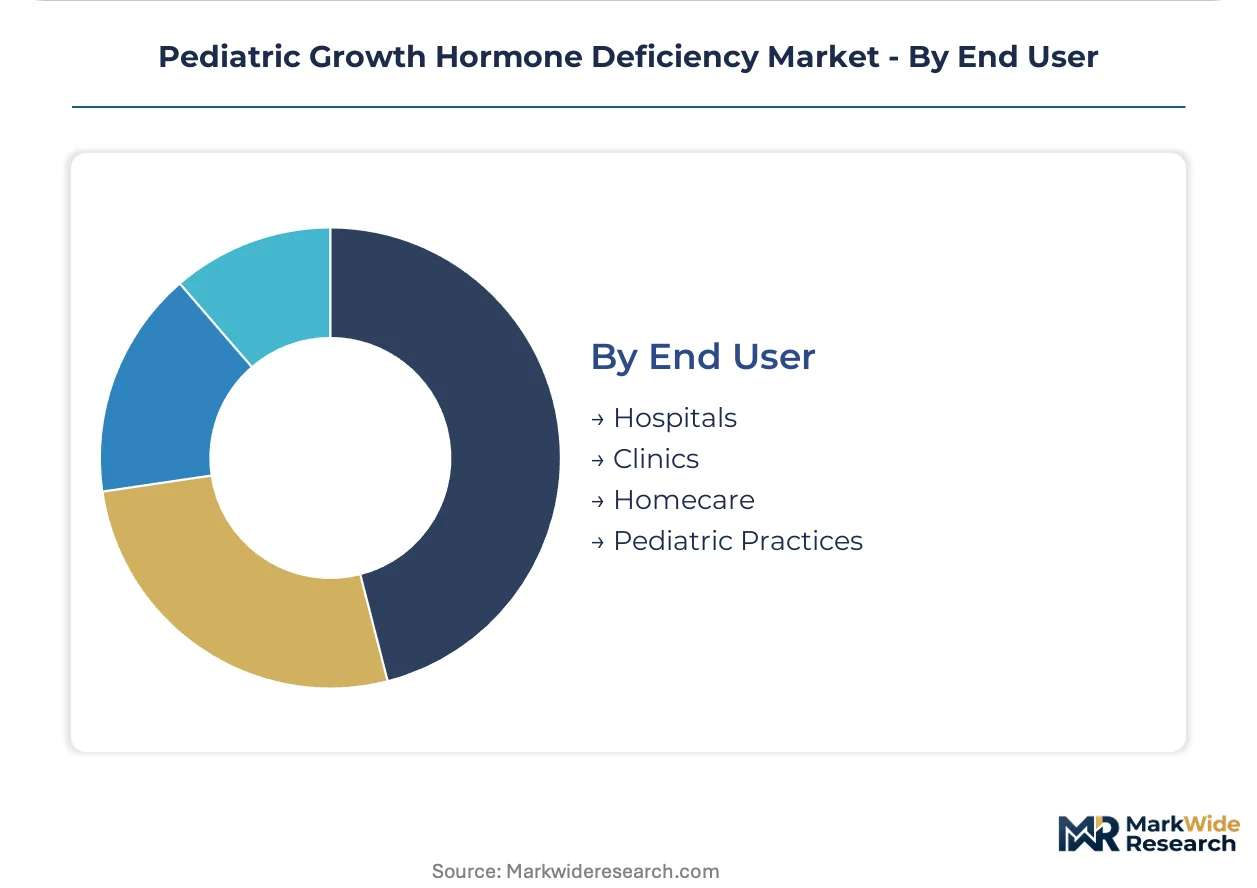
- Hospitals:Tertiary referral centers conducting diagnostic stimulation testing and treatment initiation for severe deficiency presentations. Fellowship program bottlenecks in the United States and Germany constrain patient throughput at specialized referral centers, creating waitlist dynamics that favor established formulary relationships.
- Homecare:Post-stabilization maintenance setting where pharmacy benefit managers bundle medication with adherence coaching and remote monitoring. This channel shows pronounced expansion in United States markets where vertical integration between payers and pharmacy networks accelerates consolidation.
- Clinics:Community-based endocrinology practices managing stable patients with periodic growth velocity assessment.
- Pediatric Practices:Primary care gatekeepers conducting initial screening and referral coordination.
Hospitals lead by patient acuity and revenue per case. Homecare is expanding most quickly as channel unbundling redirects patient flow toward specialty pharmacy networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States and Germany exhibit lowest price elasticity due to comprehensive reimbursement frameworks, while emerging markets in Asia and Latin America face acute sensitivity to therapy costs and limited specialist access.
United States
Pediatric endocrinology networks in Boston and New York Metro drive diagnostic throughput for growth hormone deficiency, with Medicaid programs increasingly mandating digital adherence verification for sustained coverage. FDA streamlined approval pathways for rhGH in pediatric indications accelerate label expansions for novel formulations. The Greater Boston cluster anchors specialized referral centers where fellowship program bottlenecks create waitlist dynamics favoring established formulary relationships.
Germany
EMA post-market surveillance requirements for growth velocity tracking concentrate commercialization investment in Munich and Berlin-Brandenburg, where pediatric endocrinology clinics expand patient intake protocols. The EU AI Act and GDPR shape how connected delivery devices collect adherence data across German markets. Baden-Württemberg hosts device-integrated delivery system development for long-acting somatropin formulations.
Japan
PMDA fast-track designation for rare pediatric endocrine disorders stimulates pipeline investment in long-acting delivery technologies, with Tokyo and Osaka centers leading diagnostic protocol standardization. METI industrial policy supports domestic manufacturing of recombinant hormone expression systems. The Kansai region advances transdermal microneedle convergence for pediatric needle phobia applications.
United Kingdom
NHS England specialty pharmacy networks bundle growth hormone medication with adherence coaching, redirecting patient flow from hospital-based endocrinology departments. MHRA alignment with EMA real-world evidence standards tightens evidentiary requirements for label expansion claims. The London-Southeast corridor concentrates digital health platform deployment for remote monitoring of treatment persistence.
India
CDSCO regulatory pathways for biosimilar rhGH products open reference markets as patent cliffs expire, with Maharashtra and Karnataka emerging as production centers for E. coli-derived expression systems. Price sensitivity dominates procurement decisions at tertiary care hospitals in Delhi-NCR. The Telangana cluster develops cost-adapted diagnostic protocols for stimulation testing in resource-constrained settings.
Pediatric Growth Hormone Deficiency Market Competitive Environment
Capability concentration sits with integrated pharmaceutical conglomerates possessing mammalian cell culture expertise and established pediatric regulatory dossiers; scale advantage sits with diabetes care infrastructure operators extending into adjacent endocrinology support services. The market structure reflects tiered competition between originator recombinant hormone developers, biosimilar specialists, and device-integrated delivery platform innovators. Three archetypes dominate: long-acting formulation pioneers, connected adherence system integrators, and emerging market cost optimizers. Dominant competitive moves include backward integration into expression system manufacturing and strategic partnerships with digital health platform developers.
Within the integrated pharmaceutical tier, Pfizer Inc. and Novo Nordisk A/S occupy anchor positions representing contrasting strategic vectors—Pfizer as a diversified research-based conglomerate with deep pediatric regulatory experience, Novo Nordisk as a diabetes-endocrinology specialist leveraging care infrastructure for patient support services. Eli Lilly and Company exemplifies the long-acting formulation archetype through its somatropin development focus. Merck KGaA, Genentech Inc., and Sandoz International GmbH represent European-origin players with distinct structural profiles—Merck KGaA as a family-controlled science and technology group, Genentech as a US-based biotechnology subsidiary, Sandoz as a generics and biosimilars specialist. Ferring Pharmaceuticals, Ipsen Pharma, and Ascendis Pharma A/S occupy positions within the rare disease and sustained-release formulation segments.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novo Nordisk A/S |
| Eli Lilly and Company |
| Merck KGaA |
| Genentech Inc. |
| Sandoz International GmbH |
| Ferring Pharmaceuticals |
| Ipsen Pharma |
| Ascendis Pharma A/S |
| Others |
Value Chain & Pricing Dynamics
Massachusetts' concentration of mammalian cell culture capacity anchors global recombinant hormone supply, with Boston-Cambridge biomanufacturing clusters translating upstream fermentation economics into downstream pricing power for long-acting somatropin formulations. This geographic concentration of expression system expertise creates asymmetric leverage against pharmacy benefit managers negotiating bundled adherence contracts.
Pricing Analysis
Long-term offtake agreements between specialty pharmacy networks and integrated delivery systems dominate procurement, with three-tier pricing structure across premium, standard, and economy levels separating device-integrated long-acting formulations from conventional daily injection regimens. Price differentiation hinges on FDA fast-track certification status and bundled digital adherence platform inclusion. Cost compression in biosimilar tiers is intensifying because E. coli expression system manufacturers exploit patent cliff openings. Medicaid programs exhibit highest price sensitivity; private insurers in Germany and Japan demonstrate lowest elasticity due to comprehensive reimbursement carve-outs for rare pediatric endocrine disorders.
Supply Chain Analysis
Upstream recombinant protein feedstock draws from United States, Denmark, and Switzerland, where mammalian cell culture media and E. coli expression plasmids concentrate in GMP-certified facilities. Cold-chain logistics for temperature-sensitive biologics rest on specialized courier networks and validated packaging systems. Single-source vulnerability permeates the long-acting formulation segment where proprietary PEGylation technologies anchor patent-protected supply. Distribution runs through vertically integrated specialty pharmacy channels that bundle medication with remote monitoring services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected autoinjector platforms are restructuring this market toward platform economics where adherence data interoperability determines payer contract viability, with Bluetooth-enabled dose tracking creating ecosystem lock-in comparable to diabetes care device networks.
For Market Incumbents: Pre-empt biosimilar erosion by accelerating backward integration into mammalian cell culture capacity in Baden-Württemberg and Massachusetts, while embedding FDA-cleared algorithms into delivery devices before EMA AI Act transparency requirements harden competitive barriers against retrofitted platforms. For New Entrants and Emerging Players: Establish a beachhead in transdermal microneedle development for pediatric needle phobia applications, targeting Japan's PMDA fast-track pathway and German university hospital pilot programs as regulatory validation accelerators before scaling into United States Medicaid channels. For Investors and Strategic Acquirers: Long-term, this sits as a data-monetization play because adherence platform operators will capture recurring service revenue streams detached from molecule patent lifecycles; target device-integrated delivery specialists with European CE marking and United States 510(k) clearance. Monitor FDA real-world evidence guidance convergence with EMA standards as the inflection signal for label expansion value accretion.| Strategic Initiative | Industry Significance |
|---|---|
| Long-Acting Formulation Development | Weekly injection protocols reduce patient burden and unlock value-based contracts with United States Medicaid programs. |
| Connected Device Integration | Bluetooth-enabled autoinjectors capture adherence data required for EMA post-market surveillance and payer negotiations. |
| Biosimilar Manufacturing Scale-Up | E. coli expression systems in India and South Korea exploit patent cliffs with CDSCO and MFDS pathway advantages. |
| Transdermal Microneedle Advancement | Dissolvable microarray technology addresses pediatric compliance gaps in Japan's PMDA-designated rare disorder pathway. |
| Digital Adherence Platform Launch | Mobile application integration enables outcome-based reimbursement with German statutory health insurance funds. |
Study Parameters
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings, with drug development executives, regulatory affairs leads at EMA and FDA, formulary directors at United States pharmacy benefit managers, and pediatric endocrinologists providing operational context. FDA approval databases, EMA assessment reports, ClinicalTrials.gov pediatric study records, and national reimbursement formularies supplied secondary validation. Bottom-up patient cohort modeling and top-down market sizing triangulated volume estimates across expression systems and delivery modalities.
Calibration against historical growth velocity data and regulatory approval timelines shaped the analytical framework across the analysis window, with segmentation dimensions encompassing product type, therapy area, delivery mode, and end-user channel. CAGRs derived from fitted growth curves applied to diagnosed prevalence projections and treatment penetration assumptions. Forecast inputs incorporated PMDA fast-track designation rates and EU AI Act implementation timelines for connected devices.
Stress conditions across biosimilar interchangeability rulings, cold-chain logistics disruptions, and pediatric endocrinologist workforce constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory convergence and reimbursement stability. Quarterly review of FDA real-world evidence guidance updates and EMA post-market surveillance enforcement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Paediatric Neuropsychiatric Disorders Treatment Market
Pediatrics
Pediatric Palliative Care Drugs Market
Pediatrics
Pediatric Brain Tumor Market
Pediatrics
Paediatric Influenza Treatment Market
Pediatrics
Pediatric HIV Infection Treatment Market
Pediatrics
Pediatric Tube Feeding Market
Pediatrics
Pediatric MRI Market
Pediatrics
OTC Pediatric Healthcare Market
Pediatrics
Pediatric Perfusion Products Market
Pediatrics
Autism Service Platform Market
Pediatrics
Pediatric Asthma Treatment Market
Pediatrics
Global Pediatric Clinical Trials Market
Pediatrics
Pediatric Home Healthcare Market
Pediatrics
Pediatric Catheter Market
Pediatrics
Pediatric Obesity Management Market
Pediatrics
Pediatric Dental Market