
 Colorectal Cancer Market | 2026-2036
Colorectal Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Colorectal Cancer Market Analysis
The EU Green Deal's pharmaceutical sustainability criteria is repositioning oncology supply chains toward lower-carbon manufacturing and circular API sourcing. Roche leverages its diagnostic-therapeutic integration to anchor biomarker-driven patient selection across European markets. Merck & Co. competes through its checkpoint inhibitor portfolio, while Bristol-Myers Squibb differentiates via dual immunotherapy combinations in metastatic settings.
Colorectal cancer encompasses malignancies of the colon and rectum arising from epithelial cell mutations, diagnosed through fecal immunochemical testing, colonoscopy with tissue biopsy, and circulating tumor DNA analysis, then treated via surgical resection, systemic therapy, or localized radiation depending on staging and molecular profiling. The disease ranks among the most prevalent gastrointestinal malignancies globally, driving sustained investment in early detection infrastructure and precision medicine platforms. Targeted therapy segments command premium positioning where RAS wild-type status enables EGFR inhibitor eligibility, while immunotherapy segments expand fastest in microsatellite instability-high populations. Genomic testing segments underpin treatment selection across all stages, with endoscopic techniques dominating diagnosis and surveillance workflows.
The FDA, EMA, and WHO collectively shape market access through accelerated approval frameworks, centralized oncology assessments, and essential medicines designation protocols that determine reimbursement and distribution priorities. These regulators enforce evolving standards for companion diagnostic co-development, real-world evidence submission, and post-market safety monitoring that constrain launch timelines but validate clinical utility. Stakeholders must monitor emerging biosimilar competition in established antibody franchises and prepare for competitive displacement as novel agent classes advance through registrational trials.
Market Dynamics
Immunotherapy protocols are compressing chemotherapy's historical dominance while companion diagnostic co-development requirements reshape product-launch economics across oncology portfolios.
Growth Catalysts
- Microsatellite instability-high (MSI-H) testing expansion:Hospital systems in the United States are embedding circulating tumor DNA analysis into standard-of-care pathways. This molecular stratification unlocks checkpoint inhibitor eligibility for previously chemotherapy-dependent patient cohorts.
- EU Green Deal pharmaceutical sustainability criteria:Lower-carbon manufacturing mandates are accelerating circular API sourcing investments across European supply chains. Oncology manufacturers repositioning early capture procurement preference from consolidated hospital networks.
- FDA accelerated approval pathway:Breakthrough therapy designation compresses registrational timelines from Phase I to commercial launch. Developers prioritize biomarker-enriched trials that satisfy the pathway's efficacy threshold requirements.
Market Restraints
- Companion diagnostic co-development costs:Parallel validation of therapeutic and diagnostic platforms doubles clinical trial expenditure. Smaller developers lack capital to synchronize PMA submissions with drug approval timelines.
- API supply concentration in Asian manufacturing clusters:Single-source dependencies for monoclonal antibody intermediates create vulnerability to geopolitical trade friction. European formulators face extended lead times during regional supply disruptions.
- RAS mutation testing limitations:Approximately half of metastatic colorectal cancer patients carry mutations that exclude EGFR inhibitor eligibility. This molecular ceiling constrains addressable population for targeted therapy segments.
Strategic Opportunities
- Neoadjuvant immunotherapy in locally advanced disease:Pathological complete response rates in early-phase trials suggest surgical resection may become avoidable for select patients. Academic medical centers in Germany and the Netherlands are establishing prospective registries to validate organ-preservation protocols.
- Real-world evidence generation infrastructure:Post-market safety monitoring requirements under EMA's DARWIN EU network create demand for outcomes analytics platforms. Data-capture partnerships between hospital systems and developers unlock label expansion pathways.
- Artificial intelligence-enabled polyp detection:Computer-vision algorithms integrated into colonoscopy workflows improve adenoma detection rates. Japanese endoscopy manufacturers are deploying these systems through subscription-based service models in Southeast Asian screening programs.
Industry Challenges
- Biomarker assay standardization gaps:Discordant RAS testing results between local pathology laboratories and central reference labs delay treatment initiation. Proficiency testing harmonization remains incomplete across European member states.
- Cold-chain logistics complexity for cellular therapies:Patient-specific manufacturing requires temperature-controlled transport from apheresis center to GMP facility and return. Infrastructure gaps in secondary cities extend vein-to-vein timelines beyond clinical tolerance windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colorectal Cancer Market |
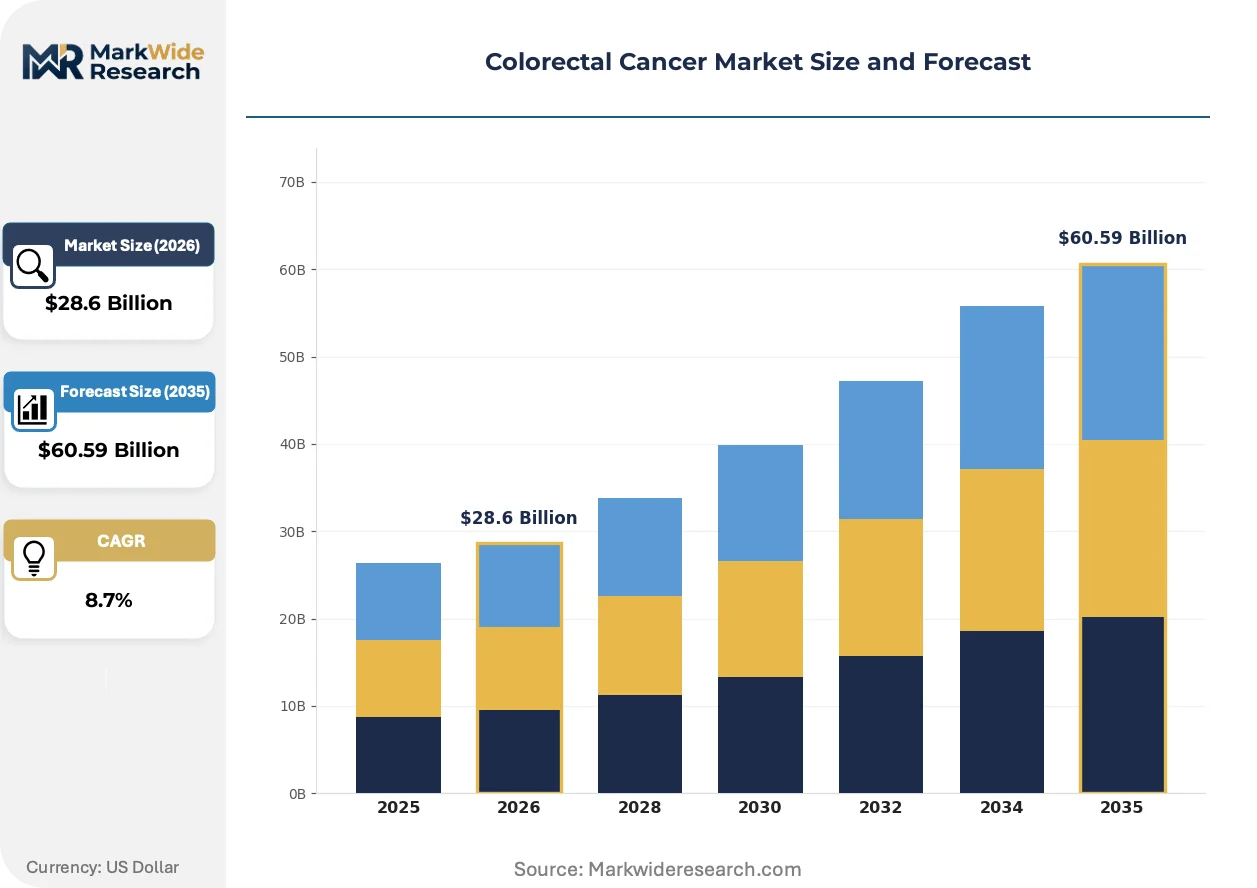
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Chemotherapy, Radiation Therapy, Targeted Therapy Technology: Immunotherapy, Genomic Testing, Endoscopic Techniques, Surgical Techniques End User: Hospitals, Cancer Research Centers, Clinics, Home Care Treatment Stage: Early Stage, Locally Advanced, Metastatic, Palliative Care |
| Companies Covered | Roche, Merck & Co., Bayer, Amgen, Bristol-Myers Squibb, Pfizer, Eli Lilly and Company, Sanofi, Takeda Pharmaceutical Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colorectal Cancer Market Emerging Trajectories
Liquid biopsy platforms are fragmenting tissue-dependent diagnostic workflows while regulatory frameworks co-evolve to validate circulating biomarker clinical utility across treatment settings.
Next-generation sequencing panels analyzing circulating tumor DNA are decentralizing molecular profiling from centralized reference laboratories to hospital-based pathology departments. Community oncology practices in the United States are adopting point-of-care platforms that return actionable mutation results within 72 hours. This geographic diffusion of testing capability is compressing time-to-treatment initiation and enabling real-time resistance monitoring without repeat tissue biopsy.
The FDA's Project Confirm initiative mandates confirmatory trial completion for accelerated approvals within specified timelines. Oncology developers face portfolio prioritization pressure as the agency exercises withdrawal authority for therapies failing to verify clinical benefit. Metastatic colorectal cancer indications with surrogate endpoints are experiencing heightened scrutiny relative to earlier-stage disease settings where overall survival remains the primary endpoint.
Integrated cancer networks are consolidating pharmaceutical procurement decisions under centralized pharmacy and therapeutics committees. Community-based oncologists in the United States now access targeted therapies through formulary contracts negotiated at the health-system level rather than individual practice purchasing. This buyer concentration is visible most acutely in the southeastern United States where hospital system mergers have reduced independent oncology practice density by half over the past decade.
Colorectal Cancer Market Segmentation
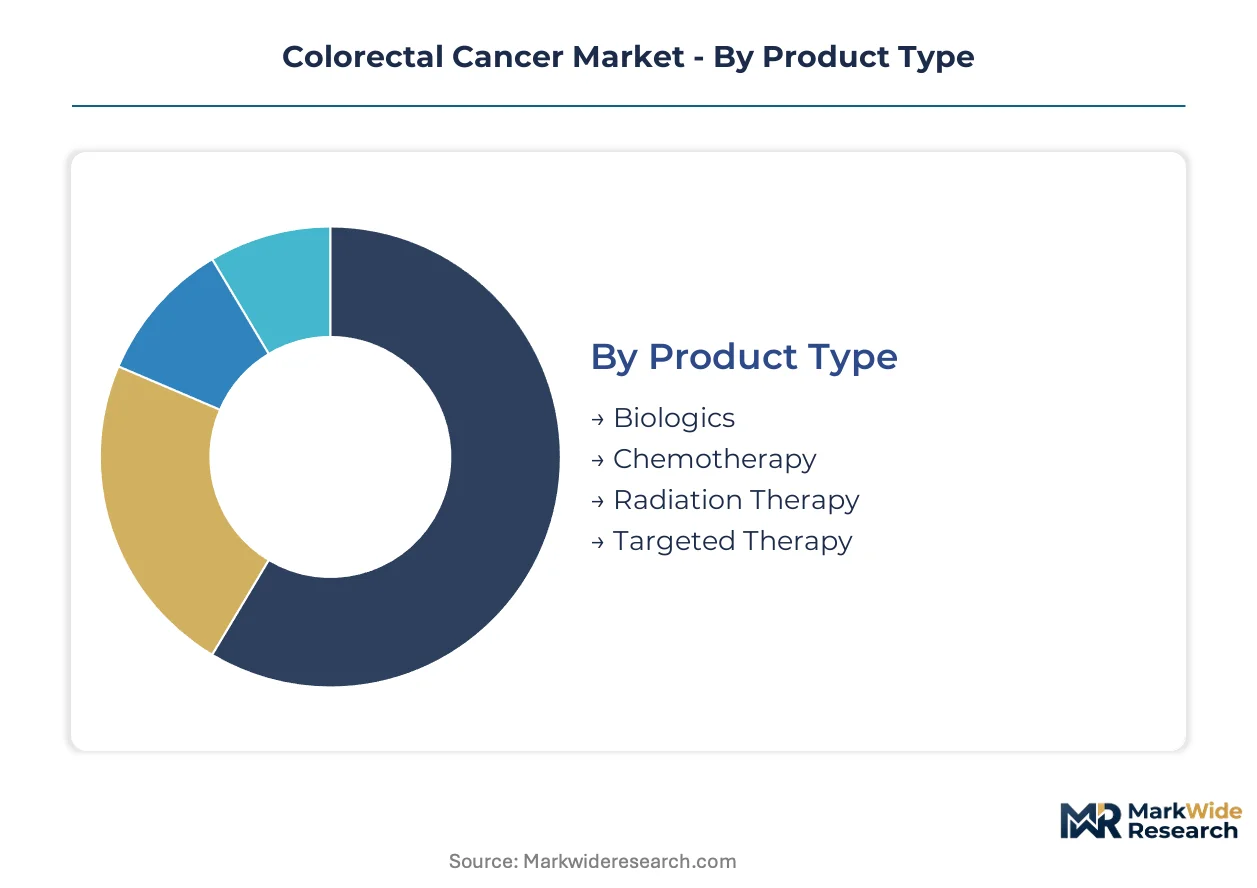
Colorectal cancer market segmentation reflects divergent clinical workflows across curative and palliative settings. Product portfolios must align with molecular stratification requirements and site-of-care economics that vary dramatically between academic medical centers and community oncology practices.
Product Type:
Standalone biologics and chemotherapy agents operate through established infusion protocols, while targeted therapies demand embedded diagnostic integration for patient eligibility determination.
- Biologics:Monoclonal antibodies and fusion proteins manufactured through mammalian cell culture systems achieve high specificity against tumor antigens. Demand concentrates in United States integrated cancer networks where centralized pharmacy committees negotiate formulary placement based on biomarker prevalence data.
- Targeted Therapy:Small-molecule inhibitors and antibody-drug conjugates require concurrent RAS wild-type testing to establish EGFR inhibitor eligibility. Academic medical centers in Germany and the Netherlands are expanding neoadjuvant protocols that embed these agents into organ-preservation strategies.
- Chemotherapy:Cytotoxic regimens remain foundational for microsatellite-stable populations ineligible for immunotherapy.
- Radiation Therapy:External beam and brachytherapy approaches address localized disease and symptomatic metastases.
Volume placements concentrate in chemotherapy; the faster expansion belongs to targeted therapy.
Technology:
Cost tiers separate capital-intensive surgical robotics from consumable-driven genomic testing platforms that scale through reagent recurring revenue.
- Immunotherapy:Checkpoint inhibitors targeting PD-1/PD-L1 pathways demonstrate durable responses in MSI-H populations. United States hospital systems are embedding circulating tumor DNA screening into standard pathways to identify eligible patients.
- Genomic Testing:Next-generation sequencing panels analyze tissue and liquid biopsy specimens to guide treatment selection. Community oncology practices in the southeastern United States are adopting point-of-care platforms that return results within 72 hours.
- Endoscopic Techniques:Optical and molecular imaging modalities enable polyp detection and resection during screening colonoscopy.
- Surgical Techniques:Minimally invasive and robotic-assisted approaches reduce recovery time for resectable disease.
Revenue concentration sits with immunotherapy; genomic testing is gaining share fastest as companion diagnostic mandates expand.
End User:
Customer type determines purchasing authority structure, with consolidated health systems exercising formulary control over independent practice decision-making.
- Hospitals:Inpatient and outpatient oncology departments manage complex infusion protocols and adverse event monitoring. Integrated delivery networks in the United States have reduced independent oncology practice density by half over the past decade.
- Cancer Research Centers:Academic medical centers conduct investigator-initiated trials and early-phase studies. EMA's DARWIN EU network creates demand for real-world evidence partnerships between these institutions and developers.
- Clinics:Community-based practices deliver standard-of-care chemotherapy and supportive services.
- Home Care:Oral targeted agents and supportive medications enable treatment outside facility settings.
Procurement volume aggregates at hospitals; cancer research centers are climbing the fastest as trial enrollment becomes a competitive differentiator.
Treatment Stage:
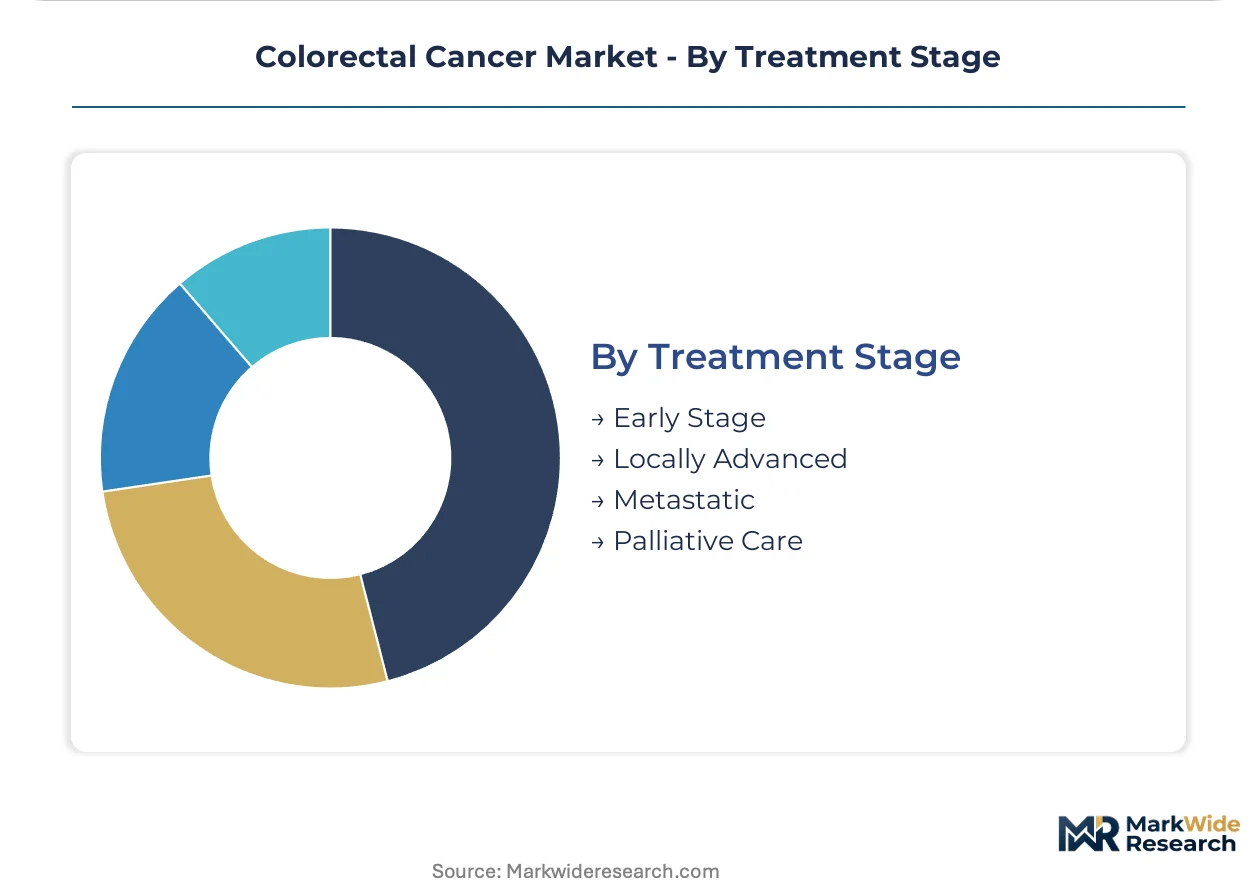
Maturity curves diverge sharply, with metastatic settings offering established reimbursement pathways versus early-stage neoadjuvant protocols still requiring evidence generation.
- Metastatic:Systemic therapy dominates clinical practice with established biomarker-driven sequencing algorithms. FDA's Project Confirm initiative is heightening scrutiny of surrogate endpoints in this setting relative to overall survival requirements.
- Locally Advanced:Neoadjuvant immunotherapy trials are evaluating pathological complete response as a surrogate for surgical avoidance. Prospective registries in Germany and the Netherlands are validating organ-preservation endpoints.
- Early Stage:Surgical resection remains curative standard with adjuvant chemotherapy for high-risk features.
- Palliative Care:Symptom management and quality-of-life interventions address end-stage disease burden.
Patient volume concentrates in metastatic disease; locally advanced protocols are expanding most quickly as immunotherapy displaces historical chemotherapy sequences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for oncology biologics and API intermediates clusters in Switzerland, Germany, and Japan, while clinical trial enrollment and therapeutic consumption tilts heavily toward the United States and major European markets.
United States
Integrated cancer networks in the southeastern states have consolidated purchasing authority under centralized pharmacy committees, compressing formulary negotiations for checkpoint inhibitors. The FDA's accelerated approval pathway and Project Confirm initiative compress development timelines while enforcing confirmatory trial completion. Academic medical centers in Boston and Houston anchor neoadjuvant immunotherapy trials evaluating organ-preservation endpoints.
Germany
University hospitals in Heidelberg and Munich are establishing prospective registries for neoadjuvant immunotherapy protocols in locally advanced disease. The EMA's centralized oncology assessments and DARWIN EU real-world evidence network create structured post-market surveillance requirements. The country's pharmaceutical supply chains are repositioning under EU Green Deal sustainability mandates for lower-carbon manufacturing.
Switzerland
Basel and Zurich host concentrated biologics manufacturing infrastructure serving European and global distribution networks. Swissmedic maintains alignment with EMA centralized procedures while offering parallel national assessment pathways. The country's diagnostic-therapeutic integration capabilities anchor biomarker-driven patient selection platforms across continental markets.
Japan
PMDA's Sakigake designation system accelerates priority review for breakthrough oncology therapies, compressing lag behind FDA approvals. Tokyo and Osaka metropolitan areas concentrate endoscopic technique innovation and AI-enabled polyp detection deployment. METI funding programs support circulating tumor DNA platform adoption in community hospital networks.
United Kingdom
The NHS England Cancer Drugs Fund provides conditional reimbursement pathways for immunotherapy agents pending real-world evidence generation. London and Manchester academic centers participate in EMA DARWIN EU data partnerships for post-market outcomes analytics. NICE technology appraisals enforce cost-effectiveness thresholds that constrain premium pricing for targeted therapies.
Colorectal Cancer Market Vendor Landscape
The competitive structure tilts toward integrated diagnostic-therapeutic platforms over standalone pharmaceutical portfolios. Large-cap developers with companion diagnostic capabilities command procurement preference from consolidated hospital networks, while mid-tier biotechnology firms compete through biomarker-enriched trial designs. Three archetypes dominate: vertically integrated health science conglomerates, precision medicine specialists with diagnostic assets, and immuno-oncology-focused biotechnology developers. Competitive intensity centers on M&A activity targeting genomic testing platforms and strategic partnerships for real-world evidence generation infrastructure.
Within the integrated health science tier, Roche and Bayer exemplify diagnostic-therapeutic convergence strategies that anchor European and North American market access. Bristol-Myers Squibb occupies a position among dual immunotherapy combination developers targeting metastatic settings. These three companies represent distinct competitive vectors—diagnostic platform control, small-molecule targeted therapy heritage, and checkpoint inhibitor portfolio breadth—that shape procurement negotiations across United States integrated delivery networks and European hospital systems.
| Leading Market Players |
|---|
| Roche |
| Merck & Co. |
| Bayer |
| Amgen |
| Bristol-Myers Squibb |
| Pfizer |
| Eli Lilly and Company |
| Sanofi |
| Takeda Pharmaceutical Company Limited |
| Others |
Supply Flow & Price Mechanics
Monoclonal antibody intermediate costs cascade through oncology supply chains, with mammalian cell culture media and purification resins anchoring premium tier pricing for checkpoint inhibitors while biosimilar competition compresses margins in mature antibody franchises.
Pricing Analysis
Value-based pricing anchors oncology therapeutics to pathological complete response rates and progression-free survival endpoints in neoadjuvant settings. Three-tier pricing structure across premium, standard, and economy levels separates branded checkpoint inhibitors from biosimilar antibodies and generic chemotherapy backbones. Cost compression in the biosimilar tier is intensifying because European hospital systems are consolidating formulary negotiations under centralized pharmacy committees. Community oncology practices in the southeastern United States exhibit highest price sensitivity, while academic medical centers in Germany and the Netherlands prioritize clinical efficacy data over acquisition cost.
Supply Chain Analysis
Dual-sourcing requirements for monoclonal antibody intermediates are now standard in European formulator contracts, with buyers mandating multi-supplier qualification to mitigate single-source vulnerability. Manufacturing gravity draws from Switzerland, Germany, and Ireland for biologics fill-finish operations, while active pharmaceutical ingredient production rests on Chinese and Indian fermentation capacity. Cold-chain logistics for patient-specific cellular therapies create tariff exposure at customs clearance points. Distribution runs through integrated cancer network warehouses in the United States and hospital system central pharmacies in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The colorectal cancer market operates as a cost-of-compliance story where FDA's Project Confirm initiative and EMA's DARWIN EU network erect regulatory moats that only well-capitalized developers can surmount.
For Market Incumbents: Anchor diagnostic-therapeutic integration capabilities through companion diagnostic platform control, defending against biosimilar displacement by embedding biomarker testing into standard-of-care pathways. Expand real-world evidence generation infrastructure partnerships with academic medical centers in Germany and the Netherlands to satisfy post-market surveillance requirements. Capacity addition in Swiss biologics manufacturing clusters secures supply security for checkpoint inhibitor portfolios.
For New Entrants and Emerging Players: Community oncology practices in the southeastern United States represent an underserved buyer archetype, with independent practice density halved over the past decade creating white-space for point-of-care genomic testing platforms. Neoadjuvant immunotherapy protocols in locally advanced disease offer the most penetrable segment, with organ-preservation endpoints still requiring validation. A go-to-market angle through subscription-based AI-enabled polyp detection services bypasses formulary committee gatekeeping.
For Investors and Strategic Acquirers: FDA withdrawal authority exercised against accelerated approvals without confirmatory trial completion is the leading indicator that portfolio prioritization discipline will separate viable oncology developers from stranded assets. Long-term viability across the analysis window favors precision medicine specialists with captive diagnostic assets over standalone pharmaceutical portfolios. Acquisition targets should display biomarker-enriched trial capabilities and EMA DARWIN EU data partnerships. Deviation in confirmatory trial success rates would shift the outlook materially.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA's accelerated approval pathway mandates parallel PMA submissions with therapeutic filings. |
| Real-World Evidence Partnership | EMA's DARWIN EU network creates structured demand for hospital system data-capture collaborations. |
| Neoadjuvant Protocol Expansion | Academic medical centers in Germany and the Netherlands are establishing prospective organ-preservation registries. |
| AI-Enabled Polyp Detection Deployment | Japanese endoscopy manufacturers are deploying computer-vision algorithms through subscription models in Southeast Asia. |
| Circular API Sourcing Investment | EU Green Deal pharmaceutical sustainability criteria are repositioning European supply chains toward lower-carbon manufacturing. |
Methodological Framework
Multi-period observation of checkpoint inhibitor formulary placements, companion diagnostic adoption curves, and neoadjuvant trial enrollment rates anchored the trend analysis, supplemented by interviews with oncology drug development executives, regulatory affairs leads at EMA and FDA, hospital formulary directors, and payer access specialists. Secondary validation drew from FDA accelerated approval filings, EMA centralized oncology assessments, ClinicalTrials.gov protocol registries, and hospital procurement databases. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation converged on segment estimates.
Segment-weighting approaches applied differential growth assumptions across immunotherapy, targeted therapy, and genomic testing categories, with treatment stage and molecular stratification dimensions modeled throughout the forecast period. CAGRs were derived from epidemiological incidence projections, biomarker prevalence data, and therapy sequencing algorithm evolution. Forecast inputs included circulating tumor DNA platform adoption curves and health system consolidation patterns in the United States.
Revisions become necessary when confirmatory trial failures trigger FDA withdrawal actions, biosimilar launches accelerate faster than modeled, or geopolitical trade friction disrupts monoclonal antibody intermediate supply. Deviation in EMA DARWIN EU real-world evidence requirements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
America Cancer Immunotherapy Market
Oncology
Testicular Cancer Treatment Market
Oncology
Ustekinumab Market
Oncology
Ovarian Cancer Market
Oncology
Kinase Inhibitors for Cancer Treatment Market
Oncology
Tumor Embolization Market
Oncology
Low-Grade Central Osteosarcoma Treatment Market
Oncology
Thyroid Cancer Market
Oncology
Esophageal Cancer Drugs Market
Oncology
Cancer/Tumor Profiling Market
Oncology
Pancreatic Cancer Market
Oncology
Cancer API Market
Oncology
BRCA Mutation-Positive Ovarian Cancer Market
Oncology
Gynecological Cancer Drugs Market
Oncology
Lung Cancer Treatment Market
Oncology
Gynecological Cancers Market