
 Oncology Imaging Software Market | 2026-2036
Oncology Imaging Software Market Size, Share, and Industry Trends Forecast 2026-2036
Oncology Imaging Software Market Analytics
Enterprise-grade diagnostic accuracy is rotating toward the center of procurement criteria in oncology imaging software. Siemens Healthineers AG leverages deep integration with PET-CT hardware to anchor its position in molecular imaging workflows. GE HealthCare sustains R&D intensity across AI-based reconstruction algorithms. Philips Healthcare dominates the European hospital channel through vendor-neutral archive compatibility.
Oncology imaging software comprises specialized digital platforms that process, reconstruct, and analyze medical images from CT, MRI, PET, and SPECT modalities using DICOM protocols and quantitative biomarker extraction algorithms. These systems enable tumor detection, treatment planning, and response monitoring by converting raw scanner data into clinician-actionable visualizations and structured reports. Cloud-based deployment is capturing the fastest expansion as health systems seek elastic compute for AI inference workloads. Hospitals command the largest installed base and drive multi-year enterprise contracts. Molecular imaging software carries premium pricing due to radiotracer quantification complexity and regulatory validation requirements.
The FDA's software-as-a-medical-device framework shapes product development timelines and clinical evidence requirements for algorithm developers. EMA's Medical Device Regulation and Japan's PMDA software guidance create parallel compliance obligations for vendors seeking multi-regional distribution. Stakeholders must monitor evolving pre-certification pathways and interoperability mandates that determine market access velocity.
Market Dynamics
AI inference workloads are compressing deployment timelines across oncology imaging software as hospitals demand real-time tumor segmentation and radiomic analysis at the point of care.
Growth Catalysts
- FDA software-as-a-medical-device framework:The FDA's streamlined pre-certification pathway accelerates algorithm clearance timelines for machine learning-based diagnostic tools. Developers submit locked algorithm versions with predetermined change control plans.
- Cloud-native architecture:Health systems in the United States, Germany, and Japan are migrating PET-CT and MRI reconstruction pipelines to elastic cloud infrastructure. This shift enables on-demand scaling for computationally intensive AI inference workloads.
- Radiology department consolidation:Hospital networks are centralizing molecular imaging operations into enterprise-wide platforms. Integrated workflows reduce manual handoffs between acquisition, quantification, and structured reporting.
Market Restraints
- Radiotracer supply volatility:Molybdenum-99 production concentrates at aging nuclear reactors in the Netherlands, Canada, and South Africa. Isotope shortages disrupt PET scan scheduling and depress utilization rates for molecular imaging software.
- Interoperability fragmentation:DICOM-RT and FHIR implementation gaps between vendor archives and AI platforms force expensive custom integration work. Health systems absorb these costs or delay procurement decisions.
- Specialized workforce scarcity:Dual-trained radiologists with nuclear medicine and informatics expertise remain concentrated at academic medical centers. Community hospitals face recruitment bottlenecks that limit software utilization depth.
Strategic Opportunities
- Community oncology networks:Independent cancer centers in the United States lack capital budgets for on-premise infrastructure. Subscription-based cloud deployment models penetrate this underpenetrated segment with lower upfront commitment.
- EU AI Act compliance services:The EU AI Act's high-risk system classification for diagnostic algorithms creates demand for conformity assessment tooling. Vendors bundling compliance documentation with software licenses capture pricing premiums.
- Theranostics integration:Lutetium-177 and actinium-225 radioligand therapies require companion imaging for patient selection and dosimetry. Software platforms quantifying tumor-specific uptake before and after treatment capture workflow centrality.
Industry Challenges
- Ground-truth data curation:AI training requires pathologically confirmed lesion annotations across diverse scanner protocols. Academic-industry data partnerships face institutional review board complexity and intellectual property negotiation friction.
- Legacy PACS integration:Decade-old picture archiving systems at mid-tier hospitals lack API access for AI orchestration. Retrofit middleware projects consume implementation resources and delay go-live dates.
- Algorithm update governance:Continuous learning models require version control and performance monitoring post-deployment. Clinical engineering teams lack standardized playbooks for managing software updates in regulated environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oncology Imaging Software Market |
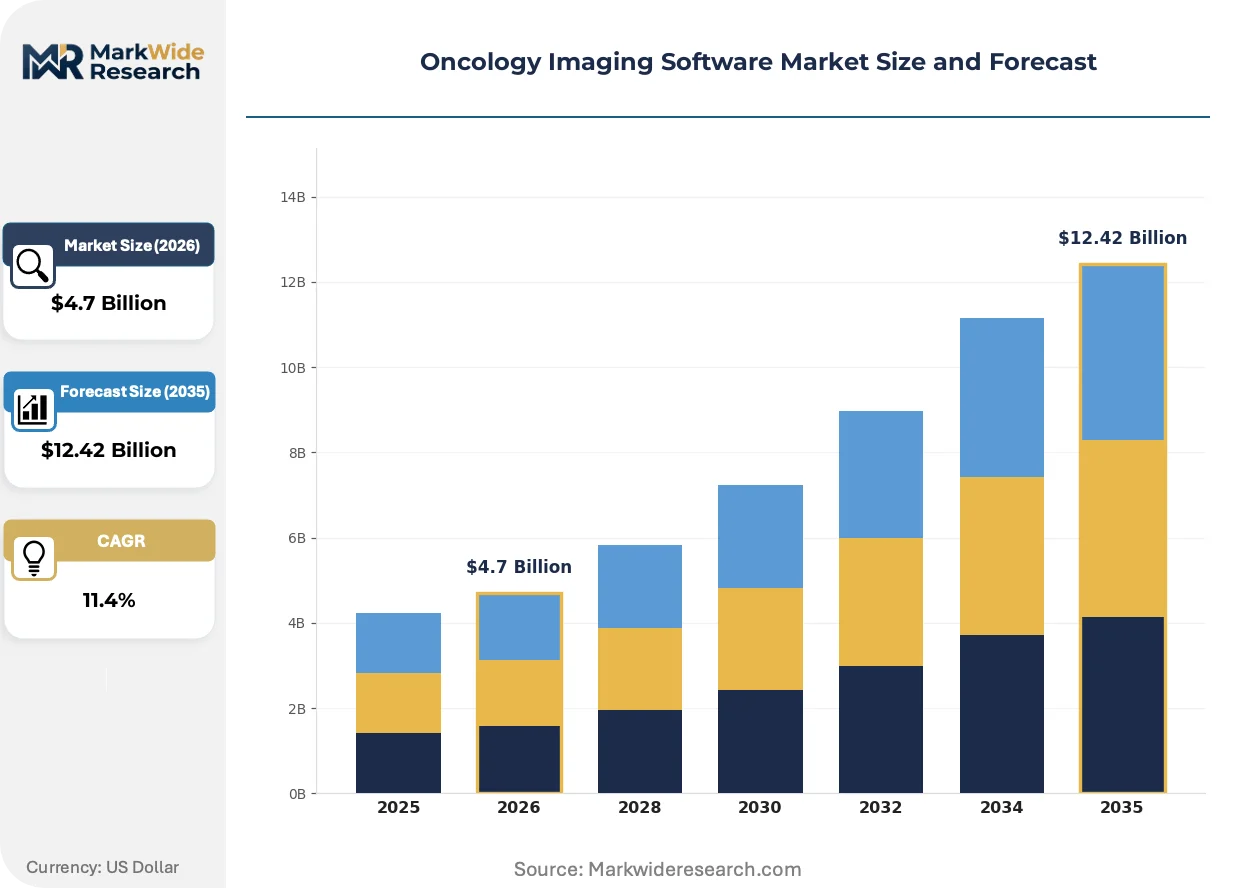
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.42 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Imaging, Molecular Imaging, CT Scanners, MRI Software End User: Hospitals, Diagnostic Centers, Research Institutes, Oncology Clinics Deployment: Cloud-based, On-premises, Hybrid Solutions, Web-based Technology: AI-based, Image Processing, Visualization Tools, DICOM Standards |
| Companies Covered | Siemens Healthineers AG, GE HealthCare, Philips Healthcare, Canon Medical Systems Corporation, Mirada Medical Ltd., Varian Medical Systems, Elekta, RaySearch Laboratories, Agfa Gevaert HealthCare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oncology Imaging Software Market Evolving Landscape
Computational architectures and regulatory frameworks are converging to reshape how oncology imaging software is developed, validated, and deployed across clinical settings.
Edge computing hardware is miniaturizing AI inference capabilities for deployment directly within CT and MRI scanner consoles. Siemens Healthineers and GE HealthCare are integrating GPU-accelerated reconstruction chips into next-generation modality platforms. This architecture is miniaturizing the latency between raw data acquisition and clinician-facing results, compressing the traditional server-room dependency for real-time decision support.
EMA's Medical Device Regulation imposes stricter clinical evidence requirements for software with diagnostic functions. Manufacturers must demonstrate analytical and clinical validation across intended use populations. European hospital procurement committees now require MDR certification documentation before contract execution, extending sales cycles but elevating competitive barriers for compliant vendors.
Hospital purchasing committees are unbundling software licenses from hardware maintenance agreements. Finance departments scrutinize total cost of ownership across five-year horizons rather than accepting bundled capital equipment proposals. This behavioral shift is most pronounced in German university hospitals, where procurement teams negotiate enterprise software contracts separately from modality service agreements.
Oncology Imaging Software Market Segmentation
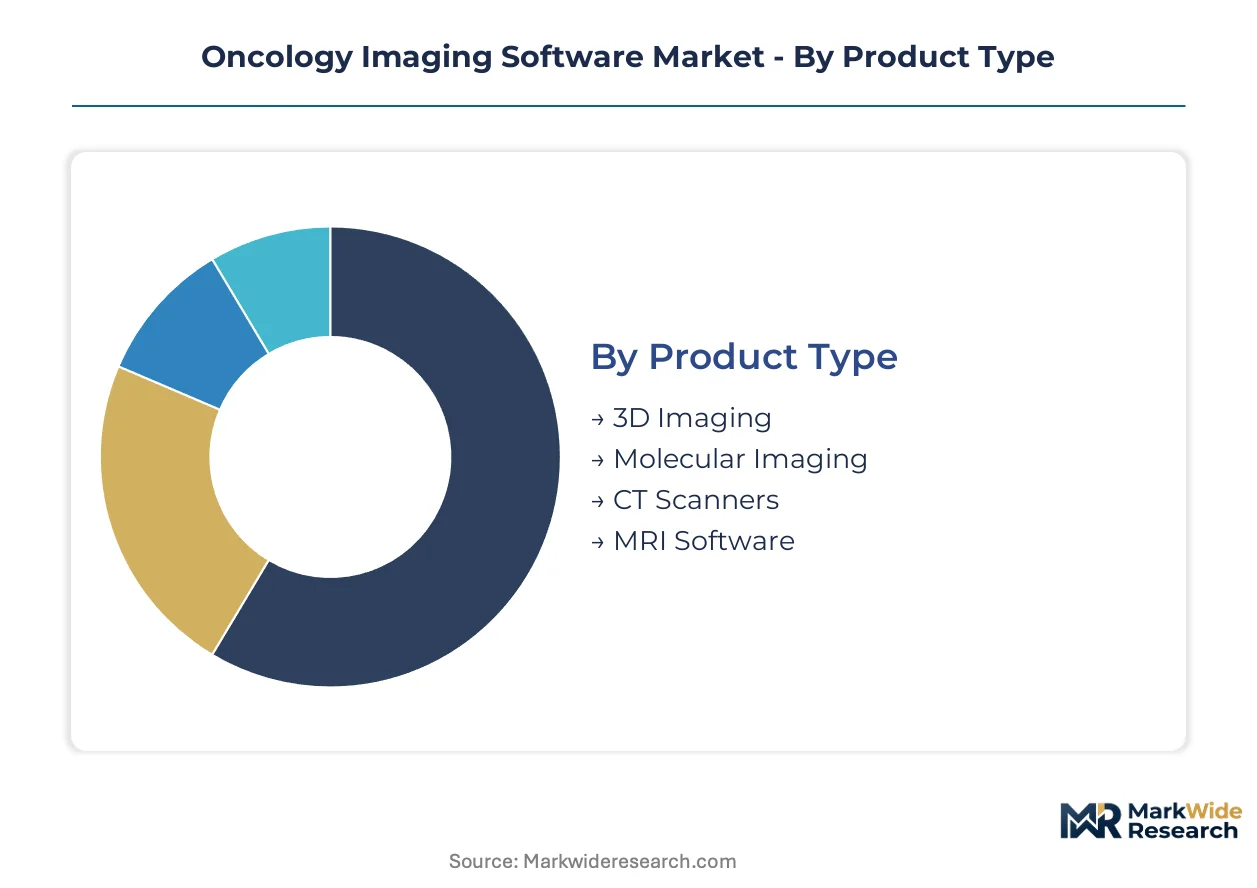
Oncology imaging software vendors configure product portfolios around four intersecting dimensions that determine pricing power and contract duration. Procurement committees evaluate segments differently based on capital intensity, regulatory burden, and integration complexity with existing PACS infrastructure.
Product Type:
Margin pools concentrate in molecular imaging software due to radiotracer quantification complexity and companion diagnostics bundling opportunities.
- Molecular Imaging:PET-CT and SPECT reconstruction platforms process radiotracer kinetics with specialized quantification algorithms. Demand clusters at academic medical centers in the United States and Germany pursuing theranostics workflows for lutetium-177 therapy monitoring.
- 3D Imaging:Volumetric rendering engines reconstruct multiplanar visualizations for surgical planning and tumor board presentations. Community oncology networks in Japan prioritize these tools for multidisciplinary case review standardization.
- CT Scanners:Acquisition software manages helical protocols and dose modulation for oncology protocols.
- MRI Software:Sequence optimization platforms enable functional and diffusion-weighted imaging for treatment response assessment.
The dominant share belongs to Molecular Imaging, while 3D Imaging is closing the gap fastest.
End User:
Contract value and renewal rates diverge sharply across purchaser sophistication and patient throughput scale.
- Hospitals:Enterprise health systems negotiate multi-year agreements spanning departmental workflows from radiology through radiation oncology. These contracts bundle AI inference licenses with vendor-neutral archive connectivity, concentrating procurement authority at integrated delivery networks in the United States.
- Diagnostic Centers:Independent imaging facilities prioritize turnkey solutions with minimal IT overhead. Subscription pricing models penetrate this segment where capital constraints limit on-premise infrastructure investment.
- Research Institutes:Clinical trial imaging cores require specialized quantification tools and regulatory-grade audit trails.
- Oncology Clinics:Community cancer centers seek workflow integration with electronic health records and practice management systems.
Hospitals command the largest installed base, though Diagnostic Centers are expanding most quickly through cloud-native deployment models.
Deployment:
Architecture choices determine total cost of ownership calculations and cybersecurity exposure profiles for health system CIOs.
- Cloud-based:Elastic compute infrastructure scales AI inference workloads without server-room capital expenditure. German university hospitals lead migration to these platforms, driven by GDPR-compliant European data residency requirements and on-demand reconstruction capacity.
- Hybrid Solutions:Edge-to-cloud pipelines process sensitive data locally while archiving to remote infrastructure. This architecture satisfies Japanese PMDA data localization mandates while enabling centralized algorithm updates.
- On-premises:Traditional server-room deployment maintains full data sovereignty for conservative health systems.
- Web-based:Browser-accessible platforms reduce client-side software maintenance for distributed clinic networks.
Cloud-based deployment holds the dominant position, with Hybrid Solutions gaining share fastest among multi-national hospital operators.
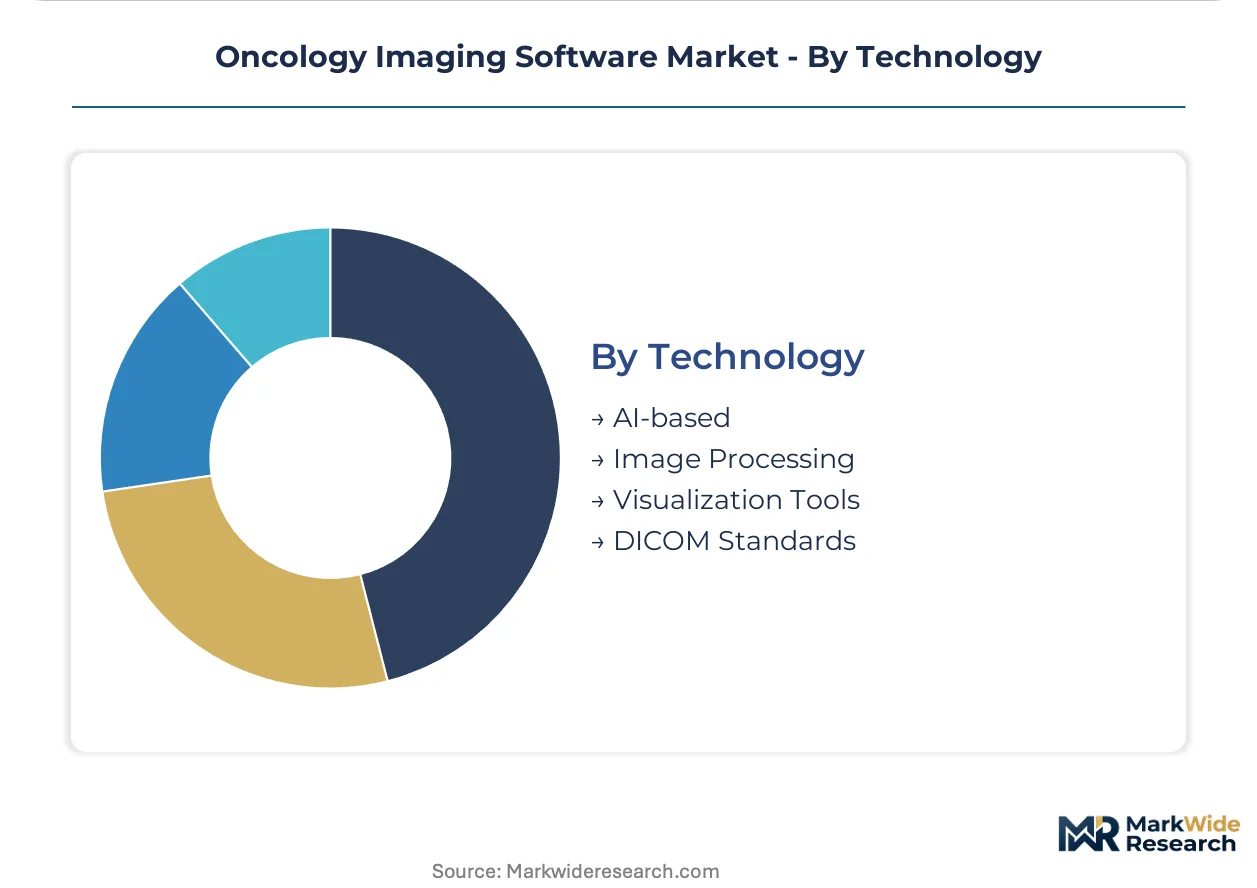
Technology:
Intellectual property differentiation and FDA clearance pathways segment competitive positioning among algorithm developers.
- AI-based:Machine learning models automate lesion detection, segmentation, and radiomic feature extraction. Siemens Healthineers and GE HealthCare anchor their portfolios here, leveraging locked algorithm submissions under FDA software-as-a-medical-device pre-certification pathways.
- Image Processing:Computational reconstruction engines convert raw scanner data into diagnostic-quality images. These platforms face commoditization pressure as hardware vendors bundle proprietary reconstruction chips directly into modality consoles.
- Visualization Tools:Advanced rendering interfaces enable real-time manipulation of multi-dimensional datasets.
- DICOM Standards:Interoperability middleware ensures seamless data exchange across vendor archives and AI platforms.
AI-based technology captures the steepest expansion trajectory, while Image Processing maintains volume leadership through hardware bundling relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. German university hospitals absorb premium molecular imaging licenses, while Indian diagnostic chains prioritize subscription elasticity. Japanese providers demand hybrid architectures balancing data sovereignty with cloud scalability.
United States
Integrated delivery networks consolidate procurement authority across multi-hospital systems. The FDA's software-as-a-medical-device pre-certification pathway accelerates clearance timelines for machine learning algorithms. Boston's Longwood Medical Area anchors theranostics research, with Massachusetts General Hospital and Dana-Farber Cancer Institute driving lutetium-177 therapy monitoring workflows.
Germany
University hospitals negotiate enterprise software contracts separately from modality service agreements, unbundling traditional vendor bundles. The EU AI Act's high-risk system classification imposes conformity assessment requirements on diagnostic algorithm developers. Heidelberg's University Hospital and the German Cancer Research Center concentrate molecular imaging expertise, advancing radiotracer quantification protocols.
Japan
Radiology departments prioritize integrated oncology workflows spanning acquisition through structured reporting. PMDA software guidance creates parallel compliance obligations for vendors seeking multi-regional distribution. Tokyo's University of Tokyo Hospital and National Cancer Center Japan anchor PET-CT standardization efforts, with Osaka's Kansai region emerging as a secondary cluster for MRI-based treatment response assessment.
United Kingdom
NHS England's imaging networks centralize procurement across regional diagnostic hubs, favoring vendor-neutral archive compatibility. MHRA recognition of FDA-cleared algorithms streamlines market access for US-developed platforms. London's Royal Marsden Hospital and University College London Hospitals anchor molecular imaging research, while Manchester's Christie Hospital drives radiotherapy planning software integration.
India
Independent diagnostic chains expand PET-CT capacity in tier-2 cities, constrained by capital budgets for on-premise infrastructure. CDSCO medical device regulations impose registration requirements on imported software platforms. Mumbai's Tata Memorial Centre and Delhi's All India Institute of Medical Sciences concentrate nuclear medicine expertise, with Bengaluru's healthcare technology corridor emerging as a hub for cloud-native deployment pilots.
Oncology Imaging Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the oncology imaging software market. Hardware-integrated vendors anchor premium pricing through PET-CT and MRI console bundling, while pure-play software specialists penetrate price-sensitive segments via subscription models. Three archetypes dominate: diversified medical technology conglomerates with imaging hardware heritage, specialized radiation oncology software developers, and emerging AI-native algorithm vendors. M&A activity concentrates on AI talent acquisition, while strategic partnerships between software vendors and radiopharmaceutical producers reshape theranostics workflows.
Among diversified medical technology conglomerates, Siemens Healthineers AG and GE HealthCare exemplify the hardware-anchored archetype, leveraging deep modality integration to secure multi-year enterprise contracts. Philips Healthcare occupies a position bridging European hospital channel dominance with vendor-neutral archive compatibility. These three entities represent the consolidation endpoint where diagnostic hardware heritage translates into software pricing power.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| GE HealthCare |
| Philips Healthcare |
| Canon Medical Systems Corporation |
| Mirada Medical Ltd. |
| Varian Medical Systems |
| Elekta |
| RaySearch Laboratories |
| Agfa Gevaert HealthCare |
| Others |
Value Network & Pricing Analysis
FDA software-as-a-medical-device pre-certification tiers gate both vendor qualification and price stratification simultaneously, as locked algorithm submissions with predetermined change control plans command premium licensing multiples over uncertified platforms while excluding non-compliant developers from hospital procurement shortlists entirely.
Pricing Analysis
After-sales service contracts and extended algorithm update subscriptions drive lifetime value capture across enterprise deployments. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared AI inference platforms from CE-marked European variants and uncertified research-grade tools. Price differentiation rests on validation depth and radiotracer quantification complexity. Cost compression in the research-grade tier is intensifying because cloud-native entrants bundle basic reconstruction tools at marginal cost. Community oncology networks exhibit highest price sensitivity; academic medical centers absorb premium molecular imaging licenses with minimal procurement friction.
Supply Chain Analysis
Molybdenum-99 reactor aging in the Netherlands, Canada, and South Africa creates a chokepoint that constrains PET radiotracer availability and depresses molecular imaging software utilization rates during isotope shortage events. GPU accelerator chips draw from Taiwan and South Korea fabrication facilities, while specialized DICOM middleware development concentrates in the United States and Germany. Single-source vulnerability runs through the Mo-99 production base, where reactor maintenance schedules disrupt downstream scan scheduling unpredictably. Distribution runs through radiopharmaceutical producer partnerships that bundle tracer logistics with software licensing for theranostics workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-source AI frameworks and cloud-native reconstruction tools threaten incumbent pricing power by commoditizing basic image processing, forcing established vendors to defend substitution through regulatory moats and hardware integration depth.
For Market Incumbents: Shield enterprise installed bases by embedding FDA-cleared algorithms directly into PET-CT and MRI console firmware, creating switching costs that cloud-native challengers cannot replicate without hardware partnerships. Deepen backward integration into GPU-accelerated reconstruction chip design to capture margin pools currently flowing to semiconductor suppliers. Prioritize theranostics workflow centrality as the defensive lever, quantifying radioligand therapy response to anchor software indispensability. For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks offer the most penetrable certification pathway for AI-native segmentation tools targeting community oncology networks in India and tier-2 United States markets. White-space concentration appears in subscription-based cloud deployment for independent diagnostic centers lacking capital budgets for on-premise infrastructure. Pursue channel partnerships with radiopharmaceutical distributors to bundle software access with tracer logistics, bypassing direct hospital procurement committee friction. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates spinning non-core radiation oncology software divisions to focus on hardware-centric theranostics platforms. Long-term viability favors vendors with locked algorithm regulatory submissions and established GPO contract relationships over pure-play AI developers facing continuous revalidation burdens. Monitor FDA pre-certification pathway expansion velocity as the inflection signal distinguishing sustainable competitive position from regulatory arbitrage.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Pathway Expansion | Accelerates locked algorithm clearance timelines for Siemens Healthineers and GE HealthCare machine learning submissions. |
| Cloud-Native Deployment Migration | Enables elastic AI inference scaling for German university hospitals pursuing GDPR-compliant European data residency. |
| Theranostics Workflow Integration | Captures software centrality for lutetium-177 therapy monitoring at Heidelberg University Hospital and Dana-Farber. |
| Radiopharmaceutical Producer Partnership | Bundles tracer logistics with molecular imaging licenses to penetrate community oncology network price sensitivity. |
| GPU-Accelerated Edge Computing | Miniaturizes reconstruction latency within scanner consoles for real-time tumor segmentation at point of care. |
Research Methodology
A standing panel of radiology department chairs, hospital procurement committee members, biomedical informatics officers, and GPO contracts managers provided ongoing calibration against primary fieldwork with molecular imaging software vendors and AI algorithm developers. Secondary validation drew from FDA 510(k) and De Novo submission databases, EMA Medical Device Regulation certification records, hospital procurement databases, and GPO contract disclosure filings. Bottom-up segmentation modeling triangulated against top-down market sizing from modality installation base estimates.
Consistency checks validated volume and value outputs against external benchmarks including hyperscaler healthcare cloud capex disclosures, radiopharmaceutical production volume reports, and academic medical center IT budget surveys. The analytical framework modeled deployment architecture, end-user sophistication tier, technology validation status, and regional regulatory cluster across the projection horizon. CAGRs derived from algorithm adoption curve analysis and hardware replacement cycle timing, with theranostics workflow penetration and AI inference workload intensity serving as oncology-specific demand drivers.
Decision-makers should treat outputs as directional under assumptions of sustained FDA pre-certification pathway stability and Mo-99 reactor operational continuity; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as EU AI Act high-risk system classification enforcement and Japanese PMDA software guidance evolution reshape compliance cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Glioma Diagnosis and Treatment Market
Oncology Diagnostics
Europe Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Personalized Medicine Biomarkers Market
Oncology Diagnostics
US Colorectal Cancer Screening Market
Oncology Diagnostics
Oncology Based Molecular Diagnostics Market
Oncology Diagnostics
Cancer Diagnostics Market
Oncology Diagnostics
Middle East and Africa Colorectal Cancer Diagnostics Market
Oncology Diagnostics
Bladder Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Liver Cancer Diagnostics Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Therapy Market
Oncology Diagnostics
Europe Liver Cancer Diagnostics Market
Oncology Diagnostics
Global Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Market
Oncology Diagnostics
Adrenal Cortical Carcinoma Diagnosis and Treatment Market
Oncology Diagnostics
Europe Kidney Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Asia-Pacific Lung Cancer Screening Software Market