
 Baking Mixes Market | 2026-2036
Baking Mixes Market Size, Share, and Industry Trends Forecast 2026-2036
Baking Mixes Market Analysis
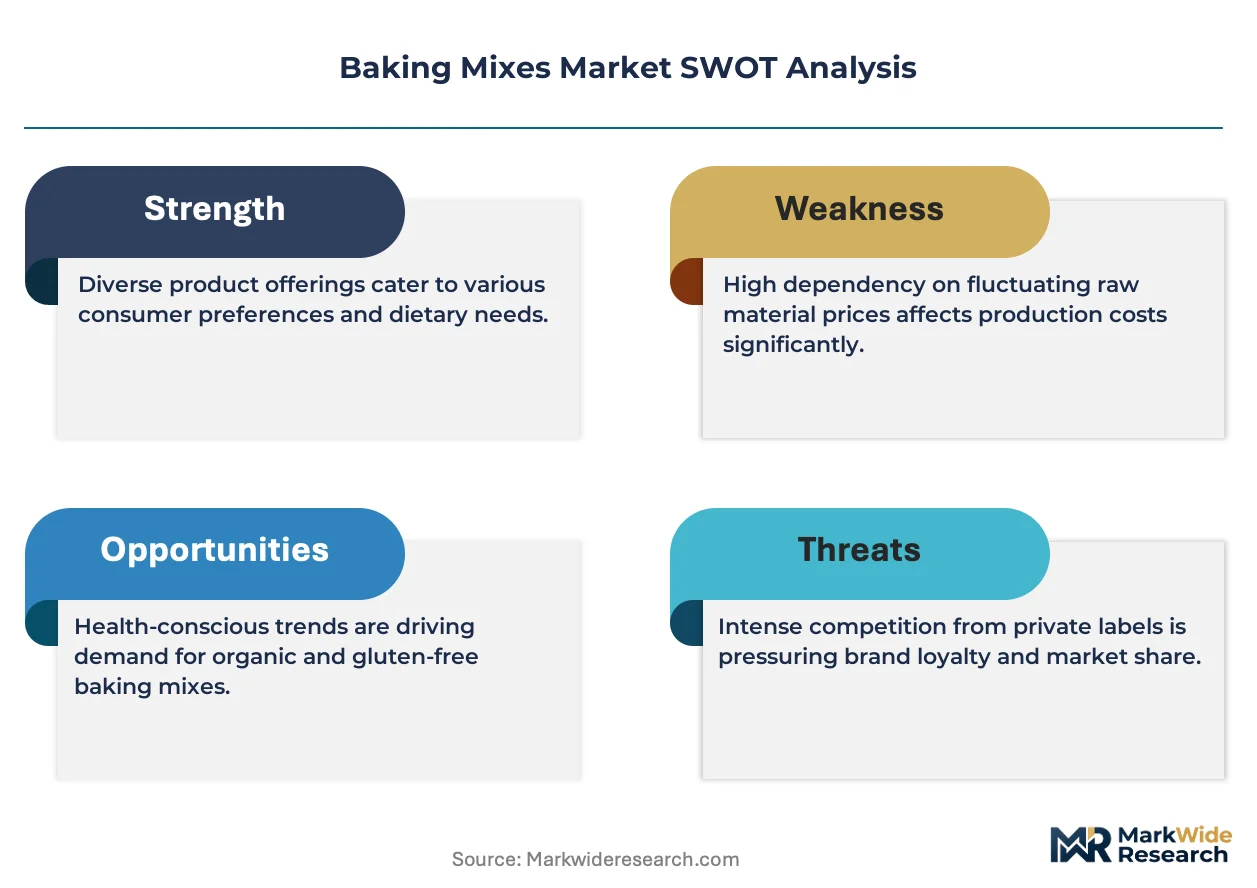
Modular pouch-and-sachet bundling is rebalancing how households and foodservice buyers evaluate portion control and storage economics. General Mills leverages its retail shelf dominance to anchor multi-pack configurations across conventional and gluten-free lines. Nestlé competes through R&D intensity in fortified formulations, while Puratos specializes in professional-grade bread mixes that sustain bakery channel loyalty.
Baking mixes comprise pre-measured dry ingredient blends—typically combining refined or whole-grain flour, chemical leavening agents, sugar, and emulsifiers—that require only the addition of wet ingredients before thermal processing. These formulations standardize texture, rise, and crumb structure while eliminating scaling errors in both home and commercial environments. Cake mix remains the mature revenue base, though gluten-free and organic ingredient-source segments capture expanding margin pools as certification costs filter out smaller private-label competitors. Pouch packaging is displacing rigid boxes in e-commerce channels, where shipping weight and breakage risk dictate format selection.
FDA labeling requirements and USDA organic certification shape permissible health claims and ingredient disclosure depth in the United States, while EU REACH and EFSA frameworks govern emulsifier and additive approvals for imported European formulations. Stakeholders must monitor divergence between FDA and EFSA acceptable daily intake thresholds for aluminum-based leavening agents, as regulatory misalignment threatens unified global formulations and forces regional recipe adaptation.
Market Dynamics
Clean-label ingredient mandates from EFSA and the EU Green Deal are forcing reformulation across conventional baking mixes, compressing acceptable additive lists while home bakers simultaneously demand performance parity with legacy formulations.
Growth Catalysts
- EFSA Additive Re-evaluation:Stricter emulsifier safety thresholds in Europe are accelerating clean-label innovation cycles, pulling premium-positioned mixes ahead of commodity competition.
- Home Baking Persistence:Post-pandemic household retention of baking habits sustains baseline demand for convenience-oriented pouch formats in the United States.
- Aluminum Phosphate Substitution:Sodium acid pyrophosphate and monocalcium phosphate blends are replacing aluminum-based leavening systems to meet evolving FDA acceptable daily intake guidance.
Market Restraints
- Wheat Flour Volatility:Black Sea supply disruptions and drought cycles in the North American plains create input cost instability that erodes margin predictability for standard cake and bread mix lines.
- Organic Certification Burden:USDA organic compliance costs and three-year transition requirements for farmland lock smaller private-label competitors out of expanding premium shelf space.
- Aluminum Leavening Divergence:Misaligned FDA and EFSA acceptable daily intake thresholds for aluminum-based agents fragment global formulation strategies, preventing unified SKU deployment.
Strategic Opportunities
- Fortified Functional Mixes:Protein-enriched and fiber-fortified formulations targeting metabolic health-conscious households capture margin pools unavailable to conventional products.
- Direct-to-Consumer Subscription:Curated monthly baking kits bypass retail slotting fees while building recurring revenue relationships with enthusiast home bakers.
- Gluten-Free Certification Gap:Dedicated allergen-free production facilities remain underbuilt relative to diagnosed celiac and non-celiac gluten sensitivity prevalence in the United States.
Industry Challenges
- Reformulation Expertise Scarcity:Clean-label emulsifier and stabilizer substitution demands food science capabilities concentrated among a limited supplier base, extending development timelines.
- Legacy Equipment Retrofit Costs:Transitioning rigid box lines to flexible pouch formats for e-commerce optimization requires capital outlays that strain mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baking Mixes Market |
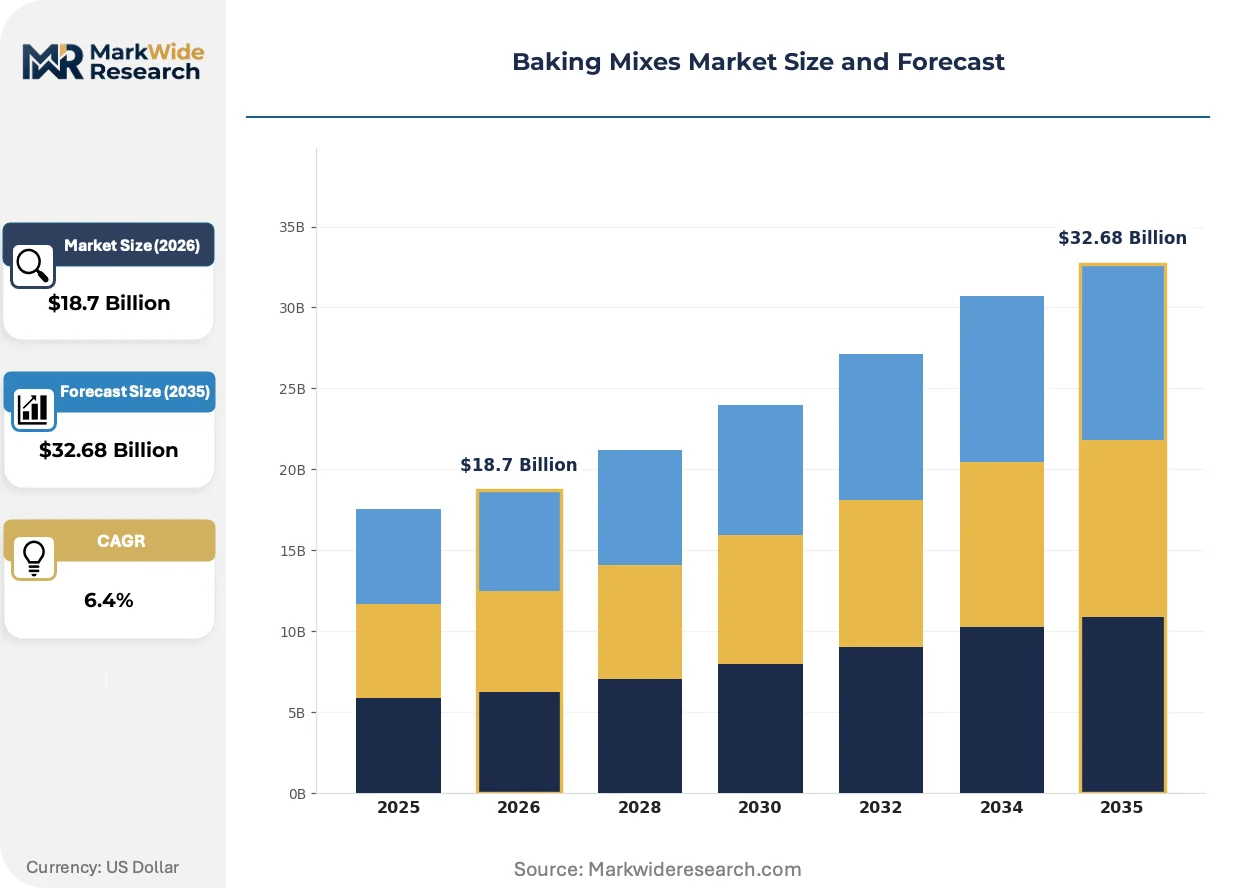
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cake Mix, Bread Mix, Pancake Mix, Muffin Mix End User: Households, Bakeries, Restaurants, Cafes Ingredient Source: Organic, Gluten-Free, Conventional, Fortified Packaging Type: Bags, Boxes, Pouches, Sachets |
| Companies Covered | Puratos, Conagra Brands, General Mills, Nestlé, Continental Mills, Cargill, The Kraft Heinz Company, Bakels Group, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baking Mixes Market Emerging Trajectories
Active fermentation biotechnology and precision dosing hardware are converging to transform how home bakers interact with dry mix formats, shifting value capture from commodity ingredients toward controlled process outcomes.
Sourdough starter-integrated dry mixes incorporating freeze-dried wild yeast cultures and precise hydration calculators are electrifying the artisan home baking segment. Enthusiast bakers in Germany and the United States adopt these formats at accelerating velocity. The technology is compressing the skill barrier between novice and professional crumb structure outcomes.
EU REACH Annex XIV authorization requirements for synthetic emulsifiers are tightening permissible substance lists across imported and domestically produced formulations. Industrial consequence includes accelerated R&D spending on plant-derived alternatives such as lecithin and acacia gum systems. Premium organic and clean-label segments in France and the Netherlands are responding fastest, with reformulated SKUs reaching shelf stability ahead of compliance deadlines.
Subscription-based replenishment models with predictive algorithmic curation based on seasonal baking patterns and dietary preference profiles are disrupting conventional grocery channel dependence. Direct-to-consumer platforms in the United States and United Kingdom are capturing household pantry share previously held by supermarket private labels. This behavioral shift concentrates most visibly among millennial and Gen-Z households with established smart home ecosystem integration.
Baking Mixes Market Segmentation
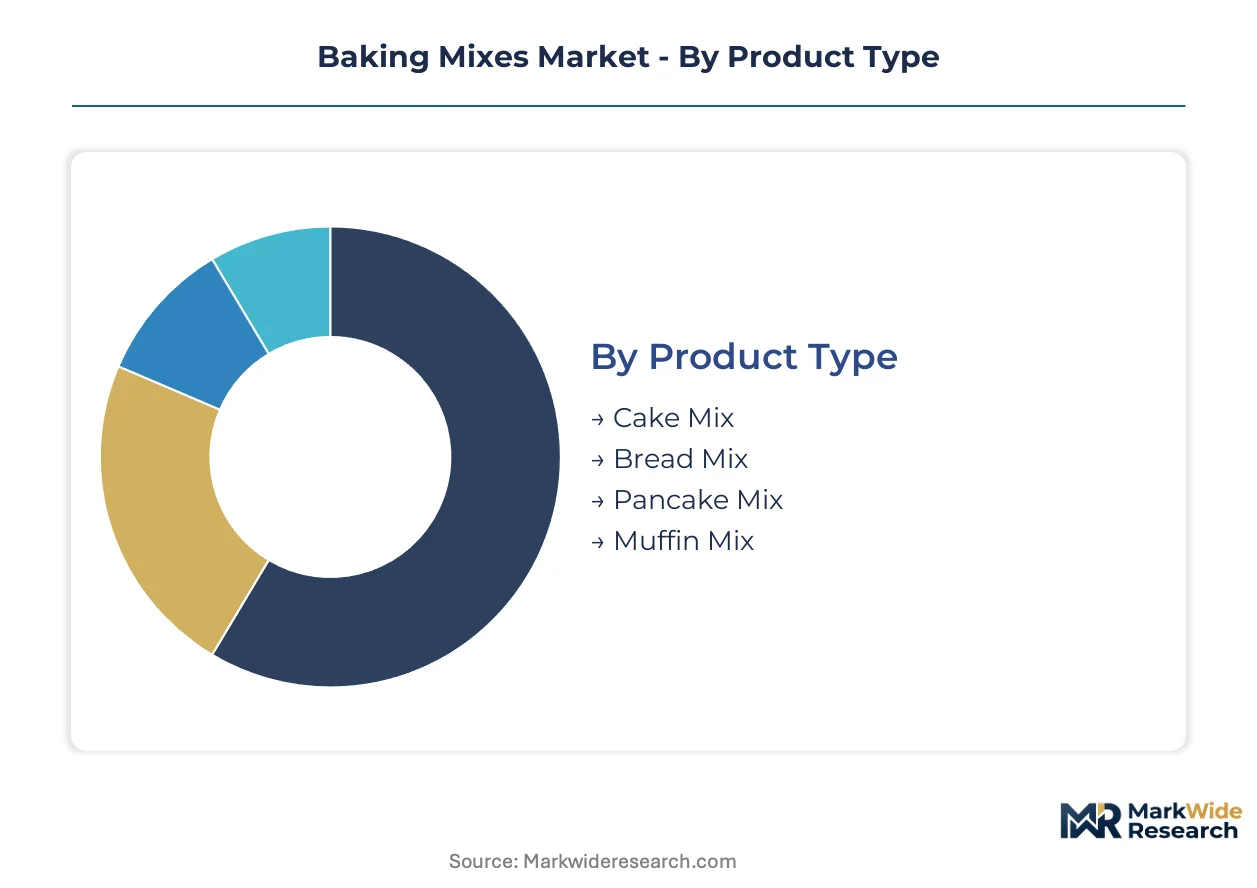
Segmentation in baking mixes separates volume-driven commodity formats from margin-rich specialty certifications. Purchase decisions hinge on certification credibility for allergen-sensitive buyers and portion economics for foodservice operators.
Product Type:
Households prioritize convenience-to-versatility ratios when selecting mix categories, while foodservice buyers emphasize batch consistency and labor reduction.
- Cake Mix:Standardized blends of refined wheat flour, granulated sugar, and aluminum-free leavening agents deliver predictable crumb structure across home ovens. Demand concentrates in the United States where retail slotting fees favor established multi-pack formats and private-label competition remains suppressed by certification barriers.
- Bread Mix:Yeast-activated formulations requiring longer fermentation windows attract enthusiast bakers seeking artisan outcomes without scaling complexity. German households and independent bakeries in France drive adoption of sourdough-integrated dry mixes incorporating freeze-dried wild cultures.
- Pancake Mix:Quick-cooking batters with optimized hydration ratios dominate North American breakfast occasions.
- Muffin Mix:Portion-controlled pouches target single-serve baking occasions in UK and Australian households.
Cake Mix leads on scale; Bread Mix leads on momentum.
End User:
Volume concentration and margin structure diverge sharply across buyer categories, with procurement authority residing in distinct organizational functions.
- Households:Individual consumers purchasing through retail or direct-to-consumer channels prioritize storage efficiency and dietary alignment. United States millennial and Gen-Z households with smart home ecosystem integration show steepest subscription adoption for algorithmically curated monthly kits.
- Bakeries:Commercial operators demand bulk formats with consistent hydration behavior across varying ambient conditions. Artisan bakeries in Belgium and the Netherlands source professional-grade mixes from specialized suppliers to maintain crust texture standards under EU clean-label mandates.
- Restaurants:Kitchens optimize for speed-scratch applications where mixes reduce prep labor without eliminating house-made positioning.
- Cafes:Smaller footprints favor sachet formats with minimal inventory carrying costs.
Households dominate absolute volume; Bakeries command premium pricing power.
Ingredient Source:
Certification depth and supply chain traceability now function as primary purchase filters, particularly for households managing diagnosed conditions.
- Organic:USDA-certified or EU organic seal-bearing formulations require three-year farmland transition and segregated processing infrastructure. United States private-label competitors face lockout from premium shelf space due to compliance cost burdens that favor scaled manufacturers with captive organic supply chains.
- Gluten-Free:Dedicated allergen-free production facilities producing blends from rice, tapioca, and sorghum flours address celiac and non-celiac gluten sensitivity prevalence. United States demand outpaces current manufacturing capacity, creating supply constraints for certified retail and foodservice formats.
- Conventional:Standard refined wheat formulations maintain cost advantages in price-sensitive retail tiers.
- Fortified:Protein-enriched and fiber-supplemented mixes target metabolic health positioning in UK and German markets.
Conventional formats retain volume leadership; Gluten-Free claims the steepest expansion trajectory.
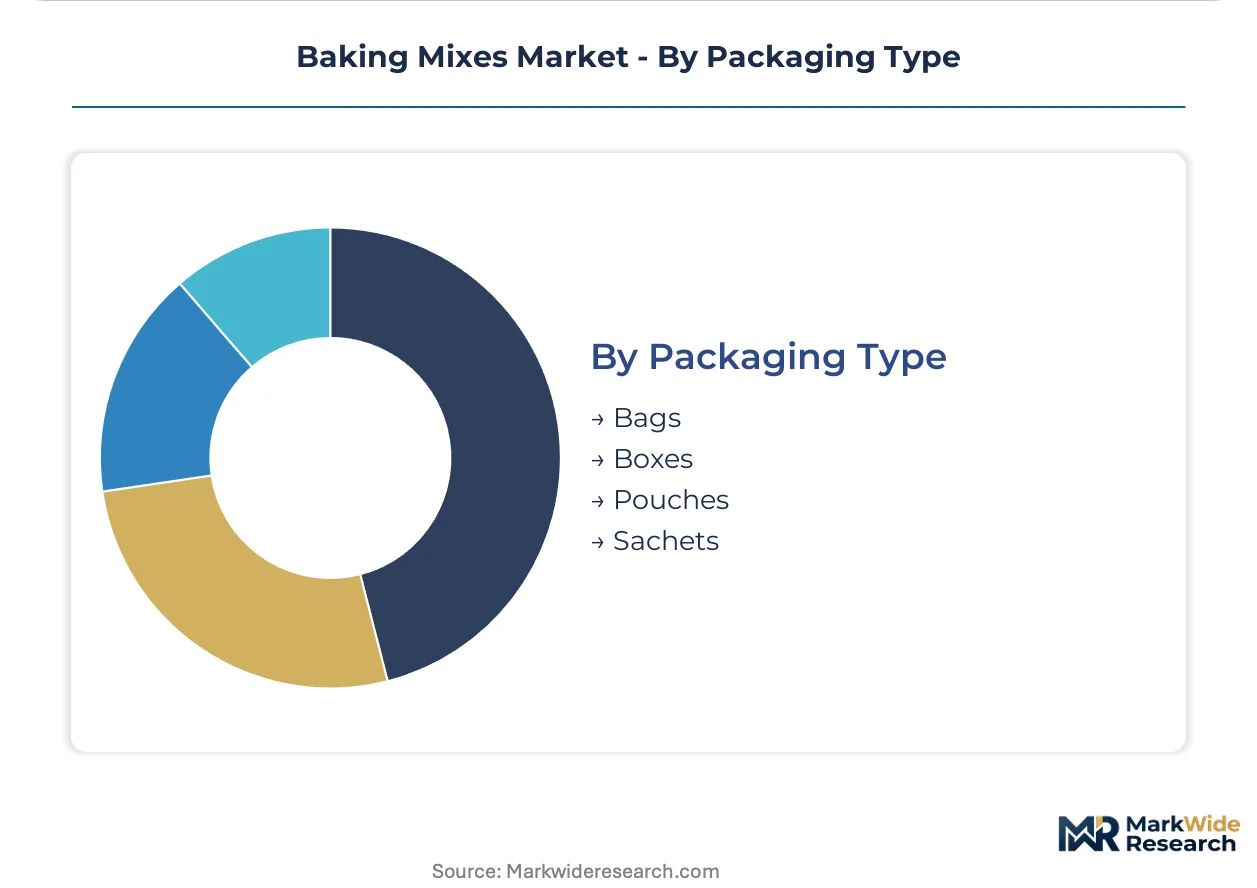
Packaging Type:
Shipping economics and breakage risk have rebalanced format preferences away from legacy rigid containers toward flexible alternatives.
- Pouches:Multi-layer flexible films with resealable closures minimize shipping weight and dimensional charges in e-commerce fulfillment. United States direct-to-consumer platforms and third-party logistics providers specify pouch formats to reduce damage rates and optimize last-mile container density.
- Bags:Larger-capacity flexible formats serve foodservice bulk purchasing with reduced per-unit material costs versus rigid alternatives.
- Boxes:Legacy cardboard cartons retain retail presence where shelf visibility and stacking stability matter.
- Sachets:Single-serve portions enable precise portion control for trial formats and institutional foodservice.
Pouches are gaining share fastest; Boxes defend established retail positions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baking mixes first achieved industrial scale in the United States during the 1930s depression era, establishing the commercial template that would later diffuse to European and Asian markets. Regional development now tracks divergent regulatory timelines and home baking cultural persistence.
United States
Millennial and Gen-Z households sustain subscription adoption for algorithmically curated monthly baking kits. FDA labeling requirements and USDA organic certification shape permissible health claims and ingredient disclosure depth. Chicago and Minneapolis anchor corporate headquarters for diversified food manufacturers with captive retail shelf space.
Germany
Enthusiast bakers drive adoption of sourdough-integrated dry mixes incorporating freeze-dried wild yeast cultures. EFSA clean-label mandates and EU REACH Annex XIV authorization requirements for synthetic emulsifiers accelerate reformulation cycles. Bavaria and Baden-Württemberg host specialized suppliers serving artisan bakery channels.
France
Artisan bakeries demand professional-grade mixes maintaining crust texture standards under tightening additive restrictions. EU Green Deal implementation compresses acceptable substance lists while preserving performance parity. Paris and Lyon concentrate reformulation R&D responding fastest to compliance deadlines.
United Kingdom
Portion-controlled pouches target single-serve baking occasions in metropolitan households with constrained kitchen storage. Fortified protein-enriched and fiber-supplemented mixes capture metabolic health positioning. London and the Southeast corridor dominate direct-to-consumer platform development.
Japan
Precision-oriented home bakers adopt controlled fermentation biotechnology formats with hydration calculators. METI standards and consumer preference for compact packaging favor sachet and pouch configurations. Tokyo and Osaka metropolitan areas concentrate specialty retail distribution for premium imported formulations.
Baking Mixes Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification depth and supply chain control. The market exhibits tiered concentration where scaled manufacturers with captive organic supply chains lock out smaller private-label competitors from premium shelf space. Three archetypes dominate: diversified conglomerates with retail anchoring power, specialized bakery-channel suppliers with professional-grade formulations, and ingredient-systems providers with backward integration into flour milling and emulsifier production. Competitive moves center on M&A to capture clean-label formulation expertise and capital deployment toward flexible pouch packaging lines for e-commerce optimization.
Within the diversified conglomerate tier, General Mills and Nestlé occupy positions defined by retail shelf dominance and R&D intensity respectively. Nestlé represents the fortified functional mix archetype targeting metabolic health-conscious households. Puratos anchors the professional-grade specialist segment serving bakery channels with clean-label compliant bread mixes. Cargill exemplifies ingredient-systems integration with captive supply chain control over core inputs.
| Leading Market Players |
|---|
| Puratos |
| Conagra Brands |
| General Mills |
| Nestlé |
| Continental Mills |
| Cargill |
| The Kraft Heinz Company |
| Bakels Group |
| Archer Daniels Midland Company |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap millers in the North American plains anchor wheat flour supply, translating their captive grain elevator networks into pricing discipline that resists spot-market volatility and protects margin structures across conventional mix tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates USDA-certified organic formulations from conventional blends and private-label commodity lines. Certification grade and volume scale drive price differentiation, with organic seals commanding shelf-position premiums that filter smaller competitors. Cost compression in economy tiers is intensifying because Black Sea wheat disruptions feed input instability. Foodservice buyers exhibit lowest price sensitivity due to labor-cost savings from speed-scratch applications, while budget retail households in the United States show highest elasticity.
Supply Chain Analysis
Freight cost escalation across intermodal rail and trucking networks is reshaping sourcing radii for Midwest-based manufacturers serving coastal population centers. Wheat supply concentrates in the United States, Canada, and Australia, with formulation chemistry inputs drawing from German and Dutch specialty chemical producers. Single-source vulnerability sits with aluminum-free leavening agent suppliers facing EFSA re-evaluation timelines. Distribution runs through retail grocery slotting agreements in the United States and direct-to-consumer subscription platforms in the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Baking mixes function as a stable compounder anchored by persistent home baking habits that survived pandemic-era peaks and settled into durable baseline demand.
For Market Incumbents: Acquire clean-label formulation expertise through specialist R&D boutiques in France and the Netherlands. Consolidate pouch packaging capacity to capture e-commerce fulfillment economics. Defend against aluminum phosphate substitution mandates by accelerating sodium acid pyrophosphate blend transitions ahead of FDA guidance finalization. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer lowest competitive density for algorithmically curated monthly kits targeting millennial households. The gluten-free certification gap in United States manufacturing capacity represents the most penetrable white-space. Partner with third-party logistics providers specifying flexible film formats to bypass retail slotting fee barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier manufacturers lacking captive organic supply chains but holding established foodservice relationships. Long-term viability frames around five-to-ten year consolidation of formulation expertise and packaging automation. Watch EFSA additive re-evaluation timelines as the signal for accelerated M&A in clean-label specialist targets.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | EFSA REACH Annex XIV compliance deadlines in Europe force R&D prioritization ahead of regulatory enforcement. |
| Pouch Packaging Line Conversion | E-commerce shipping weight optimization reduces damage rates for United States direct-to-consumer platforms. |
| Organic Supply Chain Captivity | USDA three-year farmland transition requirements lock out private-label competitors from premium retail shelf space. |
| Subscription Platform Launch | Algorithmic curation based on seasonal baking patterns captures recurring revenue from enthusiast households. |
| Gluten-Free Facility Buildout | Dedicated allergen-free production addresses diagnosed celiac prevalence outpacing current United States capacity. |
Methodological Framework
Coverage spans the United States, Germany, France, the United Kingdom, and Japan, with primary inputs from each market informing demand calibration. The analysis combines structured interviews with brand managers, category buyers at retailers, channel sales heads, and supply planners alongside secondary validation from Nielsen retail audit data, customs records, SEC filings, and EFSA regulatory submissions. Bottom-up demand modeling and top-down macroeconomic triangulation cross-check volume assumptions across the analysis window.
Rate-of-change decomposition separates volume growth from price-mix effects across product type, ingredient source, packaging format, and end-user segmentation throughout the forecast period. CAGRs derive from iterative reconciliation of historical shipment data with forward-looking capacity announcements and regulatory timeline impacts. Wheat futures curves and aluminum phosphate substitution velocity serve as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA additive re-evaluation rulings and Black Sea supply disruption persistence. Forecasts reflect documented assumptions about household baking habit retention and certification cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Gluten-Free Baking Mixes Market
Bakery Products
Dough Whitener Market
Bakery Products
South America Bakery Products Market
Bakery Products
Bakery Emulsions Market
Bakery Products
Pastry Margarine Market
Bakery Products
Bakery Mixes Market
Bakery Products
Low-Calorie Breakfast Muffins Market
Bakery Products
Biscuit Mixes Market
Bakery Products
Low Fat Bread Market
Bakery Products
Global Bakery Product Market
Bakery Products
Low Fat Muffin Market
Bakery Products
Europe Bakery Products Market
Bakery Products
GCC Bakery Products Market
Bakery Products
Organic Bread Flour Market
Bakery Products
Bakers Yeast Market
Bakery Products
Specula Market