
 Yucca Extract Market | 2026-2036
Yucca Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Yucca Extract Market Outlook
Pet nutrition is broadening as a demand pillar for yucca extract, pulling volume away from traditional agricultural surfactant applications. Desert King International anchors supply through captive desert harvesting operations in northern Mexico. Garuda International differentiates via pharmaceutical-grade purification protocols for nutraceutical clients. Bio-Botanica leverages botanical extraction expertise to serve cosmetic manufacturers seeking natural foaming agents.
Yucca extract comprises steroidal saponins, polyphenols, and resveratrol derivatives recovered from Yucca schidigera and Yucca filamentosa species through aqueous or solvent extraction at concentrations typically ranging from thirty to sixty percent active saponin content. Powder formulations dominate commercial procurement for feed and food additive blending due to stability and dosing precision, while liquid extracts capture premium positioning in cosmetic and pharmaceutical applications where rapid solubility matters. The nutraceutical segment shows the steepest growth trajectory as saponin bioactivity research expands, though agriculture retains the largest volume footprint through anti-protozoal feed inclusion.
The FDA GRAS notification process and EPA pesticide tolerance frameworks govern yucca extract market access in the United States, while EFSA novel food assessments shape European commercialization timelines for new application areas. REACH compliance and F-Gas Regulation indirect pressures push extractors toward aqueous processing methods with lower solvent residuals. Stakeholders must monitor evolving saponin purity standards across FDA, EFSA, and Health Canada channels to preempt formulation reformulation costs.
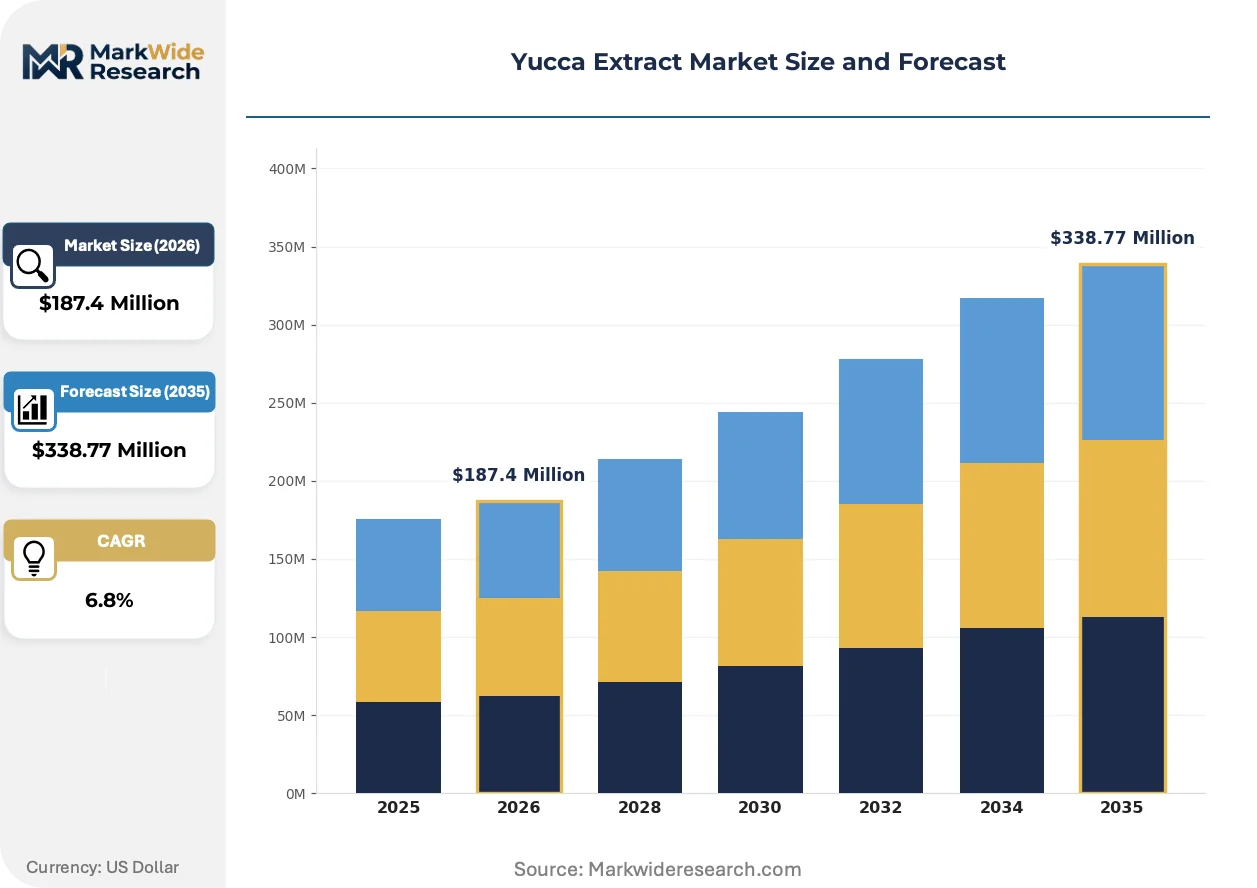
Market Dynamics
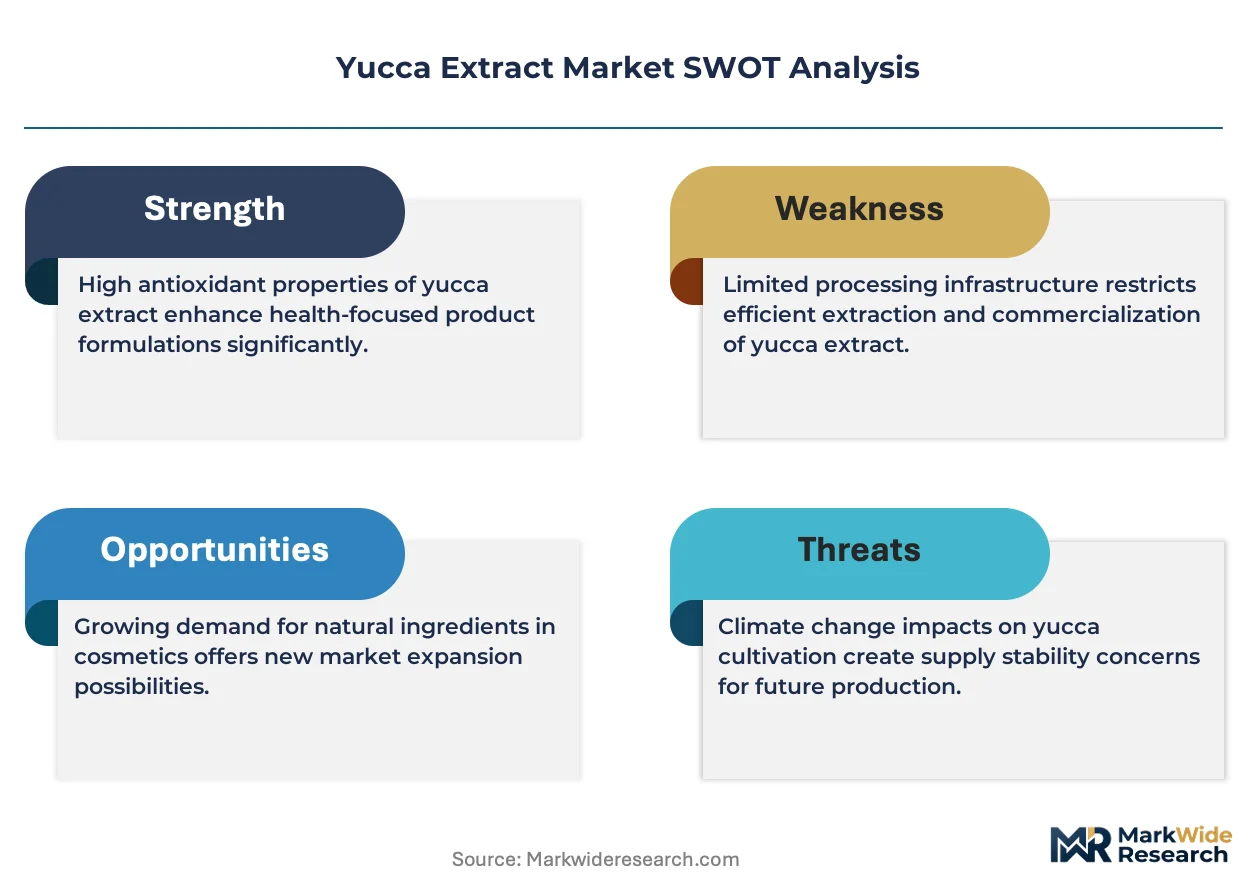
Pet food formulators are pulling volume away from agricultural surfactant applications, creating a demand pivot that concentrates procurement power among multinational feed manufacturers while desert harvesters scramble to secure captive supply.
Growth Catalysts
- GRAS Self-Affirmation Pathway:The FDA's streamlined notification process accelerates ingredient compliance timelines for US nutraceutical entrants, compressing commercialization cycles versus full food additive petitions.
- Chihuahuan Desert Harvest Zones:Concentrated wild stands of Yucca schidigera in northern Mexico enable economies of scale in raw material collection unmatched by cultivated alternatives.
- Saponin Bioactivity Research:Expanding clinical investigation into steroidal saponin mechanisms for gut microbiome modulation drives premium positioning in companion animal nutrition.
Market Restraints
- Desert Climate Volatility:Drought frequency in Coahuila and Chihuahua states threatens wild stand regeneration cycles, creating raw material availability risk without irrigation infrastructure.
- EPA Pesticide Tolerance Frameworks:Residual agricultural chemical testing requirements for imported botanicals impose analytical cost burdens and shipment detention risk at US ports.
- Synthetic Surfactant Substitution:Petroleum-derived foaming agents maintain cost advantages in industrial cleaning applications, capping yucca penetration in price-sensitive detergent segments.
Strategic Opportunities
- EFSA Novel Food Assessments:Successful authorization for yucca saponin inclusion in human dietary supplements would unlock European nutraceutical white space currently restricted to feed applications.
- Aqueous Processing Convergence:REACH compliance pressures and F-Gas Regulation indirect effects favor water-based extraction methods with lower solvent residuals, rewarding capital investment in green chemistry infrastructure.
- Direct-to-Formulator Channels:Bypassing traditional ingredient distributors through technical sales teams enables specification capture in mid-tier pet food manufacturers seeking differentiated positioning.
Industry Challenges
- Phytochemical Standardization Expertise:Scarcity of analytical chemists capable of validating saponin content variability across wild-harvested lots creates quality control bottlenecks at processing facilities.
- Multi-Jurisdiction Purity Standards:Divergent saponin concentration thresholds across FDA, EFSA, and Health Canada channels force parallel formulation development, inflating R&D overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yucca Extract Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Granules, Capsules Application: Food Additive, Nutraceutical, Cosmetics, Agriculture End User: Food Industry, Pharma Sector, Cosmetic Manufacturers, Farmers Distribution Channel: Online Sales, Retail Stores, Direct Sales, Distributors |
| Companies Covered | Garuda International, American Extracts, Desert King International, Bio-Botanica, Nova Microbials, BAJA Yucca Co, Ingredients by Nature, Avitech Nutrition, Naturex Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yucca Extract Market Strategic Shifts
Extraction technology maturation and regulatory chemistry evolution are compressing the viable process window, forcing processors to choose between capital-intensive purification upgrades or commodity positioning in undifferentiated feed markets.
Supercritical carbon dioxide extraction is consolidating as the preferred method for pharmaceutical-grade saponin recovery, displacing traditional ethanol-based protocols in high-value applications. Nutraceutical contract manufacturers in Switzerland and Germany are adopting these systems to meet residual solvent limits under European Pharmacopoeia standards. This technology shift is consolidating supply relationships around processors with seven-figure capex capacity, marginalizing smaller aqueous-only operators.
REACH registration requirements for solvent-based extraction chemicals are tightening discharge and worker exposure thresholds across EU member states. Industrial users face reformulation deadlines as ECHA evaluates additional substances of very high concern for potential restriction. German and Dutch extractors are responding with closed-loop aqueous systems that eliminate organic solvent handling entirely, trading yield efficiency for regulatory certainty.
Specification-driven procurement is compressing supplier qualification timelines as multinational pet food manufacturers consolidate vendor lists around dual-certified processors. Third-party audit protocols combining FSSC 22000 food safety with GMP+ feed assurance are displacing single-standard certifications in tender evaluations. This behavioral shift is most visible in procurement departments at companies headquartered in the Netherlands and US Midwest, where technical buyers now require batch-level saponin assay documentation before contract execution.
Yucca Extract Market Segmentation
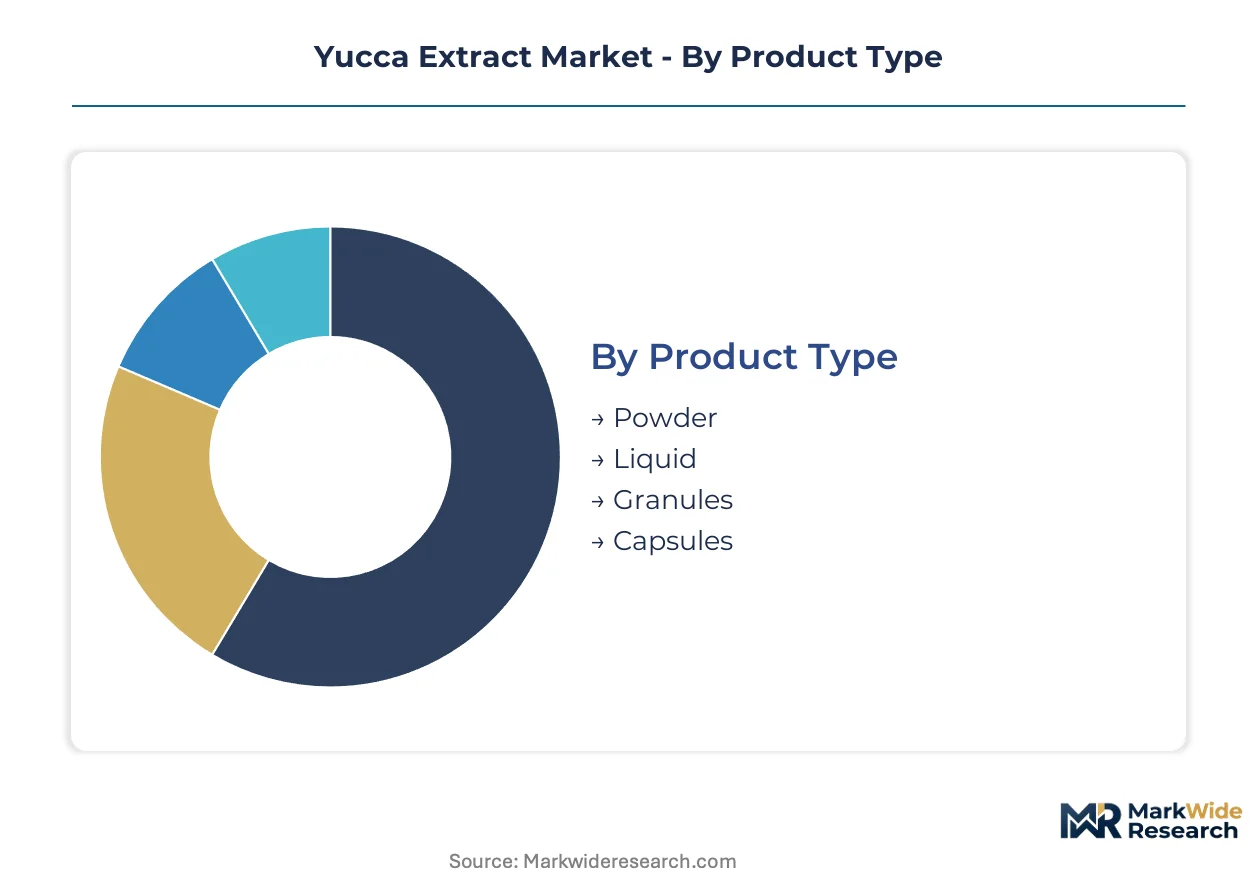
Procurement patterns in the yucca extract market diverge sharply across physical form, end-use chemistry requirements, and channel access. Specification standards from FDA, EFSA, and feed assurance schemes force parallel supply chains that rarely intersect.
Product Type:
Desert harvesters in Chihuahua and Coahuila states direct raw material flows toward processing technologies that match customer solubility and stability requirements.
- Powder:Spray-dried concentrates with thirty to sixty percent saponin content serve feed manufacturers requiring precise dosing in premix operations. Pet food formulators in the US Midwest and Netherlands specify powder for its eighteen-month shelf stability and compatibility with extrusion thermal profiles.
- Liquid:Aqueous extracts with rapid solubility capture cosmetic and pharmaceutical procurement where batch dissolution speed outweighs shipping cost premiums. Swiss and German nutraceutical contract manufacturers favor liquid for supercritical carbon dioxide processing compatibility.
- Granules:Agglomerated forms bridge powder flowability and liquid dispersibility for mid-tier agricultural compounders.
- Capsules:Pre-metered dosage units target direct-to-consumer nutraceutical channels with minimal formulation expertise.
Powder absorbs the bulk of installed capacity; liquid is expanding most quickly.
Application:
Margin structures vary dramatically across application areas, with pharmaceutical-grade purification commanding multiples over commodity feed inclusion rates.
- Food Additive:GRAS-notified saponin preparations for odor control in pet nutrition and human food processing. US-based multinational feed manufacturers drive volume through specification lock-in at the formulation stage.
- Nutraceutical:Steroidal saponin bioactivity research for gut microbiome modulation is climbing the fastest as clinical investigation expands. Health Canada and Swissmedic regulatory pathways shape commercialization timelines for human dietary supplements.
- Cosmetics:Natural foaming agents from Yucca filamentosa serve formulators seeking botanical alternatives to synthetic surfactants under REACH pressure.
- Agriculture:Anti-protozoal feed inclusion retains the largest volume footprint through established veterinary protocols, though pricing faces pressure from synthetic alternatives.
Agriculture retains the dominant volume position; nutraceutical applications show the steepest margin expansion.
End User:
Technical buying criteria fragment across customer categories, from assay documentation demands in pharmaceutical procurement to cost-per-ton optimization in agricultural channels.
- Food Industry:Pet food manufacturers consolidate vendor lists around dual-certified processors meeting FSSC 22000 and GMP+ standards simultaneously.
- Pharma Sector:European Pharmacopoeia residual solvent limits and USP monograph compliance drive supplier qualification toward supercritical extraction specialists.
- Cosmetic Manufacturers:Natural positioning requirements and REACH registration pressures favor aqueous processing methods with full supply chain documentation.
- Farmers:Price-sensitive procurement through agricultural distributors limits penetration to anti-protozoal applications with demonstrated feed conversion economics.
Food industry procurement concentrates volume; pharma sector qualification timelines stretch longest.
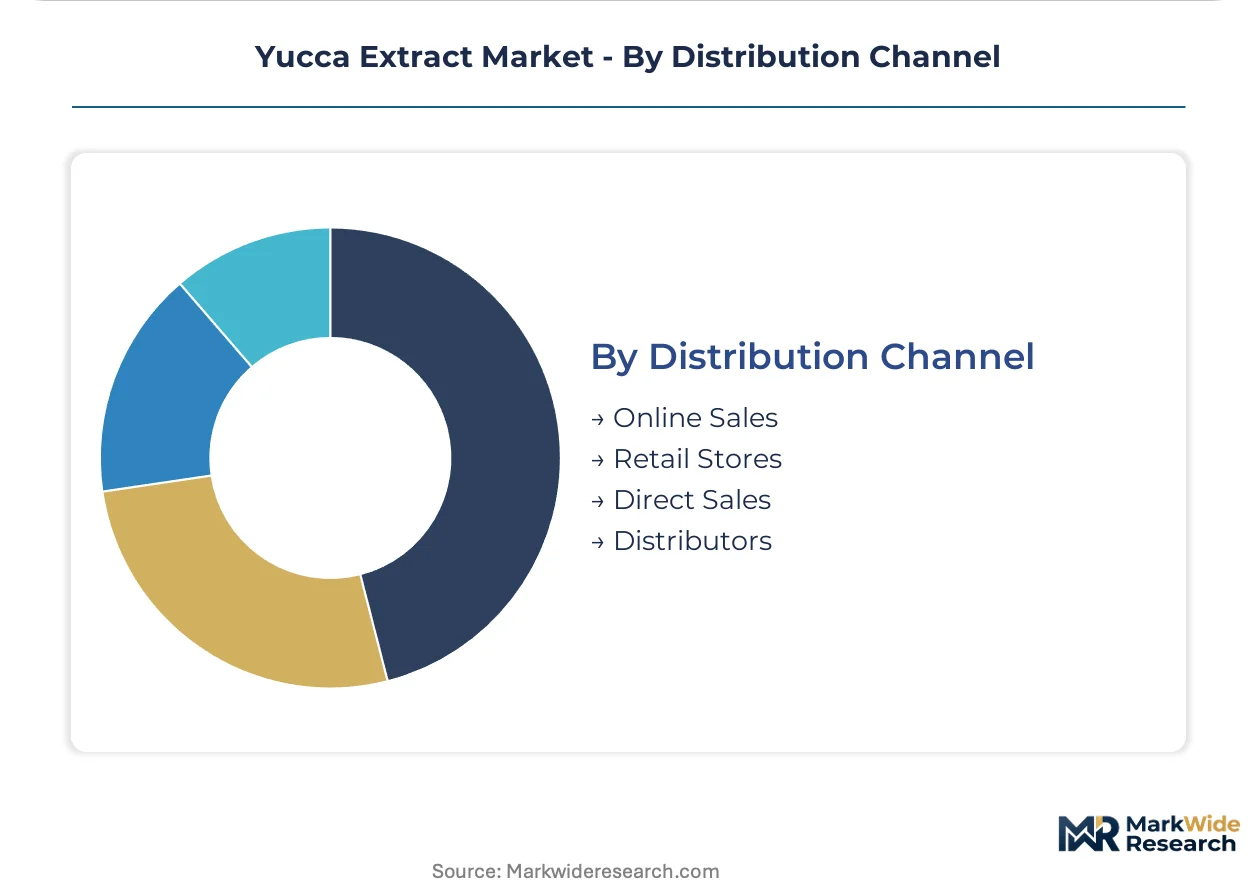
Distribution Channel:
Channel selection reflects customer technical sophistication and batch size requirements, with direct engagement displacing traditional distribution in specification-driven segments.
- Online Sales:Capsule and small-format liquid extracts for nutraceutical end-consumers and small cosmetic formulators.
- Retail Stores:Limited presence for pre-packaged supplements in natural product channels.
- Direct Sales:Technical sales teams capture mid-tier pet food manufacturers seeking differentiated positioning through bypassing traditional ingredient distributors.
- Distributors:Agricultural and commodity feed applications rely on established distribution networks for logistics efficiency at scale.
Direct sales is gaining share fastest in premium applications; distributors retain agricultural volume dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Chihuahuan Desert harvest zones in northern Mexico operate under maquiladora-adjacent tax structures that concentrate extraction capacity near Ciudad Juárez processing clusters.
United States
Pet food manufacturers in Kansas and Iowa drive saponin procurement for odor-control formulations in companion animal nutrition. FDA GRAS self-affirmation pathways compress compliance timelines for domestic nutraceutical entrants. Midwestern feed compounders consolidate vendor lists around dual-certified processors meeting FSSC 22000 and GMP+ standards simultaneously.
Mexico
Wild stands of Yucca schidigera in Coahuila and Chihuahua states supply raw material to aqueous extraction facilities clustered along the US border. PROFEPA environmental permits govern desert harvesting quotas and regeneration protocols. Desert King International anchors supply through captive collection operations in the Chihuahuan Desert with downstream processing in Monterrey industrial parks.
Germany
Swiss and German nutraceutical contract manufacturers import pharmaceutical-grade saponin preparations for supercritical carbon dioxide processing. REACH registration requirements for solvent-based extraction chemicals push processors toward closed-loop aqueous systems. Bavarian extraction specialists serve cosmetic formulators seeking REACH-compliant natural foaming agents with full supply chain documentation.
Switzerland
Swissmedic regulatory pathways shape commercialization timelines for human dietary supplements containing steroidal saponins. Geneva and Basel-based contract manufacturers demand European Pharmacopoeia residual solvent limits that favor supercritical extraction compatibility. Alpine processing facilities specialize in high-purity liquid extracts for pharmaceutical applications where rapid solubility commands premium positioning.
Canada
Health Canada purity standards for natural health products create parallel formulation requirements distinct from FDA thresholds. Prairie feed manufacturers incorporate yucca saponins for anti-protozoal protocols in cattle finishing operations. Alberta-based distributors channel agricultural-grade powder extracts to ranching operations across the western provinces.
Yucca Extract Market Competitive Environment
Top-tier vendors anchor captive desert harvesting operations, while mid-tier processors compete on extraction technology specialization. The vendor base stratifies between wild-stand controllers with upstream resource access and purification specialists serving pharmaceutical-grade demand. Three archetypes dominate: desert harvester-integrators, contract extraction service providers, and botanical ingredient platform companies. Competitive moves concentrate on securing multi-year raw material offtake agreements and upgrading from aqueous to supercritical processing capacity.
Within the harvester-integrator tier, Desert King International exemplifies upstream resource control through captive Chihuahuan Desert operations. Garuda International and Bio-Botanica occupy positions on the purification-specialist vector, with the former representing pharmaceutical-grade protocol capabilities and the latter exemplifying botanical extraction expertise for cosmetic applications. These three anchors illustrate the structural tension between resource access and technical processing differentiation that shapes procurement relationships across pet nutrition, nutraceutical, and cosmetic end-use segments.
| Leading Market Players |
|---|
| Garuda International |
| American Extracts |
| Desert King International |
| Bio-Botanica |
| Nova Microbials |
| BAJA Yucca Co |
| Ingredients by Nature |
| Avitech Nutrition |
| Naturex Group |
| Others |
Value Chain & Pricing Dynamics
Captive harvesting operations in the Chihuahuan Desert anchor both supply security and pricing power for tier-one processors, creating a structural moat that commodity aqueous extractors cannot replicate without multi-million dollar backward integration investments.
Pricing Analysis
Short lead-time premiums command fifteen to twenty percent markups over standard contract terms as pet food manufacturers rush GRAS-notified saponin batches through formulation trials. Three-tier pricing structure across pharmaceutical-grade, feed-certified, and cosmetic-standard levels separates supercritical extraction outputs from aqueous methods. Cost compression in the feed-grade tier is intensifying because synthetic surfactant alternatives maintain cost advantages in price-sensitive detergent segments. Agricultural distributors and commodity compounders exhibit the highest price sensitivity, while Swiss and German nutraceutical contract manufacturers absorb premiums for European Pharmacopoeia residual solvent compliance.
Supply Chain Analysis
Direct-to-formulator channels handle specification-capture demand from mid-tier pet food manufacturers seeking differentiated positioning through bypassing traditional ingredient distributors. Wild stand harvesting concentrates in Mexico's Coahuila and Chihuahua states, with downstream processing clusters anchored in Monterrey industrial parks and Ciudad Juárez maquiladora zones. Raw material flows draw from Yucca schidigera desert stands, aqueous extraction chemicals, and supercritical carbon dioxide processing infrastructure. Single-source vulnerability runs through PROFEPA-governed desert harvesting quotas, where drought frequency threatens regeneration cycles without irrigation backup. Distribution runs through dual-certified processors serving FSSC 22000 and GMP+ standards simultaneously.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where capital-intensive supercritical extraction upgrades and multi-jurisdiction purity compliance are forcing smaller aqueous-only operators toward acquisition or exit.
For Market Incumbents: To counter synthetic surfactant substitution pressure in industrial cleaning applications, Desert King International and Garuda International should deepen backward integration into captive Chihuahuan Desert harvesting territories while locking multi-year raw material offtake agreements with Coahuila collection cooperatives. Certification investment in simultaneous FSSC 22000 and GMP+ standards creates tender eligibility barriers for undercapitalized competitors. For New Entrants and Emerging Players: Capture the EFSA novel food assessment white space for human dietary supplements, where successful steroidal saponin authorization would unlock European nutraceutical demand currently restricted to feed applications. Target Swiss and German contract manufacturers through technical sales teams offering batch-level saponin assay documentation as a specification-capture wedge against established distributors. For Investors and Strategic Acquirers: Exit pathways concentrate in pharmaceutical-grade purification specialists with supercritical carbon dioxide capacity and European Pharmacopoeia compliance track records. Long-term viability hinges on processors that bridge wild-stand resource access with seven-figure capex extraction infrastructure across the analysis window. Watch for EFSA novel food authorization timelines as the inflection signal separating premium-margined nutraceutical positioning from commodity feed-grade pricing.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical Extraction Capacity Buildout | European Pharmacopoeia residual solvent limits favor CO2-based pharmaceutical-grade saponin recovery. |
| Captive Desert Harvesting Expansion | PROFEPA-permitted wild stand quotas in Coahuila secure raw material availability against drought volatility. |
| Dual Certification Investment | Simultaneous FSSC 22000 and GMP+ standards unlock tender eligibility at multinational pet food manufacturers. |
| Direct-to-Formulator Channel Development | Technical sales teams bypass traditional distributors to capture specification decisions at mid-tier processors. |
| Aqueous Processing Infrastructure | Closed-loop water-based systems eliminate REACH-registered solvent handling for cosmetic manufacturer compliance. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with extraction facility managers, pet food formulation chemists, nutraceutical contract manufacturing executives, and desert harvesting cooperative coordinators. FDA GRAS notification databases, EFSA novel food assessment registers, PROFEPA environmental permit records, and Mexican agricultural export statistics provided triangulation points against bottom-up processor capacity estimates and top-down end-use demand modeling.
Data-stream reconciliation across volume and value outputs employed a segmented analytical framework spanning product form, application chemistry requirements, end-user technical specifications, and distribution channel access patterns over the projection horizon. CAGRs were derived from saponin bioactivity research expansion rates, pet nutrition formulation adoption curves, and agricultural feed inclusion trend lines, cross-referenced against supercritical extraction capacity installation schedules and EFSA authorization pipeline milestones.
The model holds under stable desert climate conditions and continued GRAS self-affirmation pathway accessibility; deviation in Coahuila drought frequency or EFSA steroidal saponin restriction triggers would shift volume assumptions materially. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Flour Market
Plant Based Food
Chickpea-Based Products Market
Plant Based Food
Rice Protein Market
Plant Based Food
Veggie Burger Market
Plant Based Food
Fermented Plant-Based Food Market
Plant Based Food
India Plant Based Milk Market
Plant Based Food
Plant-Based Tzatziki and Labneh Ferment Bases Market
Plant Based Food
Low Fat Plant-Based Diet Market
Plant Based Food
West Africa Plant Based Product Market
Plant Based Food
USA Plant-Based Creamers Market
Plant Based Food
Soy Food Products Market
Plant Based Food
Plant-Based Diet Market
Plant Based Food
Global Tofu Market
Plant Based Food
United States Rice Protein Market
Plant Based Food
Global Chaga Mushroom-Based Products Market
Plant Based Food
Vegan Meat Alternatives Market