
 Pastries Market | 2026-2036
Pastries Market Size, Share, and Industry Trends Forecast 2026-2036
Pastries Market Analysis
Quick-service cafes and convenience retailers is unwinding traditional bakery-centric pastry distribution. Grupo Bimbo leverages its vertically integrated flour-to-retail network across Latin American markets. Yamazaki Baking anchors its dominance in Japanese convenience-store channels with high-frequency production cycles. Associated British Foods competes through its Primark-adjacent foodservice contracts and heritage brand portfolio.
Pastries comprise laminated, choux, shortcrust, or enriched yeast dough products baked with specified fat content, moisture activity, and shelf-stability parameters for immediate consumption or refrigerated distribution. Their primary commercial purpose centers on portion-controlled, ready-to-eat indulgence across dayparts from breakfast through late-night snacking. Croissants and Danishes capture the fastest-growing premium tier as laminated dough automation reduces unit labor costs. The Breakfast application segment sustains the largest volume base, while Catering channels generate disproportionate margin pools through event-based customization and bulk pricing.
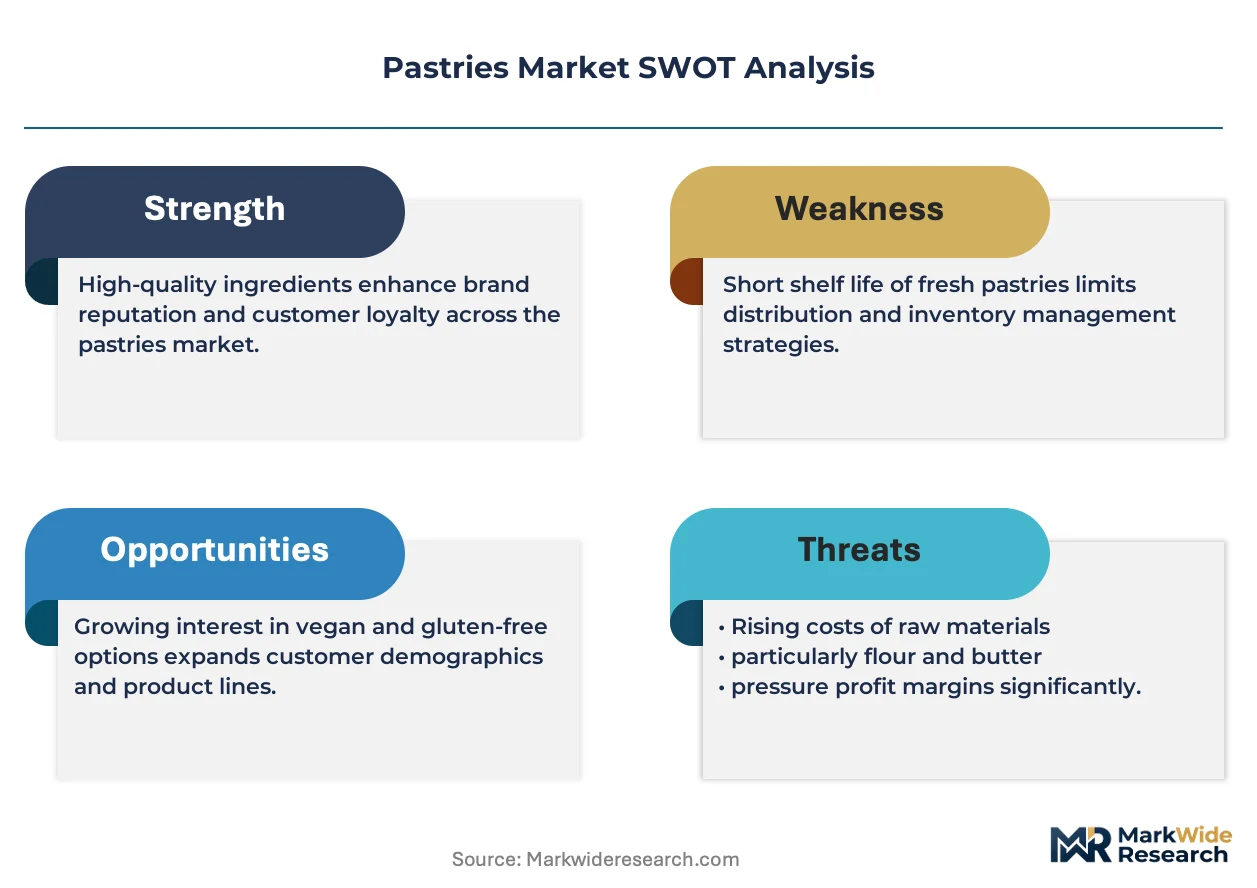
EFSA novel food guidelines, FDA Food Safety Modernization Act provisions, and EU F-Gas Regulation on industrial refrigeration collectively shape ingredient approval timelines, cold-chain compliance costs, and trans-fat reformulation pathways across manufacturing networks. These frameworks elevate capital requirements for cross-border pastry trade while creating compliance-driven segmentation between artisan and industrial producers. Stakeholders must monitor evolving allergen-labeling mandates and carbon-footprint disclosure rules to preempt supply-chain disruption and maintain retail-listing access.
Market Dynamics
Clean-label reformulation mandates from EFSA and FDA are compressing formulation timelines while fragmenting supplier relationships as manufacturers scramble for compliant ingredient alternatives.
Growth Catalysts
- Grab-and-Go Penetration:Institutional cafeterias and convenience retailers are expanding pastry procurement as daypart-agnostic snacking normalizes across corporate and educational foodservice channels.
- EFSA Novel Food Guidelines:Accelerated approval pathways for alternative proteins and fiber-enriched flours are enabling functional pastry positioning in European markets.
- Laminated Dough Automation:High-speed sheeting and lamination systems are reducing unit labor costs for croissant and Danish production, unlocking premium tier volume scaling.
Market Restraints
- Butter Price Volatility:Dairy commodity swings and concentrated European butter supply are compressing margin stability for laminated dough specialists.
- EU F-Gas Regulation:Phase-down schedules for hydrofluorocarbon refrigerants are elevating cold-chain retrofit costs across industrial bakery networks.
- Clean-Label Ingredient Scarcity:Limited commercial availability of natural preservatives with equivalent shelf-life performance is constraining reformulation velocity.
Strategic Opportunities
- Refrigerated Distribution Expansion:Extended-shelf-life chilled pastry formats are penetrating convenience retail in Germany and the Netherlands where cold-chain density supports daily replenishment.
- CSRD Carbon Disclosure:Mandatory emissions reporting is creating first-mover advantage for bakeries with verified supply-chain footprint data and regenerative flour sourcing.
- AI-Driven Demand Forecasting:Machine learning integration with high-frequency convenience-store replenishment cycles is reducing waste and enabling made-to-order production scheduling.
Industry Challenges
- Laminated Dough Artisan Skill Gap:Automated systems require technicians capable of calibrating multi-layer sheeting precision, a competency scarce in traditional bakery labor pools.
- Cross-Border Allergen Harmonization:Divergent sesame, lupin, and mustard labeling mandates between EU member states and FDA thresholds are complicating unified packaging strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pastries Market |
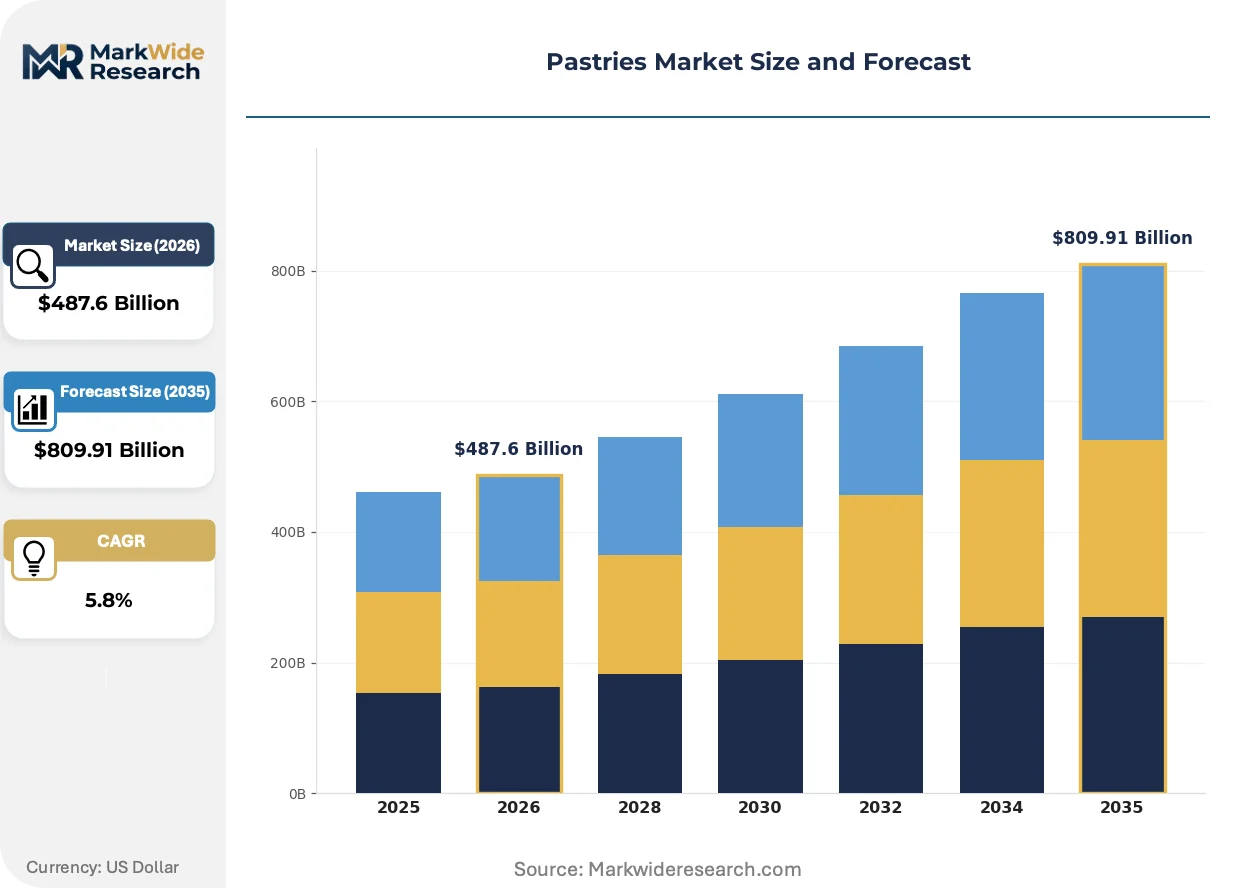
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $809.91 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Croissants, Danishes, Eclairs, Pies Application: Snacks, Breakfast, Dessert, Catering Distribution Channel: Retail Stores, Online Delivery, Bakeries, Supermarkets Customer Type: Individuals, Food Service, Corporations, Event Planners |
| Companies Covered | Associated British Foods, Flowers Foods, Grupo Bimbo, Britannia Industries, Aryzta, Mondelēz International, Yamazaki Baking, Pladis, General Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pastries Market Emerging Trajectories
Automation, regulatory transparency mandates, and channel disintermediation are converging to reshape how pastries are formulated, produced, and delivered to end consumers.
High-speed lamination robotics with real-time dough-temperature monitoring is fragmenting the traditional divide between artisan and industrial croissant production. Mid-scale regional bakeries in France and Belgium are deploying compact automated lines that replicate 27-layer structures previously achievable only through manual folding. This capability compression is enabling premium positioning at previously mass-market price points.
EFSA's updated guidance on enzymatic processing aids and the FDA's Food Safety Modernization Act traceability requirements are forcing ingredient documentation upgrades across supplier tiers. Manufacturers must now maintain lot-level digital records from flour mill to finished goods. Small-to-mid-sized producers in Italy and Spain are consolidating supplier relationships to reduce audit burden.
Direct-to-retailer replenishment apps are bypassing traditional wholesale bakery distributors in Japanese and South Korean convenience channels. Store managers now place micro-orders based on real-time POS data, compressing order-to-delivery windows from 48 hours to 6 hours. This pattern is most visible in Tokyo's 24-hour konbini network, where pastry waste rates have dropped substantially.
Pastries Market Segmentation
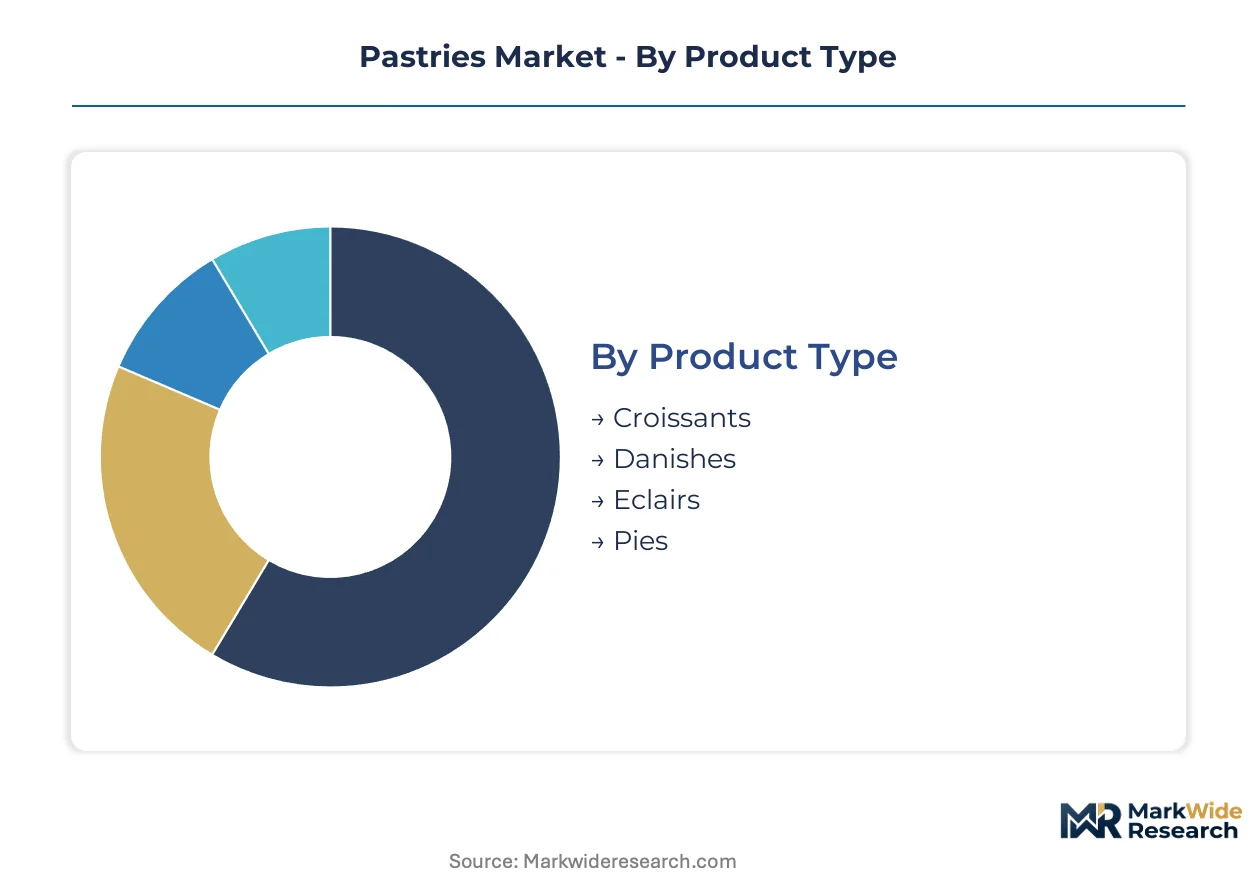
Pastry manufacturers configure production lines around specific dough chemistries and channel requirements. Segmentation clarity determines whether a bakery invests in frozen distribution infrastructure or direct-to-retail freshness protocols.
Product Type:
Channel mix varies sharply by dough structure: laminated products dominate grab-and-go retail while choux formats concentrate in foodservice.
- Croissants:27-layer laminated dough with specified butter fat content between 16-25% enables premium positioning in French and Belgian retail channels. Convenience retailers in Japan and South Korea are expanding chilled croissant sets as daily replenishment cycles compress.
- Danishes:Enriched laminated dough with fruit or cheese fillings generates disproportionate margin in North American breakfast channels. Automated sheeting systems are reducing unit labor costs and enabling regional bakeries to compete with industrial producers.
- Eclairs:Choux pastry with piped cream fillings requires cold-chain integrity and same-day consumption windows, limiting distribution to bakeries and dedicated dessert shops.
- Pies:Shortcrust or flaky pastry formats with savory or sweet fillings concentrate in seasonal retail promotions and institutional catering contracts.
By volume, Croissants lead. By expansion trajectory, Danishes are climbing the fastest as automation unlocks premium tier scaling.
Application:
Cost tier separation is pronounced: breakfast commands volume scale while catering extracts value through customization.
- Breakfast:Sustains the largest volume base across all geographies, with laminated products capturing premium positioning in French artisan channels and mass-market penetration in Japanese convenience retail.
- Catering:Event-based customization and bulk pricing generate disproportionate margin pools, particularly for wedding and corporate contract bakeries in Italy and Spain.
- Snacks:Daypart-agnostic consumption patterns are normalizing across corporate and educational foodservice channels, driving procurement expansion in institutional cafeterias.
- Dessert:Choux-based and cream-filled formats concentrate in evening dayparts, with highest per-unit pricing in dedicated patisserie channels.
Breakfast captures the greatest shipment volumes. Catering delivers the steepest margin expansion as event formats recover.
Distribution Channel:
Customer type concentration shapes channel investment: individuals drive retail density while food service demands replenishment velocity.
- Supermarkets:Extended-shelf-life chilled formats with modified atmosphere packaging are penetrating German and Dutch convenience retail where cold-chain density supports daily replenishment cycles.
- Bakeries:Fresh-daily production with limited distribution radius maintains artisan positioning in France, where heritage bakery heritage underpins export growth and premium pricing.
- Retail Stores:Grab-and-go pastry sets in convenience retailers and quick-service cafes are unwinding traditional bakery-centric distribution models.
- Online Delivery:Direct-to-consumer platforms are emerging in urban clusters, though cold-chain costs and delivery windows constrain penetration outside dense metropolitan zones.
Supermarkets move the most units. Online Delivery is gaining share fastest as last-mile cold-chain solutions mature.
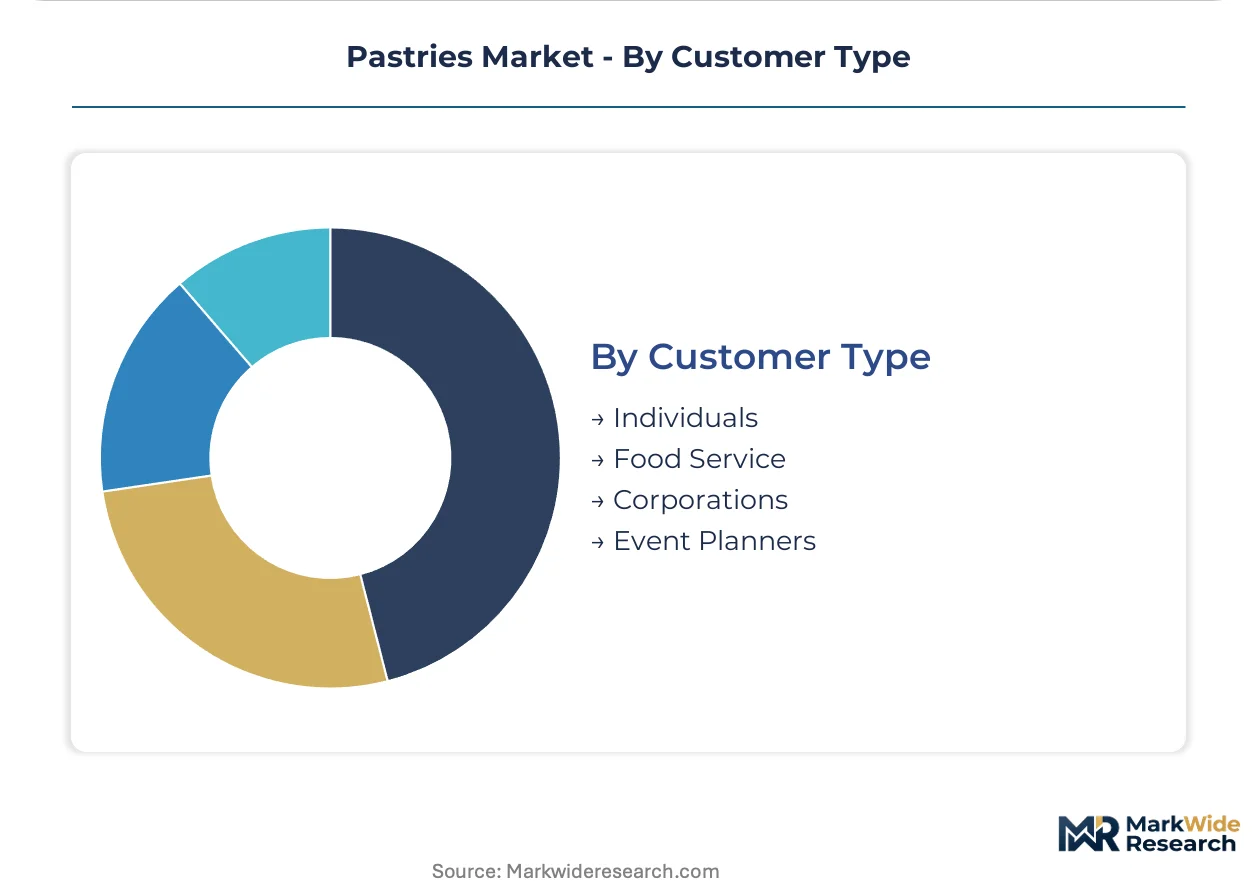
Customer Type:
Volume scale concentrates with individuals, but procurement sophistication varies by organizational buyer.
- Food Service:Quick-service cafes and institutional cafeterias are expanding pastry procurement as daypart-agnostic snacking normalizes, with EFSA and FDA clean-label mandates compressing supplier qualification timelines.
- Corporations:Contract catering and in-house cafeteria operations are consolidating supplier relationships to reduce audit burden under traceability requirements.
- Individuals:Impulse purchase patterns in convenience retail and supermarket channels sustain the broadest product variety and highest transaction frequency.
- Event Planners:Bulk customization for weddings and corporate functions generates concentrated revenue spikes with extended production planning horizons.
Individuals generate the highest transaction counts. Food Service is expanding procurement fastest as institutional channels professionalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
French artisan bakeries export premium laminated products to Japanese convenience retail networks, establishing a transcontinental trade corridor that channels heritage craftsmanship into high-frequency replenishment channels.
France
Artisan bakery heritage underpins premium positioning and export growth, with croissant production concentrating in Paris and Lyon metropolitan clusters. EFSA clean-label mandates accelerate ingredient transparency requirements for cross-border shipments. Brittany and Normandy maintain butter supply contracts that stabilize input costs for laminated dough specialists.
Japan
Convenience-store channels drive high-frequency pastry procurement as 24-hour konbini networks compress replenishment cycles. METI standards govern food additive usage in processed bakery imports. Tokyo and Osaka anchor automated production investments that replicate European lamination techniques at industrial scale.
Germany
Extended-shelf-life chilled formats penetrate supermarket channels where cold-chain density supports daily replenishment. EU F-Gas Regulation elevates refrigeration retrofit costs for industrial bakery networks. Bavaria and North Rhine-Westphalia concentrate automated sheeting system deployments for Danish production.
United States
Breakfast application segments sustain volume scale through quick-service cafe procurement expansion. FDA Food Safety Modernization Act traceability requirements compress supplier qualification timelines. Chicago and New York metro areas anchor regional bakery consolidation that reduces distribution radius for fresh-daily formats.
Italy
Catering channels generate concentrated revenue through wedding and corporate contract customization. CSRD carbon disclosure mandates create compliance-driven segmentation between artisan and industrial producers. Lombardy and Emilia-Romagna maintain heritage patisserie clusters that supply event-based premium tiers.
Pastries Market Vendor Landscape
Listed leaders compete with private specialists across capital access and operational agility, producing a tiered structure where scale-driven conglomerates face nimble regional challengers. Three archetypes dominate: vertically integrated flour-to-retail networks, heritage brand portfolio holders, and convenience-channel automation specialists. Dominant competitive moves include backward integration into captive ingredient supply and geographic expansion through distributor bypass strategies.
Within the heritage brand tier, Associated British Foods and Flowers Foods exemplify portfolio diversification approaches that span retail and foodservice channels. Grupo Bimbo occupies a position representing Latin American market anchoring through production network density. Yamazaki Baking sits within the convenience-channel specialist archetype, with its company name indicating Japanese origin and limited liability structure.
| Leading Market Players |
|---|
| Associated British Foods |
| Flowers Foods |
| Grupo Bimbo |
| Britannia Industries |
| Aryzta |
| Mondelēz International |
| Yamazaki Baking |
| Pladis |
| General Mills |
| Others |
Supply Flow & Price Mechanics
EFSA novel food guidelines and FDA Food Safety Modernization Act traceability requirements gate both supplier qualification timelines and price differentiation between artisan and industrial pastry tiers. Compliance documentation burdens compress margin pools for smaller producers while enabling premium positioning for bakeries with verified supply-chain footprint data.
Pricing Analysis
Automation-generation pricing gaps separate legacy manual lamination from compact robotic sheeting and next-generation AI-integrated production lines. Three-tier pricing structure across premium artisan, standard industrial, and economy private-label levels stratifies by butter fat content and certification tier. Cost compression in the premium tier is intensifying because laminated dough automation reduces unit labor costs for croissant and Danish production. Quick-service cafes exhibit highest price sensitivity due to procurement consolidation, while dedicated patisserie channels absorb premium markups with minimal volume elasticity.
Supply Chain Analysis
Inventory lead times for butter and specialty flour extend procurement planning horizons to 8-12 weeks for laminated dough specialists. Supply concentrates in France for premium butter contracts, Germany for automated sheeting equipment, and Japan for convenience-channel cold-chain infrastructure. Raw material dependencies rest on European dairy commodities, North American wheat varieties, and Asian palm oil derivatives. Single-source vulnerability concentrates in Brittany and Normandy butter supply contracts. Distribution runs through direct-to-retailer replenishment apps in Japanese konbini networks and traditional wholesale distributors in European artisan channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pastry incumbents face substitution pressure from protein-enriched functional snacks and meal-replacement bars that capture daypart-agnostic consumption occasions. Defense requires reinforcing premium positioning through heritage authentication and automation-enabled cost competitiveness.
For Market Incumbents: Fortify margin position through backward integration into captive butter supply contracts in Brittany and Normandy, and deploy compact automated lamination lines to replicate 27-layer structures at mass-market price points. Counter protein-snack substitution by emphasizing portion-controlled indulgence positioning. Channel control through direct-to-retailer replenishment apps reduces distributor margin extraction in Japanese and South Korean convenience networks. For New Entrants and Emerging Players: Same-day delivery gaps in urban online pastry channels present white-space opportunities where incumbents under-serve dense metropolitan zones with extended delivery windows. Target refrigerated distribution expansion in German and Dutch supermarket channels where cold-chain density supports daily replenishment but local bakery penetration remains limited. Pursue made-to-order production scheduling partnerships with AI-driven demand forecasting platforms to reduce waste rates below industry benchmarks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional bakery consolidators in Italy and Spain that have assembled event-catering contract portfolios but lack automation infrastructure for volume scaling. Long-term viability hinges on CSRD carbon disclosure compliance capabilities and regenerative flour sourcing verification. Monitor EFSA clean-label reformulation timelines as inflection indicator for supplier qualification bottleneck severity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Butter Supply | Brittany and Normandy contracts stabilize input costs for laminated dough specialists against dairy commodity swings. |
| Compact Automated Lamination Deployment | Mid-scale regional bakeries in France and Belgium replicate 27-layer structures at previously mass-market price points. |
| Direct-to-Retailer Replenishment App Launch | Tokyo konbini networks compress order-to-delivery windows from 48 hours to 6 hours with substantial waste reduction. |
| CSRD Carbon Disclosure Compliance Investment | Verified supply-chain footprint data creates first-mover advantage for regenerative flour sourcing claims. |
| AI-Driven Demand Forecasting Integration | Machine learning with high-frequency convenience-store cycles enables made-to-order production scheduling. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with bakery operations directors, convenience retail category buyers, foodservice procurement managers, and laminated dough equipment technicians; and secondary validation through EFSA novel food guidance documents, FDA Food Safety Modernization Act provisions, EU F-Gas Regulation phase-down schedules, and customs trade data for butter and wheat flour imports. Bottom-up volume modeling from production line capacity and top-down value triangulation from channel shipment data were cross-referenced for convergence.
Across the analysis window, the forecasting framework modeled segmentation dimensions including dough chemistry type, application daypart, distribution channel cold-chain requirements, and customer procurement sophistication tier. CAGRs were derived from slope analysis of historical shipment trajectories adjusted for regulatory inflection points. Forecast inputs incorporated EFSA approval pathway timelines for alternative proteins and METI standards for Japanese processed bakery imports.
Underlying assumptions cover sustained butter price volatility and clean-label ingredient commercialization rates, with deviation risk concentrated in EU F-Gas Regulation retrofit cost schedules and cross-border allergen harmonization delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Muffins Market
Bakery Products
US Retail Packaged Bread Market
Bakery Products
Gluten-Free Bakery Market
Bakery Products
Pizza Crust Market
Bakery Products
Pastry Margarine Market
Bakery Products
Bakery Cases Market
Bakery Products
Malted Rye Flour Market
Bakery Products
Baking Mats Market
Bakery Products
Europe Sweet Biscuits Market
Bakery Products
Soft Biscuit Market
Bakery Products
Europe Sourdough Market
Bakery Products
Cakes, Pastries, and Sweet Pies Market
Bakery Products
United States Bread Market
Bakery Products
Biscuits Market
Bakery Products
Cream Cheese Frosting Market
Bakery Products
North America Gluten Free Bakery Mixes Market