
 Cream Cheese Frosting Market | 2026-2036
Cream Cheese Frosting Market Size, Share, and Industry Trends Forecast 2026-2036
Cream Cheese Frosting Market Analytics
Precision fermentation and enzyme-modified dairy processing is reconfiguring how cream cheese bases achieve consistent texture without artificial stabilizers. Rich Products Corporation leverages its frozen dessert infrastructure to supply scaled cream cheese frosting solutions to national bakery chains. Dawn Food Products anchors its competitive position through vertical control over dairy sourcing and regional distribution networks. CSM Bakery Solutions differentiates via specialized emulsion technologies that extend shelf stability in food service channels.
Cream cheese frosting is a fat-in-water emulsion typically comprising cream cheese, butter, powdered sugar, and stabilizers, formulated to spread between 40°F and 70°F for cake finishing and pastry assembly. The whipped product type leads volume due to its aerated structure reducing unit cost per serving in commercial bakeries, while bagged formats represent the fastest-growing packaging configuration as food service operators prioritize portion control and labor reduction. Spreadable variants command premium positioning in retail channels where home bakers seek professional-grade consistency.
The FDA's Standards of Identity for cream cheese and USDA dairy grading requirements shape formulation parameters and interstate commerce compliance for domestic producers. State-level cottage food laws and California's Proposition 65 labeling mandates create additional compliance layers affecting small-batch and regional manufacturers. Stakeholders must monitor evolving clean-label certification thresholds and dairy alternative labeling disputes that could reclassify plant-based cream cheese frosting products outside traditional regulatory frameworks.
Market Dynamics
Clean-label reformulations and precision fermentation are compressing formulation timelines while forcing dairy processors to eliminate artificial stabilizers from cream cheese bases used in frosting production.
Growth Catalysts
- Clean-label mandates:FDA scrutiny of artificial additives and USDA dairy grading requirements push manufacturers toward enzyme-modified processing and natural stabilizers.
- Food service expansion:National bakery chains scale dessert programs, creating pull-through demand for bagged frosting formats that reduce labor costs.
- Artisanal baking culture:Home baker preference for professional-grade spreadable variants drives retail premiumization in the United States.
Market Restraints
- Butterfat cost volatility:Cream cheese base production depends on fluid milk commodity markets, exposing margins to feed-price fluctuations and dairy herd cycles.
- Supply concentration risk:Domestic cream cheese processing clusters in Wisconsin and New York, creating geographic vulnerability to regional weather or logistics disruptions.
- Regulatory friction:California's Proposition 65 labeling mandates impose compliance costs on small-batch manufacturers shipping interstate.
Strategic Opportunities
- Plant-based white space:Dairy alternative labeling disputes create opening for oat- and cashew-based cream cheese frostings outside traditional FDA identity standards.
- Precision fermentation convergence:Combining microbial dairy protein production with traditional churning yields cost-competitive clean-label bases.
- Direct-to-foodservice channels:Frozen dessert distributors bypass retail brokerage, capturing margin from quick-service bakery chains.
Industry Challenges
- Emulsion stability expertise:Maintaining fat-in-water consistency across temperature fluctuations requires specialized food science talent scarce in regional bakeries.
- Clean-label certification timelines:Third-party non-GMO and organic validations delay product launches by six to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cream Cheese Frosting Market |
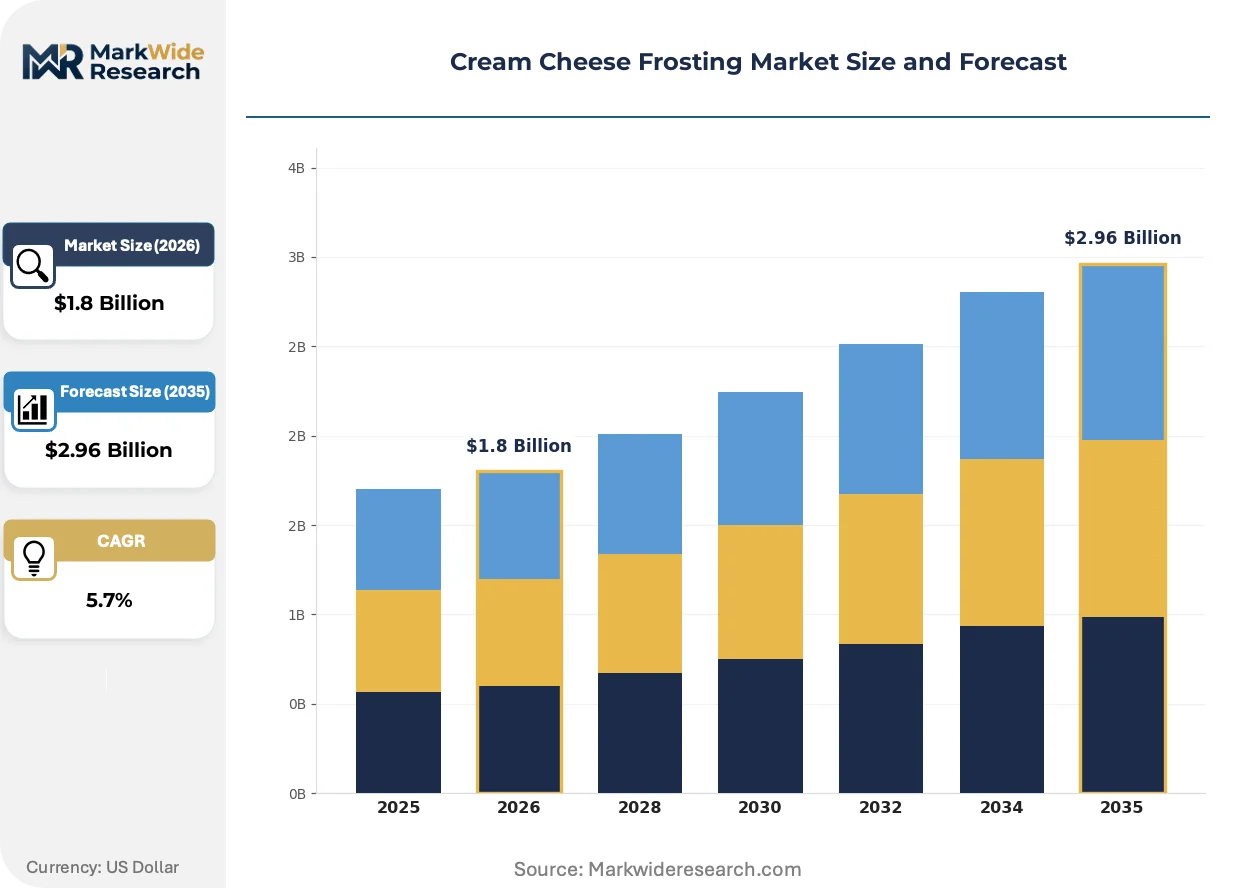
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whipped, Spreadable, Tub, Bagged Application: Baking, Dessert Topping, Dipping, Filling Packaging Type: Jar, Pouch, Container, Bottle End User: Bakeries, Restaurants, Home Bakers, Food Service |
| Companies Covered | Rich Products Corporation, Betty Crocker, CSM Bakery Solutions, Pinnacle Foods, Wilton Industries, Dawn Food Products, Lawrence Foods, Dixie's Icing, Macphie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cream Cheese Frosting Market Evolving Landscape
Formulation science and distribution architecture are undergoing simultaneous transformation as enzyme engineering and channel consolidation reshape how cream cheese frosting reaches end users.
Precision fermentation using microbial chassis is virtualizing traditional dairy processing by producing casein and whey proteins without herd infrastructure. Commercial bakeries adopt these bases rapidly for cost stability. The technology is virtualizing supply chain geography, enabling production facilities near urban demand centers rather than rural dairy belts.
REACH chemical registration requirements in Europe and evolving EPA environmental assessments in the United States tighten scrutiny on emulsifier chemistries. Manufacturers reformulate with lecithin and gum arabic to preempt regulatory action. Food service channels face the steepest compliance burden as they source across multiple jurisdictions.
Home bakers now favor single-serve portion packs over bulk tubs, compressing purchase cycles and elevating packaging costs as a share of product value. E-commerce subscription models displace supermarket center-store placement for premium spreadable lines. This behavioral shift concentrates in coastal United States metro areas where delivery density supports unit economics.
Cream Cheese Frosting Market Segmentation
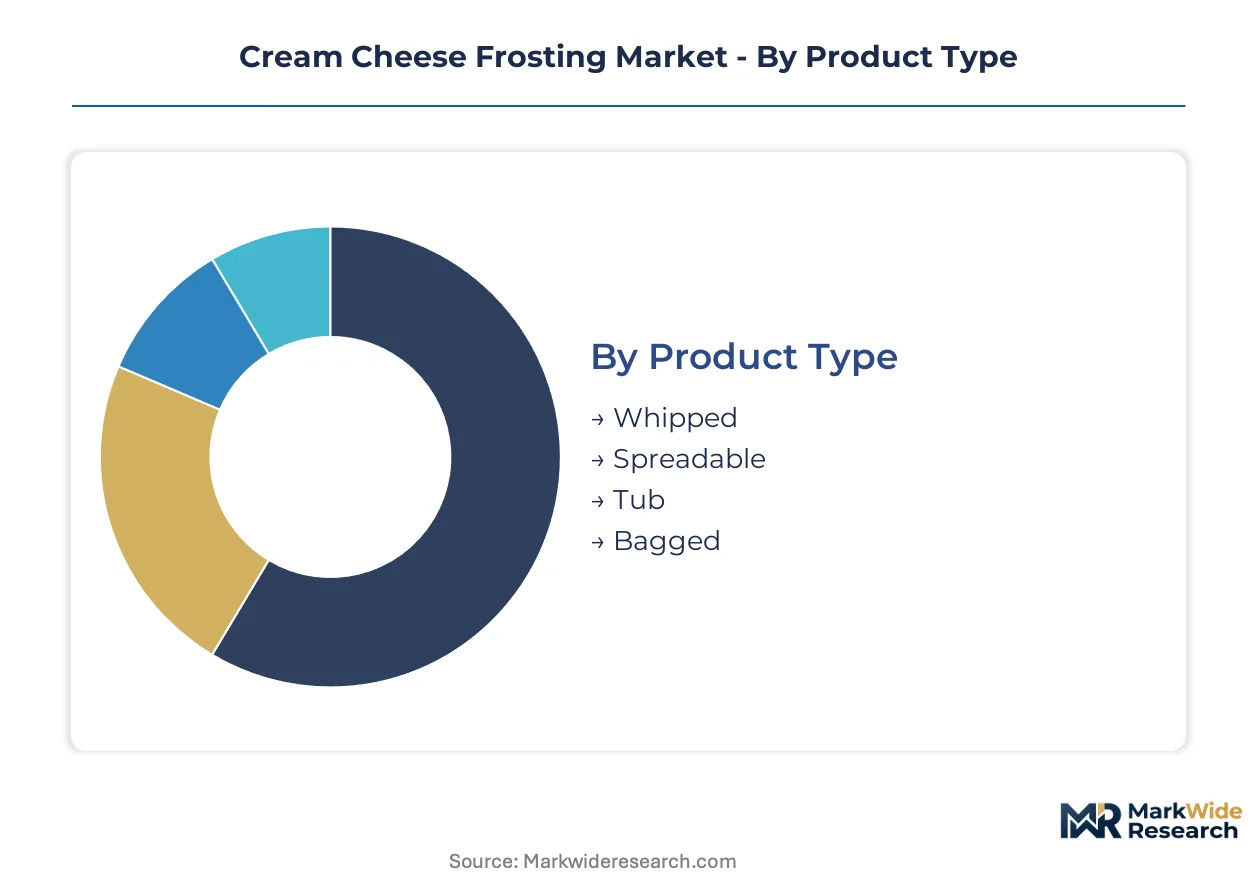
Cream cheese frosting formulation varies sharply across use cases, with viscosity requirements and shelf-stability demands dictating product architecture. Manufacturers configure emulsion density, aeration levels, and packaging formats to match specific channel economics and end-user workflows.
Product Type:
Cost tier determines manufacturing complexity and margin structure across these variants.
- Whipped:Aerated emulsion incorporating nitrogen or air injection reduces density to 0.45-0.55 g/ml, cutting per-unit ingredient costs for high-volume commercial bakeries. Demand concentrates in United States national bakery chains where portion standardization and labor reduction outweigh premium positioning.
- Spreadable:Higher butterfat content (minimum 33%) and reduced moisture yield dense, knife-friendly consistency prized by home bakers seeking professional-grade cake finishing. United States coastal metro areas drive retail premiumization through specialty grocers and direct-to-consumer channels.
- Tub:Bulk format for institutional food service requiring scoop-and-spread efficiency in high-throughput pastry operations.
- Bagged:Pre-portioned pillow packs reduce cross-contamination risk and enable precise dosing in quick-service bakery environments.
Whipped commands the established base. The steepest expansion runs through bagged formats as labor costs climb in food service channels.
Application:
Functional requirements around thermal stability and finish aesthetics segment demand by end-use workflow.
- Baking:Heat-stable formulations with modified starch systems prevent weeping and cracking during oven cycling. United States artisanal bakeries in Brooklyn and Austin drive specification tightening for cream cheese frostings that hold structural integrity across 350°F cake interiors.
- Dessert Topping:Lower viscosity variants with enhanced cold-temperature spreadability serve parfait and sundae assembly lines. European dessert café chains in France and Germany favor single-serve portion control for grab-and-go pastry cases.
- Dipping:Thickened bases with elevated acidity balance sweetness for fruit and pretzel pairing in United States convenience retail.
- Filling:High-solids emulsions resist moisture migration in layered cake applications for United Kingdom and Australian commercial bakeries.
Baking anchors volume concentration. The steepest expansion trajectory belongs to dessert topping as European café culture penetrates suburban United States markets.
Packaging Type:
Customer handling requirements and shelf-life extension needs shape material selection and format geometry.
- Jar:Wide-mouth glass or PET containers dominate United States retail home baking aisles, supporting repeated dip-and-scoop access over multi-week usage cycles.
- Pouch:Flexible film with fitment closures gains traction in European discount retail for space-efficient pantry storage and reduced shipping cube.
- Container:Tamper-evident tubs with resealable lids serve United States food service distributors supplying school and hospital cafeterias.
- Bottle:Squeeze formats with precision nozzles target decorating applications in Japanese and South Korean home baking segments.
Jar formats retain the consumer base. Pouch configurations are gaining share fastest through European private-label expansion.
End User:
Procurement scale and technical specification authority separate these demand pools.
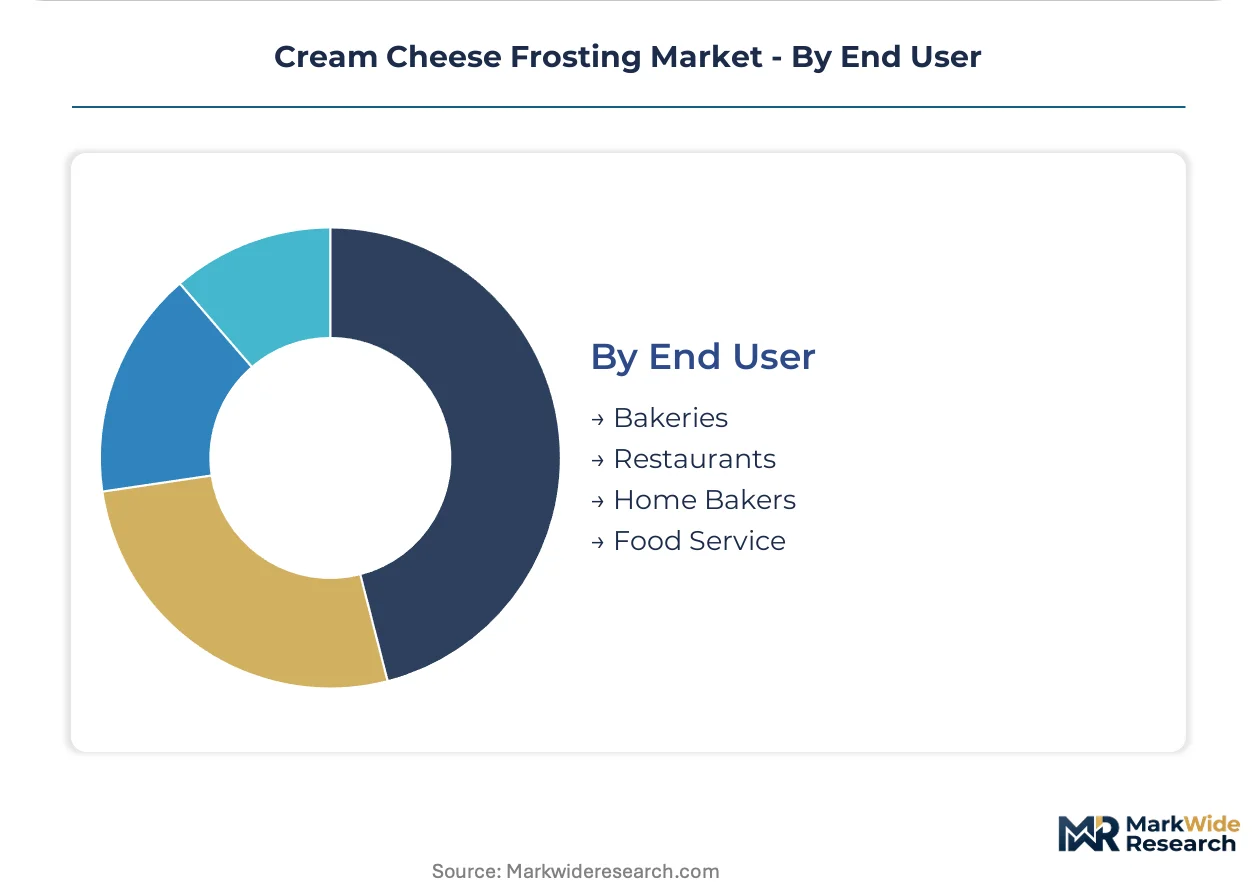
- Bakeries:Industrial-scale operations in Wisconsin and New York specify bulk tanker deliveries of cream cheese base with customized stabilizer packages for in-house frosting production.
- Restaurants:Full-service chains in California and Texas favor frozen pre-made frosting pucks for thaw-and-pipe dessert programs with minimal pastry labor.
- Home Bakers:Premium spreadable tub purchasers in United States coastal metros respond to social media recipe virality and subscription box curation.
- Food Service:Institutional contractors managing K-12 and corrections facilities in Florida and Ohio prioritize cost-stable whipped variants in portion-controlled pouches.
Bakeries anchor production volume. Food service channels are climbing the fastest as quick-service bakery chains scale nationally.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wisconsin cream cheese processors export bulk bases to United Kingdom and Australian commercial bakeries, establishing a transatlantic trade corridor that supplies industrial-scale frosting production across Commonwealth markets.
United States
Artisanal baking culture in Brooklyn and Austin drives specification tightening for heat-stable formulations. FDA Standards of Identity for cream cheese shape interstate commerce compliance. Wisconsin and New York dairy processing clusters concentrate domestic base production, with Philadelphia-area facilities supplying Northeast retail channels.
Germany
European dessert café chains in Berlin and Munich favor single-serve portion control for grab-and-go pastry cases. ECHA REACH chemical registration requirements tighten scrutiny on emulsifier chemistries. Bavarian dairy cooperatives reformulate with lecithin and gum arabic to preempt regulatory action.
United Kingdom
Commercial bakeries in London and Manchester specify high-solids emulsions for layered cake applications. Food Standards Agency labeling mandates align with evolving clean-label certification thresholds. Midlands industrial zones host regional distribution hubs supplying quick-service bakery chains.
Australia
Food service operators in Sydney and Melbourne prioritize bagged formats for labor reduction in high-throughput environments. Australian Competition and Consumer Commission dairy labeling standards affect import classification. Victorian dairy processing facilities expand capacity to serve Asia-Pacific export demand.
France
Premium spreadable variants gain traction among Parisian home bakers through specialty grocer channels. ANSM food additive oversight influences stabilizer selection in imported bases. Lyon-area food technology clusters develop enzyme-modified processing for clean-label reformulations.
Cream Cheese Frosting Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tiering. Consolidation concentrates among frozen dessert distributors and national bakery suppliers, while regional emulsion specialists retain niche positioning. Three archetypes dominate: integrated dairy processors with captive supply, frozen infrastructure operators leveraging cold-chain scale, and specialized stabilizer technology firms. Competitive moves center on backward integration into dairy sourcing and geographic expansion through direct-to-foodservice distribution.
Among integrated dairy processors, Rich Products Corporation and Dawn Food Products exemplify the frozen infrastructure archetype, leveraging cold-chain assets to supply scaled solutions. CSM Bakery Solutions occupies the specialized technology tier, representing emulsion science capabilities that extend shelf stability. These three entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Rich Products Corporation |
| Betty Crocker |
| CSM Bakery Solutions |
| Pinnacle Foods |
| Wilton Industries |
| Dawn Food Products |
| Lawrence Foods |
| Dixie's Icing |
| Macphie |
| Others |
Value Network & Pricing Analysis
Overcapacity in Wisconsin dairy processing facilities is compressing base ingredient margins while forcing regional suppliers toward volume-contract pricing with national bakery chains, simultaneously elevating butterfat cost pass-through sensitivity for smaller frosting manufacturers.
Pricing Analysis
Enzyme-modified processing technology commands a 15-20% premium over conventional stabilizer-based formulations, while precision fermentation-derived bases trade at mid-tier positioning and traditional artificial-stabilizer products face accelerating price erosion. Three-tier pricing structure across premium spreadable, standard whipped, and economy bagged levels stratifies by certification grade and volume scale. Pricing pressure stems from fluid milk commodity volatility, with commercial bakeries exhibiting highest price sensitivity due to thin dessert-program margins, while artisanal retail channels absorb premiums for clean-label positioning.
Supply Chain Analysis
Tariff exposure between United States and Canadian dairy markets dominates supply chain risk calculus for cross-border cream cheese base movements. Domestic production clusters in Wisconsin and New York, with secondary sourcing from Pennsylvania dairy cooperatives. Raw material dependencies center on fluid milk supply, butterfat fractions, and natural stabilizer inputs including lecithin and gum arabic. Single-source vulnerability concentrates in enzyme-modified processing capacity, where three suppliers control North American output. Distribution runs through frozen dessert infrastructure operators serving quick-service bakery chains and institutional food service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as clean-label certification requirements splinter demand into specialty tiers, creating defendable niches for regional emulsion specialists and precision fermentation entrants alongside integrated dairy processors.
For Market Incumbents: Pre-empt precision fermentation scale-up by securing exclusive supply agreements with microbial protein producers before cost curves flatten, while locking in long-term butterfat contracts to hedge against dairy herd cycle volatility. Rich Products Corporation and Dawn Food Products should deepen cold-chain density in Texas and Florida food service corridors to defend against frozen infrastructure challengers. For New Entrants and Emerging Players: Build out oat-based and cashew-based cream cheese frosting production capacity targeting California and New York metro areas where Proposition 65 labeling mandates and clean-label consumer preferences create regulatory moats against conventional dairy incumbents. Direct-to-consumer subscription models offer the most penetrable go-to-market angle for premium spreadable variants. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across precision fermentation sub-segments as microbial chassis optimization reduces bioreactor scale requirements. Five-to-ten-year viability favors acquisition targets possessing enzyme-modified processing patents or captive organic dairy supply. Signal to watch: FDA guidance on dairy alternative identity standards that would reclassify plant-based formulations outside traditional compliance frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dairy Sourcing | Captive cream cheese base supply secures margin stability against fluid milk price swings for integrated processors. |
| Precision Fermentation Scale-Up | Microbial casein production virtualizes geographic constraints, enabling urban production near coastal demand centers. |
| Clean-Label Certification Investment | USDA organic and non-GMO validations unlock premium positioning in Whole Foods and specialty grocer channels. |
| Direct-to-Foodservice Channel Expansion | Bypassing retail brokerage captures 12-15 point margin improvement from quick-service bakery chain contracts. |
| Plant-Based Formulation Development | Oat and cashew bases exploit FDA identity standard ambiguity to access vegan and lactose-intolerant consumer segments. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with dairy processing executives, food service procurement directors, bakery chain R&D leads, and stabilizer technology specialists; alongside secondary validation through FDA Standards of Identity filings, USDA dairy grading reports, state-level cottage food law databases, and trade flow records from Wisconsin and New York export authorities. Bottom-up volume modeling triangulated against top-down value estimates derived from channel-specific pricing benchmarks.
Forecast inputs include cream cheese base production capacity utilization, enzyme-modified processing adoption curves, and clean-label certification penetration rates across the analysis window. Segmentation dimensions modeled encompass product type, application workflow, packaging format, and end-user procurement scale. CAGRs were derived from logistic growth curve fitting to historical volume trajectories, incorporating butterfat price elasticity coefficients and food service channel expansion assumptions specific to quick-service bakery chain rollout schedules.
Stress conditions across fluid milk commodity volatility, precision fermentation regulatory reclassification, and California Proposition 65 enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about clean-label mandate timelines and dairy alternative labeling dispute resolutions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Bakery Conditioner Market
Bakery Products
Marzipan Market
Bakery Products
Bread Premix Market
Bakery Products
Bahrain Bakery Product Market
Bakery Products
No-Fat Cake Market
Bakery Products
Pastry Dough Market
Bakery Products
Global Wafer Biscuits Market
Bakery Products
Middle East and Africa Bakery Products Market
Bakery Products
South America Ice Cream Market
Bakery Products
Baking Mix, Base and Concentrate Market
Bakery Products
Pie Shells Market
Bakery Products
Frosting, Toppings, and Decorations Market
Bakery Products
Bakery Emulsions Market
Bakery Products
Low Calorie Rice Cake Market
Bakery Products
Low-Calorie Pie Market
Bakery Products
Gluten-Free Pizza Crust Market