
 Middle East and Africa Fortified Bakery Products Market | 2026-2036
Middle East and Africa Fortified Bakery Products Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Fortified Bakery Products Market Foresight
Premium micronutrient specification tiers is unwinding legacy commodity positioning across Middle East and Africa bakery shelves. Almarai leverages its integrated dairy-bakery supply chain to dominate Saudi Arabia's fortified bread segment. Britannia Industries anchors its competitive stance through deep distribution networks in East African cities. Mondelez International differentiates via protein-enriched biscuit formulations targeting Gulf urban consumers.
Fortified bakery products denote flour-based goods engineered with added vitamins, minerals, fiber, or protein at specified inclusion rates, typically produced through continuous mixing and thermal processing to preserve bioactive stability. These products serve commercial and institutional buyers seeking to address documented micronutrient gaps in populations consuming wheat-dominant diets. Breads lead volume throughput due to daily consumption frequency across North African households, while protein-fortified biscuits capture expanding margin pools in Gulf convenience retail. Fiber-enriched cakes represent the fastest-growing nutrition-type intersection as Egyptian and UAE catering services reformulate dessert menus for health-positioned hospitality contracts.
Gulf Standards Organization micronutrient thresholds and South Africa's Department of Health fortification mandates constrain import eligibility while creating compliance barriers for unregistered regional suppliers. Egypt's FSSAI-modeled food safety authority and Nigeria's NAFDAC enforce label-claim verification that shapes R&D allocation toward analytically demonstrable nutrient retention. Stakeholders must monitor evolving premarket notification pathways as Gulf regulators harmonize with Codex Alimentarius frameworks and East African Community states consolidate cross-border bakery standards.
Market Dynamics
School feeding mandates across South Africa and Nigeria are forcing industrial bakeries to reconfigure production lines for micronutrient stability at scale, compressing legacy commodity margins while creating compliance-driven volume anchors for fortified bread suppliers.
Growth Catalysts
- FSSAI-Aligned Fortification Mandates:Gulf Cooperation Council states have adopted micronutrient thresholds modeled on India's Food Safety and Standards Authority, compelling reformulation of wheat flour supplies entering institutional channels.
- Protein-Enriched Biscuit Demand:Urban convenience retail across Dubai, Riyadh, and Jeddah is expanding shelf space for high-protein bakery snacks targeting fitness-positioned consumers.
- Cairo-Alexandria Industrial Corridor:Egypt's concentrated bakery infrastructure enables centralized fortification at continuous mixing facilities serving North Africa's densest population belt.
Market Restraints
- Vitamin Premix Cost Volatility:Fortificant input costs fluctuate with global vitamin A and iron concentrate markets, squeezing margin structures for mid-scale Egyptian and Nigerian producers lacking captive blending capacity.
- Import Dependency for Enzyme Technologies:Gulf bakeries rely on European and Asian suppliers for heat-stable enzyme systems, exposing production schedules to shipping lane disruptions through the Red Sea corridor.
- NAFDAC Registration Timelines:Nigeria's national food and drug control agency enforces extended premarket verification cycles that delay product launches by 14-18 months for new fortified entrants.
Strategic Opportunities
- East African Community Harmonization:Cross-border bakery standard consolidation across Kenya, Tanzania, and Uganda creates pathway for single-sku regional distribution of vitamin-fortified breads.
- Fiber-Enriched Catering Contracts:Egyptian and UAE hospitality services are reformulating dessert menus for health-positioned hotel and airline contracts, opening premium positioning for fiber-fortified cake formulations.
- Codex Alignment in Gulf States:Gulf Standards Organization trajectory toward Codex Alimentarius frameworks will streamline export eligibility for compliant regional suppliers into wider MENA markets.
Industry Challenges
- Analytical Verification Capacity:Micronutrient retention testing requires LC-MS/MS equipment scarce outside Johannesburg, Cairo, and Dubai, forcing producers to ship samples across borders with 3-4 week turnaround delays.
- Thermal Processing Expertise Gap:Continuous mixing systems with inline fortificant dosing demand operators trained in both bakery engineering and food chemistry, a skill intersection underdeveloped in regional technical institutes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Fortified Bakery Products Market |
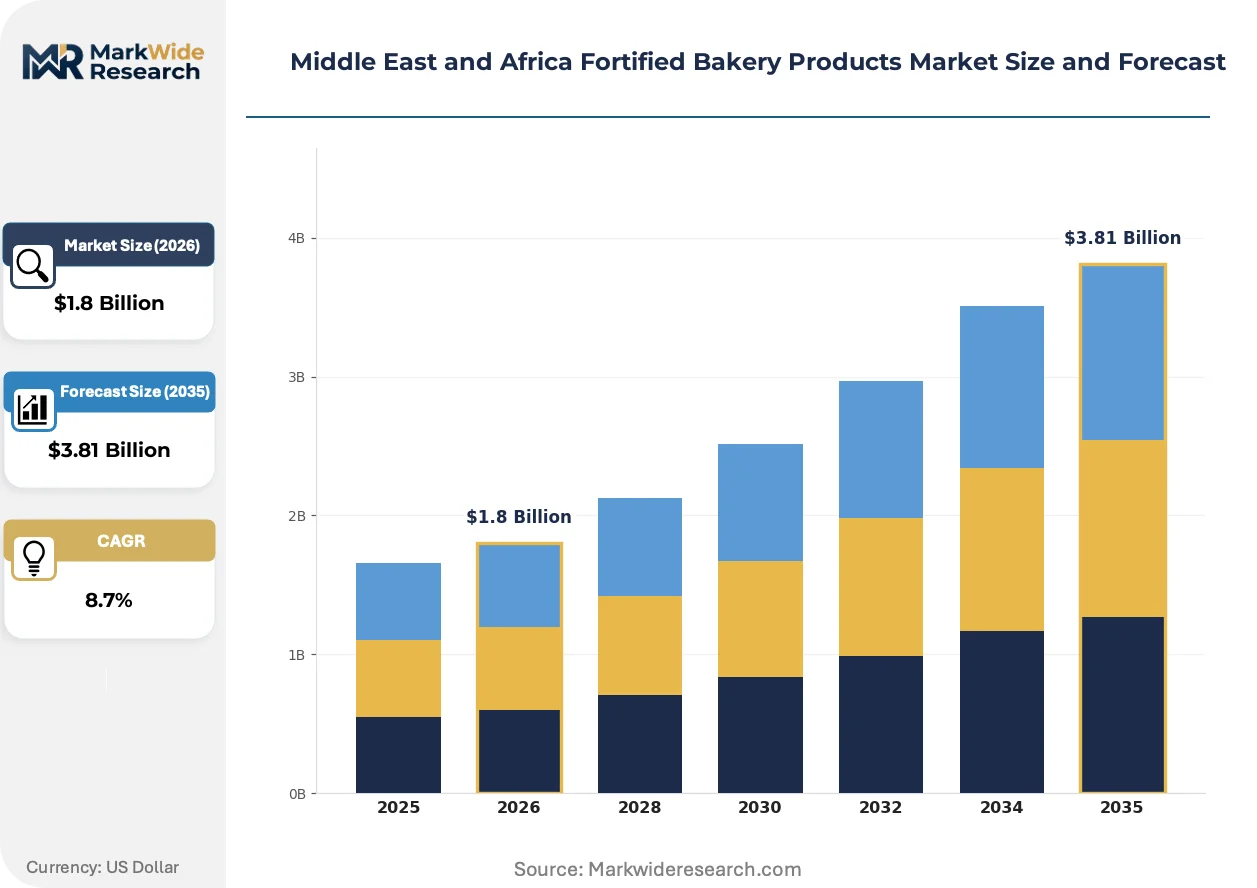
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breads, Buns, Biscuits, Cakes Nutrition Type: Vitamins, Minerals, Fiber, Protein Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale End User: Households, Restaurants, Cafes, Catering Services |
| Companies Covered | Associated British Foods plc, Barilla Holding S p A, Britannia Industries, Dawn Food Products Inc, General Mills Inc, Grupo Bimbo, Mondelez International Inc, Almarai, Nestlé, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Fortified Bakery Products Market Shifts & Advancements
Encapsulation technologies and precision dosing systems are compressing the cost-performance gap between artisan and industrial fortified production, while regulatory harmonization and procurement centralization reshape competitive entry barriers across the Middle East and Africa.
Microencapsulation of heat-labile vitamins using lipid-wall matrices is miniaturizing the fortification infrastructure required for bioactive stability. Small-scale urban bakeries in Lagos and Nairobi are adopting tabletop encapsulation units previously restricted to industrial continuous lines. This technology diffusion is eroding the volume advantage of centralized Egyptian and Saudi production facilities.
Gulf Standards Organization micronutrient thresholds are tightening alignment with Codex Alimentarius frameworks, forcing reformulation of legacy bread SKUs that predated 2019 fortification guidelines. Industrial bakeries in Saudi Arabia and Kuwait are responding by consolidating supplier relationships with premix houses capable of certificate-of-analysis documentation for every production batch.
Institutional procurement centralization is consolidating buyer power across South African school feeding programs and Nigerian federal nutrition initiatives. Tender specifications now mandate third-party micronutrient verification, displacing spot-market flour purchases with multi-year supply agreements tied to analytical compliance. This pattern concentrates volume with bakeries possessing in-house quality laboratories, visible most acutely in Gauteng province and Lagos State contract awards.
Middle East and Africa Fortified Bakery Products Market Segmentation
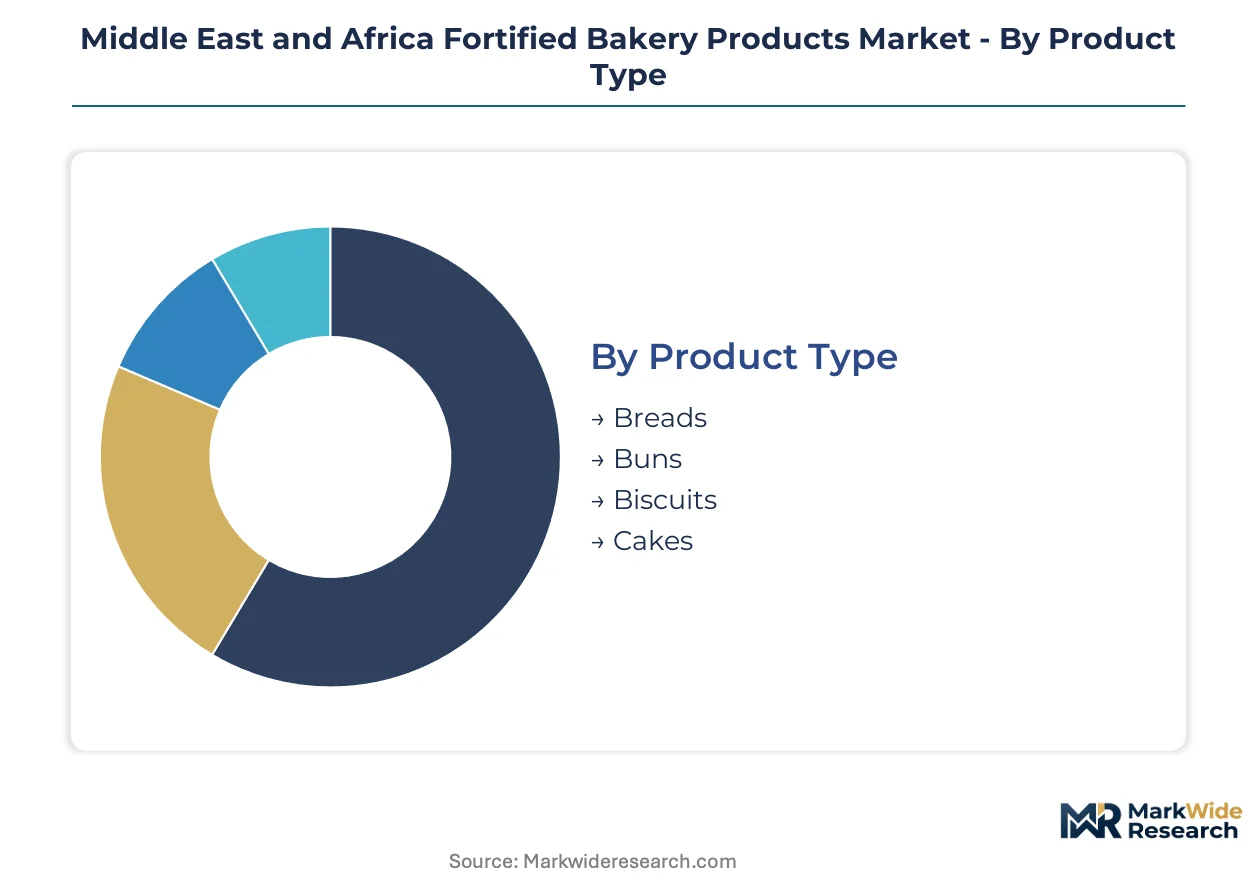
Segmentation in the Middle East and Africa fortified bakery market exposes divergent vulnerability to substitute threats. Unfortified artisan alternatives compete aggressively in household channels, while institutional buyers lock in fortified supply through multi-year procurement mandates.
Product Type:
Substitution pressure intensifies where daily consumption frequency meets low switching costs, forcing fortified variants to demonstrate measurable nutritional differentiation against commodity equivalents.
- Breads:Wheat-dominant loaves with specified vitamin A, iron, and folic acid inclusion rates anchor institutional procurement across South African school feeding programs and Nigerian federal nutrition initiatives. Cairo-Alexandria industrial bakeries scale continuous mixing output to serve North Africa's densest population belt, though vitamin premix cost volatility compresses margins for mid-scale producers lacking captive blending capacity.
- Biscuits:Protein-enriched formulations capture expanding shelf space in Dubai, Riyadh, and Jeddah convenience retail, targeting fitness-positioned urban consumers seeking portable nutrition. Heat-stable enzyme systems sourced from European and Asian suppliers expose production schedules to Red Sea shipping lane disruptions.
- Buns:Breakfast and snacking applications drive demand in Gulf urban centers, with FSSAI-aligned fortification mandates compelling reformulation of wheat flour supplies entering institutional channels.
- Cakes:Fiber-enriched variants represent the fastest-growing nutrition-type intersection as Egyptian and UAE catering services reformulate dessert menus for health-positioned hospitality contracts.
Breads retain volume leadership; cakes hold the steepest expansion curve.
Nutrition Type:
Cost tier stratification separates premium bioactive positioning from baseline compliance-grade fortification, with margin structures diverging sharply across premix sourcing strategies.
- Vitamins:Microencapsulation using lipid-wall matrices miniaturizes fortification infrastructure for bioactive stability, enabling small-scale urban bakeries in Lagos and Nairobi to adopt tabletop encapsulation units previously restricted to industrial continuous lines.
- Minerals:Iron and zinc concentrates face price volatility tied to global concentrate markets, squeezing producers without long-term supplier agreements or in-house analytical verification capacity.
- Fiber:Egyptian and UAE hospitality services drive reformulation of dessert menus for health-positioned hotel and airline contracts, opening premium positioning for fiber-fortified cake formulations.
- Protein:Urban convenience retail across Gulf cities expands shelf space for high-protein bakery snacks targeting fitness-positioned consumers.
Vitamins retain volume leadership; fiber holds the steepest expansion curve.
Distribution Channel:
Volume concentration favors channels with centralized procurement and analytical compliance infrastructure, disadvantaging fragmented retail without third-party verification capabilities.
- Supermarkets:Gulf retail chains consolidate shelf space for fortified bread SKUs compliant with tightened Gulf Standards Organization micronutrient thresholds, forcing reformulation of legacy products predating 2019 guidelines.
- Wholesale:Institutional procurement centralization across South African school feeding programs and Nigerian federal nutrition initiatives concentrates volume with bakeries possessing in-house quality laboratories, visible in Gauteng province and Lagos State contract awards.
- Convenience Stores:Protein-enriched biscuits capture expanding shelf space in Dubai, Riyadh, and Jeddah urban retail targeting fitness-positioned consumers.
- Online Retail:Direct-to-consumer channels enable niche positioning for specialty fortification blends, though cold-chain requirements for bioactive stability limit geographic reach.
Wholesale retains volume leadership; online retail holds the steepest expansion curve.
End User:
Customer type determines compliance burden intensity, with institutional buyers mandating certificate-of-analysis documentation that excludes artisan producers from tender participation.
- Households:Daily consumption frequency across North African households anchors bread volume throughput, though unfortified artisan alternatives compete aggressively on price in informal retail channels.
- Catering Services:Egyptian and UAE hospitality services reformulate dessert menus for health-positioned hotel and airline contracts, driving fiber-enriched cake demand.
- Restaurants:Menu differentiation strategies in Gulf urban centers incorporate protein-enriched biscuit offerings for health-conscious diners.
- Cafes:Premium positioning in Nairobi and Lagos urban centers favors specialty fortified buns targeting affluent consumers.
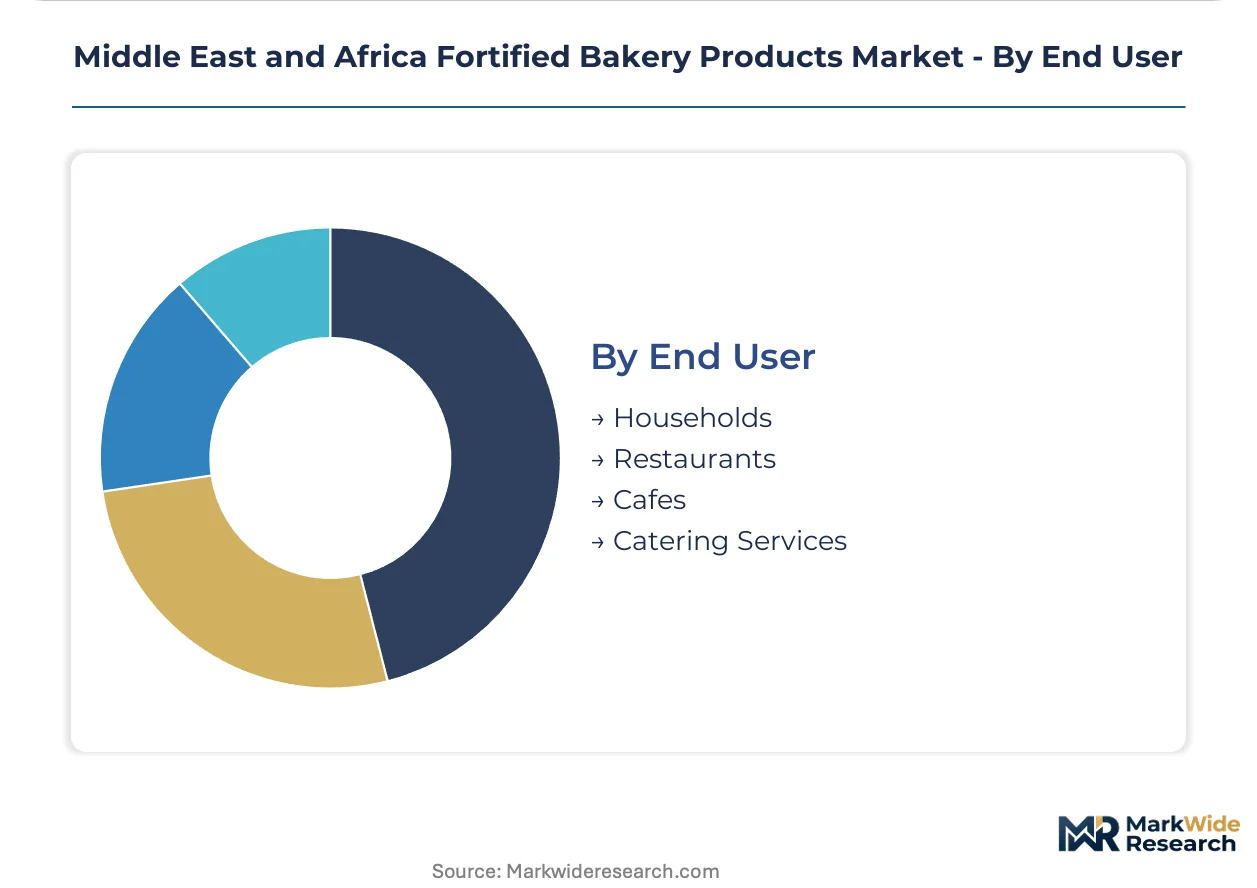
Households retain volume leadership; catering services hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial bakery infrastructure concentrates along Egypt's Cairo-Alexandria corridor and South Africa's Gauteng province, with Gulf states importing enzyme technologies and vitamin premixes through Red Sea shipping lanes. NAFDAC registration timelines and FSSAI-aligned fortification mandates reshape competitive entry across the region.
Saudi Arabia
School feeding programs and institutional procurement drive demand for vitamin-fortified breads in Riyadh and Jeddah. SFDA enforces micronutrient thresholds modeled on India's FSSAI standards, compelling reformulation of wheat flour supplies. Almarai leverages its integrated dairy-bakery supply chain to dominate the fortified bread segment through captive distribution networks.
Egypt
Daily bread consumption across Cairo-Alexandria households anchors volume throughput for industrial continuous mixing facilities. The country's FSSAI-modeled food safety authority enforces label-claim verification that shapes R&D allocation toward analytically demonstrable nutrient retention. Centralized fortification at continuous mixing facilities serves North Africa's densest population belt.
South Africa
The Department of Health fortification mandates constrain import eligibility while creating compliance barriers for unregistered regional suppliers. School feeding programs across Gauteng province force industrial bakeries to reconfigure production lines for micronutrient stability at scale. Tender specifications mandate third-party micronutrient verification, concentrating volume with bakeries possessing in-house quality laboratories.
Nigeria
Federal nutrition initiatives drive adoption of vitamin-fortified breads through institutional procurement centralization. NAFDAC enforces extended premarket verification cycles that delay product launches by 14-18 months for new fortified entrants. Lagos State contract awards favor suppliers with demonstrated analytical compliance and captive blending capacity.
United Arab Emirates
Urban convenience retail across Dubai and Abu Dhabi expands shelf space for protein-enriched biscuits targeting fitness-positioned consumers. MOHAP-aligned regulators harmonize with Gulf Standards Organization micronutrient thresholds. Hospitality services in Dubai reformulate dessert menus for health-positioned hotel and airline contracts, driving fiber-enriched cake demand.
Middle East and Africa Fortified Bakery Products Market Competitive Landscape
Concentration sits with diversified food conglomerates and regional dairy-bakery integrators that command institutional procurement channels and captive distribution infrastructure. Mid-scale producers lacking in-house analytical verification capacity face margin compression from vitamin premix cost volatility. Three archetypes dominate: multinational CPG houses with global premix sourcing agreements, regional dairy-bakery integrators with backward control over wheat milling, and specialist biscuit manufacturers targeting premium protein positioning. Competitive moves center on multi-year supply agreements tied to analytical compliance and consolidation of supplier relationships with certificate-of-analysis-capable premix houses.
Among multinational CPG houses, Mondelez International Inc and General Mills Inc exemplify scale-driven archetypes with global premix sourcing infrastructure. Britannia Industries occupies a position within the regional specialist tier, anchoring competitive stance through deep distribution networks in East African cities. Almarai represents the integrated dairy-bakery archetype, leveraging captive supply chain control to dominate Saudi Arabia's fortified bread segment.
| Leading Market Players |
|---|
| Associated British Foods plc |
| Barilla Holding S p A |
| Britannia Industries |
| Dawn Food Products Inc |
| General Mills Inc |
| Grupo Bimbo |
| Mondelez International Inc |
| Almarai |
| Nestlé |
| Others |
Supply & Pricing Matrix
Fourteen-to-eighteen-day vitamin premix lead times from European suppliers compress Egyptian and Nigerian producers' inventory flexibility, tethering pricing power to Red Sea shipping reliability and Gulf Standards Organization compliance certification tiers. This inventory constraint forces mid-scale bakeries into spot-market premix purchases while integrated players with captive blending capacity lock in contract premiums.
Pricing Analysis
Gulf Standards Organization micronutrient thresholds dictate the pricing tier structure across Middle East and Africa fortified bakery markets. Three-tier pricing structure across premium, standard, and economy levels separates certificate-of-analysis-backed institutional supply from unverified commodity flour. Price differentiation hinges on analytical verification capacity and FSSAI-aligned compliance grade. Cost compression in mid-scale Egyptian and Nigerian producer tiers is intensifying because vitamin A and iron concentrate markets fluctuate without long-term sourcing agreements. Institutional buyers in South African school feeding programs exhibit lowest price sensitivity due to tender-mandated quality floors, while informal household channels in Cairo-Alexandria remain most price-sensitive to unfortified artisan alternatives.
Supply Chain Analysis
Egypt and Saudi Arabia anchor industrial-scale fortified bread production through Cairo-Alexandria and Riyadh-Jeddah continuous mixing corridors. Production draws from European and Asian enzyme technology suppliers, Indian vitamin premix houses, and domestic wheat milling operations. Single-source vulnerability concentrates in heat-stable enzyme systems shipped through Red Sea lanes. Distribution runs through institutional procurement centralization in Gauteng province and Lagos State alongside Gulf retail chain consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward institutional procurement centralization across South African school feeding programs and Nigerian federal nutrition initiatives, consolidating tender participation around bakeries with in-house analytical laboratories.
For Market Incumbents: Consolidate supplier relationships with certificate-of-analysis-capable premix houses to defend against NAFDAC registration timeline delays and vitamin premix cost volatility. Backward integration into captive blending capacity in Egypt and Saudi Arabia secures margin structures against mid-scale competitor spot-market exposure. Lock in multi-year institutional supply agreements tied to third-party micronutrient verification before East African Community harmonization opens regional distribution pathways. For New Entrants and Emerging Players: Anchor in fiber-enriched cake formulations for Egyptian and UAE hospitality services, the fastest-growing nutrition-type intersection with premium positioning potential. Target Cairo-Alexandria industrial corridor infrastructure gaps where tabletop microencapsulation units enable small-scale urban bakery participation previously restricted to continuous mixing facilities. Pursue direct-to-consumer online retail channels for specialty fortification blends with cold-chain bioactive stability protocols. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates seeking to divest non-core bakery assets amid margin compression from regulatory compliance investments. Long-term viability centers on bakeries with demonstrated analytical verification capacity and institutional procurement channel lock-in. Monitor Gulf Standards Organization trajectory toward Codex Alimentarius frameworks as inflection indicator for export eligibility expansion into wider MENA markets.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Adoption | Tabletop lipid-wall matrix units enable Lagos and Nairobi urban bakeries to achieve bioactive stability without industrial continuous mixing infrastructure. |
| Multi-Year Institutional Supply Agreements | South African school feeding program tenders concentrate volume with Gauteng province bakeries possessing in-house LC-MS/MS verification capacity. |
| Premix House Consolidation | Certificate-of-analysis documentation for every production batch satisfies tightened Gulf Standards Organization post-2019 fortification guidelines. |
| Fiber-Enriched Catering Contract Pursuit | UAE hospitality services reformulating dessert menus for health-positioned hotel and airline contracts drive premium cake formulation demand. |
| East African Community Harmonization Positioning | Single-SKU regional distribution across Kenya, Tanzania, and Uganda awaits cross-border bakery standard consolidation completion. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with industrial bakery production managers, vitamin premix procurement leads, institutional feeding program contract officers, and Gulf retail chain category buyers. Secondary validation drew from NAFDAC registration databases, South African Department of Health fortification mandate filings, Gulf Standards Organization technical regulations, Egyptian FSSAI-modeled food safety authority guidelines, and customs records of enzyme technology imports. Bottom-up volume modeling triangulated against top-down expenditure flow analysis.
Across the analysis window, forecasting employed segmented modeling by product type, nutrition type, distribution channel, and end user with regional regulatory cluster overlays. CAGRs derived from trend extrapolation of institutional procurement centralization patterns, microencapsulation technology diffusion curves, and premix cost volatility indices. Industry-specific inputs included school feeding program enrollment trajectories, Red Sea shipping lane reliability assumptions, and hospitality services health-positioning contract award velocities.
Decision-makers should treat outputs as directional under stable Gulf regulatory alignment and premix supply continuity assumptions; material deviation in Red Sea logistics or Codex harmonization timelines would warrant model refresh. Recalibration cycles align with material shifts in institutional procurement tender specifications and micronutrient threshold regulatory updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
On-The-Go Breakfast Products Market
Bakery Products
Qatar Bakery Product Market
Bakery Products
Baking Mix, Base and Concentrate Market
Bakery Products
Pastries Market
Bakery Products
Marzipan Market
Bakery Products
Low Calorie Cake Market
Bakery Products
Bakery Premixes Market
Bakery Products
Gluten-Free Bread Market
Bakery Products
Bakery Improvers Market
Bakery Products
Bread Slicer Blades Market
Bakery Products
Cakes, Pastries, and Sweet Pies Market
Bakery Products
Bakery Flavors Market
Bakery Products
Gluten-Free Bakery Market
Bakery Products
Lentil Bread Market
Bakery Products
Muffins Market
Bakery Products
North America Fortified Bakery Products Market