
 Layer Cake Mixes Market | 2026-2036
Layer Cake Mixes Market Size, Share, and Industry Trends Forecast 2026-2036
Layer Cake Mixes Market Analytics
North American manufacturing expansion is rewriting competitive dynamics in prepared baking ingredients. General Mills Inc. leverages its Minneapolis-based R&D campus to sustain formulation leadership across chocolate and vanilla portfolios. Puratos Group anchors European supply through its Belgian innovation center, while Cargill competes via backward integration into specialty flours and cocoa processing. Associated British Foods controls retail placement density across UK and Irish grocery channels.
Layer cake mixes comprise pre-blended dry formulations of refined wheat flour, leavening agents, sugar, and flavor compounds requiring only liquid addition and thermal processing to produce stratified baked goods. Standard products target 350°F oven environments with 25-35 minute bake times, yielding consistent crumb structure for foodservice and home applications. Chocolate and vanilla variants occupy mature volume positions with stable margin profiles, while red velvet formulations generate premium price realization through cocoa alkalization and specialty colorant requirements. Pouch packaging is gaining fastest among format options as single-use portioning aligns with trial-sized purchasing behavior.
FDA nutritional labeling mandates and USDA organic certification standards shape permissible ingredient declarations and market access thresholds across domestic distribution. EFSA additive authorization frameworks and GB national food safety standards govern import eligibility for European and Chinese manufacturing origins respectively. Stakeholders must monitor evolving clean-label enforcement intensity and regional allergen disclosure harmonization to align portfolio investment with compliance-bound demand filtration.
Market Dynamics
Clean-label reformulations responding to FDA nutritional disclosure requirements are redirecting R&D spending across the layer cake mixes industry, compressing formulation cycles while elevating ingredient sourcing complexity for manufacturers.
Growth Catalysts
- Home baking resurgence:Convenience-seeking home cooks are expanding the buyer base as pouch packaging and single-use portioning align with trial-sized purchasing behavior in domestic kitchens.
- FDA nutritional transparency mandates:Disclosure requirements are accelerating clean-label portfolio redevelopment, creating first-mover advantages for manufacturers with compliant ingredient declarations already in market.
- Specialty flour backward integration:Cargill's captive supply of specialty wheat and cocoa processing assets is securing input cost stability for premium chocolate and red velvet formulations.
Market Restraints
- Cocoa alkalization cost volatility:Red velvet formulations depend on specialized cocoa processing that exposes margin profiles to commodity swings in West African supply origins.
- European supply concentration:Puratos Group's Belgian innovation center anchors regional formulation leadership, creating import dependency for North American manufacturers seeking European-developed emulsifier systems.
- USDA organic certification timelines:Multi-year transition periods for organic wheat sourcing are constraining rapid portfolio pivots toward certified-clean positioning.
Strategic Opportunities
- UK-Irish retail density control:Associated British Foods' established grocery channel presence offers template for premium private-label partnerships in underpenetrated convenience store networks.
- EFSA additive authorization harmonization:Converging European safety frameworks are reducing reformulation burdens for cross-border launches between Belgium, France, and Germany.
- Direct-to-consumer subscription channels:Home baker communities on social platforms are creating demand for limited-release flavor variants bypassing traditional retail slotting fee structures.
Industry Challenges
- Clean-label emulsifier substitution:Removing DATEM and SSL from standard formulations requires reformulation expertise currently concentrated in Minneapolis and Brussels R&D clusters.
- Legacy equipment thermal profiling:Foodservice accounts with fixed 350°F oven infrastructure limit bake-time flexibility for next-generation moisture-retention formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Layer Cake Mixes Market |
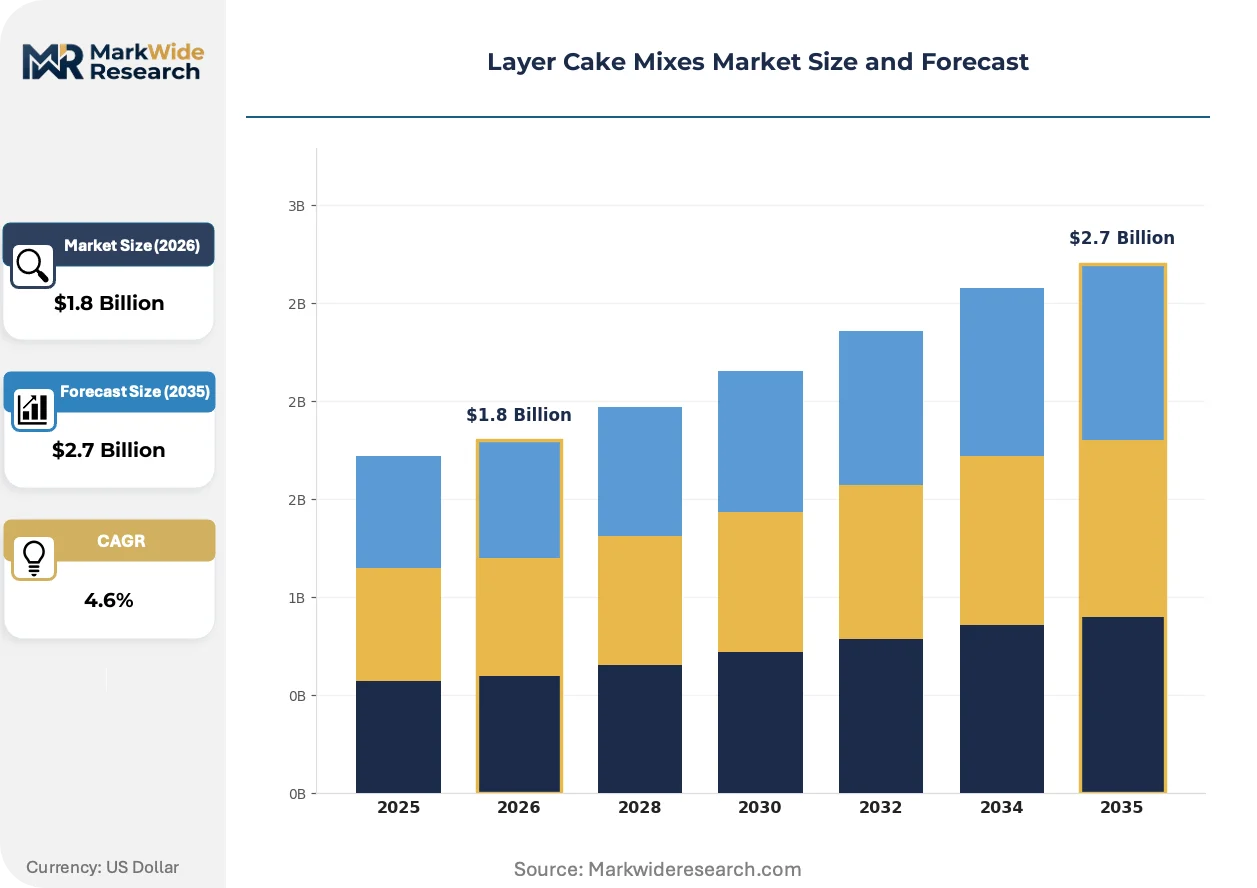
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate, Vanilla, Red Velvet, Lemon Packaging Type: Bags, Boxes, Jars, Pouches End User: Bakers, Restaurants, Retailers, Home Cooks Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | General Mills Inc., Conagra Brands Inc., Rich Products Corporation, ADM, Puratos Group, Associated British Foods, Dr. Oetker GmbH, Cargill, Dawn Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Layer Cake Mixes Market Evolving Landscape
Pouch packaging formats are compressing trial barriers while clean-label ingredient panels are becoming the primary purchase filter for home bakers. Formulation science is pivoting toward natural colorant systems that replicate synthetic visual performance.
Encapsulated leavening technology is migrating from traditional double-acting baking soda systems toward phosphate-free acidulant blends. Home bakers in premium supermarket channels are adopting these formulations at accelerating rates. The shift is compressing shelf-life extension capabilities while enabling cleaner ingredient declarations that satisfy FDA disclosure scrutiny.
EFSA additive authorization frameworks are tightening permissible emulsifier categories across European distribution. Industrial consequence includes accelerated R&D investment in enzyme-based dough conditioners. Red velvet and specialty chocolate portfolios face the steepest compliance timelines as cocoa alkalization agents undergo renewed toxicological review.
Single-use portioning is displacing bulk box formats in trial-driven purchase occasions. Convenience-oriented home bakers in US suburban markets are shifting toward pouch-based sampling before committing to standard-size boxes. This rotation is compressing average transaction values while expanding customer acquisition efficiency for premium-positioned portfolios.
Layer Cake Mixes Market Segmentation
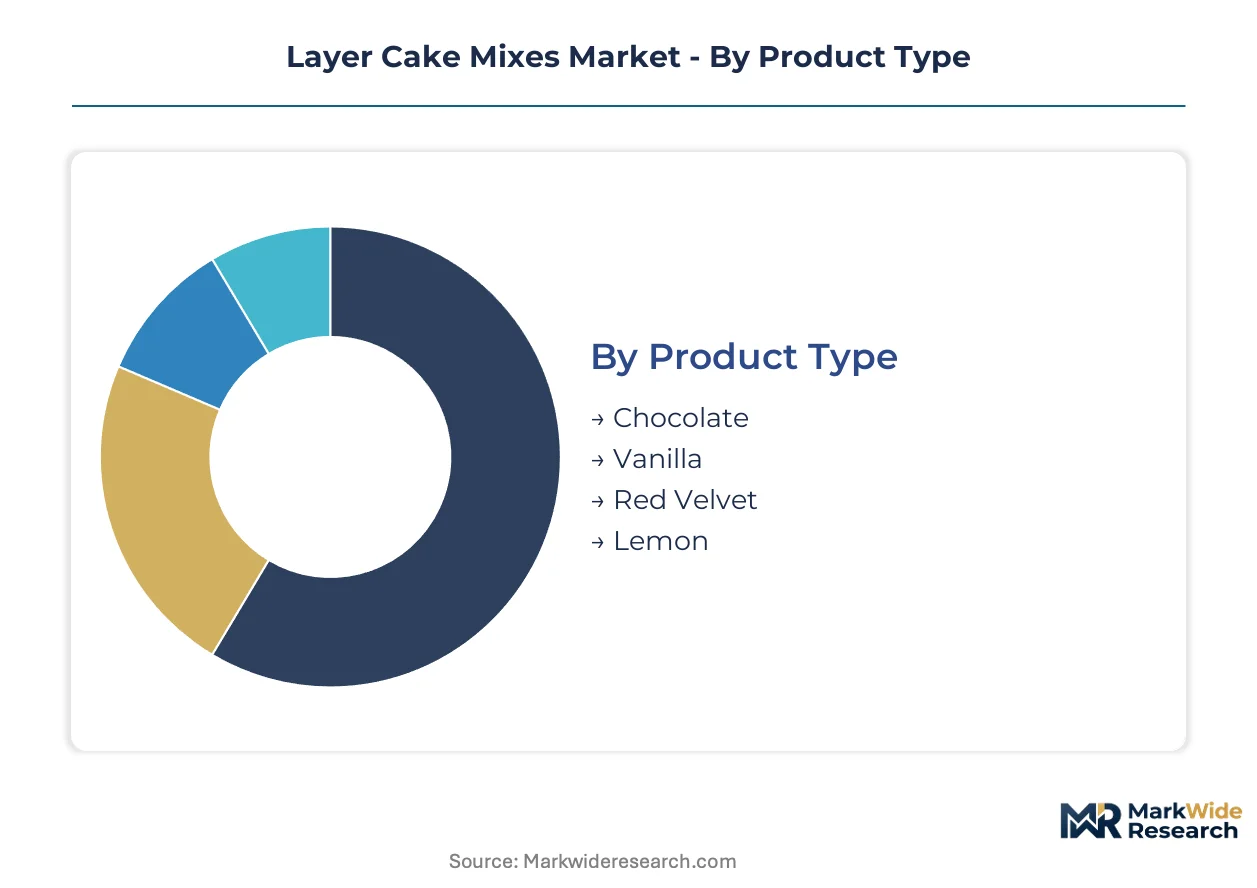
Segmentation in layer cake mixes determines formulation investment cycles and shelf-space economics. Product type and packaging format choices directly govern manufacturing asset utilization and margin capture across convenience-driven purchase occasions.
Product Type:
Chocolate and vanilla formulations turn inventory fastest through established household penetration, while red velvet and specialty variants cycle slower through premium-positioned channels.
- Chocolate:Cocoa-based formulations with alkalized powder requirements dominate volume throughput in US retail. Demand concentrates in suburban supermarket channels where General Mills and Cargill compete on back-of-package simplicity.
- Vanilla:Refined wheat flour bases with natural or artificial flavor systems sustain the broadest distribution footprint. Home cooks in Midwestern states drive repeat purchase frequency through familiar bake-time reliability.
- Red Velvet:Cocoa alkalization and specialty colorant requirements command premium price realization. Belgian emulsifier supply dependencies constrain rapid scale-up for North American manufacturers.
- Lemon:Citrus oil and acidulant blends target seasonal promotional windows. Limited-release positioning restricts year-round shelf allocation.
Chocolate dominates installed base. Red velvet is where expansion concentrates.
Packaging Type:
Cost tier separation runs from bulk institutional formats to single-serve convenience, with mid-tier box formats carrying the heaviest promotional investment.
- Pouches:Single-use portioning aligns with trial-sized purchasing behavior and social-platform recipe sharing. US suburban home bakers are shifting toward pouch-based sampling before committing to standard sizes.
- Boxes:Multi-serve cardboard formats sustain the deepest retail placement density. Supermarket slotting fee structures favor established box dimensions with proven scan velocity.
- Bags:Flexible film formats target foodservice scale with reduced unit economics. Restaurant supply distributors favor bagged formats for back-of-house storage efficiency.
- Jars:Reusable rigid containers command specialty store placement premiums. Limited production runs constrain geographic distribution breadth.
Boxes dominate installed base. Pouches are climbing the fastest.
End User:
Application requirements split between precision-dependent commercial baking and tolerance-flexible home preparation, with equipment constraints governing formulation specifications.
- Home Cooks:Convenience-seeking domestic bakers prioritize forgiving hydration ranges and consistent 350°F performance. FDA nutritional disclosure requirements are accelerating clean-label preference formation in this segment.
- Restaurants:Foodservice accounts demand batch-scalable formulations with fixed thermal profiling. Legacy oven infrastructure limits bake-time flexibility for moisture-retention innovations.
- Bakers:Commercial operations require extended shelf-life stability and bulk packaging efficiency. Puratos Group's Belgian emulsifier systems anchor supply relationships for European-origin bakeries.
- Retailers:Private-label programs seek formulation flexibility for channel-exclusive positioning. Associated British Foods' UK-Irish grocery density offers partnership templates.
Home cooks dominate installed base. Restaurants are gaining share fastest.
Distribution Channel:
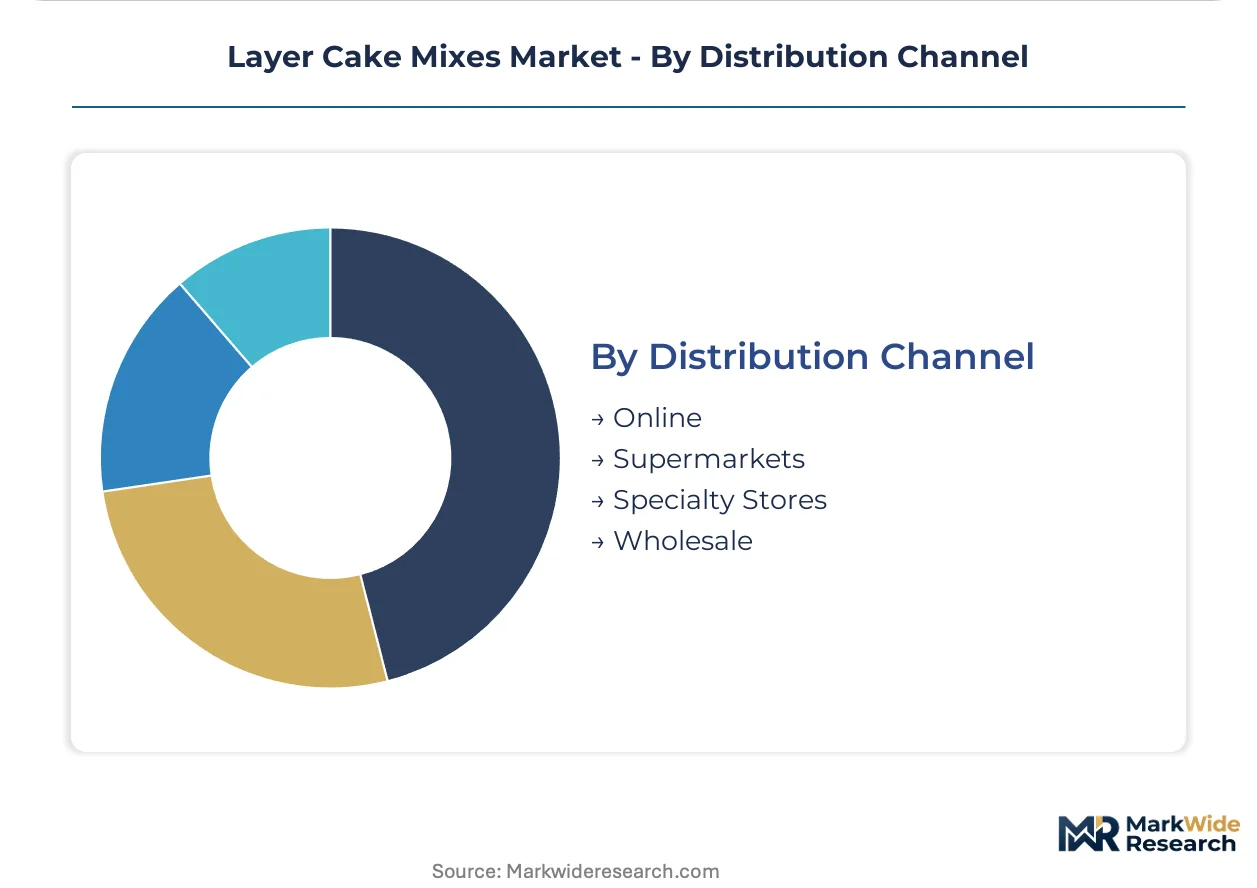
Channel concentration reflects geographic supply chain configuration, with wholesale and retail formats diverging on delivery frequency and promotional mechanics.
- Supermarkets:Primary volume channel with established planogram slots for chocolate and vanilla standards. Cargill's backward integration secures cost position for high-velocity SKUs.
- Online:Direct-to-consumer subscriptions bypass traditional slotting structures. Social-platform home baker communities drive limited-release flavor variant demand.
- Specialty Stores:Premium positioning for organic-certified and clean-label portfolios. USDA organic certification timelines constrain rapid private-label pivots.
- Wholesale:Foodservice and institutional volume through distributor networks. Associated British Foods' channel control offers margin protection.
Supermarkets dominate installed base. Online is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA nutritional disclosure requirements anchor demand formation in the United States, while EFSA additive frameworks and USDA organic certification standards shape parallel compliance pathways across Atlantic and domestic supply chains.
United States
Home baking convenience drives suburban supermarket velocity for chocolate and vanilla standards. FDA nutritional transparency mandates compress formulation cycles toward clean-label declarations. Minneapolis hosts General Mills' R&D campus, where phosphate-free acidulant blends are displacing legacy leavening systems.
Belgium
Premium red velvet formulations depend on specialized cocoa alkalization and European-developed emulsifier systems. EFSA tightening of permissible emulsifier categories accelerates enzyme-based dough conditioner investment. Brussels anchors Puratos Group's innovation center, securing regional formulation leadership for cross-border distribution.
Germany
Dr. Oetker GmbH's domestic manufacturing base sustains deep retail placement density for standardized vanilla portfolios. REACH chemical safety protocols govern colorant and flavor compound import eligibility. Baden-Württemberg's food processing corridor concentrates private-label formulation capacity for Central European markets.
United Kingdom
Associated British Foods controls grocery channel shelf allocation across UK and Irish convenience networks. GB national food safety standards filter import eligibility for non-European manufacturing origins. London and Southeast England concentrate premium organic-certified positioning for specialty store distribution.
Canada
Health Canada and PMRA pesticide residue standards constrain organic wheat sourcing timelines for certified-clean portfolio pivots. Cross-border supply integration with US Midwest grain corridors stabilizes input cost structures. Ontario's food manufacturing belt hosts secondary processing for pouch-format export to US markets.
Layer Cake Mixes Market Competitive Landscape
Multinational consumer packaged goods conglomerates and specialized baking ingredient suppliers split the market into consolidated volume leadership and niche premium positioning. Tiered competitive dynamics separate scale-driven supermarket slotting power from formulation-specialist technical differentiation. Two dominant archetypes prevail: backward-integrated agricultural processors with captive raw material supply, and R&D-intensive ingredient technology developers with emulsifier system expertise. Competitive moves concentrate on clean-label portfolio redevelopment and regional manufacturing footprint expansion to deflect tariff exposure.
Within the multinational packaged goods tier, General Mills Inc. and Conagra Brands Inc. exemplify scale-driven supermarket channel dominance through established chocolate and vanilla velocity. Puratos Group occupies a position as the European formulation technology anchor, with Belgian innovation infrastructure supporting emulsifier system development that North American competitors import. Cargill represents the backward-integrated agricultural processor archetype, with captive specialty flour and cocoa processing assets securing input cost stability for premium red velvet and chocolate formulations. Associated British Foods and Dr. Oetker GmbH sit within regional retail density specialists, leveraging UK-Irish and German grocery channel control respectively to defend shelf position against private-label encroachment.
| Leading Market Players |
|---|
| General Mills Inc. |
| Conagra Brands Inc. |
| Rich Products Corporation |
| ADM |
| Puratos Group |
| Associated British Foods |
| Dr. Oetker GmbH |
| Cargill |
| Dawn Foods |
| Others |
Value Network & Pricing Analysis
Minneapolis anchors North American formulation capacity where General Mills' R&D campus concentration translates to downstream pricing power for premium chocolate and vanilla portfolios. Belgian emulsifier supply dependencies for red velvet formulations create geographic price spreads that favor backward-integrated processors with captive cocoa alkalization assets.
Pricing Analysis
Geographic price spreads between US Midwest production and European-imported specialty formulations run 15-25 percent for red velvet variants. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified pouch formats from conventional box standards and foodservice bag volumes. Price differentiation hinges on clean-label certification grade and volume scale, with pouch single-serve formats commanding per-ounce premiums. Cost compression in standard chocolate and vanilla tiers is intensifying because Cargill's backward integration into specialty flours compresses input costs for high-velocity SKUs. Home cooks in suburban supermarket channels exhibit highest price sensitivity, while commercial bakeries sourcing through wholesale distributors show lowest elasticity due to formulation consistency requirements.
Supply Chain Analysis
Extended payment terms from Belgian emulsifier suppliers to North American manufacturers compress working capital cycles and elevate financing costs for premium portfolio expansion. Geographic supply concentration centers on the United States for wheat flour processing, Belgium for cocoa alkalization and emulsifier systems, and Germany for standardized vanilla formulations. Raw material dependencies rest on alkalized cocoa powder from West African origins, specialty wheat varieties from US Midwest grain corridors, and phosphate-free acidulant blends migrating from traditional leavening systems. Single-source vulnerability in Belgian emulsifier supply creates structural risk for red velvet scale-up. Distribution runs through supermarket slotting fee structures for retail velocity, with direct-to-consumer subscription channels bypassing traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits as a service-attach opportunity where formulation consulting and direct-to-consumer subscription layers expand faster than base mix volumes. Recurring revenue from clean-label certification support and social-platform recipe communities outpaces hardware-like box and pouch transactions.
For Market Incumbents: Entrench supermarket slotting power through exclusive clean-label pouch launches that preempt private-label encroachment. Deepen backward integration into organic wheat sourcing to compress USDA certification timelines and defend margin position against Cargill's captive supply advantages. Channel control in UK-Irish grocery networks offers template replication for North American convenience store penetration.
For New Entrants and Emerging Players: Establish a beachhead in direct-to-consumer subscription channels where social-platform home baker communities drive limited-release flavor variant demand. Underpenetrated specialty store placement for organic-certified portfolios offers white-space access with reduced slotting fee barriers. Go-to-market angle should center on phosphate-free acidulant blends with transparent supply chain storytelling.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because R&D-intensive emulsifier expertise concentrates in Minneapolis and Brussels clusters that resist rapid replication. Acquisition target archetype includes regional private-label formulators with established retailer relationships and pending clean-label certification. Signal to watch is FDA enforcement intensity on legacy additive disclosures that accelerates compliant portfolio premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | FDA disclosure mandates accelerate phosphate-free acidulant adoption across General Mills and Cargill portfolios. |
| Backward Integration | Cargill's captive specialty flour and cocoa processing assets secure input cost stability for premium formulations. |
| Direct-to-Consumer Launch | Subscription channels bypass supermarket slotting fees while capturing social-platform home baker community demand. |
| Distribution Channel Expansion | Associated British Foods' UK-Irish grocery density offers template for North American convenience store partnerships. |
| Sustainability Repositioning | USDA organic certification timelines constrain rapid pivots but command sustained shelf space premiums. |
Research Methodology
Initial hypotheses were tested against primary input from brand managers at CPG conglomerates, category buyers at supermarket chains, supply planners at foodservice distributors, and R&D directors at ingredient technology firms and refined through secondary validation. FDA nutritional labeling databases, USDA organic certification records, Nielsen retail audit data, and SEC 10-K filings from publicly traded manufacturers provided triangulation anchors. Bottom-up volume modeling from SKU-level retail velocity combined with top-down category spend analysis across the projection horizon.
Demand-supply-balance framing anchored the analytical framework throughout the modeling period. Segmentation dimensions included product type, packaging format, end-user application, and distribution channel, with regional regulatory cluster as an additional cross-cutting variable. CAGRs were derived from trend extrapolation of historical velocity patterns adjusted for clean-label adoption curves and pouch format penetration rates. Industry-specific forecast inputs incorporated cocoa alkalization cost volatility and EFSA additive authorization timelines.
Stress conditions across West African cocoa supply disruptions, FDA enforcement intensity variations, and organic wheat sourcing transition periods were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about clean-label preference formation and pouch format adoption rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Low-Calorie Toast Market
Bakery Products
Low Calorie Bread Market
Bakery Products
Global Bakery Product Market
Bakery Products
Flour Mixes Market
Bakery Products
Bread Market
Bakery Products
Instant Cake Gel Market
Bakery Products
South America Ice Cream Market
Bakery Products
Pastry Premixes Market
Bakery Products
Teaseed Cake Market
Bakery Products
Cream Cheese Frosting Market
Bakery Products
Cakes and Pastries Market
Bakery Products
Baking Molds and Trays Market
Bakery Products
Asia-Pacific Baked Food and Cereals Market
Bakery Products
Pizza Crust Market
Bakery Products
Dough Conveyor Market
Bakery Products
Southeast Asia Bakery Products Market