
 Bread Crumbs Market | 2026-2036
Bread Crumbs Market Size, Share, and Industry Trends Forecast 2026-2036
Bread Crumbs Market Outlook
The EU Green Deal is rebalancing ingredient sourcing priorities across European bread crumb supply chains, pushing manufacturers toward lower-carbon grain inputs and reduced processing waste. Newly Weds Foods leverages its vertical integration across milling and blending operations to control input costs. General Mills sustains broad retail distribution through its established shelf-stable portfolio. McCormick & Company differentiates via flavor-infused crumb varieties that command premium positioning in food service channels.
Bread crumbs consist of pulverized dried bread, typically processed to particle sizes between 0.5 and 4 millimeters, functioning primarily as adhesive coatings, texture modifiers, and moisture-retention agents in prepared foods. Dried bread crumbs dominate volume due to extended shelf stability and lower logistics costs, while Panko segments expand fastest in North American food service driven by fusion-menu proliferation. Food processing end users anchor the largest demand pool, though retail gluten-free crumb offerings are carving out higher-margin niches in specialty channels.
The FDA governs allergen labeling and GRAS status for breadcrumb additives in the United States, while the USDA oversees organic certification pathways for grain inputs. EFSA and national EU regulators enforce acrylamide thresholds and pesticide residue limits that constrain processing methods. Stakeholders must monitor evolving clean-label mandates and carbon-border adjustments that will reshape supplier qualification criteria and reformulation investments.
Market Dynamics
Clean-label mandates from EFSA and the FDA are forcing bread crumb manufacturers to strip artificial additives and simplify ingredient decks, compressing formulation flexibility while opening premium positioning for transparent supply chains.
Growth Catalysts
- EU Green Deal carbon-border adjustments:Lower-carbon grain sourcing protocols are qualifying European suppliers for preferential procurement by multinational food processors seeking Scope 3 reductions.
- Fusion-menu proliferation in food service:Panko-style Japanese bread crumbs are displacing conventional dried crumbs in North American quick-service coating applications.
- Gluten-free retail channel expansion:Specialty grocers are carving dedicated shelf space for allergen-free crumb alternatives, commanding price premiums over standard formulations.
Market Restraints
- Wheat price volatility:Input cost swings for hard red winter wheat constrain margin predictability for mid-sized milling operations without captive grain elevators.
- Acrylamide threshold enforcement:EFSA-mandated limits on Maillard reaction byproducts restrict high-temperature drying protocols, lengthening processing cycles.
- Alternative coating substitutes:Rice flour and cornmeal breading systems are capturing share in cost-sensitive institutional food service accounts.
Strategic Opportunities
- India food processing modernization:FSSAI-aligned cold chain investments are enabling crumb distribution to emerging quick-service networks in tier-2 cities.
- Flavor-infused premium segments:Herb and spice integration is creating differentiated positioning for food service distributors seeking menu differentiation.
- USDA organic certification pathways:Certified organic grain inputs are unlocking access to school nutrition and hospital procurement programs with strict ingredient standards.
Industry Challenges
- Acrylamide testing compliance timelines:Third-party laboratory validation for EFSA thresholds adds 6-8 weeks to new product launches.
- Legacy drying equipment retrofit costs:Converting conventional ovens to lower-temperature acrylamide-compliant systems demands capital outlays that strain regional processors.
- Cross-contamination control protocols:Gluten-free production lines require dedicated facilities or complex clean-down procedures that reduce effective capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bread Crumbs Market |
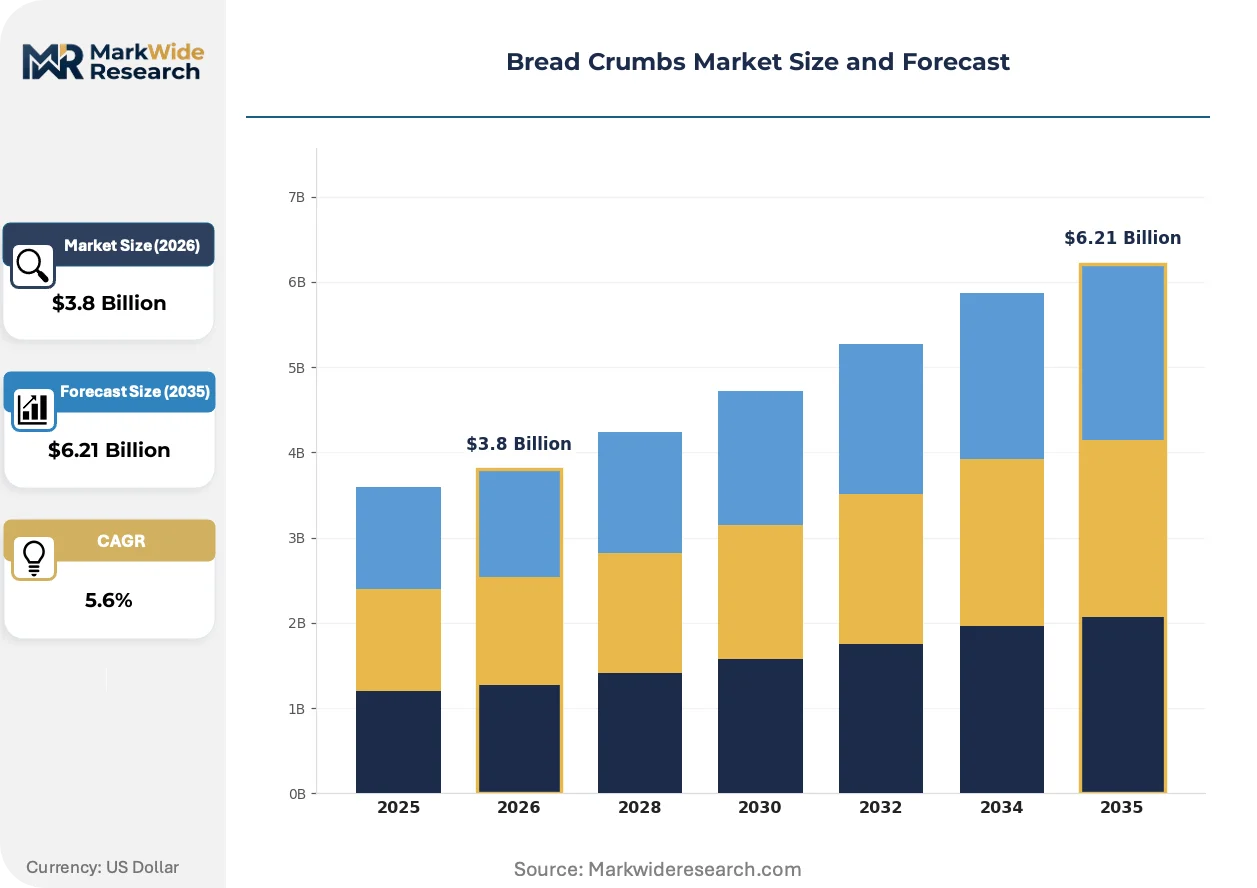
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Fresh, Dried, Panko, Gluten-Free Application: Coating, Fillings, Toppings, Breading End User: Food Service, Retail, Food Processing, Households Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Newly Weds Foods, General Mills, Kraft Heinz, McCormick & Company, Gonnella Baking Company, ConAgra Brands, Kikkoman Corporation, Hearthside Food Solutions, Associated British Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bread Crumbs Market Strategic Shifts
Processing technology convergence and regulatory chemistry constraints are reshaping how bread crumbs are formulated, dried, and positioned across retail and food service channels.
Advanced thermal profiling systems are unifying moisture control and browning management in a single processing stage. Food manufacturers in Japan and South Korea are adopting these integrated platforms to maintain Panko texture consistency while meeting acrylamide thresholds. The technology is unifying what were previously separate quality-control checkpoints, compressing capital requirements for mid-scale entrants.
EFSA's updated acrylamide benchmarks are tightening allowable levels in cereal-based foods including bread crumbs. European processors are reformulating with asparaginase enzymes and lower-temperature drying curves to maintain compliance. Italian and Spanish manufacturers are most exposed due to traditional high-heat processing methods inherited from regional bread-making heritage.
Quick-service restaurant chains are consolidating supplier bases around vertically integrated milling-blending operations capable of certifying full supply chain traceability. Distributor middlemen are losing share to direct procurement relationships in the United States, where McDonald's and Yum! Brands have implemented approved-supplier lists with audit requirements. This concentration is most visible in the American Midwest, where grain proximity advantages reinforce supplier lock-in.
Bread Crumbs Market Segmentation
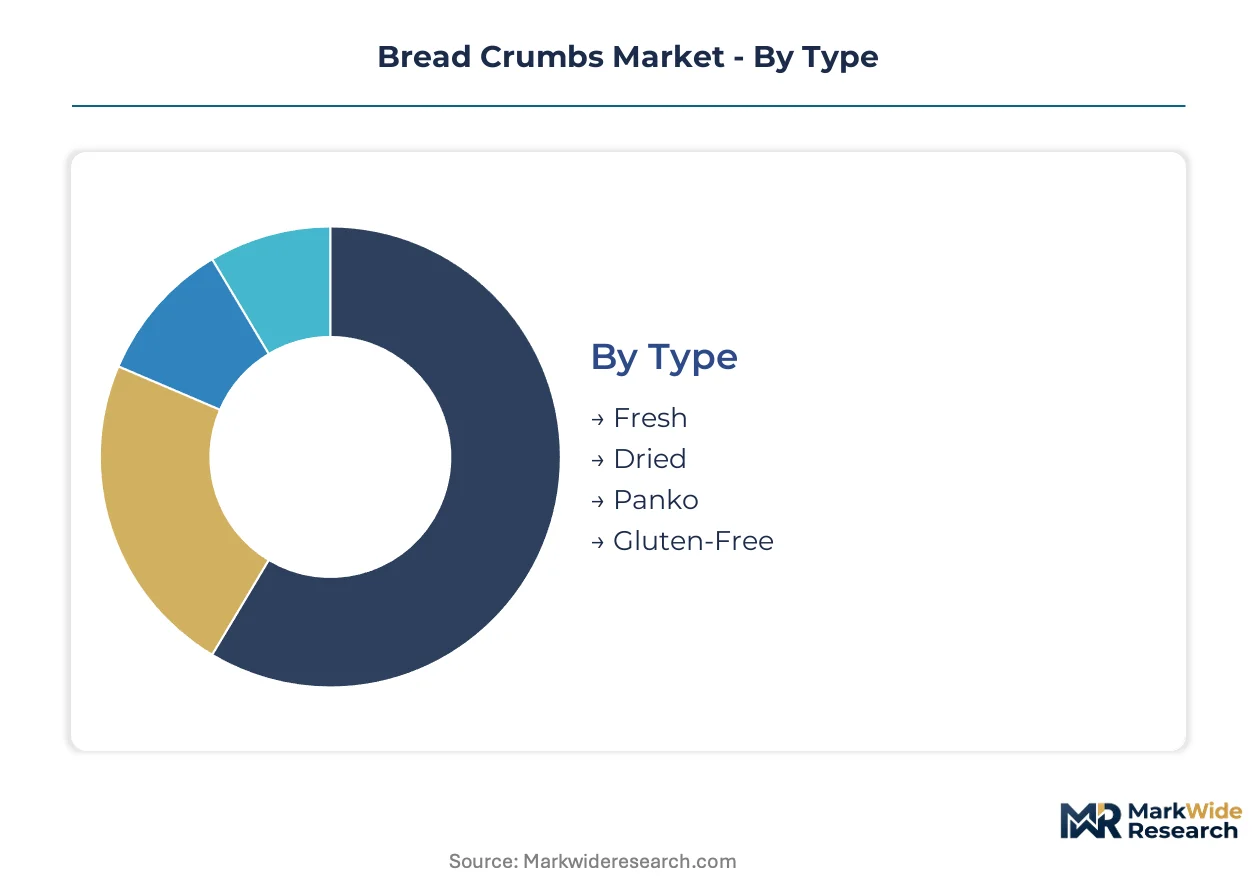
Bread crumb manufacturers navigate divergent certification burdens across type categories, with organic and allergen-free variants demanding USDA and FDA compliance that conventional dried products avoid. Segmentation strategy determines margin capture, as food service bulk contracts favor standardized dried formats while retail channels reward premium positioning through specialty certifications.
Type:
USDA organic certification and FDA allergen-labeling requirements split this category into regulated premium tiers versus conventional commodity production.
- Dried:Dehydrated to moisture levels below 7% for shelf stability extending 18-24 months. Quick-service restaurant chains in the United States drive bulk procurement of standardized particle sizes between 0.5 and 4 millimeters, though acrylamide threshold enforcement from EFSA and FDA constrains high-temperature drying protocols.
- Panko:Japanese-style flakes with larger, slivered particle geometry creating crispier coating textures. Fusion-menu proliferation across North American food service accounts accelerates displacement of conventional dried crumbs, particularly in chicken and seafood coating applications where texture differentiation commands supplier premiums.
- Fresh:Higher moisture content limits distribution radius to regional bakery networks without dehydration investment.
- Gluten-Free:Requires dedicated production lines and third-party validation to meet FDA 20ppm threshold standards.
Dried sits at the top of the volume ranking, with Panko climbing the fastest.
Application:
Cost tier stratification separates commodity coating applications from premium topping segments where ingredient visibility justifies higher price points.
- Coating:Adhesive breading for fried and baked proteins, constituting the largest functional demand pool. Food processing lines in the United States standardize around automated breading equipment calibrated to specific crumb flow characteristics, locking suppliers into long-term specification contracts.
- Breading:Pre-dust and final coating layers for frozen prepared foods, with EFSA acrylamide thresholds forcing reformulation of browning agents.
- Fillings:Moisture-retention and texture modification in processed meat and savory pastry applications.
- Toppings:Visual and textural finishing for casseroles and gratins, concentrated in retail premium positioning.
Coating dominates volume throughput, while Toppings gains share fastest through specialty retail channel expansion.
End User:
Customer type determines procurement scale and specification rigor, from institutional audit requirements to household convenience purchasing.
- Food Processing:Industrial-scale coating operations requiring certified supply chain traceability. Multinational quick-service networks in the United States consolidate approved-supplier lists with audit requirements, favoring vertically integrated milling-blending operations capable of documenting grain elevator-to-finished-product lineage.
- Food Service:Restaurant and catering operations purchasing through distributor networks or direct relationships.
- Retail:Packaged goods for consumer preparation, with gluten-free variants commanding shelf space premiums in specialty grocers.
- Households:Small-format convenience purchasing through online and supermarket channels.
Food Processing anchors absolute volume, with Retail expanding most quickly through allergen-free product line proliferation.
Distribution Channel:
Supply concentration varies sharply by channel, with wholesaler consolidation in food service contrasting fragmented specialty retail competition.
- Wholesalers:Bulk distribution to food service and processing accounts, where distributor middlemen lose share to direct procurement by quick-service chains implementing approved-supplier programs with full traceability mandates.
- Supermarkets:Mass retail placement for standard dried and Panko varieties, with shelf-stable formats dominating packaged goods aisles.
- Specialty Stores:Curated selection of organic, gluten-free, and imported Panko products targeting ingredient-conscious consumers.
- Online:Direct-to-consumer and B2B platforms expanding access for regional processors outside traditional distribution networks.
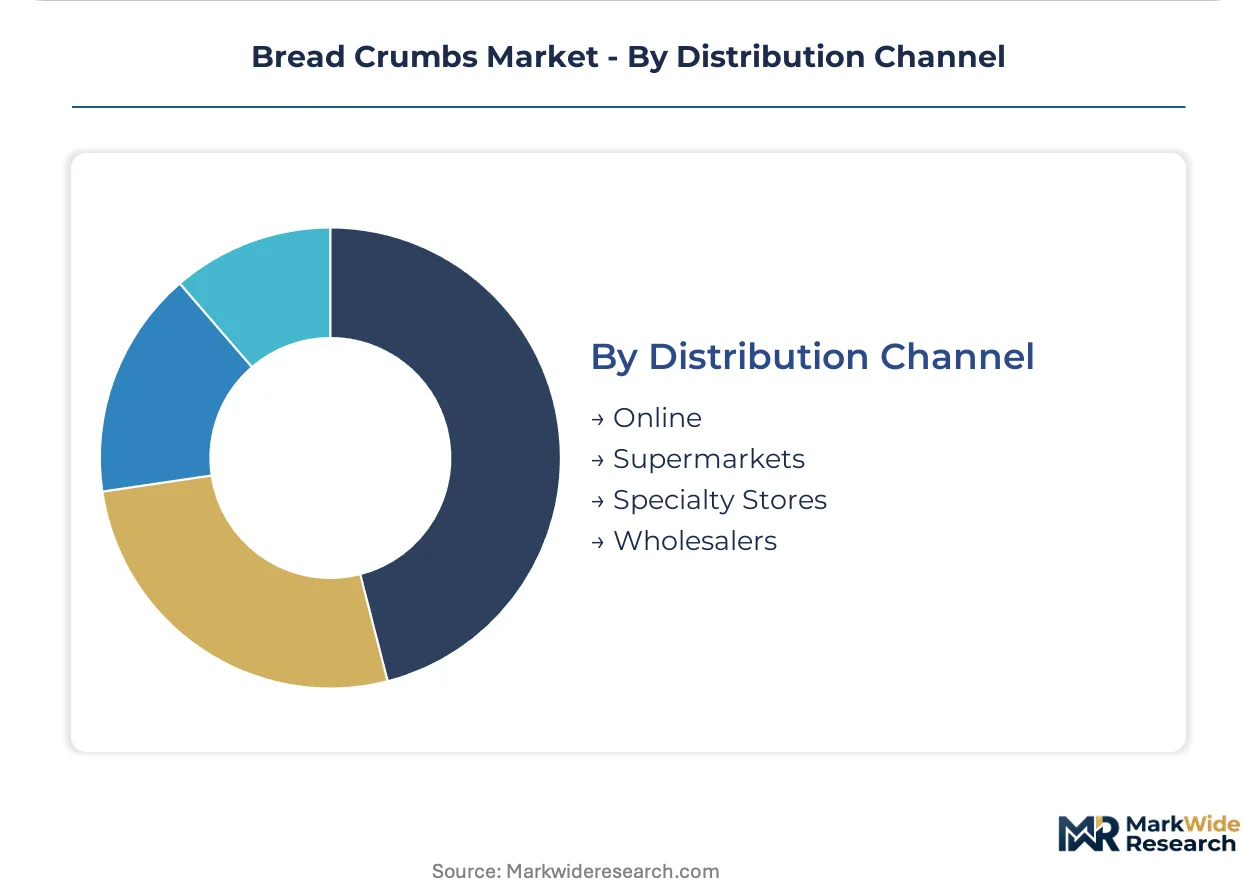
Wholesalers maintain volume leadership, with Online gaining traction fastest among small-batch artisanal suppliers bypassing conventional distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bread crumb manufacturing originated in industrial-scale European milling operations during the early twentieth century, with Italian and Spanish processors developing high-heat drying protocols that persist in regional heritage production today. This historical foundation established quality benchmarks that now collide with modern acrylamide regulations.
United States
Quick-service restaurant chains in the American Midwest drive bulk procurement of standardized dried crumbs, locking suppliers into long-term specification contracts. FDA allergen-labeling mandates and GRAS status requirements constrain formulation flexibility. Chicago and Minneapolis-St. Paul anchor vertically integrated milling-blending clusters where grain elevator proximity reinforces supplier consolidation.
Germany
Industrial bakeries supply food processors with precision-calibrated coating materials for frozen prepared foods. EFSA acrylamide thresholds and EU Green Deal carbon-border adjustments force reformulation investments and lower-carbon grain sourcing. The Bavarian and North Rhine-Westphalian industrial corridors host retrofitting programs for legacy drying equipment compliance.
Japan
Panko-style flake production serves domestic food service and export markets across Asia-Pacific fusion-menu networks. METI standards on food manufacturing equipment and JIS quality benchmarks govern texture consistency protocols. The Kanto region around Tokyo maintains integrated thermal profiling systems that unify moisture control with browning management.
India
Emerging quick-service networks in tier-2 cities expand distribution demand for shelf-stable coating materials. FSSAI-aligned cold chain investments enable crumb penetration beyond metropolitan centers. Maharashtra and Gujarat food processing zones attract modernization capital targeting institutional breading applications.
Italy
Traditional high-heat processing methods inherited from regional bread-making heritage face acute pressure from EFSA-mandated acrylamide limits. Reformulation with asparaginase enzymes and lower-temperature drying curves disrupts established production economics. Emilia-Romagna and Lombardy clusters retrofit conventional ovens to maintain EU market access.
Bread Crumbs Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification and flavor-infusion dimensions, with organic and allergen-free variants commanding supplier premiums while standardized dried formats compete on volume scale. The vendor base fragments between multinational milling conglomerates with captive grain supply and regional processors dependent on spot wheat markets. Three archetypes dominate: vertically integrated milling-blending operations, flavor-specialist innovators, and contract manufacturing specialists serving private-label retail. Competitive moves concentrate on backward integration into grain elevators and direct procurement relationships that displace distributor middlemen.
Among North American-based diversified food manufacturers, General Mills and ConAgra Brands occupy positions anchored by shelf-stable retail distribution infrastructure, while McCormick & Company exemplifies the flavor-infused premium archetype through spice integration capabilities. Newly Weds Foods represents vertically integrated milling-blending operations with cost-control advantages across input sourcing. These three players illustrate the structural tension between scale-driven commodity supply and differentiated positioning through formulation complexity.
| Leading Market Players |
|---|
| Newly Weds Foods |
| General Mills |
| Kraft Heinz |
| McCormick & Company |
| Gonnella Baking Company |
| ConAgra Brands |
| Kikkoman Corporation |
| Hearthside Food Solutions |
| Associated British Foods |
| Others |
Value Chain & Pricing Dynamics
Hard red winter wheat futures on the Chicago Board of Trade cascade through bread crumb supply chains, compressing margins for regional processors without captive grain elevators while concentrating pricing power among vertically integrated milling-blending operations in the American Midwest.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and volume scale. Organic and gluten-free variants command supplier premiums through USDA certification and dedicated production line investments, while commodity dried formats compete on throughput scale to quick-service chains. Cost compression in the standard tier intensifies because wheat price volatility and acrylamide compliance retrofit costs strain mid-sized regional processors. Institutional food service accounts exhibit the highest price sensitivity, whereas specialty retail channels absorb premium positioning for transparent supply chains.
Supply Chain Analysis
Wheat supply rests on agricultural output from the United States, Canada, and the Black Sea region, with hard red winter and spring wheat varieties serving as the primary starch inputs for crumb production. Asparaginase enzymes for acrylamide reduction and precision thermal profiling equipment constitute critical processing dependencies. Single-source vulnerability concentrates in specialized enzyme suppliers serving European reformulation mandates. Distribution runs through wholesaler networks facing displacement by direct procurement relationships from consolidated quick-service chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in bread crumb manufacturing hinges on backward integration into grain elevators and the accelerating premium-tier shift toward flavor-infused and certified-organic variants.
For Market Incumbents: Deepen upstream control over grain sourcing through elevator acquisitions in the American Midwest, locking in input cost predictability against wheat futures volatility. Fortify food processing segment positions by certifying full supply chain traceability for quick-service approved-supplier programs, displacing distributor-dependent competitors. Accelerate thermal profiling equipment deployment to compress acrylamide compliance timelines and defend against regional processors achieving regulatory parity. For New Entrants and Emerging Players: Precision fermentation-based alternative protein coating technologies offer a technology-first wedge into institutional food service accounts seeking to reduce wheat dependency. Target tier-2 Indian cities where FSSAI-aligned cold chain investments are enabling crumb distribution to emerging quick-service networks ahead of established multinational footprints. Lead with direct-to-food-service sales bypassing legacy distributor markups. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale flavor-specialist innovators possessing spice integration capabilities and existing food service channel relationships. Long-term viability over a multi-year horizon favors targets with demonstrated reformulation agility under tightening EFSA acrylamide thresholds. Watch for regulatory acceleration in carbon-border adjustments as the inflection indicator that revalues lower-carbon grain sourcing protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Elevators | Captive wheat supply from American Midwest elevators insulates margin against futures volatility. |
| Acrylamide-Compliant Thermal Profiling Deployment | Integrated moisture-browning systems from Japanese equipment suppliers compress EFSA validation timelines. |
| Flavor-Infused Premium Line Extension | Herb and spice integration creates differentiation for McCormick-caliber food service distributors. |
| USDA Organic Certification Pathway | Certified grain inputs unlock hospital and school nutrition procurement with strict ingredient standards. |
| Direct Procurement Relationship Establishment | Bypassing distributor middlemen captures margin from quick-service chains consolidating supplier bases. |
Study Parameters
Multiple input streams — milling operations executives, food service procurement directors, grain elevator operators, and specialty retail category buyers — were reconciled against customs records, USDA crop production reports, SEC 10-K filings from diversified food manufacturers, and EFSA regulatory guidance documents. Bottom-up volume modeling from individual processing facility capacities was triangulated against top-down demand estimates from quick-service chain breading specifications and retail scanner data.
Cross-referencing historical production trends against panel input from supply chain stakeholders shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include crumb type, application function, end-user category, and distribution channel, with regional regulatory cluster as an additional industry-specific dimension. CAGRs were derived from weighted average growth trajectories across these segments, incorporating wheat futures curve assumptions and food processing capacity expansion pipelines as forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA acrylamide threshold revisions, EU Green Deal carbon-border implementation timing, and wheat supply disruptions from Black Sea export volatility. Assumptions underlying projections reflect current regulatory trajectories and documented procurement consolidation trends. A small set of named triggers — regulatory acceleration, input cost spikes, and channel structure shifts — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Baking Molds and Trays Market
Bakery Products
Fondant Market
Bakery Products
Global Baked Food and Cereals Market
Bakery Products
Bread and Baked Food Market
Bakery Products
Cookies Market
Bakery Products
Baking Mats Market
Bakery Products
North America Gluten Free Bakery Mixes Market
Bakery Products
Bake Stable Pastry Fillings Market
Bakery Products
Bahrain Bakery Product Market
Bakery Products
United States Cookies Market
Bakery Products
No-Fat Cake Market
Bakery Products
Bread Market
Bakery Products
Bakery Mixes Market
Bakery Products
Lentil Bread Market
Bakery Products
Low Calorie Rice Cake Market
Bakery Products
Pizza Crust Mix Market