
 No-Fat Cake Market | 2026-2036
No-Fat Cake Market Size, Share, and Industry Trends Forecast 2026-2036
No-Fat Cake Market Foresight
FDA low-fat labeling certification is bifurcating competitive access in the no-fat cake sector. Smart Baking Company leverages its in-house R&D pipeline to sustain clean-label positioning across North American retail channels. General Mills anchors volume production through supermarket distribution networks, while Noshu Foods Pty Ltd differentiates via all-natural sweetener formulations in Australian and expanding export markets.
No-fat cake denotes baked desserts formulated with less than 0.5 grams fat per reference serving, typically achieved through fruit puree fat replacement, egg replacer emulsification, and modified starch structuring to maintain moisture and crumb stability. The primary commercial purpose is serving health-positioned retail and foodservice channels where consumers seek indulgence without dietary fat intake. Chocolate Cake and Vanilla Cake product types dominate current shelf space, though Carrot Cake variants are gaining traction among Fitness Enthusiasts seeking vegetable-forward ingredient narratives. Online Retail channels capture the fastest-growing transaction volume, while Specialty Bakeries retain margin concentration through premium pricing on whole-grain and all-natural sweetener formulations.
The FDA governs low-fat nutrient content claims under 21 CFR 101.62, directly shaping permissible marketing language and formulation thresholds. EFSA and FSSAI maintain parallel standards in Europe and India, creating compliance complexity for exporters seeking multi-territory positioning. Stakeholders must monitor evolving definitions of "low-fat" versus "fat-free" across jurisdictions, as regulatory divergence threatens to fragment formulation strategies and label architectures.
Market Dynamics
FDA low-fat labeling certification under 21 CFR 101.62 is bifurcating competitive access, forcing reformulation investments that separate clean-label specialists from conventional bakers unable to meet the 0.5-gram threshold.
Growth Catalysts
- Health-Conscious Consumer Demand:Fitness Enthusiasts and weight-management segments are pulling no-fat cake variants into mainstream retail channels previously dominated by conventional desserts.
- Modified Starch Structuring Technology:Advanced hydrocolloid and starch hybrid systems now replicate traditional fat-based mouthfeel, eliminating the primary sensory barrier to adoption.
- Fruit Puree Fat Replacement:Apple and prune puree formulations achieve moisture retention without lipid content, enabling clean-label positioning that commands premium shelf placement.
Market Restraints
- Ingredient Cost Volatility:Natural sweetener prices fluctuate with agricultural yields, compressing margins on all-natural formulations versus conventional sugar-based alternatives.
- Shelf Stability Limitations:Fat-free formulations exhibit shorter ambient shelf life due to reduced oxidative stability, constraining distribution radius and retail inventory turns.
- Regulatory Fragmentation:Divergent low-fat definitions between FDA, EFSA, and FSSAI force multi-territory producers to maintain parallel label architectures and formulation inventories.
Strategic Opportunities
- Online Retail Channel Expansion:Direct-to-consumer subscription models bypass conventional bakery distribution constraints, enabling national reach for regional specialty producers.
- Carrot Cake Variant Development:Vegetable-forward ingredient narratives attract Fitness Enthusiasts seeking functional food positioning beyond simple fat reduction claims.
- All-Natural Sweetener Convergence:Monk fruit and stevia blends paired with ancient grain flours create dual-claim products eligible for both organic and low-fat certification premiums.
Industry Challenges
- Clean-Label R&D Talent Scarcity:Formulation chemists capable of balancing sensory performance with zero-fat thresholds command premium compensation, constraining mid-tier producer innovation pipelines.
- Multi-Jurisdiction Compliance Timelines:Synchronized FDA, EFSA, and FSSAI approval cycles delay product launches by 12-18 months for exporters seeking unified global positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | No-Fat Cake Market |
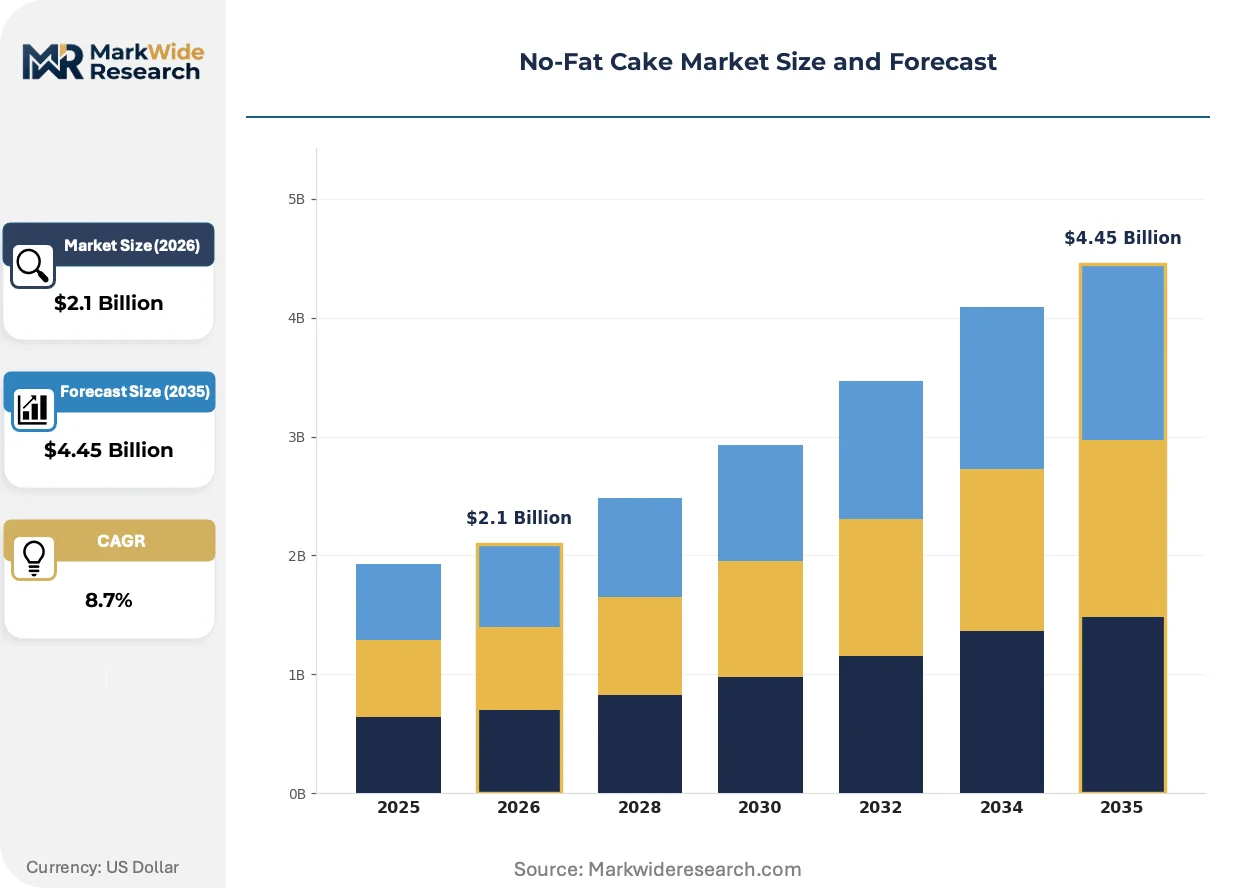
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate Cake, Vanilla Cake, Carrot Cake, Lemon Cake End User: Health-Conscious Consumers, Fitness Enthusiasts, Dietary Restriction Individuals, Busy Professionals Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Bakeries Ingredient Type: All-Natural Sweeteners, Fruit Purees, Egg Replacers, Whole Grains |
| Companies Covered | Love Kupcakes Inc., Smart Baking Company, Noshu Foods Pty Ltd, Monginis, Elite Sweets, General Mills, A Birthday Place, Wilton, Miss Cherry Dessert, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
No-Fat Cake Market Shifts & Advancements
Egg replacer emulsification systems are decomposing traditional bakery supply chains by enabling plant-based fat-free formulations that bypass conventional dairy and egg supplier relationships entirely.
Enzymatic fat mimetic technology is decomposing the texture-performance gap between no-fat and conventional cakes. Specialty bakeries in the United States are adopting these systems fastest, integrating them into premium whole-grain lines that justify price premiums through dual clean-label positioning. The structural consequence is compression of commodity baking margins as enzymatic solutions democratize previously proprietary texture science.
EFSA's evolving guidance on nutrient profile models is tightening permissible health claims across European retail channels. Reformulation costs are rising for exporters seeking CE-marked positioning, with chocolate cake variants facing particular scrutiny due to cocoa butter replacement complexity. German and French supermarket buyers are now demanding third-party validated fat-content testing before listing approval.
Direct subscription purchasing is displacing conventional wholesale bakery distribution for premium no-fat cake segments. Specialty food e-commerce platforms in the United States and Australia are capturing repeat purchase loyalty through personalized flavor rotation programs. This channel shift is most visible among Fitness Enthusiasts who prioritize ingredient transparency over immediate retail availability.
No-Fat Cake Market Segmentation
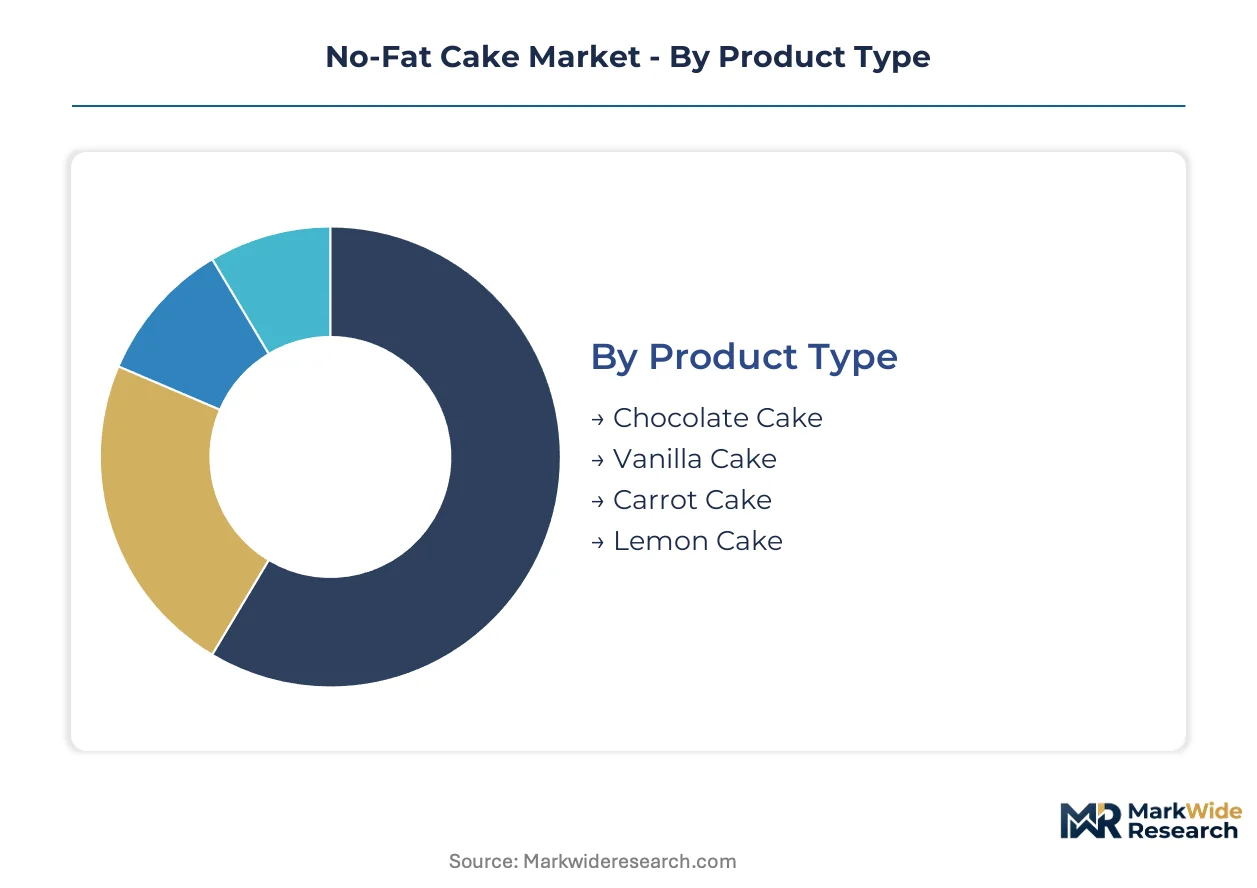
No-fat cake producers navigate four intersecting segmentation dimensions where substitution threats reshape portfolio priorities. Product type and distribution channel decisions determine which formulations survive direct competition from conventional desserts and alternative health snacks.
Product Type:
Substitution pressure from protein bars and fresh fruit bowls is strongest in chocolate and vanilla segments where taste expectations are highest.
- Chocolate Cake:Cocoa butter replacement demands enzymatic fat mimetic systems to replicate mouthfeel. United States specialty bakeries anchor premium positioning through single-origin cocoa sourcing that justifies price premiums despite zero-fat claims.
- Vanilla Cake:Vanilla bean extract and natural flavor carriers replace lipid-based flavor dispersion. Fitness Enthusiasts in Australian online retail channels drive repeat purchasing through subscription models emphasizing clean-label ingredient transparency.
- Carrot Cake:Vegetable-forward narratives attract wellness-positioned consumers seeking functional food credentials beyond simple fat reduction.
- Lemon Cake:Citrus acidity compensates for missing fat flavor carriers in lighter formulations targeting summer seasonal purchasing.
Chocolate Cake retains volume leadership; Carrot Cake holds the steepest expansion curve.
End User:
Cost tier stratification separates mass-market accessibility from premium specialization across consumer motivation types.
- Health-Conscious Consumers:Broad demographic seeking permissive indulgence without dietary compromise. United States supermarket channels capture this segment through price-competitive private label offerings that undercut specialty bakery premiums.
- Fitness Enthusiasts:Macro-tracking consumers prioritizing protein-carb-fat ratios over taste alone. Australian direct-to-consumer platforms dominate through personalized subscription rotations and detailed nutritional labeling.
- Dietary Restriction Individuals:Medical necessity drives loyalty to verified allergen-free production facilities with third-party certification.
- Busy Professionals:Convenience purchasing favors single-serve packaging in urban grab-and-go retail locations.
Health-Conscious Consumers generate the largest transaction base; Fitness Enthusiasts demonstrate the highest repurchase frequency and subscription attachment.
Distribution Channel:
Volume concentration in legacy retail constrains margin expansion while digital channels reshape geographic reach.
- Online Retail:Direct subscription models bypass wholesale bakery distribution constraints. United States specialty food e-commerce platforms capture national reach previously impossible for regional producers.
- Supermarkets:Shelf space competition from conventional desserts limits no-fat cake facings to health-aisle segregation. Volume throughput depends on promotional pricing cycles.
- Health Food Stores:Premium positioning through educated staff recommendation and co-located supplement sales.
- Specialty Bakeries:Highest margin capture through whole-grain and all-natural sweetener formulations with transparent production visibility.
Supermarkets move the highest unit volumes; Online Retail is climbing the fastest with direct subscription attachment rates.
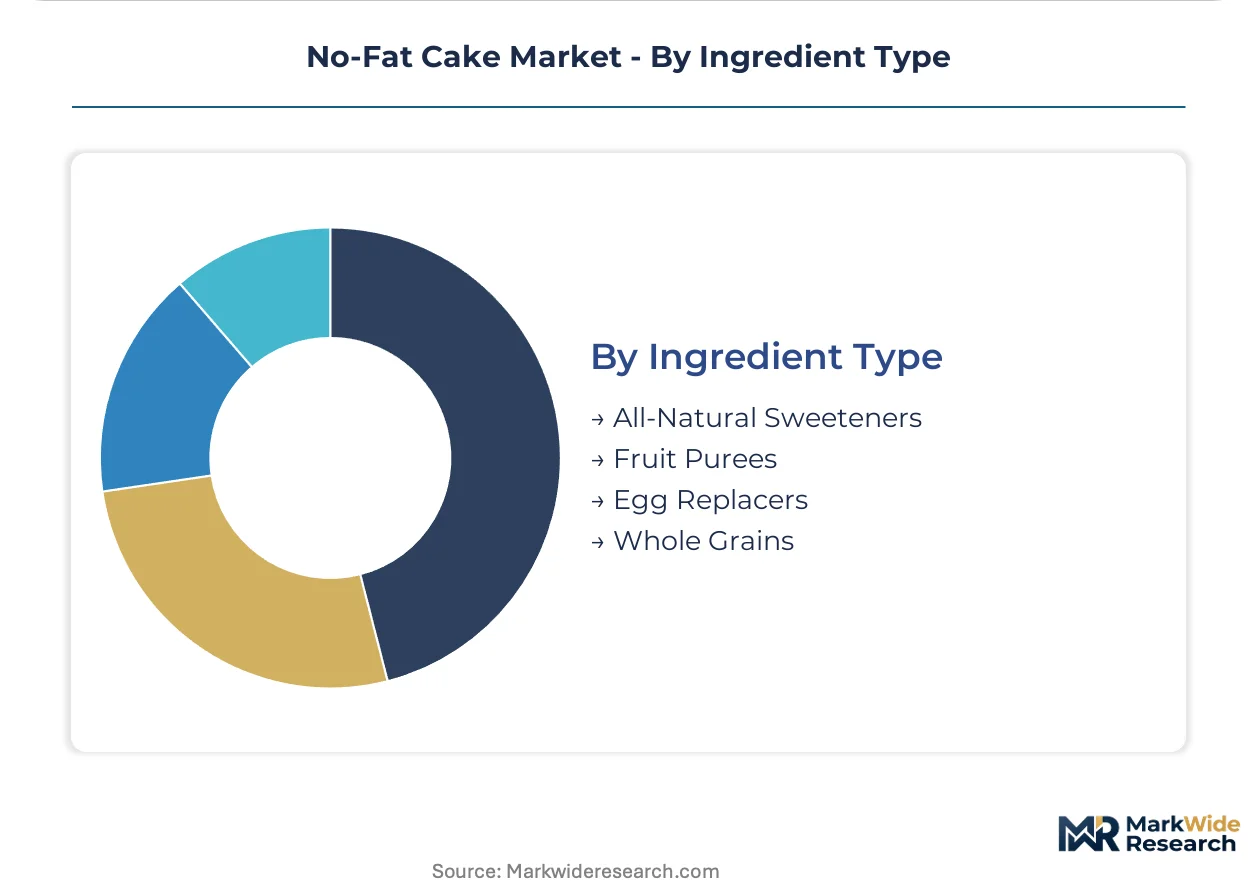
Ingredient Type:
Supply concentration in natural sweetener agriculture creates input cost volatility that fragments formulation strategies.
- All-Natural Sweeteners:Monk fruit and stevia blends enable dual organic-low-fat certification premiums. Indian FSSAI import regulations constrain supply chain flexibility for exporters seeking multi-territory positioning.
- Fruit Purees:Apple and prune formulations achieve moisture retention without lipid content. United States clean-label specialists leverage domestic orchard supply contracts for cost stability.
- Egg Replacers:Plant-based emulsification systems decompose traditional dairy-egg supplier relationships entirely.
- Whole Grains:Ancient grain flours create texture differentiation that commands specialty bakery price premiums.
Fruit Purees retain formulation prevalence across mass-market production; All-Natural Sweeteners are gaining share fastest as certification premiums expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach handles containerized food ingredients that supply California's specialty bakery cluster, anchoring North American distribution for no-fat cake formulations. This infrastructure underwrites the United States' position as the primary demand center for health-positioned desserts.
United States
Fitness Enthusiasts in urban coastal markets drive subscription-based purchasing through direct-to-consumer platforms. FDA enforcement of 21 CFR 101.62 low-fat labeling thresholds forces reformulation investments that separate compliant specialists from conventional bakers. Los Angeles and San Diego host the densest concentration of clean-label specialty bakeries leveraging California's agricultural supply chain for fruit puree inputs.
Germany
EFSA's tightening nutrient profile models constrain permissible health claims on chocolate cake variants, elevating compliance costs for exporters. German supermarket buyers now mandate third-party validated fat-content testing before listing approval. The Rhine-Ruhr metropolitan region concentrates industrial baking R&D facilities adapting enzymatic fat mimetic systems for European palate preferences.
Australia
Online retail channels capture the fastest-growing transaction volume as Melbourne and Sydney consumers prioritize ingredient transparency over immediate retail availability. FSSAI import regulations on natural sweeteners create supply chain friction for producers seeking multi-territory positioning. Noshu Foods exemplifies the plant-based formulation archetype dominating domestic premium positioning.
India
Health-Conscious Consumers in Mumbai and Delhi generate emerging demand for permissive indulgence without dietary compromise. FSSAI maintains parallel low-fat standards to FDA thresholds, though enforcement consistency varies across state-level food safety departments. Maharashtra's industrial corridor attracts contract manufacturing investment targeting both domestic retail and Middle East export markets.
United Kingdom
Specialty bakeries in London retain margin concentration through premium pricing on whole-grain and all-natural sweetener formulations. Post-Brexit regulatory divergence from EFSA guidance creates label architecture complexity for pan-European exporters. The Greater Southeast cluster integrates direct subscription fulfillment infrastructure bypassing conventional wholesale distribution constraints.
No-Fat Cake Market Competitive Landscape
Listed leaders compete with private specialists across formulation certification and channel access dimensions. The vendor base stratifies into three tiers: multinational CPG conglomerates with supermarket network dominance, mid-cap clean-label specialists with in-house R&D pipelines, and regional craft bakeries with localized production visibility. Strategic moves concentrate on M&A absorption of formulation talent and capacity expansion into direct-to-consumer fulfillment infrastructure.
Within the clean-label specialist tier, Smart Baking Company and Noshu Foods occupy positions exemplifying divergent geographic strategies—North American retail channel penetration versus Australian domestic anchoring with export expansion. General Mills represents the scale-driven conglomerate archetype, leveraging existing supermarket relationships to anchor volume production. Love Kupcakes Inc. sits within the regional craft segment where production visibility and localized ingredient sourcing command premium pricing power.
| Leading Market Players |
|---|
| Love Kupcakes Inc. |
| Smart Baking Company |
| Noshu Foods Pty Ltd |
| Monginis |
| Elite Sweets |
| General Mills |
| A Birthday Place |
| Wilton |
| Miss Cherry Dessert |
| Others |
Supply & Pricing Matrix
FDA low-fat labeling certification under 21 CFR 101.62 gates both supplier qualification and price tiering simultaneously, as only facilities achieving third-party validated fat-content testing gain access to premium supermarket shelf placement while conventional bakers remain trapped in promotional pricing cycles.
Pricing Analysis
Certification level creates the primary spread between premium specialty bakery tiers and mass-market private label offerings. Three-tier pricing structure across premium, standard, and economy levels reflects dual organic-low-fat certification premiums, volume scale discounts, and geographic delivery cost differentials. Cost compression in the all-natural sweetener tier is intensifying because Indian FSSAI import regulations constrain monk fruit and stevia supply flexibility. Health-Conscious Consumers in United States supermarket channels exhibit highest price sensitivity, while Fitness Enthusiasts in Australian online retail demonstrate lowest sensitivity due to subscription attachment and ingredient transparency prioritization.
Supply Chain Analysis
Shorter ambient shelf life in fat-free formulations compresses inventory turns and tightens lead-time windows for regional distribution. Supply concentrates in the United States, Australia, and Germany, with California's agricultural corridor feeding fruit puree inputs to domestic specialty bakeries. Formulation draws from natural sweetener agriculture, enzymatic fat mimetic systems, and modified starch structuring technology. Single-source vulnerability in natural sweetener supply chains threatens margin stability when Indian FSSAI regulations disrupt import flows. Distribution runs through direct-to-consumer subscription platforms bypassing conventional wholesale bakery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
No-fat cake markets function as service-attach opportunities where personalized flavor rotation subscriptions and nutritional consultation layers expand faster than base product transactions.
For Market Incumbents: Compound defensive moats by acquiring in-house R&D talent capable of balancing sensory performance with zero-fat thresholds, and deepen backward integration into California fruit puree supply contracts to offset natural sweetener price volatility. Plant-based egg replacer technologies threaten traditional dairy-egg supplier relationships and demand rapid formulation pipeline adaptation. For New Entrants and Emerging Players: Anchor in the Carrot Cake variant segment where vegetable-forward narratives remain underexploited by established chocolate and vanilla specialists. Target Fitness Enthusiasts in Australian direct-to-consumer channels through transparent ingredient sourcing and macro-tracking app integrations as the most penetrable entry vector. For Investors and Strategic Acquirers: EFSA's tightening nutrient profile models reshapes the acquisition landscape toward clean-label specialists with pre-validated European compliance pathways. Five-to-ten year viability favors mid-cap producers with captive enzymatic fat mimetic technology rather than commodity bakers dependent on outsourced formulation. Monitor German supermarket buyer mandates for third-party validated fat-content testing as the inflection signal indicating which target facilities possess scalable European access.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Bypasses wholesale bakery distribution constraints and captures Fitness Enthusiant loyalty through personalized rotation programs. |
| Enzymatic Fat Mimetic Technology Acquisition | Secures proprietary texture science that replicates mouthfeel without lipid content, defending premium positioning. |
| California Fruit Puree Supply Contract | Locks in domestic moisture-retention inputs that stabilize formulation costs against natural sweetener volatility. |
| FDA Low-Fat Certification Investment | Unlocks premium supermarket shelf placement and separates compliant specialists from promotional pricing traps. |
| EFSA Pre-Validation Pathway Development | Accelerates European market entry before nutrient profile model tightening elevates competitor compliance costs. |
Research Methodology
Initial hypotheses were tested against primary input from specialty bakery operations directors, supermarket category buyers, clean-label R&D formulation chemists, and direct-to-consumer platform founders, then refined through secondary validation against FDA 21 CFR 101.62 filings, EFSA nutrient profile guidance documents, FSSAI import regulation notices, and Nielsen retail audit data. Bottom-up volume triangulation across product type and distribution channel segments converged with top-down value estimates anchored in disclosed revenue ranges from public CPG conglomerates.
Variance decomposition across the projection horizon isolates growth contributions from Health-Conscious Consumer segment expansion, Fitness Enthusiast subscription attachment, and regulatory certification threshold changes. Segmentation dimensions modeled include product type, end user motivation, distribution channel, and ingredient certification tier. CAGRs were derived from fitted growth curves applied to base-year estimates, with cross-checks against enzymatic technology adoption rates and natural sweetener supply elasticity assumptions.
Decision-makers should treat outputs as directional under assumptions of sustained FDA enforcement consistency and stable natural sweetener agricultural yields; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Matcha Cookie Market
Bakery Products
Bakery Cases Market
Bakery Products
Middle East and Africa Bakery Products Market
Bakery Products
Europe Sweet Biscuits Market
Bakery Products
Waffle Market
Bakery Products
Baking Molds and Trays Market
Bakery Products
Bakery Premixes Market
Bakery Products
Canada Frozen Bakery Market
Bakery Products
Frozen Bakery Market
Bakery Products
Soft Biscuit Market
Bakery Products
Baking Mats Market
Bakery Products
North America Sweet Biscuits Market
Bakery Products
Asia-Pacific Baked Food and Cereals Market
Bakery Products
Organic Bakery Products Market
Bakery Products
Sweet Biscuits Market
Bakery Products
Europe Zwieback Market