
 Pizza Crust Market | 2026-2036
Pizza Crust Market Size, Share, and Industry Trends Forecast 2026-2036
Pizza Crust Market Intelligence
Food service distributors is collapsing into direct procurement from specialized crust manufacturers. Papa Johns leverages its captive supply chain to control dough consistency across franchise locations. Domino's anchors its competitive stance through regional commissary networks that par-bake crusts for last-mile finishing. Little Caesars differentiates via high-volume, low-touch production economics that sustain price leadership in the value segment.
Pizza crust comprises a leavened dough foundation, typically formulated from wheat flour, water, yeast, and salt, then baked to achieve specific textural properties ranging from crispy thin formats to airy, chewier structures that support sauce and topping loads. Its primary commercial purpose is to serve as the standardized base for prepared pizza products across retail and food service channels. Thin crust and gluten-free formats are capturing disproportionate margin pools as health-positioned menus expand, while stuffed crust remains a mature, promotion-dependent category tied to legacy pizza chains. Frozen preparation methods lead volume throughput due to extended shelf stability and logistics flexibility, though par-baked systems are gaining share in fast-casual kitchens seeking speed-scratch positioning.
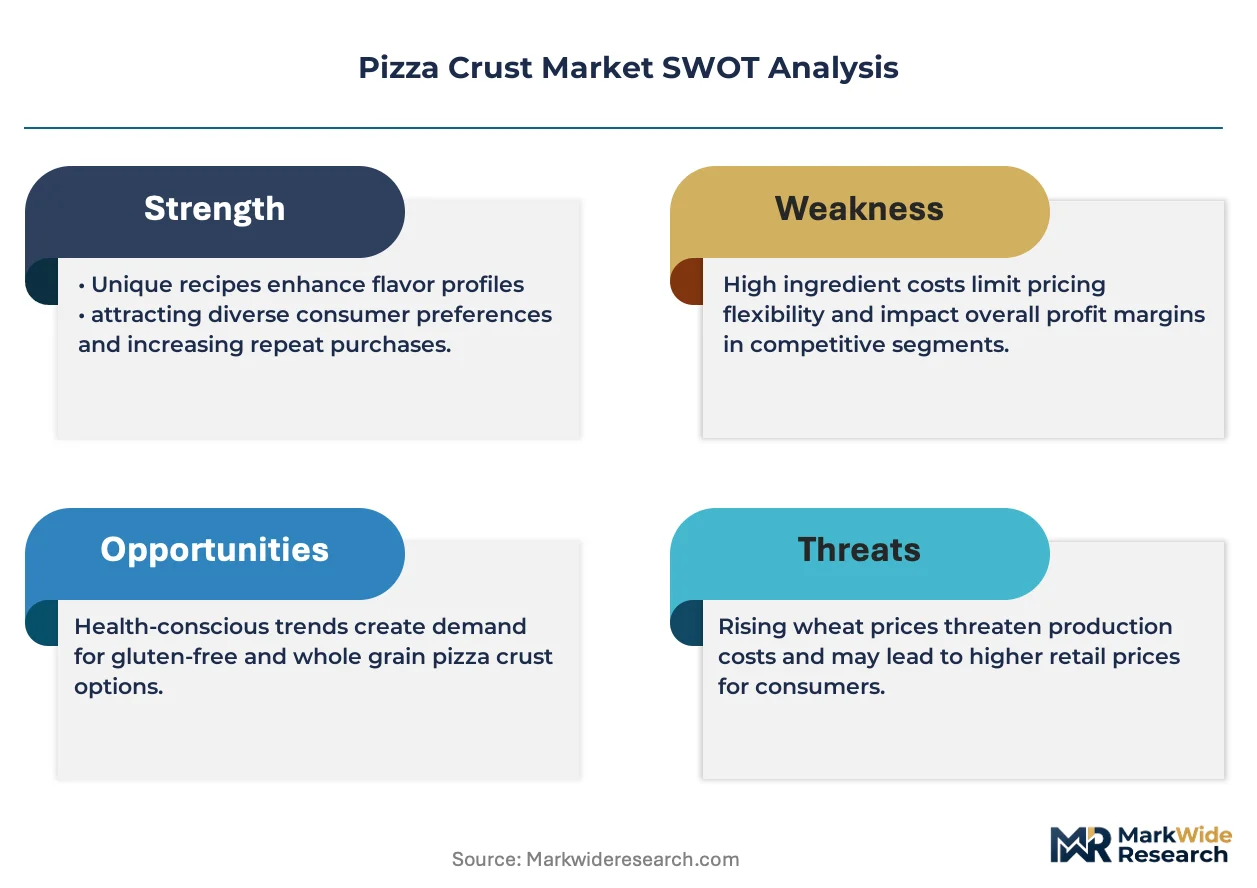
The FDA enforces allergen labeling and gluten-free claims under the Food Allergen Labeling and Consumer Protection Act, directly shaping ingredient sourcing and clean-label formulation priorities for US manufacturers. The EU's Food Information to Consumers Regulation mandates detailed nutritional declarations and origin tracing, raising compliance costs for crust exporters targeting European retail and food service accounts. Stakeholders must monitor evolving front-of-pack labeling mandates and carbon footprint disclosure requirements that will increasingly determine market access across major economies.
Market Dynamics
Food service distributors are abandoning legacy procurement layers to source directly from specialized crust manufacturers, compressing margin capture at the intermediary tier and forcing volume commitments upstream.
Growth Catalysts
- EU Food Information to Consumers Regulation:Mandates detailed nutritional declarations and origin tracing, creating compliance-driven demand for certified clean-label crust formulations across European retail channels.
- Quick-service restaurant chains:Private-label crust programs are expanding as franchise operators seek supply chain control and dough consistency standardization across dispersed locations.
- Par-bake technology:Fast-casual kitchens are adopting speed-scratch positioning, driving equipment retrofit cycles and specialized training for last-mile finishing protocols.
Market Restraints
- Wheat input volatility:Commodity price swings in North American grain markets compress margin predictability for high-volume thin-crust producers operating on fixed-price food service contracts.
- Gluten-free certification costs:FDA enforcement under the Food Allergen Labeling and Consumer Protection Act raises formulation and testing overhead for manufacturers targeting allergen-sensitive segments.
- Artisanal frozen crust substitution:Premium-positioned imported alternatives from Italy are capturing share in European food service channels, displacing domestic commodity production.
Strategic Opportunities
- Carbon footprint disclosure mandates:Early compliance with emerging EU Green Deal reporting requirements positions exporters for preferential access to sustainability-scored procurement tenders.
- Stuffed crust format revival:Cheese-injection processing equipment upgrades enable limited-time promotional cycles that reactivate dormant consumer interest in mature legacy formats.
- Direct-to-franchise distribution:Bypassing traditional broadline distributors captures margin recovery and builds captive relationships with multi-unit pizza operators.
Industry Challenges
- Clean-label formulation expertise:Talent scarcity in enzyme replacement and natural preservative systems slows reformulation timelines for manufacturers exiting artificial additive portfolios.
- Commissary network reconfiguration:Capital intensity of regional par-bake facilities strains balance sheets as chains pivot from frozen distribution to fresh-finished models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pizza Crust Market |
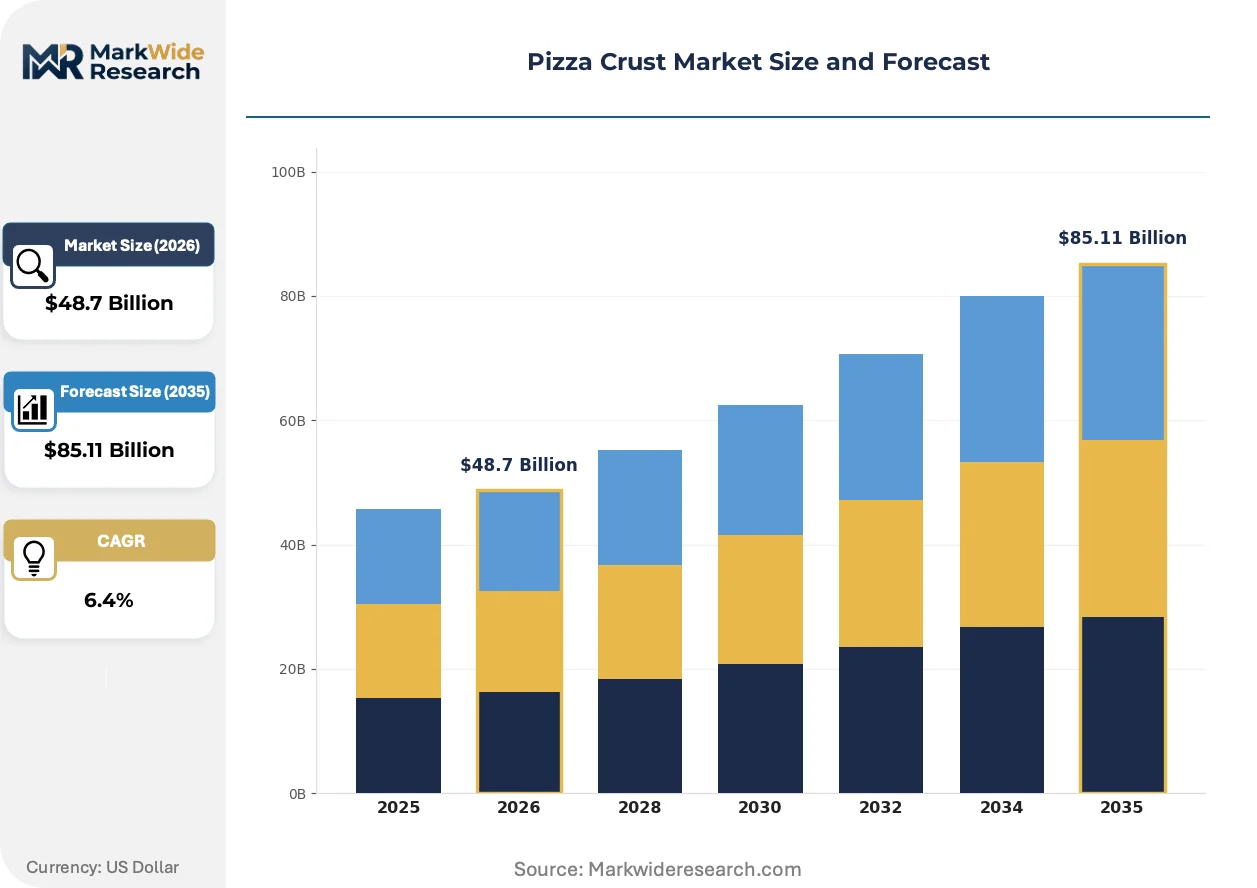
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin Crust, Thick Crust, Stuffed Crust, Gluten-Free Ingredient: Wheat Flour, Cauliflower, Whole Grain, Almond Flour Preparation Method: Hand-Stretched, Pre-Baked, Par-Baked, Frozen Distribution Channel: Retail Stores, Online, Food Service, Wholesalers |
| Companies Covered | Papa Johns, Donatos Pizza, Domino's, Stoner's Pizza Joint, Toppers Pizza, Pizza Hut, Marco's Pizza, King Arthur, Little Caesars, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pizza Crust Market Strategic Shifts & Innovations
Processing technology and regulatory disclosure requirements are converging to reshape how crust manufacturers compete on transparency, speed, and format flexibility.
Modified-atmosphere packaging systems are miniaturizing from industrial-scale nitrogen-flush tunnels to compact chamber units suitable for fast-casual back-of-house deployment. Regional pizza chains are retrofitting commissaries with these systems at accelerating pace. The technology is miniaturizing capital barriers, enabling smaller operators to capture extended-shelf-life benefits previously exclusive to frozen distribution networks.
REACH chemical registration requirements in Europe are tightening scrutiny on dough conditioners and processing aids, forcing reformulation audits across export-oriented manufacturers. Industrial consequence includes accelerated substitution of synthetic emulsifiers with enzyme-based alternatives. Frozen crust exporters targeting EU retail accounts are responding with dedicated clean-label product lines and third-party certification stacking.
Food service buyers are consolidating purchase authority into centralized procurement teams, collapsing the fragmented distributor relationships that historically characterized pizza chain supply. Broadline distributors are losing share to direct manufacturer contracts as franchise systems standardize specifications across regions. This concentration is most visible in US quick-service networks, where captive supply agreements now govern dough consistency protocols.
Pizza Crust Market Segmentation
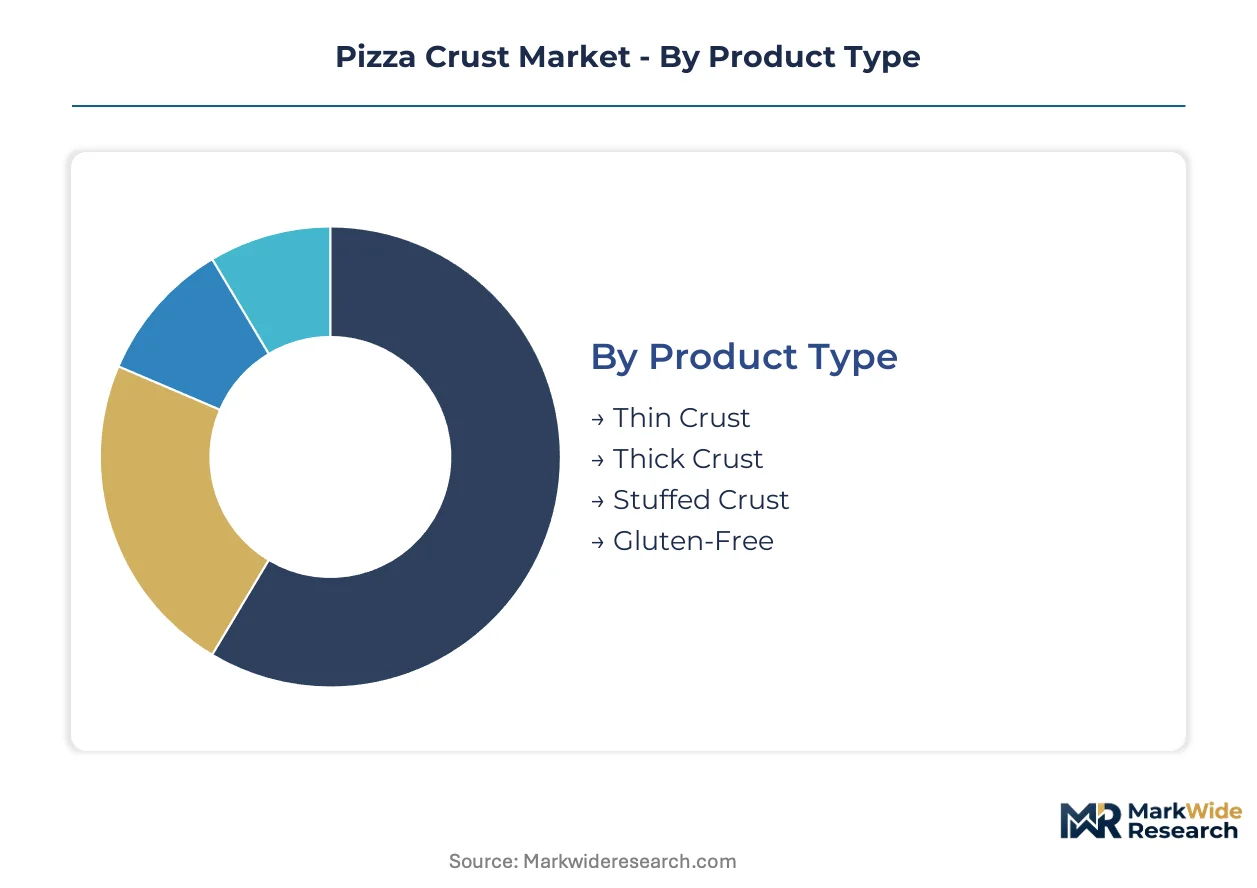
Crust manufacturers configure production lines around format specifications that determine channel eligibility and margin capture. Segment boundaries in this market reflect divergent technical requirements for frozen distribution versus fresh-finished food service deployment.
Product Type:
Channel-mix patterns split sharply between retail frozen aisles and food service back-of-house operations, with format thickness and ingredient positioning dictating where volume concentrates.
- Thin Crust:Low-moisture dough formulations achieve crispy texture through high-heat baking profiles. Quick-service chains in the United States deploy thin formats for speed-of-service metrics, while European retail channels favor these for home oven compatibility.
- Thick Crust:Higher hydration levels and extended fermentation build airy, chewier structures that support heavy topping loads. Independent pizzerias in Italy and Chicago-style operators in the US Midwest specify these for dine-in experiences.
- Stuffed Crust:Cheese-injection processing requires specialized equipment for molten filling containment. Legacy pizza chains activate promotional cycles around this mature format.
- Gluten-Free:Alternative flour blends and dedicated production lines prevent cross-contamination. FDA enforcement of gluten-free labeling standards shapes formulation investments for US manufacturers.
Thin crust dominates installed base. Gluten-free is where expansion concentrates.
Ingredient:
Cost tier stratification separates commodity wheat formulations from premium-positioned alternatives that command shelf-space premiums in health-focused retail channels.
- Wheat Flour:Standard hard red winter wheat delivers protein content optimal for gluten network development. North American grain price volatility compresses margins for high-volume producers locked into fixed-price food service contracts.
- Cauliflower:Vegetable-pulp binding systems replace traditional flour bases for carbohydrate reduction claims. Fast-casual chains in California and New York feature these on limited menus for dietary segmentation.
- Whole Grain:Bran and germ inclusion requires adjusted hydration protocols and extended mixing cycles. EU Food Information to Consumers Regulation mandates nutritional disclosure that elevates these in European retail.
- Almond Flour:High-fat content demands modified baking temperatures to prevent scorching. Premium natural grocery channels in Germany and the United Kingdom stock these for paleo and ketogenic diet adherents.
Wheat flour anchors volume throughput. Cauliflower is climbing the fastest.
Preparation Method:
Application requirements determine whether crusts ship frozen for extended shelf stability or par-baked for last-mile finishing protocols.
- Hand-Stretched:Artisanal production preserves irregular edge characteristics valued in Neapolitan-style service. Independent operators in Naples and New York City maintain these for authenticity positioning.
- Pre-Baked:Complete thermal processing enables direct topping application without additional dough handling. Convenience retail formats in Japan favor these for home assembly kits.
- Par-Baked:Partial thermal arrest creates speed-scratch flexibility for fast-casual kitchens. Regional commissary networks in the United States are retrofitting for par-bake throughput.
- Frozen:Blast-freezing at dough peak preserves yeast activity for thaw-and-proof protocols. Mass-market retail distribution depends on this method for logistics flexibility.
Frozen leads installed capacity. Par-baked is gaining share fastest.
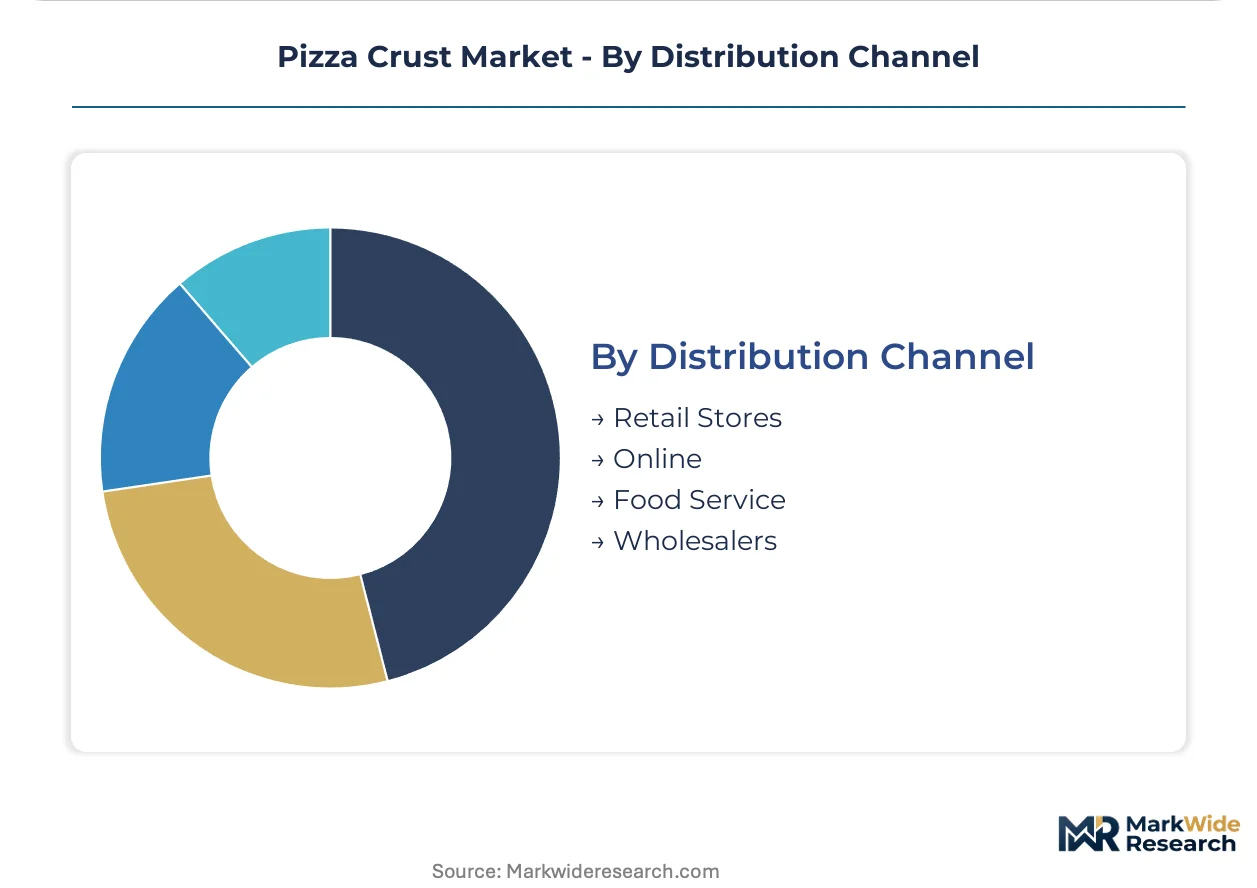
Distribution Channel:
Customer type concentration shapes whether manufacturers invest in retail packaging lines or bulk food service formats.
- Retail Stores:Modified-atmosphere packaging extends shelf life for grocery aisle placement. European supermarket chains are consolidating private-label crust procurement into centralized buying teams.
- Online:Direct-to-consumer fulfillment requires insulated packaging for cold-chain integrity. Meal-kit subscription services in the United Kingdom and Germany include crusts in pizza assembly boxes.
- Food Service:Direct manufacturer contracts are displacing broadline distributor relationships. Quick-service restaurant chains specify dough consistency protocols in captive supply agreements.
- Wholesalers:Palletized bulk shipment serves institutional accounts and regional distributor networks. Food service distributors are collapsing legacy procurement layers to source directly from specialized manufacturers.
Food service captures volume concentration. Online is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy exports artisanal frozen crusts to Germany, France, and the United Kingdom, establishing the dominant trade corridor in European food service channels.
United States
Quick-service restaurant chains drive volume through captive commissary networks and private-label programs. FDA enforcement of gluten-free labeling standards under FALCPA shapes formulation investments for allergen-sensitive segments. Chicago hosts dense clusters of thick-crust specialists serving regional pizzeria chains, while California fast-casual operators pioneer cauliflower-based alternatives.
Italy
Artisanal frozen crust exports gain traction across European food service channels, displacing commodity domestic production in buyer markets. EU Food Information to Consumers Regulation mandates nutritional declarations and origin tracing, elevating compliance costs for exporters. Naples maintains concentrated hand-stretched production for authenticity-positioned independent pizzerias, while northern industrial zones supply scaled frozen formats.
Germany
Premium natural grocery channels stock almond-flour and whole-grain variants for paleo and ketogenic diet adherents. REACH chemical registration requirements tighten scrutiny on dough conditioners, accelerating enzyme-based emulsifier substitution. Munich and Berlin anchor demand concentration for clean-label retail formats, with centralized procurement teams consolidating private-label crust buying.
Japan
Convenience retail formats favor pre-baked crusts for home assembly kits, supporting speed-scratch consumer positioning. METI standards influence processing equipment specifications for domestic manufacturers. Tokyo-Osaka corridor hosts specialized packaging firms miniaturizing modified-atmosphere systems for compact back-of-house deployment.
United Kingdom
Meal-kit subscription services include crusts in pizza assembly boxes, driving insulated cold-chain packaging demand. EU Green Deal reporting requirements shape sustainability-scored procurement tender access for exporters. London and Manchester concentrate fast-casual kitchen retrofit activity for par-bake adoption.
Pizza Crust Market Key Industry Players
Listed leaders compete with private specialists across supply chain control dimensions, with franchise systems and ingredient suppliers occupying distinct competitive tiers. The market structures around three archetypes: captive commissary operators, specialized crust manufacturers, and diversified bakery conglomerates. Dominant competitive moves include direct-to-franchise distribution bypassing broadline intermediaries, and equipment retrofit partnerships enabling par-bake technology adoption.
Among US-based quick-service operators, Domino's, Papa Johns, and Little Caesars exemplify divergent supply chain strategies. Domino's anchors regional commissary networks for par-bake throughput. Papa Johns leverages captive supply chains for dough consistency standardization. Little Caesars occupies the value-segment position through high-volume production economics. These three represent the primary competitive vectors shaping procurement patterns for specialized crust manufacturers.
| Leading Market Players |
|---|
| Papa Johns |
| Donatos Pizza |
| Domino's |
| Stoner's Pizza Joint |
| Toppers Pizza |
| Pizza Hut |
| Marco's Pizza |
| King Arthur |
| Little Caesars |
| Others |
Cost & Logistics Intelligence
Sixty-day frozen inventory cycles anchor margin predictability for high-volume thin-crust producers, compressing pricing power when North American wheat futures spike and locking contract structures to commodity-indexed adjustments.
Pricing Analysis
Par-bake technology premiums over frozen and hand-stretched formats widen as fast-casual chains retrofit commissaries for speed-scratch positioning. Three-tier pricing structure across premium clean-label, standard commercial, and economy private-label levels stratifies by certification grade and volume commitment scale. Pricing pressure stems from Italian artisanal frozen crust exports capturing European food service share. Independent pizzerias exhibit highest price sensitivity; captive quick-service networks absorb premiums for dough consistency guarantees.
Supply Chain Analysis
Strategic stockpiling of hard red winter wheat dominates over just-in-timed flour sourcing, buffering North American producers against grain market volatility. Supply concentrates in the United States, Italy, and Germany for distinct format specializations. Raw material dependencies center on wheat futures, enzyme-based dough conditioners, and modified-atmosphere packaging films. Single-source vulnerability runs through specialized cheese-injection equipment for stuffed crust production. Distribution runs through collapsing broadline distributor tiers toward direct manufacturer-franchise contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment retrofit partnerships and certification-stacking services expand faster than commodity crust volume, creating attach-revenue streams that outpace hardware margins across the analysis window.
For Market Incumbents: Consolidate regional commissary networks to capture par-bake technology premiums before fast-casual retrofit cycles mature. Lock multi-year dough consistency protocols with quick-service chains to defend against Italian artisanal frozen crust substitution. Prioritize FDA gluten-free certification investments to maintain allergen-segment access.
For New Entrants and Emerging Players: Lead with cauliflower-based and almond-flour alternative formats targeting California and New York fast-casual dietary segmentation. White-space concentrates in EU Green Deal carbon footprint disclosure compliance services for exporters. Go-to-market through direct-to-franchise distribution bypassing legacy broadline intermediaries.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because distributor-tier collapse concentrates procurement authority into fewer captive supply relationships. Target specialized crust manufacturers with clean-label formulation expertise and existing enzyme-replacement R&D capacity. Watch EU REACH enforcement intensity on dough conditioners as inflection signal for reformulation-driven M&A activity.
| Strategic Initiative | Industry Significance |
|---|---|
| Par-Bake Commissary Retrofit | Domino's regional networks demonstrate speed-scratch positioning captures fast-casual kitchen demand. |
| Clean-Label Certification Stacking | FDA gluten-free and EU Food Information compliance opens retail and food service channel access. |
| Direct-to-Franchise Distribution | Papa Johns captive supply chain model eliminates broadline margin capture and standardizes dough consistency. |
| Alternative Ingredient R&D | Cauliflower and almond-flour formulations address carbohydrate-reduction and ketogenic diet adherent segments. |
| Carbon Footprint Disclosure Compliance | Early EU Green Deal alignment positions exporters for sustainability-scored procurement tenders. |
Research Approach
The analysis maps thin-crust, thick-crust, stuffed-crust, and gluten-free sub-sectors, each validated through procurement directors at quick-service chains, food service distributor category managers, and specialized crust manufacturer operations heads. Primary interview data triangulates against FDA enforcement records, EU Food Information to Consumers Regulation compliance filings, and North American grain futures trade data. Bottom-up production capacity estimates and top-down channel volume assessments cross-validate segment sizing.
Consistency checks against external benchmarks include customs data on Italian frozen crust export volumes and quick-service chain commissary capital expenditure disclosures. The projection horizon spans product type, ingredient, preparation method, and distribution channel dimensions, with CAGRs derived from segment-level growth rate reconciliation. Wheat input cost trajectories and par-bake equipment adoption curves inform forecast sensitivity.
Underlying assumptions cover sustained quick-service chain expansion of private-label programs, with deviation risk concentrated in EU regulatory enforcement intensity and North American grain price volatility. Revision becomes warranted when artisanal frozen crust import penetration in European food service channels crosses thresholds that trigger domestic producer capacity rationalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Fortified Bakery Market
Bakery Products
Personalized Bakery Products Market
Bakery Products
No-Fat Cake Market
Bakery Products
Ready-To-Finish Bakery Products Market
Bakery Products
Bread Crumbs Market
Bakery Products
Bread Premix Market
Bakery Products
Low Calorie Bread Market
Bakery Products
Dough Whitener Market
Bakery Products
Bakery Flavors Market
Bakery Products
Bakery Mixes Market
Bakery Products
Middle East and Africa Sweet Biscuits Market
Bakery Products
Low Calorie Rice Cake Market
Bakery Products
Malted Rye Flour Market
Bakery Products
Ice Cream Cake Market
Bakery Products
Bread Improver Market
Bakery Products
GCC Frozen Bakery Products Market