
 Topcon Solar Cell Market | 2026-2036
Topcon Solar Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Topcon Solar Cell Market Insights
Software-defined performance monitoring and predictive maintenance subscriptions is expanding how Topcon cell suppliers monetize long-term asset relationships. LONGi leverages its integrated wafer-to-module footprint to bundle digital energy yield guarantees with hardware shipments. Trina Solar anchors its competitive position through advanced bifacial tracking algorithms sold as annual service tiers. JinkoSolar differentiates by offering module-level diagnostics that extend customer lifetime value beyond initial installation.
A tunnel oxide passivated contact solar cell sandwiches an ultrathin silicon oxide layer between crystalline silicon and a doped polysilicon emitter, suppressing surface recombination to push commercial efficiencies past 25 percent in mass production. N-type bifacial configurations now lead capacity additions because they deliver higher bifaciality coefficients and lower degradation rates than legacy P-type architectures. Utility-scale deployments absorb the dominant share of volume, while building-integrated applications represent the fastest-growing margin pool as aesthetic and structural dual-use specifications tighten.
China's MIIT sets cell efficiency minimums through GB standards that filter low-performing capacity from domestic project eligibility. The EU Green Deal and F-Gas Regulation together constrain fluorinated gas use in semiconductor process equipment, pushing equipment makers toward alternative passivation chemistries. India's BIS certification and PLI scheme for solar module manufacturing reshape where foreign cell producers must locate fabrication to access subsidized domestic tenders. Stakeholders must track how jurisdictional content rules fragment supply chain planning across multiple certification regimes.
Market Dynamics
Utility-scale solar developers in India and China are scaling procurement of N-type tunnel oxide passivated contact modules as national renewable portfolio standards tighten, compressing supplier qualification timelines and rewarding integrated wafer-to-module footprints.
Growth Catalysts
- China's dual carbon goals:Beijing's national targets for carbon peak and neutrality are filtering project eligibility toward high-efficiency cell architectures, accelerating factory retooling across Jiangsu province.
- EU Green Deal implementation:The European Union's binding decarbonization framework is redirecting module sourcing toward low-carbon manufacturing footprints, creating pull-through for advanced passivation technologies.
- Building-integrated photovoltaics:Aesthetic and structural dual-use specifications in commercial construction are opening margin pools for bifacial N-type configurations with customized form factors.
Market Restraints
- Polysilicon input volatility:Concentration of metallurgical-grade silicon refining in Xinjiang and Inner Mongolia exposes cell fabricators to energy-cost-driven feedstock price swings.
- Equipment fluorinated gas constraints:The EU F-Gas Regulation is restricting access to sulfur hexafluoride and nitrogen trifluoride for plasma-enhanced chemical vapor deposition tools, forcing chemistry transitions.
- Silver paste dependency:Screen-printed metallization for tunnel oxide contacts relies on silver flake supply concentrated among Japanese and Korean chemical processors.
Strategic Opportunities
- Gujarat solar park cluster:India's PLI scheme for solar module manufacturing is creating captive demand for localized cell fabrication to access subsidized domestic tenders.
- Software-defined performance monitoring:Predictive maintenance subscriptions bundled with hardware shipments are extending customer lifetime value beyond initial installation.
- Alternative passivation chemistries:Atomic layer deposition of aluminum oxide is converging with tunnel oxide stacks to enable thinner interface control without fluorinated process gases.
Industry Challenges
- Process integration complexity:Tunnel oxide formation requires sub-nanometer thickness control across 300-millimeter wafer formats, demanding scarce vacuum equipment engineering talent.
- Multi-jurisdictional certification:China's GB standards, India's BIS certification, and EU CE marking create divergent test protocols that fragment product platform economics.
- Legacy P-type capacity stranding:Existing PERC fabrication lines face accelerated obsolescence as N-type bifacial configurations capture utility-scale procurement preference.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Topcon Solar Cell Market |
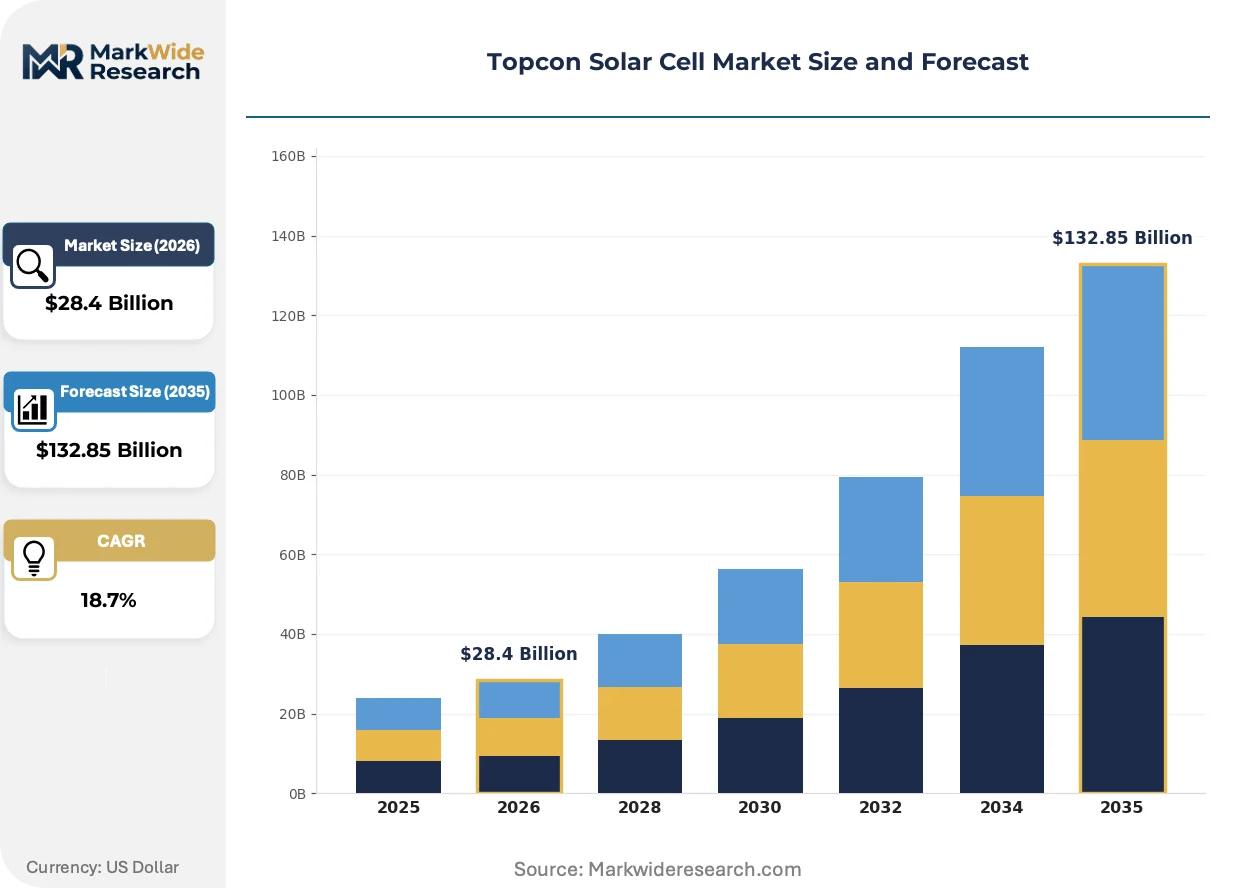
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $132.85 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: P-Type, N-Type, Bifacial, Monofacial Technology: Passivated Emitter, Rear Cell, Half-Cell, Heterojunction End User: Residential, Commercial, Industrial, Utility Application: Grid-Tied, Off-Grid, Hybrid, Building Integrated |
| Companies Covered | LONGi, Trina Solar, JA Solar Technology, JinkoSolar, Tongwei Solar, Canadian Solar, Hanwha Q CELLS, Jolywood, Suntech Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Topcon Solar Cell Market Trends and Innovations
Equipment makers and cell fabricators are racing to commercialize alternative chemistries and digital service layers that decouple revenue from commodity hardware margins.
Atomic layer deposition of aluminum oxide is decentralizing the tunnel oxide formation step from centralized chemical vapor deposition clusters. Mid-size cell fabricators in Southeast Asia are adopting modular ALD tools to bypass fluorinated gas dependencies. This equipment topology is compressing the capital barrier for new market entrants.
China's MIIT efficiency minimums through GB standards are disqualifying sub-23-percent cell architectures from domestic project eligibility. Low-performing capacity is exiting the eligible supply base. Tier-one fabricators are responding with accelerated wafer thinning and advanced texturing to protect qualification status.
Buyer preference is rotating toward module-level diagnostics and energy yield guarantees over component-centric procurement. Utility-scale developers in India are unbundling hardware from long-term performance contracts. This service-layer pivot is most visible in Gujarat's solar park cluster, where annual availability commitments now dominate tender evaluation.
Topcon Solar Cell Market Segmentation
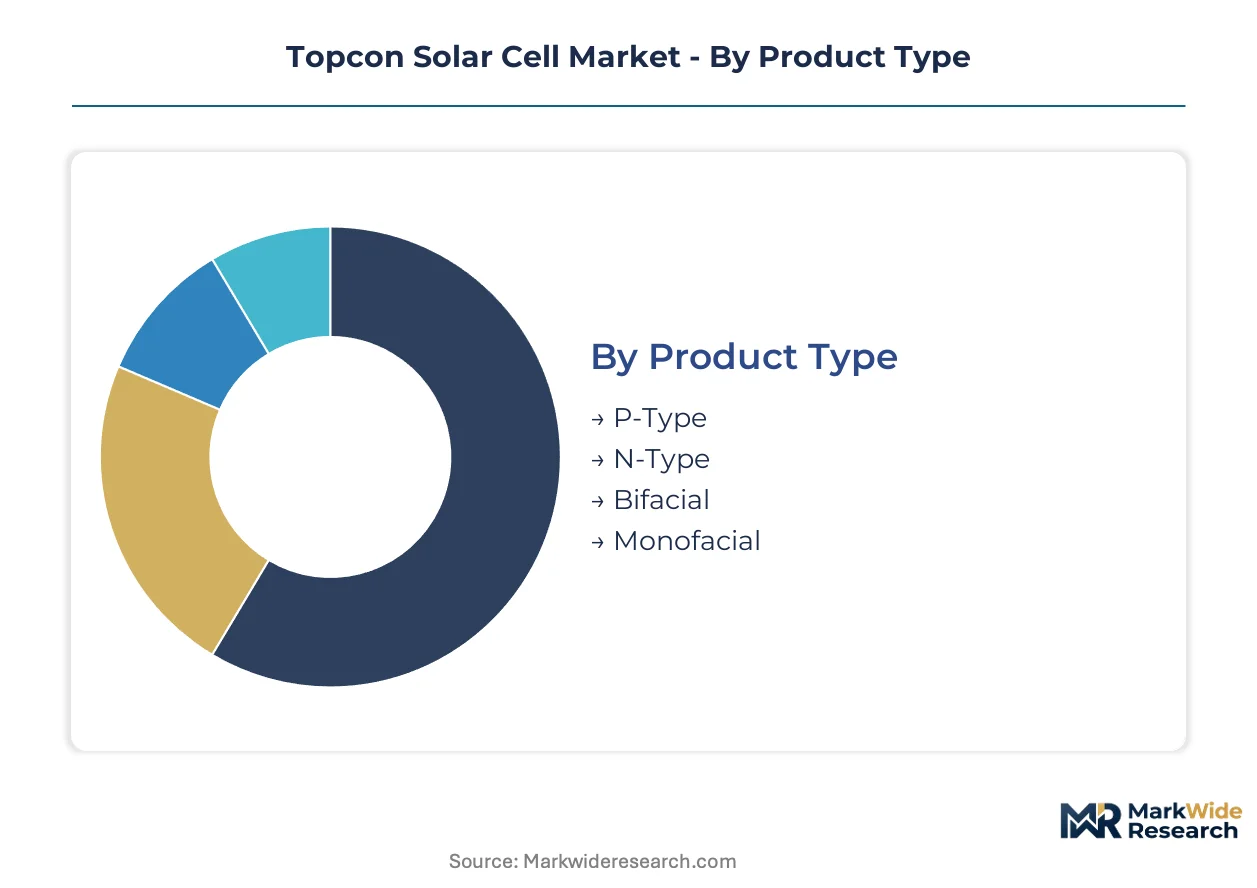
Topcon solar cell procurement patterns diverge sharply across product architectures, installation contexts, and grid connectivity models. Segment boundaries determine equipment qualification timelines, financing structures, and long-term performance contracting terms.
Product Type:
N-type bifacial configurations function as standalone premium offerings commanding yield guarantees, while P-type monofacial variants embed into cost-sensitive procurement bundles with shorter warranty horizons.
- N-Type:Crystalline silicon wafers with phosphorus doping deliver lower temperature coefficients and reduced light-induced degradation. Utility-scale developers in China's Jiangsu province prioritize N-type modules for projects under MIIT efficiency minimums.
- Bifacial:Dual-sided light capture architectures achieve bifaciality coefficients exceeding 80 percent in mass production. Gujarat's solar park cluster specifies bifacial configurations for tracking installations to maximize land-use efficiency.
- P-Type:Boron-doped silicon substrates with established supply chains face accelerated obsolescence as efficiency thresholds tighten.
- Monofacial:Single-sided cell architectures retain cost advantages in rooftop applications where rear-side irradiance remains limited.
N-type leads volumes today; bifacial configurations are gaining share fastest.
Technology:
Passivation chemistry choices stratify manufacturing capital intensity and regulatory compliance burdens across fabrication footprints.
- Passivated Emitter:Tunnel oxide layers beneath doped polysilicon suppress surface recombination velocities below 10 centimeters per second. EU F-Gas Regulation constraints are redirecting equipment procurement toward alternative deposition chemistries.
- Rear Cell:Back-contact architectures eliminate front-side shading losses through interdigitated electrode patterns. India's BIS certification protocols require dedicated testing for rear-cell module configurations accessing PLI-subsidized tenders.
- Half-Cell:Laser-scribed wafer segmentation reduces resistive losses and hot-spot susceptibility in large-format modules.
- Heterojunction:Amorphous silicon-crystalline silicon interfaces enable open-circuit voltages exceeding 750 millivolts.
Passivated emitter dominates current capacity; heterojunction is expanding most quickly.
End User:
Customer scale determines performance contracting structures, with utility buyers unbundling hardware from energy yield guarantees while residential procurement remains component-centric.
- Utility:Gigawatt-scale project developers negotiate module-level diagnostics and predictive maintenance subscriptions. China's dual carbon goals filter procurement toward high-efficiency architectures with 25-year performance warranties.
- Industrial:C&I offtakers with captive load profiles prioritize bifacial tracking systems for behind-the-meter generation.
- Commercial:Building owners balance aesthetic constraints against structural load limits in rooftop deployments.
- Residential:Distributed installers favor standardized form factors with simplified permitting pathways.
Utility procurement leads volumes today; commercial installations are climbing the fastest.
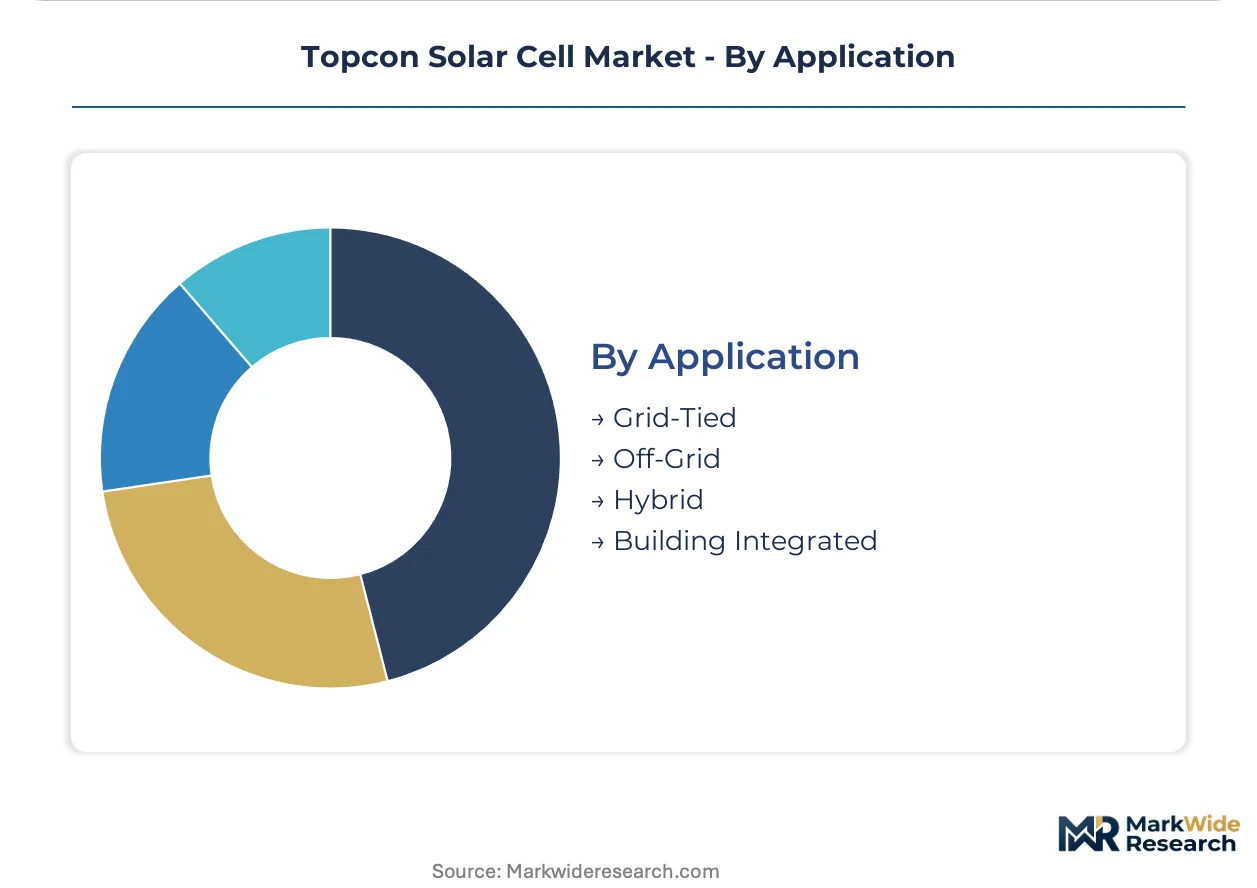
Application:
Grid interconnection topology shapes inverter selection, storage co-location requirements, and revenue stream diversification for project sponsors.
- Grid-Tied:Direct utility interconnection without storage buffers dominates utility-scale deployment economics. India's national renewable portfolio standards mandate grid-tied configurations for PLI scheme eligibility.
- Building Integrated:Structural and aesthetic dual-use specifications open premium margin pools for customized form factors. EU Green Deal implementation is accelerating BIPV adoption in commercial construction across member states.
- Hybrid:Co-located battery storage enables energy time-shifting and ancillary service participation.
- Off-Grid:Standalone systems with diesel backup persist in remote industrial and rural electrification contexts.
Grid-tied installations lead volumes today; building-integrated applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting cell fabrication capacity toward jurisdictions with subsidized power tariffs and streamlined environmental permitting. Manufacturers migrate production to exploit gaps in carbon-border compliance costs and local content incentive thresholds.
China
Beijing's dual carbon goals and MIIT efficiency minimums are filtering project eligibility toward N-type architectures above 23 percent conversion efficiency. Jiangsu province's cell fabrication corridor anchors mass production retooling as tier-one fabricators accelerate wafer thinning to protect qualification status. Factory automation investments concentrate in Suzhou and Wuxi municipal zones.
India
National renewable portfolio standards and the PLI scheme for solar module manufacturing are creating captive demand for localized cell production. BIS certification protocols require dedicated testing for rear-cell configurations accessing subsidized domestic tenders. Gujarat's solar park cluster drives procurement preference for bifacial tracking installations with 25-year performance warranties.
Germany
The EU Green Deal and F-Gas Regulation are constraining fluorinated gas use in plasma-enhanced chemical vapor deposition equipment. Equipment makers redirect toward alternative passivation chemistries to maintain CE marking compliance. Industrial R&D clusters in Saxony and Bavaria host pilot lines for atomic layer deposition integration.
United States
Domestic content bonuses under the Inflation Reduction Act are reshaping where foreign cell producers locate fabrication to access subsidized utility-scale procurement. FERC interconnection queue reforms compress project development timelines for high-efficiency module deployments. Southeast manufacturing corridors in Georgia and South Carolina attract module assembly investments.
Vietnam
Export-oriented cell fabrication is expanding to bypass tariff exposure in Western markets and exploit ASEAN trade agreement benefits. Mid-size fabricators adopt modular ALD tools to bypass fluorinated gas dependencies concentrated in legacy supply chains. Industrial zones in Bac Ninh and Thai Nguyen provinces host emerging capacity.
Topcon Solar Cell Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated wafer-to-module footprints commanding premium positioning in utility-scale procurement. The vendor base stratifies into three tiers: tier-one fabricators with captive polysilicon supply, tier-two specialists licensing passivation IP, and tier-three contract assemblers serving regional markets. Dominant competitive moves include backward integration into metallurgical-grade silicon refining and strategic partnerships for alternative metallization chemistries.
Among China-based integrated specialists, LONGi and JinkoSolar exemplify the tier-one archetype with captive wafer supply chains. Trina Solar occupies a position within the digital service-layer segment, bundling predictive maintenance subscriptions with hardware shipments. These three anchors demonstrate how competitive positioning stratifies between upstream material control and downstream performance contracting.
| Leading Market Players |
|---|
| LONGi |
| Trina Solar |
| JA Solar Technology |
| JinkoSolar |
| Tongwei Solar |
| Canadian Solar |
| Hanwha Q CELLS |
| Jolywood |
| Suntech Power |
| Others |
Pricing and Supply Chain Analysis
Utility-scale developers in Gujarat and Jiangsu are unbundling hardware procurement from long-term performance guarantees, forcing suppliers to absorb yield-risk premiums into contract pricing while competing on upfront module costs. This bifurcation compresses margins for pure-play manufacturers without captive polysilicon or integrated service layers.
Pricing Analysis
Distributor margins for N-type bifacial modules in India compress under the PLI scheme's domestic-content thresholds, while direct-to-utility contracts in China command loyalty discounts tied to multi-gigawatt offtake commitments. Pricing stratifies across premium, standard, and economy tiers based on MIIT efficiency certification and BIS compliance status. Cost compression in standard-tier P-type inventory is intensifying as Jiangsu fabricators liquidate legacy PERC capacity. Industrial C&I buyers in Europe exhibit the highest price sensitivity due to F-Gas Regulation compliance adders, whereas utility developers in China prioritize availability guarantees over unit economics.
Supply Chain Analysis
India's PLI scheme and the US Inflation Reduction Act domestic-content bonuses are reshaping sourcing patterns, pulling polysilicon procurement away from Xinjiang concentration zones toward alternative metallurgical-grade silicon corridors in Vietnam and Malaysia. Cell fabrication draws from silver paste supply anchored in Japanese and Korean chemical processing clusters, boron-doped silicon substrates from Jiangsu wafer pullers, and fluorinated process gases now constrained by EU regulatory ceilings. Single-source vulnerability concentrates in vacuum equipment engineering talent for sub-nanometer tunnel oxide deposition. Distribution runs through integrated wafer-to-module fabricators for utility-scale tenders and regional EPC aggregators for distributed rooftop deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where manufacturers locate fabrication to exploit gaps between India's subsidized power tariffs and the EU's carbon-border compliance costs.
For Market Incumbents: Acquire captive metallurgical-grade silicon refining capacity to insulate margin structures from Xinjiang energy-cost volatility. Secure backward integration into silver paste precursor supply through offtake agreements with Korean chemical processors. Heterojunction cell architectures represent the most credible substitute technology threat to tunnel oxide passivated contact dominance in premium efficiency tiers. For New Entrants and Emerging Players: Capture modular atomic layer deposition equipment niches serving mid-size Southeast Asian fabricators seeking fluorinated-gas-independent process flows. Vietnam's Bac Ninh industrial zone offers the most penetrable geography for greenfield capacity with ASEAN trade agreement benefits. A service-layer go-to-market bundling predictive maintenance subscriptions with hardware shipments bypasses commodity margin compression. For Investors and Strategic Acquirers: Asymmetric upside sits with tier-two specialists licensing passivation IP who can pivot equipment footprints across multiple jurisdictional certification regimes. Long-term viability hinges on five-to-ten-year positioning for post-PERC technology transitions rather than near-term capacity utilization rates. Watch for MIIT efficiency minimum threshold revisions as the inflection signal for accelerated legacy capacity stranding.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Captive metallurgical-grade silicon supply insulates margin structures from Xinjiang energy-cost volatility. |
| Alternative Metallization Chemistry Partnership | Silver-reduction paste development with Japanese chemical processors addresses critical input concentration risk. |
| Software-Defined Service Layer Launch | Predictive maintenance subscriptions bundled with Gujarat utility tenders extend customer lifetime value beyond installation. |
| Modular ALD Equipment Deployment | Atomic layer deposition tools bypass EU F-Gas Regulation constraints for Vietnam-based fabricators. |
| Multi-Jurisdictional Certification Investment | Parallel GB standards, BIS, and CE marking qualification protects platform economics across China, India, and EU procurement pools. |
Research Methodology
Coverage spans China, India, Germany, the United States, and Vietnam, with primary inputs from each market combining structured interviews with cell fabrication engineers, utility procurement officers, EPC contractors, and equipment manufacturing executives alongside secondary validation. Bottom-up triangulation incorporated MIIT efficiency standard filings, EU F-Gas Regulation implementation guidance, India BIS certification databases, and customs data on metallurgical-grade silicon trade flows. Top-down cross-checks referenced IEA renewable deployment trackers and national renewable portfolio standard implementation reports.
Granularity-level modeling disaggregated volume and value across the analysis window by product architecture (N-type bifacial, P-type monofacial), passivation technology (tunnel oxide, heterojunction), end-user scale (utility, industrial, commercial, residential), and grid connectivity topology (grid-tied, building-integrated, hybrid, off-grid). CAGRs were derived from capacity addition pipelines, equipment order backlogs, and tender award trajectories. Industry-specific forecast inputs included wafer thinning adoption curves and atomic layer deposition tool penetration rates.
Polysilicon input price volatility, regulatory threshold revisions for cell efficiency minimums, and fluorinated gas chemistry substitution timelines are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on technology transition speeds and jurisdictional content rule enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Die Spacer Market
Semiconductor Devices
Smart Gate Driver Market
Semiconductor Devices
Amorphous-Semiconductor Devices Market
Semiconductor Devices
China Semiconductor Diode Market
Semiconductor Devices
Gan on Silicon Technology Market
Semiconductor Devices
Global Transistor Market
Semiconductor Devices
China Power Transistor Market
Semiconductor Devices
Advanced IC Substrates Market
Semiconductor Devices
Asia Pacific Motherboard Market
Semiconductor Devices
DNA Chip Market
Semiconductor Devices
Japan Semiconductor Diode Market
Semiconductor Devices
Global Embedded FPGA Market
Semiconductor Devices
Silicon Carbide Mosfets Market
Semiconductor Devices
Global Gan Semiconductor Device Market
Semiconductor Devices
Ferroelectric FET Market
Semiconductor Devices
Digital Transistor Market