
 Chemical Storage Tank and Bottle for Semiconductor Market | 2026-2036
Chemical Storage Tank and Bottle for Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Storage Tank and Bottle for Semiconductor Market Outlook
Preventive maintenance contracts and predictive replacement scheduling is recalibrating how semiconductor fabs procure chemical storage systems. Entegris, Inc. leverages its vertical integration in clean transport solutions to dominate the high-purity bottle segment. Avantor, Inc. anchors its position through specialized fluoropolymer formulations that meet sub-ppb contamination thresholds.
Chemical storage tanks and bottles for semiconductor manufacturing are engineered containment systems constructed from electropolished stainless steel or fluoropolymer resins, designed to maintain chemical purity below parts-per-billion contamination levels during transport, dispensing, and static holding of process chemicals. These systems prevent metallic ion leaching and particle shedding that would destroy nanometer-scale device yields. Bottle containers command premium pricing due to their dominance in photoresist chemical handling where optical clarity and inertness are non-negotiable. Stainless steel vertical tanks sustain the largest installed base for bulk solvent and etchant storage, while polyethylene intermediate bulk containers represent the fastest-growing format for specialty chemical distribution to mid-size foundries.
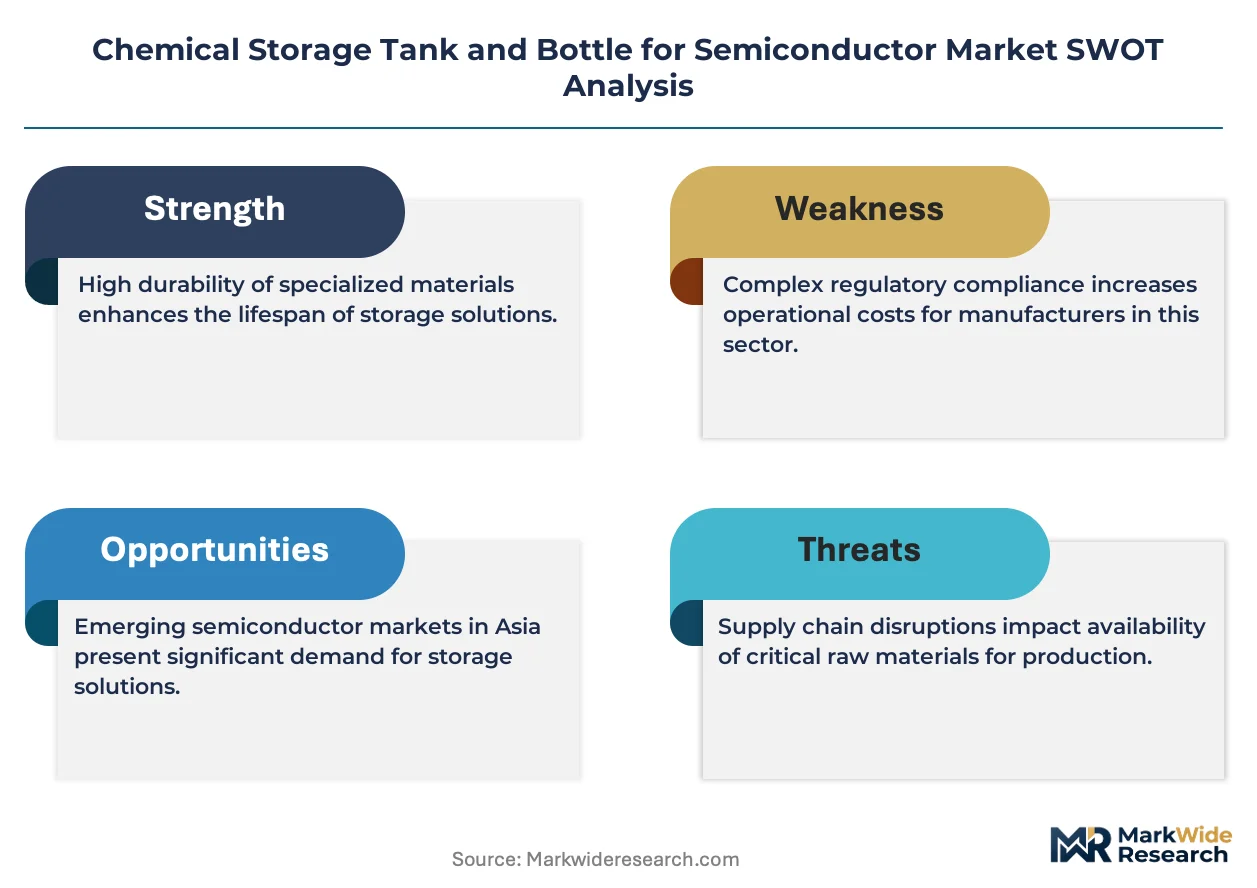
EPA regulations on per- and polyfluoroalkyl substances are forcing reformulation of fluoropolymer linings and accelerating qualification of alternative barrier materials. SEMI standards and ISO 14644 cleanroom classifications shape container surface finish requirements and certification protocols for supplier market access. Buyers must monitor evolving material restrictions while weighing total cost of ownership against purity performance across their chemical supply chains.
Market Dynamics
The transition to sub-3nm logic nodes at Samsung's Pyeongtaek and TSMC's Tainan facilities is forcing wholesale replacement of legacy stainless steel vessels with fluoropolymer alternatives that eliminate metallic ion contamination risks at atomic-scale dimensions.
Growth Catalysts
- Advanced Node Proliferation:Logic production below 5nm requires fluoropolymer bottles with sub-ppb metallic leaching thresholds, expanding addressable equipment spend per fab.
- EU F-Gas Regulation:Tightening containment standards for fluorinated greenhouse gases is mandating upgraded sealing systems and material traceability across European semiconductor supply chains.
- Photoresist Volume Expansion:EUV lithography adoption at leading foundries multiplies photoresist consumption, driving bottle demand for light-sensitive chemical handling.
Market Restraints
- Fluoropolymer Feedstock Concentration:PFA and PTFE resin supply concentrates among Japanese and Chinese chemical conglomerates, exposing buyers to allocation risk during semiconductor upcycles.
- EPA PFAS Scrutiny:Per- and polyfluoroalkyl substance restrictions under US environmental law are forcing costly reformulation of barrier linings and extended qualification timelines.
- Stainless Steel Inertia:Bulk solvent storage infrastructure at mature fabs resists replacement despite fluoropolymer purity advantages, slowing upgrade cycles.
Strategic Opportunities
- India Semiconductor Mission:Central and state government incentives for domestic fab construction create first-mover advantage for container suppliers establishing local molding and finishing capacity.
- Closed-Loop Chemical Delivery:Refillable bottle systems with integrated RFID tracking are displacing single-use containers in Taiwanese and South Korean foundry clusters.
- Carbon Border Adjustment:EU CBAM implementation favors regional fluoropolymer processing over Asian imports, rewarding European molding investments with tariff insulation.
Industry Challenges
- Cleanroom Welding Certification:ASME BPE and SEMI F57 compliance for orbital welding of stainless steel tanks requires scarce technician credentials that extend commissioning schedules.
- Legacy System Integration:Retrofitting fluoropolymer dispensing hardware into existing bulk chemical distribution architectures demands custom manifold engineering that fragments supplier margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Storage Tank and Bottle for Semiconductor Market |
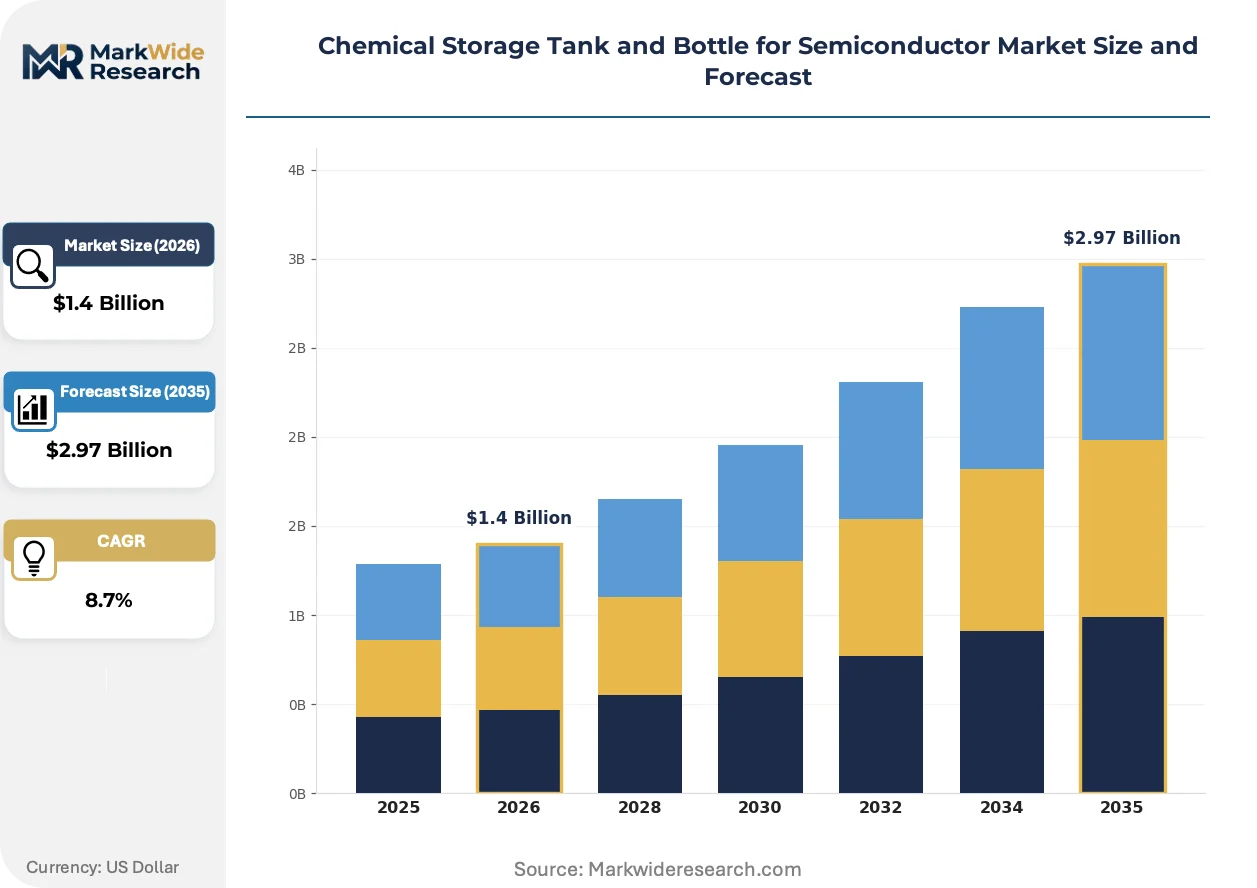
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Tanks, Horizontal Tanks, Bottle Containers, Intermediate Bulk Containers Material: Stainless Steel, Polyethylene, Fiberglass, Carbon Steel Application: Photoresist Chemicals, Etchants, Solvents, Cleaners End User: Fabless Companies, Semiconductor Foundries, Equipment Manufacturers, Research Institutions |
| Companies Covered | Entegris, Inc., Avantor, Inc., Air Liquide, Honeywell International Inc., BASF SE, Kanto Chemical Co., Inc., Shin-Etsu Chemical Co., Ltd., Mitsubishi Chemical Corporation, Fujifilm Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Storage Tank and Bottle for Semiconductor Market Strategic Shifts
Material science advances and regulatory pressure are compressing qualification cycles while elevating performance thresholds for containment systems across semiconductor manufacturing.
Fluoropolymer nanocomposite barrier layers are converging with embedded sensor arrays to enable real-time chemical purity monitoring during transport and static holding. Leading foundries in South Korea and Taiwan are piloting these intelligent vessels for high-value photoresist and etchant chemistries. The structural consequence is converging with predictive maintenance platforms to collapse unplanned downtime events and extend replacement intervals.
The EU F-Gas Regulation's phasedown schedule for hydrofluorocarbons is compelling fluoropolymer processors to document supply chain carbon intensity and transition to low-GWP blowing agents. Industrial consequence includes accelerated qualification of bio-based barrier alternatives and recycled content certifications. High-purity bottle manufacturers serving European equipment OEMs are most affected, responding with mass-balance accounting and third-party verified environmental product declarations.
Foundry procurement teams are consolidating chemical storage spend under multi-year total cost of ownership contracts that unbundle hardware from installation and validation services. The equipment distributor channel faces margin compression as direct manufacturer relationships capture aftermarket revenue. This behavioral shift is most visible in Taiwan's Tainan Science Park, where TSMC's supplier reduction programs favor vertically integrated container specialists over component assemblers.
Chemical Storage Tank and Bottle for Semiconductor Market Segmentation
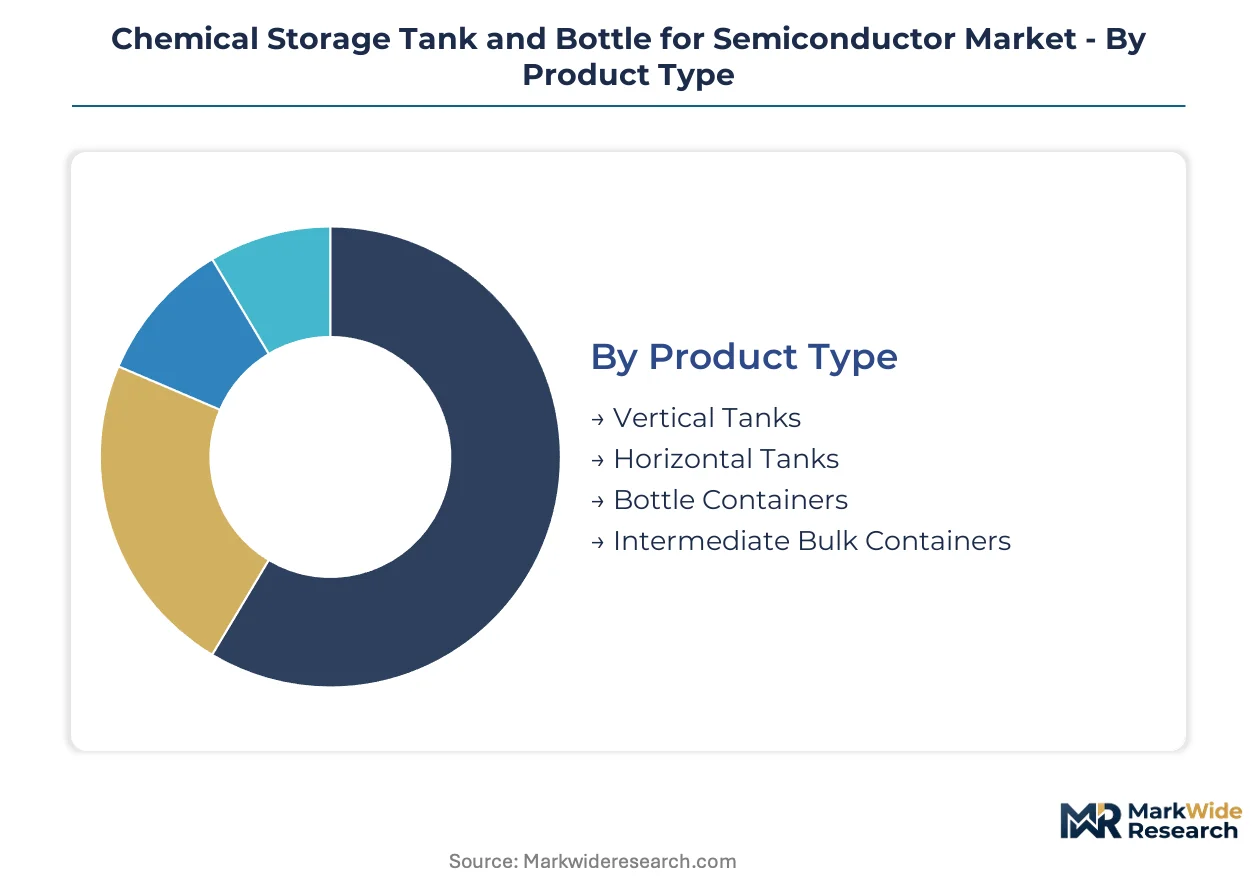
Containment system selection in semiconductor manufacturing hinges on purity thresholds, chemical reactivity profiles, and distribution logistics. Each segmentation dimension reveals distinct procurement patterns across fab operations and supply chain tiers.
Product Type:
Supply concentration in precision molding and orbital welding capabilities shapes competitive positioning across container formats.
- Vertical Tanks:Electropolished stainless steel vessels with ASME BPE certification sustain the largest installed base for bulk solvent and etchant storage at mature fabs. Samsung's Pyeongtaek cluster and TSMC's Tainan facilities deploy these for high-volume chemical distribution where metallic ion leaching risks are managed through surface finish specifications rather than material substitution.
- Bottle Containers:Fluoropolymer resin bottles engineered for sub-ppb contamination thresholds command premium pricing due to non-negotiable optical clarity and inertness requirements in EUV photoresist handling. Demand concentrates at leading foundries transitioning to sub-3nm logic nodes where atomic-scale device yields require elimination of metallic ion contamination risks.
- Horizontal Tanks:Low-profile stainless steel configurations optimize cleanroom floor space utilization in legacy fab retrofits.
- Intermediate Bulk Containers:Polyethylene-based portable units address specialty chemical distribution to mid-size foundries with flexible volume requirements.
Today's leader: Bottle Containers. Tomorrow's challenger: Intermediate Bulk Containers.
Material:
Cost tier stratification separates premium fluoropolymer formulations from commodity metal alternatives.
- Stainless Steel:Electropolished 316L grade dominates bulk storage economics despite purity limitations, with entrenched infrastructure at solvent distribution nodes resisting replacement cycles.
- Polyethylene:Intermediate purity tier serves specialty chemical logistics where metallic contamination risks are moderate and cost sensitivity elevates.
- Fiberglass:Reinforced polymer composites address corrosive etchant containment in secondary chemical handling applications.
- Carbon Steel:Unlined configurations restricted to non-critical utility chemical storage outside cleanroom environments.
Current procurement favors Stainless Steel for volume. Fluoropolymer migration is gaining share fastest in photoresist-critical applications.
Application:
Volume scale and purity sensitivity diverge sharply across process chemical categories.
- Photoresist Chemicals:Light-sensitive formulations demand fluoropolymer bottles with embedded UV protection and particulate shedding controls below SEMI F57 thresholds. EUV lithography adoption at TSMC and Samsung foundries multiplies consumption volumes and tightens handling protocols.
- Etchants:Corrosive acid and solvent blends require barrier-lined vessels with real-time chemical compatibility monitoring, concentrating demand at wet process equipment integration points.
- Solvents:High-purity organic carriers for deposition and cleaning processes utilize stainless steel bulk storage with point-of-use fluoropolymer dispensing.
- Cleaners:Aqueous and solvent-based surface preparation chemistries deploy intermediate bulk formats for flexible fab-wide distribution.
Photoresist Chemicals anchor premium spend. Etchants present the steepest expansion trajectory from advanced node etch complexity.
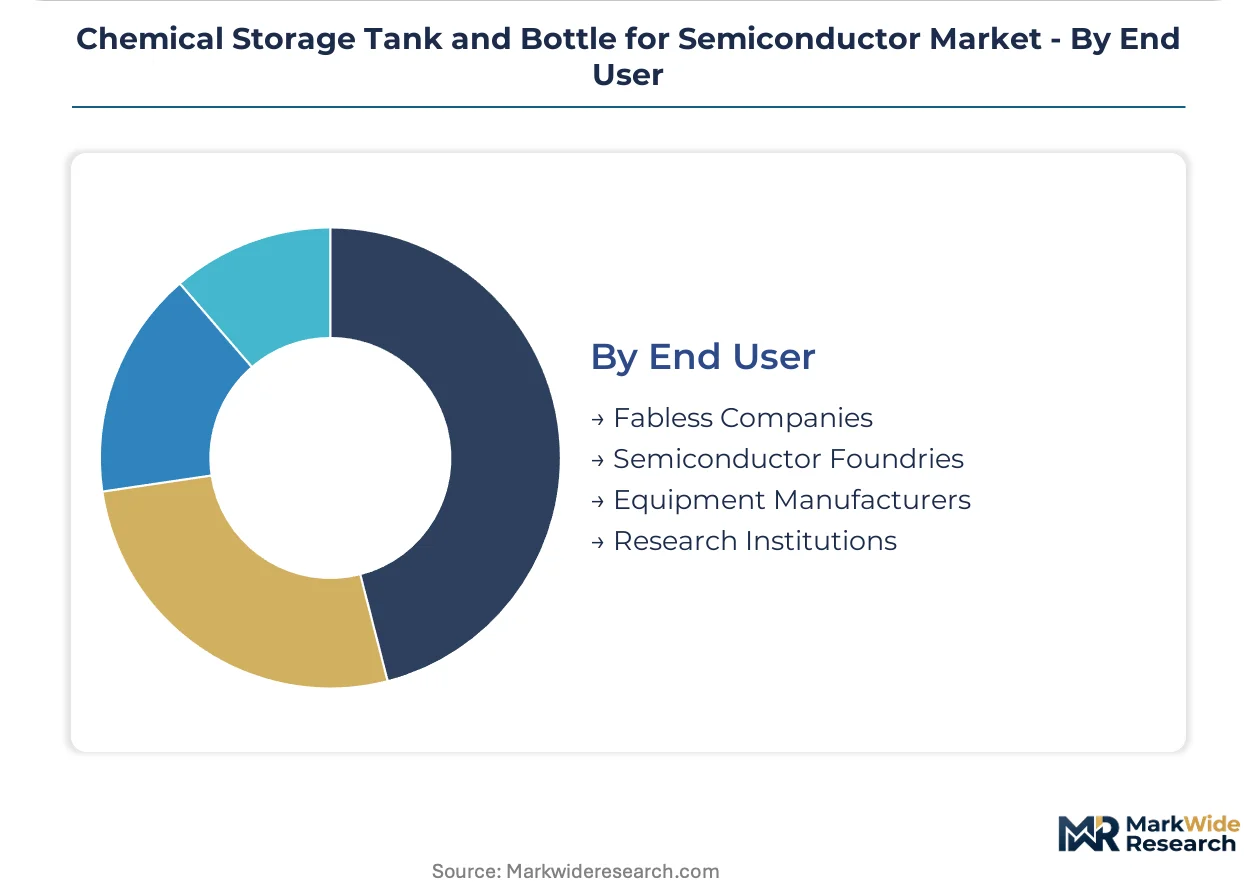
End User:
Customer type determines contract structure, validation burden, and replacement cycle predictability.
- Semiconductor Foundries:Integrated device manufacturers and pure-play foundries drive specification-setting through multi-year total cost of ownership contracts that unbundle hardware from installation and validation services. TSMC's supplier reduction programs in Taiwan's Tainan Science Park favor vertically integrated container specialists.
- Fabless Companies:Design houses without captive fab capacity procure through equipment OEM channels with limited direct specification influence.
- Equipment Manufacturers:Lithography and wet process tool builders integrate containment systems as subassemblies, capturing aftermarket revenue through direct manufacturer relationships.
- Research Institutions:University and national laboratory facilities generate fragmented demand with extended qualification timelines and specialized small-batch requirements.
Semiconductor Foundries command procurement gravity. Equipment Manufacturers are capturing aftermarket revenue previously held by distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's Pyeongtaek cluster commands larger chemical storage vessel volumes than Taiwan's Tainan Science Park, though both foundry hubs drive premium fluoropolymer bottle demand for sub-3nm logic production. Japan maintains critical resin supply dominance while facing EPA-aligned environmental scrutiny. China's domestic fab buildout and India's emerging semiconductor mission reshape procurement geography.
South Korea
Samsung's Pyeongtaek foundry complex drives fluoropolymer bottle consumption for EUV photoresist handling at advanced logic nodes. The Ministry of Trade, Industry and Energy (METI-equivalent industrial policy) channels subsidies through the K-Semiconductor Belt initiative. Seoul Capital Area suppliers cluster around Pangyo and Hwaseong to serve just-in-time chemical delivery contracts.
Taiwan
TSMC's Tainan Science Park facilities anchor Asia-Pacific demand for sub-ppb contamination threshold containers. The National Development Council's chip industry incentives reinforce local supply chain requirements. Taichung and Hsinchu Science Park form secondary concentration nodes for specialty chemical distribution infrastructure.
United States
Intel's Arizona and Ohio fab investments drive stainless steel bulk tank procurement for solvent distribution networks. EPA PFAS restrictions under the Toxic Substances Control Act force fluoropolymer lining reformulation and extended qualification timelines. Phoenix and Columbus metro areas concentrate equipment supplier engineering support functions.
Japan
Shin-Etsu and Kanto Chemical anchor domestic fluoropolymer resin production for high-purity bottle manufacturing. The Ministry of Economy, Trade and Industry (METI) enforces chemical substance management standards aligned with international semiconductor equipment protocols. Chiba and Ibaraki prefectures host precision molding facilities serving foundry customers across Northeast Asia.
India
The India Semiconductor Mission's production-linked incentive scheme attracts first-mover container suppliers for domestic fab construction. Central and state government approvals under the Modified Special Incentive Package Scheme (M-SIPS) framework govern equipment import and local value-add requirements. Gujarat and Karnataka states concentrate projected demand from Vedanta-Foxconn and ISMC Digital fab projects.
Chemical Storage Tank and Bottle for Semiconductor Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated material science companies capturing premium fluoropolymer bottle volumes while regional metal fabricators serve stainless steel tank replacement cycles. Market structure tilts toward consolidation in high-purity resin formulation, with three to five conglomerates controlling PFA and PTFE feedstock supply. Dominant strategic archetypes include vertically integrated clean transport specialists, diversified chemical conglomerates with captive container production, and precision molding contractors serving equipment OEM channels. Competitive dynamics center on backward integration into fluoropolymer resin production and multi-year total cost of ownership contracting that unbundles hardware from validation services.
Among diversified chemical conglomerates, Entegris, Inc. and Avantor, Inc. occupy positions exemplifying the vertically integrated archetype, with geographic naming conventions indicating US-based corporate structures. Japanese resin and chemical specialists including Shin-Etsu Chemical Co., Ltd. and Kanto Chemical Co., Inc. represent the feedstock-anchored tier, their naming conventions signaling domestic manufacturing heritage. These groupings illustrate how competitive positioning stratifies between those commanding upstream material control and those specializing in precision fabrication and foundry-direct service models.
| Leading Market Players |
|---|
| Entegris, Inc. |
| Avantor, Inc. |
| Air Liquide |
| Honeywell International Inc. |
| BASF SE |
| Kanto Chemical Co., Inc. |
| Shin-Etsu Chemical Co., Ltd. |
| Mitsubishi Chemical Corporation |
| Fujifilm Holdings Corporation |
| Others |
Value Chain & Pricing Dynamics
PFA resin price indices from Japanese chemical conglomerates cascade through three distinct pricing tiers for semiconductor chemical containment systems, with sub-ppb fluoropolymer bottles commanding substantial premiums over electropolished stainless steel alternatives. Foundry procurement teams in South Korea and Taiwan negotiate multi-year total cost of ownership contracts that unbundle hardware from validation services, compressing margins for distributors while rewarding backward-integrated resin producers.
Pricing Analysis
Capacity additions in China's fluoropolymer compounding sector are reshaping price floors for standard-grade containers, though sub-ppb certified bottles retain pricing power through scarcity of precision molding capabilities. Three-tier pricing structure across premium, standard, and economy levels separates ASME BPE-certified stainless steel tanks from intermediate polyethylene bulk containers and commodity carbon steel vessels. Cost compression in the mid-tier is intensifying because Indian and Southeast Asian fabricators are qualifying for foundry-direct supply contracts. Mature fabs with entrenched bulk solvent infrastructure exhibit highest price sensitivity, while sub-3nm logic producers show least sensitivity due to yield-risk calculations.
Supply Chain Analysis
India's Modified Special Incentive Package Scheme local-content thresholds are reshaping sourcing patterns for container suppliers establishing Gujarat and Karnataka molding facilities. PFA and PTFE resin supply concentrates in Japan and China, while precision fabrication clusters orbit Samsung's Pyeongtaek and TSMC's Tainan facilities. Raw material dependencies rest on fluoropolymer feedstocks, electropolished 316L stainless steel, and semiconductor-grade polyethylene resins. Single-source vulnerability from Japanese resin conglomerates exposes buyers to allocation risk during semiconductor upcycles. Distribution runs through equipment OEM channels and direct manufacturer relationships with foundry procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EPA PFAS regulatory stringency in the United States and the India Semiconductor Mission's production-linked incentive schemes, with cost differentials exceeding qualification timeline advantages.
For Market Incumbents: Anchor market position through captive PFA resin supply and orbital welding certification programs that scarcity-protect technician credentials. Defensive consolidation should target precision molding contractors in Taiwan's Tainan Science Park to block channel access for emerging competitors. Threat from EPA PFAS restrictions demands accelerated qualification of bio-based barrier alternatives. Capacity addition in South Korea's K-Semiconductor Belt reinforces proximity to Samsung's Pyeongtaek demand center. For New Entrants and Emerging Players: Mid-size Indian foundries under Vedanta-Foxconn and ISMC Digital projects represent the most penetrable buyer archetype, with flexible volume requirements and limited incumbent relationships. White-space targets include refillable bottle systems with integrated RFID tracking for closed-loop chemical delivery, and European fluoropolymer processing investments that exploit EU Carbon Border Adjustment tariff insulation. Go-to-market angle should emphasize rapid qualification timelines against legacy supplier backlogs. For Investors and Strategic Acquirers: Asymmetric upside sits with precision molding specialists possessing SEMI F57 certification and established foundry-direct relationships, particularly those positioned for India Semiconductor Mission procurement waves. Long-term viability hinges on backward integration into resin formulation or forward integration into predictive maintenance platforms. Acquisition target archetype: mid-cap container specialists with orbital welding capabilities and cleanroom certification infrastructure. Watch EPA PFAS enforcement pace and EU F-Gas Regulation phasedown schedules as inflection indicators for material substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Resin Production | Captures margin from Shin-Etsu and Kanto Chemical supply concentration while securing allocation priority during semiconductor upcycles. |
| Orbital Welding Certification Investment | Addresses ASME BPE and SEMI F57 compliance scarcity that extends commissioning schedules at Samsung and TSMC facilities. |
| Closed-Loop Chemical Delivery System Launch | Displaces single-use containers in Taiwanese and South Korean foundry clusters through RFID-tracked refillable bottle platforms. |
| India Local Molding Capacity Buildout | Captures first-mover advantage under M-SIPS local value-add requirements for Vedanta-Foxconn and ISMC Digital fab projects. |
| Bio-Based Barrier Material Qualification | Preempts EPA PFAS restriction impacts and EU F-Gas Regulation carbon intensity documentation demands on European equipment OEMs. |
Study Parameters
Coverage spans South Korea, Taiwan, United States, Japan, and India, with primary inputs from each market's foundry procurement managers, chemical distribution specialists, fluoropolymer resin producers, precision molding technicians, and cleanroom equipment integrators. Secondary validation drew from SEMI industry reports, EPA PFAS regulatory filings, EU F-Gas Regulation implementation documents, India Semiconductor Mission policy circulars, and customs trade data for fluoropolymer container imports. Bottom-up and top-down triangulation reconciled fab-level equipment spend estimates with resin producer shipment disclosures.
Granularity-level modeling deployed product type, material grade, application chemistry, and end-user contract structure as core segmentation dimensions across the projection horizon. CAGRs were derived from weighted fab capacity expansion schedules and node-transition timelines for sub-3nm logic production. Industry-specific forecast inputs included EUV lithography adoption curves for photoresist volume expansion and EPA PFAS enforcement probability assessments for material substitution timing.
Underlying measurement precision varies by segment; fluoropolymer bottle demand for photoresist handling carries tighter precision than stainless steel bulk tank replacement cycles due to disclosed foundry capex visibility. Forecasts reflect documented assumptions about node-transition pace, regulatory enforcement timing, and resin supply allocation behavior. Semiconductor upcycle amplitude, EPA PFAS restriction scope expansion, and EU Carbon Border Adjustment implementation pace warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Cold Plate Market
Industrial Equipment
Asia-Pacific Fans and Blowers Market
Industrial Equipment
Asia-Pacific Industrial Centrifuge Market
Industrial Equipment
Electrodynamic Shaker Systems Market
Industrial Equipment
Vacuum Concentrators Market
Industrial Equipment
Refrigeration Coolers Market
Industrial Equipment
Linear Shaft Motor Market
Industrial Equipment
United States Fusion Splicer Market
Industrial Equipment
PCB Punching Machine Market
Industrial Equipment
Mounted Bearing Market
Industrial Equipment
Soldering Iron Market
Industrial Equipment
Global Safety Relays and Timers Market
Industrial Equipment
Global Cryostat Market
Industrial Equipment
Global Electro Hydraulic Servo Valve Market
Industrial Equipment
Global Refrigeration Compressor Market
Industrial Equipment
Global Linear Bearings Market