
 Gallium Arsenide Market | 2026-2036
Gallium Arsenide Market Size, Share, and Industry Trends Forecast 2026-2036
Gallium Arsenide Market Analysis
REACH compliance is shifting the cost-of-entry calculus for European GaAs substrate suppliers, forcing purification upgrades and supply chain documentation that smaller refiners cannot absorb. Freiberger Compound Materials leverages its captive germanium sourcing to sustain margin stability under these rules. Sumitomo Electric Industries anchors high-frequency device demand through its dominance in molecular beam epitaxy equipment for defense and telecom clients. AXT Inc. competes on 6-inch wafer scale, differentiating through vertical integration from raw gallium to polished substrates.
Gallium arsenide is a III-V compound semiconductor with a direct bandgap of 1.42 eV and electron mobility roughly six times that of silicon, manufactured through liquid encapsulated Czochralski pulling or vertical gradient freeze methods to produce semi-insulating substrates for high-frequency and optoelectronic applications. Wafer products occupy the largest revenue pool, though laser diode applications for lidar and facial recognition are accelerating fastest as automotive and consumer electronics OEMs qualify GaAs-based vertical-cavity surface-emitting lasers. Molecular beam epitaxy technology leads in premium device layers where atomic precision determines performance, while chemical vapor deposition dominates volume production of solar cell structures for space applications.
The EPA monitors gallium and arsenic discharge from U.S. refining operations, while China's MEE enforces wastewater standards at Yunnan Germanium's Kunming facilities; the EU RoHS directive restricts hazardous substances in finished GaAs-containing electronics, shaping design rules for medical device and automotive end users. Japan's METI coordinates national compound semiconductor roadmaps that direct R&D subsidies toward 5G and satellite communication substrates. Stakeholders must monitor divergence between U.S. export controls on advanced substrates and China's push for gallium refining self-sufficiency, as this tension will determine which foundry clusters secure long-term supply commitments.
Market Dynamics
Defense procurement agencies in the United States, Japan, and South Korea are accelerating radar and electronic warfare programs that depend on semi-insulating GaAs substrates, tightening long-term supply commitments to East Asian foundry clusters.
Growth Catalysts
- 5G Infrastructure Deployment:Base station manufacturers in Taiwan and South Korea are scaling orders for high-frequency power amplifiers built on GaAs wafers.
- EU F-Gas Regulation:Tightening energy efficiency standards for compound semiconductor manufacturing are favoring established refiners with captive purification capabilities.
- Satellite Communications:Low-earth orbit constellation operators are qualifying GaAs-based millimeter-wave components for phased-array antennas.
Market Restraints
- Arsenic Supply Concentration:China controls roughly 90% of global arsenic trioxide refining, creating single-source vulnerability for substrate manufacturers.
- Germanium Cost Volatility:Ge substrate prices fluctuate with photovoltaic demand cycles, compressing margins for GaAs-on-Ge solar cell producers.
- Silicon Carbide Substitution:SiC power devices are capturing voltage applications above 600V that GaAs once dominated in defense and aerospace.
Strategic Opportunities
- Automotive Lidar:Tier-1 suppliers in Germany and Japan are qualifying vertical-cavity surface-emitting lasers for next-generation driver-assistance systems.
- India's PLI Scheme:Domestic compound semiconductor fabrication incentives are attracting GaAs wafer processing investments from East Asian equipment vendors.
- Convergence with Photonics:Silicon photonics foundries are integrating GaAs laser sources through heterogeneous bonding for datacenter transceivers.
Industry Challenges
- Molecular Beam Epitaxy Technician Shortage:Atomic-precision deposition expertise concentrates at a handful of defense contractors and telecom equipment suppliers.
- REACH Documentation Burden:European substrate suppliers face escalating compliance costs for supply chain traceability of gallium and arsenic inputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gallium Arsenide Market |
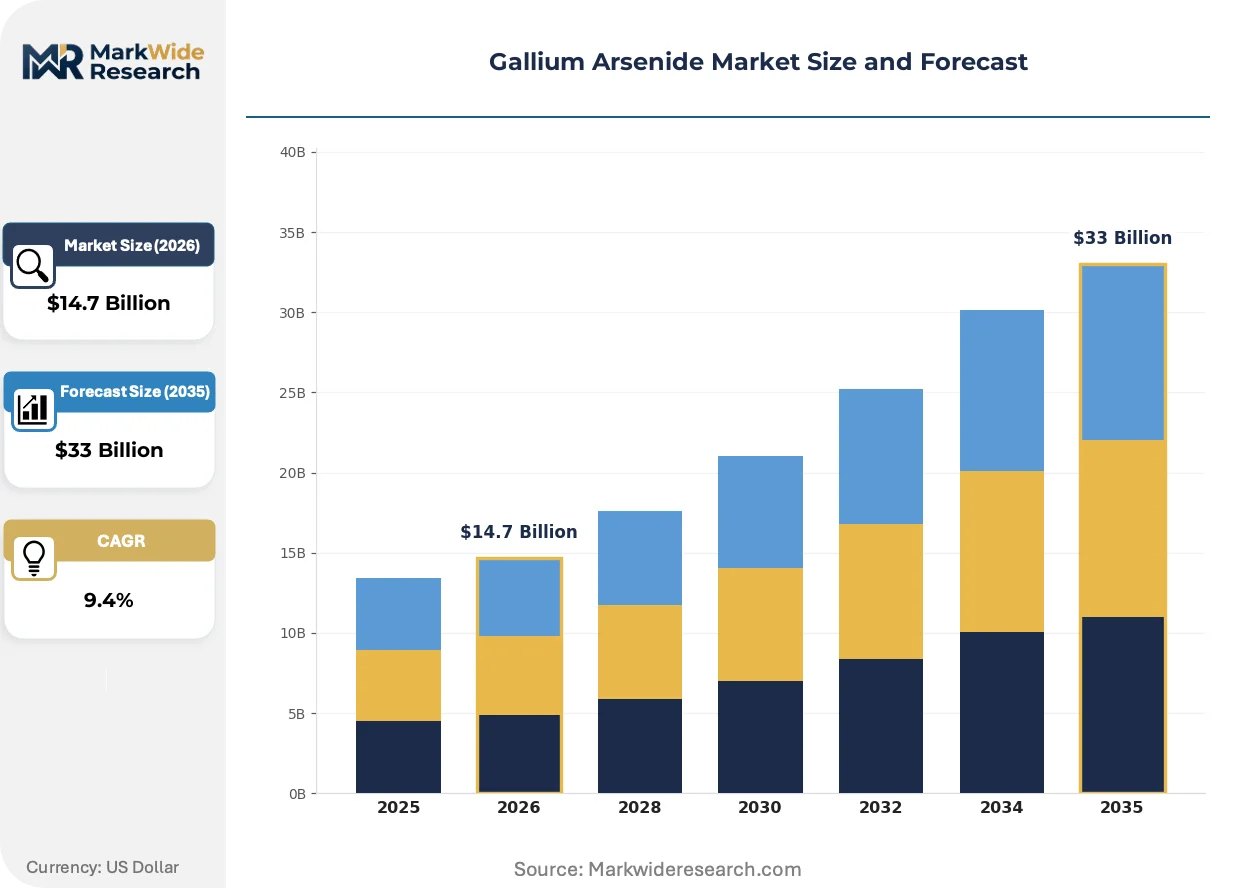
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $33 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wafer, Substrate, Laser Diode, Solar Cell Application: Telecommunications, Solar Energy, LED, Optoelectronics Technology: Molecular Beam Epitaxy, Liquid Phase Epitaxy, Chemical Vapor Deposition, Bridgman Method End User: Aerospace, Consumer Electronics, Automotive, Medical Devices |
| Companies Covered | Freiberger Compound Materials GmbH, China Crystal Technologies, Wafer Technology, DOWA Electronics Materials, Yunnan Germanium, Sumitomo Electric Industries, Xiamen Powerway Advanced Material, Vital Materials, AXT Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gallium Arsenide Market Emerging Trajectories
Wafer processing automation and regulatory tightening around fluorinated gases are compressing production timelines while expanding application boundaries for compound semiconductors.
Atomic layer deposition is automating interface engineering for high-electron-mobility transistors, enabling foundries in Taiwan to achieve sub-nanometer gate oxide uniformity at 6-inch scale. Defense prime contractors are qualifying these processes for satellite payload applications. The technology is automating yield improvement previously requiring manual metrology intervention.
China's dual carbon goals are forcing Kunming-based refiners to install closed-loop wastewater systems at gallium extraction facilities, adding 18-24 months to capacity expansion timelines. The MIIT is coordinating national stockpiling directives that prioritize semiconductor-grade material over LED-grade output. Substrate manufacturers in Japan and South Korea are diversifying toward Australian and Canadian gallium feedstock to reduce concentration risk.
Consolidated procurement by hyperscale datacenter operators is displacing fragmented purchasing from specialized telecom component distributors. Amazon Web Services and Microsoft Azure are issuing direct substrate specifications for optical transceiver modules, bypassing traditional merchant market channels. This concentration is most visible in North American and European cloud infrastructure buildouts.
Gallium Arsenide Market Segmentation
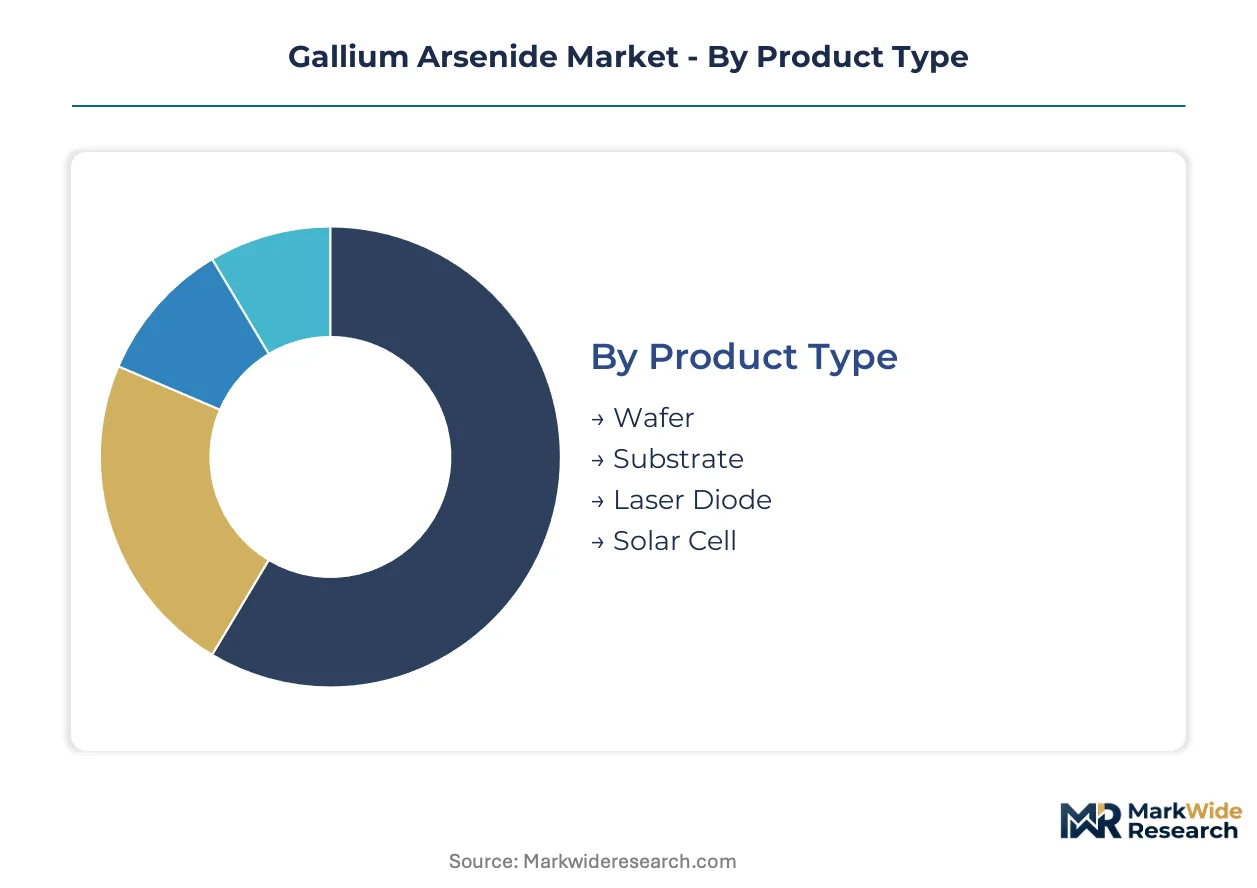
Segmentation in the gallium arsenide market reveals how supply concentration and technical specifications intersect to determine margin capture. Manufacturers align product portfolios with foundry capabilities in Taiwan and South Korea while navigating regulatory constraints on arsenic sourcing.
Product Type:
Supply concentration in high-purity arsenic trioxide refining shapes which product categories sustain margin stability under environmental compliance pressures.
- Wafer:Semi-insulating wafers processed through liquid encapsulated Czochralski pulling command premium pricing for 5G base station power amplifiers. Taiwan's foundry clusters absorb over half of global 6-inch wafer output for RF device fabrication.
- Substrate:Polished substrates for molecular beam epitaxy growth require atomic-level surface preparation. Defense contractors in the United States and Japan lock in multi-year supply agreements for radar and electronic warfare applications.
- Laser Diode:Vertical-cavity surface-emitting laser structures for automotive lidar and facial recognition systems.
- Solar Cell:GaAs-on-germanium triple-junction cells for space satellite power generation.
Today's leader: Wafer. Tomorrow's challenger: Laser Diode.
Application:
Cost tier differentiation separates defense-qualified material from commercial-grade output, with certification cycles creating sticky supplier relationships.
- Telecommunications:High-frequency power amplifiers and millimeter-wave components for 5G infrastructure and low-earth orbit satellite constellations. South Korean base station manufacturers scale orders as phased-array antenna deployment accelerates.
- Solar Energy:Concentrator photovoltaics and space-rated solar arrays requiring radiation-hardened GaAs junctions. Germanium substrate price volatility compresses margins for terrestrial concentrator applications.
- LED:Infrared and visible emitters for sensing and illumination applications.
- Optoelectronics:Photodetectors and optical transceiver components for datacenter interconnects.
Telecommunications commands current volume leadership. Solar Energy faces margin pressure from silicon alternatives.
Technology:
Volume scale separates deposition methods, with atomic-precision techniques serving defense and premium telecom while vapor-phase methods dominate space solar production.
- Molecular Beam Epitaxy:Atomic-layer deposition of heterostructures for high-electron-mobility transistors and quantum cascade lasers. Equipment scarcity and technician concentration at defense contractors limit capacity expansion.
- Liquid Phase Epitaxy:Cost-effective growth of thick active layers for LED and detector applications.
- Chemical Vapor Deposition:Dominant method for space solar cell structures, enabling uniform coating of large-area germanium substrates.
- Bridgman Method:Directional solidification for bulk crystal growth of substrate ingots.
Molecular Beam Epitaxy anchors premium device margins. Chemical Vapor Deposition sustains volume throughput.
End User:
Customer type determines qualification timelines and pricing power, with aerospace and medical applications imposing the most stringent traceability requirements.
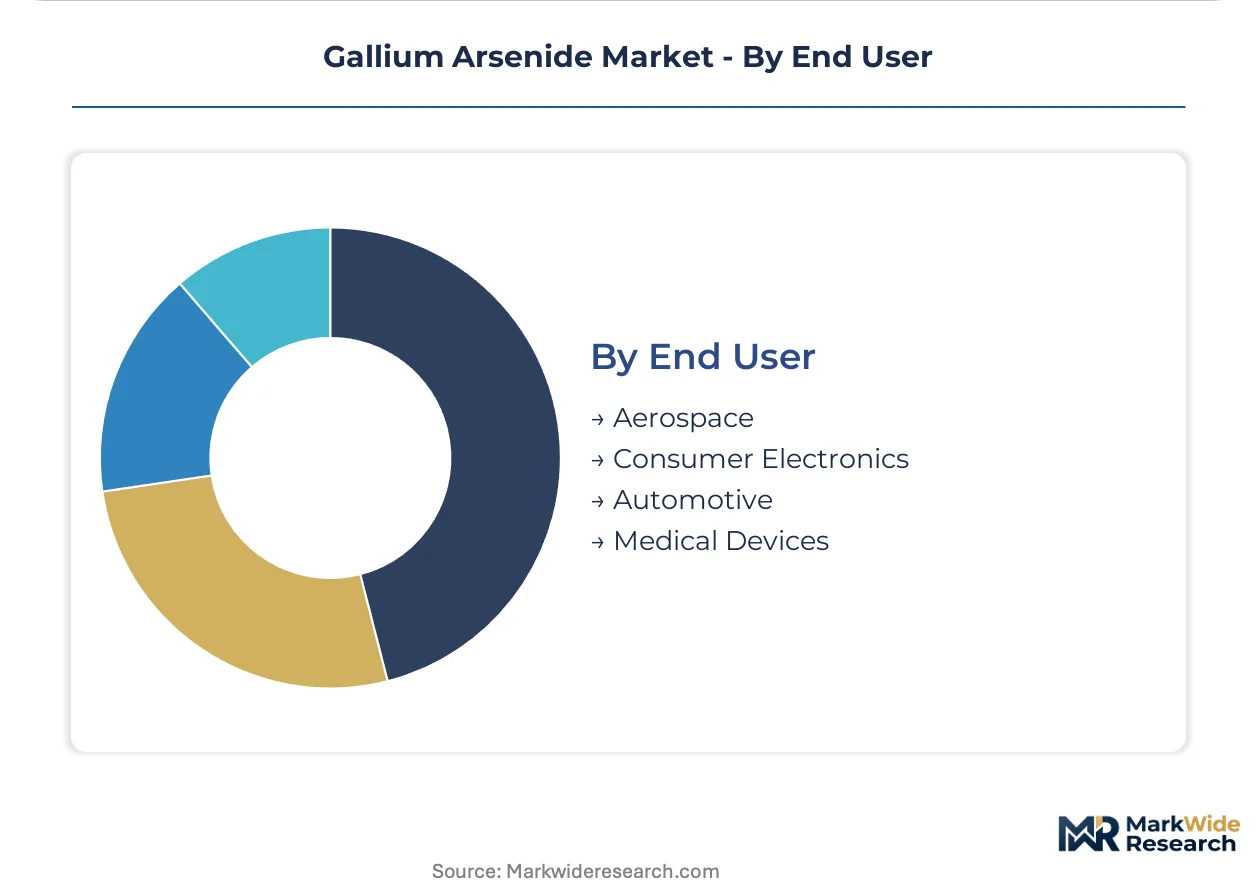
- Aerospace:Satellite payloads and radar systems requiring radiation-hardened, space-qualified material with full supply chain documentation. U.S. defense procurement agencies prioritize domestic sourcing for sensitive applications.
- Consumer Electronics:Facial recognition modules and proximity sensors for smartphones. Volume concentration at tier-1 OEMs drives consolidation in substrate purchasing.
- Automotive:Lidar systems and in-cabin sensing for advanced driver-assistance platforms.
- Medical Devices:Imaging and diagnostic equipment subject to EU RoHS and REACH substance restrictions.
Aerospace sustains pricing power through qualification barriers. Automotive represents the steepest expansion trajectory as lidar deployment scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GaAs substrate manufacturing traces its commercial origins to Bell Laboratories in the United States during the 1960s, with subsequent scaling concentrated in German crystal growth facilities and Japanese epitaxy equipment development. Today's production geography reflects this tripartite legacy, with foundry clusters in Taiwan and South Korea now processing the majority of finished wafers.
United States
Defense procurement agencies in the United States accelerate radar and electronic warfare programs requiring semi-insulating GaAs substrates. The EPA monitors gallium and arsenic discharge from domestic refining operations, tightening discharge permits for substrate manufacturers. Defense contractors in California and Massachusetts lock in multi-year supply agreements for space-qualified material.
Germany
German substrate suppliers serve European telecom and automotive lidar markets through specialized wafer processing capabilities. REACH compliance forces purification upgrades and supply chain documentation that smaller refiners cannot absorb. Freiberger Compound Materials leverages captive germanium sourcing in Saxony to sustain margin stability under these rules.
Japan
Japanese base station manufacturers scale orders for high-frequency power amplifiers built on GaAs wafers for 5G infrastructure deployment. METI coordinates national compound semiconductor roadmaps directing R&D subsidies toward satellite communication substrates. Equipment vendors in Osaka and Tokyo dominate molecular beam epitaxy system supply for defense and telecom clients.
China
China controls roughly 90% of global arsenic trioxide refining, creating single-source vulnerability for substrate manufacturers worldwide. MEE enforces wastewater standards at Yunnan Germanium's Kunming facilities under dual carbon goals, adding 18-24 months to capacity expansion timelines. MIIT coordinates national stockpiling directives prioritizing semiconductor-grade material over LED-grade output.
South Korea
South Korean foundry clusters absorb significant volume of global 6-inch wafer output for RF device fabrication. Base station manufacturers scale orders as phased-array antenna deployment accelerates for 5G and satellite communications. Seoul-area processing facilities qualify GaAs-based millimeter-wave components for low-earth orbit constellation operators.
Gallium Arsenide Market Vendor Landscape
The competitive structure tilts toward vertically integrated material suppliers with captive feedstock control. Concentration is pronounced at the refining stage where arsenic trioxide purification capabilities limit viable substrate production. Three archetypes dominate: German crystal growth specialists with legacy purification assets, Japanese equipment-integrated suppliers leveraging epitaxy system dominance, and Chinese state-coordinated refiners with arsenic supply security. Capacity expansion and backward integration into gallium extraction represent the primary competitive vectors as feedstock security trumps pure manufacturing scale.
Among German crystal growth specialists, Freiberger Compound Materials GmbH exemplifies the captive-feedstock archetype through its integrated germanium sourcing. Sumitomo Electric Industries and AXT Inc. represent contrasting scale positions within the equipment-integrated and wafer-specialist tiers respectively. These three companies anchor the competitive structure without exhausting its diversity, as Chinese state-coordinated entities including Yunnan Germanium occupy a parallel strategic lane defined by raw material security rather than processing technology differentiation.
| Leading Market Players |
|---|
| Freiberger Compound Materials GmbH |
| China Crystal Technologies |
| Wafer Technology |
| DOWA Electronics Materials |
| Yunnan Germanium |
| Sumitomo Electric Industries |
| Xiamen Powerway Advanced Material |
| Vital Materials |
| AXT Inc. |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between defense-qualified and commercial-grade GaAs substrates creates divergent margin profiles that propagate through both pricing structures and procurement network configurations. Military buyers absorb 40-60% premiums for full traceability documentation while automotive lidar suppliers negotiate on volume scale, forcing suppliers to maintain parallel production lines with incompatible cost bases.
Pricing Analysis
Contract-based long-term offtake dominates premium tiers where defense contractors lock in multi-year supply agreements for semi-insulating substrates, while spot-market transactions govern LED-grade material flows. Price differentiation hinges on certification level—ITAR compliance and space-qualification documentation command substantial premiums—and volume scale, with 6-inch wafer lots attracting tiered discounts above threshold quantities. Cost compression in commercial-grade wafers is intensifying because Chinese refiners are expanding gallium extraction capacity ahead of quality-upgrade timelines. Defense procurement agencies exhibit lowest price sensitivity due to mission-critical specifications, whereas consumer electronics OEMs drive hardest bargain negotiations.
Supply Chain Analysis
Defense-qualified material gating through ITAR and space-grade certification restricts viable supplier pools to a handful of established crystal growth specialists. Geographic supply concentration centers on China for arsenic trioxide refining, Taiwan and South Korea for wafer processing, and Germany for germanium substrate integration. Raw material dependencies draw from high-purity gallium metal, arsenic trioxide, and germanium single-crystal feedstock. Single-source vulnerability in Chinese arsenic refining exposes substrate manufacturers to export restriction risk. Distribution runs through direct long-term contracts for defense and aerospace end users, while merchant distributors serve commercial electronics and LED applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GaAs substrate economics favor margin expansion as defense procurement agencies absorb certification premiums while automation drives down molecular beam epitaxy processing costs. The shift toward automotive lidar qualification creates new premium-tier demand with less stringent documentation than aerospace but higher performance thresholds than consumer electronics.
For Market Incumbents: Anticipate silicon carbide substitution pressure in power applications above 600V by accelerating qualification of GaAs-on-SiC heterogeneous integration for next-generation radar systems. Lock in captive gallium supply through backward integration into extraction partnerships in Australia and Canada, reducing exposure to Chinese concentration risk. Prioritize MBE technician pipeline development through defense contractor apprenticeship programs to sustain atomic-precision deposition capacity. For New Entrants and Emerging Players: Enter via India's PLI scheme for compound semiconductor fabrication, where domestic incentives and underdeveloped local supply chains create first-mover advantage for wafer processing investments. Target automotive lidar substrate qualification as the most penetrable segment, where Tier-1 suppliers in Germany and Japan are actively diversifying beyond established Japanese and German incumbents. Pursue joint development agreements with VCSEL design houses to secure volume commitments before capacity buildout. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance costs and captive feedstock requirements exceed smaller European refiners' capital access, creating distressed acquisition opportunities in German crystal growth specialists. Long-term viability over a 5-10 year window favors vertically integrated material suppliers with arsenic security and MBE equipment relationships over pure-play wafer polishers. Watch for inflection in U.S. export control expansion to advanced substrates, which would trigger supply chain restructuring and margin repricing for domestic-qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Gallium Extraction Partnership | Australian and Canadian mining partnerships reduce Chinese arsenic trioxide dependency for substrate manufacturers. |
| MBE Technician Apprenticeship Program | Defense contractor training pipelines address atomic-precision deposition expertise scarcity constraining capacity expansion. |
| Automotive Lidar Qualification Fast-Track | German and Japanese Tier-1 supplier partnerships unlock VCSEL substrate demand from advanced driver-assistance deployment. |
| REACH Compliance Automation Investment | Supply chain traceability software upgrades preserve European market access as documentation burdens escalate. |
| Defense Procurement Direct Contracting | Bypassing merchant distributors captures full margin on ITAR-qualified material for radar and electronic warfare programs. |
Methodological Framework
Direct dialogue with substrate manufacturing executives, defense procurement officers, MBE equipment specialists, and compound semiconductor foundry managers grounded qualitative assessment in operational reality. Secondary validation drew from SEC filings of listed wafer suppliers, EPA discharge permit records, MIIT stockpiling directives, and EU REACH substance restriction updates. Bottom-up capacity modeling across Taiwan and South Korean foundry clusters was triangulated against top-down demand aggregation from 5G base station deployment schedules and satellite constellation launch manifests.
Bottom-up volume projections tracked wafer output by diameter and doping specification across identified crystal growth facilities, while top-down value estimates applied pricing tier differentials from defense contract disclosures and merchant market quotations. Segmentation dimensions modeled encompassed product type, application vertical, deposition technology, and end-user qualification tier. CAGRs were derived from slope analysis of capacity expansion timelines against demand pull from phased-array antenna deployment and lidar qualification curves.
Inputs from defense procurement databases and foundry equipment utilization reports were available through the study window; gaps in Chinese state-refiner cost structures introduce uncertainty bands around margin compression scenarios. Forecasts reflect assumptions on ITAR compliance continuity and gallium extraction capacity expansion schedules. A model refresh is warranted upon material change in U.S. export control scope or Chinese arsenic trioxide export licensing protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Optoelectronic Development Tools Market
Optoelectronics
EPON ONU Market
Optoelectronics
3D Projector Market
Optoelectronics
Europe Wigig Market
Optoelectronics
2-Ethyl-3,4-Ethylenedioxythiophene Market
Optoelectronics
Smart Compact Projectors Market
Optoelectronics
Gaas Epiwafer Market
Optoelectronics
Electro-Optical/Infrared (EO/IR) Systems Market
Optoelectronics
Optical Pulse Sensor Market
Optoelectronics
Automotive Optoelectronics Market
Optoelectronics
Japan Optoelectronics Market
Optoelectronics
Gaas Photodiode Market
Optoelectronics
Americas Optoelectronics Market
Optoelectronics
Laser Projector Market
Optoelectronics
South Korea Optoelectronics Market
Optoelectronics
Vertical Cavity Surface Emitting Laser (Vcsels) Market