
 Europe Wigig Market | 2026-2036
Europe Wigig Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wigig Market Foresight
The gap between legacy Wi-Fi architectures and Wigig's 60 GHz millimeter-wave stack is narrowing as silicon integration advances. Qualcomm Technologies Inc. leverages its modem-RF system expertise to anchor early design wins in consumer electronics reference platforms. Intel Corporation sustains R&D intensity in photonic integration for backhaul applications. Sivers Ima Holding AB specializes in beamforming front-end modules that differentiate its offering for fixed wireless access deployments.
WiGig denotes wireless communication operating in the unlicensed 60 GHz band, delivering multi-gigabit throughput through oxygen-absorption-limited propagation ranges of roughly 10 meters with beamforming compensation for directional link stability. The technology serves industrial and commercial purposes where fiber substitution or cable-free device docking demands low-latency, high-density data transmission. Beamforming and MIMO implementations are leading the technology segment as these architectures resolve line-of-sight constraints inherent to millimeter-wave propagation. Smart manufacturing and autonomous navigation applications are expanding fastest within the deployment category, driven by factory automation and sensor fusion requirements that demand deterministic wireless performance.
CE marking under the EU Radio Equipment Directive shapes market access by mandating electromagnetic compatibility and spectrum efficiency thresholds for 60 GHz equipment sold across member states. The European Telecommunications Standards Institute coordinates harmonized frequency allocations that reduce national fragmentation barriers for Wigig hardware vendors. Germany's Federal Network Agency and France's ANFR enforce national spectrum coordination rules that influence product certification timelines and operational power limits. Stakeholders must monitor upcoming revisions to the EU's 5G and 6G spectrum roadmaps, as these frameworks will determine whether Wigig receives expanded contiguous bandwidth or faces encroachment from sub-terahertz research bands.
Market Dynamics
Millimeter-wave silicon integration is collapsing cost curves for 60 GHz beamforming chipsets, enabling Wigig modules to displace fiber drops in German automotive plants and French industrial zones where cable installation disrupts continuous production.
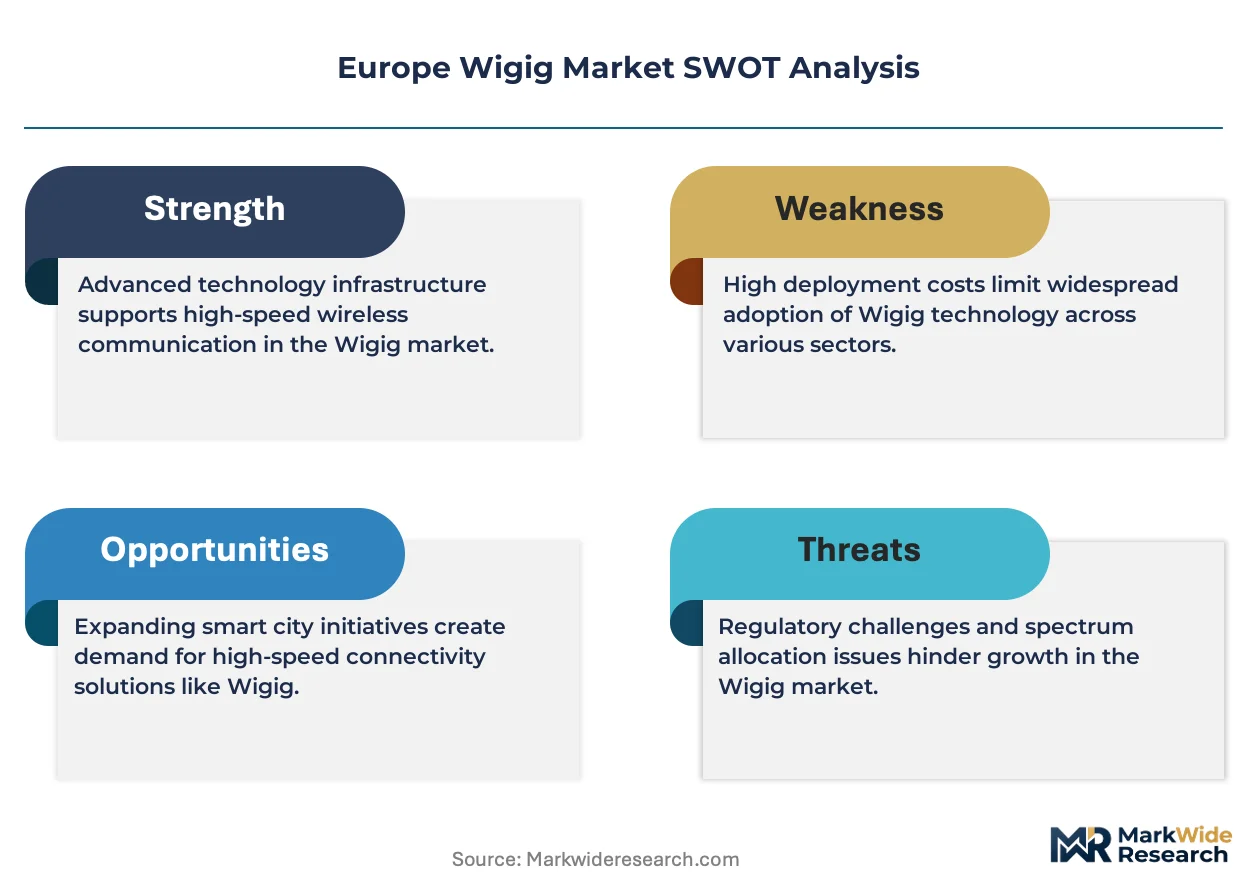
Growth Catalysts
- EU Radio Equipment Directive harmonization:CE marking streamlines cross-border equipment certification, reducing national fragmentation barriers for Wigig hardware vendors deploying across member states.
- Smart manufacturing backhaul demand:Factory automation clusters in Bavaria and Baden-Württemberg deploy millimeter-wave links for real-time machine control and deterministic wireless performance.
- Oxygen-absorption propagation physics:The 60 GHz band's natural interference containment enables dense frequency reuse in industrial environments without complex coordination protocols.
Market Restraints
- Line-of-sight dependency:Millimeter-wave signals attenuate rapidly through physical obstructions, limiting deployment flexibility in cluttered industrial settings without clear transmission paths.
- Specialized RF engineering talent scarcity:Beamforming system design requires expertise in phased-array antenna theory that remains concentrated within a narrow supplier base.
- Legacy Wi-Fi infrastructure sunk costs:Enterprises with recent 802.11ax deployments face capital efficiency pressures that delay Wigig refresh cycles despite performance gaps.
Strategic Opportunities
- France industrial corridor expansion:Auvergne-Rhône-Alpes manufacturing hubs present underpenetrated demand for cable-free device docking and wireless backhaul solutions.
- Photonic integration convergence:Silicon photonics merging with millimeter-wave RF front-ends promises power efficiency gains for fixed wireless access base stations.
- EU Green Deal operational mandates:Industrial decarbonization targets incentivize wireless infrastructure that eliminates cable production and installation emissions.
Industry Challenges
- CE marking certification timelines:National spectrum coordination rules enforced by Germany's Federal Network Agency and France's ANFR create variable approval durations that compress product launch windows.
- Legacy industrial network integration:Deterministic Ethernet protocols in existing automation systems require gateway development that extends deployment complexity.
- Phased-array calibration skill gaps:Manufacturing yield for beamforming modules depends on specialized test equipment operation that outpaces workforce development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wigig Market |
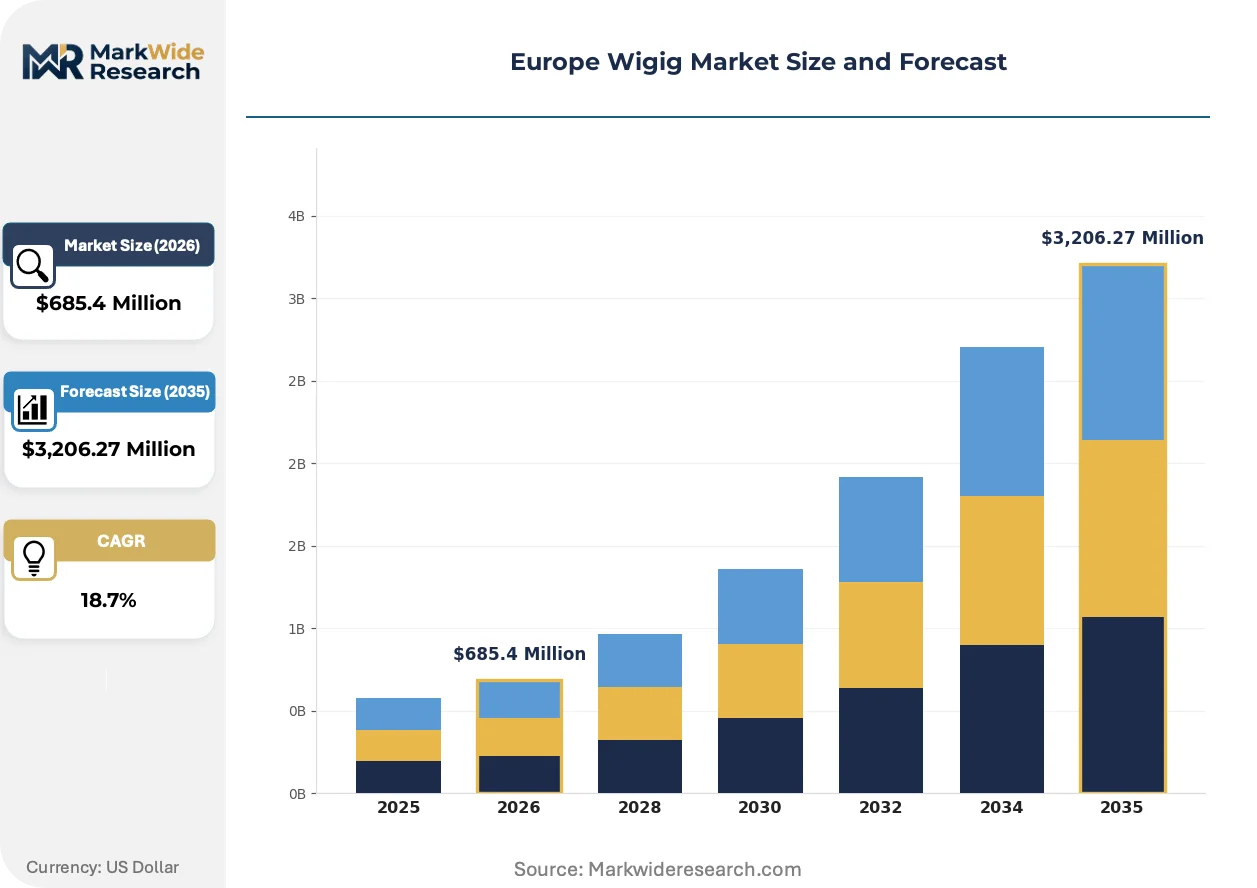
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $3,206.27 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Beamforming, MIMO, Photonic Integration, Optical Components, Frequency Modulation Application: Consumer Electronics, Smart Manufacturing, Autonomous Navigation, Augmented Reality, Robotics Deployment: Fixed Wireless Access, Portable Devices, Wearable Equipment, Industrial Automation, Transportation Systems End User: Telecom Operators, Research Institutes, Defense Agencies, Transportation Authorities, Smart City Projects |
| Companies Covered | Panasonic Corporation, Qualcomm Technologies Inc., Intel Corporation, Broadcom Inc., Blu Wireless Technology Limited, Sivers Ima Holding AB, Fujikura Ltd., Cisco Systems Inc., Infineon Technologies AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wigig Market Shifts & Advancements
Active antenna systems are redefining deployment economics across European industrial zones, compressing installation timelines while expanding addressable use cases beyond consumer electronics into mission-critical infrastructure.
Phased-array beamforming chipsets with integrated calibration loops are rendering obsolete discrete component architectures that required manual antenna alignment. Automotive Tier-1 suppliers in Stuttgart and Munich are qualifying these modules for in-vehicle sensor backhaul at accelerated validation cycles. The shift collapses supplier qualification timelines from eighteen months to under six months.
CE marking enforcement under the EU Radio Equipment Directive is tightening electromagnetic compatibility thresholds for 60 GHz equipment sold across member states. Manufacturers must now demonstrate spectrum efficiency metrics that exceed prior self-certification norms. German industrial automation vendors are front-loading compliance testing to secure first-mover positioning in harmonized markets.
Factory procurement teams are consolidating wireless infrastructure spending under single-vendor framework agreements that bundle Wigig backhaul with managed services. System integrators in the Ruhr industrial region are displacing component resale models with performance-guaranteed contracts. French automotive OEMs have pioneered this structure at plants in Hauts-de-France.
Europe Wigig Market Segmentation
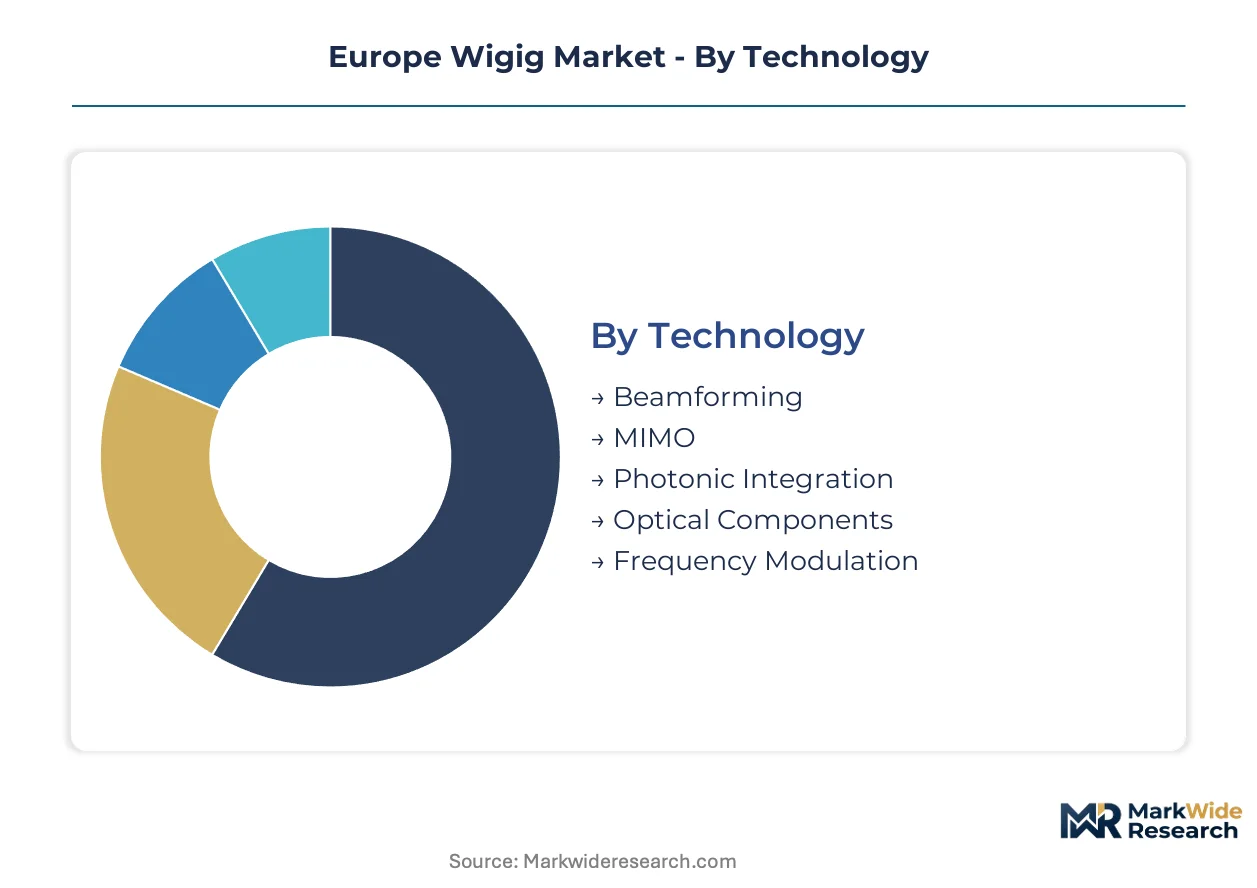
WiGig market segmentation reveals how 60 GHz technology traverses radically different maturity curves across industrial and consumer domains. The technology stack splits between proven beamforming architectures and emerging photonic integration, while deployment patterns diverge between established fixed wireless access and nascent wearable equipment categories.
Technology:
Mature beamforming implementations dominate commercial deployments, while photonic integration represents the emerging frontier for power-efficient millimeter-wave systems.
- Beamforming:Phased-array antenna systems with integrated calibration loops enable directional link stability in cluttered industrial environments. Bavarian automotive plants deploy these modules for deterministic machine-to-machine communication where line-of-sight constraints demand adaptive signal steering.
- MIMO:Multiple-input multiple-output architectures exploit spatial multiplexing to multiply spectral efficiency in dense factory deployments. Auvergne-Rhône-Alpes manufacturing hubs favor MIMO configurations for wireless backhaul where spectrum reuse must maximize throughput per square meter.
- Photonic Integration:Silicon photonics merging with RF front-ends promises thermal efficiency gains for base station deployments.
- Optical Components:Discrete laser and detector modules support hybrid fiber-millimeter-wave architectures.
- Frequency Modulation:Advanced modulation schemes optimize spectral occupancy under EU harmonized allocation rules.
Beamforming handles the majority of throughput; photonic integration is expanding most quickly on share.
Application:
Cost tier stratification separates capital-intensive industrial automation from consumer electronics volume plays.
- Smart Manufacturing:Real-time machine control and deterministic wireless performance drive millimeter-wave backhaul adoption in German industrial clusters. Factory automation protocols demand sub-millisecond latency that legacy Wi-Fi architectures cannot satisfy.
- Consumer Electronics:Wireless docking and cable-free display interfaces anchor early WiGig volume in premium laptop and peripheral segments. CE marking harmonization has accelerated reference design availability across EU member states.
- Autonomous Navigation:Sensor fusion backhaul for mobile robotics requires interference-contained 60 GHz links in dynamic environments.
- Augmented Reality:Untethered headsets demand high-density video streaming with minimal motion-to-photon latency.
- Robotics:Collaborative robot arm communication benefits from oxygen-absorption-limited propagation that enables dense frequency reuse.
Smart Manufacturing commands the premium pricing tier; Autonomous Navigation is climbing the fastest on deployment share.
Deployment:
Volume concentration favors infrastructure-heavy categories, while customer type differentiation separates enterprise procurement from research-scale acquisition.
- Fixed Wireless Access:Point-to-point millimeter-wave links displace fiber drops in French industrial zones where cable installation disrupts continuous production. Ruhr region system integrators bundle these deployments with managed service frameworks.
- Industrial Automation:Deterministic Ethernet gateways integrate WiGig backhaul into existing programmable logic controller networks. Stuttgart automotive Tier-1 suppliers qualify these modules under accelerated validation cycles.
- Portable Devices:Laptop and tablet docking stations leverage 60 GHz for uncompressed video transport.
- Wearable Equipment:Head-mounted displays and body-area networks represent nascent demand with unproven volume economics.
- Transportation Systems:In-vehicle sensor backhaul and rail communication infrastructure present long-cycle certification requirements.
Fixed Wireless Access captures the infrastructure investment wave; Industrial Automation is gaining share fastest among manufacturing end-users.
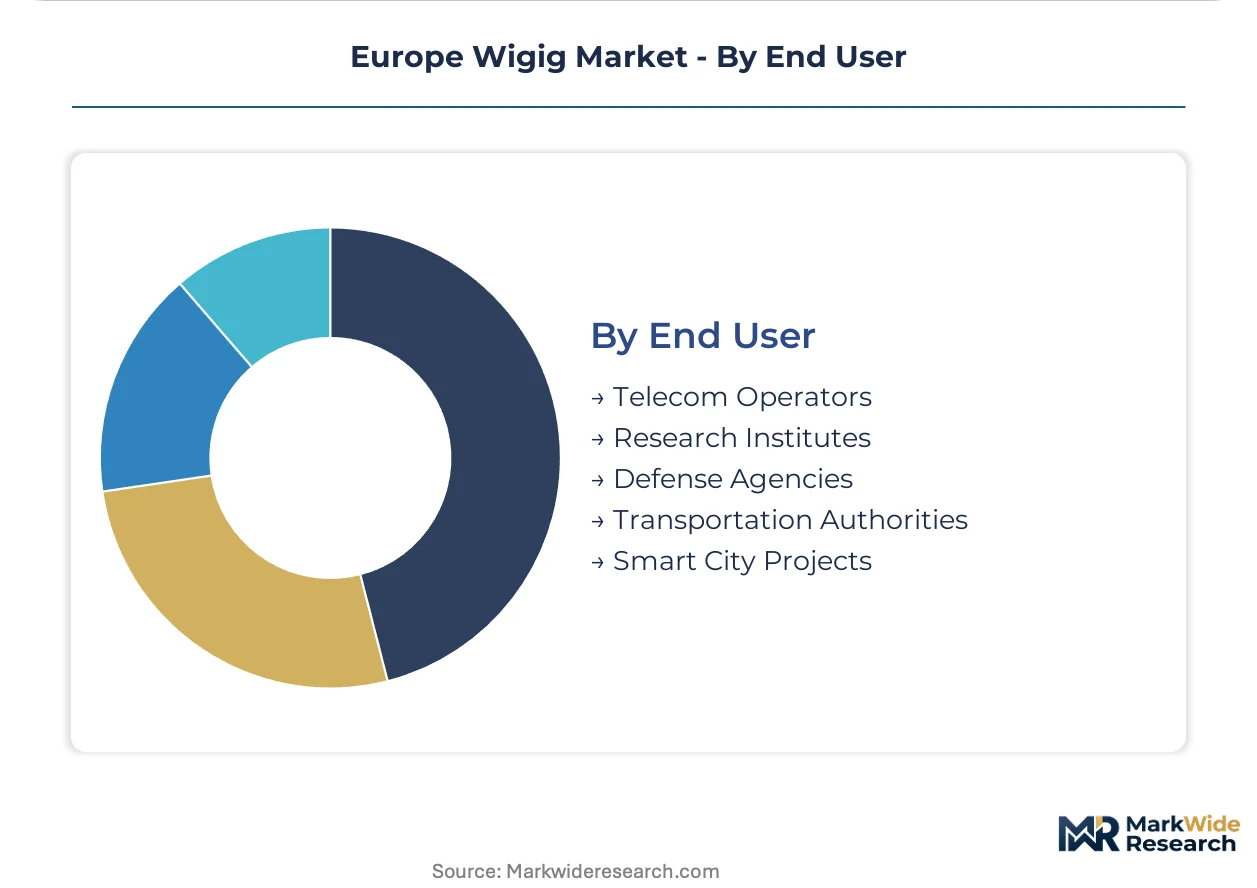
End User:
Supply concentration clusters around telecom operator procurement, with margin differentiation favoring defense and research segments over municipal smart city projects.
- Telecom Operators:Mobile network densification drives millimeter-wave small cell backhaul procurement under EU 5G spectrum roadmaps. German and French carriers front-load equipment certification to secure harmonized market positioning.
- Defense Agencies:Secure, high-bandwidth communication links for tactical applications demand specialized electromagnetic hardening and national spectrum coordination.
- Research Institutes:ETSI-coordinated standardization participation and sub-terahertz exploratory work sustain institutional demand for advanced test equipment.
- Transportation Authorities:Rail and aviation regulators impose safety-critical certification timelines that extend deployment cycles.
- Smart City Projects:Municipal procurement frameworks bundle wireless infrastructure with broader urban digitization initiatives.
Telecom Operators anchor procurement volume; Defense Agencies command the steepest expansion trajectory on classified application development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial automation procurement teams in Germany, France, and the United Kingdom concentrate demand for millimeter-wave backhaul solutions, with system integrators in the Ruhr and Auvergne-Rhône-Alpes regions front-loading equipment certification under CE marking harmonization.
Germany
Automotive Tier-1 suppliers and factory automation clusters in Bavaria and Baden-Württemberg deploy WiGig-enabled wireless connectivity for real-time machine control. The Federal Network Agency enforces national spectrum coordination rules that influence operational power limits and certification timelines. Stuttgart-based validation cycles for beamforming modules have compressed from eighteen months to under six months.
France
Manufacturing hubs in Auvergne-Rhône-Alpes present underpenetrated demand for cable-free device docking and wireless backhaul in industrial zones where cable installation disrupts continuous production. ANFR coordinates national spectrum allocation with ETSI harmonized standards. Hauts-de-France automotive OEMs pioneered single-vendor framework agreements bundling WiGig infrastructure with managed services.
United Kingdom
Research institutes and defense agencies sustain institutional demand for advanced millimeter-wave test equipment and secure high-bandwidth tactical communication links. Ofcom implements EU-aligned spectrum frameworks while maintaining national flexibility for experimental licensing. Cambridge and Oxfordshire technology clusters participate in ETSI-coordinated standardization for sub-terahertz exploratory work.
Italy
Industrial machinery manufacturers in Lombardy and Emilia-Romagna evaluate WiGig for deterministic wireless performance in smart manufacturing environments. The Ministry of Economic Development aligns national spectrum policy with EU Radio Equipment Directive requirements. Milan-based system integrators are qualifying beamforming modules for fixed wireless access deployments in northern industrial corridors.
Netherlands
Telecom operators in the Randstad region front-load equipment certification to secure harmonized market positioning for 5G network densification using millimeter-wave small cell backhaul. The Radiocommunications Agency enforces CE marking compliance for cross-border equipment sales. Eindhoven's semiconductor ecosystem supplies phased-array calibration expertise to European beamforming module manufacturers.
Europe Wigig Market Competitive Landscape
Channel-controlling players compete with product-specialist players across the European WiGig ecosystem. The vendor base organizes around three tiers: integrated platform providers supplying reference designs to consumer electronics manufacturers, RF front-end specialists delivering beamforming modules for industrial automation, and networking infrastructure vendors bundling millimeter-wave backhaul with managed services. Strategic moves concentrate on accelerated certification timelines under EU harmonization and vertical integration into silicon photonics for power-efficient base station deployments.
Within the RF front-end specialist tier, Sivers Ima Holding AB and Blu Wireless Technology Limited represent the beamforming module archetype for fixed wireless access and industrial applications. Qualcomm Technologies Inc. anchors the integrated platform provider category with modem-RF system expertise. Among networking infrastructure vendors, Cisco Systems Inc. occupies a position bundling enterprise wireless solutions with service frameworks.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Qualcomm Technologies Inc. |
| Intel Corporation |
| Broadcom Inc. |
| Blu Wireless Technology Limited |
| Sivers Ima Holding AB |
| Fujikura Ltd. |
| Cisco Systems Inc. |
| Infineon Technologies AG |
| Others |
Supply & Pricing Matrix
CE marking certification chokepoints under the EU Radio Equipment Directive determine both three-tier pricing stratification across premium, standard, and economy certification levels and supply chain regionalization toward Eindhoven calibration expertise and German validation clusters.
Pricing Analysis
Cost-plus contracts indexed to silicon wafer pricing dominate beamforming module procurement between automotive Tier-1 suppliers and RF front-end vendors. Price differentiation separates CE-marked premium tiers from self-certified economy modules, with volume scale and after-sales service bundling as secondary drivers. Pricing pressure stems from compressed certification timelines demanded by Bavarian factory automation clusters. Research institutes exhibit lowest price sensitivity; municipal smart city projects face acute budget constraints.
Supply Chain Analysis
Export-control restrictions on phased-array calibration equipment limit flows from Dutch semiconductor ecosystems to non-EU manufacturing partners. Geographic supply concentration centers on Germany, the Netherlands, and Taiwan for beamforming chipsets, calibration test equipment, and silicon foundry capacity. Raw material dependencies include gallium arsenide substrates, RF-grade silicon, and precision antenna substrates. Single-source vulnerability concentrates in Eindhoven calibration expertise. Distribution runs through system integrators in the Ruhr region bundling hardware with managed service frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe WiGig market constitutes a high-growth disruption justified by EU Radio Equipment Directive harmonization collapsing cross-border certification barriers from eighteen-month cycles to under six months.
For Market Incumbents: Pre-empt emerging photonic integration specialists by accelerating backward integration into silicon photonics for power-efficient base station deployments. Secure capacity expansion in Auvergne-Rhône-Alpes manufacturing corridors before competitor qualification cycles complete. CE marking investment remains the priority defensive lever against uncertified economy-tier entrants.
For New Entrants and Emerging Players: Pursue underpenetrated demand in French industrial zones where cable installation disrupts continuous production and incumbent footprint remains shallow. Target fixed wireless access deployments bundled with performance-guaranteed service contracts as the most penetrable entry vector. Channel partnership with Ruhr region system integrators offers the clearest go-to-market acceleration.
For Investors and Strategic Acquirers: RF front-end specialists with captive beamforming calibration expertise represent the highest-conviction acquisition archetype for long-term positioning across the 5G-to-6G transition window. Watch for EU spectrum roadmap revisions expanding contiguous 60 GHz bandwidth as the definitive demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Acceleration | Compressed certification timelines secure first-mover positioning in harmonized EU markets. |
| Photonic Integration Investment | Silicon photonics convergence delivers thermal efficiency gains for base station deployments. |
| Framework Agreement Consolidation | Single-vendor procurement structures displace component resale in German automotive clusters. |
| Regional Calibration Capacity | Eindhoven expertise expansion reduces single-source vulnerability in beamforming module manufacturing. |
| Spectrum Roadmap Monitoring | ETSI coordination participation enables rapid response to EU 5G and 6G allocation revisions. |
Research Methodology
A spread of perspectives from RF system architects at automotive Tier-1 suppliers, procurement leads at French manufacturing hubs, certification engineers at German Federal Network Agency liaison offices, and beamforming module test equipment operators converged on the working assumptions. Primary interview insights combined with secondary validation from ETSI standardization documents, CE marking regulatory filings, customs equipment trade data, and hyperscaler capex disclosures for 5G densification. Bottom-up module shipment estimates and top-down spectrum allocation demand projections underwent triangulation.
Demand-supply balance modeling across the projection horizon segmented by technology maturity, application latency requirements, deployment infrastructure intensity, and end-user procurement scale. CAGRs derived from fitted adoption curves calibrated to German automotive validation cycle compression and French industrial corridor penetration rates. Forecast inputs incorporated EU Green Deal operational mandate timelines and sub-terahertz research band allocation probabilities.
Sensitivities concentrate around EU spectrum roadmap revisions, CE marking enforcement intensity shifts, and photonic integration yield improvements. Forecasts reflect documented assumptions on harmonized certification timeline stability and industrial automation capital expenditure continuity. Material shifts in ETSI 6G band allocation priorities or German Federal Network Agency power limit adjustments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Smart Compact Projectors Market
Optoelectronics
Electro-Optical/Infrared (EO/IR) Systems Market
Optoelectronics
Japan Optoelectronics Market
Optoelectronics
China Optical Detector Market
Optoelectronics
United States Optoelectronics Market
Optoelectronics
Gaas Wafer and Epiwafer Market
Optoelectronics
Green Laser Diode Market
Optoelectronics
Taiwan Optoelectronics Market
Optoelectronics
Infrared Emitter and Receiver Market
Optoelectronics
Global Infrared Optoelectronics Market
Optoelectronics
Algainp Epitaxial Wafers Market
Optoelectronics
Europe Optoelectronics Market
Optoelectronics
Americas Optoelectronics Market
Optoelectronics
Opto-Electronics Device Market
Optoelectronics
Gallium Arsenide Gaas Wafer Market
Optoelectronics
Global Opto-Isolator Market